
 Dry Chilies Market | 2026-2036
Dry Chilies Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Chilies Market Foresight
Multi-source procurement is pivoting toward vertically integrated supply chains as price volatility and climate risk disrupt traditional spot-market buying. Everest Food Products Pvt. Ltd. anchors its competitiveness through deep backward integration into Indian agricultural zones. McCormick & Company, Inc. leverages global blending facilities to sustain consistent flavor profiles across regional formulations. Olam International Limited operates extensive sourcing networks that span African and Asian growing belts, reducing single-origin dependency.
Dry chilies are Capsicum fruits dehydrated to moisture levels below 10 percent, preserving capsaicinoids and carotenoids for shelf-stable heat and color delivery to food manufacturers. The primary commercial purpose centers on standardized pungency and hue inputs for industrial sauce, seasoning, and ready-meal production. Paprika varieties command premium positioning in European and North American color-intensive applications where extractable pigment value exceeds commodity heat pricing. Culinary and food processing end uses generate the deepest volume pools, while sauces and seasoning segments extract higher per-kilogram value through formulation specificity. Wholesale and direct sales channels dominate volume movement, though online distribution is gaining traction among artisanal and specialty buyers seeking traceable origin documentation.
India's BIS enforces moisture and aflatoxin thresholds that determine export eligibility for domestic processors. The EU's EFSA pesticide maximum residue limits and REACH-aligned contaminant protocols shape formulation choices for European-bound shipments. FDA enforcement of the Food Safety Modernization Act preventive controls affects US import acceptance criteria for dried chili lots. Stakeholders must monitor evolving mycotoxin testing protocols and origin certification requirements as regulatory stringency tightens across destination markets.
Market Dynamics
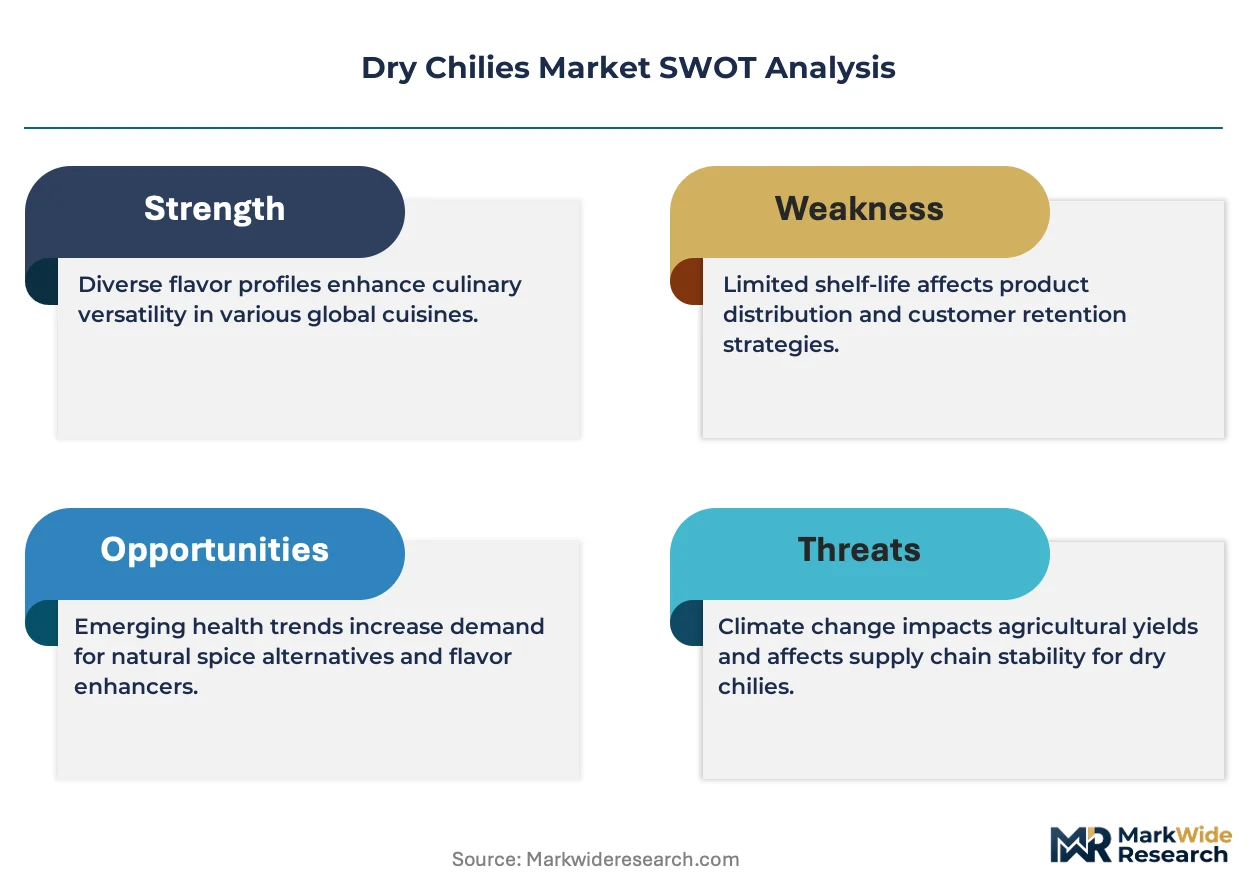
Climate-induced harvest volatility and tightening pesticide residue protocols are forcing processors to reconfigure sourcing networks around certified-origin supply pools rather than spot-market procurement.
Growth Catalysts
- Capsaicinoid extraction technology:Advanced solvent-free methods enable food manufacturers to standardize heat units precisely, expanding industrial formulation applications beyond traditional grinding.
- EFSA-aligned import protocols:European processors seeking compliant supply chains are driving demand for Indian and African lots with pre-certified residue documentation.
- Sauce and seasoning expansion:Food processing companies in the condiment sector are scaling procurement of paprika and cayenne varieties for color-stable product lines.
Market Restraints
- Input cost volatility:Natural gas prices directly impact dehydration energy costs, compressing processor margins during price spike cycles.
- Single-origin concentration:Andhra Pradesh and Karnataka clusters supply over half of India's export-grade dried chilies, creating geographic risk exposure.
- Aflatoxin technical limitations:Pre-harvest fungal contamination in humid growing zones remains difficult to eliminate entirely through post-harvest sorting.
Strategic Opportunities
- Artisanal online channels:Direct-to-consumer platforms with blockchain traceability are capturing specialty buyers seeking single-origin documentation.
- FSSAI harmonization tailwind:India's alignment of domestic standards with Codex Alimentarius protocols reduces dual-certification burdens for export-oriented processors.
- Ready-meal heat customization:Frozen and shelf-stable meal manufacturers are specifying Scoville-calibrated chili inputs for regional flavor profiles.
Industry Challenges
- Skilled agronomist scarcity:Expertise in integrated pest management for capsaicin crop protection is concentrated among aging specialist cohorts in growing belts.
- Certification timeline compression:BIS and EFSA testing protocols now require sequential rather than parallel laboratory verification, extending lot-release cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Chilies Market |
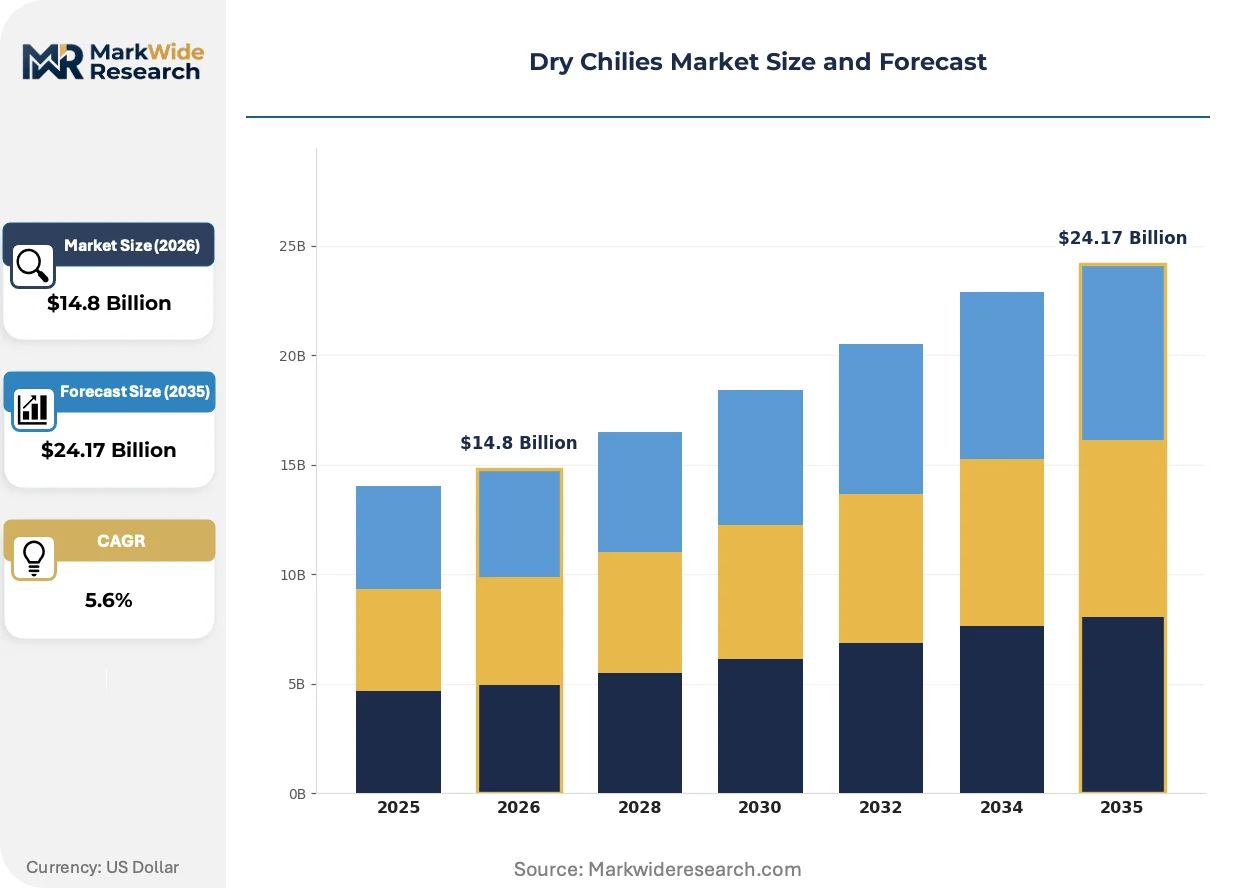
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.17 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Byadgi, Kashmiri, Paprika, Jwala End Use: Culinary, Food Processing, Sauces, Seasoning Distribution Channel: Online, Retail, Wholesale, Direct Sales Packaging Type: Bags, Jars, Pouches, Bulk |
| Companies Covered | Everest Food Products Pvt. Ltd., Cuihong, McCormick & Company, Inc, Swani Spice, Synthite Industries, Olam International Limited, Gansu Yasheng, Akay Spices, MDH Spices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Chilies Market Shifts & Advancements
Processing technology and compliance architecture are converging to redefine value capture in dried chili supply chains, with efficiency and traceability becoming inseparable competitive requirements.
Solar-assisted dehydration systems are overtaking conventional fuel-fired drying infrastructure in Indian and African processing hubs. Mid-scale cooperatives in Karnataka and Ethiopian growing zones are installing photovoltaic-thermal hybrid units to reduce energy input costs and stabilize moisture-content uniformity. This technology shift is compressing the cost advantage of large centralized dryers while enabling smaller processors to meet export-grade specifications.
REACH-aligned contaminant protocols are reshaping formulation choices for European-bound shipments. ECHA substance restrictions on specific pesticide categories are forcing exporters to substitute approved active compounds and maintain residue testing documentation across multiple laboratory chains. Sauce manufacturers serving EU retail channels are now requiring pre-shipment certificates from accredited third-party validators.
Traceability-driven procurement is displacing anonymous bulk purchasing among North American spice houses. Large food manufacturers are mandating farm-level geolocation data and harvest-date documentation for paprika and cayenne inputs. This behavioral shift is most visible in the organic and fair-trade certified segments, where origin storytelling commands measurable price premiums over commodity-grade alternatives.
Dry Chilies Market Segmentation
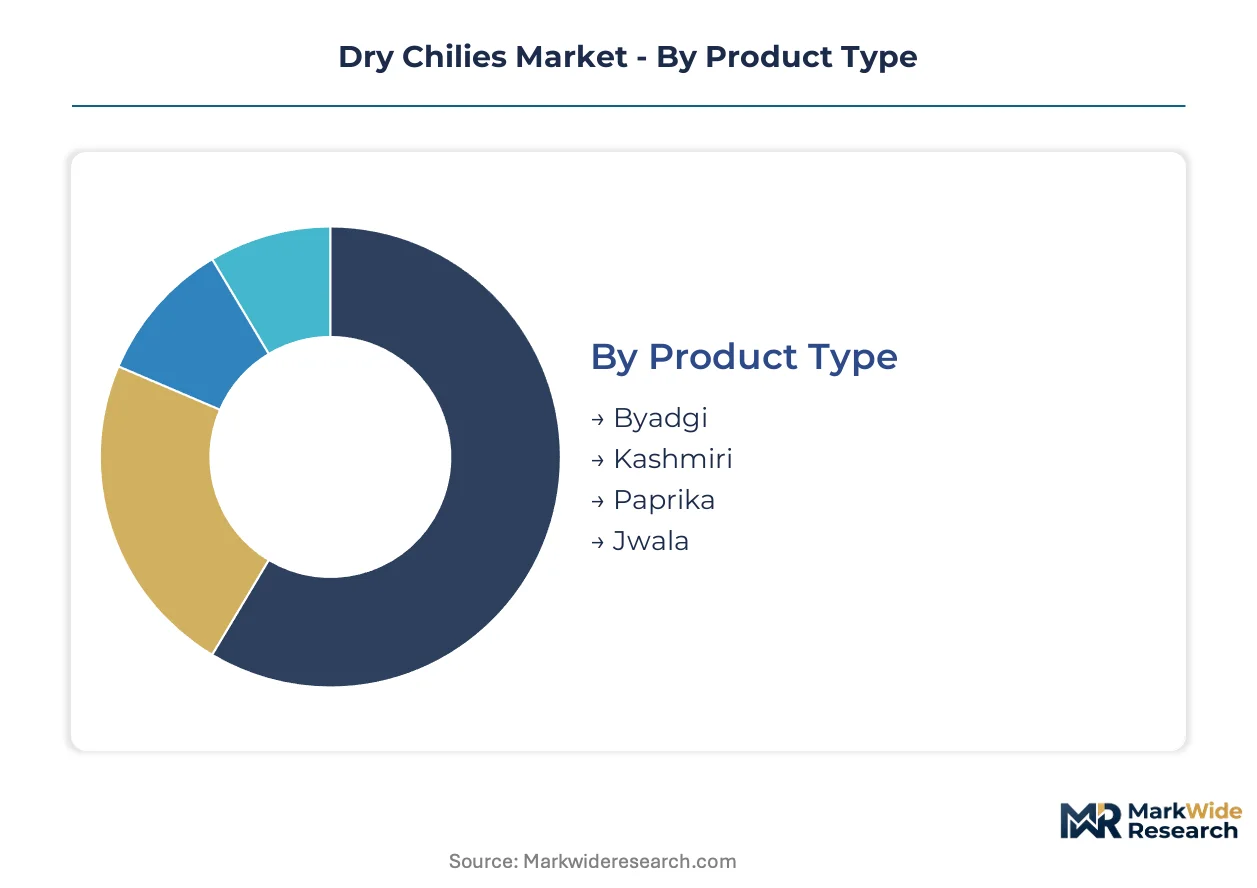
Dry chilies serve divergent buyer requirements across heat specification, color intensity, and formulation precision. Segmentation reveals how procurement patterns split between commodity-grade bulk supply and premium traceable inputs for branded food products.
Product Type:
Replacement cycles in industrial formulations drive variety selection, as sauce manufacturers recalibrate heat profiles to match regional taste thresholds.
- Paprika:Low-pungency Capsicum annuum varieties deliver standardized extractable pigment for color-intensive European and North American applications. Demand concentrates in smoked and sweet paprika grades where pigment value exceeds commodity heat pricing, with EFSA residue documentation now mandatory for EU-bound shipments.
- Byadgi:Deep-red Indian cultivar from Karnataka growing belts provides oleoresin extraction feedstock with measured capsaicin retention. Andhra Pradesh processors favor Byadgi for domestic masala supply chains where color depth commands premium positioning over pure heat intensity.
- Kashmiri:Mild-heat variety prized for visual appeal in North Indian cuisine and export-oriented ethnic food manufacturing.
- Jwala:High-pungency cultivar serving concentrated heat requirements in pickle and chutney segments.
Volume placements concentrate in Byadgi for domestic Indian processors; the faster expansion belongs to Paprika driven by European color-extraction demand.
End Use:
Application-specific formulation requirements split procurement between standardized industrial inputs and specialty-grade traceable supply.
- Food Processing:Industrial manufacturers of ready-meals, frozen foods, and snack seasonings specify Scoville-calibrated chili powders with batch-to-batch consistency. BIS moisture and aflatoxin thresholds determine supplier eligibility for India's domestic processors, while REACH-aligned protocols govern European-bound shipments.
- Sauces:Condiment formulators extract highest per-kilogram value through pungency precision and color stability specifications. McCormick and Everest Food Products anchor procurement in pre-certified Indian and African origin lots to satisfy retail channel compliance requirements.
- Culinary:Restaurant and institutional buyers prioritize cost-efficient bulk supply with regional heat profile familiarity.
- Seasoning:Blended spice manufacturers combine multiple chili varieties to achieve signature heat-color balances for branded retail lines.
Food Processing captures the deepest volume pools; Sauces deliver the steepest expansion trajectory as premium condiment lines proliferate.
Distribution Channel:
Channel selection reflects buyer scale, certification burden tolerance, and traceability documentation requirements.
- Wholesale:Aggregators in Guntur and Byadgi mandis move commodity-grade dried chilies in multi-tonne lots to domestic masala manufacturers and export processors. Price discovery operates through spot-market auctions with BIS certification as the primary quality gate.
- Direct Sales:Large food manufacturers bypass intermediaries to contract directly with Karnataka and Andhra Pradesh farmer-producer organizations, securing farm-level geolocation data and harvest-date documentation for EFSA-compliant European shipments.
- Online:Artisanal platforms with blockchain traceability serve specialty buyers seeking single-origin storytelling and organic certification.
- Retail:Packaged consumer brands distribute through supermarket and ethnic grocery networks for household culinary use.
Wholesale channels dominate absolute volume movement; Online distribution is climbing the fastest among specialty and certified-origin buyers.
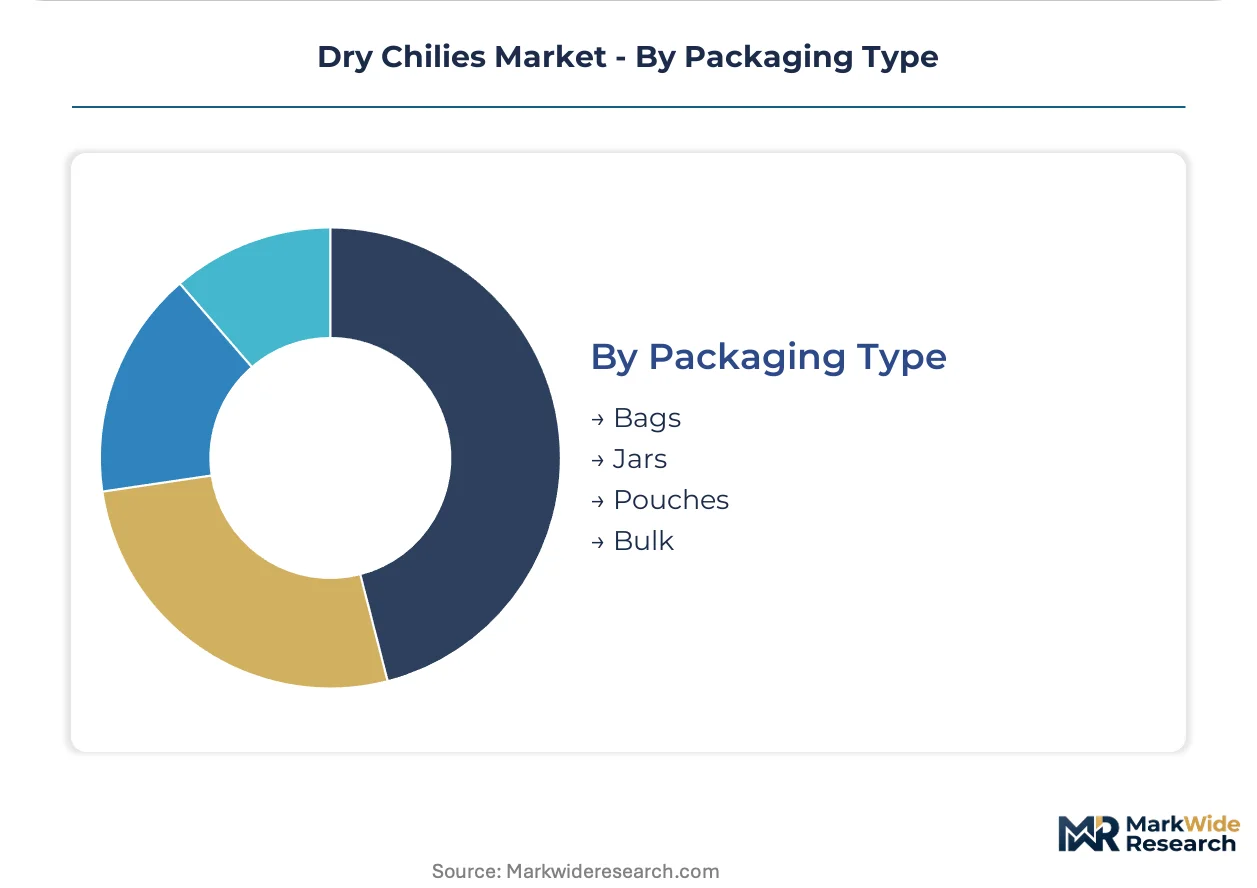
Packaging Type:
Packaging configuration aligns with moisture control requirements, handling scale, and end-user sophistication.
- Bulk:Loose jute or polypropylene sacks containing 25-50 kg serve industrial processors and spice grinding units with immediate consumption cycles. Karnataka cooperatives increasingly deploy hermetic liners within bulk sacks to suppress aflatoxin development during monsoon storage.
- Pouches:Laminated flexible packaging with oxygen barriers protects retail-grade chili powder from moisture ingress and color degradation. Everest Food Products and similar processors specify pouch formats for branded masala lines requiring extended shelf stability.
- Bags:Multi-wall paper or woven polypropylene containers serve institutional and foodservice buyers with intermediate volume requirements.
- Jars:Rigid glass or PET containers position premium whole-dried and flaked varieties for specialty retail and gift segments.
Bulk packaging commands the greatest tonnage throughput; Pouches are gaining share fastest as branded retail seasoning lines expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Andhra Pradesh's Guntur belt supplies the foundational raw material for global dried chili trade. Karnataka's Byadgi cultivation clusters anchor color-intensive oleoresin extraction. These Indian production zones feed processors across three continents with distinct compliance requirements.
India
Domestic masala manufacturers and export-oriented oleoresin extractors drive demand for Byadgi and Guntur Sannam varieties. FSSAI alignment with Codex Alimentarius protocols reduces dual-certification burdens for processors serving European and Gulf markets. Guntur's regulated mandis auction export-grade lots with BIS moisture documentation to Everest Food Products and Olam International sourcing teams.
United States
Specialty spice houses and hot sauce formulators seek Scoville-standardized inputs for regional heat profiles. FDA enforcement of FSMA preventive controls mandates supplier verification programs for imported dried chili lots. Texas and California-based blenders contract directly with Indian farmer-producer organizations to secure harvest-date traceability for retail channel compliance.
Germany
Paprika extractors serving Central European food colorant demand prioritize EFSA-compliant residue documentation. REACH-aligned contaminant protocols from ECHA restrict specific pesticide categories in incoming shipments. Hamburg and Frankfurt processing hubs validate Indian and African origin lots through accredited third-party laboratories before release to sauce manufacturers.
China
Domestic hot pot seasoning producers and pigment extraction facilities absorb Xinjiang and Shandong dried chili output. NMPA food additive standards govern capsaicinoid concentrate purity for pharmaceutical and nutraceutical applications. Zhengzhou and Qingdao trading clusters coordinate bulk procurement from Gansu Yasheng and regional cooperatives for industrial processing.
Spain
Smoked paprika formulators in Extremadura and Murcia defend geographic indication status against imported color substitutes. EU Green Deal agricultural protocols shape on-farm drying infrastructure investments in La Vera and Murcia growing zones. Valencia and Barcelona spice houses blend domestic Ñora varieties with imported Indian paprika to balance pigment yield and cost positioning.
Dry Chilies Market Competitive Landscape
Backward integration into agricultural zones dominates the current landscape as processors secure certified-origin supply pools against climate volatility. The vendor base splits between integrated spice houses with captive farming contracts and trading specialists with multi-origin sourcing networks. Three archetypes define positioning: vertically integrated processors controlling cultivation-to-grinding value chains, global traders optimizing geographic arbitrage across African and Asian belts, and regional specialists serving ethnic food channels with single-origin storytelling. Competitive moves concentrate on farm-level certification partnerships and solar-assisted drying infrastructure deployment.
Among India-based integrated processors, Everest Food Products Pvt. Ltd. and MDH Spices exemplify the backward-integration archetype with agricultural zone control. McCormick & Company, Inc. represents the global formulation specialist leveraging multi-origin blending to sustain consistent flavor profiles across regional product lines. Olam International Limited occupies the trading-network position with sourcing infrastructure spanning multiple growing belts to reduce single-origin concentration risk.
| Leading Market Players |
|---|
| Everest Food Products Pvt. Ltd. |
| Cuihong |
| McCormick & Company, Inc |
| Swani Spice |
| Synthite Industries |
| Olam International Limited |
| Gansu Yasheng |
| Akay Spices |
| MDH Spices |
| Others |
Supply & Pricing Matrix
Food processing companies in the sauces and seasoning segments anchor procurement volume and dictate contract structures. Their demand for EFSA-compliant documentation and batch-to-batch consistency rewards suppliers with pre-certified residue testing over spot-market alternatives.
Pricing Analysis
Certification-bundled contracts separate premium-tier paprika with full EFSA documentation from standard-grade Byadgi with BIS-only certification and unbundled economy lots lacking origin traceability. Price differentiation hinges on residue testing tier and solar-drying infrastructure investment. Cost compression in economy grades is intensifying because natural gas price spikes feed directly into conventional dehydration energy costs. Small-scale cooperatives show highest price sensitivity; multinational sauce manufacturers absorb premium-tier premiums for compliance security.
Supply Chain Analysis
Natural gas supply for dehydration energy draws from domestic Indian grids and imported LNG spot markets, while pigment-grade paprika seed stock rests on proprietary cultivar control in Karnataka and Murcia growing belts. Raw material dependencies include capsaicinoid-rich cultivars, hermetic packaging liners, and photovoltaic-thermal hybrid drying units. Single-origin concentration in Andhra Pradesh and Karnataka clusters creates geographic risk exposure from monsoon disruption. Distribution runs through Guntur mandi auctions for commodity grades and direct farmer-producer organization contracts for traceable premium tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solar-assisted dehydration technology is displacing conventional fuel-fired drying infrastructure. This transition rewards processors with captive renewable energy assets and punishes those locked into volatile natural gas input costs.
For Market Incumbents: Deploy backward integration into Karnataka and Andhra Pradesh agricultural zones to secure certified-origin supply pools. Incumbents must lock in FSSAI-Codex aligned dual-certification capacity before EFSA testing protocol timelines compress further. Solar-thermal hybrid drying infrastructure investment protects margin structure against natural gas price spike cycles.
For New Entrants and Emerging Players: Enter via blockchain-traceable artisanal online channels serving North American specialty spice houses seeking single-origin storytelling. The most penetrable white space sits in organic-certified paprika with farm-level geolocation data for EU retail compliance. A direct-to-consumer platform with harvest-date documentation offers the cleanest go-to-market angle.
For Investors and Strategic Acquirers: The window for entry favors mid-scale Indian processors with existing BIS certification infrastructure and untapped EFSA compliance capability. Long-term viability centers on supply chain control over dehydration energy inputs and cultivar development programs. Watch for EFSA maximum residue limit revisions as the inflection signal triggering accelerated consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Solar-Assisted Dehydration Deployment | Photovoltaic-thermal hybrid units in Karnataka reduce energy input costs and stabilize moisture-content uniformity for export-grade compliance. |
| Backward Integration into Agricultural Zones | Captive farming contracts in Andhra Pradesh secure certified-origin supply pools against climate-induced harvest volatility. |
| EFSA Pre-Certification Partnership | Accredited third-party laboratory validation in Hamburg and Frankfurt accelerates lot-release cycles for European-bound shipments. |
| Blockchain Traceability Implementation | Farm-level geolocation data and harvest-date documentation satisfy McCormick and Everest Food Products procurement mandates. |
| Dual-Certification Infrastructure Buildout | FSSAI-Codex alignment reduces dual-certification burdens for processors serving European and Gulf markets simultaneously. |
Research Methodology
Document review covered BIS quality standards documentation, EFSA pesticide residue protocols, and FSSAI regulatory filings, complemented by interviews with oleoresin extraction plant managers, procurement leads at sauce manufacturers, Karnataka cooperative technical directors, and Guntur mandi auction operators. Secondary validation drew from customs export data, FAO agricultural statistics, and CDSCO food additive registrations. Bottom-up cultivation area estimates and top-down processor consumption surveys were triangulated against trade flow records.
Segment-level value outputs across the projection horizon reflect calibrated assumptions for paprika, Byadgi, Kashmiri, and Jwala variety demand trajectories, disaggregated by food processing, sauces, culinary, and seasoning end uses, with distribution channel splits between wholesale mandi auctions, direct farmer-producer contracts, online artisanal platforms, and retail packaged goods. CAGRs were derived from trend extrapolation of climate-adjusted yield forecasts and regulatory compliance cost trajectories. Industry-specific inputs included solar-drying adoption curves and EFSA testing protocol timeline compression effects.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extreme monsoon disruption or sudden EFSA residue limit tightening. Forecasts reflect documented assumptions about energy price trajectories and certification harmonization timelines. A small set of triggers—natural gas price spike duration, EFSA protocol revision timing, and FSSAI enforcement intensity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Condiments
Frangipani Extract Market
Spices and Condiments
Japanese Curry Market
Spices and Condiments
Mustard Brown Extract Market
Spices and Condiments
Acacia Concinna Extracts Market
Spices and Condiments
Culinary Powder Market
Spices and Condiments
Savory Flavor Blends Market
Spices and Condiments
Peeled Garlic Market
Spices and Condiments
Asia-Pacific Dehydrated Onion Market
Spices and Condiments
Garlic Extract Market
Spices and Condiments
Global Pickles and Pickle Products Market
Spices and Condiments
Gourmet Salts Market
Spices and Condiments
Cayenne Pepper Market
Spices and Condiments
Geranium Oil Market
Spices and Condiments
Dehydrated Garlic Market
Spices and Condiments
Gravy Mixes Market
Spices and Condiments
Middle East and Mediterranean Tahini Market