
 Global Pickles and Pickle Products Market | 2026-2036
Global Pickles and Pickle Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pickles and Pickle Products Market Outlook
Clean-label fermentation is narrowing the technology gap between artisanal producers and mass-market brands. The Kraft Heinz Company leverages its refrigerated supply chain to extend distribution reach for fresh-pack pickles. Mt. Olive Pickle Company anchors its position through vertical control over cucumber sourcing across the southeastern United States. ADF Foods Limited specializes in ethnic pickle formats that compete in diaspora markets across the United Kingdom and Canada.
Pickles and pickle products comprise vegetables preserved through brine fermentation or acidification, achieving pH levels below 4.6 to inhibit pathogenic growth and deliver tangy flavor profiles. The primary commercial purpose centers on shelf-stable condiment supply for retail and foodservice channels requiring minimal cold-chain dependency. Dill pickles occupy the largest volume position among product types, while pickled vegetables represent the fastest-expanding margin pool as Asian and Mediterranean cuisines penetrate Western supermarkets. Glass jars dominate premium positioning in distribution channels, though pouches are gaining traction in online retail for their reduced shipping weight and breakage rates.
The FDA enforces acidified food regulations under 21 CFR 114, mandating scheduled process filings for all pickle manufacturers selling in the United States. EFSA evaluates sodium reduction claims across European pickle imports, influencing reformulation targets for exporters targeting EU member states. India's FSSAI maintains separate standards for traditional fermented pickles versus chemically preserved variants, creating compliance complexity for multinational entrants. Stakeholders must monitor evolving front-of-pack labeling requirements in multiple jurisdictions, as salt-content disclosure rules reshape consumer purchase patterns and retail placement priorities.
Market Dynamics
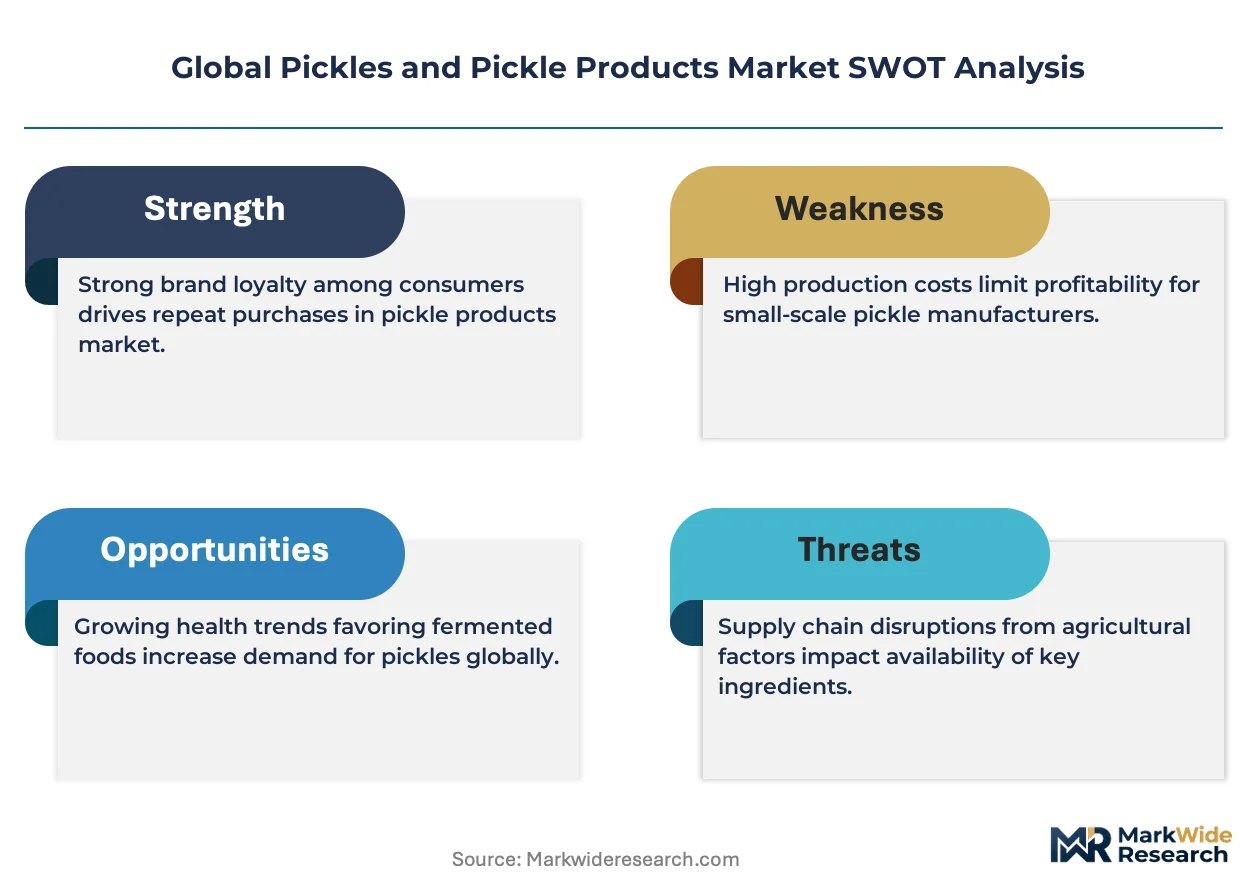
Clean-label fermentation technology is compressing the cost gap between artisanal pickle producers and mass-market manufacturers, forcing incumbents to retool processing lines or cede premium shelf space to craft brands with authentic probiotic positioning.
Growth Catalysts
- EFSA sodium-reduction guidance:European reformulation mandates are accelerating clean-label R&D investments, pushing manufacturers toward natural acidification methods that preserve taste without salt overload.
- Foodservice gut-health menus:North American restaurant chains are expanding fermented vegetable placements as consumer demand for digestive wellness intersects with chef-driven flavor innovation.
- India organized retail penetration:Modern trade expansion in tier-2 and tier-3 Indian cities is creating standardized distribution channels for traditional pickle formats previously confined to unorganized outlets.
Market Restraints
- Cucumber supply concentration:Southeastern United States growing regions face climate volatility that disrupts raw material availability for fresh-pack processors dependent on specific harvest windows.
- FSSAI dual-standard complexity:India's separate compliance pathways for fermented versus chemically preserved pickles create regulatory friction for multinational entrants attempting unified product portfolios.
- Refrigerated distribution cost structure:Cold-chain requirements for fresh-pack variants impose margin pressure that shelf-stable competitors avoid, limiting geographic expansion for premium refrigerated lines.
Strategic Opportunities
- United Kingdom diaspora channels:Ethnic grocery formats serving South Asian populations represent underpenetrated white space for authentic regional pickle varieties beyond standard mango and lime offerings.
- Pouch packaging innovation:E-commerce optimized flexible formats are displacing glass jars in online retail, reducing breakage rates and shipping weights for direct-to-consumer penetration.
- PLI scheme alignment:India's production-linked incentive framework for food processing offers capital subsidy pathways for domestic manufacturing scale-up of export-oriented pickle operations.
Industry Challenges
- Scheduled process filing timelines:FDA 21 CFR 114 compliance requires extensive laboratory validation that delays new product launches by 12-18 months for acidified food entrants.
- Legacy equipment retrofit costs:Sodium-reduction processing demands stainless steel tank upgrades and pH monitoring systems that strain mid-tier manufacturer capex budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pickles and Pickle Products Market |
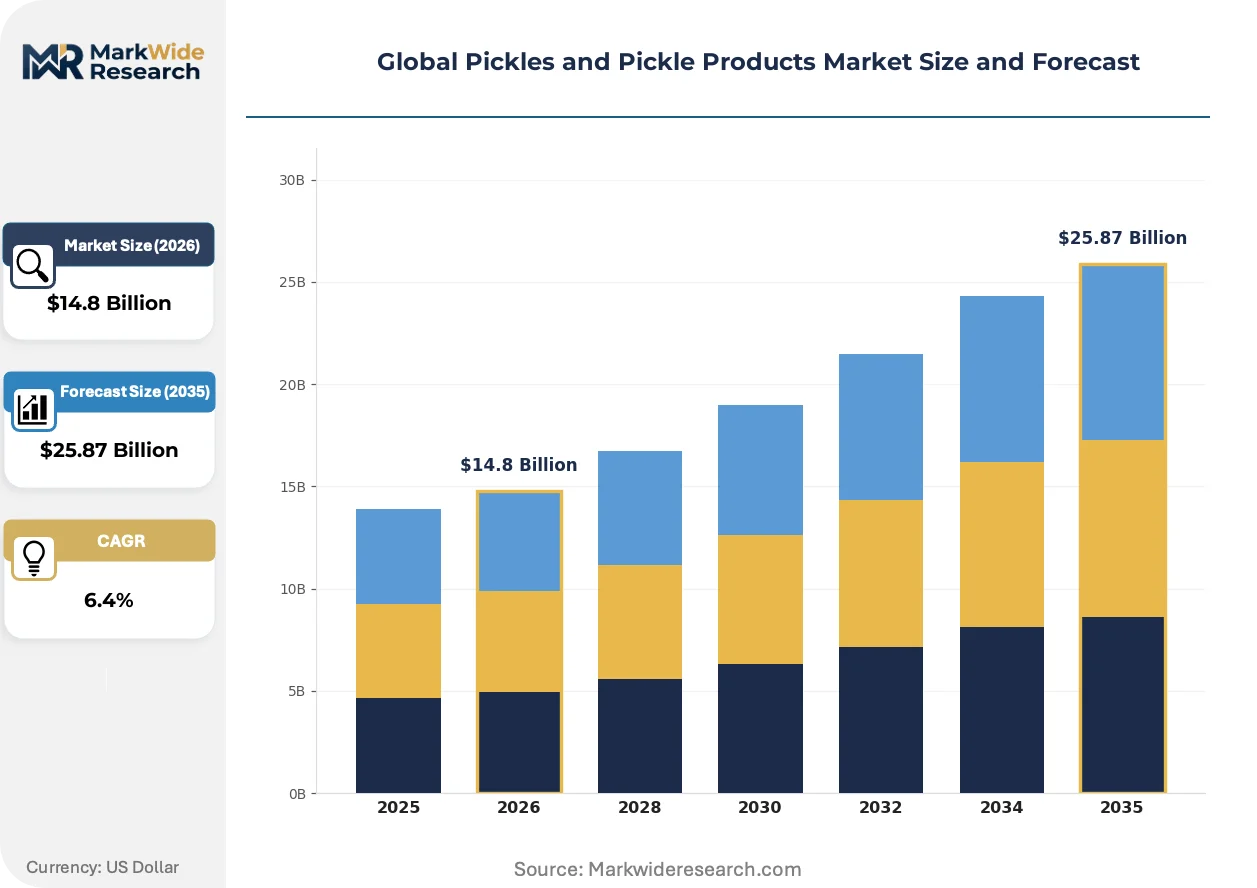
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweet Pickles, Dill Pickles, Gherkins, Pickled Vegetables Packaging Type: Glass Jars, Plastic Containers, Pouches, Tubs Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Farmers' Markets End User: Household, Restaurants, Food Manufacturers, Catering Services |
| Companies Covered | Del Monte Foods, ADF Foods Limited, The Kraft Heinz Company, Grillo's Pickles, Vlasic, Mt. Olive Pickle Company, Conagra Brands, Orkla ASA, B&G Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pickles and Pickle Products Market Strategic Shifts
Fermentation science and packaging engineering are converging to reshape competitive positioning, with shelf-stable probiotic claims and lightweight distribution formats emerging as the primary vectors of differentiation.
Controlled fermentation technology is hybridizing traditional anaerobic preservation with precision temperature and humidity monitoring. Large-scale manufacturers in Germany and Japan are deploying sensor-equipped brine tanks that replicate artisanal conditions at industrial volume. This convergence is compressing the authenticity premium that craft producers previously commanded in Western European supermarkets.
REACH chemical safety evaluations are tightening scrutiny on processing aids and residual sanitizers in European pickle imports. EFSA is requiring expanded toxicological data for acidification accelerators previously deemed GRAS, forcing exporters to reformulate with natural starter cultures. Mediterranean and Eastern European suppliers are responding by certifying traditional fermentation methods as additive-free alternatives.
Restaurant procurement patterns are fragmenting as independent operators bypass broadline distributors for direct relationships with regional fermenteries. Chefs in California and New York are specifying small-batch pickle varieties with transparent ingredient sourcing, displacing standardized foodservice packs. This disintermediation is most visible in fast-casual chains where menu differentiation drives supplier selection over contract pricing.
Global Pickles and Pickle Products Market Segmentation
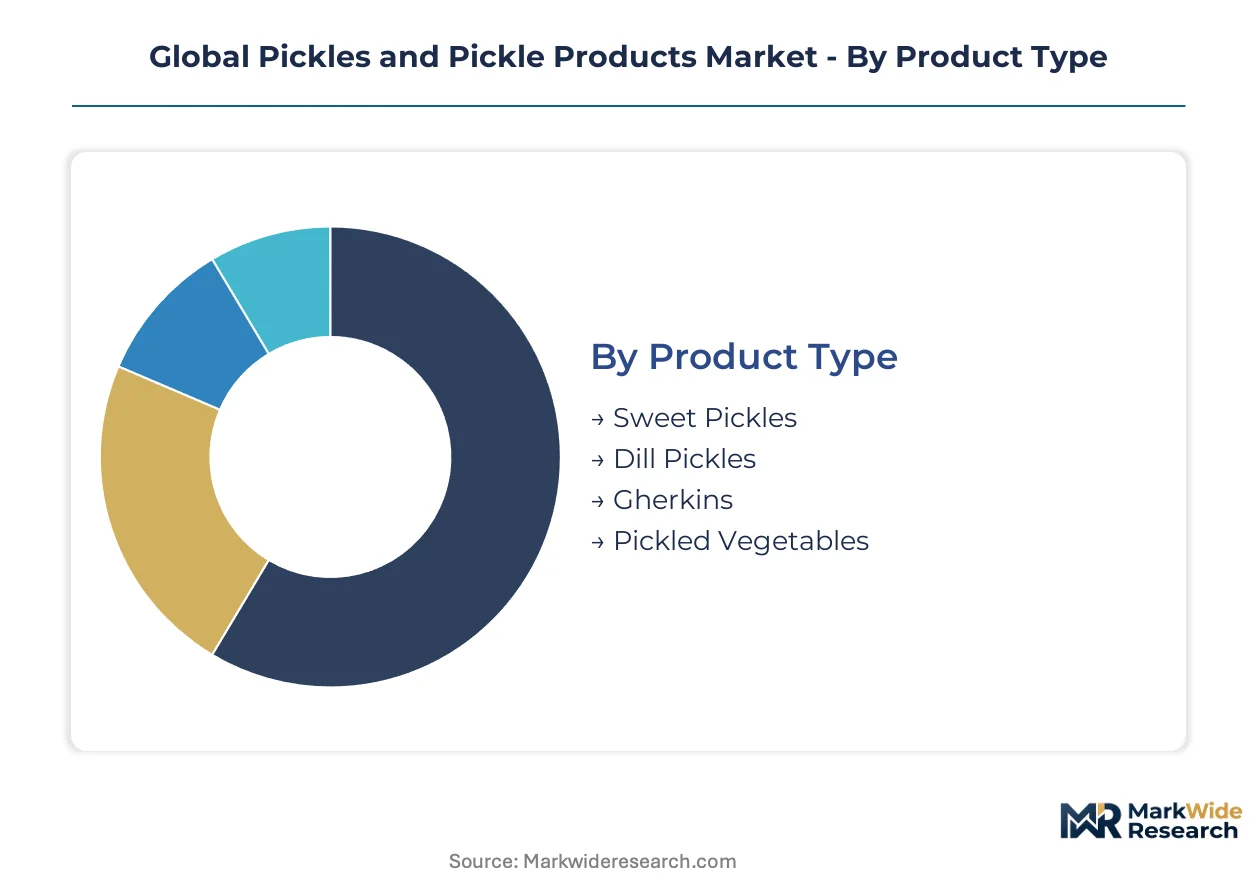
Pickle market segmentation reveals divergent growth mechanics across preservation chemistry, material science, and channel economics. Understanding these fault lines exposes where capital deployment and R&D investment generate asymmetric returns.
Product Type:
Mature segments dominate volume while emerging formats capture margin expansion through health-positioning premiums.
- Dill Pickles:Fermented cucumber varieties rely on Lactobacillus-driven acidification to achieve pH below 4.6 without vinegar addition. Demand concentrates in the United States, where refrigerated fresh-pack variants command shelf space in conventional grocery. FDA 21 CFR 114 scheduled process requirements constrain rapid format innovation.
- Pickled Vegetables:Non-cucumber preservation spans carrots, cauliflower, beets, and mixed Asian vegetables in rice bran or vinegar solutions. Demand concentrates in India and Japan, where traditional fermentation intersects with export-oriented clean-label positioning. EFSA sodium-reduction guidance accelerates natural acidification R&D.
- Sweet Pickles:Sugar-acid balance preserved through pasteurization rather than fermentation, targeting sandwich condiment and relish applications. Shelf-stable processing suits mass-market retail placement.
- Gherkins:Small-format cucumbers harvested pre-maturity for dense texture, predominantly sourced from India and Eastern Europe for European Union import markets. Size grading determines foodservice versus retail channel allocation.
Dill pickles retain volume leadership; pickled vegetables hold the steepest expansion curve.
Packaging Type:
Cost tier stratification separates premium glass positioning from economy plastic and emerging flexible formats.
- Glass Jars:Inert material preserves flavor integrity across multi-year shelf life while supporting premium brand aesthetics and visible product quality. Supermarkets and specialty stores favor transparent packaging for consumer inspection.
- Pouches:Multilayer flexible films reduce shipping weight by 60-70% versus glass, enabling e-commerce economics and direct-to-consumer subscription models. Breakage elimination supports last-mile delivery optimization.
- Plastic Containers:Polypropylene tubs and PET jars balance cost efficiency with moderate barrier properties for short-shelf-life refrigerated pickles. Foodservice bulk formats favor stackable geometry.
- Tubs:High-density polyethylene containers target food manufacturer and catering bulk procurement with resealable lids and pallet-optimized dimensions.
Glass jars anchor premium positioning; pouches are expanding most quickly through digital channels.
Distribution Channel:
Customer type fragmentation separates mass-market convenience seekers from experience-driven and procurement-specialized buyers.
- Supermarkets:Conventional grocery chains dominate volume throughput with standardized planogram placement, private-label competition, and promotional calendar dependency. Slotting fees and category management discipline favor incumbent brands.
- Online Retail:Digital-native brands bypass traditional retail gatekeepers through direct fulfillment, subscription mechanics, and review-driven discovery. Packaging innovation and logistics integration determine unit economics.
- Specialty Stores:Ethnic grocers, natural food cooperatives, and gourmet retailers curate regional varieties and small-batch producers for diaspora communities and culinary enthusiasts.
- Farmers' Markets:Direct producer-to-consumer channels support seasonal fresh-pack sales, transparent sourcing narratives, and price premiums for local provenance claims.
Supermarkets retain volume leadership; online retail holds the steepest expansion curve.
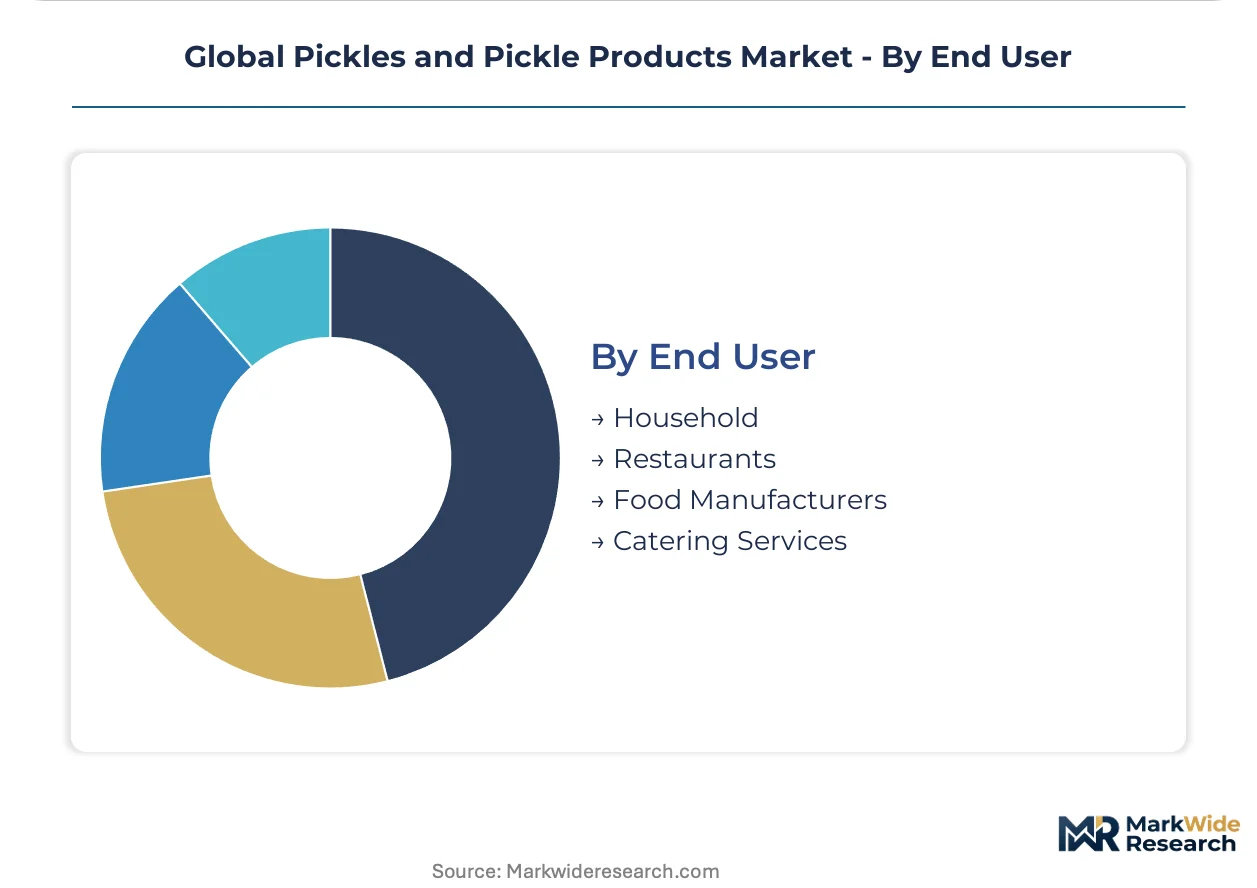
End User:
Application diversity spans consumption occasion and procurement sophistication, from household pantry stocking to industrial ingredient sourcing.
- Restaurants:Foodservice operators specify pickle varieties for menu differentiation, with fast-casual chains driving fermented vegetable placement for gut-health positioning. Direct supplier relationships displace broadline distributor intermediation.
- Household:Retail consumers purchase for home consumption across sandwich condiment, snacking, and cooking ingredient use cases. Brand loyalty and price sensitivity vary by demographic and cuisine tradition.
- Food Manufacturers:Industrial buyers source bulk pickles for further processing into sauces, relishes, and prepared meal components, with specification-driven procurement emphasizing consistency and food safety certification.
- Catering Services:Event and institutional food providers require shelf-stable, portion-controlled formats for large-scale service with minimal preparation labor.
Household consumption retains volume leadership; restaurants hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports traditional fermented pickles to diaspora communities across the United Kingdom and Canada, creating a specialized trade corridor that connects heritage production methods with organized retail penetration in Western markets.
United States
Refrigerated fresh-pack pickles command premium shelf space in conventional grocery, with fast-casual restaurant chains driving fermented vegetable placement for gut-health menu differentiation. FDA enforces 21 CFR 114 scheduled process filings that constrain rapid product innovation. North Carolina's cucumber-growing belt anchors fresh-pack processing capacity for national distribution.
Germany
Sensor-equipped brine tank technology replicates artisanal fermentation conditions at industrial scale, compressing authenticity premiums previously commanded by craft producers. EFSA sodium-reduction guidance accelerates natural acidification R&D investments. Bavaria's food processing clusters host precision fermentation equipment manufacturers serving EU-wide pickle operations.
India
Organized retail expansion into tier-2 and tier-3 cities creates standardized distribution channels for traditional pickle formats previously confined to unorganized outlets. FSSAI maintains separate compliance pathways for fermented versus chemically preserved variants, creating regulatory friction for multinational entrants. Gujarat and Maharashtra house concentrated manufacturing capacity for mango and lime pickle exports.
United Kingdom
Ethnic grocery formats serving South Asian populations represent underpenetrated white space for authentic regional pickle varieties beyond standard mango and lime offerings. EFSA evaluates sodium reduction claims across European pickle imports, influencing reformulation targets for exporters. London's wholesale distribution hubs connect Indian subcontinent suppliers with nationwide specialty retail networks.
Japan
Traditional rice bran fermentation methods for pickled vegetables intersect with export-oriented clean-label positioning for Western health-conscious consumers. METI supports food processing technology exports that include precision fermentation monitoring systems. Nagoya's industrial corridor hosts automated pickling equipment manufacturers supplying domestic and Asian markets.
Global Pickles and Pickle Products Market Competitive Environment
Channel-controlling players compete with product-specialist players across refrigerated and shelf-stable segments, creating a tiered structure where mass-market brands defend retail shelf space against craft fermenteries pursuing direct-to-consumer penetration. The market fragments across three strategic archetypes: vertically integrated cucumber processors, ethnic format specialists serving diaspora channels, and digital-native brands leveraging pouch packaging for e-commerce optimization. Dominant competitive moves include backward integration into agricultural sourcing and strategic partnerships with restaurant chains for menu placement.
Among North American processors, The Kraft Heinz Company and Mt. Olive Pickle Company occupy positions that exemplify contrasting supply chain strategies, while ADF Foods Limited represents the ethnic specialist archetype targeting diaspora markets across the United Kingdom and Canada.
| Leading Market Players |
|---|
| Del Monte Foods |
| ADF Foods Limited |
| The Kraft Heinz Company |
| Grillo's Pickles |
| Vlasic |
| Mt. Olive Pickle Company |
| Conagra Brands |
| Orkla ASA |
| B&G Foods |
| Others |
Value Chain & Pricing Dynamics
North Carolina's cucumber-growing belt anchors fresh-pack processing capacity that shapes downstream pricing power across United States refrigerated pickle segments. Seasonal harvest volatility in this southeastern cluster compresses margins for processors dependent on narrow procurement windows while amplifying price premiums for shelf-stable competitors with diversified sourcing.
Pricing Analysis
Fresh-pack versus fermented-generation pricing gaps separate refrigerated premium tiers from shelf-stable economy positioning. Three-tier pricing structure across premium refrigerated, standard shelf-stable, and economy private-label levels stratifies the market, with brand heritage and probiotic certification commanding measurable uplifts. Pricing pressure stems from sodium-reduction reformulation costs that strain mid-tier manufacturer capex budgets. Foodservice buyers exhibit lowest price sensitivity due to menu differentiation requirements, while mass-market retail consumers gravitate toward promotional private-label alternatives.
Supply Chain Analysis
Contract-manufacturing concentration for acidified food processing rests with specialized facilities in India, Germany, and Japan that hold FDA 21 CFR 114 scheduled process validation. Raw material dependencies center on cucumber cultivars from southeastern United States growing regions, vinegar supply from industrial fermentation operations, and glass packaging from specialized container manufacturers. Single-source vulnerability concentrates in fresh-pack cucumber procurement tied to climate-exposed harvest windows. Distribution runs through refrigerated and ambient networks that bifurcate between cold-chain-dependent fresh formats and shelf-stable alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics anchored to organized retail penetration waves in emerging consumption centers. India's tier-2 and tier-3 city expansion drives the current upswing phase.
For Market Incumbents: Build captive cucumber supply moats through backward integration into southeastern United States agricultural operations or long-term offtake agreements with Gujarat and Maharashtra processing clusters. Sodium-reduction R&D investment and FSSAI dual-standard compliance capability defend against craft fermentery encroachment and multinational entrant disruption. Cold-chain optimization and pouch packaging adoption preserve margin structure against refrigerated distribution cost pressures. For New Entrants and Emerging Players: United Kingdom ethnic grocery channels serving South Asian diaspora populations represent the most penetrable white space for authentic regional pickle varieties beyond standardized mango and lime formats. India's PLI scheme-aligned manufacturing subsidies offer capital-efficient scale-up pathways for export-oriented operations. Direct-to-consumer subscription models leveraging pouch packaging innovation bypass supermarket slotting fee barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision fermentation equipment manufacturers and clean-label processing technology providers over commodity packagers. Long-term viability across the analysis window rests on probiotic shelf-stable capability and regulatory compliance infrastructure. Acquisition target archetypes include ethnic format specialists with established diaspora distribution and sensor-equipped brine tank technology developers. Quarterly review of FDA scheduled process filing backlogs and EFSA sodium-reduction enforcement patterns is advised to detect inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cucumber Sourcing | Captive agricultural supply from North Carolina growing regions insulates processors against climate-driven harvest volatility. |
| Pouch Packaging Format Transition | Flexible film adoption reduces e-commerce shipping weights and breakage rates for direct-to-consumer penetration. |
| Clean-Label Fermentation Technology Deployment | Sensor-equipped brine tanks replicate artisanal conditions at industrial volume, compressing craft authenticity premiums. |
| FSSAI Dual-Standard Compliance Investment | Unified product portfolios across fermented and chemically preserved pathways unlock Indian organized retail expansion. |
| Restaurant Chain Direct Partnership | Fast-casual menu placement for gut-health positioning displaces broadline distributor intermediation. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pickle processing plant managers, retail category buyers at supermarket chains, foodservice procurement directors, and regulatory affairs specialists at acidified food manufacturers. Secondary validation drew from FDA 21 CFR 114 scheduled process filings, FSSAI compliance bulletins, EFSA sodium-reduction guidance documents, and customs trade data for pickle product flows. Bottom-up volume modeling triangulated against top-down market sizing across preservation chemistry, packaging format, and distribution channel dimensions.
Calibration against historical volume trajectories and regulatory implementation timelines anchored the analytical framework across the projection horizon. Segmentation modeling spanned product type, packaging material science, channel economics, and end-user application sophistication. CAGRs were derived from trend extrapolation adjusted for regulatory catalyst timing and retail infrastructure buildout patterns. Forecast inputs incorporated PLI scheme disbursement schedules and EFSA enforcement intensity assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Indian export-oriented processors or accelerated FDA filing clearances would shift outcomes. Unmodeled risks include REACH chemical safety evaluation tightening on processing aids and climate disruption in southeastern United States cucumber regions. Quarterly review of organized retail penetration metrics in Indian tier-2 cities and refrigerated distribution cost indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Condiments
Asia-Pacific Dehydrated Onion Market
Spices and Condiments
Savory Flavor Blends Market
Spices and Condiments
Middle East and Mediterranean Tahini Market
Spices and Condiments
Middle East and Africa Vanilla Beans and Extract Market
Spices and Condiments
Rosemary Extracts Market
Spices and Condiments
Cayenne Pepper Market
Spices and Condiments
Dry Chilies Market
Spices and Condiments
Culinary Powder Market
Spices and Condiments
Gravy Mixes Market
Spices and Condiments
Fermented Mediterranean Pepper and Tomato Complexes Market
Spices and Condiments
Geranium Oil Market
Spices and Condiments
Garlic Extract Market
Spices and Condiments
Mustard Brown Extract Market
Spices and Condiments
Frangipani Extract Market
Spices and Condiments
Europe Dehydrated Onion Market
Spices and Condiments
Global Dehydrated Onion Market