
 Dehydrated Garlic Market | 2026-2036
Dehydrated Garlic Market Size, Share, and Industry Trends Forecast 2026-2036
Dehydrated Garlic Market Analysis
Fresh garlic paste is restructuring ingredient economics across commercial kitchens as dehydration technology narrows the flavor gap while slashing cold-chain costs. Kings Dehydrated Foods Pvt. Ltd. leverages its Indian supply base to dominate bulk powder exports into European food processing. Olam Food Ingredients sustains vertical integration from farm-level sourcing through industrial grinding operations in multiple hemispheres. Shandong Key Foods Co., Ltd anchors the granules segment with Shandong province's dense garlic cultivation belt.
Dehydrated garlic comprises Allium sativum bulbs processed through air-drying, freeze-drying, or vacuum dehydration to moisture levels below 6%, yielding shelf-stable products with concentrated allicin-derived flavor compounds for seasoning and food manufacturing. Powder commands the largest volume share due to its dispersion properties in dry soup mixes and spice blends, while flakes retain structural integrity in premium visual applications such as artisan bread toppings. Granules occupy a mid-tier position where rapid hydration matters for sauce and dressing formulations.
USDA grading standards and FDA food safety regulations govern moisture content and microbial thresholds for dehydrated garlic entering the United States, while China's GB standards and the EU's contamination limits under EFSA oversight shape export-access requirements for Asian producers. India's FSSAI mandates labeling and additive restrictions that processors must navigate for domestic retail distribution. Stakeholders should monitor evolving pesticide maximum residue limits across destination markets as these thresholds increasingly determine supplier eligibility and testing cost burdens.
Market Dynamics
Low-temperature dehydration technology is compressing the cost-performance gap between fresh and processed garlic, redirecting procurement decisions across commercial kitchens and food manufacturing toward shelf-stable formats while cold-chain economics deteriorate.
Growth Catalysts
- Clean-label mandates:EFSA contamination limits and tightening EU pesticide thresholds push manufacturers toward controlled dehydration supply chains with documented residue testing protocols.
- Ready-to-eat meal expansion:Powdered garlic dispersion properties accelerate adoption in North American dry soup and sauce manufacturing where hydration speed determines production line throughput.
- Freeze-drying advances:Vacuum microwave dehydration preserves allicin-derived compounds at rates matching fresh paste, unlocking premium positioning in functional food categories.
Market Restraints
- Input cost volatility:Raw garlic bulb prices swing with Shandong province weather patterns and Indian monsoon timing, compressing processor margins without forward-contract coverage.
- Supply concentration risk:Three provinces in China account for the majority of global dehydrated garlic raw material, creating single-origin vulnerability to trade flow disruptions.
- Substitution pressure:Fresh garlic paste refrigerated distribution improvements and aseptic packaging narrow the convenience gap for high-volume foodservice operators.
Strategic Opportunities
- Southeast Asian penetration:Vietnam and Indonesia processed food sectors remain underpenetrated by standardized dehydrated garlic formats, offering first-mover positioning for quality-certified suppliers.
- Pharmaceutical extraction demand:Allicin concentrate applications in nutraceuticals create premium pricing tiers for processors with pharmaceutical-grade certification infrastructure.
- E-commerce ingredient channels:Direct-to-manufacturer platforms bypass traditional spice broker networks, capturing margin compression and accelerating sample-to-contract velocity.
Industry Challenges
- Regulatory testing timelines:USDA and FDA microbial threshold verification for each export lot extends working capital cycles and delays revenue recognition.
- Equipment specialization gaps:Vacuum dehydration technicians with simultaneous process engineering and food safety audit experience command scarcity premiums in hiring markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dehydrated Garlic Market |
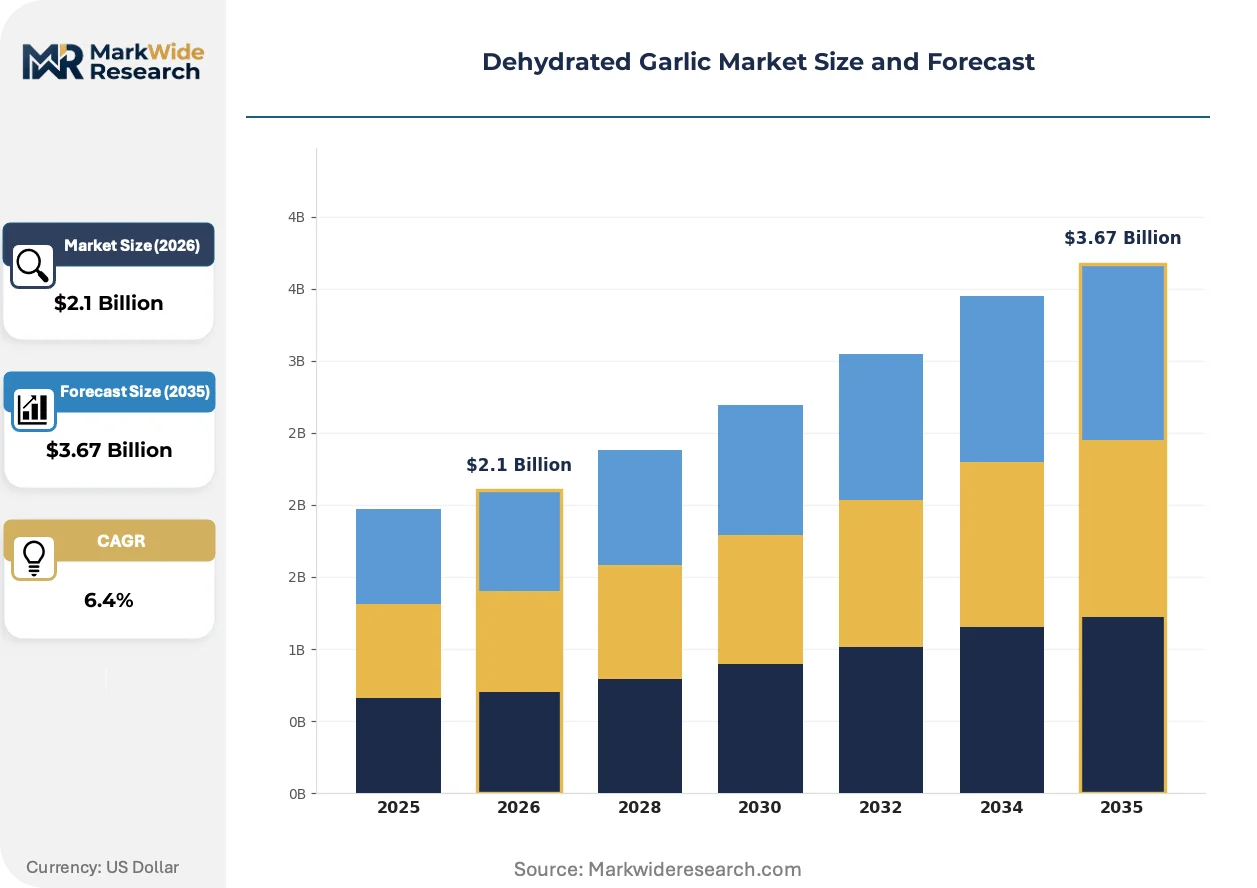
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Minced, Granules, Powder, Flakes Packaging Type: Bags, Jars, Bulk, Sachets Distribution Channel: Online, Supermarkets, Wholesale, Specialty Stores End User: Food Processing, Restaurants, Households, Catering Services |
| Companies Covered | Jiyan Food Ingredients, Kings Dehydrated Foods Pvt. Ltd., ShunDi Foods, Sensient Natural Ingredients, Olam Food Ingredients, Shandong Key Foods Co., Ltd, Garlico Industries Ltd., Chiping ShengKang Foodstuff Co. Ltd, Laiwu Manhing Vegetables Fruits Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dehydrated Garlic Market Emerging Trajectories
Processing technology convergence with quality verification systems is redefining competitive differentiation, while regulatory fragmentation across import jurisdictions forces adaptive compliance architectures.
Infrared-assisted dehydration is converging with real-time moisture sensors to enable precision endpoint detection without batch interruption. Mid-tier processors in India and China are retrofitting existing air-drying lines with this hybrid approach to meet EU and US moisture specifications without full equipment replacement. The technology is converging with blockchain-based batch documentation, compressing audit timelines and reducing rejection rates at destination ports.
REACH substance restrictions and evolving EU Green Deal agricultural input standards are tightening acceptable pesticide residue catalogs for dehydrated garlic entering European markets. Processors must now maintain dual testing protocols—one for legacy markets, one for EU compliance—adding fixed cost burdens that favor scaled operators with captive laboratory capacity. German and Dutch import distributors are consolidating supplier lists to those with pre-certified EU compliance, marginalizing smaller processors without dedicated regulatory affairs functions.
Long-term contracting is displacing spot market purchasing among North American seasoning blend manufacturers seeking supply security amid raw material volatility. Three-to-five year offtake agreements with fixed escalators now dominate procurement for volume buyers above fifty metric tons annually, compressing spot market liquidity and price discovery transparency. This shift is most visible in United States dry soup and sauce manufacturing, where procurement departments prioritize supply continuity over quarterly price optimization.
Dehydrated Garlic Market Segmentation
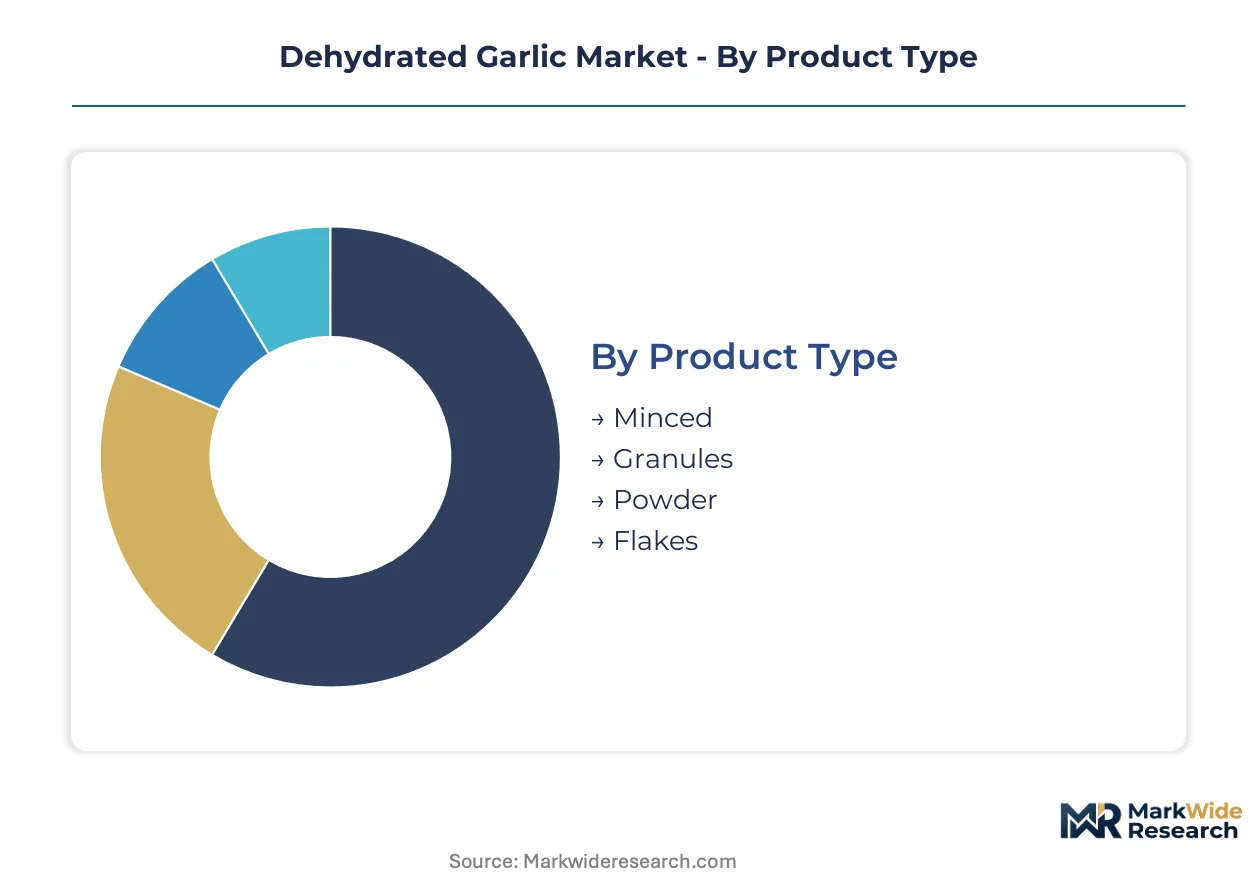
Segmentation in the dehydrated garlic market determines procurement economics, shelf-life requirements, and regulatory compliance pathways. Powder and granules command industrial volumes, while flakes and minced formats serve visual and texture-specific applications where structural integrity commands premium positioning.
Product Type:
Dehydration technology intensity and particle geometry define performance boundaries across commercial and consumer use cases.
- Powder:Finely ground particles below 0.5mm enable rapid dispersion in dry soup bases and seasoning blends. United States dry sauce manufacturers prioritize powder for hydration speed on high-throughput production lines, though dust handling requirements add capital cost for processors.
- Granules:Intermediate particle size between 0.5mm and 2mm balances rehydration velocity with flowability in automated dispensing systems. Shandong province processors dominate granule exports into European condiment manufacturing where EFSA moisture specifications favor controlled dehydration protocols.
- Flakes:Sliced and dried garlic pieces retain visual identity for artisan bread toppings and premium retail packaging.
- Minced:Coarse-cut particles suit foodservice applications requiring fresh-garlic texture simulation.
Powder leads on scale; granules lead on momentum across industrial procurement channels.
Packaging Type:
Packaging format selection tracks end-use volume thresholds and moisture protection requirements through distribution.
- Bulk:Industrial totes and fiber drums above 20kg dominate food manufacturing procurement in China and India, where processors supply ingredient departments directly. Shandong Key Foods and Kings Dehydrated Foods anchor this segment with captive logistics networks reducing intermediate handling.
- Bags:Multi-layer laminate pouches with oxygen barriers serve mid-volume food processing and foodservice redistribution, particularly in North American wholesale channels where shelf stability extends distributor inventory cycles.
- Jars:Glass and PET containers target retail households and specialty culinary stores.
- Sachets:Single-serve packets align with institutional catering and airline meal specifications.
Bulk commands volume concentration; bags gain share fastest in intermediate distribution tiers.
Distribution Channel:
Channel structure reflects buyer sophistication, order scale, and regulatory documentation requirements.
- Wholesale:Direct processor-to-manufacturer relationships dominate volume flows above fifty metric tons annually, with three-to-five year offtake agreements displacing spot purchasing among United States seasoning blend manufacturers seeking supply security.
- Supermarkets:Retail shelf placement requires FSSAI, FDA, or EFSA compliance documentation depending on jurisdiction, favoring scaled processors with captive laboratory capacity.
- Online:Direct-to-manufacturer platforms bypass traditional spice broker networks, compressing margin capture and accelerating sample-to-contract velocity for mid-tier buyers.
- Specialty Stores:Gourmet and ethnic retail channels emphasize origin labeling and organic certification premiums.
Wholesale anchors volume throughput; online channels climb the fastest in contract velocity metrics.
End User:
End-use segmentation separates commodity ingredient demand from value-added formulation requirements.
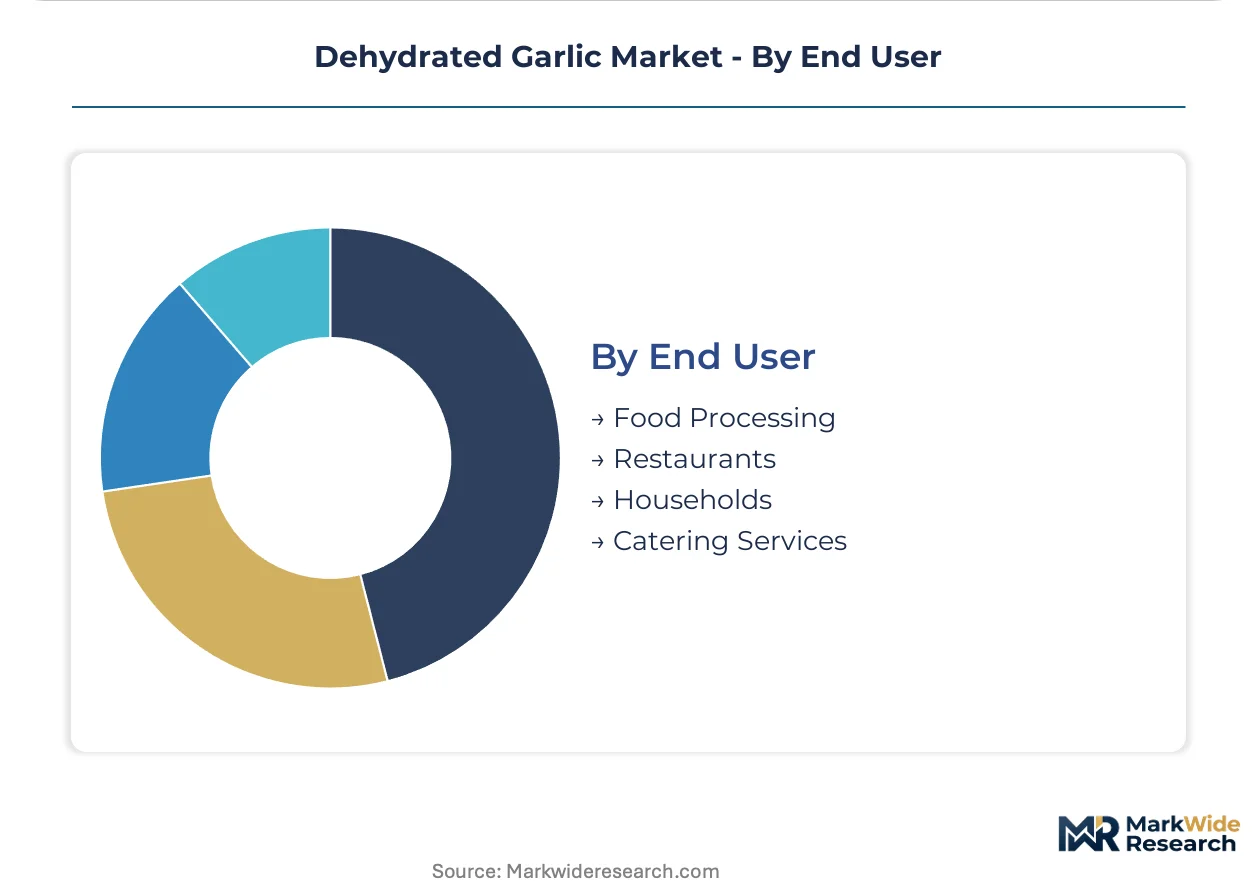
- Food Processing:Dry soup, sauce, and ready-meal manufacturers constitute the largest volume sink, with powdered garlic dispersion properties determining production line throughput. Clean-label mandates from EFSA and FDA push processors toward documented residue testing protocols.
- Restaurants:Foodservice operators balance labor cost reduction against flavor authenticity, with refrigerated garlic paste improvements narrowing the convenience gap for high-volume chains.
- Households:Retail consumers prioritize convenience and storage stability over flavor intensity.
- Catering Services:Institutional meal preparation requires standardized portion control and extended holding stability.
Food processing leads on absolute volume; restaurants show steepest expansion trajectory as labor cost pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong province anchors global dehydrated garlic processing capacity, with provincial clusters supplying raw material for powder and granule exports across three continents. Regional demand patterns diverge sharply between industrial food manufacturing hubs and emerging processed food economies.
United States
Dry soup and sauce manufacturers in the Midwest drive powder procurement volumes above fifty metric tons annually through multi-year offtake agreements. FDA microbial threshold verification governs each export lot entry, extending working capital cycles for international suppliers. Chicago and Minneapolis-St. Paul processing corridors concentrate seasoning blend manufacturing where hydration speed determines production line economics.
China
Shandong province's dense garlic cultivation belt supplies the majority of global dehydrated garlic raw material, creating single-origin concentration risk. GB standards and SAMR oversight shape domestic quality specifications while EU Green Deal agricultural input standards tighten export-access thresholds. Jinan and Qingdao processing clusters dominate granule exports into European condiment manufacturing.
India
Bulk powder exports to European food processing sustain Kings Dehydrated Foods and regional competitors leveraging domestic supply bases. FSSAI labeling and additive restrictions govern domestic retail distribution while DGFT export protocols facilitate international shipment. Gujarat and Maharashtra dehydration facilities expand capacity to capture pharmaceutical-grade allicin extraction demand.
Germany
EFSA contamination limits and REACH substance restrictions drive import distributor consolidation toward pre-certified EU compliance suppliers. Hamburg and Rotterdam redistribution hubs filter Asian exports based on documented residue testing protocols. German seasoning manufacturers prioritize supply continuity over quarterly price optimization amid raw material volatility.
Vietnam
Processed food sectors remain underpenetrated by standardized dehydrated garlic formats, offering positioning opportunities for quality-certified suppliers entering Southeast Asian markets. Local food safety regulations align with ASEAN harmonization frameworks while import infrastructure develops. Ho Chi Minh City and Hanoi manufacturing corridors expand ready-meal production capacity.
Dehydrated Garlic Market Vendor Landscape
Global majors compete with regional champions across supply chain control and regulatory compliance capabilities. The vendor base separates into scaled processors with captive laboratory capacity and mid-tier operators dependent on third-party certification. Three archetypes dominate: vertically integrated agricultural processors, specialized dehydration technology providers, and commodity traders with seasonal sourcing networks. Competitive moves center on backward integration into farm-level sourcing and geographic expansion into underpenetrated Southeast Asian markets.
Within the Asia-Pacific processor tier, Kings Dehydrated Foods Pvt. Ltd. and Shandong Key Foods Co., Ltd exemplify regional champions with province-level supply base control. Olam Food Ingredients occupies a position spanning multiple hemispheres through diversified sourcing networks. Sensient Natural Ingredients represents the flavor-house integration archetype, while Jiyan Food Ingredients and ShunDi Foods anchor Chinese domestic capacity expansion. Garlico Industries Ltd. and Chiping ShengKang Foodstuff Co. Ltd sit within the Shandong province cluster specialization pattern.
| Leading Market Players |
|---|
| Jiyan Food Ingredients |
| Kings Dehydrated Foods Pvt. Ltd. |
| ShunDi Foods |
| Sensient Natural Ingredients |
| Olam Food Ingredients |
| Shandong Key Foods Co., Ltd |
| Garlico Industries Ltd. |
| Chiping ShengKang Foodstuff Co. Ltd |
| Laiwu Manhing Vegetables Fruits Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Raw garlic bulb volatility in Shandong province feeds through three distinct pricing tiers before reaching United States dry soup manufacturers, with monsoon-driven Indian harvest swings compressing margins for processors lacking forward-contract coverage.
Pricing Analysis
Input-cost pass-through from Shandong cultivation belts runs through contract-based long-term offtake agreements dominating procurement above fifty metric tons annually, displacing spot purchasing among North American seasoning blend manufacturers. Price differentiation hinges on EU Green Deal pesticide compliance certification and volume scale, with pre-certified suppliers commanding premiums over mid-tier operators dependent on third-party testing. Pricing pressure stems from refrigerated garlic paste distribution improvements narrowing the convenience gap for foodservice chains. Small-scale retail households show highest price sensitivity; pharmaceutical-grade allicin extract buyers demonstrate lowest sensitivity due to functional ingredient premiums.
Supply Chain Analysis
Regional distribution centers in Hamburg and Rotterdam filter Asian exports through hub-and-spoke patterns reaching German condiment manufacturers. Supply concentrates in China, India, and the United States, with three Shandong provinces creating single-origin vulnerability to trade flow disruptions. Raw material dependencies rest on Allium sativum bulb supply, dehydration equipment, and pharmaceutical-grade extraction infrastructure. Tariff exposure looms as REACH substance restrictions tighten. Distribution runs through direct processor-to-manufacturer wholesale channels for industrial volumes, with e-commerce platforms gaining share in mid-tier sample-to-contract flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Shandong province's dense cultivation belt and EU Green Deal compliance premiums, with regulatory testing cost differentials separating scaled laboratory operators from marginal competitors.
For Market Incumbents: Lock in backward integration into farm-level sourcing across Shandong and Gujarat cultivation belts to defend against raw material volatility and substitution pressure from refrigerated garlic paste. Capture pharmaceutical-grade certification infrastructure as a margin lever against mid-tier processors lacking captive laboratory capacity. For New Entrants and Emerging Players: Direct-to-manufacturer e-commerce platforms offer the fastest route past entrenched spice broker networks, with Vietnam and Indonesia processed food sectors presenting underpenetrated white-space targets. Lead with quality-certified positioning and documented residue testing protocols to differentiate from commodity traders. For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory testing timelines extend working capital cycles beyond mid-tier balance sheet capacity, favoring scaled operators with captive EU compliance infrastructure. Target processors with Shandong supply base control and pharmaceutical extraction certification. Watch REACH substance restriction expansion as inflection signal for supplier list consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farm-Level Sourcing | Shandong province cultivation belt control insulates processors from monsoon-driven Indian price swings. |
| Pharmaceutical-Grade Certification Investment | Allicin extraction infrastructure unlocks premium nutraceutical pricing tiers beyond commodity seasoning. |
| EU Green Deal Compliance Pre-Certification | Documented residue testing protocols secure access to Hamburg and Rotterdam redistribution hubs. |
| Direct-to-Manufacturer E-Commerce Platform Launch | Bypassing spice broker networks compresses margin capture and accelerates sample-to-contract velocity. |
| Southeast Asian Geographic Expansion | Vietnam and Indonesia ready-meal manufacturing corridors offer first-mover positioning in underpenetrated markets. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dehydration plant managers, procurement leads at United States dry soup manufacturers, European condiment distribution channel partners, and FSSAI regulatory affairs specialists with secondary validation against FDA filings, EFSA contamination limit databases, USDA trade statistics, and Shandong provincial agricultural output records. Bottom-up processor capacity assessments and top-down import flow analysis were triangulated for convergence.
Comparable-period anchoring tied projection assumptions to historical volatility patterns across raw material and regulatory enforcement cycles over the analysis window. Segmentation dimensions modeled include product type geometry, packaging format, distribution channel structure, and end-use application intensity. CAGRs were derived from demand elasticity coefficients and supply expansion trajectories. Forecast inputs incorporated Shandong province weather pattern distributions and EU pesticide threshold evolution pathways.
The model assumes a particular technology adoption path; alternative pathways for vacuum microwave dehydration would alter the outlook if allicin preservation rates diverge from baseline assumptions. Forecasts reflect documented parameter sets and scenario boundaries. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Condiments
Japanese Curry Market
Spices and Condiments
Global Dehydrated Onion Market
Spices and Condiments
Middle East and Africa Dehydrated Onion Market
Spices and Condiments
Paprika Market
Spices and Condiments
Peeled Garlic Market
Spices and Condiments
Geranium Oil Market
Spices and Condiments
Asia-Pacific Prepared Mustard Market
Spices and Condiments
Mustard Brown Extract Market
Spices and Condiments
Culinary Powder Market
Spices and Condiments
Savory Flavor Blends Market
Spices and Condiments
Global Pickles and Pickle Products Market
Spices and Condiments
Cayenne Pepper Market
Spices and Condiments
Asia-Pacific Dehydrated Onion Market
Spices and Condiments
Acacia Concinna Extracts Market
Spices and Condiments
Rosemary Extracts Market
Spices and Condiments
Garlic Extract Market