
 Europe Dehydrated Onion Market | 2026-2036
Europe Dehydrated Onion Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Dehydrated Onion Market Foresight
Spain is reconfiguring part of its vegetable processing infrastructure toward onion dehydration, leveraging the country's extended harvest windows and established agricultural logistics. Garlico Industries Ltd. anchors its European supply position through backward integration into Indian onion sourcing, while Olam International controls extensive procurement networks across multiple origin markets. Sensient Technologies differentiates through flavor extraction technologies that pair dehydrated onion with complementary savory ingredients.
Dehydrated onion comprises fresh Allium cepa subjected to controlled thermal reduction to moisture levels typically below 6%, preserving pungency compounds and enzymatic activity for extended shelf stability. The resulting material serves as a concentrated flavoring and textural ingredient across industrial food manufacturing, institutional catering, and retail seasoning applications. Powdered formats dominate volume flows into seasoning blends and dry soup bases where rapid solubility matters, while flakes sustain premium positioning within artisanal and visible-ingredient applications. Granules occupy a mid-tier functional position, balancing dispersibility with identifiable particle character for processed meat and snack coatings.
EFSA maintains compositional standards for dried vegetable ingredients entering EU food channels, while REACH governs chemical inputs in processing aids and packaging migration. National food safety agencies in France, Germany, and Italy conduct border inspections that shape import acceptance criteria for non-EU dehydrated onion shipments. Stakeholders must monitor evolving EU deforestation regulation traceability requirements that will soon extend to vegetable supply chains beyond their current scope.
Market Dynamics
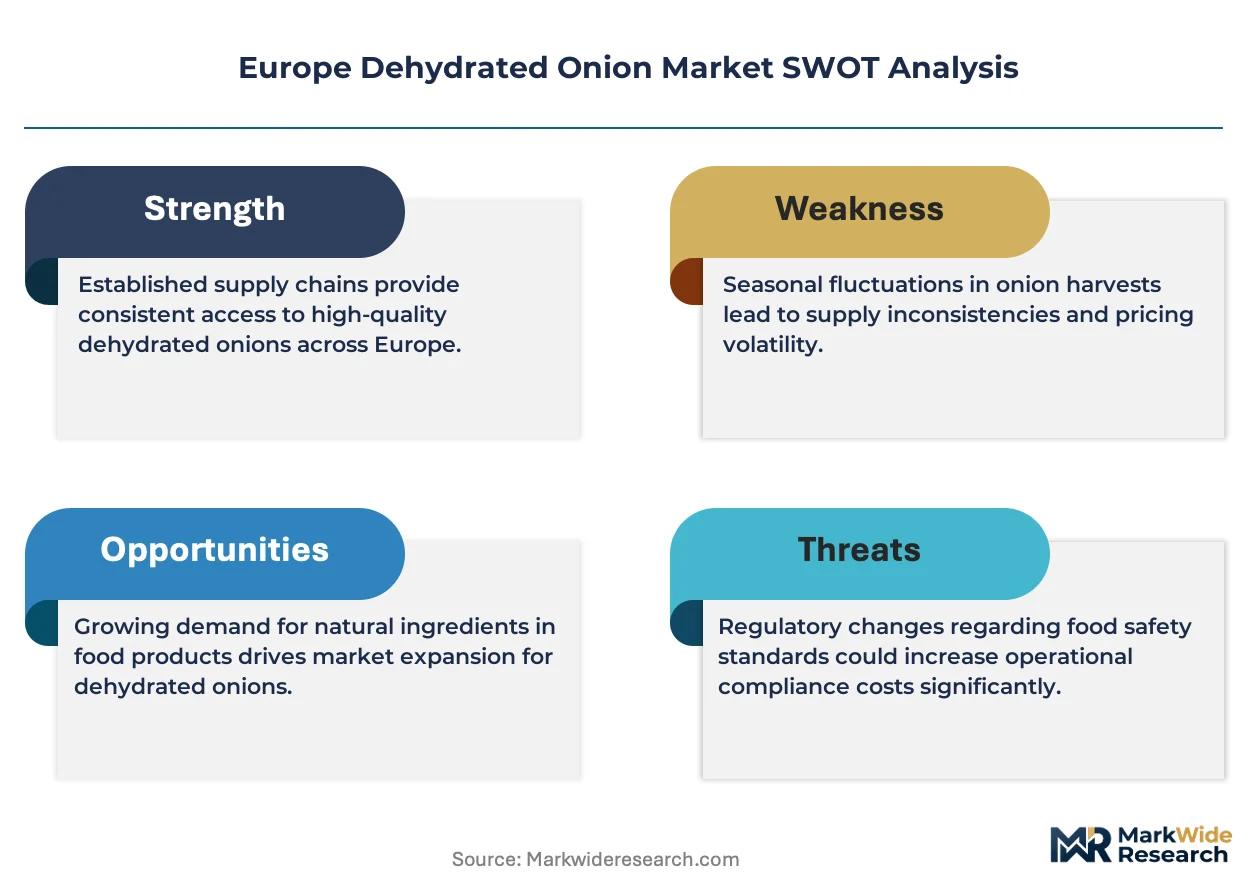
The EU Green Deal's farm-to-fork sustainability targets are compressing food waste tolerance across European processing chains, forcing dehydration technology adoption as a compliance necessity rather than operational choice. This regulatory pressure is restructuring procurement relationships between ingredient suppliers and ready-meal manufacturers.
Growth Catalysts
- EU Deforestation Regulation traceability mandates:Dried vegetable processors gain competitive advantage through established supply chain documentation that incoming rules will require. Early compliance investments now convert to market access later.
- Ready-meal manufacturing expansion:Industrial soup and sauce facilities across Germany and France are consolidating ingredient purchasing around stable-shelf-life inputs. Dehydrated onion replaces fresh in formulations where batch consistency matters.
- Controlled atmosphere dehydration:Energy-efficient thermal reduction systems cut moisture extraction costs by 15-20% versus conventional air-drying. Spanish processors are retrofitting tomato dehydration lines for onion seasonality.
Market Restraints
- Indian monsoon dependency:Raw onion pricing volatility tracks rainfall patterns in Maharashtra and Gujarat growing belts. European processors face margin compression when contract coverage gaps align with poor harvests.
- REACH chemical input restrictions:Processing aids and packaging migration controls limit preservative options for color retention. Reformulation cycles extend 8-14 months for compliance validation.
- Freeze-dried vegetable substitution:Premium soup and seasoning brands in Benelux markets are substituting freeze-dried for air-dried onion where rehydration speed justifies cost premiums.
Strategic Opportunities
- Polish processing infrastructure gap:Central Europe lacks dedicated large-scale onion dehydration capacity relative to its growing ready-meal production base. Greenfield facility investments capture eastward demand migration.
- CSRD sustainability reporting requirements:Food manufacturers need documented Scope 3 emissions reductions from ingredient suppliers. Dehydration's waste-reduction metrics satisfy procurement scorecard criteria.
- Plant-based meat texturizing applications:Onion fiber and particulate structures replicate mouthfeel in European alternative protein formulations. Flake and granule formats penetrate this emerging specification channel.
Industry Challenges
- EFSA novel food authorization timelines:New dehydration process technologies face 12-18 month safety assessment queues. Product launch schedules misalign with seasonal procurement windows.
- Cross-border logistics reconfiguration:Brexit customs procedures disrupted established UK-EU onion product flows. Warehousing and documentation systems require parallel investment for dual-market service.
- Skilled thermal process engineering scarcity:Optimization of moisture reduction curves demands expertise combining food chemistry and energy systems. Recruitment competition intensifies with pharmaceutical drying sectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Dehydrated Onion Market |
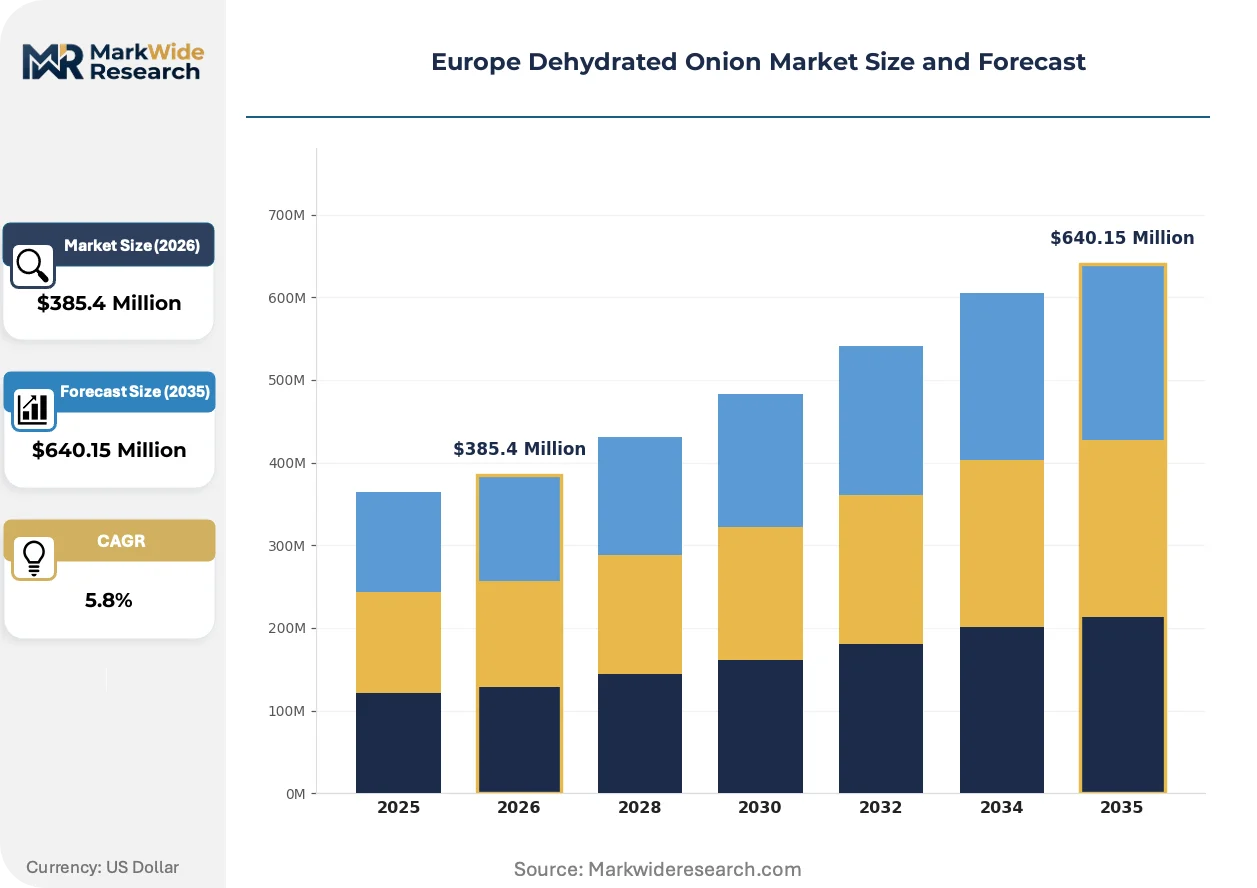
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chopped, Powdered, Flakes, Granules End Use: Food Processing, Snacks, Seasonings, Soups Packaging Type: Bags, Jars, Bulk, Pouches Distribution Channel: Online, Supermarkets, Wholesalers, Specialty Stores |
| Companies Covered | Garlico Industries Ltd., Givaudan, Olam International, Oceanic Foods Limited, Vibrant Nature Herbals & Foods, Jain Farm Fresh Foods, Sensient Technologies, Silva International Inc., Van Drunen Farms, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Dehydrated Onion Market Shifts & Advancements
Digital moisture monitoring and predictive process control are displacing manual quality checkpoints across European dehydration facilities. Automation investments concentrate where energy costs and labor availability pressures intersect most acutely.
Advanced infrared spectroscopy systems are virtualizing real-time moisture measurement in continuous-flow dehydration tunnels. German seasoning manufacturers are retrofitting these sensors across legacy production lines to reduce over-drying energy waste. The technology is virtualizing quality assurance labor roles while compressing batch-to-batch variation penalties in contract supply agreements.
EFSA is tightening maximum residue limits for pesticide metabolites in dried vegetables entering EU food channels. The regulatory tightening is forcing Indian and Egyptian origin suppliers toward integrated pest management certification programs. Organic dehydrated onion shipments face expanded border inspection protocols at Rotterdam and Hamburg entry points.
Ingredient specification consolidation is compressing supplier rosters at major European food manufacturers. Procurement teams at soup and sauce multinationals are reducing qualified vendor lists from 8-12 to 3-4 per ingredient category. This concentration trend is most visible in Germany, where annual volume commitments now determine pricing tier access rather than spot-market negotiation.
Europe Dehydrated Onion Market Segmentation
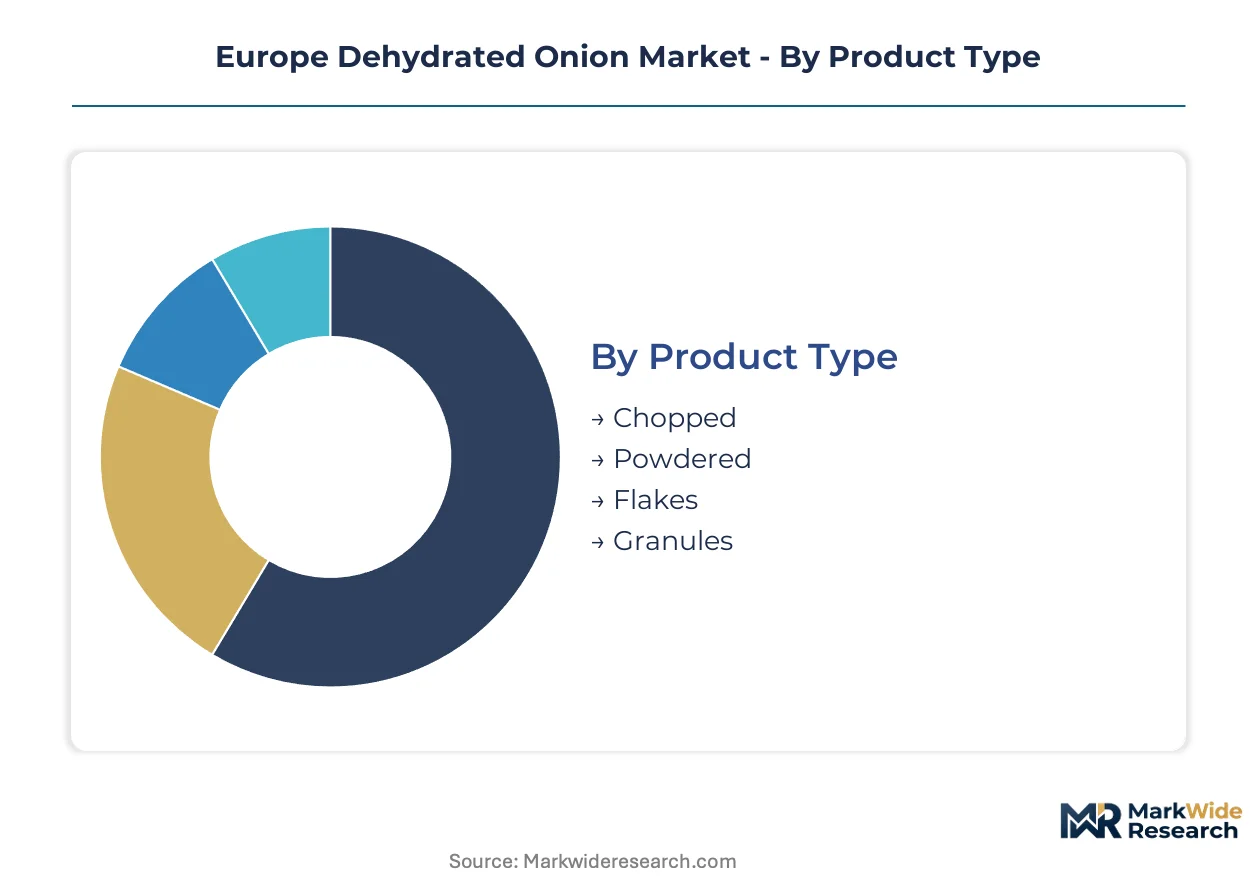
Segmentation in the Europe dehydrated onion market reveals how distinct product formats, end-use applications, and channel configurations command differentiated pricing power and procurement relationships. Manufacturers optimize production lines around specific moisture specifications and particle geometries that align with customer formulation requirements.
Product Type:
After-sales service intensity varies sharply across product formats, with powdered grades demanding intensive technical support for solubility troubleshooting while flake products require minimal post-sale intervention.
- Chopped:Coarse-cut onion pieces retain visible cellular structure and rehydrate with substantial bite. German processed meat manufacturers specify chopped formats for sausage and ready-meal applications where texture recognition matters.
- Powdered:Fine-milled material below 80 mesh delivers rapid dispersion in dry soup bases and seasoning blends. French sauce manufacturers concentrate procurement around powdered grades for batch consistency in industrial kitchens.
- Flakes:Thin-sheet dehydration produces premium visible ingredients for artisanal applications. Italian pasta and pizza seasoning houses favor flakes for aesthetic differentiation in retail packaging.
- Granules:Intermediate particle size balances dispersibility with identifiable texture. Snack coating operations in Spain and Poland specify granules for adhesion control on fried and baked products.
Powdered formats hold the largest share; momentum sits with granules as snack manufacturing expands across Central Europe.
End Use:
Application-driven cost tiers separate commodity bulk purchasers from premium specification buyers, with food processing facilities commanding volume discounts unavailable to artisanal seasoning houses.
- Food Processing:Industrial manufacturers of ready-meals, sauces, and prepared foods constitute the foundational demand base. German and French facilities run 12-month supply contracts with penalty clauses for moisture specification deviations.
- Snacks:Savory coating and flavoring applications for crisps, crackers, and extruded products. Spanish processors supply this segment through converted tomato dehydration infrastructure during onion harvest windows.
- Seasonings:Retail and foodservice dry blends require consistent pungency profiles across production lots. Benelux markets show substitution pressure toward freeze-dried alternatives in premium positioning tiers.
- Soups:Dehydrated soup manufacturers demand rapid rehydration kinetics and clean flavor release. Powdered onion dominates this channel where solubility failure triggers immediate batch rejection.
Food processing commands the largest share; snack applications are climbing the fastest as Central European manufacturing capacity expands.
Packaging Type:
Volume concentration determines packaging configuration, with bulk shipments dominating industrial procurement while retail formats fragment across channel-specific requirements.
- Bags:Multi-wall paper or polymer bags for mid-scale foodservice and small industrial users. French institutional catering distributors specify bagged product for kitchen-level inventory rotation.
- Jars:Glass packaging sustains premium retail positioning in specialty and gourmet channels. Italian and Greek markets favor jarred flakes for home-cooking visibility.
- Bulk:Flexible intermediate bulk containers and tanker shipments for large-scale manufacturing. German soup multinationals contract bulk deliveries direct to processing facilities with silo storage.
- Pouches:Stand-up and flat pouches serve retail seasoning and convenience-oriented foodservice. Online channel growth favors pouch formats for shipping efficiency and shelf presentation.
Bulk packaging holds the largest share; pouches are expanding most quickly through e-commerce penetration in Northern Europe.
Distribution Channel:
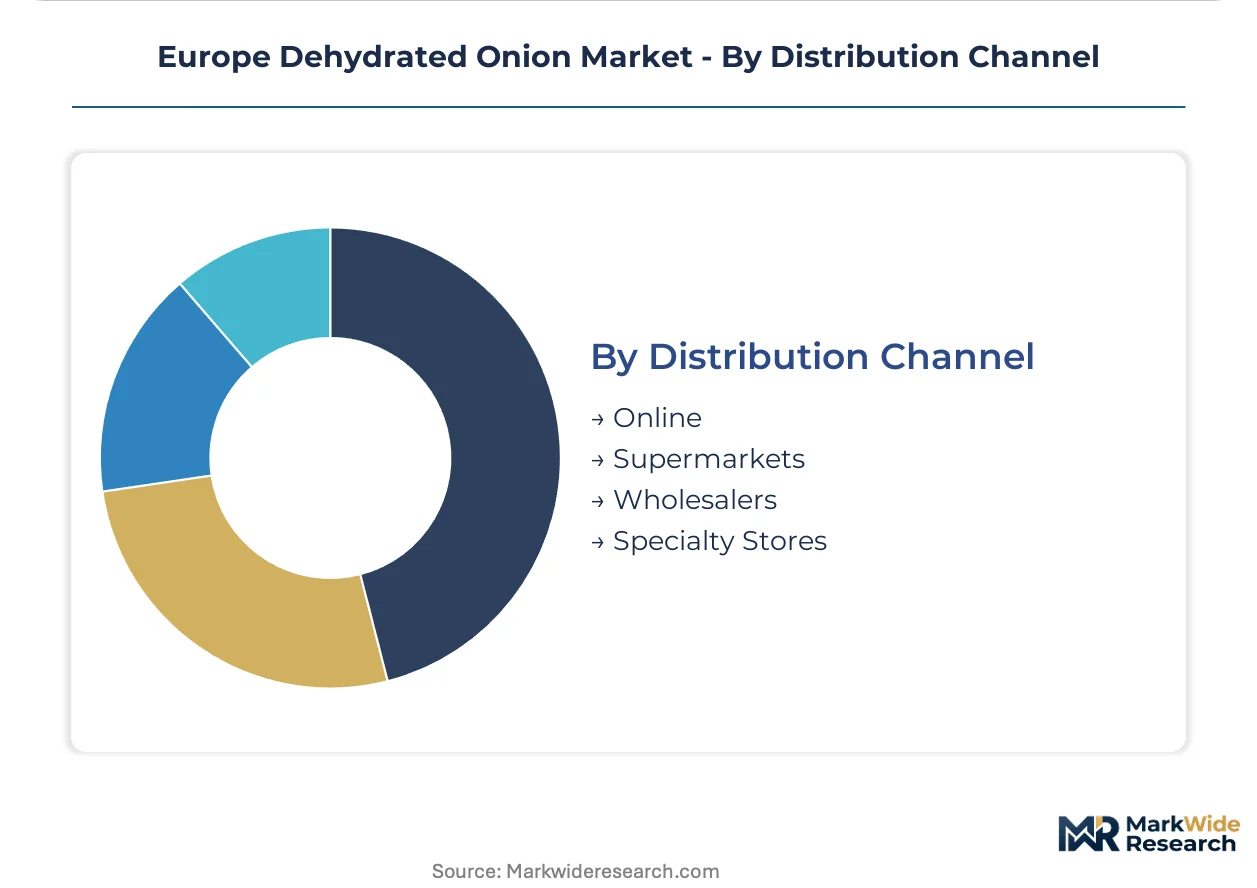
Customer type fragmentation separates price-sensitive volume buyers from specification-driven premium purchasers, with procurement patterns diverging across channel economics.
- Online:Direct-to-manufacturer and retail e-commerce platforms reduce intermediary margins. German and UK industrial buyers increasingly source dehydrated onion through specialized ingredient marketplaces.
- Supermarkets:Retail grocery channels stock jarred and pouched products for consumer cooking applications. Private label concentration in France and Spain compresses branded margin structures.
- Wholesalers:Broadline distributors serve foodservice and small manufacturing with consolidated ingredient sourcing. Polish and Romanian markets rely heavily on wholesaler networks for supply security.
- Specialty Stores:Gourmet and ethnic food retailers stock premium flake and specialty cut formats. Italian deli and gastronomia channels sustain higher price points for visible-quality ingredients.
Wholesalers hold the largest share; online channels are gaining share fastest as procurement digitization accelerates among mid-scale manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA compositional standards govern dried vegetable ingredients entering EU food channels, anchoring regulatory compliance across the continent's dehydration sector. National food safety agencies in France, Germany, and Italy conduct border inspections that shape import acceptance criteria. Procurement relationships restructure as the EU Green Deal's farm-to-fork targets compress food waste tolerance.
Germany
Large-scale soup and seasoning manufacturers anchor regional offtake through 12-month supply contracts with penalty clauses for moisture specification deviations. REACH chemical input restrictions limit preservative options for color retention, forcing reformulation cycles of 8-14 months. The Rhine-Ruhr industrial corridor hosts concentrated ready-meal production facilities that consolidate ingredient purchasing around stable-shelf-life inputs.
France
French sauce manufacturers concentrate procurement around powdered grades for batch consistency in industrial kitchens. EFSA maintains tightened maximum residue limits for pesticide metabolites in dried vegetables entering EU food channels. The Île-de-France region houses major seasoning multinationals reducing qualified vendor lists from 8-12 to 3-4 per ingredient category.
Spain
Spanish processors are retrofitting tomato dehydration lines for onion seasonality, leveraging extended harvest windows and established agricultural logistics. The EU Green Deal's sustainability targets pressure processors to reduce food waste through dehydration technologies. Andalusian processing infrastructure is reconfiguring toward onion dehydration to capture Central European demand migration.
Poland
Central Europe lacks dedicated large-scale onion dehydration capacity relative to its growing ready-meal production base. CSRD sustainability reporting requirements drive food manufacturers to seek documented Scope 3 emissions reductions from ingredient suppliers. Warsaw and Łódź manufacturing zones present greenfield facility investment opportunities to capture eastward demand migration.
Italy
Italian pasta and pizza seasoning houses favor flakes for aesthetic differentiation in retail packaging. National food safety agencies conduct expanded border inspection protocols at entry points for organic dehydrated onion shipments. Emilia-Romagna's gastronomia channels sustain higher price points for visible-quality ingredients in specialty retail.
Europe Dehydrated Onion Market Competitive Landscape
Vertically integrated agricultural processors and specialized flavor houses split the market between scale-driven commodity supply and premium ingredient differentiation. The vendor base concentrates around three strategic archetypes: Indian-origin suppliers with backward integration into raw onion sourcing, European flavor technology specialists, and diversified agricultural commodity traders. Dominant competitive moves include capacity expansion in Spanish processing infrastructure and strategic partnerships linking dehydration technology with ready-meal manufacturer procurement scorecards.
Within the Indian-origin supplier tier, Garlico Industries Ltd. and Jain Farm Fresh Foods exemplify backward integration archetypes controlling upstream raw material flows. Sensient Technologies occupies a position representing European flavor extraction specialization, pairing dehydration capabilities with complementary savory ingredient portfolios. Olam International anchors the diversified agricultural trader archetype, leveraging procurement networks across multiple origin markets to manage Indian monsoon dependency risks.
| Leading Market Players |
|---|
| Garlico Industries Ltd. |
| Givaudan |
| Olam International |
| Oceanic Foods Limited |
| Vibrant Nature Herbals & Foods |
| Jain Farm Fresh Foods |
| Sensient Technologies |
| Silva International Inc. |
| Van Drunen Farms |
| Others |
Supply & Pricing Matrix
The Rotterdam-Hamburg freight corridor carries dehydrated onion shipments from Indian and Egyptian origins into Central European processing hubs, with container rate volatility compressing margins for spot-market buyers while contract-covered suppliers maintain pricing power through volume commitments. This logistics cost dynamic stratifies procurement relationships, as German soup multinationals lock in annual offtake agreements while smaller French seasoning houses absorb freight surcharges that widen their cost disadvantage against integrated competitors.
Pricing Analysis
Geographic price spreads between Indian-origin bulk shipments and European-processed specialty grades run 40-60% across comparable specifications, with Rotterdam entry-point premiums reflecting EFSA compliance documentation and REACH-validated processing inputs. Pricing stratifies across premium, standard, and economy tiers, where organic certification and freeze-dried alternatives command top positioning while conventional air-dried material faces cost compression from energy price spikes. Polish and Romanian buyers exhibit highest price sensitivity due to nascent supply chain development, whereas Benelux premium brands prioritize specification consistency over unit cost.
Supply Chain Analysis
Contract manufacturing concentration sits with Spanish tomato dehydration facilities retrofitted for onion seasonality, alongside dedicated Indian processors in Maharashtra and Gujarat growing belts. Raw material flows draw from Maharashtra onion harvests, Egyptian late-season supplies, and Polish domestic production, with energy inputs for thermal reduction representing 25-30% of processing cost structure. Single-source vulnerability concentrates in Indian monsoon-dependent harvests, which trigger spot price spikes when contract coverage gaps align with poor rainfall. Distribution runs through Rotterdam and Hamburg entry points into German industrial corridors, with secondary flows reaching French sauce manufacturers via Antwerp consolidation hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against freeze-dried vegetable alternatives that penetrate premium soup and seasoning tiers in Benelux markets, where rehydration speed justifies cost premiums that air-dried suppliers struggle to match.
For Market Incumbents: Entrench procurement relationships through CSRD-compliant Scope 3 emissions documentation that satisfies manufacturer sustainability scorecards, while retrofitting Spanish processing infrastructure to capture Central European demand migration. Backward integration into Indian onion sourcing mitigates monsoon-driven margin compression, though EFSA novel food authorization timelines for advanced dehydration technologies require 12-18 month lead planning to align with seasonal procurement windows.
For New Entrants and Emerging Players: Central European processing infrastructure gaps present white-space capture opportunities, particularly in Poland where ready-meal manufacturing expansion outpaces dedicated onion dehydration capacity. Plant-based meat texturizing applications offer specification-driven entry with lower incumbent concentration, while digital moisture monitoring technology partnerships with German seasoning manufacturers provide differentiated service positioning against commodity suppliers.
For Investors and Strategic Acquirers: Mid-scale Spanish processors with established agricultural logistics and EU Green Deal compliance infrastructure represent priority acquisition targets, given their retrofit flexibility and proximity to expanding Central European demand. Long-term viability hinges on dehydration technology differentiation and traceability documentation that satisfies incoming EU Deforestation Regulation mandates. Monitor Indian monsoon patterns and EFSA residue limit tightening as inflection indicators that restructure competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Indian Sourcing | Captive supply of Maharashtra and Gujarat onion harvests reduces monsoon-driven price volatility exposure. |
| Spanish Processing Infrastructure Retrofit | Tomato dehydration line conversion captures onion seasonality with established EU logistics networks. |
| CSRD Sustainability Documentation Investment | Waste-reduction metrics satisfy German manufacturer procurement scorecards for Scope 3 emissions reporting. |
| Digital Moisture Monitoring Deployment | Infrared spectroscopy systems reduce German seasoning manufacturer energy costs and batch variation penalties. |
| Freeze-Dried Alternative Product Development | Rehydration speed specifications defend premium positioning against air-dried substitution in Benelux markets. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dehydrated onion procurement managers at German soup multinationals, French sauce manufacturers, Spanish processing facility engineers, and Italian seasoning house technical directors. Secondary validation drew from EFSA compositional standards documentation, REACH chemical input restriction filings, EU trade customs data for dried vegetable imports, and CSRD sustainability reporting framework disclosures. Bottom-up volume estimates from processing facility capacity assessments were triangulated against top-down demand calculations from ready-meal manufacturing expansion rates across the analysis window.
Calibration against historical price volatility patterns and procurement contract structures anchored the analytical framework, with segmentation modeling across product format, end-use application, and packaging configuration dimensions. CAGRs were derived from trend extrapolation of food processing facility expansion rates, snack manufacturing capacity buildout in Central Europe, and e-commerce penetration effects on retail channel distribution. Industry-specific forecast inputs included Indian monsoon rainfall correlation models, energy cost trajectories for thermal reduction processes, and EU Deforestation Regulation implementation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Indian-origin suppliers or accelerated freeze-dried substitution in premium tiers would shift outcomes beyond modeled ranges. Quarterly review of Rotterdam-Hamburg freight rates, EFSA residue limit enforcement intensity, and German manufacturer vendor consolidation progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Condiments
Asia-Pacific Dehydrated Onion Market
Spices and Condiments
Acacia Concinna Extracts Market
Spices and Condiments
Dry Chilies Market
Spices and Condiments
Culinary Powder Market
Spices and Condiments
Garlic Extract Market
Spices and Condiments
Savory Flavor Blends Market
Spices and Condiments
Middle East and Africa Vanilla Beans and Extract Market
Spices and Condiments
Mustard Brown Extract Market
Spices and Condiments
Japanese Curry Market
Spices and Condiments
Gourmet Salts Market
Spices and Condiments
Peeled Garlic Market
Spices and Condiments
Fermented Mediterranean Pepper and Tomato Complexes Market
Spices and Condiments
Global Pickles and Pickle Products Market
Spices and Condiments
Global Dehydrated Onion Market
Spices and Condiments
Cayenne Pepper Market
Spices and Condiments
Paprika Market