
 Gravy Mixes Market | 2026-2036
Gravy Mixes Market Size, Share, and Industry Trends Forecast 2026-2036
Gravy Mixes Market Foresight
Premium clean-label specification tiers are rotating toward the center of competitive strategy. McCormick & Company sustains its position through deep R&D investment in natural flavor extraction and reduced-sodium formulations. Southeastern Mills, Inc. dominates foodservice channels with specialized institutional-grade concentrates. Knorr leverages Unilever's global procurement infrastructure to control input costs on key savory base materials.
Gravy mixes comprise dehydrated or concentrated blends of starches, hydrolyzed proteins, fats, flavor precursors, and seasonings that reconstitute with water or drippings to produce finished sauce. Manufacturing employs drum-drying, spray-drying, or extrusion to achieve target viscosity, shelf stability, and dispersibility in hot liquid. Instant gravy and powdered gravy lead volume due to their extended shelf life and minimal preparation steps, while concentrated gravy captures higher margins in foodservice and prepared meal manufacturing where labor reduction carries premium value. Liquid and paste forms remain niche but expand in refrigerated retail cases where freshness signaling commands price premiums.
The FDA's Food Safety Modernization Act requirements and EFSA's additive authorization frameworks shape ingredient permissibility and label claims across major markets. USDA grading standards for meat-derived flavor bases and Health Canada's CFIA labeling rules further constrain formulation freedom and import eligibility. Stakeholders must monitor evolving sodium reduction mandates and clean-label certification thresholds as these standards increasingly determine shelf placement and contract eligibility in institutional procurement.
Market Dynamics
Clean-label reformulation mandates from the FDA and EFSA are compressing ingredient decks while foodservice operators demand instant formats that slash labor costs in prepared meal assembly.
Growth Catalysts
- Instant format adoption:Quick-service restaurants and contract food manufacturers are standardizing powdered and concentrated gravy mixes to accelerate sauce station throughput and reduce skilled labor dependency.
- FSMA compliance:The FDA's Food Safety Modernization Act preventive controls are compelling manufacturers to invest in validated kill-step documentation, which favors larger producers with dedicated food safety infrastructure.
- Natural flavor extraction:Enzymatic and fermentation-derived savory base technologies are displacing synthetic hydrolyzed proteins in premium product lines, opening clean-label positioning in retail and institutional channels.
Market Restraints
- Wheat starch volatility:Input cost swings for modified starches and maltodextrins constrain margin predictability, particularly for mid-tier producers without forward contracting capabilities.
- Supply concentration risk:Specialty hydrolyzed vegetable protein production clusters in China and Southeast Asia, exposing formulation continuity to geopolitical friction and shipping lane disruption.
- EFSA additive authorization delays:Novel emulsifier and preservative approvals for extended-shelf-life liquid formats face 18-24 month evaluation timelines, blocking innovation pipelines.
Strategic Opportunities
- Refrigerated retail expansion:Fresh-positioned paste and liquid gravies in chilled cases command price premiums in US coastal metropolitan markets where freshness signaling outweighs shelf-stable convenience.
- Sodium reduction mandates:Health Canada's phased sodium targets for processed foods create formulation service opportunities for technical ingredient suppliers with potassium chloride and yeast extract masking expertise.
- Direct-to-foodservice platforms:Digital procurement portals are disintermediating traditional broadline distributors, enabling specialized concentrate manufacturers to capture institutional accounts with customized viscosity specifications.
Industry Challenges
- Flavor chemist scarcity:The specialized skill set for natural savory flavor reconstruction commands premium compensation, constraining R&D bandwidth at mid-scale manufacturers competing against multinational flavor houses.
- Legacy equipment retrofit costs:Transitioning from conventional spray-drying to low-temperature vacuum drying for heat-sensitive natural extracts demands capital outlays that strain private-equity-owned operators with short holding periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gravy Mixes Market |
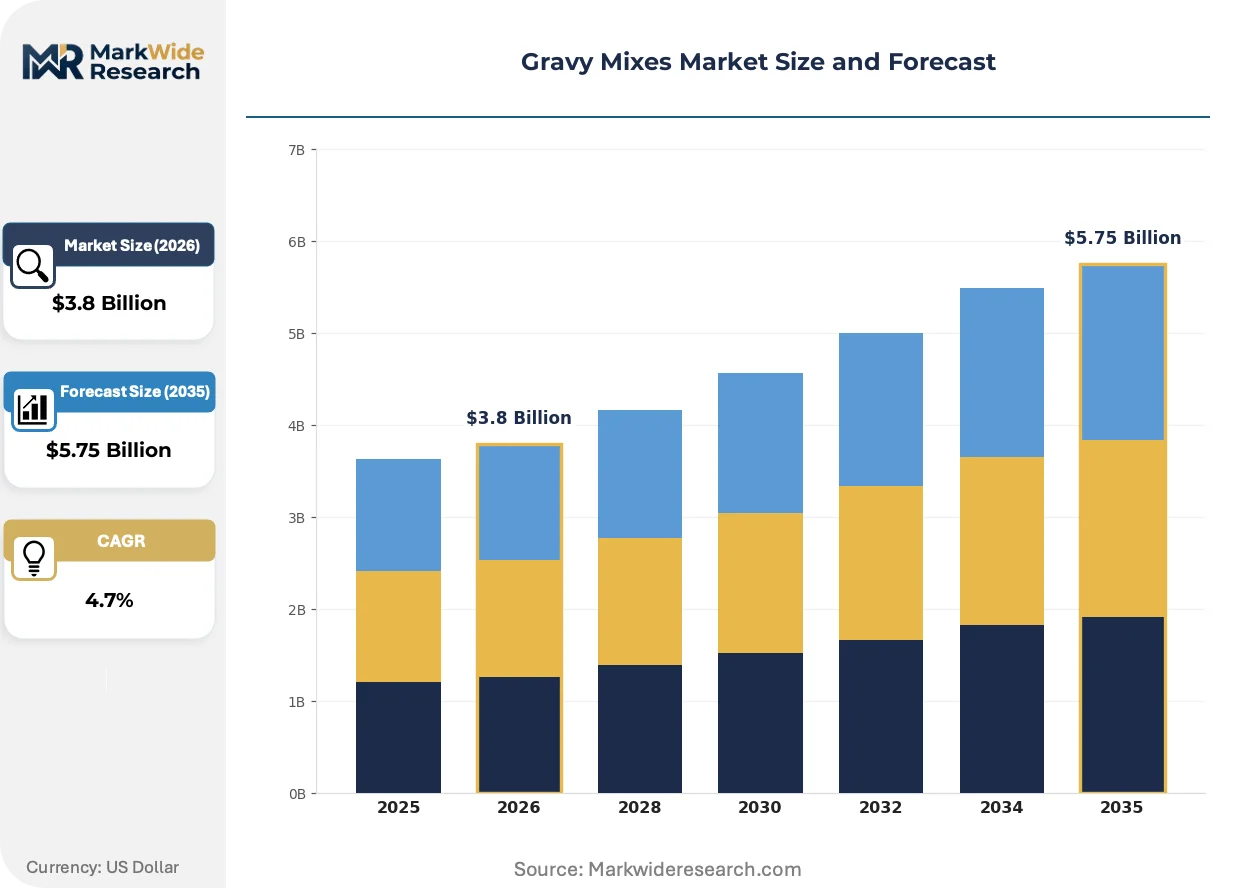
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Gravy, Sauce Mix, Concentrated Gravy, Powdered Gravy End User: Households, Restaurants, Catering Services, Food Manufacturers Distribution Channel: Retail Stores, Online Stores, Wholesale, Supermarkets Form: Liquid, Powder, Granulate, Paste |
| Companies Covered | Edward & Sons, Knorr, Southeastern Mills, Inc., Pioneer Foods, Schwartz, McCormick & Company, Inc., Kent Precision Foods Group, Inc., Bisto, Campbell Company of Canada, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gravy Mixes Market Shifts & Advancements
Processing technology and procurement patterns are diverging sharply between mass-market efficiency plays and premium authenticity positioning, with regulatory pressure accelerating both tracks simultaneously.
Low-temperature vacuum drying technology is bifurcating the manufacturing base. This method preserves volatile aromatic compounds in meat-derived and vegetable base materials that high-heat spray-drying degrades. Premium retail and foodservice brands with clean-label commitments are adopting it aggressively, while conventional drum-drying lines serve cost-sensitive institutional contracts. The technology is bifurcating production economics: capital-intensive vacuum systems enable margin capture in premium tiers but compress returns in commodity segments where price competition dominates.
REACH authorization requirements for food-contact substances are tightening migration limits for packaging materials used in gravy mix sachets and bulk concentrates. The European Chemicals Agency's evolving substance restrictions are forcing laminate film reformulations, particularly for oxygen-barrier layers in retort-stable pouches. Manufacturers exporting to EU member states are accelerating compliance timelines, with some diverting investment from product innovation to packaging qualification to maintain market access.
Buyer concentration among consolidated foodservice distributors is compressing supplier negotiation leverage. Sysco, US Foods, and broadline operators are unbundling gravy mixes from bundled protein contracts, forcing standalone price competition on volume specifications. This disintermediation of traditional category management is most visible in the US Southeast and Midwest, where regional restaurant chains are consolidating purchasing through group purchasing organizations that demand transparent cost-plus pricing and direct manufacturer relationships.
Gravy Mixes Market Segmentation
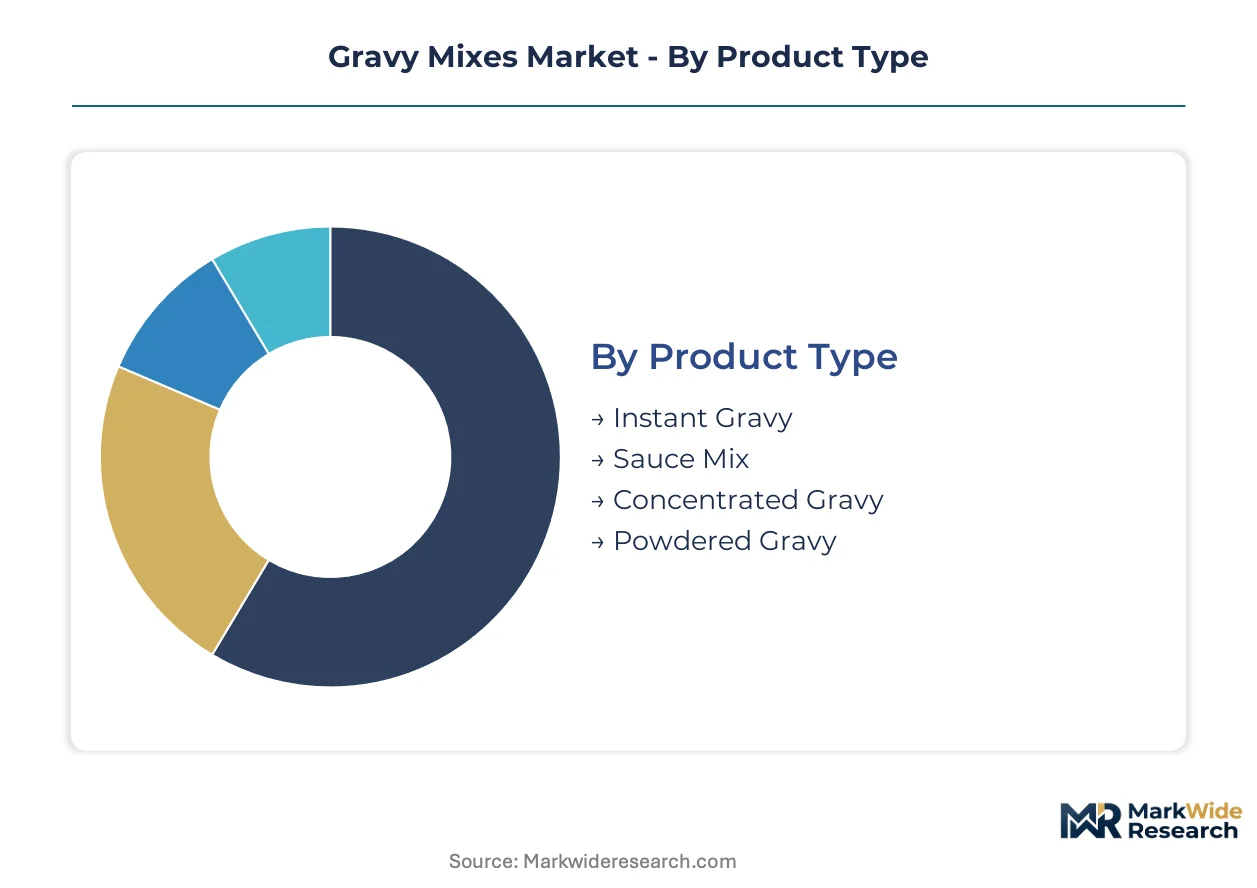
Segmentation in gravy mixes reveals divergent manufacturing economics and channel strategies. Powdered and instant formats dominate foodservice procurement for labor efficiency, while paste and liquid gravies command retail premiums through freshness positioning.
Product Type:
Substitution pressure from prepared sauce alternatives and ready-to-eat meals weighs heaviest on powdered formats in retail, while concentrated gravies face limited direct substitutes in institutional cooking.
- Instant Gravy:Pre-gelatinized starch and hydrolyzed protein blends reconstitute in hot water without additional thickening steps. Quick-service restaurants in the United States standardize this format for sauce station speed, though EFSA clean-label mandates are forcing sodium and additive reductions that compress margins.
- Concentrated Gravy:Reduced-moisture bases requiring dilution with water or drippings deliver intense flavor with controlled viscosity. Food manufacturers in prepared meal assembly favor concentrates for precise portioning and extended refrigerated stability, though FSMA preventive controls documentation demands strain smaller suppliers.
- Sauce Mix:Multi-functional blends incorporating seasonings beyond basic gravy profiles serve home cooks seeking meal versatility. Retail channels in suburban markets move these through bundled holiday promotions.
- Powdered Gravy:Dehydrated starch and fat emulsions offer lowest unit cost and longest ambient shelf life. Institutional procurement contracts favor powdered formats for inventory simplicity.
Powdered gravy anchors the volume base while concentrated gravy gains share at the steepest rate.
End User:
Cost tier stratification separates price-sensitive institutional buyers from premium-positioned household segments willing to pay for clean-label credentials and convenience formats.
- Restaurants:Independent operators and chain kitchens drive demand for instant and concentrated formats that minimize skilled labor at sauce stations. Group purchasing organizations in the US Southeast and Midwest consolidate buying power, forcing transparent cost-plus pricing from manufacturers.
- Food Manufacturers:Prepared meal and frozen dinner producers specify custom viscosity and sodium profiles for automated sauce deposition lines. Health Canada's phased sodium targets create formulation service opportunities for technical ingredient suppliers.
- Households:Home cooks purchase retail formats for holiday meals and weeknight convenience, with coastal metropolitan markets showing strongest preference for refrigerated paste and liquid options.
- Catering Services:High-volume event operators prioritize powdered and instant formats for holding stability and rapid batch preparation.
Restaurants anchor the volume base while food manufacturers expand most quickly as prepared meal production scales.
Distribution Channel:
Volume concentration in consolidated foodservice distributors is compressing supplier leverage and forcing standalone price competition outside traditional bundled protein contracts.
- Wholesale:Broadline distributors serve as the primary route to institutional accounts, though digital procurement portals are enabling direct manufacturer relationships. Sysco and US Foods unbundle gravy mixes from protein contracts, exposing suppliers to transparent price competition.
- Supermarkets:Chilled retail cases in coastal US metropolitan markets command freshness premiums for paste and liquid formats, while center-store powdered gravies compete on promotional price.
- Retail Stores:Independent grocers and regional chains maintain seasonal gravy mix displays tied to holiday cooking cycles.
- Online Stores:E-commerce penetration remains limited for ambient gravy mixes due to shipping cost economics, though specialty and subscription formats gain traction.
Wholesale anchors the volume base while supermarkets expand most quickly through refrigerated format expansion.
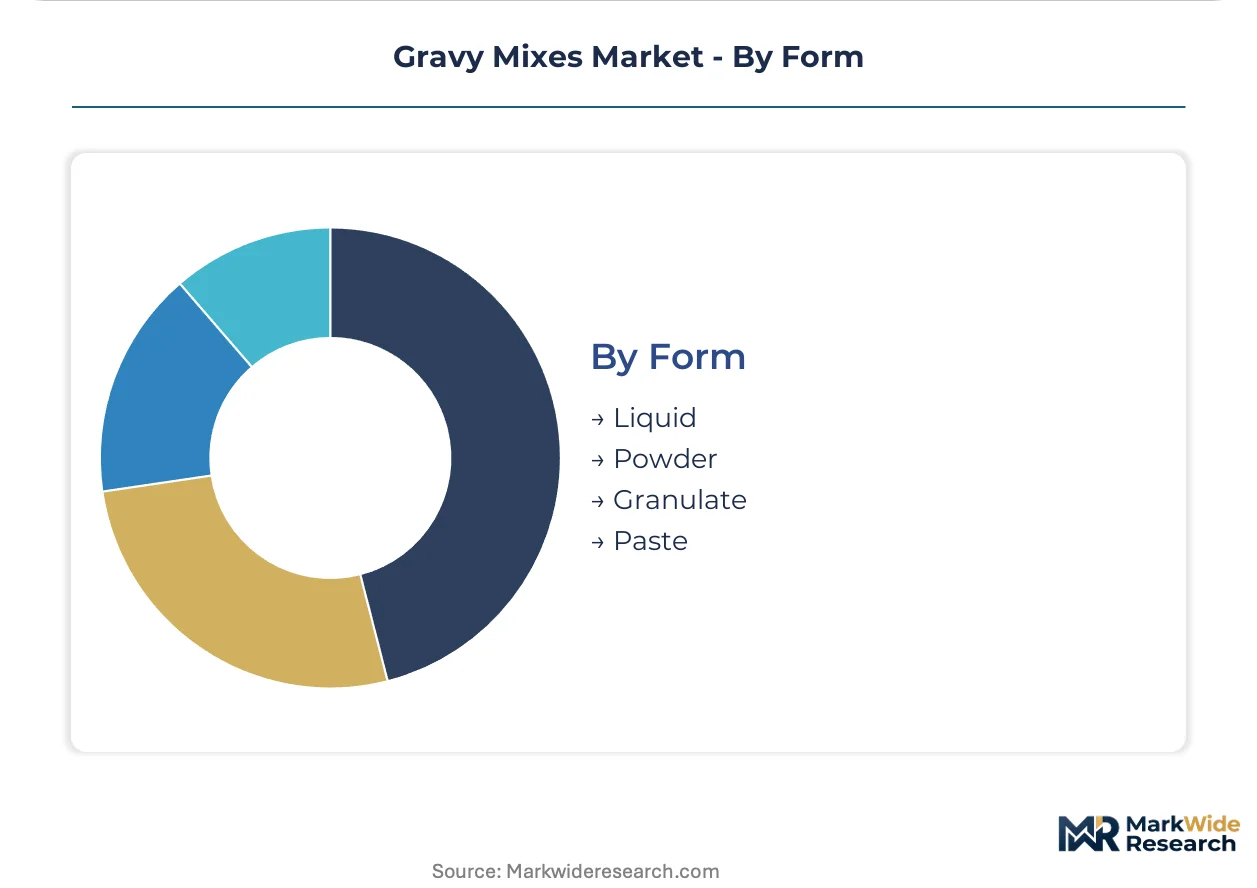
Form:
Supply concentration in spray-drying equipment for powder production contrasts with fragmented co-packer networks for refrigerated liquid and paste gravies.
- Powder:Drum-dried and spray-dried particles achieve target dispersibility and shelf stability through controlled particle size distribution. Conventional spray-drying lines serve cost-sensitive institutional contracts, while vacuum-drying investments target premium retail positioning.
- Liquid:Retort-stable and refrigerated formats require oxygen-barrier packaging compliant with REACH migration limits for laminate films. ECHA substance restrictions force packaging qualification investments that divert resources from product innovation.
- Paste:Intermediate moisture content enables intense flavor concentration with spoonable texture, popular in European retail and emerging in US coastal markets.
- Granulate:Agglomerated particles improve dispersibility over conventional powders, serving premium retail positioning.
Powder anchors the volume base while liquid gains share at the steepest rate in refrigerated retail expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based manufacturers export concentrated gravy formats to Canadian foodservice operators and Mexican prepared meal producers, establishing a North American trade corridor that channels formulation expertise southward while sourcing specialty hydrolyzed proteins from Asian suppliers.
United States
Quick-service restaurants in the Southeast and Midwest drive volume for instant gravy formats through group purchasing organizations that demand transparent cost-plus pricing. FDA Food Safety Modernization Act preventive controls compel manufacturers to maintain validated kill-step documentation. Chicago and Atlanta anchor foodservice distribution hubs where specialized concentrate producers customize viscosity specifications for institutional accounts.
Germany
EFSA clean-label mandates accelerate sodium reduction and additive reformulation across retail gravy mix portfolios. REACH authorization requirements for food-contact substances tighten migration limits for laminate films in retort-stable pouches. The Rhine-Ruhr industrial corridor hosts packaging qualification laboratories that serve EU-wide compliance needs for oxygen-barrier layer reformulation.
China
Domestic food manufacturers scale prepared meal production using imported concentrated gravy bases from North American suppliers. SAMR labeling standards and GB food safety codes constrain ingredient permissibility for foreign brands seeking market entry. Shanghai and Guangzhou processing clusters specialize in hydrolyzed vegetable protein production that supplies global savory base demand.
United Kingdom
Retail demand for powdered gravy concentrates peaks during holiday cooking cycles, with supermarket chains deploying seasonal promotional displays. EFSA additive authorization frameworks align with post-Brexit UK food standards that maintain equivalent safety thresholds. The Midlands manufacturing belt retains drum-drying capacity that serves cost-sensitive institutional contracts across Northern Europe.
Canada
Health Canada's phased sodium targets for processed foods create formulation service opportunities for technical ingredient suppliers. CFIA labeling rules constrain import eligibility for gravy mixes containing non-compliant meat-derived flavor bases. Toronto and Vancouver metropolitan markets show strongest preference for refrigerated paste and liquid formats that signal freshness in chilled retail cases.
Gravy Mixes Market Competitive Landscape
Listed leaders compete with private specialists across R&D investment capacity and food safety infrastructure scale. The vendor base separates into multinational flavor houses with dedicated natural extraction laboratories, regional concentrate producers serving institutional procurement, and private-label specialists manufacturing for retail chains. Three archetypes dominate: premium clean-label innovators, foodservice volume suppliers, and cost-optimized commodity blenders. M&A activity concentrates on natural flavor technology acquisitions, while capacity expansion targets low-temperature vacuum drying for heat-sensitive extracts.
Within the premium-tier vector, McCormick & Company exemplifies deep research investment in natural flavor extraction and reduced-sodium formulations. Southeastern Mills, Inc. anchors the foodservice concentrate segment with institutional-grade production capabilities. Knorr represents multinational scale advantages through global procurement infrastructure that controls input costs on savory base materials.
| Leading Market Players |
|---|
| Edward & Sons |
| Knorr |
| Southeastern Mills, Inc. |
| Pioneer Foods |
| Schwartz |
| McCormick & Company, Inc. |
| Kent Precision Foods Group, Inc. |
| Bisto |
| Campbell Company of Canada |
| Others |
Supply & Pricing Matrix
Drum-drying capacity utilization in the US Southeast and Midwest creates scale thresholds that marginalize sub-scale blenders while anchoring price floors for powdered gravy contracts. Concentrated format producers exploit vacuum-drying investments to capture premium positioning, compressing commodity-tier margins through asymmetric cost structures.
Pricing Analysis
Conventional spray-drying versus low-temperature vacuum-drying versus next-generation enzymatic extraction creates a three-tier pricing structure across premium, standard, and economy levels. Contract-based long-term offtake dominates institutional procurement, with price differentiation driven by certification grade (FDA FSMA compliance tier) and volume scale. Pricing pressure stems from unbundling by Sysco and US Foods, which exposes suppliers to transparent cost-plus negotiation. Food manufacturers prove least price-sensitive due to formulation lock-in, while independent restaurants exhibit highest elasticity.
Supply Chain Analysis
Inventory cycles for hydrolyzed vegetable protein extend lead times, forcing manufacturers to hold 60-90 day safety stocks of savory base materials. Specialty hydrolyzed protein production clusters in China and Southeast Asia, while modified starch supply concentrates in the US Corn Belt and European grain processing hubs. Raw material dependencies include wheat starch, maltodextrin, and yeast extract. Single-source vulnerability in Asian savory base supply creates discontinuity exposure. Distribution runs through consolidated broadline distributors, with digital procurement portals emerging as direct channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through FDA FSMA preventive controls documentation creates sticky relationships that resist supplier switching.
For Market Incumbents: Shield market position by deepening backward integration into natural flavor extraction capabilities and expanding low-temperature vacuum-drying capacity in the US Southeast. Clean-label reformulation mandates from EFSA threaten margin compression for additive-dependent portfolios. Channel control through direct-to-foodservice digital platforms offers defensive leverage against distributor unbundling.
For New Entrants and Emerging Players: Lead with refrigerated paste and liquid formats targeting US coastal metropolitan markets where freshness signaling commands price premiums. White-space concentration sits in clean-label sodium-reduction formulations for Health Canada compliance. Direct procurement portals disintermediate traditional distributors, enabling customized viscosity specifications for regional restaurant chains.
For Investors and Strategic Acquirers: Natural extraction technology specialists with enzymatic and fermentation-derived savory base capabilities represent priority acquisition targets. Long-term viability over the next decade hinges on clean-label certification thresholds determining shelf placement and contract eligibility. Watch EFSA additive authorization timelines as inflection indicators for liquid format innovation pipelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Natural Extraction | Enzymatic and fermentation capabilities displace synthetic hydrolyzed proteins for EFSA clean-label positioning. |
| Low-Temperature Vacuum Drying Capacity Expansion | Preserves volatile aromatic compounds that high-heat spray-drying degrades in premium retail tiers. |
| Direct-to-Foodservice Digital Platform Launch | Sysco and US Foods unbundling creates opening for customized viscosity specifications and transparent pricing. |
| Sodium Reduction Formulation Service | Health Canada phased targets create technical ingredient opportunities for potassium chloride masking expertise. |
| Refrigerated Retail Format Introduction | US coastal metropolitan markets signal freshness preference that commands price premiums over shelf-stable alternatives. |
Research Methodology
The analysis maps instant gravy, concentrated gravy, powdered gravy, and paste/liquid formats, each validated through foodservice procurement directors, R&D formulation leads, retail category buyers, and contract manufacturing executives. Primary interview data triangulates against FDA FSMA compliance documentation, EFSA additive authorization filings, Health Canada sodium target publications, and USDA grading standards. Customs records for hydrolyzed protein trade flows and Nielsen retail audit data for gravy mix velocity complete secondary validation. Bottom-up segment sizing reconciles with top-down market value estimates.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models product type, end user, distribution channel, and form dimensions, with regulatory compliance tier as an industry-specific overlay. CAGRs derive from segment-level growth trajectory analysis incorporating input cost volatility for wheat starch and hydrolyzed proteins, sodium reduction mandate phase-in schedules, and foodservice labor cost inflation assumptions.
The analysis sits within stated boundaries; outcomes outside stable regulatory frameworks and intact Asian supply corridors would require recalibration. Forecasts reflect documented assumptions regarding EFSA authorization timelines, REACH packaging compliance costs, and distributor consolidation trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Condiments
Dehydrated Garlic Market
Spices and Condiments
Cayenne Pepper Market
Spices and Condiments
Garlic Extract Market
Spices and Condiments
Asia-Pacific Dehydrated Onion Market
Spices and Condiments
Acacia Concinna Extracts Market
Spices and Condiments
Savory Flavor Blends Market
Spices and Condiments
Peeled Garlic Market
Spices and Condiments
Global Dehydrated Onion Market
Spices and Condiments
Rosemary Extracts Market
Spices and Condiments
Asia-Pacific Prepared Mustard Market
Spices and Condiments
Gourmet Salts Market
Spices and Condiments
Dry Chilies Market
Spices and Condiments
Frangipani Extract Market
Spices and Condiments
Global Pickles and Pickle Products Market
Spices and Condiments
Middle East and Africa Vanilla Beans and Extract Market
Spices and Condiments
Europe Dehydrated Onion Market