

Conveyor-Free Sortation Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Conveyor-Free Sortation Modules Market Insights
Third-party logistics buyer concentration is consolidating around operators running multi-tenant fulfillment campuses. Swisslog leverages its KUKA robotics heritage to anchor large-scale European deployments. GreyOrange competes through its Ranger mobile robot fleet designed explicitly for conveyor-free sortation workflows. Daifuku sustains dominance in Asia-Pacific airport and parcel hub installations through decades of baggage handling systems expertise.
Conveyor-free sortation modules are autonomous robotic systems that transport, identify, and divert parcels or goods using mobile robots, robotic arms, or goods-to-person stations without fixed belt infrastructure, typically achieving throughput rates of 1,500 to 3,500 items per hour depending on payload and robot density. Their primary purpose is to eliminate single points of failure inherent in traditional conveyor architectures while enabling rapid facility reconfiguration. Autonomous mobile robots and goods-to-person systems now occupy the fastest-expanding technology segments as warehouse operators prioritize flexibility over peak-speed fixed systems. E-commerce fulfillment and parcel handling applications generate the deepest margin pools, though food and beverage distribution is emerging as a structurally underserved vertical where cold-chain-compatible mobile sortation commands pricing premiums.
The EU Machinery Directive and CE marking requirements enforced by national regulators in Germany and France shape robot safety standards and market access protocols for European deployments. In the United States, OSHA workplace safety guidelines and state-level warehouse automation labor codes influence system design and human-robot collaboration parameters. Stakeholders must monitor how evolving AI liability frameworks and energy efficiency certifications reshape total cost of ownership calculations for modular sortation investments.
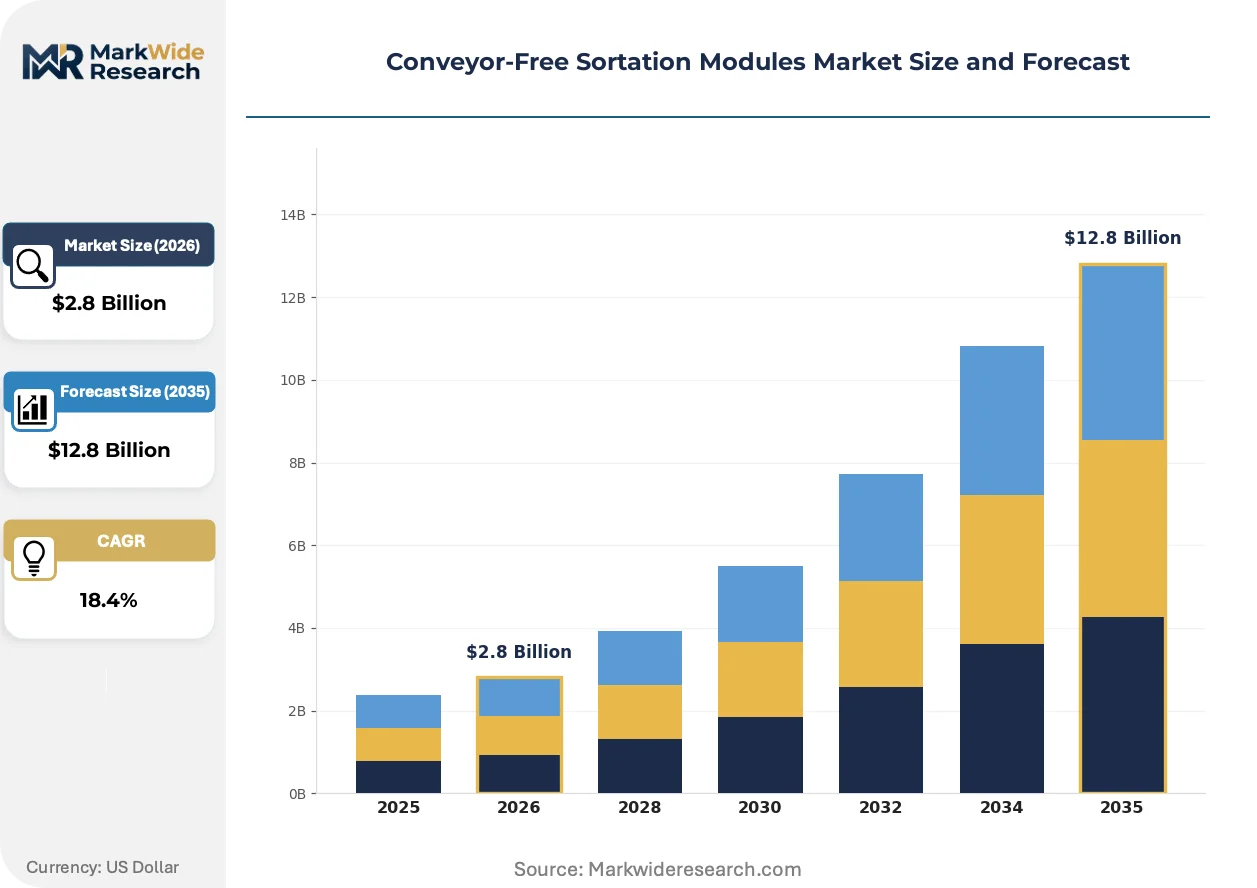
Market Dynamics
Modular robotic architectures are compressing facility retrofit timelines from years to months, forcing warehouse operators to abandon fixed conveyor investments in favor of reconfigurable mobile robot fleets that adapt to SKU volatility and seasonal demand swings.
Growth Catalysts
- EU Machinery Directive compliance mandates:German and French distribution centers face accelerated depreciation schedules on legacy belt systems as CE marking requirements for collaborative robotics tighten human-robot safety protocols.
- Last-mile parcel density:Urban fulfillment nodes in the United States absorb conveyor-free modules to process 2,000-plus items per hour within 50,000-square-foot footprints where traditional infrastructure cannot fit.
- Lithium-ion power density improvements:Extended mobile robot duty cycles now support 18-hour continuous sortation operations, eliminating battery swap downtime that previously constrained throughput.
Market Restraints
- Steel and rare earth magnet cost volatility:Permanent magnet motors in mobile robot drivetrains expose OEMs to neodymium price swings originating from Chinese processing concentration.
- Single-source lidar dependency:Warehouse-grade 3D vision sensors concentrate among three component suppliers, creating procurement bottlenecks for system integrators scaling deployments.
- Floor flatness tolerances:Autonomous mobile robot navigation demands concrete surface variations below three millimeters over ten meters, disqualifying 40 percent of legacy industrial real estate without costly slab remediation.
Strategic Opportunities
- Cold-chain food distribution:Refrigerated mobile robots with IP67 sealing command 35 percent pricing premiums in North American protein and dairy fulfillment where frozen conveyor maintenance costs are prohibitive.
- India PLI scheme for robotics:Production-linked incentives for automated material handling equipment create localized manufacturing pathways for cost-competitive export to Southeast Asian e-commerce markets.
- 5G private network convergence:Ultra-reliable low-latency communication enables centralized fleet optimization across 500-plus robot deployments, compressing coordination overhead previously handled by edge computing.
Industry Challenges
- Mechatronics technician scarcity:Facilities in the Midwestern United States struggle to staff maintenance roles requiring simultaneous competency in PLC programming, sensor calibration, and mechanical repair.
- ISO 3691-4 certification timelines:Safety validation for autonomous mobile robot systems extends 14 to 18 months, delaying revenue recognition for integrators with backlog concentration.
- Warehouse management system integration:Legacy WMS architectures built for conveyor logic require middleware development that consumes 30 percent of project implementation hours.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conveyor-Free Sortation Modules Market Trends and Innovations
Software-defined orchestration layers are decoupling robot hardware from facility control systems, enabling mixed-fleet operations where equipment from competing OEMs interoperate through standardized APIs.
Swarm-based sortation algorithms is modularizing fulfillment architecture by enabling 50-robot clusters to self-organize pick-and-pass routes without centralized traffic management. Third-party logistics operators in the Netherlands deploy these configurations to handle Black Friday volume spikes that would require 300 meters of fixed conveyor. The approach compresses capital deployment from permanent infrastructure to variable robot-as-a-service contracts.
REACH substance restrictions on industrial battery chemistries are forcing mobile robot manufacturers to eliminate cobalt content from lithium-thionyl-chloride backup cells used in safety systems. German system integrators now source solid-state alternatives from South Korean suppliers, adding eight to twelve weeks to procurement lead times. Cold-chain operators face the steepest compliance costs as temperature-rated power systems fall outside standard substitution pathways.
Facility leasing structures are fragmenting automation ownership models. Real estate investment trusts in the United Kingdom now embed conveyor-free modules as tenant improvements, amortizing hardware across 10-year lease terms rather than requiring 3PLs to carry capital equipment. This shifts technology obsolescence risk to property owners while accelerating tenant move-in velocity.
Conveyor-Free Sortation Modules Market Segmentation
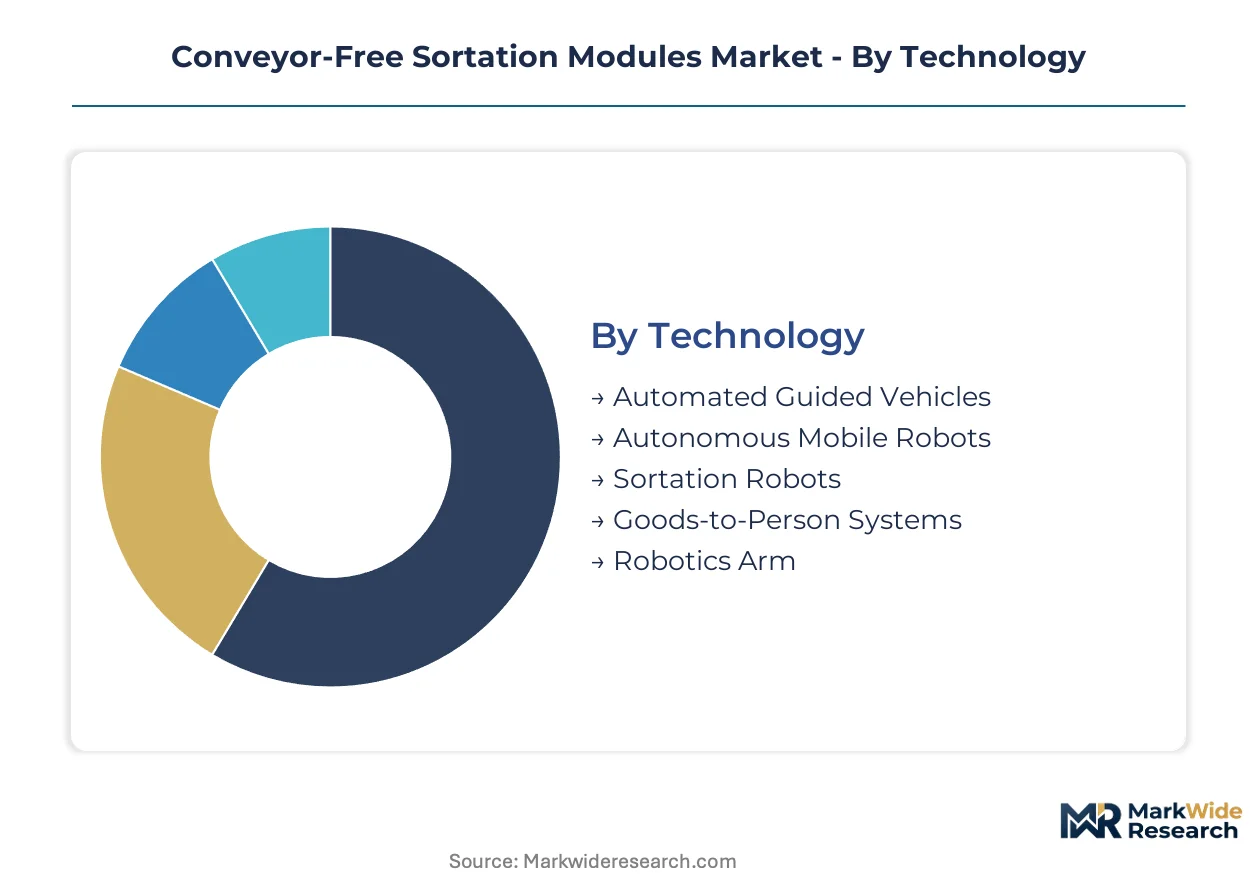
Segmentation in conveyor-free sortation modules reveals how buyer priorities diverge across operational scale, facility age, and SKU complexity. Technology choices separate capital-intensive greenfield projects from retrofit scenarios, while application segments expose which verticals absorb pricing premiums for environmental hardening.
Technology:
Buyers differentiate by throughput requirements versus flexibility needs, with peak-volume operators favoring fixed-path systems and multi-tenant facilities prioritizing reconfigurable fleets.
- Autonomous Mobile Robots:Battery-powered units navigate dynamic warehouse layouts using lidar and 3D vision without fixed infrastructure. E-commerce fulfillment centers in the United States deploy these for seasonal volume surges that would require permanent conveyor expansion. Demand concentrates where SKU volatility exceeds 40 percent annually.
- Goods-to-Person Systems:Robotic shuttles retrieve inventory to stationary pick stations, eliminating worker travel time. Parcel hubs in Germany adopt these for last-mile sortation where labor costs exceed 25 euros hourly. Cold-chain food distribution commands sealed, temperature-rated variants at substantial premiums.
- Automated Guided Vehicles:Wire-guided or magnetic-tape-following transport vehicles follow predetermined routes. Legacy manufacturing facilities retain these where layout changes occur less than once per decade.
- Sortation Robots:Articulated units with suction or gripper end-effectors divert parcels to destination containers. Asian airport baggage systems utilize these for irregular-shaped items that defy conveyor handling.
- Robotics Arm:Multi-axis manipulators perform pick-and-place operations from unstructured inputs. Electronics handling applications specify these for fragile component manipulation requiring sub-millimeter precision.
Autonomous Mobile Robots lead volumes today; Goods-to-Person Systems are gaining share fastest in cold-chain deployments.
Application:
Margin structures vary dramatically by handling environment, with temperature-controlled applications extracting 35 percent pricing premiums over ambient operations due to sealing and material requirements.
- E-commerce Fulfillment:High-velocity operations processing 2,000-plus items hourly within constrained urban footprints. United States-based Amazon and Walmart facilities drive specification toward modular, rapid-deployment architectures. Peak seasonality demands systems that scale robot count within 48 hours.
- Parcel & Postal:Hub-and-spoke networks handling polybags, boxes, and irregular parcels. European operators face EU Machinery Directive compliance deadlines accelerating replacement of legacy belt systems. Last-mile density in urban centers favors compact mobile robot configurations.
- Food & Beverage Distribution:Refrigerated and frozen supply chains requiring IP67 sealing and corrosion-resistant components. North American protein fulfillment absorbs the steepest capital costs due to continuous 18-hour duty cycles.
- Apparel Distribution:Soft-goods handling with high return rates and polybag predominance. Fast-fashion retailers specify gentle handling to prevent packaging damage.
- Electronics Handling:Fragile, high-value items requiring anti-static and shock-isolated transport. Semiconductor distribution centers specify vibration damping beyond standard industrial ratings.
Parcel & Postal generates the deepest installed base; Food & Beverage Distribution shows the steepest expansion trajectory as cold-chain automation penetrates protein and dairy networks.
End User Industry:
Procurement authority concentrates differently across verticals, with 3PLs demanding vendor-agnostic APIs while captive retail operators accept single-source stacks for tighter integration.
- Third-Party Logistics Providers:Multi-tenant operators serving divergent client requirements with shared infrastructure. These buyers prioritize robot-as-a-service contracts that transfer obsolescence risk to vendors. Swiss and Dutch campus-style facilities specify mixed-fleet interoperability.
- Retail Distribution Centers:Captive networks optimized for private-label SKU portfolios. Big-box operators in the United States retrofit legacy buildings where floor flatness disqualifies 40 percent of available industrial real estate.
- Manufacturing Facilities:Production-integrated material handling with just-in-time sequencing. Automotive suppliers specify AGVs for predictable, high-volume component delivery.
- Warehousing Operators:General-purpose storage providers adding value-added services. These buyers lag in adoption due to fragmented ownership and short lease terms.
- Courier Services:Express networks with time-definite delivery commitments. Asian hub operators prioritize throughput density over reconfiguration flexibility.
Third-Party Logistics Providers lead contract value today; Retail Distribution Centers are expanding fastest as grocery e-commerce forces ambient and cold-chain automation.
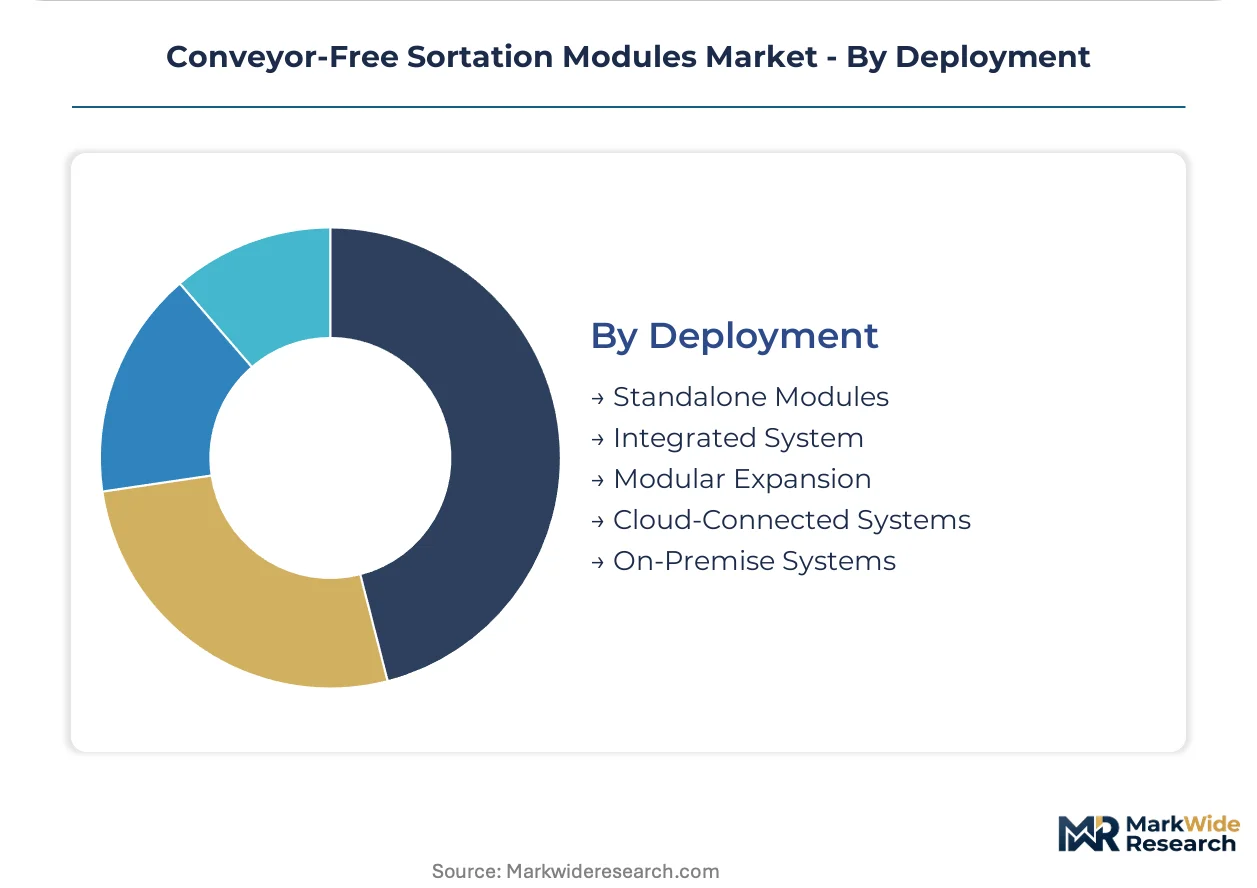
Deployment:
Ownership models fragment between capital-intensive on-premise installations and operational-expense-focused cloud-managed services, with real estate investment trusts increasingly embedding hardware as tenant improvements.
- Modular Expansion:Phased capacity additions that preserve initial capital outlay. United Kingdom-based property owners amortize these across 10-year lease terms, accelerating tenant move-in velocity.
- Cloud-Connected Systems:Centralized fleet optimization via ultra-reliable low-latency 5G private networks. These configurations enable 500-plus robot deployments with coordination overhead previously requiring edge computing.
- Standalone Modules:Self-contained sortation cells for pilot programs or overflow capacity. Regional 3PLs deploy these to test workflows before facility-wide commitment.
- Integrated System:Comprehensive facility automation with unified control architecture. Large-scale European deployments specify these for greenfield campuses.
- On-Premise Systems:Locally hosted control software with no external connectivity. Defense and pharmaceutical verticals mandate these for data sovereignty compliance.
Integrated System retains the largest installed base; Cloud-Connected Systems are climbing the fastest as 5G private networks mature and multi-site operators demand centralized visibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys conveyor-free modules at triple the density of Germany, yet German operators face steeper regulatory deadlines that compress replacement timelines. China and Japan anchor Asia-Pacific adoption through e-commerce volume and airport modernization respectively. India emerges as a manufacturing alternative through production-linked incentive schemes.
United States
Amazon and Walmart drive specification toward modular architectures that scale robot counts within 48 hours for peak seasonality. OSHA workplace safety guidelines shape human-robot collaboration parameters in retrofit facilities. Chicago and Dallas-Fort Worth logistics corridors concentrate multi-tenant 3PL campuses where floor flatness remediation unlocks 40 percent of previously disqualified industrial real estate.
Germany
Distribution centers absorb accelerated depreciation schedules on legacy belt systems as CE marking requirements tighten collaborative robotics safety protocols. The EU Machinery Directive enforces validation timelines that extend 14 to 18 months for autonomous mobile robot certification. The Rhine-Ruhr industrial cluster hosts Swisslog and KUKA-heritage deployments serving pan-European fulfillment networks.
China
E-commerce fulfillment centers process 2,000-plus items hourly within constrained urban footprints where traditional conveyor infrastructure cannot fit. National standards under MIIT and SAMR govern robot safety and data sovereignty in automated warehouses. The Yangtze River Delta around Shanghai anchors Hikrobot and domestic OEM production serving Southeast Asian export markets.
Japan
Airport baggage handling systems sustain Daifuku dominance through decades of irregular-item sortation expertise. METI industrial automation incentives support 5G private network convergence for 500-plus robot fleet coordination. The Kansai region around Osaka concentrates parcel hub modernization for time-definite courier networks.
India
Production-linked incentives for automated material handling equipment create localized manufacturing pathways for cost-competitive export. BIS certification requirements shape component sourcing for temperature-rated mobile robots. The Maharashtra-Gujarat industrial corridor attracts system integrators serving Middle Eastern and African e-commerce fulfillment markets.
Conveyor-Free Sortation Modules Market Competitive Landscape
European producers anchor the premium-system tier; Asian fabricators hold volume-manufacturing positions. The vendor base concentrates around five to eight integrated system specialists with decades of material handling heritage, supplemented by emerging mobile-robot pure-plays. Two strategic archetypes dominate: robotics-first entrants with software-defined orchestration layers, and conveyor incumbents retrofitting portfolios toward modular architectures. Competitive moves center on strategic partnerships for 5G private network integration and geographic expansion through robot-as-a-service licensing.
Within the integrated-system tier, Swisslog leverages KUKA robotics heritage to anchor large-scale European deployments. Daifuku sustains Asia-Pacific airport and parcel hub dominance through baggage handling systems expertise. GreyOrange occupies the mobile-robot pure-play position with fleet designs explicitly engineered for conveyor-free workflows. These three exemplify how heritage in adjacent automation domains translates into sortation module market positioning without requiring identical technical foundations.
| Leading Market Players |
|---|
| Swisslog |
| GreyOrange |
| KNAPP |
| Daifuku |
| Hikrobot |
| SSI SCHAEFER |
| Dematic |
| Vanderlande |
| TGW Logistics Group |
| Others |
Pricing and Supply Chain Analysis
REACH substance restrictions on industrial battery chemistries gate qualified supply access and premium-tier pricing for cold-chain-compatible mobile robots, forcing manufacturers toward solid-state alternatives that command substantial procurement premiums while disqualifying standard substitution pathways for temperature-rated power systems.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for lithium-thionyl-chloride alternatives as solid-state cell production scales. Robot-as-a-service contracts dominate, with three-tier pricing structure across premium, standard, and economy levels differentiated by duty-cycle rating and IP sealing certification. Cost compression in economy-tier AMR fleets is intensifying because Chinese OEMs are exporting surplus production capacity. Third-party logistics operators show highest price sensitivity; captive retail distribution centers absorb premium pricing for tighter WMS integration.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for 500-plus robot deployments, while system integrators serve mid-tier retrofit projects. Component supply draws from China for rare earth magnet processing, Germany for precision drivetrain manufacturing, and South Korea for solid-state battery cells. Neodymium price volatility originating from Chinese processing concentration creates persistent margin exposure. Distribution runs through certified system integrators who validate ISO 3691-4 compliance before facility commissioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in conveyor-free sortation rests on lithium-ion power density improvements compressing total cost of ownership, while cold-chain hardening commands 35 percent pricing premiums that shift buyer willingness-to-pay curves upward.
For Market Incumbents: Anchor large-scale European deployments through KUKA-heritage robotics platforms that leverage decades of material handling expertise. Defend against mobile-robot pure-plays by embedding software-defined orchestration layers that enable mixed-fleet interoperability. Prioritize 5G private network partnerships for centralized fleet optimization across multi-tenant campuses. Invest in cold-chain IP67 sealing capabilities to capture protein and dairy fulfillment premiums. For New Entrants and Emerging Players: The EU Machinery Directive in Germany opens a window for specialized safety validation services that compress 14-to-18-month certification timelines for autonomous mobile robot systems. Target food and beverage distribution as the most penetrable vertical, where frozen conveyor maintenance costs render legacy systems economically unviable. Lead with robot-as-a-service contracts that transfer obsolescence risk and accelerate procurement decisions among capital-constrained 3PLs. For Investors and Strategic Acquirers: Roll-up economics work for mechatronics service specialists because ISO 3691-4 certification scarcity extends revenue recognition delays and creates captive maintenance relationships. Long-term viability favors platform-agnostic orchestration software over hardware-tethered fleets. Watch for 5G private network deployment velocity as the inflection signal indicating which operators can scale beyond 500-robot coordination thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| 5G Private Network Integration | Ultra-reliable low-latency communication enables centralized optimization of 500-plus robot fleets across multi-site deployments. |
| Cold-Chain Hardware Hardening | IP67 sealing and solid-state battery adoption unlocks 35 percent pricing premiums in North American protein fulfillment. |
| Robot-as-a-Service Licensing | Operational-expense models transfer technology obsolescence risk while accelerating tenant move-in velocity for property owners. |
| Software-Defined Orchestration | API standardization decouples hardware from control systems, enabling mixed-fleet operations across competing OEM equipment. |
| ISO 3691-4 Certification Investment | Safety validation capabilities compress 14-to-18-month timelines that currently delay revenue recognition for integrators. |
Research Methodology
Bottom-up e-commerce fulfillment modeling reconciled against top-down mobile robot production tracking forms the analytical core of this study. Primary interviews with warehouse operations directors, system integrator project managers, OEM procurement leads, and 3PL technology officers combined with secondary validation from customs trade data, SEC equipment supplier filings, EU Machinery Directive certification registries, and 5G private network deployment disclosures. Triangulation across stakeholder perspectives and quantitative supply-side indicators ensures segment-level accuracy.
Historical trendline analysis of facility automation capex cycles and robot density per square foot informed projection frameworks across the analysis window. Segmentation dimensions modeled include technology type, application environment, deployment ownership structure, and regional regulatory cluster. CAGRs derived from installed base growth trajectories, replacement cycle compression, and greenfield facility automation rates. Cold-chain penetration curves and 5G network maturity served as industry-specific forecast inputs.
Revisions become necessary when EU Machinery Directive enforcement timelines accelerate, rare earth magnet supply disruptions persist, or floor flatness remediation costs shift retrofit economics. Forecasts reflect documented assumptions about lithium-ion duty cycle improvements and cloud-connected system adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.