
 Global Architecture Software Market | 2026-2036
Global Architecture Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Architecture Software Market Intelligence
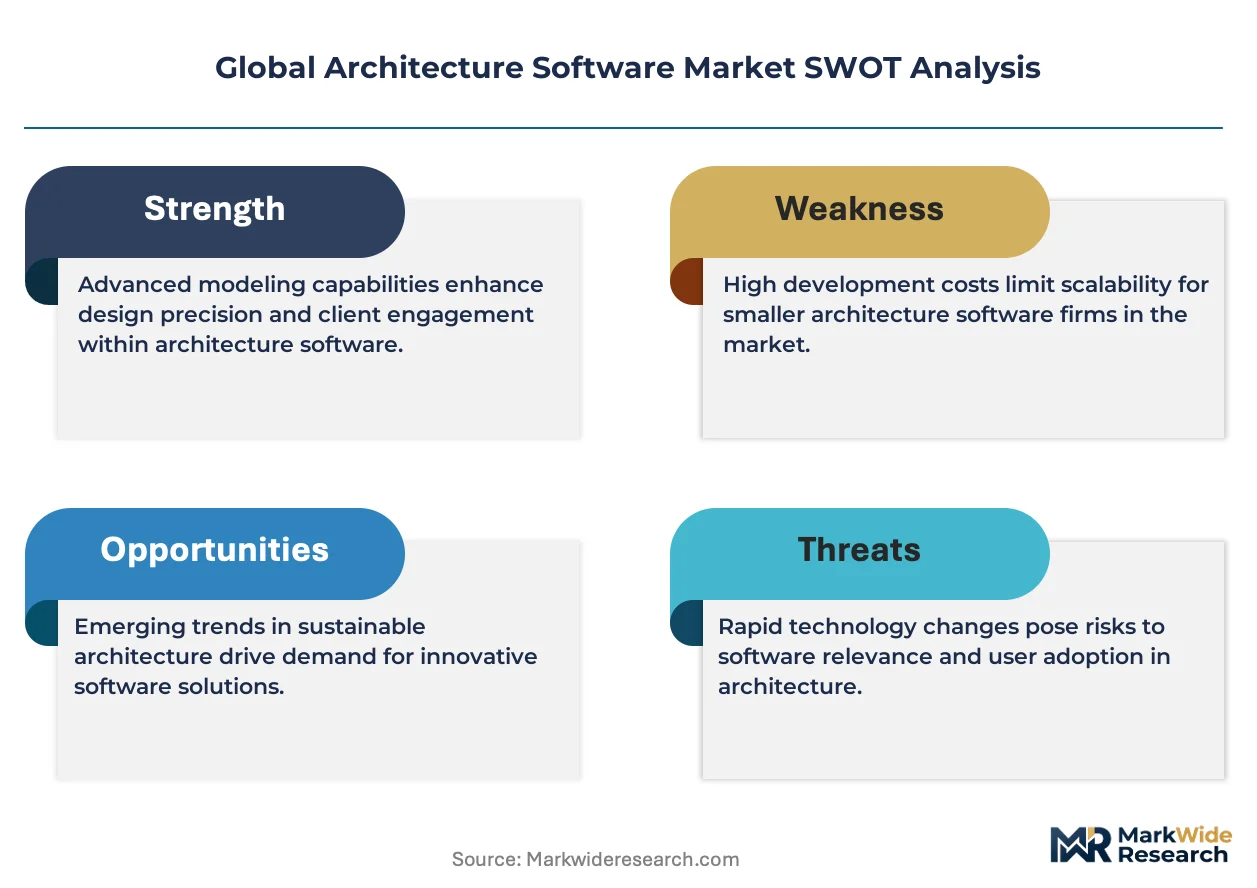
Enterprise-grade BIM certification is collapsing the gap between mid-market tools and premium platforms. Autodesk leverages its vertical integration across design-to-construction workflows to sustain pricing power. Bentley Systems anchors large infrastructure accounts with deep civil engineering functionality. Trimble competes through hardware-software convergence in field-to-office coordination.
Architecture software encompasses computational platforms for building design, documentation, and performance simulation, typically operating through parametric modeling engines that process geometric data, material specifications, and environmental load calculations to generate construction-ready deliverables. Building Information Modeling leads structural segment value due to its mandate-driven adoption in public procurement across multiple jurisdictions, while cloud-based deployment shows the fastest expansion as distributed project teams require real-time model synchronization. SaaS delivery captures growing margin pools through recurring revenue structures that reduce upfront capital barriers for smaller architectural firms.
The EU Green Deal and Energy Performance of Buildings Directive tighten digital documentation requirements across France, Germany, and the Netherlands. The US EPA and state-level stretch codes in California and New York compel energy modeling integration within design software. China's GB standards and dual carbon goals enforce building lifecycle carbon tracking. Stakeholders must monitor which regulatory jurisdictions will mandate open BIM interoperability standards first, as this determination will reshape competitive positioning across vendor ecosystems.
Market Dynamics
Cloud-native deployment is fragmenting traditional perpetual-license revenue models while EU Green Deal mandates compress procurement timelines for energy-compliant design tools.
Growth Catalysts
- EU Green Deal:Building performance standards in France, Germany, and the Netherlands mandate digital energy documentation, forcing BIM adoption across public procurement workflows.
- Commercial real estate:Large-scale mixed-use developments in Singapore and Dubai require integrated design-to-construction platforms for complex facade and MEP coordination.
- Generative design engines:Parametric optimization tools reduce material waste by automating structural load path calculations during early schematic phases.
Market Restraints
- Cloud infrastructure concentration:Hyperscale data center reliance creates vendor lock-in risks for SaaS-dependent architectural practices.
- Interoperability friction:Proprietary file formats between competing BIM platforms increase translation errors and rework costs on multi-consultant projects.
- Specialized talent scarcity:Computational design expertise remains concentrated in top-tier metropolitan practices, limiting mid-market adoption velocity.
Strategic Opportunities
- India's Smart Cities Mission:Urban infrastructure digitization creates demand for GIS-integrated planning tools across 100 designated municipalities.
- Retrofit-focused SaaS modules:Existing building energy modeling addresses Europe's renovation wave requirements under the Energy Performance of Buildings Directive.
- AI-enabled code compliance:Automated zoning and accessibility checking reduces permit approval cycles for multifamily housing developers.
Industry Challenges
- Legacy CAD migration costs:Established practices face workflow disruption and retraining expenses when transitioning from 2D documentation to model-based delivery.
- Open BIM standard delays:Fragmented industry governance slows universal IFC implementation, perpetuating data loss between design and construction phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Architecture Software Market |
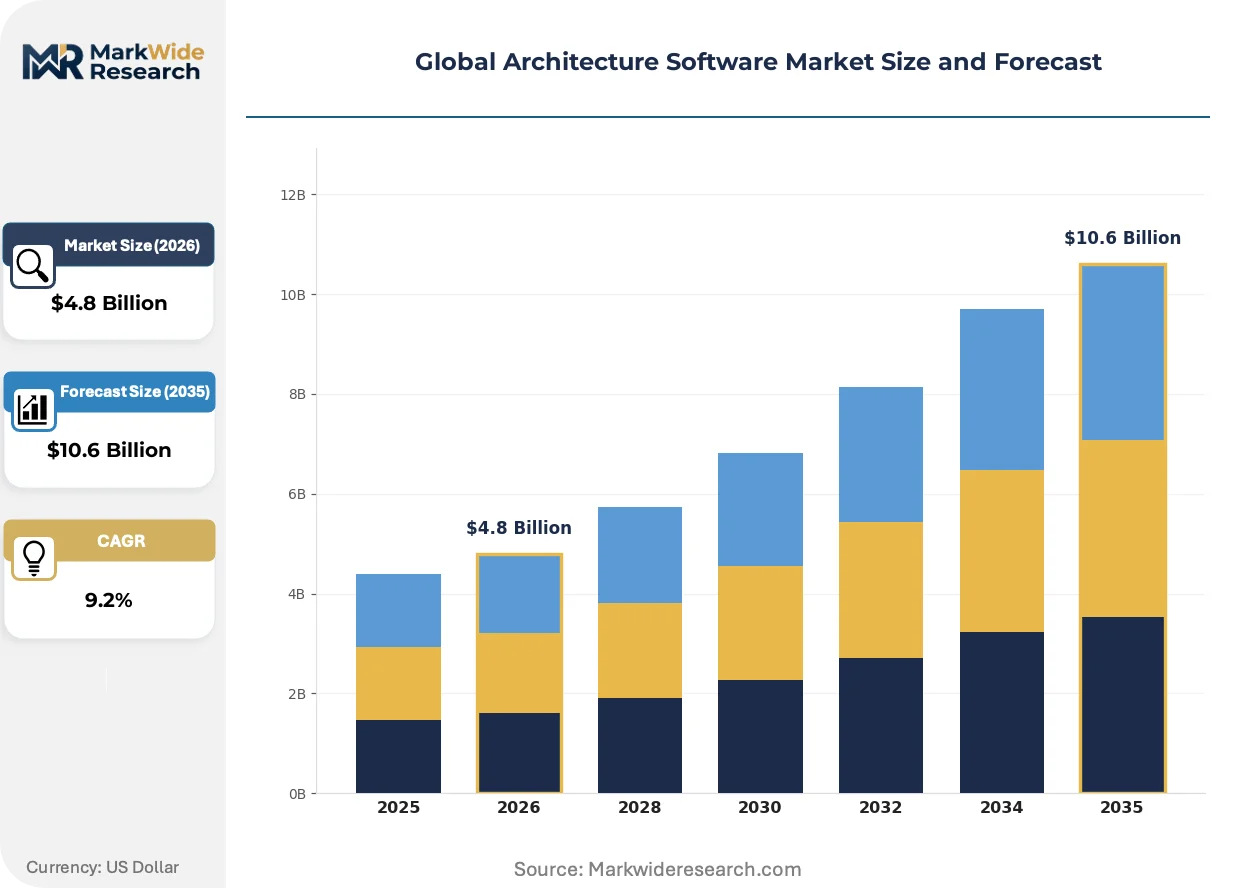
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.6 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Software Type: Building Information Modeling, Computer-Aided Design, Project Management, Visualization, Cost Estimation Deployment Mode: Cloud-Based, On-Premises, Hybrid, Hosted, SaaS Application: Residential Development, Commercial Complexes, Institutional Facilities, Urban Planning, Interior Design, Landscape Architecture End User: Architectural Firms, Engineering Consultants, Construction Managers, Real Estate Developers, Urban Planners |
| Companies Covered | Trimble, Epic Games, Autodesk, Robert McNeel and Associates, Chaos Software, Bentley Systems, Vectorworks, Blender Foundation, Graphisoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Architecture Software Market Strategic Shifts & Innovations
Computational methods are displacing rule-of-thumb design heuristics while regulatory pressure accelerates embedded carbon tracking capabilities across vendor roadmaps.
AI-assisted generative design is fragmenting traditional architect-led schematic workflows. Boutique firms and developer in-house teams deploy topology optimization for structural efficiency. This capability is compressing fee structures for early-phase design services as automation substitutes for junior staff hours.
CSRD disclosure requirements in Europe mandate embodied carbon reporting across building lifecycles. Software vendors integrate Environmental Product Declaration databases directly into material specification workflows. French and German public clients now reject proposals lacking automated carbon accounting modules.
Subscription fatigue among mid-sized practices is driving unbundled procurement of specialized analysis tools. Firms assemble best-of-breed stacks for daylighting, acoustics, and energy rather than accepting monolithic suites. This pattern is most pronounced in Australia's competitive residential sector where margins resist full-platform commitments.
Global Architecture Software Market Segmentation
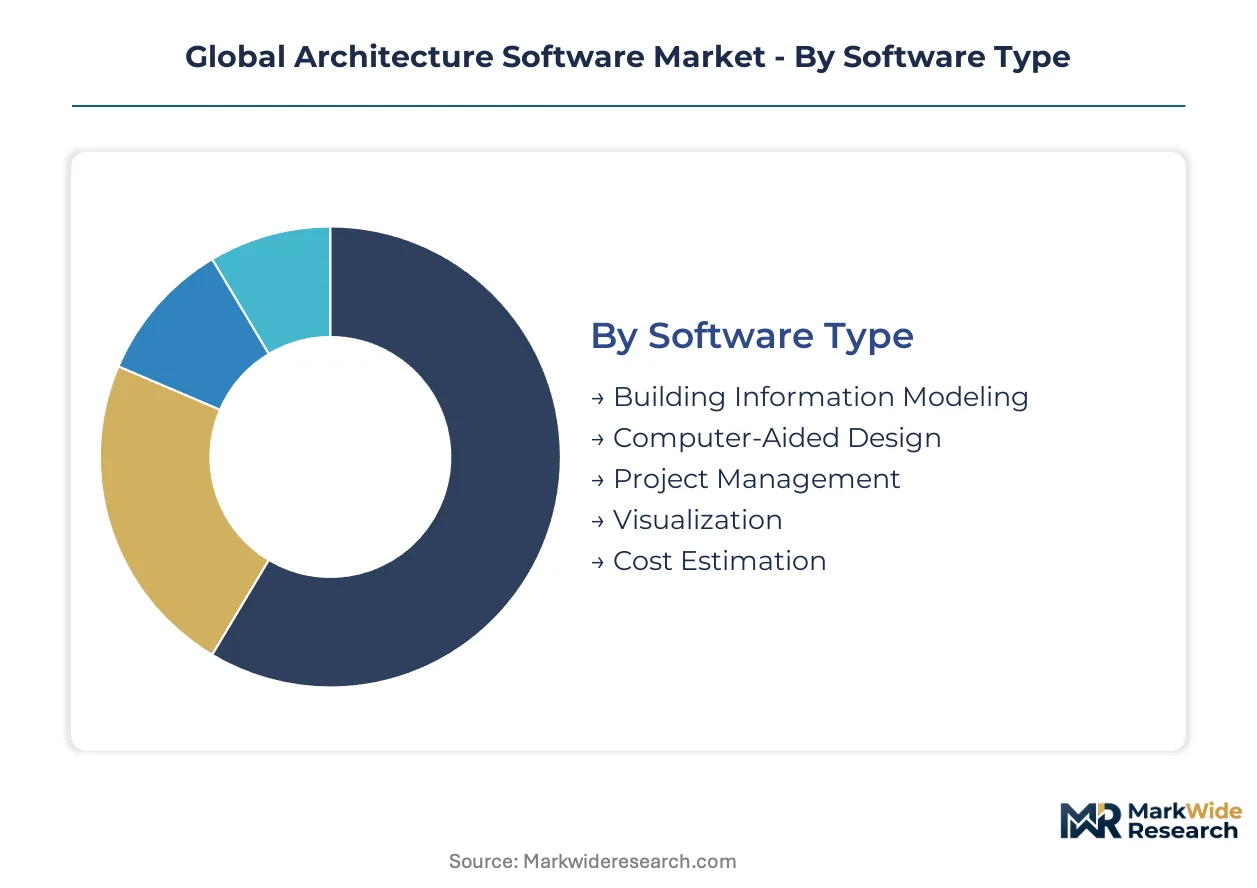
Architecture software vendors configure product roadmaps around distinct capability bundles that align with regulatory mandates and project complexity tiers. Segmentation reveals where pricing power concentrates and which deployment models capture margin expansion across geographic markets.
Software Type:
Building Information Modeling dominates procurement in jurisdictions with mandatory digital deliverables, while Computer-Aided Design retains entrenched positions in markets with legacy documentation requirements.
- Building Information Modeling:Parametric modeling engines process geometric data, material specifications, and environmental load calculations for construction-ready deliverables. Germany's energy-efficient building mandates and France's public procurement rules accelerate BIM deployment across public sector workflows.
- Computer-Aided Design:2D drafting platforms persist in established practices facing workflow disruption costs during model-based transitions. Smaller firms in Australia's residential sector resist full-platform commitments due to margin compression.
- Project Management:Integrated scheduling and resource allocation modules address coordination complexity in Singapore and Dubai mixed-use developments.
- Visualization:Real-time rendering engines serve client presentation requirements and design review cycles.
- Cost Estimation:Automated quantity takeoff tools reduce manual calculation errors in quantity surveying workflows.
Building Information Modeling commands the established base. The steepest expansion runs through Project Management modules as integrated design-to-construction platforms gain traction.
Deployment Mode:
Cost tier differentiation separates enterprise-grade subscriptions from entry-level offerings, with recurring revenue structures reducing upfront capital barriers for smaller practices.
- Cloud-Based:Distributed project teams require real-time model synchronization across multiple locations. EU Green Deal mandates compress procurement timelines, favoring rapid deployment without infrastructure investment.
- SaaS:Recurring revenue models capture growing margin pools while reducing customer acquisition friction. Subscription fatigue among mid-sized practices drives unbundled procurement of specialized analysis tools.
- On-Premises:Data sovereignty requirements and legacy IT infrastructure maintain relevance in regulated sectors.
- Hybrid:Mixed deployment accommodates sensitive project data alongside collaborative workflows.
- Hosted:Managed service arrangements address IT capability gaps in smaller architectural practices.
On-Premises retains the installed base among security-sensitive clients. Cloud-Based deployment is gaining share fastest as distributed teams become standard across multinational projects.
Application:
Volume concentration tracks urbanization intensity, with commercial and institutional segments driving platform standardization.
- Commercial Complexes:Large-scale mixed-use developments require integrated platforms for complex facade and MEP coordination. Singapore and Dubai developments specify BIM deliverables as contract requirements.
- Residential Development:Multifamily housing developers deploy automated zoning and accessibility checking to compress permit approval cycles. Australia's competitive residential sector shows pronounced unbundled procurement patterns.
- Institutional Facilities:Public sector mandates enforce digital documentation standards across healthcare and education projects.
- Urban Planning:India's Smart Cities Mission creates demand for GIS-integrated planning tools across 100 designated municipalities.
- Interior Design:Specialized visualization requirements drive best-of-breed tool selection.
- Landscape Architecture:Terrain modeling and environmental integration capabilities address site-specific design challenges.
Commercial Complexes anchor current revenue concentration. Urban Planning shows the steepest trajectory as infrastructure digitization accelerates across emerging economies.
End User:
Customer type determines purchasing authority and platform commitment depth, with construction-phase stakeholders gaining influence over software selection.
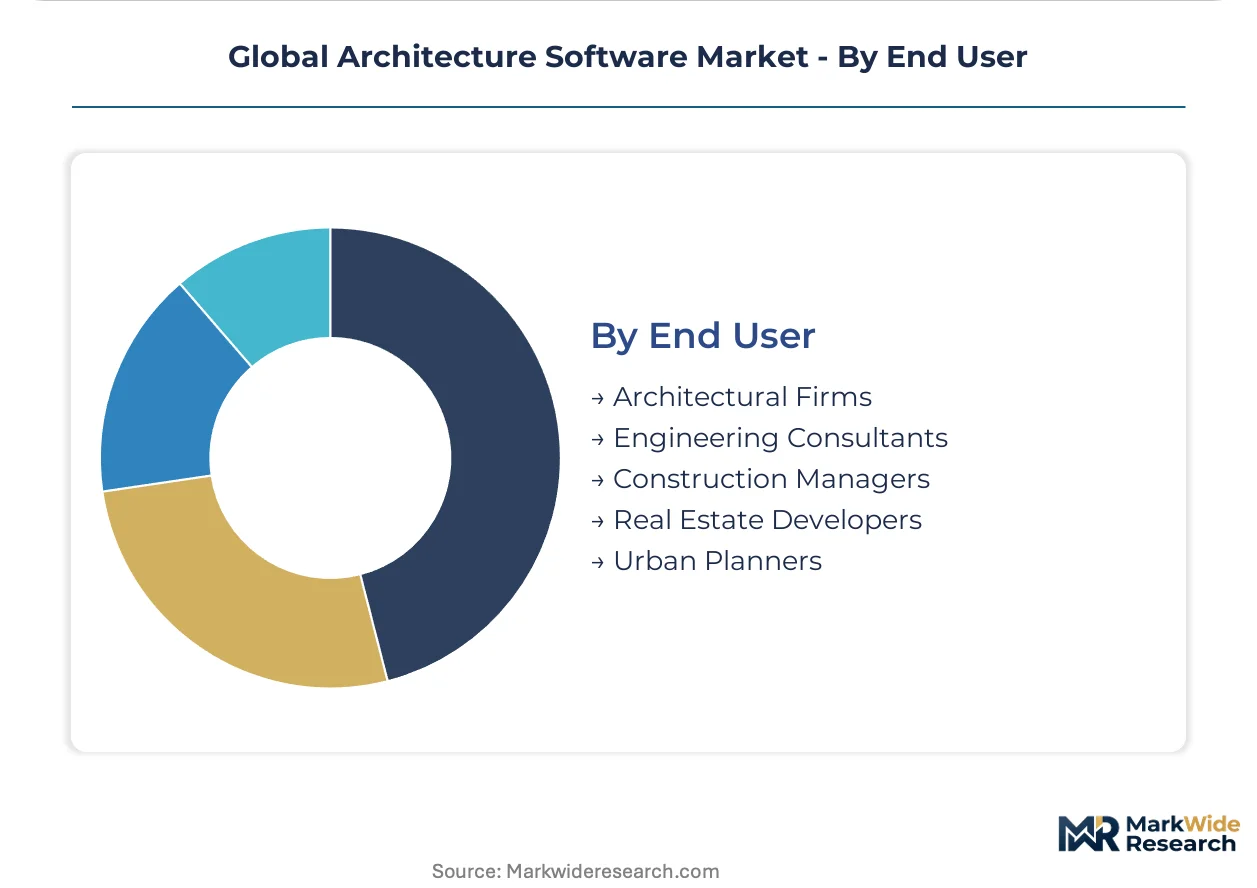
- Architectural Firms:Design-led practices face workflow disruption and retraining expenses when transitioning from 2D documentation to model-based delivery. CSRD disclosure requirements in Europe mandate embodied carbon reporting capabilities.
- Construction Managers:Field-to-office coordination requirements drive hardware-software convergence in procurement decisions. China's GB standards enforce building lifecycle carbon tracking across project phases.
- Engineering Consultants:Structural and MEP specialists require deep civil engineering functionality for large infrastructure accounts.
- Real Estate Developers:Asset lifecycle management interests align with integrated design-to-construction platforms.
- Urban Planners:Municipal authorities specify open data standards and interoperability requirements in procurement frameworks.
Architectural Firms represent the established customer base. Construction Managers are expanding most quickly as project delivery methods shift toward integrated teams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German software vendors export BIM platforms to French and Dutch public procurement markets, establishing a trade-flow corridor that channels energy-compliant design tools across EU member states.
United States
Commercial real estate developers in Manhattan and San Francisco deploy integrated design-to-construction platforms for complex mixed-use towers. The EPA and state-level stretch codes in California and New York compel energy modeling integration within design software. Austin and Denver tech corridors host emerging computational design consultancies serving multifamily housing developers.
Germany
Energy-efficient building mandates from the KBA and federal construction standards accelerate BIM deployment across public sector workflows. The EU Green Deal tightens digital documentation requirements for building performance standards. Munich and Frankfurt engineering clusters drive demand for civil engineering functionality in large infrastructure accounts.
China
Urban infrastructure digitization under GB standards and dual carbon goals enforces building lifecycle carbon tracking across project phases. The MIIT oversees software certification for smart city applications. Shenzhen and Shanghai development zones specify BIM deliverables as contract requirements for commercial complexes.
United Arab Emirates
Dubai and Abu Dhabi mixed-use developments require integrated platforms for complex facade and MEP coordination. MOHAP procurement frameworks increasingly mandate digital documentation standards. The Dubai Design District clusters architectural practices adopting hardware-software convergence for field-to-office coordination.
India
The Smart Cities Mission creates demand for GIS-integrated planning tools across 100 designated municipalities. BIS standards for building information modeling gain traction in public infrastructure tenders. Bengaluru and Hyderabad tech corridors host distributed project teams requiring real-time model synchronization for commercial developments.
Global Architecture Software Market Key Industry Players
Listed leaders compete with private specialists across capital access and product development velocity. Autodesk leverages its position across design-to-construction workflows to sustain pricing power. Bentley Systems anchors large infrastructure accounts with deep civil engineering functionality. Three archetypes dominate: platform consolidators with vertical workflow integration, specialized engineering tool developers, and hardware-software convergence players. Competitive moves center on strategic partnerships for interoperability standards and portfolio diversification into retrofit-focused SaaS modules.
Among North American platform consolidators, Autodesk and Trimble occupy positions spanning architecture, engineering, and construction workflows. Bentley Systems represents the specialized engineering tier with its infrastructure-focused portfolio. These three exemplify how vendor ecosystems differentiate through workflow depth rather than horizontal breadth alone.
| Leading Market Players |
|---|
| Trimble |
| Epic Games |
| Autodesk |
| Robert McNeel and Associates |
| Chaos Software |
| Bentley Systems |
| Vectorworks |
| Blender Foundation |
| Graphisoft |
| Others |
Cost & Logistics Intelligence
Project-based SaaS licensing locks in multi-year platform commitments for architectural firms while compressing procurement cycles under EU Green Deal timelines. This contract structure anchors price visibility across deployment tiers and secures cloud infrastructure access for distributed design teams in Germany, France, and the Netherlands.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates enterprise BIM suites from mid-market subscriptions and entry-level CAD tools. Subscription fatigue among Australian residential practices intensifies cost compression in the standard tier, while CSRD-mandated carbon accounting modules command brand premiums in France and Germany. Cloud-native deployment models reduce upfront capital barriers but embed recurring revenue obligations that smaller firms resist.
Supply Chain Analysis
Hyperscale data center concentration in the United States, Ireland, and Singapore creates single-source vulnerability for SaaS-dependent architectural practices. Software vendors draw from NVIDIA GPU clusters, AWS compute instances, and proprietary rendering engines to deliver real-time collaboration features. Distribution runs through direct enterprise sales teams and channel partners serving mid-market practices across EU member states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Architecture software sits in early-cycle expansion as mandatory BIM adoption in public procurement creates irreversible platform commitments across EU jurisdictions.
For Market Incumbents: Shield installed-base revenue by embedding carbon accounting modules ahead of CSRD enforcement timelines. Deepen backward integration into cloud rendering infrastructure to reduce hyperscaler dependency. Acquire specialized energy modeling boutiques before regulatory mandates consolidate procurement around integrated platforms. For New Entrants and Emerging Players: EU Green Deal certification fast-tracks market access for retrofit-focused SaaS modules addressing Europe's renovation wave. White-space concentrates in India's Smart Cities Mission municipalities lacking GIS-integrated planning tools. Position through unbundled procurement channels serving Australia's margin-compressed residential sector. For Investors and Strategic Acquirers: Capital is best deployed toward vertical workflow integrators with design-to-construction platform breadth. Long-term viability hinges on regulatory mandate capture across multiple jurisdictions. Monitor which EU member state first mandates open BIM interoperability standards as the inflection signal for competitive reshuffling.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Autodesk's design-to-construction workflow convergence sustains pricing power across enterprise accounts. |
| Acquisition of Specialist Firm | Bentley Systems' infrastructure engineering depth anchors large civil accounts with embedded carbon tracking. |
| Strategic Partnership | Trimble's hardware-software convergence addresses field-to-office coordination in Dubai mixed-use developments. |
| Geographic Expansion | Cloud deployment captures India's Smart Cities Mission demand across 100 designated municipalities. |
| Product Launch | AI-enabled code compliance tools compress permit cycles for multifamily housing developers in California. |
Research Approach
A spread of perspectives from software vendor product managers, architectural firm CTOs, construction manager procurement leads, and EU regulatory affairs specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against SEC filings, EU tender databases, and hyperscaler capex disclosures. Bottom-up deployment modeling triangulated against top-down market sizing across software type, deployment mode, and application segments.
Segmentation dimensions modeled include deployment architecture, organization scale tier, vertical integration depth, and regional regulatory adoption pattern. CAGRs derive from installed base migration curves and new license origination rates across the analysis window. Forecast inputs incorporate EU Green Deal implementation timelines and India's Smart Cities Mission procurement schedules.
Decision-makers should treat outputs as directional under sustained public procurement mandate expansion; material deviation in regulatory enforcement velocity would warrant model refresh. Practitioners should keep alternative scenarios live as open BIM standard adoption timelines and cloud infrastructure sovereignty requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Middle-East Virtual Data Room Market
Software & Services
Gym Motion Tracking Software Market
Software & Services
Freight Management Software Market
Software & Services
Middleware Market
Software & Services
Asia-Pacific Database Management Software Market
Software & Services
B2B Gateway Software Market
Software & Services
Construction Suites Software Market
Software & Services
Global App Store Optimization Tools Software Market
Software & Services
Global Printing Software Market
Software & Services
Nonconformance Management Software Market
Software & Services
Global Apparel Management Software Market
Software & Services
Global Gamification Software Market
Software & Services
Eclinical Solutions and Software Market
Software & Services
Programmable Automation Controller (PAC) Programming Software Market
Software & Services
Stock Control Software Market
Software & Services
Global VR Game Engine Software Market