
 Revitalizing Skin Wands Market | 2026-2036
Revitalizing Skin Wands Market Size, Share, and Industry Trends Forecast 2026-2036
Revitalizing Skin Wands Market Analytics
Med-spa and dermatology clinic procurement is repositioning toward multi-technology platforms that combine microcurrent, LED, and RF modalities in single devices. HydraFacial leverages its professional-channel installed base to cross-sell wand accessories into clinic workflows. Kansa anchors its position through Ayurvedic-metal differentiation and direct-to-consumer storytelling. PureLift competes on microcurrent waveform IP developed for pre-event facial lifting protocols.
Revitalizing skin wands are handheld electromechanical or photonic devices engineered to deliver subcutaneous stimulation through controlled energy output, typically operating at frequencies between 1–3 MHz for ultrasonic variants or wavelengths of 630–850 nm for LED systems, with primary commercial purpose being non-invasive dermal rejuvenation and muscle toning. Ultrasonic wands and microcurrent devices lead volume shipments due to lower per-unit cost and established consumer education, while LED wands capture expanding margin pools as phototherapy efficacy claims gain clinical bibliography support. RF Technology segments sustain premium pricing through thermal collagen remodeling protocols that require higher safety documentation and practitioner training.
FDA 510(k) clearance requirements for RF and microcurrent devices shape product development timelines and limit market access for unvalidated hardware imports. EU MDR and REACH compliance obligations add material biocompatibility testing burdens, particularly for wand surfaces contacting facial skin. Stakeholders must monitor evolving home-use versus professional-use classification boundaries, as regulatory reclassification could reshape channel economics and liability exposure across the value chain.
Market Dynamics
Multi-modality device convergence is compressing procurement cycles across dermatology clinics and med-spa networks, forcing single-technology vendors to defend installed bases through accessory compatibility or platform migration incentives.
Growth Catalysts
- FDA 510(k) pathway maturation:Clearance precedents for RF-microcurrent combinations reduce regulatory uncertainty for follow-on filers, accelerating US market entry timelines.
- Med-spa network consolidation:Roll-up activity among aesthetic clinic chains creates centralized procurement authority favoring multi-wand platform contracts.
- Phototherapy bibliography expansion:Peer-reviewed LED efficacy studies in dermatology journals validate consumer-facing claims, reducing education burden for direct-to-consumer brands.
Market Restraints
- EU MDR biocompatibility testing:REACH-compliant surface material documentation adds 12-18 month pre-market timelines for wand manufacturers targeting European dermatology clinics.
- Gallium nitride supply concentration:LED driver chip fabrication concentrates in East Asian foundries, exposing margin pressure from input cost volatility.
- Ultrasonic frequency saturation:1-3 MHz output bands face crowded patent landscapes, limiting waveform differentiation for new entrants.
Strategic Opportunities
- Brazilian clinic channel underpenetration:ANVISA regulatory alignment with FDA precedents creates expedited pathway for cleared US devices to capture aesthetic clinic procurement.
- Microcurrent-LED convergence:Simultaneous muscle toning and photobiomodulation protocols open premium positioning above single-modality price tiers.
- Direct-to-clinic subscription models:Hardware-as-a-service financing displaces capital expenditure barriers for independent dermatology practices.
Industry Challenges
- Biomedical engineer talent scarcity:RF safety documentation and thermal modeling expertise concentrates among legacy medical device firms, constraining startup hiring pipelines.
- 510(k) substantial equivalence disputes:FDA challenge rates for microcurrent predicate claims extend clearance timelines and burn development runway.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Revitalizing Skin Wands Market |
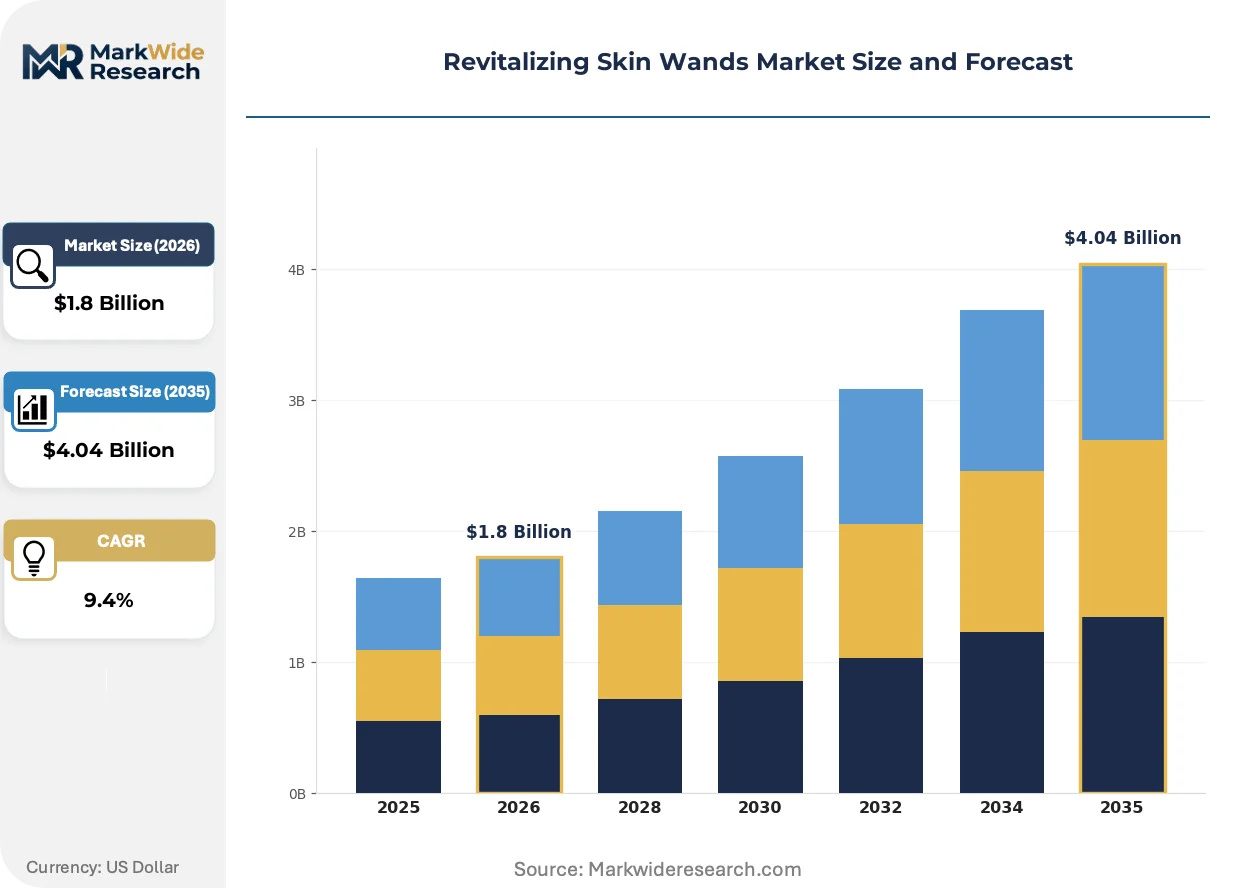
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Facial Rollers, Ultrasonic Wands, LED Wands, Microcurrent Devices End User: Retail Customers, Salons, Dermatology Clinics, Home Users Technology: RF Technology, Ion Technology, Vibrational Technology, Phototherapy Application: Anti-Aging, Hydration, Skin Tightening, Relaxation |
| Companies Covered | Derma, Kansa, PureLift, Opte's, LXMI, Olay, The Zorb, Vanity Planet, HydraFacial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Revitalizing Skin Wands Market Evolving Landscape
Platform unification across energy modalities is erasing category boundaries between professional and home-use device tiers, while regulatory documentation requirements reshape competitive moats around safety validation capabilities.
Hybrid RF-microcurrent-LED platforms are unifying previously separate treatment protocols into single handheld units. Dermatology clinic procurement teams now specify triple-modality compatibility as baseline requirements for new device contracts. This convergence is compressing addressable market scope for standalone ultrasonic or single-frequency RF vendors.
EU MDR technical documentation requirements for active implantable device classification boundaries are forcing wand manufacturers to reevaluate home-use versus professional-use labeling strategies. Surface contact biocompatibility testing under REACH now consumes disproportionate development budgets relative to core energy delivery engineering. German and French notified bodies are imposing additional clinical evidence demands for thermal RF claims above 45°C epidermal contact thresholds.
Clinic procurement teams are consolidating vendor relationships around full-platform contracts that bundle device hardware, disposable consumables, and training certification into single-source agreements. Independent med-spa operators face exclusion from preferred pricing tiers as chain networks leverage volume concentration. This buyer consolidation pattern is most visible in South Korea and the United States, where dermatology clinic roll-up activity has advanced furthest.
Revitalizing Skin Wands Market Segmentation
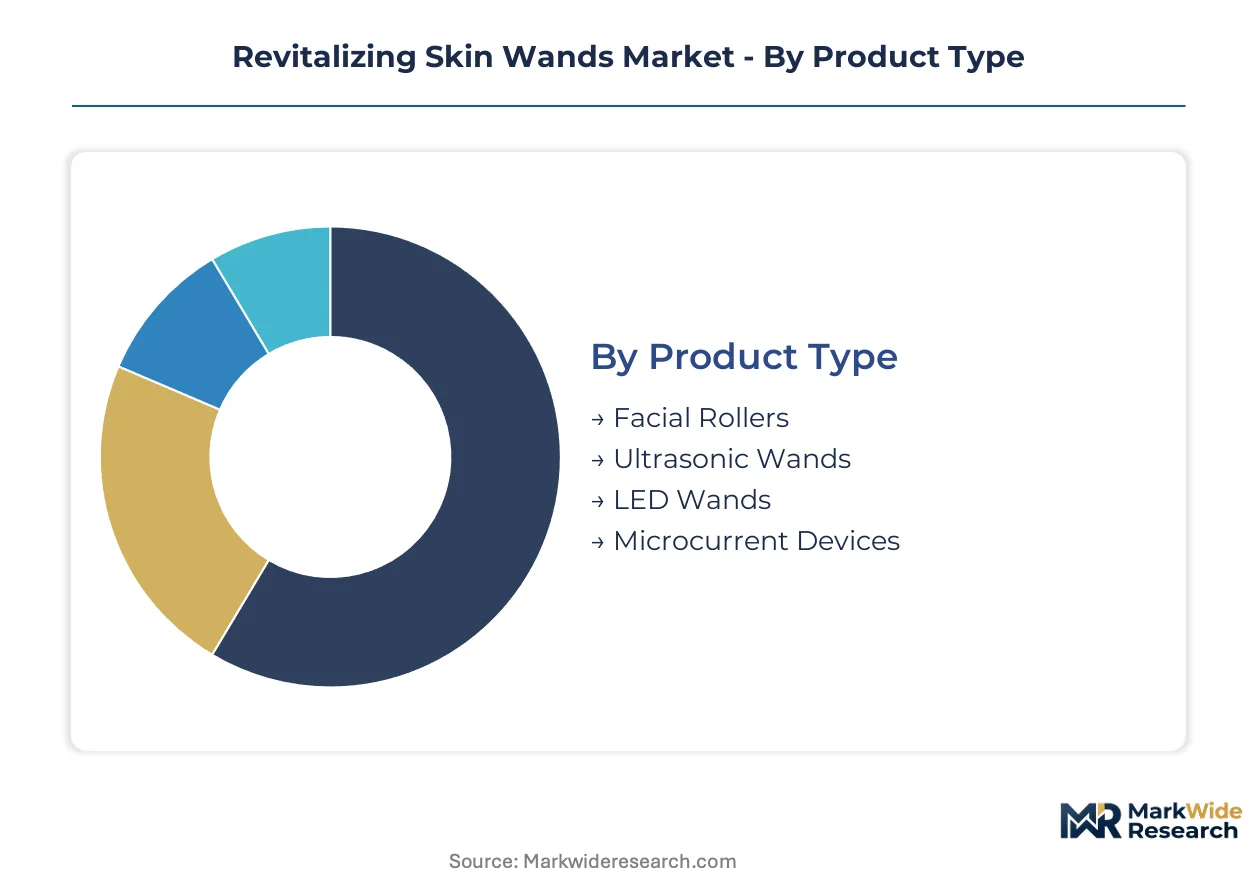
Technology convergence and regulatory classification boundaries reshape how vendors segment the revitalizing skin wands market. Procurement specifications now prioritize multi-modality compatibility over single-technology performance metrics.
Product Type:
Product architecture determines energy delivery mechanism and corresponding safety documentation burden under FDA and EU MDR pathways.
- Ultrasonic Wands:Piezoelectric transducers generate 1–3 MHz mechanical vibrations for epidermal exfoliation and serum penetration. Dermatology clinics in South Korea and the United States specify these as entry-tier devices for patient education protocols.
- Microcurrent Devices:Low-amplitude electrical waveforms stimulate facial musculature through subsurface tissue conductivity. Demand concentrates among med-spa chains seeking pre-event facial lifting protocols without thermal injury risk.
- LED Wands:Narrow-band photon emission at 630–850 nm wavelengths drives collagen synthesis through chromophore activation.
- Facial Rollers:Manual mechanical manipulation without active energy components occupies economy pricing tiers.
Ultrasonic wands lead on scale; microcurrent devices lead on momentum.
End User:
Channel economics diverge sharply between capital-intensive clinic procurement and direct-to-consumer subscription models.
- Dermatology Clinics:Licensed practitioners operate Class II medical devices under physician supervision, requiring FDA 510(k) clearance and thermal safety documentation. Clinic procurement teams in the United States negotiate multi-year platform contracts bundling hardware, disposables, and training certification.
- Salons:Aesthetic service providers occupy regulatory gray zones between professional medical devices and cosmetic appliances. Brazilian salon chains represent underpenetrated demand as ANVISA aligns with FDA clearance precedents.
- Home Users:Direct-to-consumer brands bypass clinical channel markups through e-commerce and influencer distribution.
- Retail Customers:Mass-market distribution through beauty retailers targets price-sensitive trial purchasers.
Home users expand most quickly; dermatology clinics capture premium margin pools.
Technology:
Energy modality selection determines thermal safety classification and corresponding biocompatibility testing scope under REACH and MDR.
- RF Technology:Radiofrequency oscillations at 0.3–10 MHz generate controlled dermal heating for collagen remodeling. German and French notified bodies impose additional clinical evidence demands for thermal claims above 45°C epidermal contact thresholds.
- Phototherapy:LED and laser-based light delivery systems leverage expanding peer-reviewed efficacy bibliographies to validate consumer-facing claims.
- Ion Technology:Galvanic current manipulation enhances topical product penetration through electrochemical gradient modification.
- Vibrational Technology:Mechanical oscillation without thermal or photonic energy components occupies simplified regulatory pathways.
RF technology commands pricing power; phototherapy gains share fastest.
Application:
Clinical indication targeting shapes device specification requirements and reimbursement positioning where applicable.
- Anti-Aging:Collagen induction and wrinkle reduction protocols drive premium device specifications combining RF thermal delivery with microcurrent muscle toning.
- Skin Tightening:Dermal elasticity restoration through neocollagenesis represents the highest-margin application segment.
- Hydration:Transdermal delivery enhancement for topical actives occupies mid-tier pricing through ultrasonic and iontophoretic mechanisms.
- Relaxation:Facial massage and stress reduction applications occupy entry-level price tiers with minimal regulatory burden.
Skin tightening leads on margin capture; anti-aging shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing manufacturing capacity toward jurisdictions with streamlined biocompatibility documentation, while procurement authority concentrates in clinic networks across mature aesthetic device markets. Compliance cost gaps between FDA 510(k) pathways and EU MDR obligations shape vendor geographic prioritization.
United States
Med-spa chain consolidation in Texas and Florida generates centralized procurement contracts favoring multi-modality platform vendors. FDA 510(k) clearance precedents for RF-microcurrent combinations reduce regulatory uncertainty for domestic filers. Los Angeles and New York City host the densest clinic clusters, with dermatology practices negotiating hardware-as-a-service financing to displace capital expenditure barriers.
South Korea
Seoul's Gangnam district anchors global aesthetic device innovation, with domestic clinic networks specifying triple-modality compatibility as baseline procurement requirements. MFDS streamlined pathways for LED phototherapy devices accelerate home-use product registration. Busan-Ulsan manufacturing corridors supply piezoelectric transducers for ultrasonic wand OEMs serving Asia-Pacific distribution.
Germany
Notified body concentration in Munich and Tübingen imposes additional clinical evidence demands for thermal RF claims above 45°C epidermal contact thresholds. REACH-compliant surface material documentation consumes disproportionate development budgets for European market entry. Baden-Württemberg precision engineering clusters fabricate high-frequency oscillators for professional-grade RF platforms.
China
NMPA regulatory harmonization with FDA technical standards creates expedited pathways for cleared US devices seeking domestic registration. Yangtze River Delta manufacturing bases dominate LED driver chip assembly, though gallium nitride foundry concentration exposes margin volatility. Shanghai and Beijing dermatology clinics drive premium device adoption through direct-to-consumer cross-selling from professional installed bases.
Brazil
ANVISA alignment with FDA clearance precedents creates expedited regulatory pathways for US-cleared devices targeting aesthetic clinic procurement. São Paulo salon chains represent underpenetrated demand for mid-tier microcurrent platforms. Southeast Asian component suppliers route ultrasonic transducer shipments through Brazilian free trade zones to circumvent import duty escalations.
Revitalizing Skin Wands Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with professional-channel vendors defending installed bases through platform migration incentives while direct-to-consumer brands bypass clinical markups via e-commerce distribution. Market structure tilts toward consolidation around multi-technology platform providers, compressing scope for standalone ultrasonic or single-frequency RF entrants. Three archetypes dominate: legacy dermatology device houses with regulatory validation depth, direct-to-consumer brands leveraging influencer distribution, and Asian OEMs supplying private-label hardware. Competitive intensity centers on M&A-driven clinic network penetration and biocompatibility documentation capabilities that accelerate EU MDR compliance.
Among professional-channel platform vendors, HydraFacial occupies a position exemplifying installed-base leverage through cross-selling workflows, while Kansa represents Ayurvedic-metal differentiation archetypes competing on direct-to-consumer storytelling. PureLift sits within the microcurrent waveform IP tier, with specialization in pre-event facial lifting protocols. These three anchors illustrate how regulatory validation depth, cultural positioning, and technical IP respectively structure competitive moats across segment boundaries.
| Leading Market Players |
|---|
| Derma |
| Kansa |
| PureLift |
| Opte's |
| LXMI |
| Olay |
| The Zorb |
| Vanity Planet |
| HydraFacial |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up dermatology clinic chains anchor procurement discipline across the revitalizing skin wands market, compressing vendor margins through multi-year platform contracts while concentrating volume leverage that reshapes upstream component sourcing priorities.
Pricing Analysis
Distributor markups in the professional channel compress as med-spa networks negotiate direct-to-manufacturer agreements. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA clearance tier and bundled training certification. Cost compression in the ultrasonic segment intensifies because East Asian OEMs flood private-label supply. Home users exhibit highest price sensitivity; dermatology clinics demonstrate lowest, prioritizing thermal safety documentation over per-unit cost.
Supply Chain Analysis
Domestic-content mandates in South Korea and China are reshaping sourcing patterns for LED driver chips and piezoelectric transducers. Manufacturing concentrates in China, South Korea, and Germany. Supply chains draw from gallium nitride foundries, precision oscillators, and biocompatible surface alloys. Single-source vulnerability in East Asian semiconductor fabrication exposes margin volatility. Distribution runs through med-spa procurement consortia and direct-to-consumer e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The revitalizing skin wands market compounds steadily as dermatology clinic network consolidation sustains recurring hardware upgrade cycles across installed bases.
For Market Incumbents: To counter microcurrent-LED convergence from Asian OEMs, deepen FDA 510(k) predicate libraries to accelerate clearance timelines for combination devices. Secure exclusive training certification contracts with rolling up clinic chains to lock in platform loyalty. For New Entrants and Emerging Players: Enter via Brazilian salon chains where ANVISA alignment with FDA precedents lowers regulatory barriers for cleared US devices. Target São Paulo aesthetic service networks with mid-tier microcurrent platforms distributed through hardware-as-a-service financing models. For Investors and Strategic Acquirers: Med-spa roll-up specialists are the most active acquirer in this space, seeking multi-modality platform vendors to consolidate procurement authority. Five-to-ten-year viability hinges on biocompatibility documentation capabilities that compress EU MDR timelines. Watch FDA challenge rates for microcurrent predicate claims as inflection signal for regulatory risk repricing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Precedent filings for RF-microcurrent combinations reduce regulatory uncertainty for follow-on entrants. |
| Multi-Modality Platform Integration | Triple-technology bundling satisfies Gangnam district clinic procurement specifications as baseline requirement. |
| Hardware-as-a-Service Financing | Subscription models displace capital expenditure barriers for independent dermatology practices in Texas and Florida. |
| EU MDR Biocompatibility Certification | REACH-compliant surface documentation accelerates market access for professional-grade RF platforms. |
| Direct-to-Consumer Channel Expansion | Influencer-driven e-commerce bypasses clinical markups while leveraging peer-reviewed phototherapy bibliographies. |
Research Methodology
Multiple input streams — primary interviews with dermatology clinic procurement directors, biomedical engineers at device manufacturers, and regulatory affairs specialists at notified bodies; secondary validation through FDA 510(k) filings, EU MDR technical documentation databases, and hospital procurement contract registries — were reconciled through bottom-up shipment tracking and top-down market sizing triangulation.
Historical adoption curves were cross-referenced against expert panel inputs across the projection horizon. Segmentation dimensions modeled include energy modality, end-user channel, and regulatory classification tier. CAGRs were derived from installed base replacement cycles and clinic network expansion trajectories. Industry-specific forecast inputs incorporate MFDS streamlined pathway timelines and ANVISA alignment protocols.
Inputs from regulatory filing databases and clinic procurement systems were available through the study window; gaps in private-label OEM shipment data introduce uncertainty bands around ultrasonic wand volume estimates. Forecasts reflect assumptions on clearance timeline standardization and chain consolidation velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Asia-Pacific Skincare Market
Skincare
Global Eczema Skin-Care Products Market
Skincare
Cystic Acne Market
Skincare
Moisturizing Cream Market
Skincare
Global Anti-Aging Products and Services Market
Skincare
After Sun Care Products Market
Skincare
DNA-Based Skin Care Products Market
Skincare
Exfoliators and Scrubs Market
Skincare
Encapsulated Retinol Market
Skincare
Europe Functional Cosmetics Market
Skincare
Medicine Skin Care Market
Skincare
Incontinence Skin Care Products Market
Skincare
Skin Replacement Market
Skincare
Herbal Skincare Products Market
Skincare
Skin Care Supplements Market
Skincare
Preoperative Skin Preparation Market