
 Exfoliators and Scrubs Market | 2026-2036
Exfoliators and Scrubs Market Size, Share, and Industry Trends Forecast 2026-2036
Exfoliators and Scrubs Market Analysis
South Korea is tilting toward advanced biotech-enabled exfoliation manufacturing, drawing contract development partners from across Asia-Pacific. L'Oréal leverages integrated fermentation-derived enzyme supply chains to secure cost advantages in premium peels. Estée Lauder Companies anchors North American prestige distribution through dermatologist office channels and dedicated e-commerce infrastructure. Shiseido competes on JIS-compliant botanical extraction standards that command pricing power in Japanese domestic retail.
Exfoliators and scrubs are topical skin-resurfacing formulations containing abrasive particles, hydroxy acids, or proteolytic enzymes that accelerate corneocyte desquamation through mechanical or biochemical action, typically delivered at pH 3.0–4.5 for acid-based variants to optimize keratinocyte turnover without barrier compromise. Their primary commercial purpose centers on addressing hyperkeratosis, post-inflammatory hyperpigmentation, and comedonal acne within both consumer self-care and professional treatment protocols. Chemical exfoliators lead value generation due to higher per-unit pricing and clinical positioning, while enzyme variants from fungal and fruit sources represent the fastest-expanding formulation class as brands reformulate away from polyethylene microbeads under microplastic restrictions. The professional segment within target audience segmentation captures disproportionate margin pools through bundled service protocols in medi-spa and aesthetic clinic settings.
The FDA oversees cosmetic safety labeling under the Federal Food, Drug, and Cosmetic Act, while the EPA monitors microplastic environmental discharge from rinse-off personal care products; REACH in Europe mandates pre-market registration of chemical exfoliants above one ton annual volume, directly shaping formulation choices for brands seeking dual-market access. China's SAMR enforces GB standards for cosmetics safety that require animal-alternative testing compliance, adding compliance layers for imported acid-based exfoliators. Stakeholders must monitor pending state-level microplastic legislation in California and New York that could trigger broader North American reformulation deadlines ahead of federal action.
Market Dynamics
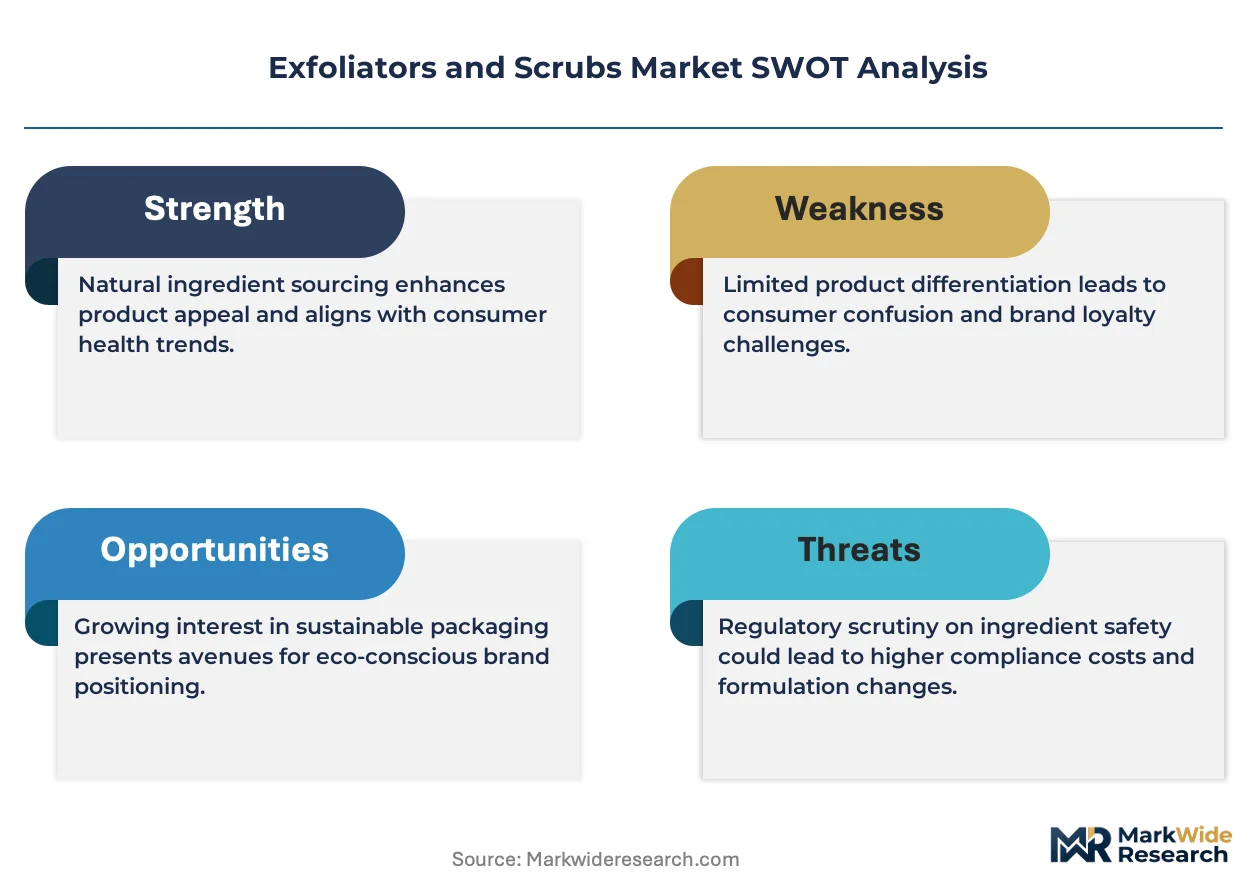
The EU's REACH microplastic ban is forcing wholesale reformulation of mechanical scrubs toward biodegradable abrasives, compressing legacy polyethylene supply chains while elevating enzyme and acid-based alternatives.
Growth Catalysts
- Professional channel expansion:Medi-spa bundling of clinical-grade chemical peels with aesthetic services drives premium per-treatment pricing. Dermatologist office dispensing creates recurring revenue streams for acid-based formulations.
- Biotechnology maturation:Fermentation-derived proteolytic enzymes from fungal sources now match polyethylene bead efficacy at comparable cost. Integrated bioreactor supply chains secure feedstock consistency for scaled production.
- Regulatory harmonization:California's pending microplastic legislation signals broader North American adoption timelines. Brands with REACH-compliant formulations gain first-mover advantage in preemptive compliance.
Market Restraints
- Input cost volatility:Glycolic acid and lactic acid feedstocks fluctuate with petrochemical and agricultural commodity cycles. Formulators lack pricing power to pass through raw material spikes in mass-market segments.
- Supply concentration risk:South Korean contract manufacturers dominate advanced enzyme fermentation capacity. Single-source dependencies create vulnerability for brands without captive biotech assets.
- Technical substitution ceiling:Enzyme exfoliators underperform on thickened keratotic plaques compared to mechanical abrasion. Dermatology patients with ichthyosis and psoriasis remain tethered to legacy scrub formats.
Strategic Opportunities
- Men's grooming penetration:Underdeveloped male exfoliation routines in the United States present white-space expansion. Gender-neutral packaging and simplified regimens unlock incremental household penetration.
- Sustainability premium capture:Ocean-plastic-negative certification and carbon-neutral shipping protocols command pricing power. Clean beauty retailers prioritize brands with verified lifecycle assessments.
- Telemedicine integration:Virtual dermatology platforms enable prescription-strength retinoid and acid combinations. Direct-to-patient fulfillment bypasses traditional retail margin extraction.
Industry Challenges
- Formulation stability engineering:Enzyme activity preservation across temperature excursions demands cold-chain investment. Last-mile logistics complexity erodes margin in e-commerce channels.
- Clinical substantiation burden:FDA cosmetic-drug distinction requires careful claim architecture. Brands face warning letter risk for acne treatment positioning without NDA submission.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Exfoliators and Scrubs Market |
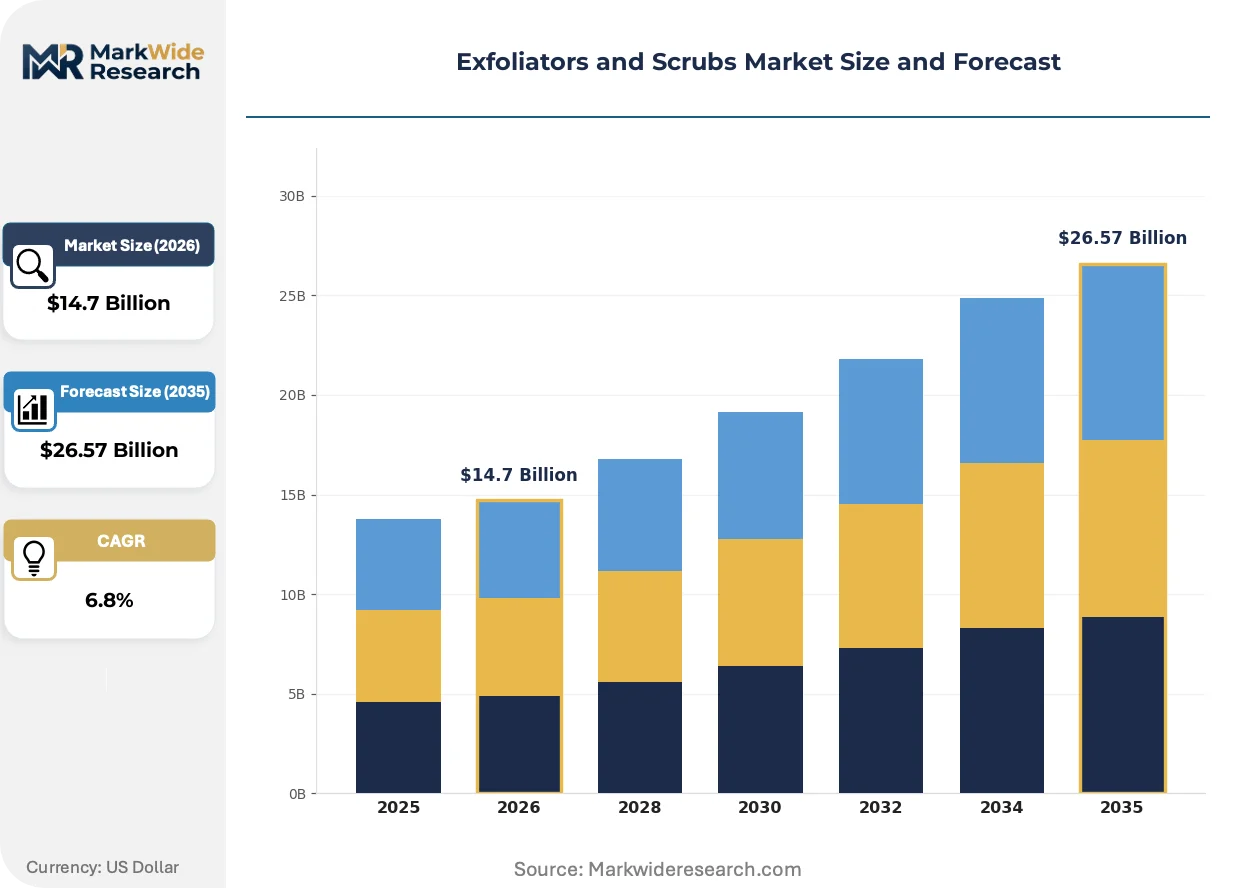
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Physical Exfoliators, Chemical Exfoliators, Enzyme Exfoliators, Scrubs Formulation: Creams, Gels, Powders, Peels Skin Type: Oily Skin, Dry Skin, Combination Skin, Sensitive Skin Target Audience: Men, Women, Teens, Professionals |
| Companies Covered | L'Oréal, Estée Lauder Companies, Unilever, Procter & Gamble, Shiseido, Beiersdorf, Kao Corporation, Johnson & Johnson Services, Clarins, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Exfoliators and Scrubs Market Emerging Trajectories
Formulation science is pivoting toward bioengineered actives and pH-optimized delivery systems, compressing development cycles while elevating clinical validation requirements across all price tiers.
Biotechnology is virtualizing exfoliator manufacturing through CRISPR-edited yeast strains that secrete customized protease cocktails. Prestige brands in South Korea and Japan are adopting these fermentation platforms to reduce dependence on plant-derived enzyme variability. The technology is virtualizing traditional agricultural supply chains into controlled bioreactor environments with batch-to-batch consistency guarantees.
REACH Annex XV restrictions on microplastics in rinse-off cosmetics have triggered mandatory reformulation deadlines across European manufacturing. Formulators are abandoning polyethylene and polypropylene beads for cellulose, jojoba ester, and mineral alternatives. Professional salon channels face compressed compliance timelines as member states accelerate enforcement ahead of 2027 phase-outs.
Subscription-based replenishment models are displacing traditional retail purchasing for acid-based home peels. Direct-to-consumer brands capture recurring revenue through personalized regimen algorithms matched to skin type diagnostics. This behavioral shift concentrates most visibly in United States urban markets where convenience positioning outweighs tactile retail sampling preferences.
Exfoliators and Scrubs Market Segmentation
Segmentation in exfoliators and scrubs reveals divergent service intensity requirements across product categories. Professional-grade chemical peels demand clinical consultation support, while mass-market scrubs operate through self-service retail channels with minimal after-sales engagement.
Product Type:
After-sales-service intensity varies sharply across exfoliation technologies, with professional peels requiring trained application support and home-use scrubs relying on digital instruction.
- Chemical Exfoliators:Acid-based formulations using glycolic, lactic, or salicylic acids at pH 3.0–4.5 for controlled keratinocyte turnover. Demand concentrates in United States medi-spa channels where dermatologist protocols bundle peels with aesthetic services, creating recurring professional consultation requirements.
- Enzyme Exfoliators:Proteolytic formulations derived from fungal fermentation or fruit sources that digest corneocytes without mechanical abrasion. South Korean biotech manufacturers supply these to Asia-Pacific clean beauty brands reformulating away from microplastics under tightening environmental regulations.
- Physical Exfoliators:Mechanical scrubs utilizing cellulose, jojoba esters, or mineral particles as biodegradable polyethylene replacements. Mass-market retailers in the United States stock these for price-sensitive consumers seeking tactile cleansing rituals.
- Scrubs:Rinse-off formulations combining abrasive particles with surfactant bases for body and face applications. Professional salon channels in Japan favor these for pre-treatment skin preparation protocols.
Chemical exfoliators hold the largest share; momentum sits with enzyme variants as regulatory pressure accelerates biodegradable reformulation.
Formulation:
Cost tier stratification separates premium peel formulations from mass-market gel and powder alternatives across retail and professional channels.
- Peels:Professional-grade acid solutions requiring neutralization protocols and post-treatment care regimens. United States dermatology offices dispense these as part of clinical acne and hyperpigmentation protocols.
- Creams:Emulsion-based delivery systems suspending abrasive particles or acids in occlusive bases for dry skin applications. European pharmacies stock these for mature consumers seeking barrier-supporting exfoliation.
- Gels:Hydroalcoholic matrices providing rapid penetration and cooling sensation for oily skin types. Asian e-commerce platforms move volume in this format through subscription replenishment models.
- Powders:Anhydrous enzyme or acid precursors activated with water at point of use, extending stability and enabling travel-friendly formats. Japanese domestic brands lead innovation in this concentration-efficient category.
Creams dominate unit volume; powders are climbing fastest on portability and preservation advantages.
Skin Type:
Application specificity drives formulation customization, with sensitive skin variants commanding premium positioning through dermatological testing investments.
- Sensitive Skin:Fragrance-free, pH-buffered formulations with minimal active concentrations and barrier-repair adjuncts. European consumers with rosacea and eczema drive demand for these clinically validated variants.
- Oily Skin:Higher-strength acid concentrations and oil-absorbing clay bases targeting sebaceous hyperplasia and comedonal acne. Teen demographics in the United States represent core demand for this specification.
- Dry Skin:Cream-based vehicles with humectant pairing and reduced abrasion to prevent barrier compromise. Japanese aging demographics sustain volume in this moisturizing-exfoliation hybrid segment.
- Combination Skin:Zone-specific formulations or adjustable-strength systems addressing divergent T-zone and cheek requirements. South Korean beauty routines normalize multi-product regimens for this skin type.
Oily skin formulations hold the largest share; sensitive skin variants are gaining share fastest on clinical positioning and allergen-free certification.
Target Audience:
Customer type segmentation reveals underdeveloped male routines alongside mature female purchasing patterns and emerging teen prevention behaviors.
- Women:Established purchasers across all price tiers with sophisticated multi-step regimen expectations. United States prestige retailers capture loyalty through personalized skin diagnostic services.
- Professionals:Time-constrained consumers seeking clinical-grade results through abbreviated protocols. Telemedicine platforms in the United States now serve this segment with prescription-strength acid combinations.
- Men:Underpenetrated demographic responding to gender-neutral packaging and simplified single-step formats. Barbershop channels in the United Kingdom are testing professional exfoliation add-on services.
- Teens:Acne-focused purchasers prioritizing affordability and social media-validated trends. Drugstore chains in the United States stock these at entry price points with influencer co-developed branding.
Women hold the largest share; professionals are expanding most quickly on convenience-oriented clinical service integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA cosmetic labeling requirements anchor United States market structure, while REACH microplastic enforcement reshapes European formulation priorities. Asia-Pacific biotech clusters now supply enzyme alternatives to brands reformulating away from polyethylene beads.
United States
Dermatologist office dispensing and medi-spa bundling drive premium acid-based peel demand. FDA warning letters on acne treatment claims force careful cosmetic-drug distinction architecture. Greater Los Angeles hosts contract manufacturers serving prestige brands with fermentation-derived enzyme supply chains.
Germany
Pharmacy-channel distribution of barrier-supporting cream formulations sustains mature consumer loyalty. ECHA REACH Annex XV microplastic deadlines accelerate polyethylene bead phase-outs ahead of 2027. Hamburg-based formulators specialize in cellulose and jojoba ester abrasive alternatives for mass-market scrubs.
South Korea
Multi-step beauty routines normalize adjustable-strength systems for combination skin types. MFDS cosmetics safety standards enforce animal-alternative testing compliance for imported acid exfoliators. Seoul Capital Area biotech parks house CRISPR-edited yeast fermentation platforms supplying protease cocktails to Asia-Pacific clean beauty brands.
Japan
Aging demographics sustain moisturizing-exfoliation hybrid demand in dry skin segments. METI JIS-compliant botanical extraction standards command pricing power in domestic retail. Osaka-Kansai manufacturers lead anhydrous powder format innovation for travel-friendly enzyme activation.
United Kingdom
Barbershop channels test professional exfoliation add-on services for underpenetrated male routines. UK Environment Agency microplastic monitoring pressures rinse-off cosmetic reformulation timelines. London prestige retailers capture female loyalty through personalized skin diagnostic services.
Exfoliators and Scrubs Market Vendor Landscape
Capability concentration sits with biotech-enabled specialists; scale advantage sits with integrated personal care conglomerates. The market structures around three tiers: fermentation-platform owners, dermatologist-channel prestige houses, and mass-market retailers with private-label scrubs. Dominant competitive moves include backward integration into enzyme supply chains and strategic partnerships with South Korean contract manufacturers.
Within the biotechnology tier, L'Oréal and Shiseido exemplify integrated fermentation strategies. L'Oréal leverages captive enzyme supply chains for cost advantages in premium peels. Shiseido anchors Japanese domestic positioning through JIS-compliant botanical extraction standards. Among North American prestige distributors, Estée Lauder Companies occupies the dermatologist office channel with dedicated e-commerce infrastructure.
| Leading Market Players |
|---|
| L'Oréal |
| Estée Lauder Companies |
| Unilever |
| Procter & Gamble |
| Shiseido |
| Beiersdorf |
| Kao Corporation |
| Johnson & Johnson Services |
| Clarins |
| Others |
Supply Flow & Price Mechanics
Overcapacity in South Korean enzyme fermentation facilities is compressing contract manufacturing rates while elevating pricing leverage for brands with captive bioreactor assets. This utilization asymmetry stratifies the market into price-takers dependent on outsourced supply and margin-defenders with integrated production.
Pricing Analysis
Geographic price spreads widen significantly between United States dermatologist-dispensed peels and European pharmacy-channel creams. Three-tier pricing structure across premium, standard, and economy levels separates professional protocol bundles from mass-market scrubs and entry-level enzyme powders. Cost compression in mass-market physical scrubs is intensifying because of agricultural commodity volatility in cellulose feedstocks. Teen and price-sensitive male segments exhibit highest price sensitivity; medi-spa professionals demonstrate lowest sensitivity due to bundled service pricing.
Supply Chain Analysis
Upstream glycolic acid and lactic acid feedstocks draw from petrochemical complexes in the United States, Germany, and China. Proteolytic enzyme manufacturing rests on fungal fermentation capacity concentrated in South Korea and Japan, with jojoba ester abrasives sourcing from Israeli and Argentine agricultural processors. Single-source vulnerability permeates advanced bioreactor supply, where CRISPR-edited yeast strains remain proprietary to select contract manufacturers. Distribution runs through professional salon and spa channels for clinical-grade formulations, while mass-market alternatives move through drugstore and e-commerce replenishment models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from regulatory-driven reformulation cycles, with REACH microplastic enforcement acting as the cyclical catalyst compressing legacy polyethylene supply chains and elevating enzyme alternatives.
For Market Incumbents: Pre-empt further margin erosion by securing captive fermentation capacity in Seoul Capital Area biotech parks before contract manufacturing rates inflect upward. Invest in cold-chain logistics infrastructure to preserve enzyme activity stability across temperature-variable e-commerce fulfillment. Counter emerging clean beauty entrants by accelerating JIS-compliant botanical certification for Japanese domestic positioning. For New Entrants and Emerging Players: Pursue white-space expansion in United States male grooming through barbershop channel partnerships and simplified single-step scrub formats. Target teen acne prevention segments with influencer-co-developed branding and entry price-point powder formulations. Deploy direct-to-consumer subscription models with personalized skin diagnostic algorithms to bypass incumbent retail margin extraction. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across enzyme exfoliation manufacturing as fermentation platforms achieve scale efficiencies. Five-to-ten year viability favors acquisition of South Korean contract manufacturers with CRISPR-edited yeast capabilities and integrated bioreactor assets. Monitor California state-level microplastic legislation passage as the signal for broader North American reformulation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enzyme Supply | L'Oréal's captive fermentation chains secure cost advantages in premium peel formulations. |
| Direct-to-Consumer Subscription Launch | Replenishment algorithms matched to skin diagnostics concentrate recurring revenue in United States urban markets. |
| Professional Channel Expansion | Medi-spa bundling of clinical-grade peels with aesthetic services captures disproportionate margin pools. |
| Sustainability Repositioning | Ocean-plastic-negative certification commands pricing power in clean beauty retailer prioritization. |
| Telemedicine Platform Integration | Virtual dermatology enables prescription-strength acid fulfillment bypassing traditional retail extraction. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and retail audit databases. Conversations with brand managers at prestige houses, procurement leads at South Korean contract manufacturers, dermatology clinic dispensing coordinators, and clean beauty retailer category buyers informed demand-side validation. FDA warning letters, ECHA REACH Annex XV restriction timelines, and MFDS cosmetics safety standards provided regulatory anchoring. Bottom-up segmentation modeling triangulated against top-down macroeconomic overlays.
Forecast inputs span product type, formulation vehicle, skin type specificity, and target audience channel across the analysis window. Chemical exfoliator, enzyme, physical scrub, and traditional scrub categories were modeled with professional versus mass-market channel splits. CAGRs derived from volume trajectory analysis incorporating regulatory phase-out timelines and biotechnology adoption curves. Raw material cost indices for glycolic acid, lactic acid, and fermentation feedstocks informed margin compression assumptions.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending, agricultural commodity prices, or petrochemical feedstock costs would shift the trajectory. Forecasts reflect documented assumptions regarding REACH enforcement timelines and California legislative adoption. Cross-checking against external retail audit benchmarks from Nielsen and Circana is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Sheet Face Mask Market
Skincare
Preoperative Skin Preparation Market
Skincare
Cosmeceutical Ingredients Market
Skincare
Dermocosmetics Skin Care Products Market
Skincare
Facial Mask Market
Skincare
Herbal Skincare Products Market
Skincare
Skin Bioactive Market
Skincare
Pseudo Collagen Market
Skincare
Asia Pacific Traditional Chinese Herbal Medicine for Face-Care Market
Skincare
Skin Boosters Market
Skincare
Skin Care Body Products Market
Skincare
Facial Cleansing Balm Market
Skincare
Revitalizing Skin Wands Market
Skincare
After Sun Care Products Market
Skincare
Incontinence Skin Care Products Market
Skincare
CBD Skincare Products Market