
 Herbal Skincare Products Market | 2026-2036
Herbal Skincare Products Market Size, Share, and Industry Trends Forecast 2026-2036
Herbal Skincare Products Market Outlook
Subscription-based replenishment services for herbal skincare is consolidating how consumers discover and repurchase botanical formulations. Himalaya Global Holdings Ltd. leverages its vertically integrated herb cultivation in India to secure supply consistency for these recurring delivery models. L'Oréal S.A. anchors its herbal portfolio through dedicated R&D centers in France that validate plant-derived efficacy claims. Weleda differentiates by controlling biodynamic farming operations across Germany and Switzerland, giving its subscription offerings certified ingredient traceability.
Herbal skincare products are topical preparations formulated with plant-derived active compounds—typically containing standardized botanical extracts between 0.5% and 5% concentration—manufactured through cold-press extraction or supercritical CO2 processing to preserve volatile phytochemicals, serving primarily to modulate skin barrier function and oxidative stress without synthetic petrochemical bases. Moisturizers and serums capture the deepest margin pools as consumers prioritize daily-use products with documented hyaluronic acid and botanical oil synergies. Cleansers and masks compete on volume throughput, though masks show faster expansion through professional channel adoption. Anti-aging applications lead the application dimension, while hydration-focused formulations are gaining fastest among men and teen segments where entry barriers remain lower.
FDA cosmetic labeling requirements and the EU Green Deal's chemical transparency mandates compel reformulation of preservative systems and full botanical supply chain disclosure. BIS certification in India and ECHA REACH compliance in Europe further constrain which herb suppliers qualify for commercial-scale procurement. Stakeholders must monitor how evolving microbiome testing standards and green chemistry certifications reshape which botanical actives achieve formulary inclusion across regulated markets.
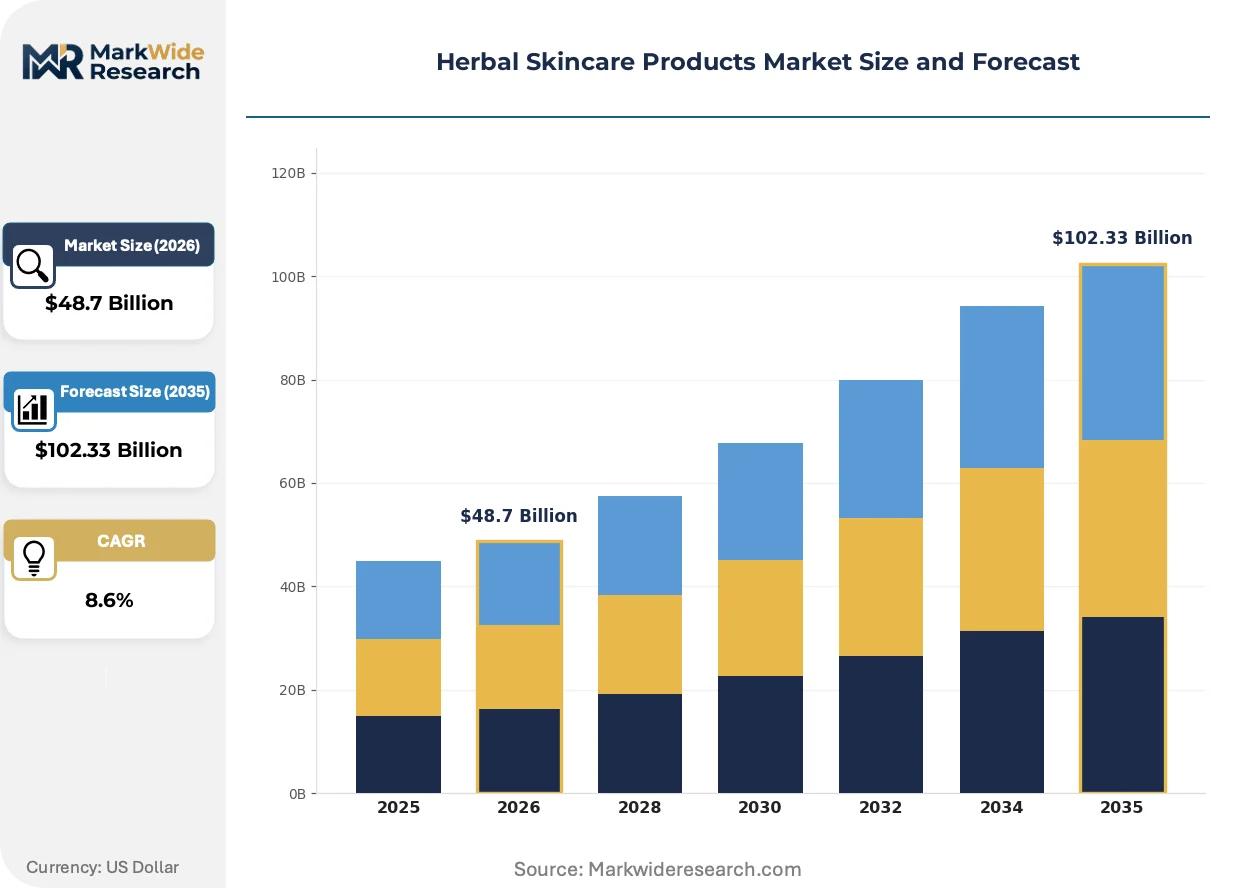
Market Dynamics
Clean beauty subscription services are consolidating consumer discovery and repurchase patterns for botanical formulations, while EU Green Deal chemical transparency mandates force reformulation of preservative systems across supply chains.
Growth Catalysts
- EU Green Deal mandates:Chemical transparency requirements are accelerating demand for fully traceable botanical supply chains and certified organic herb cultivation.
- Professional salon channel expansion:Clean beauty subscription services are penetrating high-frequency service environments where estheticians influence product selection.
- Seoul metropolitan cluster demand:South Korea's concentrated beauty innovation ecosystem is driving premium herbal serum adoption across Asian export markets.
Market Restraints
- Wild-harvested herb supply volatility:Climate-sensitive botanical sourcing from Himalayan and Andean highland regions creates raw material inconsistency.
- ECHA REACH compliance costs:European chemical safety dossier requirements impose six-figure registration burdens on small-scale herb extract suppliers.
- Synthetic biotech substitutes:Lab-engineered squalane and fermented actives are displacing traditional plant-derived oils in cost-sensitive formulations.
Strategic Opportunities
- Men's hydration segment:Male consumers in urban India and Brazil show rising receptivity to simplified herbal moisturizing routines with lower entry barriers.
- Biodynamic certification premium:Demeter-certified farming protocols command price premiums in German-speaking and Nordic markets seeking ingredient traceability.
- Microbiome testing integration:Convergence of genomic sequencing and topical formulation is enabling personalized herbal skincare based on skin flora analysis.
Industry Challenges
- Phytochemistry standardization gaps:Batch-to-batch variation in active compound concentration complicates efficacy claims and regulatory filings.
- Cold-chain preservation infrastructure:Supercritical CO2 extracts and volatile essential oils require capital-intensive temperature-controlled logistics networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herbal Skincare Products Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $102.33 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Cleansers, Masks, Serums Ingredient Source: Botanical Extracts, Essential Oils, Herbs, Natural Oils Application: Anti-aging, Hydration, Acne Treatment, Brightening End User: Women, Men, Teens, Professionals |
| Companies Covered | Himalaya Global Holdings Ltd., L'Oréal S.A., Unilever PLC, Weleda, The Estée Lauder Companies Inc., Procter & Gamble Company, Beiersdorf AG, Lotus Herbals, Dabur Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herbal Skincare Products Market Strategic Shifts
Biotechnology and regulatory transparency are converging to redefine how botanical actives are sourced, validated, and delivered to consumers across professional and direct channels.
Supercritical CO2 extraction technology is electrifying how volatile phytochemicals are preserved in high-end serums. Premium spa chains and dermatology clinics are adopting these cold-processed formulations at accelerated rates. The technology is electrifying margin structures by compressing oxidation losses and extending shelf stability without synthetic preservatives.
REACH registration requirements in Europe are forcing reformulation of traditional preservative systems toward plant-derived alternatives. Cosmetic manufacturers must now submit full toxicological dossiers for every botanical ingredient above one-ton annual volume. Mid-sized formulators in France and Italy are responding by consolidating supplier bases to pre-qualified ECHA-compliant herb processors.
Subscription-based replenishment models are displacing traditional retail discovery for daily-use herbal moisturizers. Direct-to-consumer channels in Seoul, Mumbai, and São Paulo are capturing repeat purchase loyalty through personalized botanical matching algorithms. Professional salon chains in these cities are integrating subscription fulfillment into service appointments to secure recurring revenue streams.
Herbal Skincare Products Market Segmentation
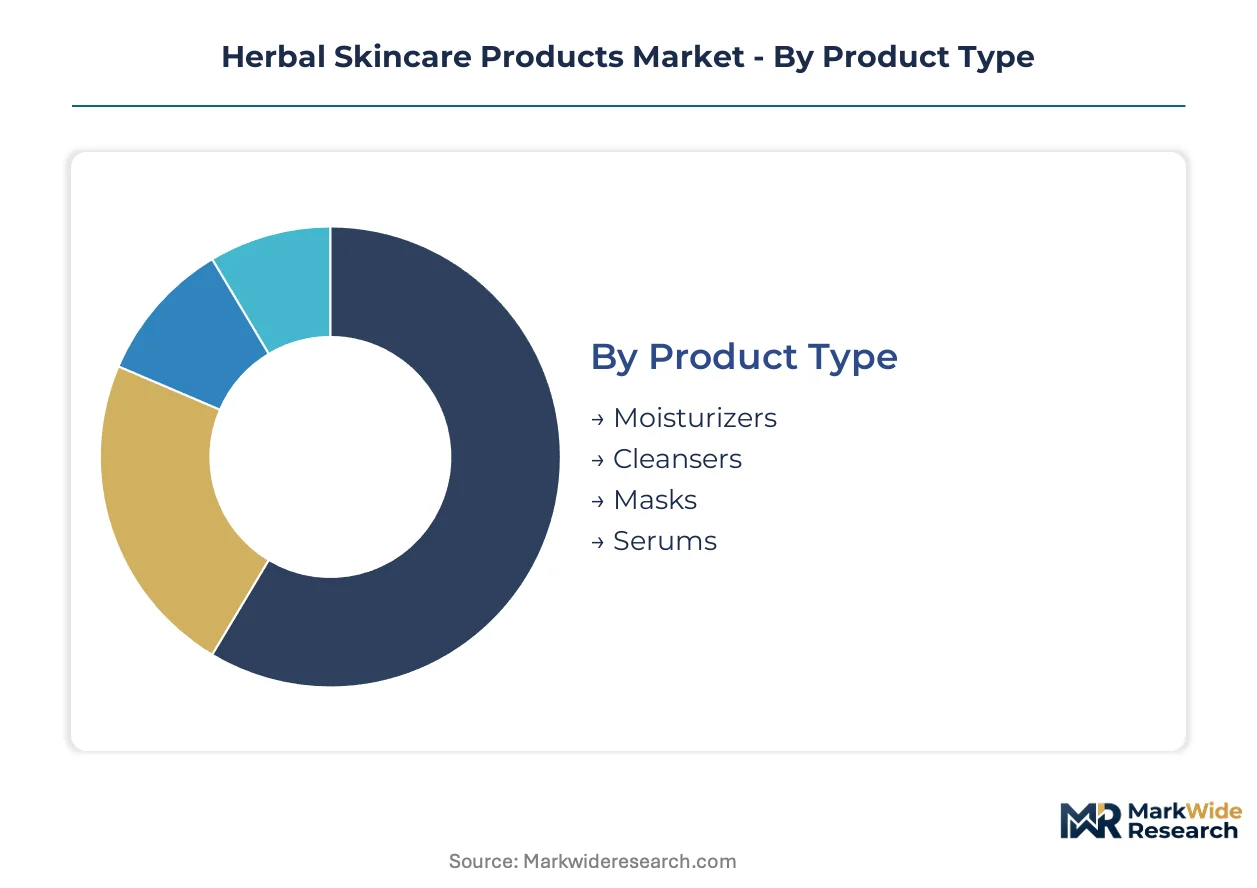
Herbal skincare segmentation reflects distinct upgrade cycles across product formats and user cohorts. Replenishment frequency and formulation complexity vary sharply between daily-use moisturizers and occasional treatment masks, while ingredient traceability requirements reshape sourcing strategies across all tiers.
Product Type:
Upgrade cycles compress for formats with higher daily contact frequency and visible efficacy windows.
- Moisturizers:Daily-application formulations with hyaluronic acid and botanical oil synergies command the deepest margin pools. Demand concentrates among professional salon chains in Seoul and Mumbai where estheticians prescribe personalized regimens with 30-45 day replenishment cycles.
- Serums:Concentrated actives between 0.5% and 5% botanical extract concentration require supercritical CO2 processing to preserve volatile phytochemicals. South Korea's metropolitan beauty cluster drives premium adoption through dermatology clinic channels where efficacy documentation matters most.
- Cleansers:Volume throughput products competing on per-unit accessibility with shorter ingredient disclosure requirements.
- Masks:Professional channel adoption accelerates expansion through spa and clinic environments in São Paulo and urban India.
Volume placements concentrate in moisturizers; the faster expansion belongs to masks.
Ingredient Source:
Cost tier stratification separates cold-processed premium extracts from commodity botanical inputs.
- Botanical Extracts:Standardized phytochemical concentrations manufactured through cold-press or supercritical CO2 extraction. EU Green Deal chemical transparency mandates force full supply chain disclosure for these inputs, favoring vertically integrated cultivators in India and Germany.
- Essential Oils:Volatile aromatic compounds requiring temperature-controlled logistics networks. Seoul and Mumbai direct-to-consumer channels capture repeat loyalty through personalized botanical matching algorithms.
- Herbs:Whole-plant materials subject to wild-harvested supply volatility from Himalayan and Andean highland regions.
- Natural Oils:Base carriers facing displacement pressure from lab-engineered squalane in cost-sensitive formulations.
Margin concentration sits with botanical extracts; essential oils climb the fastest through subscription replenishment models.
Application:
Customer maturity and entry barriers segment users across functional need states.
- Anti-aging:Lead application dimension requiring documented efficacy claims and clinical validation. ECHA REACH compliance costs impose six-figure registration burdens that consolidate supplier bases toward pre-qualified European herb processors.
- Hydration:Fastest-gaining segment among men and teens where simplified routines lower entry barriers. Urban India and Brazil show rising receptivity to streamlined herbal moisturizing protocols.
- Acne Treatment:Microbiome testing integration enables personalized formulation based on skin flora genomic sequencing.
- Brightening:Asian export market demand concentrated in Seoul's innovation ecosystem with specific regulatory pathways through MFDS and NMPA.
Anti-aging captures the steepest expansion trajectory in professional channels; hydration gains share fastest among emerging male and teen cohorts.
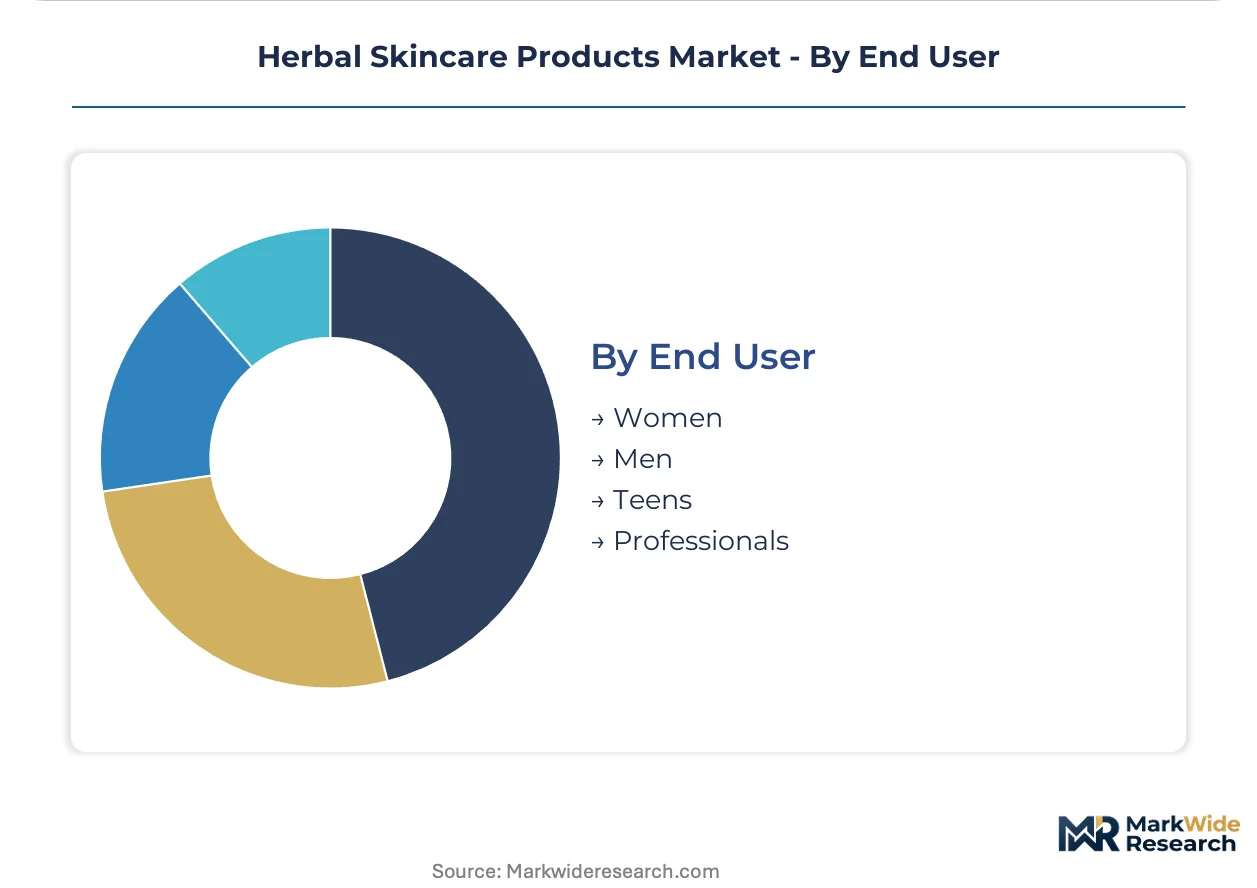
End User:
Procurement patterns diverge between self-directed discovery and expert-mediated selection.
- Women:Established core segment with highest subscription service penetration and multi-step routine complexity. Clean beauty subscription services consolidate discovery and repurchase across Seoul, Mumbai, and São Paulo metropolitan clusters.
- Men:Emerging segment with simplified product expectations and lower SKU tolerance. Brazilian and Indian urban markets show particular receptivity to streamlined herbal moisturizing offerings.
- Teens:Price-sensitive entry point focused on hydration and acne applications with social media-influenced discovery patterns.
- Professionals:Estheticians and dermatologists acting as gatekeepers in high-frequency service environments where product selection influences treatment outcomes.
Women anchor current volume; men represent the fastest-climbing cohort as formulation simplification reduces friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in herb-cultivating regions with vertically integrated supply chains, while consumption gravitates toward metropolitan beauty clusters where professional channels and subscription models dominate discovery patterns.
United States
Clean beauty subscription services drive replenishment loyalty in New York and Los Angeles metro areas. FDA cosmetic labeling requirements compel full botanical supply chain disclosure for products above interstate commerce thresholds. Brooklyn-based formulators are consolidating supplier bases toward ECHA REACH-compliant herb processors to secure European export access.
Germany
Biodynamic certification premiums command price differentiation in German-speaking markets seeking ingredient traceability. EU Green Deal chemical transparency mandates accelerate reformulation of preservative systems toward plant-derived alternatives. Weleda's biodynamic farming operations across Baden-Württemberg and Switzerland anchor certified ingredient sourcing for premium subscription offerings.
South Korea
Seoul's metropolitan beauty cluster drives premium herbal serum adoption through dermatology clinic channels. MFDS regulatory pathways enable export positioning across Asian markets with specific documentation requirements. Gangnam-based estheticians integrate subscription fulfillment into service appointments to secure recurring revenue streams.
India
Men's hydration segments show rising receptivity in Mumbai and Bangalore urban markets with simplified routine expectations. BIS certification constrains which herb suppliers qualify for commercial-scale procurement across domestic and export channels. Himalaya Global Holdings leverages vertically integrated herb cultivation in the Himalayan foothills to secure supply consistency for recurring delivery models.
Brazil
Urban male consumers in São Paulo demonstrate particular receptivity to streamlined herbal moisturizing protocols with lower SKU tolerance. ANVISA registration requirements impose documentation burdens that favor established formulators with regulatory affairs capacity. São Paulo's professional salon chains are accelerating mask adoption through spa environments with esthetician-mediated product selection.
Herbal Skincare Products Market Competitive Environment
Top-tier vendors anchor premium positioning through biodynamic certification and vertical supply chain control, while mid-tier players compete on subscription model execution and regional regulatory compliance. The vendor base stratifies across three tiers: heritage botanical houses with captive cultivation, multinational beauty conglomerates with dedicated R&D centers, and regional specialists with localized herb sourcing networks. Dominant competitive moves include backward integration into herb cultivation and strategic consolidation of supplier bases toward pre-qualified regulatory-compliant processors.
Within the heritage botanical tier, Weleda represents biodynamic farming archetypes with certified ingredient traceability, while Himalaya Global Holdings exemplifies vertically integrated supply chain control from cultivation through formulation. L'Oréal S.A. occupies a position among multinational conglomerates leveraging dedicated R&D centers to validate plant-derived efficacy claims.
| Leading Market Players |
|---|
| Himalaya Global Holdings Ltd. |
| L'Oréal S.A. |
| Unilever PLC |
| Weleda |
| The Estée Lauder Companies Inc. |
| Procter & Gamble Company |
| Beiersdorf AG |
| Lotus Herbals |
| Dabur Ltd |
| Others |
Value Chain & Pricing Dynamics
Himalayan herb commodity indices cascade through three distinct pricing tiers as wild-harvested supply volatility forces formulators toward captive cultivation contracts. EU Green Deal chemical transparency mandates compound procurement costs, compressing margins for mid-tier players while biodynamic-certified premiums expand in German-speaking markets.
Pricing Analysis
Margin tightening in standard-grade formulations reflects synthetic biotech substitute penetration from lab-engineered squalane and fermented actives. Three-tier pricing structure across premium, standard, and economy levels separates Demeter-certified biodynamic extracts from conventional organic and commodity botanical inputs. Cost-down pressure on essential oil serums accelerates because cold-chain preservation infrastructure demands capital-intensive temperature-controlled logistics networks. Professional salon chains in Seoul and Mumbai show least price sensitivity due to subscription-locked replenishment cycles, while teen hydration segments in urban India and Brazil exhibit highest elasticity.
Supply Chain Analysis
Specialized extraction technician availability constrains supercritical CO2 processing capacity in India's Himalayan foothills, Germany's Black Forest region, and Switzerland's biodynamic farming belts. Geographic supply concentration centers on India for vertically integrated herb cultivation, Germany for biodynamic certification protocols, and South Korea for dermatology clinic channel integration. Raw material dependencies draw from wild-harvested Himalayan botanicals, cold-pressed carrier oils, and standardized phytochemical concentrates. Single-source vulnerability from climate-sensitive highland herb harvesting creates batch-to-batch active compound variation. Distribution runs through professional salon chains in metropolitan beauty clusters and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Herbal skincare represents a consolidation play as ECHA REACH compliance costs and six-figure toxicological dossier burdens force sub-scale herb extract suppliers toward exit. Regulatory compliance scale economies favor integrated players with captive cultivation and pre-qualified processing infrastructure.
For Market Incumbents: Acquire biodynamic-certified farming operations in Germany and Switzerland to secure ingredient traceability premiums against synthetic biotech substitute threats. Consolidate supplier bases toward ECHA REACH-compliant herb processors in France and Italy to defend margin position from registration cost inflation. Invest in supercritical CO2 extraction capacity additions in India's Himalayan foothills to lock in supply consistency for subscription replenishment models. For New Entrants and Emerging Players: Enter via men's hydration segments in urban Brazil and India where simplified routine expectations lower formulation complexity barriers. Target teen acne treatment applications with microbiome testing integration as the most penetrable white space. Deploy personalized botanical matching algorithms through direct-to-consumer channels in São Paulo and Mumbai as the primary go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated mid-cap specialists with captive herb cultivation in India and biodynamic certification in German-speaking markets. Long-term viability over a multi-year horizon rests on regulatory compliance infrastructure and subscription platform lock-in. Watch ECHA registration deadline accelerations as the key inflection signal for supplier base consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Herb Cultivation | Himalaya Global Holdings' captive Himalayan foothills operations eliminate wild-harvested supply volatility for subscription models. |
| Biodynamic Certification Investment | Weleda's Demeter-certified farming commands price premiums in German-speaking and Nordic traceability-seeking markets. |
| Supercritical CO2 Extraction Scale-Up | Cold-processed volatile phytochemical preservation extends shelf stability without synthetic preservatives for premium serums. |
| Subscription Platform Integration | Seoul's Gangnam estheticians embed replenishment fulfillment into service appointments to secure recurring revenue streams. |
| ECHA REACH Compliance Consolidation | Mid-sized French and Italian formulators pre-qualify supplier bases to secure European market access against registration burdens. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this herbal skincare market assessment. Primary interviews with cosmetic formulators, estheticians at professional salon chains, herb cultivation operations managers, regulatory affairs specialists at ECHA-compliant processors, and subscription platform operators combined with bottom-up and top-down triangulation. Secondary validation drew from EU Green Deal implementation documents, BIS certification registries, MFDS cosmetic approval databases, and botanical supply chain disclosure filings.
Granularity-level modeling addressed product type at the moisturizer-serum-cleanser-mask dimension, ingredient source across botanical extract and essential oil tiers, application segmentation through anti-aging and hydration cohorts, and end-user categories spanning women, men, teens, and professional intermediaries. CAGRs across the analysis window derived from segment-level volume trajectories and value-per-unit expansion patterns. Industry-specific forecast inputs incorporated subscription replenishment adoption curves and professional channel penetration rates in Seoul, Mumbai, and São Paulo metropolitan clusters.
Revisions become necessary when ECHA REACH registration timelines accelerate, synthetic biotech substitute cost curves steepen, or climate events disrupt Himalayan and Andean highland herb harvesting. Forecasts reflect assumptions around regulatory compliance cost pass-through and subscription model retention rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Facial Skincare Market
Skincare
Facial Massage Cream Market
Skincare
Organic Skincare Products Market
Skincare
Skin Toner Market
Skincare
Retinol Skincare Product Market
Skincare
Allantoin Extract for Skincare Products Market
Skincare
Germany Skincare Product Market
Skincare
Skin Care Emulsion Market
Skincare
Cystic Acne Market
Skincare
Non-Surgical Skin Tightening Market
Skincare
Peel Off Face Mask Market
Skincare
South Korea Anti-Acne Dermal Patch Market
Skincare
Skincare Serums Market
Skincare
CBD Skin Care Market
Skincare
Cosmeceuticals Market
Skincare
Ultrasound Skin Cleaners Market