
 Skin Care Supplements Market | 2026-2036
Skin Care Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Skin Care Supplements Market Analytics
Multi-source ingredient procurement is broadening across the skin care supplements value chain as brands reduce dependency on single collagen or botanical suppliers. Amway Corporation leverages its vertically integrated Nutrilite farming operations to control raw material traceability from seed to supplement. Nestlé S.A. sustains competitive positioning through its Galderma-aligned dermatological science credentials and pharmaceutical-grade manufacturing protocols. Unilever plc anchors its portfolio with ingestible beauty lines that merge food science expertise with cosmetic brand equity.
Skin care supplements comprise orally administered nutraceuticals formulated with bioactive compounds—collagen peptides, hyaluronic acid, ceramides, polyphenols, and carotenoids—designed to modulate dermal matrix synthesis, oxidative stress, and barrier function from systemic circulation. These products undergo tablet compression, powder blending, or liquid emulsification with specified dissolution profiles and bioavailability markers to ensure active compound absorption rates compatible with physiological skin turnover cycles. Collagen and antioxidant segments command premium positioning due to clinical trial substantiation and consumer familiarity with topical analogues, while gummies and liquid formats capture fastest-growing demand through palatability advantages and TikTok-driven trial behavior. Pills retain mature volume leadership in pharmacy channels where healthcare practitioner endorsement still governs purchase decisions.
FDA oversight of structure-function claims under DSHEA and EMA novel food assessments for marine-derived collagen create compliance thresholds that favor established manufacturers with regulatory affairs infrastructure. BIS and CDSCO in India impose incremental testing requirements on imported beauty-from-within products, channeling demand toward domestic contract manufacturers with certified facilities. Stakeholders must monitor evolving pharmacovigilance frameworks as regulators reconsider whether skin-specific health claims warrant stricter pre-market authorization than general wellness positioning.
Market Dynamics
The skin care supplements market is experiencing structural compression as regulatory frameworks governing structure-function claims tighten across multiple jurisdictions, forcing manufacturers to rebuild substantiation pipelines and reformulate positioning strategies around clinically validated endpoints rather than cosmetic-adjacent marketing.
Growth Catalysts
- DSHEA Framework Evolution:FDA's evolving interpretation of permissible structure-function claims creates compliance clarity that rewards manufacturers with robust clinical trial infrastructure, channeling investment toward substantiated bioactive formulations.
- TikTok-Driven Trial Behavior:Short-form video platforms compress consumer education cycles for ingestible beauty, with gummy and liquid formats capturing disproportionate trial volume from Millennial and Gen-Z demographics in the United States and South Korea.
- Marine Collagen Processing Advances:Enzymatic hydrolysis technologies improve peptide bioavailability profiles, enabling tablet and powder formats to achieve absorption markers previously restricted to liquid delivery systems.
Market Restraints
- Bovine-Derived Collagen Substitution Pressure:Religious dietary restrictions and zoonotic disease concerns in Indonesia and Malaysia accelerate demand for marine and plant-based alternatives, compressing addressable market for traditional sources.
- Single-Source Botanical Concentration:Polyphenol extraction from French maritime pine bark and Indian amla fruit creates geographic supply vulnerability, with harvest variability in Bordeaux and Uttar Pradesh propagating through formulation costs.
- EMA Novel Food Assessment Timelines:Marine collagen and exotic botanical extracts face 18-24 month pre-market authorization cycles, freezing product pipeline velocity for European market entry.
Strategic Opportunities
- Men's Ingestible Dermatology:Underpenetrated male consumer segments in Germany and Japan present white space for testosterone-modulating and stress-adaptogen formulations targeting sebum regulation and barrier function.
- Pharmacy-Channel Professionalization:Healthcare practitioner endorsement protocols in Italy and Spain create margin expansion through prescription-adjacent positioning, displacing mass-market retail commoditization.
- Microbiome-Targeted Ceramide Complexes:Convergence of gut-skin axis research with targeted delivery technologies enables next-generation formulations addressing atopic dermatitis and rosacea from systemic circulation.
Industry Challenges
- Pharmacovigilance Infrastructure Buildout:Post-market adverse event reporting systems require specialized regulatory affairs talent scarce in contract manufacturing organizations across India and Brazil.
- Cross-Border E-Commerce Compliance:Divergent import testing requirements between BIS in India, CDSCO pharmaceutical classifications, and FSSAI food safety mandates fragment direct-to-consumer fulfillment architecture.
- Clinical Endpoint Standardization:Absence of harmonized biomarker protocols for skin elasticity, hydration, and wrinkle depth measurement complicates multi-site trial design and cross-study comparability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skin Care Supplements Market |
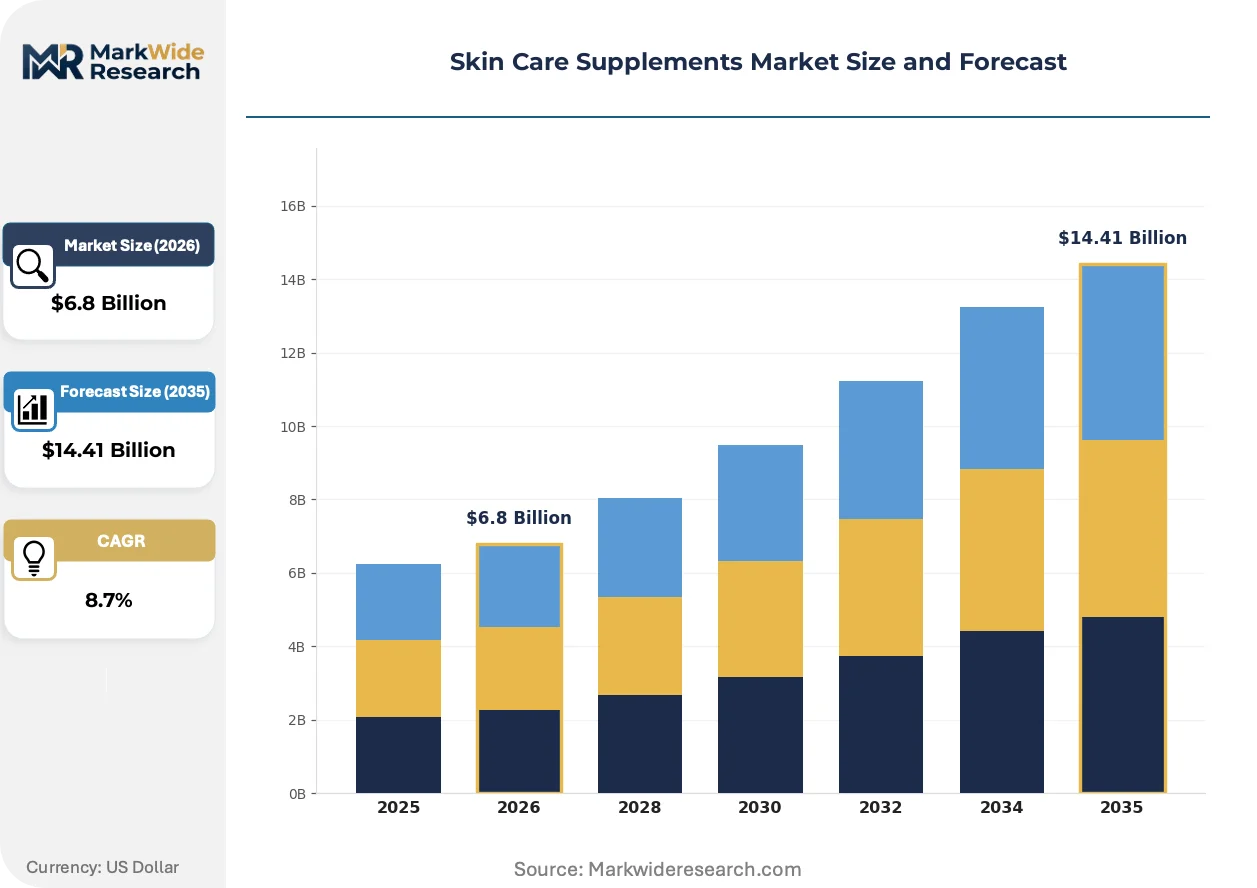
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Collagen, Antioxidants, Minerals Form: Pills, Powders, Gummies, Liquids Target Consumer: Women, Men, Teenagers, Seniors Distribution Channel: Online Retail, Pharmacies, Health Stores, Supermarkets |
| Companies Covered | Amway Corporation, Nestlé S.A., Unilever plc, HUM Nutrition Inc., Meiji Holdings Co., Ltd., Johnson & Johnson Services Inc., Perricone MD, Vitabiotics Ltd., Plix The Plant Fix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skin Care Supplements Market Evolving Landscape
Active ingredient delivery technologies and regulatory substantiation requirements are converging to reshape competitive positioning, with manufacturers investing in pharmaceutical-grade manufacturing protocols and bioavailability validation to defend premium positioning against commoditized alternatives.
Liposomal encapsulation of hyaluronic acid and ceramide compounds is consolidating around pharmaceutical-grade manufacturing standards previously reserved for parenteral nutrition. Dermatology-focused supplement brands in Switzerland and South Korea are adopting these technologies to differentiate from mass-market competitors. The structural consequence is compressing price-band differentiation between pharmacy-channel and premium e-commerce positioning, forcing mid-tier brands to choose between clinical investment or private-label conversion.
EMA's tightening novel food assessments for marine-derived collagen and exotic botanical extracts are extending pre-market timelines and elevating documentation burdens. Manufacturers with established regulatory affairs infrastructure in Germany and the Netherlands are capturing disproportionate European market access. Small and mid-cap entrants without dedicated compliance teams are pivoting toward U.S. market prioritization under DSHEA's more permissive structure-function framework.
Subscription-based replenishment models are displacing traditional retail trial-and-repeat cycles in direct-to-consumer channels. Beauty-focused supplement brands in California and Seoul are bundling quarterly dermatologist consultations with product shipments, converting transactional purchases into ongoing care relationships. This behavioral shift is most visible among Millennial consumers managing chronic skin conditions, where perceived therapeutic continuity overrides price sensitivity.
Skin Care Supplements Market Segmentation
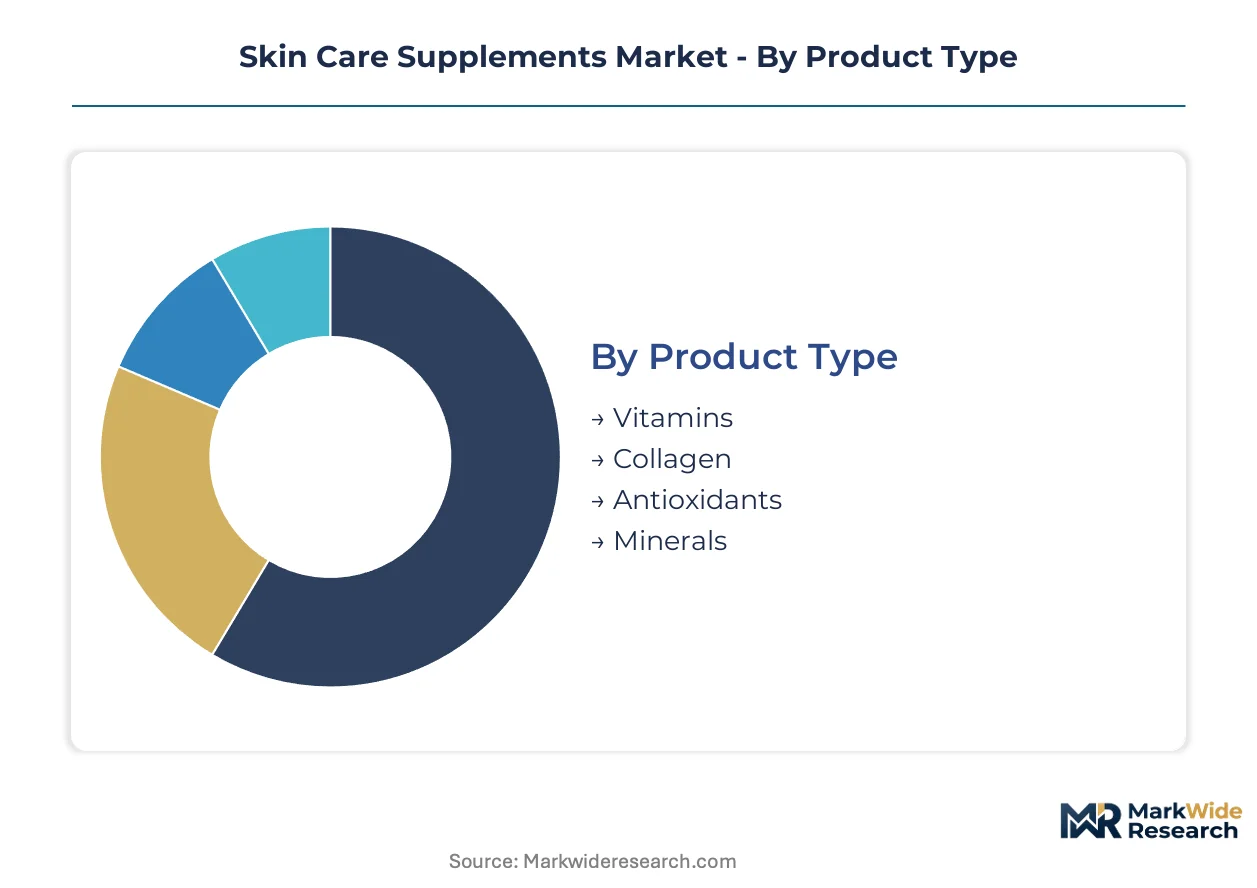
Segmentation in skin care supplements reveals divergent purchasing logics across delivery formats, demographic targets, and channel preferences. Manufacturers calibrate formulation complexity, packaging formats, and clinical substantiation levels to match the decision criteria dominant in each slice.
Product Type:
Buyers in this category separate by their tolerance for ingredient complexity versus single-compound familiarity and the degree of clinical validation they demand before purchase.
- Collagen:Hydrolyzed peptide formulations derived from marine, bovine, or porcine sources deliver specific amino acid profiles—glycine, proline, hydroxyproline—designed to stimulate fibroblast activity and dermal matrix synthesis. Demand concentrates in South Korea and the United States where TikTok-driven education has normalized daily collagen regimens among consumers aged 25-40; EMA novel food assessments for marine sources create compliance bottlenecks that favor established manufacturers with European regulatory infrastructure.
- Antioxidants:Polyphenol complexes, carotenoid blends, and vitamin C derivatives target oxidative stress modulation through systemic circulation rather than topical application. German and Japanese consumers drive premium positioning for these formulations, particularly those combining French maritime pine bark extract with astaxanthin from Haematococcus pluvialis microalgae; supply vulnerability from single-source botanical harvesting in Bordeaux and Uttar Pradesh propagates through formulation costs and margin pressure.
- Vitamins:Retinol precursors, niacinamide, and biotin complexes address micronutrient deficiencies linked to barrier dysfunction and keratinization disorders.
- Minerals:Zinc, selenium, and copper formulations target sebum regulation and wound healing support through enzymatic cofactor replenishment.
Volume sits with Collagen; growth tilts toward Antioxidants.
Form:
Format selection tracks directly against consumer age cohort and channel context, with palatability and convenience trading against perceived clinical seriousness.
- Gummies:Gelatin or pectin-based matrices with flavor masking systems deliver bioactive compounds through chewable formats that bypass swallowing aversion. Millennial and Gen-Z consumers in California and Seoul drive disproportionate trial volume through TikTok discovery; the format's expansion is climbing the fastest as brands bundle quarterly dermatologist consultations with subscription shipments to convert transactional purchases into ongoing care relationships.
- Pills:Compressed tablets and hard-shell capsules with specified dissolution profiles remain the default for pharmacy-channel purchases where healthcare practitioner endorsement governs decisions. Italian and Spanish consumers over 45 sustain mature volume leadership through prescription-adjacent positioning; manufacturers defend this segment through pharmaceutical-grade manufacturing protocols and bioavailability validation that mass-market alternatives cannot replicate.
- Powders:Bulk peptide and botanical extracts with scoop-measured dosing appeal to consumers already integrated into supplement routines.
- Liquids:Emulsified liposomal delivery systems and ready-to-drink shots capture consumers prioritizing absorption speed over cost efficiency.
Pills retain the revenue base; Gummies capture the steepest expansion trajectory.
Target Consumer:
Demographic targeting determines whether brands invest in hormonal research, stress-adaptogen science, or age-specific biomarker validation.
- Women:Formulations addressing hormonal fluctuations, pregnancy-related skin changes, and menopause-associated collagen depletion command the largest absolute spend. Brazilian and Indian consumers drive volume through mass-market positioning; regulatory divergence between BIS import testing requirements and CDSCO pharmaceutical classifications fragments direct-to-consumer fulfillment architecture for international brands.
- Men:Testosterone-modulating and stress-adaptogen formulations targeting sebum regulation and barrier function remain underpenetrated in Germany and Japan, presenting white space for brands willing to depart from cosmetic-adjacent marketing.
- Teenagers:Acne-focused zinc and vitamin A complexes with palatability engineering address parental purchase decisions.
- Seniors:Ceramide and hyaluronic acid combinations targeting age-related barrier compromise and hydration loss.
Women anchor current revenue; Men offer the largest untapped expansion potential.
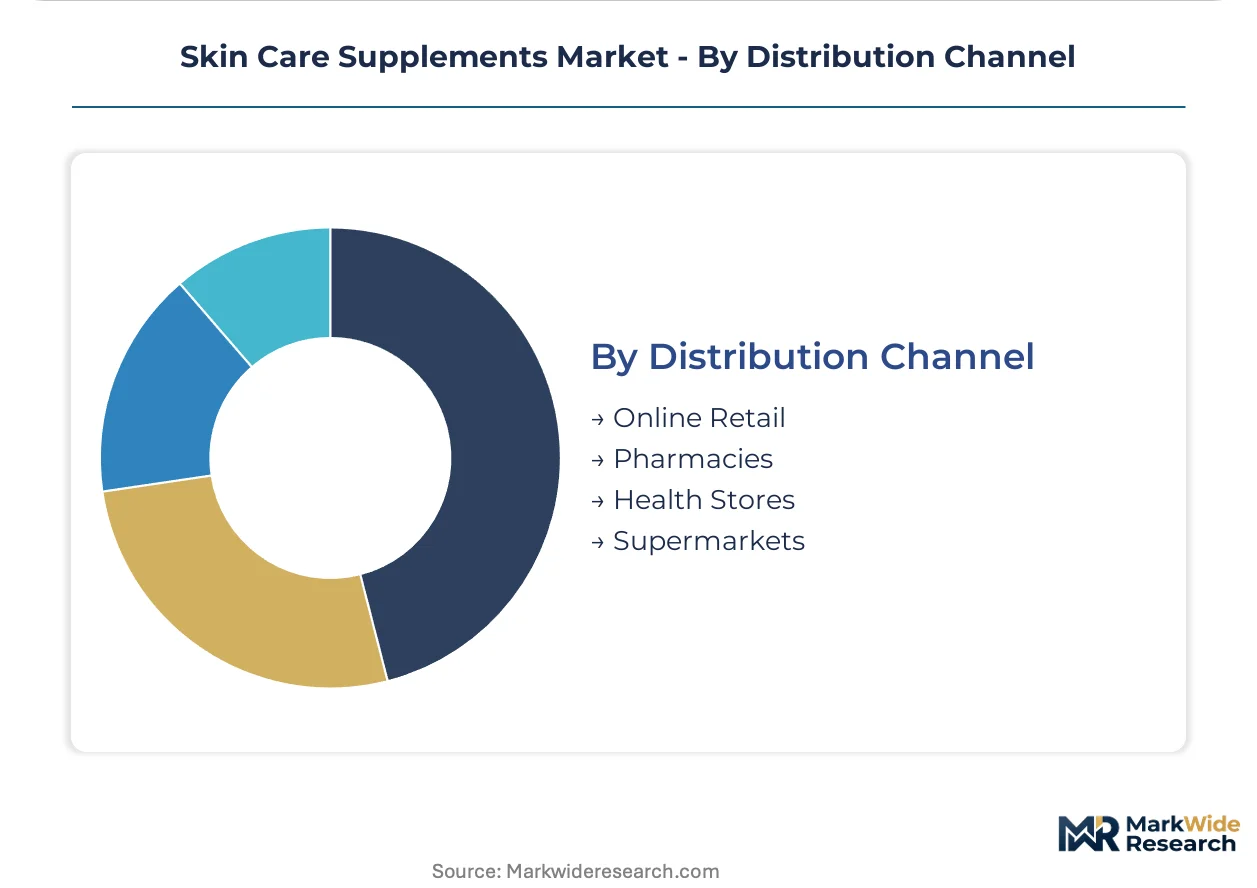
Distribution Channel:
Channel strategy determines whether brands compete on clinical credibility, price transparency, or impulse accessibility.
- Online Retail:Direct-to-consumer platforms and marketplace listings enable subscription-based replenishment models that displace traditional trial-and-repeat cycles. Beauty-focused supplement brands in Seoul and California leverage bundled dermatologist consultations; cross-border e-commerce compliance complexity between BIS, CDSCO, and FSSAI mandates fragments fulfillment architecture for brands without localized regulatory affairs teams.
- Pharmacies:Healthcare practitioner endorsement protocols in Italy and Spain create margin expansion through prescription-adjacent positioning that mass-market retail cannot match.
- Health Stores:Specialist retailers with trained staff cater to consumers already educated in nutraceutical differentiation.
- Supermarkets:Mass-market placement with price-competitive positioning drives volume in Brazil and Southeast Asia.
Pharmacies hold the margin premium; Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marine collagen processing clusters in South Korea and enzymatic hydrolysis facilities in Switzerland anchor raw material transformation for premium formulations. Consumer adoption concentrates in metropolitan corridors with established dermatological services and direct-to-consumer logistics infrastructure.
United States
Millennial and Gen-Z consumers in California and New York drive gummy format adoption through TikTok discovery and subscription bundling with telehealth consultations. FDA's evolving DSHEA interpretation for structure-function claims rewards manufacturers with clinical trial infrastructure. Los Angeles-based brands leverage influencer marketing networks to compress consumer education cycles for ingestible beauty regimens.
South Korea
Seoul's beauty-tech ecosystem integrates marine collagen extraction with pharmaceutical-grade manufacturing protocols for export markets. MFDS oversight of health functional foods creates compliance thresholds that favor established manufacturers with dedicated regulatory affairs teams. Busan-Ulsan industrial corridor concentrates enzymatic hydrolysis capacity serving domestic and Chinese demand.
Germany
EMA novel food assessment timelines for marine-derived collagen extend pre-market authorization to 18-24 months, freezing pipeline velocity for European entrants. Munich and Hamburg host regulatory affairs specialists navigating substantiation requirements for antioxidant polyphenol complexes. Pharmacy-channel professionalization in Bavaria creates margin expansion through prescription-adjacent positioning.
India
BIS import testing requirements and CDSCO pharmaceutical classifications fragment direct-to-consumer fulfillment for international brands, channeling demand toward domestic contract manufacturers. Mumbai and Delhi-NCR concentrate certified facilities serving mass-market women's segments. FSSAI food safety mandates impose incremental compliance burdens on beauty-from-within product categories.
Japan
Tokyo and Osaka metropolitan areas sustain mature demand for ceramide and hyaluronic acid combinations targeting age-related barrier compromise. METI guidance on functional food labeling shapes competitive positioning for ingestible dermatology products. Underpenetrated male consumer segments present white space for testosterone-modulating formulations in Nagoya and Fukuoka corridors.
Skin Care Supplements Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance infrastructure and clinical substantiation capabilities. The vendor base stratifies into three tiers: multinational consumer goods conglomerates with pharmaceutical-grade manufacturing protocols, mid-cap specialists with vertically integrated raw material control, and direct-to-consumer disruptors leveraging subscription bundling. Dominant competitive moves include M&A to acquire regulatory affairs talent and strategic partnerships with dermatology clinics for endorsement protocols.
Among multinational consumer goods conglomerates, Amway Corporation, Nestlé S.A., and Unilever plc occupy positions defined by manufacturing scale and traceability infrastructure. Amway exemplifies backward integration into raw material supply through controlled farming operations. Nestlé represents pharmaceutical-grade protocol adoption aligned with dermatological science credentials. Unilever anchors portfolio positioning at the intersection of food science expertise and cosmetic brand equity. These three entities sit within the premium-tier competitive vector where clinical validation and regulatory compliance capabilities determine market access.
| Leading Market Players |
|---|
| Amway Corporation |
| Nestlé S.A. |
| Unilever plc |
| HUM Nutrition Inc. |
| Meiji Holdings Co., Ltd. |
| Johnson & Johnson Services Inc. |
| Perricone MD |
| Vitabiotics Ltd. |
| Plix The Plant Fix |
| Others |
Value Network & Pricing Analysis
Backward integration into raw material supply anchors pricing power for skin care supplement manufacturers, with controlled farming operations and enzymatic hydrolysis facilities in South Korea and Switzerland determining cost structures across premium and mass-market tiers. This integration choice separates brands capable of pharmaceutical-grade protocol adoption from contract manufacturers exposed to single-source botanical vulnerability.
Pricing Analysis
Subscription bundling with dermatologist consultations separates premium positioning from unbundled transactional purchases, with quarterly shipment models capturing Millennial consumers managing chronic skin conditions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and clinical validation depth, with pharmacy-channel products commanding margin premiums through healthcare practitioner endorsement. Cost compression in mass-market gummy formats is intensifying because TikTok-driven trial behavior rewards palatability engineering over bioavailability investment. Direct-to-consumer subscribers show least price sensitivity; supermarket shoppers in Brazil and Southeast Asia exhibit highest.
Supply Chain Analysis
Returns and quality-control flows from European novel food assessment rejections create reverse-logistics burdens for marine collagen exporters, with 18-24 month EMA authorization cycles generating stranded inventory. Raw material transformation concentrates in South Korea, Switzerland, and India, with enzymatic hydrolysis capacity and certified contract manufacturing facilities determining regional supply positions. Formulation draws from marine collagen peptides, French maritime pine bark extract, and Indian amla fruit polyphenols. Single-source botanical harvesting in Bordeaux and Uttar Pradesh propagates supply vulnerability through harvest variability. Distribution runs through direct-to-consumer platforms, pharmacy chains in Italy and Spain, and mass-market retail in Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Skin care supplement supply is constrained by EMA novel food assessment capacity, with 18-24 month authorization timelines propping pricing for manufacturers with established European regulatory infrastructure.
For Market Incumbents: Lock in raw material traceability through controlled farming operations or long-term offtake agreements with marine collagen processors in South Korea, defending against zoonotic disease substitution pressure and religious dietary restriction shifts in Southeast Asia. Invest in pharmaceutical-grade manufacturing protocols to maintain pharmacy-channel margin premiums against direct-to-consumer disruptors. For New Entrants and Emerging Players: Launch via subscription bundling with telehealth dermatologist consultations, targeting underpenetrated male consumer segments in Germany and Japan with testosterone-modulating formulations. White space exists in microbiome-targeted ceramide complexes addressing atopic dermatitis through gut-skin axis positioning, with pharmacy-channel professionalization in Italy offering prescription-adjacent credibility. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational consumer goods conglomerates seeking regulatory affairs infrastructure and clinical trial capabilities. Long-term viability hinges on substantiation pipeline depth rather than influencer marketing scale. Target mid-cap specialists with vertically integrated raw material control and EMA submission track records. Monitor EMA novel food assessment timeline compression as inflection signal for European market entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Affairs Infrastructure Buildout | EMA novel food assessment expertise unlocks 18-24 month faster European market access than competitors. |
| Clinical Trial Substantiation Investment | FDA DSHEA-compliant structure-function claims defend premium positioning against commoditized alternatives. |
| Subscription Bundling with Telehealth | Quarterly dermatologist consultations convert transactional purchases into ongoing care relationships. |
| Marine Collagen Processing Scale-Up | Enzymatic hydrolysis capacity in Busan-Ulsan corridor serves domestic and Chinese demand expansion. |
| Men's Ingestible Dermatology Line Extension | Testosterone-modulating formulations capture white space in Nagoya and Fukuoka metropolitan corridors. |
Research Methodology
Document review covered FDA DSHEA guidance documents, EMA novel food assessment databases, and MFDS health functional food registrations, complemented by interviews with regulatory affairs directors at multinational consumer goods conglomerates, dermatology clinic procurement managers, and contract manufacturing facility operators in India and Brazil. Secondary validation drew from customs import records, pharmacy channel sales audits, and direct-to-consumer platform transaction data. Bottom-up demand modeling and top-down market sizing were triangulated against clinical trial publication databases.
Segmentation outputs across product type, delivery format, target demographic, and distribution channel were projected across the analysis window using adoption curve modeling calibrated to TikTok-driven trial behavior and subscription renewal rates. CAGRs were derived from price-volume elasticity functions and regulatory timeline probability distributions. Forecast inputs included EMA assessment queue depth, marine collagen hydrolysis capacity expansion schedules, and dermatologist consultation bundling penetration rates.
EMA authorization timeline extensions, marine harvest variability in Bordeaux, and TikTok algorithm shifts affecting discovery rates are the dominant revision risks to demand projections. Practitioners should monitor EMA novel food assessment throughput, French maritime pine bark crop yields, and short-form video platform content moderation policies for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
South Korea Anti-Acne Dermal Patch Market
Skincare
Skin Antiseptic Market
Skincare
Cosmeceuticals Market
Skincare
Global Physician Dispensed Cosmeceuticals Market
Skincare
Retinol Skincare Product Market
Skincare
CBD Skincare Products Market
Skincare
United Kingdom Skincare Market
Skincare
Anti-Aging Services Market
Skincare
After Sun Care Products Market
Skincare
Incontinence Skin Care Products Market
Skincare
Skin Replacement Market
Skincare
Fragrance-Free Skin Care Products Market
Skincare
Sun-Care Wipes Market
Skincare
Skincare Ingredients Market
Skincare
Hidradenitis Suppurativa Market
Skincare
Hyaluronic Acid Personal Care Products Market