
 Asia-Pacific Skincare Market | 2026-2036
Asia-Pacific Skincare Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Skincare Market Analytics
The gap between premium biotech-infused skincare and mass-market commodity lines is shifting from a price divide into a formulation-capability chasm. Amorepacific Corporation dominates Seoul's luxury retail channels with fermented-ingredient platforms. Unilever PLC leverages its India manufacturing scale to push affordable derma-cosmetics into tier-two cities. Shiseido Company Limited anchors Japan's pharmacy-driven skin health segment with physician-credentialed lines.
Asia-Pacific skincare encompasses topical formulations designed to maintain, protect, or restore skin barrier function through active delivery systems typically containing humectants, emollients, occlusives, and biologically active concentrations between 0.5% and 15%. These products serve both therapeutic outcomes under dermatological guidance and daily maintenance regimens across consumer segments. Serums lead value generation due to higher active-loading and concentrated positioning, while natural and hybrid formulations capture the fastest trajectory as clean-beauty expectations migrate from niche to mainstream. The acne-treatment application remains mature in Japan but accelerates across Southeast Asian humid-climate markets where occlusion-related conditions multiply.
China's NMPA, South Korea's MFDS, and Japan's Ministry of Health, Labour and Welfare each enforce distinct cosmetic safety assessment pathways that fragment registration timelines and reformulation costs for cross-border brands. South Korea's MFDS color-code system for functional cosmetics and China's NMPA animal-testing exemptions for imported general cosmetics create divergent compliance landscapes that reward localized R&D investment. Stakeholders must monitor regulatory reciprocity negotiations between Seoul and Beijing, as mutual recognition agreements would reshape competitive entry costs for regional players.
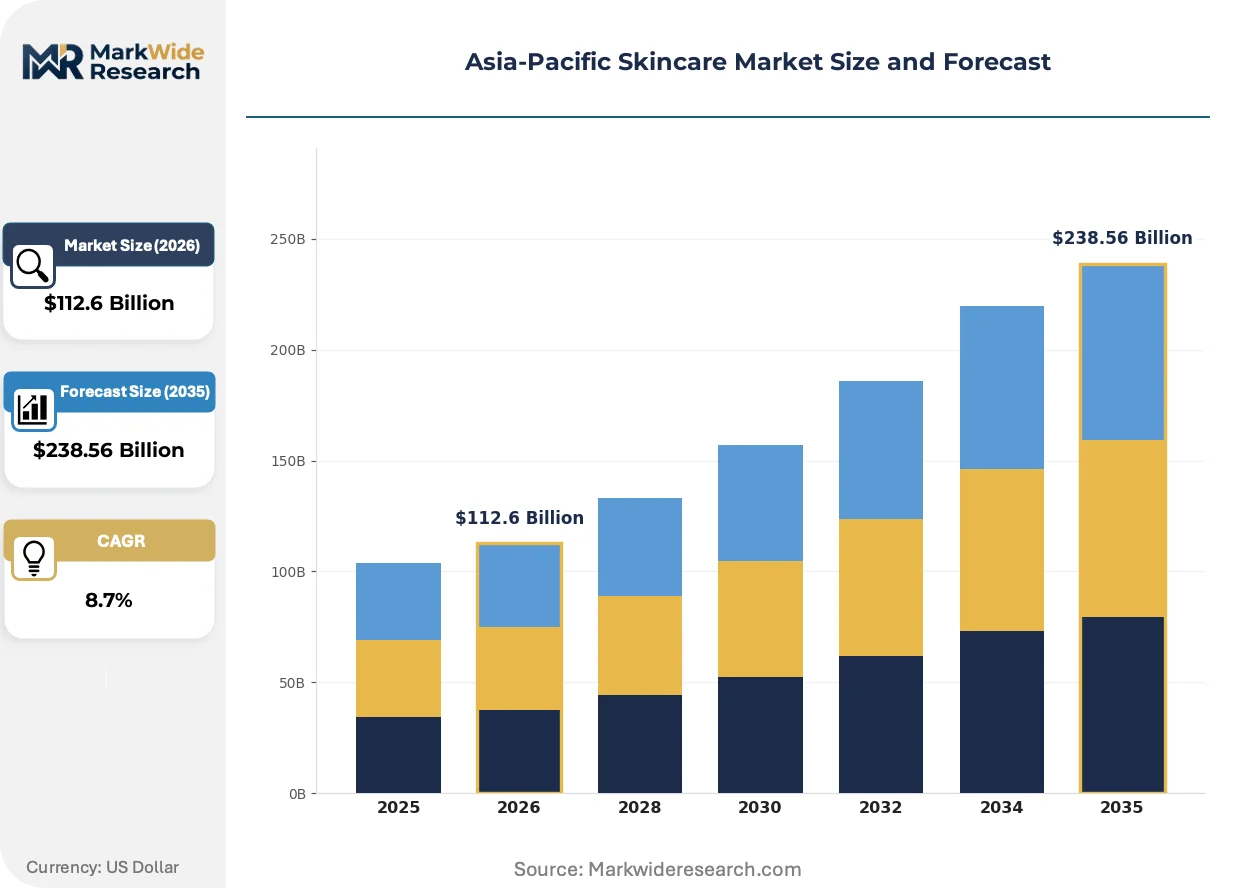
Market Dynamics
China's NMPA tightening of cosmetic ingredient disclosure rules is compressing product development cycles across the Asia-Pacific skincare market. Brands now face 12-18 month reformulation timelines to meet evolving safety assessment standards.
Growth Catalysts
- K-beauty export infrastructure:South Korea's government-backed cosmetic certification fast-tracks and dedicated export zones in Incheon Free Economic Zone accelerate regional brand expansion into Southeast Asian retail channels.
- MFDS functional cosmetics pathway:South Korea's color-code system for whitening, anti-wrinkle, and UV protection claims creates regulatory clarity that attracts foreign direct investment in localized R&D facilities.
- Fermentation biotechnology:Advances in microbial strain engineering for postbiotic actives enable Seoul-based labs to develop proprietary ingredient platforms with differentiated barrier-repair mechanisms.
Market Restraints
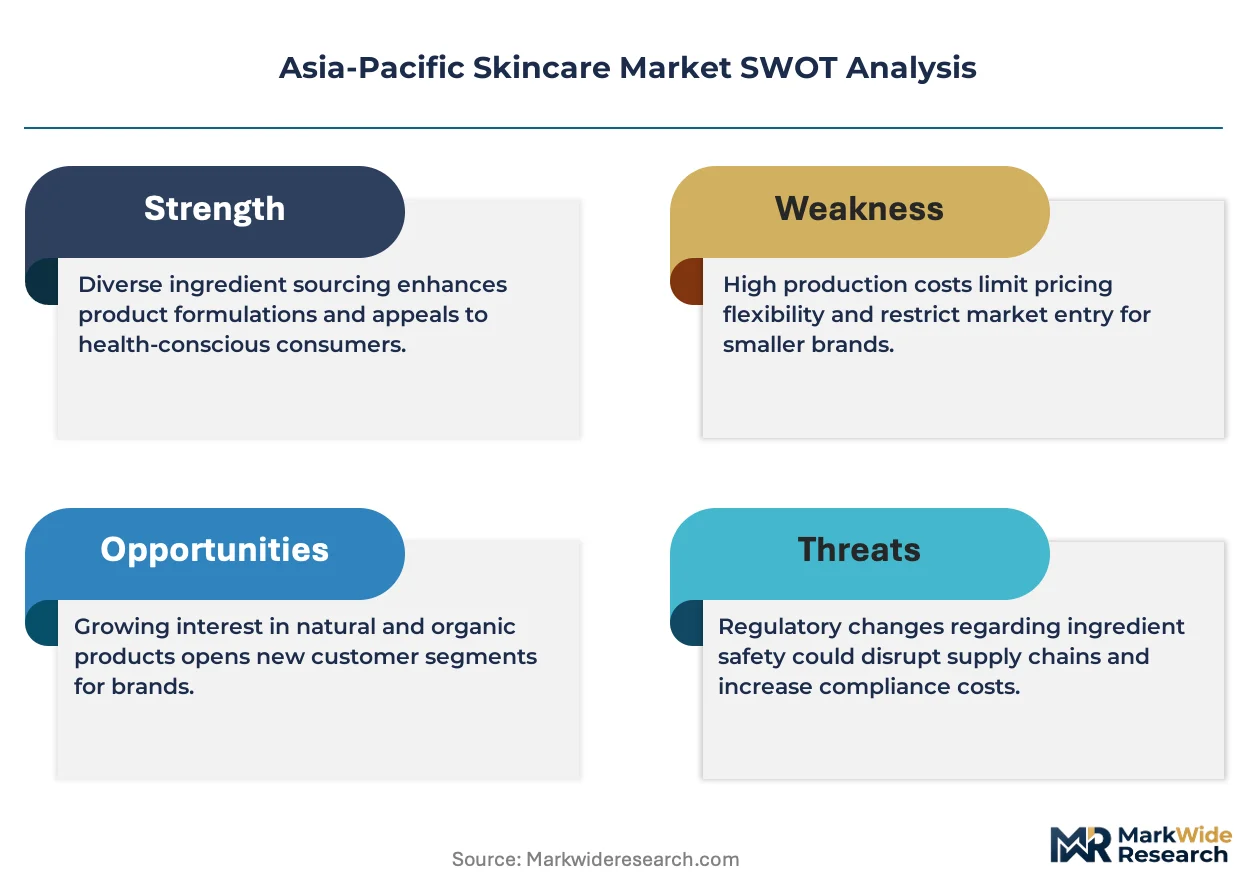
- Raw material concentration:Over 60% of ceramide and peptide active suppliers cluster in eastern China, creating geographic supply vulnerability amplified by Yangtze River delta logistics disruptions.
- Regulatory fragmentation:Divergent safety assessment timelines between China's NMPA, Japan's Ministry of Health, Labour and Welfare, and South Korea's MFDS inflate cross-border registration costs for unified product portfolios.
- Substitution pressure:Medical aesthetic procedures including laser resurfacing and injectable biostimulators capture spending from high-end topical anti-aging categories in Shanghai and Tokyo metro markets.
Strategic Opportunities
- Vietnam and Indonesia penetration:Skincare per-capita spending in Ho Chi Minh City and Jakarta remains 70% below Bangkok levels, creating whitespace for derma-cosmetic lines positioned between mass and pharmacy tiers.
- Men's grooming application:Underdeveloped male-specific skincare routines across Asia-Pacific present first-mover advantage for brands developing sebum-regulating formulations targeting humid-climate concerns.
- NMPA animal-testing exemptions:China's 2021 removal of mandatory animal testing for imported general cosmetics enables cruelty-free positioning that resonates with younger consumers in Chengdu and Hangzhou.
Industry Challenges
- Formulation chemist scarcity:Qualified professionals capable of navigating multi-jurisdictional stability testing and preservative efficacy protocols command 40% salary premiums across Seoul, Shanghai, and Singapore hiring markets.
- Clean beauty certification complexity:Competing standards from COSMOS, EWG Verified, and China's own green cosmetic guidelines force parallel documentation tracks that extend go-to-market timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Skincare Market |
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $238.56 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Cleansers, Sunscreens, Serums Application: Anti-Aging, Hydration, Brightening, Acne Treatment Formulation: Natural, Organic, Synthetic, Hybrid End User: Women, Men, Teens, Professionals |
| Companies Covered | Unilever PLC, Procter & Gamble Company, Shiseido Company Limited, Beiersdorf AG, Kao Corporation, Amorepacific Corporation, Estée Lauder Companies Inc, Johnson & Johnson Services Inc, L'Oréal SA, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Skincare Market Evolving Landscape
Biotechnology convergence with traditional herbal extraction is redefining active ingredient sourcing across Asia-Pacific skincare manufacturing. This shift compresses the gap between pharmaceutical-grade efficacy claims and cosmetic regulatory boundaries.
Artificial intelligence-driven skin analysis tools embedded in retail apps and smart mirrors are automating personalized regimen recommendations at scale. Seoul-based beauty tech firms deploy computer vision algorithms trained on Asian skin type databases to match consumers with precise active concentrations. Major pharmacy chains in Osaka and Taipei now integrate these diagnostic layers into their in-store consultation workflows, reducing reliance on trained beauty advisor headcount.
China's NMPA implementation of full ingredient disclosure on product labels and e-commerce listings is forcing reformulation transparency across regional supply chains. Domestic brands in Guangzhou and Hangzhou accelerate "clean" positioning to preempt consumer scrutiny of preservative systems and fragrance compounds. Japanese exporters to China face particular pressure as their traditional quasi-drug functional claims require expanded safety documentation under tightened interpretation guidelines.
Social commerce live-streaming models pioneered on Douyin and Xiaohongshu are displacing traditional department store counter distribution for new product launches. Younger consumers in Chengdu and Xi'an purchase directly from KOL-hosted sessions that demonstrate texture and immediate skin feel, bypassing physical retail entirely. This channel shift rewards brands with agile content production capabilities and penalizes those dependent on fixed retail infrastructure investments.
Asia-Pacific Skincare Market Segmentation
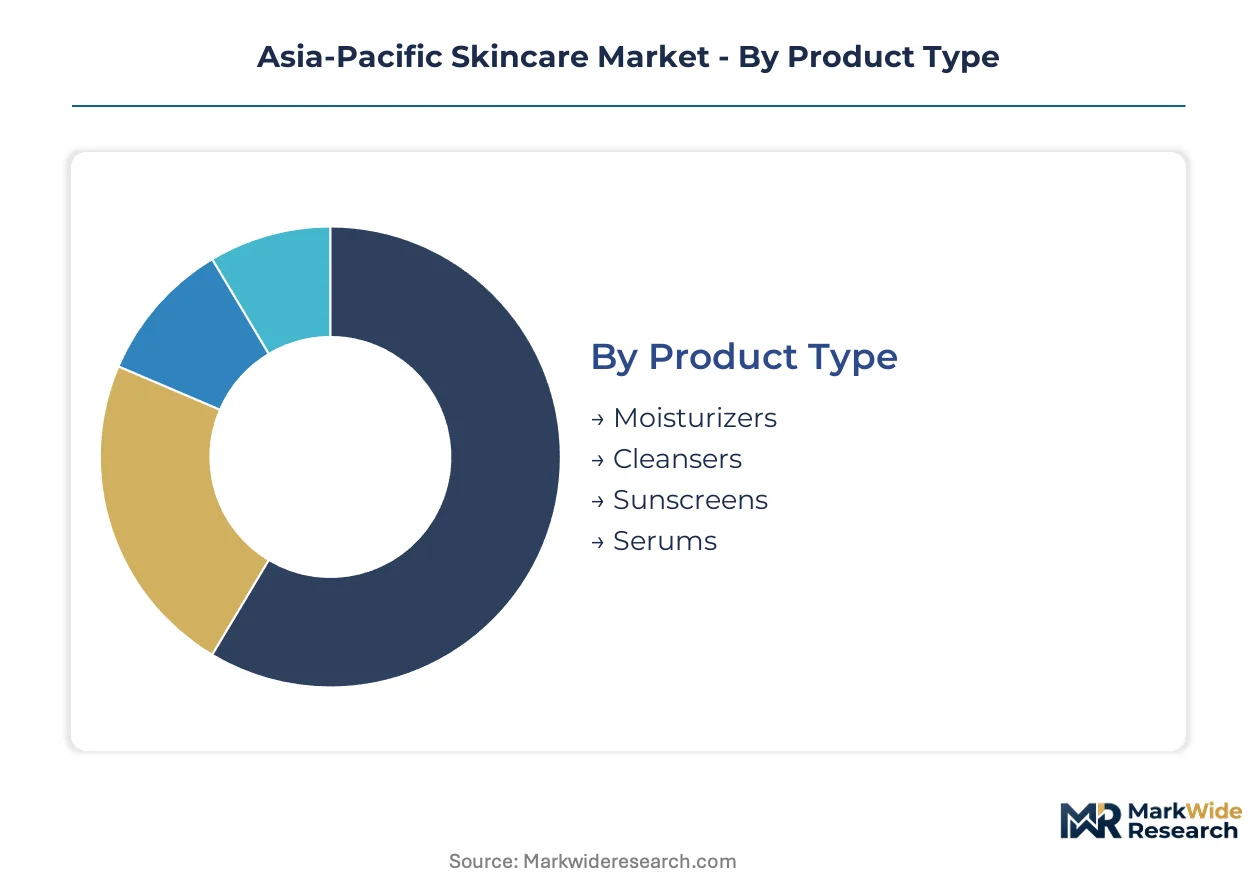
Asia-Pacific skincare segmentation reveals divergent margin architectures across product tiers. Volume concentration in mass-market cleansers contrasts with value capture in concentrated serums, while regulatory complexity fragments formulation strategies across national boundaries.
Product Type:
Volume concentrates in daily-use formats; premium gravitates toward treatment-grade delivery systems with higher active-loading.
- Moisturizers:Emollient-occlusive bases dominate unit sales across humid Southeast Asian climates where lightweight gel-cream textures outperform heavy balms. Indonesia and Vietnam drive volume through mass-market channels as per-capita spending climbs from low bases.
- Cleansers:Oil-based and micellar formats capture growing share in Seoul and Tokyo as double-cleansing routines migrate from Korean beauty influence into mainstream practice. Surfactant innovation focuses on pH-balanced, non-stripping formulations for barrier-conscious consumers.
- Sunscreens:Chemical-physical hybrid filters lead NMPA-compliant lines entering China, with texture innovation targeting matte finishes for tropical Southeast Asian humidity.
- Serums:Ampoule and essence formats anchor K-beauty export growth, with concentrated active delivery commanding price premiums in Shanghai and Bangkok duty-free corridors.
Today's leader: Serums. Tomorrow's challenger: Sunscreens as photoprotection awareness spreads beyond Japan into Southeast Asia.
Application:
Functional claims face divergent regulatory treatment across MFDS, NMPA, and Japan's Ministry of Health, Labour and Welfare pathways.
- Anti-Aging:Peptide and retinoid formulations target Seoul's professional demographic with clinical-positioned lines. Medical aesthetic substitution in Tokyo and Shanghai metro markets constrains pure topical growth.
- Hydration:Hyaluronic acid and ceramide blends serve as entry-point products for emerging middle-class consumers in Jakarta and Ho Chi Minh City, building regimen loyalty before upsell to treatment categories.
- Brightening:Niacinamide and arbutin complexes navigate NMPA whitening claim restrictions through careful ingredient positioning in China, while Korean MFDS functional cosmetics pathway provides clearer regulatory runway.
- Acne Treatment:Salicylic acid and benzoyl peroxide formulations accelerate across humid-climate Southeast Asia where occlusion-related conditions multiply; Japan remains mature with pharmacy-driven maintenance routines.
Anti-Aging commands current value pools. Acne Treatment gains share fastest as Southeast Asian humidity drives condition incidence.
Formulation:
Clean-beauty migration from niche positioning to baseline expectation restructures R&D allocation across regional labs.
- Natural:Plant-derived extracts with documented traditional use in Chinese medicine or Korean hanbang heritage anchor domestic brand positioning in Hangzhou and Seoul, though preservative challenges limit shelf stability.
- Organic:COSMOS-certified supply chains concentrate in Australian and New Zealand sourcing corridors, with premium pricing limiting penetration to affluent urban pockets in Singapore and Hong Kong.
- Synthetic:Peptide and ceramide platforms engineered through biotechnology deliver reproducible efficacy at scale, dominating Unilever's India-tier-two-city expansion and mass-market lines across the region.
- Hybrid:Fermentation biotechnology combining microbial postbiotics with botanical substrates enables Amorepacific's proprietary barrier-repair platforms, bridging pharmaceutical credibility with cosmetic accessibility.
Hybrid formulations capture investment priority. Natural segments face pressure from disclosure-driven consumer scrutiny under NMPA label requirements.
End User:
Gendered segmentation loosens as male-specific routines emerge from underpenetrated bases in humid-climate markets.
- Women:Multi-step regimen culture sustains category depth in Seoul, Shanghai, and Tokyo, with age-cohort targeting from preventive early-twenties lines to menopause-adapted formulations.
- Men:Sebum-regulating and pore-minimizing products target first-mover advantage as grooming routines expand beyond basic cleansing in Bangkok, Jakarta, and Manila professional demographics.
- Teens:Acne-focused, fragrance-free lines with social-media-native branding capture early loyalty through Douyin and Xiaohongshu channels before household purchasing power consolidates.
- Professionals:Time-compressed formats—essence-in-mist, overnight masks—address Seoul and Shanghai white-collar schedules, with portable sizing for business travel corridors.
Women sustain revenue concentration. Men represent the steepest expansion trajectory as category development closes the grooming gap with Western markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemists and biotechnology researchers cluster in Seoul, Shanghai, and Singapore, anchoring the region's innovation pipeline. These talent concentrations shape where premium product development occurs and where regulatory expertise accumulates.
China
Domestic brands in Guangzhou and Hangzhou accelerate clean-beauty positioning as NMPA ingredient disclosure rules force transparency on preservative systems. The regulator's 2021 animal-testing exemption for imported general cosmetics enables cruelty-free positioning that resonates with younger consumers in Chengdu and Xi'an. Social commerce live-streaming on Douyin and Xiaohongshu now displaces traditional department store distribution for new product launches.
South Korea
K-beauty export infrastructure leverages Incheon Free Economic Zone certification fast-tracks to accelerate regional brand expansion into Southeast Asian retail channels. MFDS color-code clarity for functional cosmetics attracts foreign direct investment in localized R&D facilities. Seoul-based labs deploy fermentation biotechnology advances to develop proprietary postbiotic platforms with differentiated barrier-repair mechanisms.
Japan
Pharmacy-driven skin health segments sustain physician-credentialed lines targeting mature maintenance routines. The Ministry of Health, Labour and Welfare enforces distinct safety assessment pathways that fragment registration timelines for cross-border brands. Osaka and Taipei pharmacy chains integrate AI-driven skin analysis tools into in-store consultation workflows, reducing reliance on trained beauty advisor headcount.
India
Affordable derma-cosmetics push into tier-two cities leverages domestic manufacturing scale for cost-efficient distribution. BIS standards and CDSCO pathways create compliance requirements that reward localized formulation adaptation. Mumbai and Delhi-NCR serve as hubs for sebum-regulating product development targeting humid-climate male grooming expansion.
Vietnam
Skincare per-capita spending in Ho Chi Minh City remains significantly below Bangkok levels, creating whitespace for derma-cosmetic lines positioned between mass and pharmacy tiers. Import tariff structures and emerging retail infrastructure attract regional brands seeking first-mover positioning. Local distributors build capacity to handle the temperature-controlled logistics that concentrated serums and fermentation-based actives require.
Asia-Pacific Skincare Market Competitive Landscape
Capital-heavy producers with integrated biotechnology labs compete with asset-light brand houses outsourcing manufacturing to contract formulators. The market structure tierizes between global conglomerates with multi-brand portfolios, regional specialists leveraging fermentation heritage, and emerging domestic challengers capitalizing on social commerce agility. Three archetypes dominate: Seoul-centered biotech innovators, Mumbai-scaled mass-market distributors, and Paris/Tokyo-headquartered luxury houses. Competitive moves concentrate on localized R&D facility investment and cruelty-free certification acquisition to satisfy NMPA compliance and consumer positioning simultaneously.
Among Seoul-based biotechnology innovators, Amorepacific Corporation exemplifies the fermentation-platform archetype, while Kao Corporation represents Japanese pharmacy-channel integration. Unilever PLC occupies a position anchoring India-scaled affordable derma-cosmetic expansion. These three illustrate how geographic origin and structural form—Co., Ltd., Corporation, PLC—correlate with distinct strategic postures in formulation capability versus distribution reach.
| Leading Market Players |
|---|
| Unilever PLC |
| Procter & Gamble Company |
| Shiseido Company Limited |
| Beiersdorf AG |
| Kao Corporation |
| Amorepacific Corporation |
| Estée Lauder Companies Inc |
| Johnson & Johnson Services Inc |
| L'Oréal SA |
| Others |
Value Network & Pricing Analysis
Captive biotechnology infrastructure anchors both cost position and margin defense for Seoul-based fermentation platforms, while outsourced contract manufacturing in Guangzhou and Mumbai enables price-competitive mass-market entry. This structural split between in-house R&D integration and third-party production defines how pricing power accumulates at the premium tier and erodes in commoditized segments.
Pricing Analysis
Bundled regimen positioning commands premium capture in Seoul and Shanghai, where multi-step K-beauty protocols justify kit pricing; unbundled single-SKU transactions dominate Jakarta and Ho Chi Minh City mass channels. Three-tier pricing structure across premium, standard, and economy levels separates MFDS-certified functional cosmetics from NMPA-compliant general lines and basic cleansers. Price differentiation hinges on fermentation-derived active concentrations and cruelty-free certification status. Cost compression in mass-market ceramide moisturizers is intensifying because Yangtze River delta logistics disruptions inflate eastern China sourcing costs. Tier-two city consumers in India and Vietnam exhibit highest price sensitivity; Tokyo and Singapore professional demographics show lowest.
Supply Chain Analysis
Single-source vulnerability sits with eastern China peptide and ceramide active suppliers, where over sixty percent of regional capacity clusters in Jiangsu and Zhejiang provinces. Raw material dependencies center on postbiotic fermentation substrates, hyaluronic acid precursors, and photostable UV filter compounds. Supply chain risk manifests as tariff exposure on Korean-manufactured ampoules entering Chinese e-commerce channels. Distribution runs through temperature-controlled logistics networks serving Incheon Free Economic Zone export corridors and domestic pharmacy chains in Osaka and Taipei.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific skincare market functions as a geographic-arbitrage play where NMPA animal-testing exemptions enable cruelty-free positioning at fifteen to twenty percent pricing premiums in Chengdu and Hangzhou versus pre-2021 compliance costs.
For Market Incumbents: Anchor fermentation biotechnology capabilities through captive Seoul lab investment to defend against medical aesthetic substitution in Tokyo and Shanghai metro markets. Deepen backward integration into postbiotic strain engineering to protect proprietary barrier-repair platforms from generic replication. Prioritize MFDS color-code certification maintenance as NMPA disclosure rules tighten competitive transparency requirements.
For New Entrants and Emerging Players: Begin with men's sebum-regulating formulations in Jakarta and Manila, where grooming routine penetration trails Bangkok by seventy percent and first-mover content advantages persist. Target social commerce live-streaming channels on Douyin and Xiaohongshu for launch velocity, bypassing fixed retail infrastructure entirely. Position between mass and pharmacy tiers in Ho Chi Minh City to capture emerging middle-class regimen building.
For Investors and Strategic Acquirers: Roll-up economics work for contract fermentation manufacturers with NMPA-registered facilities because regulatory reciprocity negotiations between Seoul and Beijing would reshape cross-border entry costs and stranded asset risk. Five-to-ten year viability favors platforms with dual MFDS and NMPA pathway expertise. The signal to watch is mutual recognition agreement announcements between South Korea's MFDS and China's NMPA, which would compress registration timelines for unified regional portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Localized R&D Facility Investment | MFDS color-code clarity attracts foreign direct investment in Seoul fermentation labs. |
| Cruelty-Free Certification Acquisition | NMPA animal-testing exemptions enable premium positioning in Chengdu and Xi'an. |
| Social Commerce Channel Expansion | Douyin and Xiaohongshu live-streaming displaces department store distribution for launches. |
| Backward Integration into Biotechnology | Captive postbiotic strain engineering protects proprietary barrier-repair platforms. |
| Men's Grooming Line Extension | Sebum-regulating formulations target underpenetrated Jakarta and Manila professional demographics. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with brand managers, category buyers at regional pharmacy chains, MFDS regulatory consultants, and fermentation biotechnology R&D directors with secondary validation. Customs records, NMPA filing databases, MFDS functional cosmetics registries, and Nielsen retail audit data anchor volume and value estimates. This triangulation ensures capture of both channel-level demand signals and production-capacity constraints across Seoul, Shanghai, and Singapore innovation clusters.
Input-output matrices map active ingredient loading concentrations to finished product pricing tiers across the projection horizon, with segmentation modeled by product type, application, formulation, and end user. CAGRs derive from regression analysis of historical per-capita spending patterns, regulatory pathway timelines, and channel shift velocities. Forecast inputs include MFDS-NMPA reciprocity negotiation status and social commerce penetration rates in tier-two Chinese cities.
Several conditions sit outside the modeled scope, including unforeseen pandemic-related logistics disruptions, abrupt NMPA interpretation shifts on whitening claim enforcement, and medical aesthetic technology breakthroughs accelerating substitution beyond projected rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Germany Skincare Product Market
Skincare
Global Cosmetic Skin Care Market
Skincare
Hand Care Market
Skincare
Hyaluronic Acid Personal Care Products Market
Skincare
Algae Skincare Products Market
Skincare
Skin Care Body Products Market
Skincare
Cystic Acne Market
Skincare
Acne Treatment Market
Skincare
Fragrance-Free Skin Care Products Market
Skincare
Sensitive Skin Care Products Market
Skincare
Global Eczema Skin-Care Products Market
Skincare
South Korea Anti-Acne Dermal Patch Market
Skincare
Facial Massage Cream Market
Skincare
Non-Surgical Skin Tightening Market
Skincare
Anti-Aging Services Market
Skincare
Revitalizing Skin Wands Market