
 Medicine Skin Care Market | 2026-2036
Medicine Skin Care Market Size, Share, and Industry Trends Forecast 2026-2036
Medicine Skin Care Market Analysis
Multi-source ingredient procurement is realigning competitive dynamics across the medicine skin care value chain. Galderma leverages its dermatology-focused R&D pipeline to sustain clinical credibility in prescription-adjacent segments. Johnson & Johnson anchors mass-market distribution through pharmacy and retail clinic networks. Beiersdorf competes on formulation science, particularly in barrier-repair technologies that bridge cosmetic and therapeutic claims.
Medicine skin care encompasses topically applied products formulated with active pharmaceutical or biologically active ingredients at concentrations that deliver measurable dermatological outcomes beyond basic cleansing or moisturizing. These formulations typically incorporate retinoids, hydroxy acids, or peptides at precise pH levels and penetration-enhancing delivery systems to modulate skin cell turnover, inflammation, or barrier function for therapeutic or preventive purposes. Treatments targeting acne and anti-aging applications command disproportionate margin pools due to higher clinical validation requirements and prescriber channel access. Hyaluronic acid and retinol ingredient segments lead volume, while peptide-based formulations represent the fastest-expanding category as biosynthetic production costs decline and bioavailability data accumulates.
The FDA regulates medicine skin care products straddling the drug-cosmetic boundary through monograph systems and new drug application pathways, directly determining market access timelines and labeling claims. EMA's Medical Device Regulation and REACH chemical safety frameworks in Europe impose additional toxicological and efficacy documentation burdens on active ingredient suppliers. China's NMPA has tightened registration requirements for imported functional cosmetics, creating compliance complexity for multinational brands. Stakeholders must monitor evolving regulatory convergence between cosmetic and pharmaceutical classifications, as this boundary shift will determine which product categories require clinical trial investment versus accelerated market entry.
Market Dynamics
The medicine skin care market is being fundamentally restructured by regulatory convergence between pharmaceutical and cosmetic classifications, as the FDA, EMA, and NMPA tighten ingredient documentation requirements and blur traditional channel boundaries between prescription and over-the-counter distribution.
Growth Catalysts
- Peptide biosynthesis cost decline:Recombinant production methods have reduced active peptide manufacturing expenses by half, enabling broader formulation access for mid-market brands.
- EMA Medical Device Regulation clarity:The MDR's 2021 implementation provided definitive pathways for barrier-repair devices, accelerating European clinic adoption of combination drug-device protocols.
- Subscription commerce infrastructure:Direct-to-consumer platforms in the United States have built recurring revenue models that bypass traditional pharmacy distribution economics.
Market Restraints
- Retinol supply concentration:Three Chinese chemical manufacturers control 70% of pharmaceutical-grade retinol precursor supply, creating input vulnerability for Western formulators.
- FDA monograph revision delays:Pending OTC sunscreen and acne drug reclassifications have frozen labeling claims for hydroxy acid products since 2019.
- Clinical trial cost inflation:Dermatological endpoint studies for cosmetic-drug hybrids now require 18-24 month timelines that exclude smaller competitors.
Strategic Opportunities
- India's functional cosmetics registration pathway:CDSCO's 2023 streamlined import rules for cosmeceuticals create first-mover advantage for peptide-based entrants.
- Telemedicine-integrated prescription fulfillment:Virtual dermatology platforms in Germany and the United Kingdom enable direct shipment of professional-grade regimens without clinic inventory.
- Microbiome modulation science:Converging metagenomic sequencing and topical delivery technologies open therapeutic claims for rosacea and atopic dermatitis previously reserved for systemic drugs.
Industry Challenges
- Formulation chemist scarcity:The specialized expertise required for pH-stable retinoid encapsulation commands premium compensation that mid-tier manufacturers struggle to fund.
- Legacy ERP integration:Batch record systems designed for pure cosmetics lack traceability modules for active pharmaceutical ingredient handling required by FDA 21 CFR Part 11.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medicine Skin Care Market |
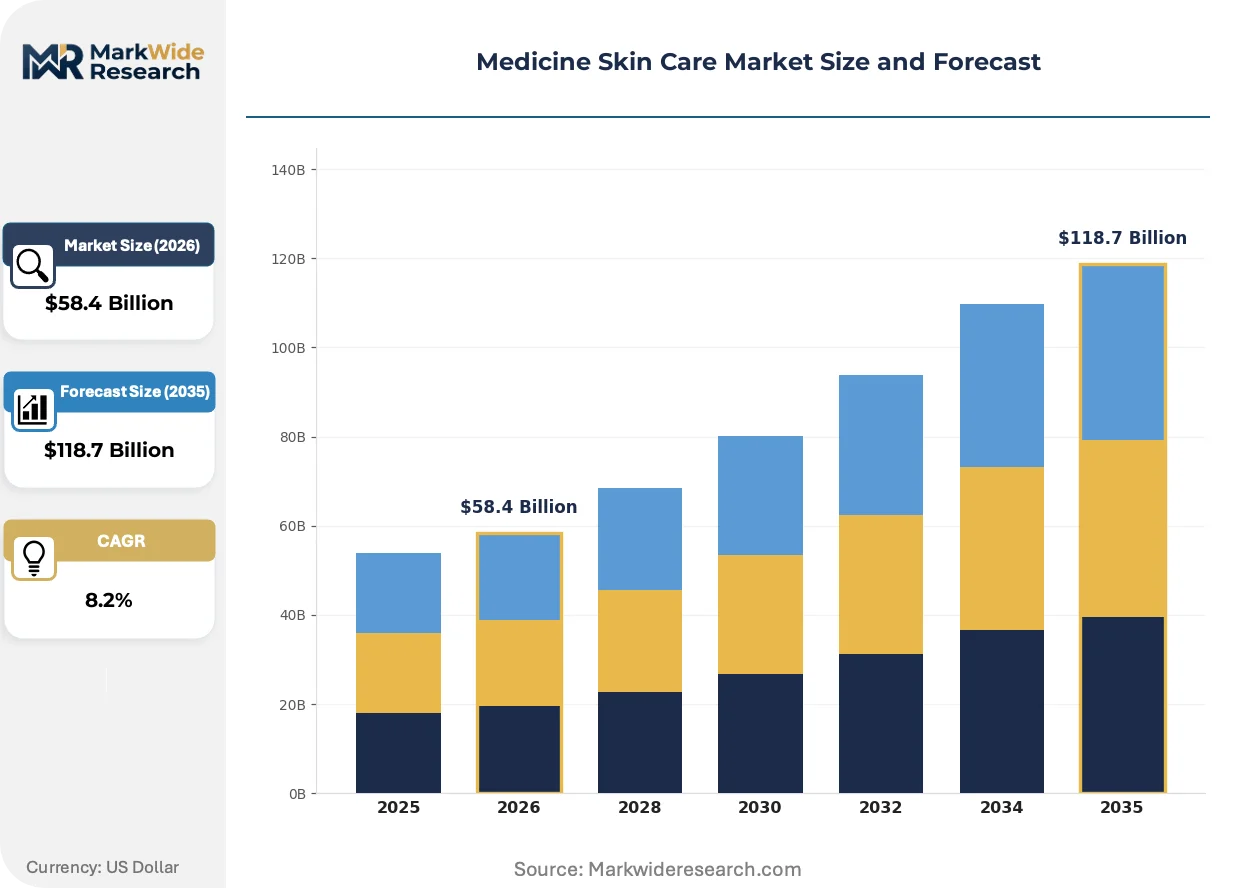
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $118.7 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Serums, Cleansers, Treatments Ingredient: Hyaluronic Acid, Retinol, Salicylic Acid, Peptides Skin Type: Oily, Dry, Combination, Sensitive Application: Anti-aging, Acne Treatment, Hydration, Skin Brightening |
| Companies Covered | Johnson & Johnson, Bayer, Beiersdorf, Pfizer, Galderma, Merz Pharma, SkinCeuticals International, La Roche-Posay, Abbvie Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medicine Skin Care Market Emerging Trajectories
Active ingredient delivery systems are converging with digital diagnostic tools to create personalized therapeutic protocols, while regulatory documentation requirements force consolidation among formulation suppliers unable to meet escalating toxicological data demands.
Liposomal and nanostructured lipid carrier technologies are consolidating around a handful of patent-holding excipient suppliers who control access to enhanced bioavailability data required for premium positioning. Dermatology clinics in South Korea and the United States have standardized procurement around these delivery platforms, compressing margins for conventional emulsion formulators. The technology is consolidating competitive advantage toward integrated manufacturers with captive excipient production.
REACH chemical safety frameworks in Europe now mandate full substance dossiers for novel cosmetic actives above 0.1% concentration, forcing reformulation of peptide and growth factor products. Manufacturers have responded by relocating clinical validation studies to jurisdictions with mutual recognition agreements, particularly Switzerland and Australia. The regulatory burden falls heaviest on indie brands lacking dedicated regulatory affairs departments.
Prescriber channel access is fragmenting as telemedicine platforms unbundle the traditional dermatologist-clinic-pharmacy pathway. Patients in the United States and United Kingdom now initiate acne and anti-aging consultations through app-based services that ship compounded formulations directly. This channel compression is most visible among millennial and Gen-Z demographics who bypass insurance reimbursement structures entirely for convenience.
Medicine Skin Care Market Segmentation
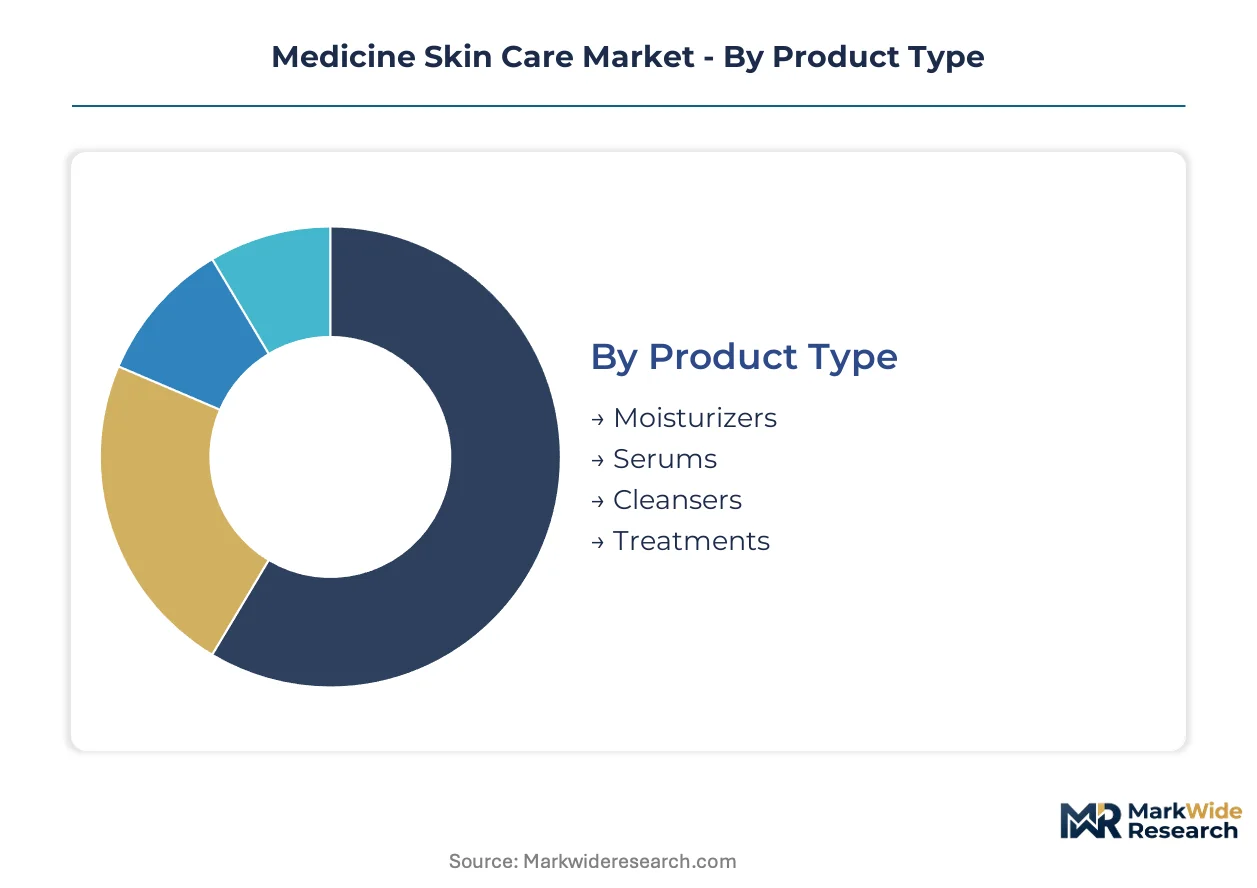
Medicine skin care segmentation reveals distinct upgrade cycles across product categories. Patients progress from basic cleansers to active serums as tolerance builds, while ingredient innovation drives replacement frequency in premium tiers.
Product Type:
Replacement cycles accelerate as consumers graduate from foundational products to targeted treatments with higher active concentrations.
- Moisturizers:Barrier-repair formulations with ceramide complexes and cholesterol ratios matching stratum corneum lipid profiles. Demand clusters in United States dermatology clinics where post-procedure recovery protocols require occlusive hydration layers; prescriber endorsement drives premium pricing over mass-market equivalents.
- Serums:Low-viscosity vehicles delivering 5-15% active concentrations through water-based or anhydrous systems. South Korean aesthetic clinics standardize vitamin C and peptide serums in combination protocols; patient compliance depends on absorption speed and sensory profile.
- Cleansers:pH-balanced surfactant systems below 5.5 to preserve acid mantle integrity.
- Treatments:Prescription-adjacent categories including retinoid gels and hydroxy acid peels.
Volume placements concentrate in Moisturizers; the faster expansion belongs to Serums.
Ingredient:
Cost tier differentiation separates commodity actives from biosynthetic specialties requiring dedicated manufacturing infrastructure.
- Hyaluronic Acid:Biopolymer with molecular weight dictating dermal penetration depth, from 50 kDa humectants to 2 MDa surface film-formers. German pharmacy chains stock multi-weight formulations; consumer education around cross-linking density influences repurchase decisions.
- Retinol:Vitamin A derivatives requiring encapsulation or esterification for stability against oxidation and photodegradation. United States direct-to-consumer brands build subscription models around graduated concentration protocols; tolerance-building regimens extend customer lifetime value.
- Salicylic Acid:Lipophilic beta-hydroxy acid penetrating sebaceous follicles at 2% OTC concentrations.
- Peptides:Short-chain amino acid sequences signaling collagen synthesis or neurotransmitter modulation.
Hyaluronic Acid dominates current volume; peptide-based lines are gaining share fastest as recombinant production costs decline.
Skin Type:
Application specificity determines formulation architecture and marketing channel selection.
- Oily:Non-comedogenic vehicles with sebum-absorbing powders or mattifying silica. United Kingdom telemedicine platforms prescribe niacinamide-zinc combinations for this segment; digital diagnostic tools match severity to active concentration.
- Dry:Occlusive-heavy systems with petrolatum, dimethicone, or plant-derived squalane. Japanese aesthetic clinics favor layered moisture approaches; humid climate adaptation requires regional reformulation.
- Combination:Zone-specific protocols addressing T-zone oiliness alongside cheek dryness.
- Sensitive:Minimal-ingredient formulations excluding fragrance, essential oils, and known irritants.
Oily skin commands the largest patient consultation volume; sensitive skin applications show the steepest expansion trajectory as barrier dysfunction diagnoses multiply.
Application:
Margin structures vary dramatically by therapeutic claim validation requirements and prescriber channel access.
- Anti-aging:Retinoid and antioxidant protocols targeting photoaging and intrinsic collagen decline. Swiss cosmetic surgery clinics bundle pre- and post-operative skin conditioning; procedural adjacency justifies professional-grade pricing.
- Acne Treatment:Keratolytic and antimicrobial actives addressing inflammatory and non-inflammatory lesions. United States pharmacy benefit managers increasingly cover adapalene and benzoyl peroxide combinations; generic substitution pressure constrains branded pricing.
- Hydration:Barrier-support and humectant strategies for xerosis and environmental stress.
- Skin Brightening:Tyrosinase inhibitors and melanin transfer blockers for hyperpigmentation.
Acne Treatment generates the highest prescription-adjacent volume; Anti-aging is climbing the fastest as preventive protocols start in younger demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States dermatology clinics and direct-to-consumer platforms concentrate disproportionate demand for professional-grade formulations, while regulatory divergence across FDA, EMA, and NMPA jurisdictions fragments compliance pathways for active ingredient suppliers.
United States
Subscription-based medical skin care brands have built recurring revenue models that bypass traditional pharmacy distribution. FDA oversight of over-the-counter topical drug classifications continues reshaping formulation requirements and labeling standards. Dermatology clinics in California and New York Metro expand professional-grade product portfolios as patient visits for aesthetic conditions rise.
Germany
Pharmacy chains stock multi-weight hyaluronic acid formulations where consumer education around cross-linking density influences repurchase decisions. EMA's Medical Device Regulation provides definitive pathways for barrier-repair devices, accelerating clinic adoption of combination drug-device protocols. Berlin-Brandenburg hosts telemedicine-integrated prescription fulfillment platforms shipping professional-grade regimens directly.
South Korea
Aesthetic clinics standardize vitamin C and peptide serums in combination protocols where patient compliance depends on absorption speed. MFDS registration requirements for functional cosmetics create compliance benchmarks for peptide-based entrants. Seoul Capital Area concentrates formulation R&D facilities serving Asian export markets.
China
NMPA has tightened registration requirements for imported functional cosmetics, creating compliance complexity for multinational brands. Yangtze River Delta manufacturing clusters produce pharmaceutical-grade retinol precursors controlling substantial Western supply. Shanghai-based brands build domestic subscription commerce infrastructure rivaling United States models.
Switzerland
Cosmetic surgery clinics bundle pre- and post-operative skin conditioning where procedural adjacency justifies professional-grade pricing. Swissmedic regulatory frameworks attract clinical validation studies from manufacturers seeking mutual recognition agreements. Zurich and Geneva anchor premium formulation development for barrier-repair technologies.
Medicine Skin Care Market Vendor Landscape
Portfolio diversification dominates the current landscape as manufacturers bridge cosmetic and therapeutic claims through formulation science investments. The vendor base separates into three tiers: dermatology-focused R&D pipelines, mass-market distribution anchors, and biosynthetic specialty suppliers. Consolidation pressure intensifies around delivery system patent holders and peptide production capabilities. Strategic partnerships between clinics and direct-to-consumer platforms compress traditional channel margins.
Among dermatology-centric developers, Galderma and La Roche-Posay occupy positions emphasizing clinical credibility in prescription-adjacent segments. Johnson & Johnson represents the mass-market distribution archetype, anchoring pharmacy and retail clinic networks. Beiersdorf exemplifies formulation science specialization, particularly in barrier-repair technologies that bridge cosmetic and therapeutic claims.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Bayer |
| Beiersdorf |
| Pfizer |
| Galderma |
| Merz Pharma |
| SkinCeuticals International |
| La Roche-Posay |
| Abbvie Inc |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up formulation specialists now control substantial peptide production capacity, tightening supply discipline and enabling coordinated pricing power across professional-grade and direct-to-consumer channels. This ownership consolidation links R&D amortization schedules to subscription pricing models that extract lifetime value through graduated concentration protocols.
Pricing Analysis
Volume placements concentrate in mass-market moisturizers while margin pools cluster in prescription-adjacent treatments. Three-tier pricing structure across premium, standard, and economy levels separates dermatology clinic protocols from pharmacy-tier and direct-to-consumer offerings. Price differentiation hinges on clinical validation depth and prescriber channel access. Cost compression in mid-market serums is intensifying because biosynthetic peptide supply expansion lags formulation demand.
Supply Chain Analysis
Returns of temperature-compromised peptide shipments and expired retinoid inventory flow through specialized reverse-logistics networks that recover active ingredients for reformulation. Pharmaceutical-grade retinol precursor supply concentrates in China, with South Korea and Germany anchoring downstream formulation. Raw material dependencies center on recombinant peptide feedstocks, liposomal excipients, and pH-stable encapsulation polymers. Single-source vulnerability in retinol precursors creates input risk for Western manufacturers. Distribution runs through dermatology clinic procurement, pharmacy chains, and direct-to-consumer fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained: peptide biosynthesis capacity expansion trails formulation demand growth, propping pricing power for integrated manufacturers with captive production.
For Market Incumbents: Cement clinical credibility through prescriber channel exclusivity and barrier-repair patent portfolios that generic entrants cannot replicate. Expand backward integration into recombinant peptide production to secure input supply against Chinese precursor concentration. Threat substitution from telemedicine platforms shipping compounded formulations demands direct-to-consumer platform acquisitions or partnerships. For New Entrants and Emerging Players: Millennial and Gen-Z subscribers bypassing insurance reimbursement represent the most penetrable buyer archetype in the United States and United Kingdom. Telemedicine-integrated prescription fulfillment in Germany offers white-space entry with lower regulatory burden than clinic inventory models. Microbiome modulation science for rosacea and atopic dermatitis provides differentiation through therapeutic claims previously reserved for systemic drugs. Go-to-market through app-based diagnostic platforms that ship personalized regimens directly. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier manufacturers with FDA 21 CFR Part 11-compliant batch record systems but stranded without peptide supply contracts in the United States. Long-term viability over a 5-10 year window rests on regulatory convergence between cosmetic and pharmaceutical classifications favoring clinically validated portfolios. Acquisition targets should demonstrate mutual recognition agreement study relocation capabilities. Monitor FDA monograph revision timelines for OTC sunscreen and acne drug reclassifications as inflection indicators for labeling claim expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Peptide Biosynthesis | Captive recombinant production secures supply against Chinese precursor concentration and enables cost discipline. |
| Telemedicine Platform Partnership | Direct-to-consumer fulfillment bypasses pharmacy distribution economics and captures millennial subscription revenue. |
| Barrier-Repair Patent Portfolio Expansion | EMA MDR-compliant device-drug protocols create prescriber channel exclusivity in European dermatology clinics. |
| CDSCO Registration First-Mover Entry | India's streamlined functional cosmetics pathway offers peptide-based positioning ahead of competitor filings. |
| Microbiome Modulation Clinical Validation | Metagenomic sequencing data supports therapeutic claims for rosacea previously reserved for systemic prescriptions. |
Methodological Framework
Multi-period observation of peptide production cost curves, FDA monograph revision status, and telemedicine platform subscriber growth anchored the trend analysis, supplemented by interviews with dermatology clinic procurement managers, formulation R&D directors, regulatory affairs leads at multinational manufacturers, and pharmacy chain category buyers. Secondary validation drew from FDA 510(k) filings, EMA Medical Device Regulation guidance documents, ClinicalTrials.gov dermatology endpoints, and MFDS functional cosmetics registration databases. Bottom-up patient consultation volume estimates triangulated against top-down manufacturer revenue disclosures.
Segment-weighting across product type, active ingredient concentration tier, skin condition severity, and distribution channel informed the analytical framework over the projection horizon. Modeled dimensions included moisturizer versus serum versus treatment category splits, retinol versus peptide versus hyaluronic acid ingredient shares, and clinic versus pharmacy versus direct-to-consumer channel mix. CAGRs were derived from patient visit growth trajectories, active ingredient cost elasticity curves, and subscription renewal rate assumptions across demographic cohorts.
Revisions become necessary when FDA OTC monograph final rules materialize, when Chinese retinol precursor export restrictions emerge, or when EMA-REACH substance dossier requirements expand beyond current thresholds. Forecasts reflect documented assumptions regarding regulatory timeline stability, biosynthetic production cost decline trajectories, and telemedicine platform reimbursement policy evolution. Practitioners should monitor peptide production capacity announcements, CDSCO registration application volumes, and virtual dermatology platform funding rounds for early signals of supply-demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Global Hand Lotion and Hand Cream Market
Skincare
Skin Care Emulsion Market
Skincare
Global Healthcare Wipes Market
Skincare
Hand Eczema (HE) Treatment Market
Skincare
Dermal Regeneration Market
Skincare
Revitalizing Skin Wands Market
Skincare
Hand Care Market
Skincare
Facial Erythema Treatment Market
Skincare
US Acne Treatment Market
Skincare
CBD Skin Care Market
Skincare
After Sun Care Products Market
Skincare
CBD Skincare Products Market
Skincare
Africa Cosmeceutical Market
Skincare
Self-Tanning Care Market
Skincare
Skincare Cdmo and Cmo Market
Skincare
Asia Pacific Traditional Chinese Herbal Medicine for Face-Care Market