
 Global Eczema Skin-Care Products Market | 2026-2036
Global Eczema Skin-Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
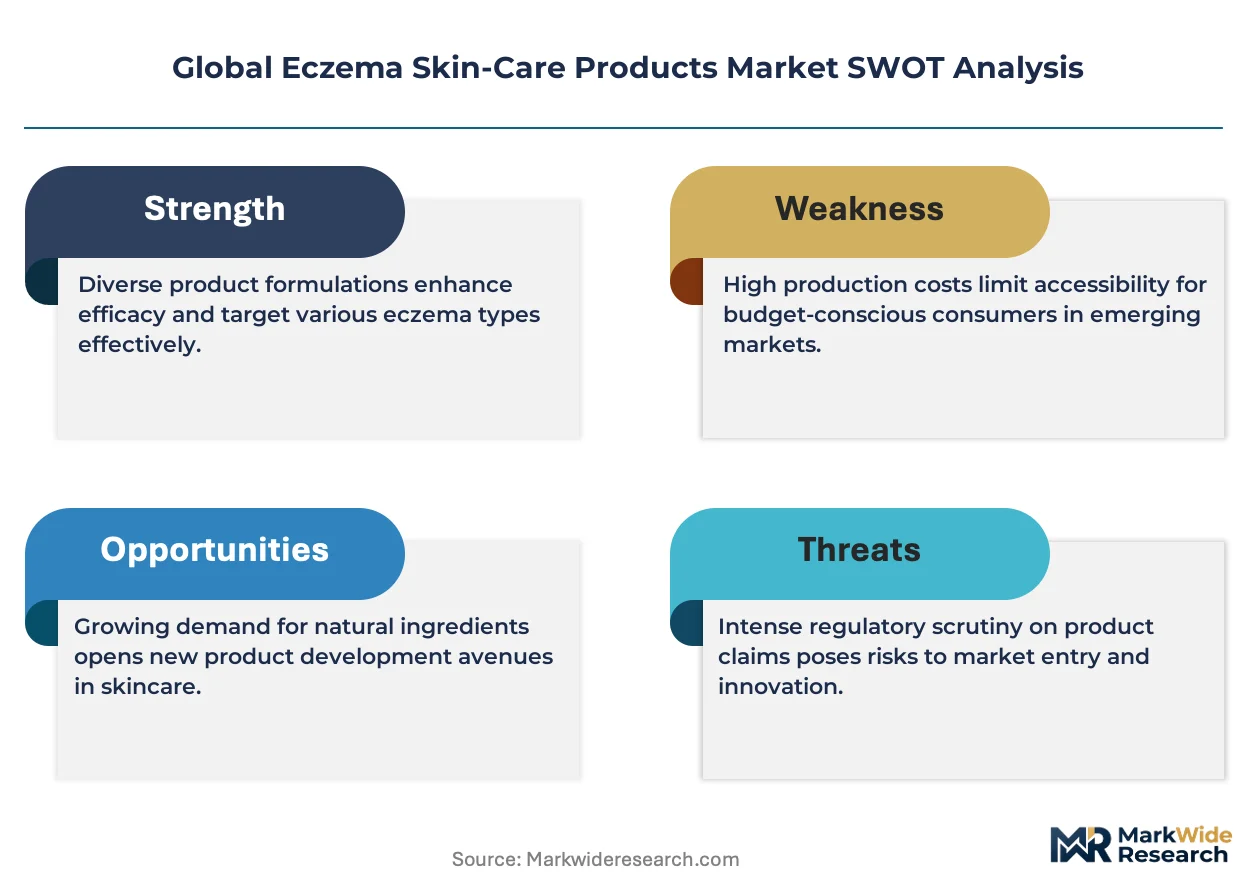
Global Eczema Skin-Care Products Market Analysis
North American manufacturing capacity for ceramide-based emollients is tilting toward dedicated dermatological production lines. Eucerin leverages its German R&D heritage to sustain prescription credibility in European markets. Johnson & Johnson Consumer Inc. anchors mass-market distribution through pharmacy and retail hybrid channels. Galderma Laboratories, L.P. specializes in physician-dispensed positioning that commands premium shelf placement in clinical settings.
Eczema skin-care products comprise topical formulations designed to restore barrier function, modulate inflammation, and maintain cutaneous hydration through lipid-replenishing matrices typically containing ceramides, cholesterol, and free fatty acids in a 3:1:1:1 molar ratio. These products serve both acute flare management and chronic maintenance protocols across outpatient dermatology, retail pharmacy, and direct-to-consumer channels. Cream formulations dominate volume due to patient compliance advantages in pediatric applications, while calcineurin inhibitor segments capture disproportionate margin pools in adult atopic dermatitis maintenance. Online retail channels are expanding fastest as tele-dermatology platforms validate remote prescribing workflows.
FDA OTC monograph reforms and the EU MDR are converging to demand enhanced safety documentation for long-term corticosteroid exposure, directly influencing formulation R&D priorities across manufacturers. ECHA REACH compliance for preservative systems and fragrance allergens is narrowing the acceptable excipient palette for European market access. China's NMPA biocompatibility standards for infant-directed topicals are adding a third regulatory vector that multinational portfolios must address. Stakeholders should monitor how regulator alignment on microbiome preservation claims reshapes competitive differentiation in barrier-repair positioning.
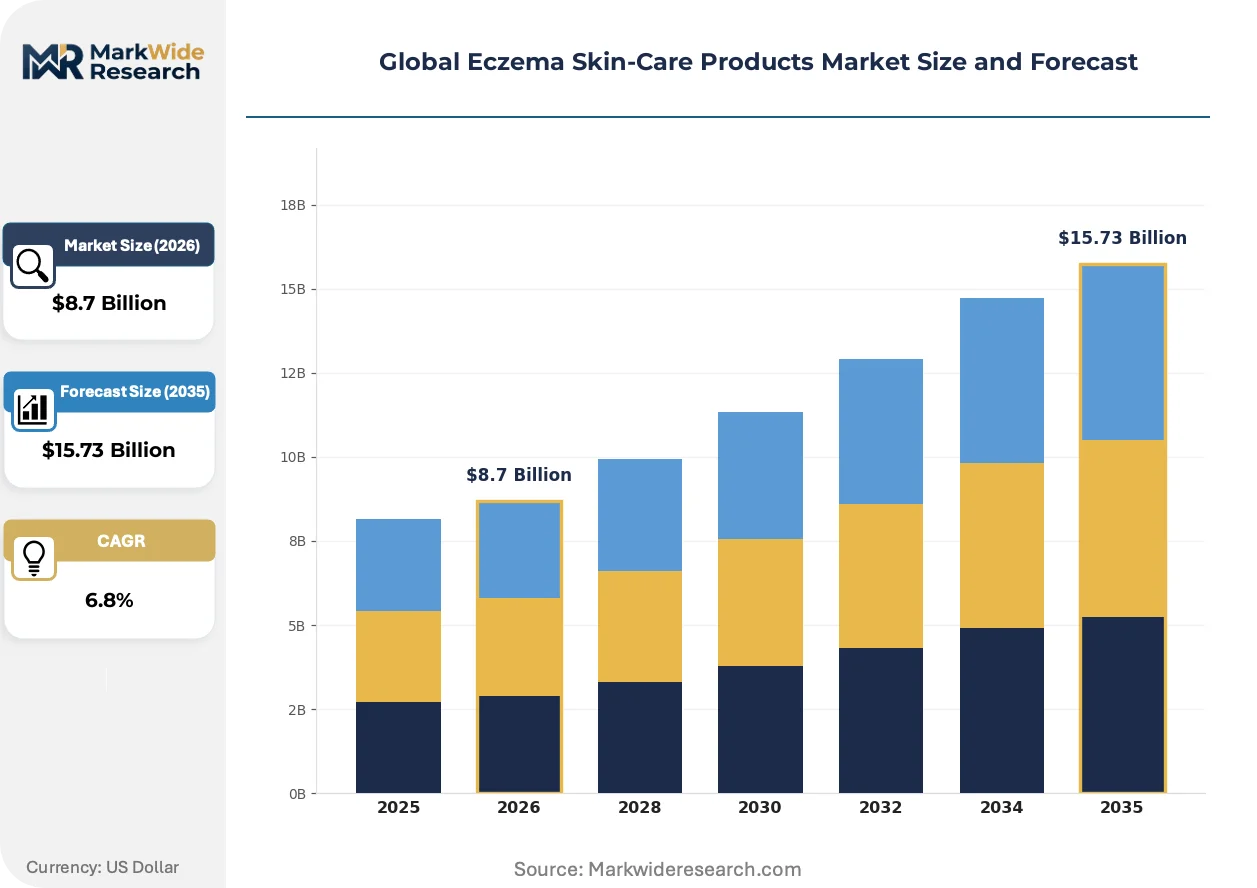
Market Dynamics
Regulatory convergence on long-term corticosteroid safety documentation is forcing manufacturers to reallocate R&D expenditure toward steroid-sparing active ingredients and ceramide-dominant barrier matrices.
Growth Catalysts
- EU MDR ingredient disclosure mandates:Heightened transparency requirements for fragrance allergens and preservative systems are accelerating reformulation toward microbiome-compatible excipients in European markets.
- Pediatric dermatology procurement:North American clinics are expanding dedicated procurement protocols for steroid-sparing maintenance formulations in atopic dermatitis protocols.
- Tele-dermatology platform validation:Remote prescribing workflows are normalizing direct-to-patient distribution channels for prescription-strength emollients.
Market Restraints
- Petrochemical feedstock volatility:Squalane and ceramide precursor supply chains face input cost pressure from specialty lipid intermediate markets.
- Single-source API concentration:Tacrolimus and pimecrolimus active pharmaceutical ingredients concentrate among limited contract manufacturers in South Korea and India.
- ECHA REACH compliance burden:Preservative system reauthorization timelines create formulation lock-in effects that constrain rapid product iteration.
Strategic Opportunities
- Japan hospital outpatient channel:Reimbursement pathway expansion for barrier-repair products in adult atopic dermatitis maintenance creates premium positioning potential.
- China NMPA biocompatibility standards:Infant-directed topical certification requirements favor established multinationals with documented safety dossiers.
- Microbiome preservation claim convergence:Regulator alignment on skin flora-friendly positioning opens differentiation white space currently unoccupied by legacy brands.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in lipid matrix stabilization and controlled-release ceramide delivery commands premium compensation in competitive labor markets.
- Dual regulatory dossier maintenance:Simultaneous FDA OTC monograph compliance and EU MDR technical documentation requirements strain regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Eczema Skin-Care Products Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creams, Ointments, Lotions, Gels Active Ingredient: Corticosteroids, Calcineurin Inhibitors, Moisturizers, Antihistamines Age Group: Infants, Children, Adults, Elderly Sales Channel: Online Retail, Pharmacies, Supermarkets, Health Stores |
| Companies Covered | Eucerin, Johnson & Johnson Consumer Inc., Aveeno, Galderma Laboratories, L.P., L'Oréal USA, Inc., CeraVe, La Roche-Posay, Aquaphor, Cetaphil, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Eczema Skin-Care Products Market Emerging Trajectories
Digital validation of skin barrier function through consumer-grade devices is compressing the feedback loop between product application and perceived efficacy, reshaping how manufacturers demonstrate clinical credibility.
Biomimetic lipid nanostructures engineered to replicate the stratum corneum's native 3:1:1:1 ceramide-cholesterol-fatty acid architecture are penetrating dermatology clinic dispensing protocols. Academic medical centers in Germany and the Netherlands are piloting these formulations for post-flare maintenance. This precision-mimicry approach is virtualizing the traditional emollient category by collapsing the distinction between cosmetic moisturization and therapeutic barrier repair.
FDA OTC monograph reforms targeting long-term corticosteroid exposure documentation are compelling manufacturers to generate multi-year safety datasets for previously grandfathered active ingredients. The industrial consequence is delayed new-entry timelines for abbreviated new drug applications. Pediatric indication expansions face the steepest compliance burden, with sponsors now required to submit juvenile toxicology studies previously waived under predicate rules.
Subscription-based replenishment models for chronic maintenance regimens are displacing episodic pharmacy purchasing in adult atopic dermatitis populations. Direct-to-consumer platforms with integrated teledermatology consultation are capturing patient cohorts previously managed through retail pharmacy channels. This behavioral shift is most pronounced in urban Australian and Canadian markets where dermatologist wait times exceed eight weeks.
Global Eczema Skin-Care Products Market Segmentation
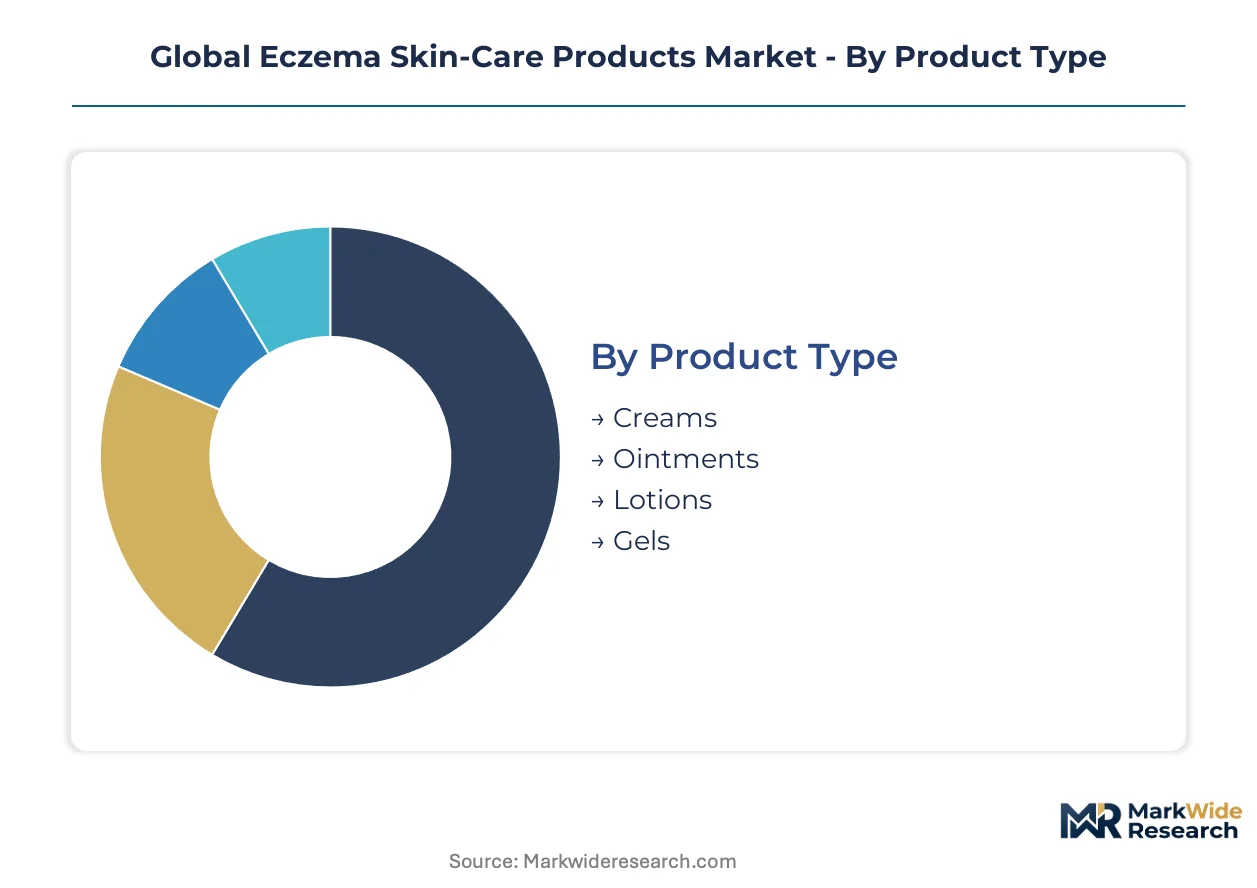
Formulation texture, active mechanism, patient life stage, and purchase venue each create distinct competitive arenas with divergent margin structures and regulatory pathways. Manufacturers must align R&D investment and channel strategy to the specific requirements of each dimension.
Product Type:
Cost tier stratification in topical delivery systems determines reimbursement eligibility, patient compliance rates, and manufacturing complexity across dermatology portfolios.
- Creams:Oil-in-water emulsions with intermediate occlusivity balance spreadability with barrier repair efficacy. Pediatric dermatology clinics in the United States and Germany concentrate procurement here due to caregiver acceptance and formulary inclusion.
- Ointments:Petrolatum-dominant matrices deliver maximum transepidermal water loss reduction through fully occlusive films. Demand clusters in severe atopic dermatitis protocols and elderly populations with xerotic eczema where Medicare and statutory health insurance systems cover prescription-strength variants.
- Lotions:Lower-viscosity formulations suit large-surface-area application and humid climates. Rapid absorption appeals to active adult demographics in Australian and Brazilian markets.
- Gels:Hydroalcoholic or aqueous polymer bases accommodate hair-bearing areas and cosmetic elegance preferences. Acute intertriginous flare management drives hospital outpatient dispensing in Japan.
Creams command the established base. The steepest expansion runs through ointments as reimbursement pathways broaden for high-efficacy maintenance protocols.
Active Ingredient:
Application purpose divides the market into acute intervention, chronic modulation, and preventive maintenance categories with fundamentally different clinical evidence requirements.
- Corticosteroids:Anti-inflammatory glucocorticoid actives classified by potency from hydrocortisone to clobetasol. FDA OTC monograph reform and EMA safety documentation mandates are compressing long-term use indications and accelerating prescription-to-OTC reclassification timelines.
- Calcineurin Inhibitors:Tacrolimus and pimecrolimus macrolactams suppress T-cell activation without skin atrophy risk. Premium positioning in facial and pediatric applications drives disproportionate margin capture in German pharmacy and Japanese hospital channels.
- Moisturizers:Ceramide-dominant barrier-repair matrices with biomimetic 3:1:1:1 lipid ratios. Tele-dermatology platforms validate subscription-based replenishment models in Canadian and Australian urban markets.
- Antihistamines:Topical H1-receptor antagonists for pruritus control in acute flares. Limited formulary inclusion constrains volume outside symptomatic relief protocols.
Moisturizers command the established base. Calcineurin inhibitors are gaining share fastest as steroid-sparing protocols displace corticosteroid maintenance regimens.
Age Group:
Customer type determines formulation safety thresholds, packaging design, clinical trial design, and channel access restrictions across the product lifecycle.
- Infants:Fragrance-free, preservative-minimized formulations with documented percutaneous absorption safety. China NMPA biocompatibility certification creates competitive moats for multinationals with established juvenile toxicology dossiers.
- Children:School-age protocols balancing efficacy with cosmetic acceptance. Parental purchasing through online retail channels accelerates as pediatric dermatology wait times extend beyond eight weeks in major Canadian metropolitan areas.
- Adults:Broadest indication range spanning occupational hand eczema to facial atopic dermatitis. Workplace accommodation and cosmetic compatibility drive formulation diversity.
- Elderly:Xerosis-focused maintenance with Medicare Part D and statutory insurance reimbursement alignment. Polypharmacy interaction screening influences prescribing patterns in German and Japanese geriatric protocols.
Adults command the established base. The steepest expansion trajectory runs through infants as regulatory barriers favor incumbents with documented safety portfolios.
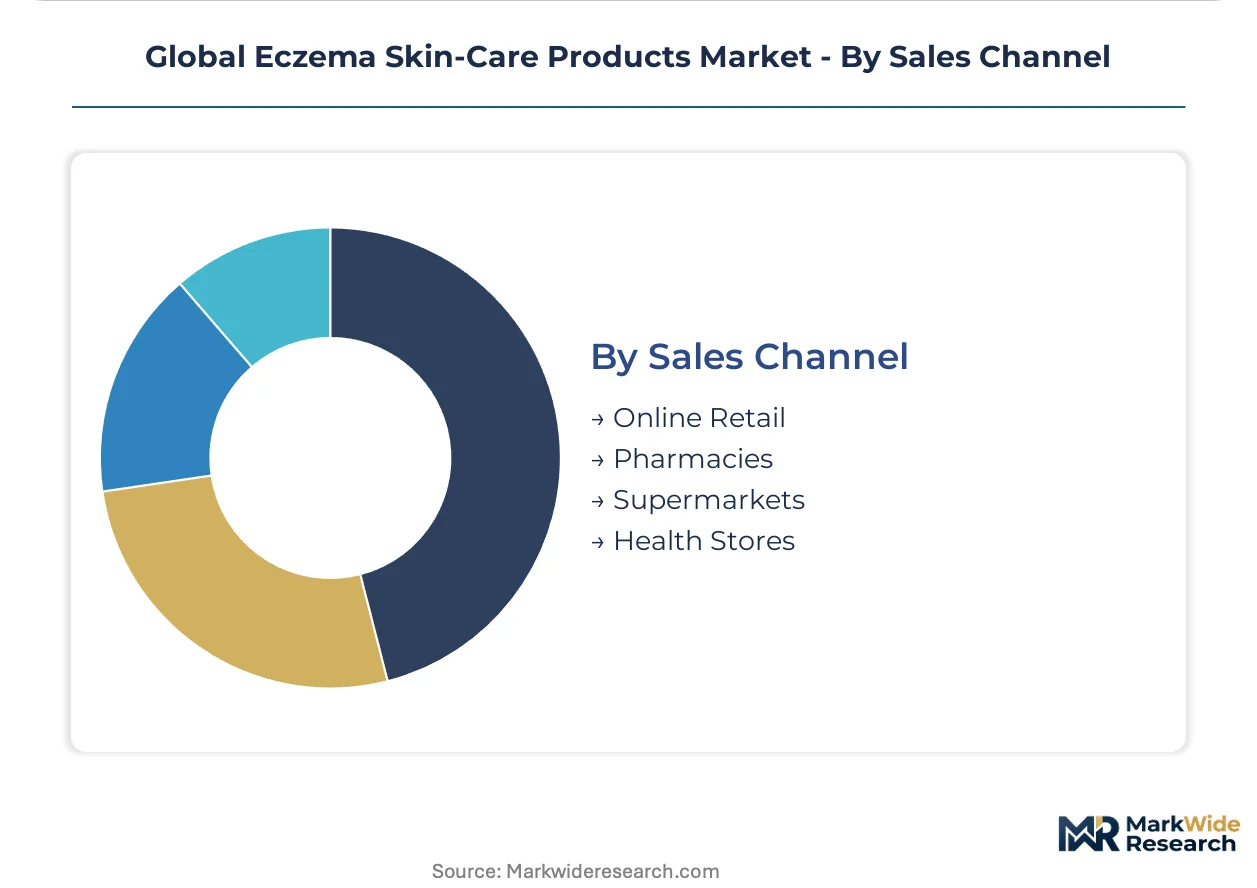
Sales Channel:
Volume concentration and margin capture diverge sharply between institutional procurement, retail pharmacy, and direct-to-consumer pathways with distinct logistics and validation requirements.
- Online Retail:Direct-to-patient platforms with integrated teledermatology consultation and subscription replenishment. Urban Australian markets demonstrate highest penetration as dermatologist access constraints normalize remote prescribing workflows.
- Pharmacies:Hybrid prescription and OTC dispensing with pharmacist counseling. Germany's pharmacy channel concentrates demand for premium barrier-repair positioning due to reimbursement integration and professional recommendation authority.
- Supermarkets:Mass-market emollient access for mild maintenance and preventive use. Price compression and private-label expansion characterize competitive dynamics.
- Health Stores:Natural-positioned and microbiome-friendly formulations targeting ingredient-conscious consumers. ECHA REACH fragrance allergen disclosure accelerates migration from conventional retail.
Pharmacies command the established base. Online retail is expanding most quickly as platform validation and reimbursement integration mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty lipid intermediate manufacturing clusters in Germany, South Korea, and India anchor upstream supply for ceramide precursors and calcineurin inhibitor APIs. Finished formulation capacity tilts toward North American and European sites serving dermatology clinic networks.
United States
Pediatric dermatology clinics in Boston and Philadelphia are expanding dedicated procurement protocols for steroid-sparing maintenance formulations. FDA OTC monograph reforms are compressing timelines for corticosteroid safety documentation in juvenile indications. North Carolina's Research Triangle hosts contract manufacturing organizations specializing in controlled-release ceramide delivery systems.
Germany
Pharmacy channel concentration in Munich and Hamburg drives premium positioning for barrier-repair products with reimbursement integration. ECHA REACH compliance mandates for fragrance allergen disclosure are accelerating reformulation toward microbiome-compatible excipients. Heidelberg's academic medical centers pilot biomimetic lipid nanostructures for post-flare maintenance protocols.
Japan
Hospital outpatient departments in Tokyo and Osaka are expanding reimbursement pathways for adult atopic dermatitis maintenance regimens. PMDA guidance on long-term topical safety documentation aligns with FDA and EMA convergence trends. Kobe's pharmaceutical manufacturing corridor specializes in high-purity ceramide production for clinical-grade emollients.
China
NMPA biocompatibility certification requirements for infant-directed topicals are creating competitive moats for multinationals with documented juvenile toxicology dossiers. Shanghai and Beijing concentrate demand through hospital-affiliated retail pharmacies. Guangdong Province's chemical synthesis clusters supply ceramide precursors to regional formulation facilities.
Australia
Tele-dermatology platforms in Sydney and Melbourne are normalizing remote prescribing workflows for prescription-strength emollients. TGA alignment with FDA OTC monograph reforms is tightening documentation requirements for corticosteroid-containing products. Melbourne's dermatology wait times exceeding eight weeks are accelerating subscription-based replenishment model adoption.
Global Eczema Skin-Care Products Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in lipid synthesis and controlled-release matrix engineering. The vendor base separates into mass-market consumer goods conglomerates, physician-dispensed dermatology specialists, and pharmacy-channel premium positioning firms. Three archetypes dominate: heritage European dermocosmetic houses, North American mass-market consumer health divisions, and clinical-dispensing prescription skincare laboratories. Capacity expansion and strategic portfolio diversification toward steroid-sparing actives represent the dominant competitive vectors.
Within the heritage dermocosmetic tier, Eucerin and La Roche-Posay exemplify prescription-credibility positioning sustained through European R&D heritage. Johnson & Johnson Consumer Inc. anchors mass-market distribution architecture spanning pharmacy and retail hybrid channels. Galderma Laboratories, L.P. occupies the physician-dispensed specialist position with premium shelf placement in clinical settings.
| Leading Market Players |
|---|
| Eucerin |
| Johnson & Johnson Consumer Inc. |
| Aveeno |
| Galderma Laboratories, L.P. |
| L'Oréal USA, Inc. |
| CeraVe |
| La Roche-Posay |
| Aquaphor |
| Cetaphil |
| Others |
Supply Flow & Price Mechanics
Rotterdam-Antwerp petrochemical corridor freight costs directly shape ceramide precursor pricing power, concentrating margin capture among German and South Korean manufacturers while forcing downstream price stratification between clinical-grade and mass-market emollient tiers.
Pricing Analysis
FDA OTC monograph reforms dictate the pricing tier structure across prescription-strength and consumer emollient segments. Three-tier pricing separates physician-dispensed calcineurin inhibitors from pharmacy-channel barrier-repair creams and supermarket private-label lotions. Certification-grade differentiation between EMA-compliant and grandfathered formulations widens price spreads. Pricing pressure stems from ECHA REACH reauthorization timelines that lock in preservative system costs. Mass-market supermarket buyers exhibit highest price sensitivity; German pharmacy channel purchasers demonstrate lowest elasticity due to reimbursement integration.
Supply Chain Analysis
Single-source API concentration between South Korea and India dominates supply risk exposure for tacrolimus and pimecrolimus actives. Specialty lipid intermediate manufacturing draws from German chemical clusters and Kobe pharmaceutical corridors. Squalane and ceramide precursor supply chains rest on petrochemical feedstock volatility. Distribution runs through North American dermatology clinic networks, European pharmacy chains, and Australian tele-dermatology platforms with integrated subscription fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tele-dermatology platform economics are collapsing the traditional pharmacy-channel intermediary layer, creating winner-take-most dynamics for emollient brands that achieve integrated prescription-to-fulfillment interoperability.
For Market Incumbents: Pre-empt subscription-model displacement by capturing pediatric dermatology clinic formulary lock-in before tele-dermatology platforms achieve critical mass. Secure backward integration into ceramide precursor supply through South Korean API manufacturing partnerships. Defend against private-label erosion by investing in juvenile toxicology dossiers that satisfy China NMPA certification barriers. For New Entrants and Emerging Players: Microbiome-friendly positioning in European health stores represents the most penetrable entry point, as ECHA REACH fragrance allergen disclosure accelerates consumer migration from legacy preservative systems. Japan's hospital outpatient reimbursement expansion for adult atopic dermatitis maintenance offers second-mover premium positioning. Direct-to-consumer launch with integrated skin barrier diagnostic devices provides differentiated patient acquisition economics. For Investors and Strategic Acquirers: Carve-out targets emerge from consumer health conglomerates divesting non-core dermatology assets lacking tele-dermatology platform integration. Five-to-ten year viability hinges on steroid-sparing active ingredient pipelines and regulatory dossier depth. Monitor FDA-EU-PMDA alignment on long-term corticosteroid safety documentation as the signal for accelerated prescription-to-OTC reclassification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Tele-Dermatology Platform Integration | Remote prescribing workflows in Australian and Canadian urban markets validate direct-to-patient distribution economics. |
| Juvenile Toxicology Dossier Investment | China NMPA biocompatibility certification creates competitive moats against private-label encroachment in infant-directed segments. |
| Ceramide Precursor Backward Integration | South Korean API manufacturing partnerships secure supply continuity amid petrochemical feedstock volatility. |
| Microbiome-Compatible Reformulation | ECHA REACH fragrance allergen mandates accelerate migration toward preservative-minimized excipient palettes. |
| Subscription-Based Replenishment Launch | Urban dermatology wait times exceeding eight weeks normalize automated chronic maintenance regimen fulfillment. |
Methodological Framework
The analysis maps corticosteroid, calcineurin inhibitor, and barrier-repair moisturizer sub-sectors, each validated through dermatology clinic procurement officers, pharmacy category managers, and tele-dermatology platform operators. Primary interviews with formulation chemists specializing in lipid matrix stabilization and regulatory affairs directors navigating FDA-EU dual dossier requirements anchor qualitative inputs. Secondary validation draws from FDA OTC monograph filings, EMA safety documentation submissions, ClinicalTrials.gov pediatric indication records, and pharmacy reimbursement databases. Bottom-up patient population modeling and top-down manufacturer revenue triangulation converge on segment-level estimates.
Forecast assumptions hold fixed the current regulatory convergence trajectory across FDA, EMA, and PMDA while varying tele-dermatology platform penetration rates and subscription-model adoption curves. The analytical framework projects volume and value across formulation texture, active mechanism, patient life stage, and purchase venue dimensions. CAGRs derive from longitudinal patient cohort persistence modeling and channel-shift elasticity parameters. Ceramide precursor input cost trajectories and calcineurin inhibitor API manufacturing capacity utilization serve as industry-specific forecast inputs throughout the projection horizon.
Practitioners should monitor regulator alignment on microbiome preservation claims and pediatric indication safety documentation requirements for early signals of competitive repositioning. Forecasts reflect assumptions about tele-dermatology reimbursement integration and ECHA REACH reauthorization timelines that could shift materially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Global Anti-Aging Market
Skincare
Skin Barrier Market
Skincare
Global Anti-Aging Products and Services Market
Skincare
Biocellulose Mask Market
Skincare
Global Skin Rejuvenation Market
Skincare
Rice Water Skincare Market
Skincare
Retinoids Market
Skincare
Skin Grafting System Market
Skincare
Africa Cosmeceutical Market
Skincare
Body Scrub Market
Skincare
Global Cosmetic Skin Care Market
Skincare
United Kingdom Skincare Market
Skincare
Skin Care Emulsion Market
Skincare
Facial Erythema Treatment Market
Skincare
Cosmeceuticals Market
Skincare
Incontinence Skin Care Products Market