
 Reusable Sanitary Pads Market | 2026-2036
Reusable Sanitary Pads Market Size, Share, and Industry Trends Forecast 2026-2036
Reusable Sanitary Pads Market Analytics
Multi-source fabric procurement is recalibrating cost structures across the reusable sanitary pads supply chain. Eco Femme leverages its South Indian cooperative network to sustain organic cotton traceability from farm to finished pad. AFRIpads anchors East African production with localized sewing collectives that control labor costs and community distribution channels.
Reusable sanitary pads consist of layered absorbent textiles—typically organic cotton, bamboo fiber, or hemp—enclosed in moisture-wicking outer shells with snap-fastened wings, designed for repeated washing and wear over 12-24 months of menstrual cycles. Organic cotton dominates current production volumes due to established certification infrastructure and consumer familiarity, though bamboo fiber represents the fastest-expanding material segment because of its natural antibacterial properties and lower irrigation requirements. Light flow and regular flow capacity tiers occupy the broadest consumer base, while super absorbent variants command premium positioning among postpartum mothers and health-conscious individuals seeking overnight protection.
The EU Green Deal and REACH chemical compliance frameworks govern material safety and biodegradability claims across European distribution channels, while India's BIS textile standards and PLI scheme incentives shape domestic manufacturing scale and export eligibility. The U.S. FDA regulates absorbent menstrual products as medical devices, creating compliance thresholds that filter market entrants and elevate quality benchmarks for interstate commerce. Stakeholders must monitor how evolving extended producer responsibility laws in France and Germany will mandate take-back programs and recyclability disclosures, fundamentally altering packaging and end-of-life obligations before the next regulatory cycle completes.
Market Dynamics
EU Green Deal extended producer responsibility mandates for textile waste are forcing supply chain reconfiguration across absorbent hygiene manufacturing, compelling producers to redesign packaging materials and establish take-back infrastructure before certification deadlines.
Growth Catalysts
- REACH chemical compliance:Stricter EU material safety standards filter out low-quality imports, elevating certified organic cotton producers who meet biodegradability benchmarks for European distribution channels.
- Bamboo fiber cultivation:Lower irrigation requirements and natural antibacterial properties accelerate farmer conversion from conventional cotton in water-stressed regions, expanding raw material availability.
- Germany:Municipal zero-waste programs subsidize sustainable menstrual products through direct consumer rebates and public procurement contracts for educational institutions.
Market Restraints
- Organic cotton price volatility:Climate-induced yield fluctuations in South Asian growing regions create input cost instability for manufacturers dependent on certified fiber supplies.
- FDA medical device classification:Absorbent menstrual product regulations in the United States impose testing and documentation burdens that filter smaller entrants from interstate commerce.
- Disposable pad incumbency:Established single-use product distribution through mass retail chains limits shelf space allocation for reusable alternatives in conventional channels.
Strategic Opportunities
- University campus networks:North American higher education sustainability offices represent underpenetrated direct procurement channels with concentrated decision-making authority.
- Postpartum care integration:Hospital discharge kit partnerships and midwife network distribution create clinical credibility pathways beyond traditional retail.
- India PLI scheme incentives:Domestic manufacturing scale subsidies reduce export eligibility barriers for textile producers meeting BIS certification standards.
Industry Challenges
- Absorbency certification timelines:ISO laboratory testing protocols for reusable pad performance claims require extended validation periods that delay product launches.
- Sewing collective skill standardization:Quality consistency across decentralized East African and South Asian production networks demands ongoing technical training investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reusable Sanitary Pads Market |
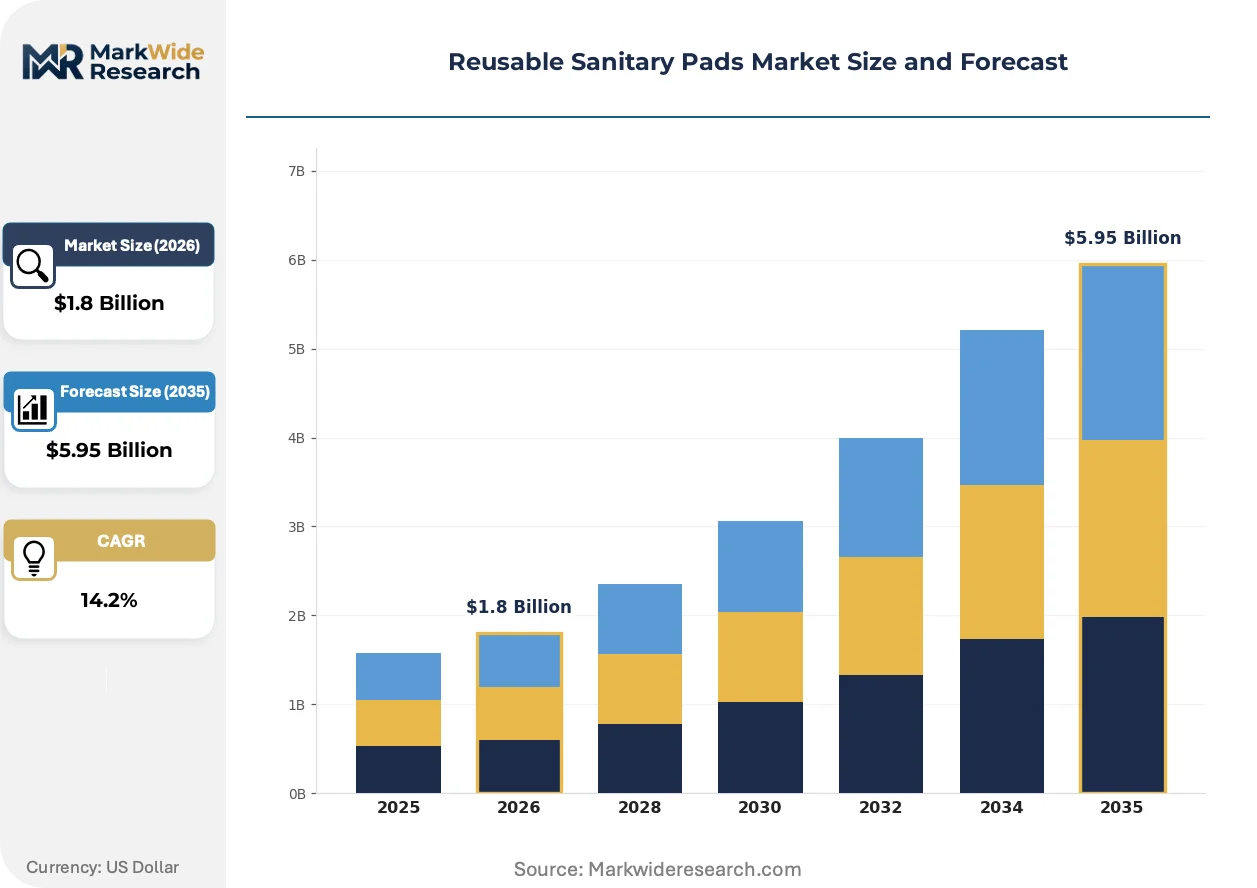
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Cotton, Bamboo Fiber, Hemp, Microfiber Capacity: Light Flow, Regular Flow, Heavy Flow, Super Absorbent Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales Customer Type: Eco-Conscious Consumers, Students, Mothers, Health-Conscious Individuals |
| Companies Covered | Rebelle, Fabpad, Eco Femme, Naari Cloth Pads, Rael, Thinx, Aisle, AFRIpads, Saathi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reusable Sanitary Pads Market Evolving Landscape
Digital traceability platforms and automated cutting systems are compressing production lead times while regulatory disclosure requirements reshape how manufacturers document material origins across multi-tier supply chains.
Ultrasonic bonding equipment is automating the assembly of moisture-wicking outer shells, eliminating stitched seam leakage points. University procurement offices and direct-to-consumer subscription services adopt this production standard fastest. The technology is automating quality consistency previously dependent on skilled manual labor, enabling scale without proportional workforce expansion.
France's implementation of extended producer responsibility for textiles mandates recyclability disclosures and take-back program infrastructure. Domestic distributors must now register with national waste management authorities and finance end-of-life collection systems. Light flow product lines face immediate reformulation pressure to meet mono-material recyclability targets ahead of heavier absorbent variants.
Campus sustainability officers now specify plastic-free packaging and carbon-neutral shipping in institutional procurement criteria. Student-led menstrual equity campaigns displace traditional distributor relationships with direct manufacturer contracts. This pattern concentrates most visibly in California and New York where public university systems maintain centralized sustainability procurement offices.
Reusable Sanitary Pads Market Segmentation
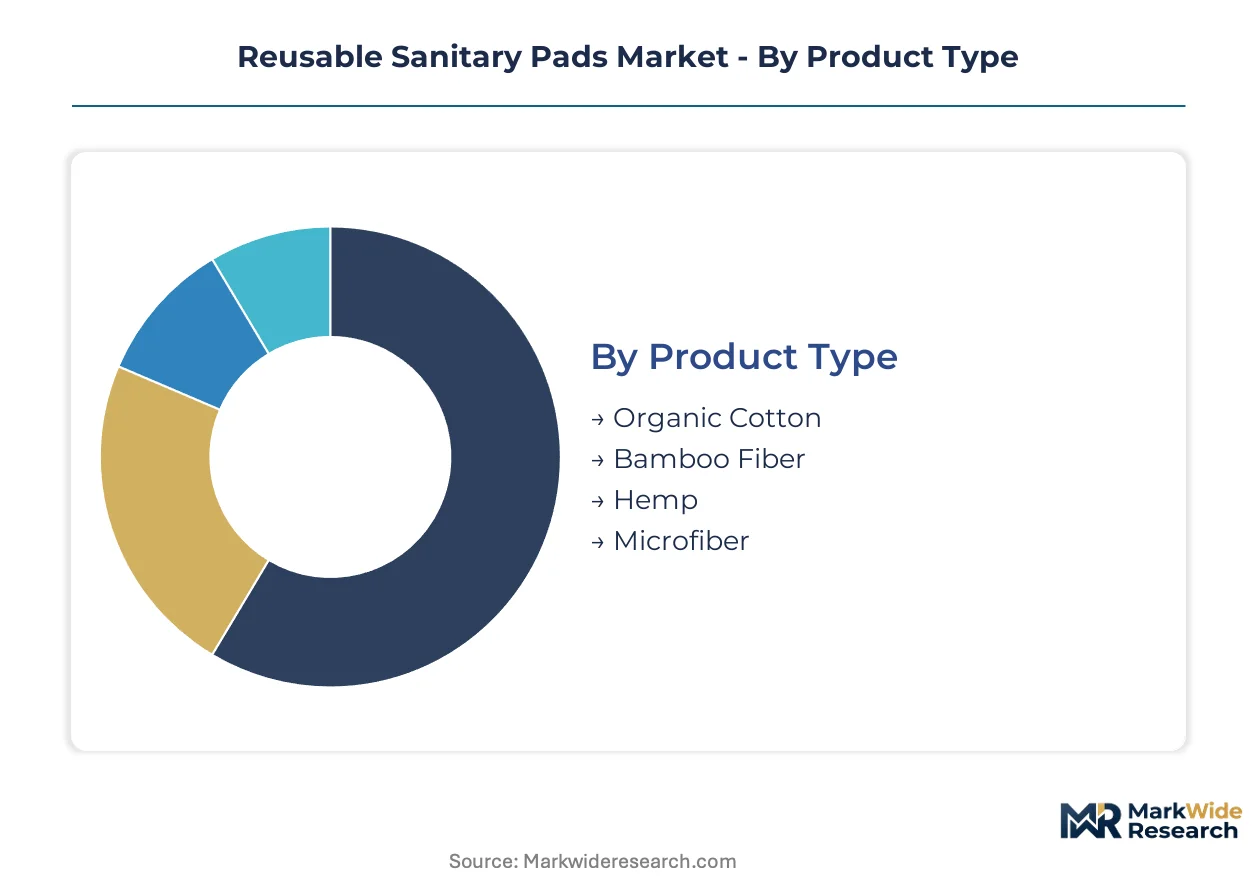
Material composition and absorbency specifications create distinct manufacturing requirements and certification pathways across the reusable sanitary pads supply chain. Distribution channel selection determines margin structures and customer education burdens, while buyer psychographics shape pricing tolerance and brand loyalty patterns.
Product Type:
Buyers differentiate primarily by fiber origin certification and irrigation footprint, with water-stressed sourcing regions commanding premium positioning.
- Organic Cotton:Certified fiber with established traceability infrastructure dominates current production volumes. Demand concentrates in Germany where municipal zero-waste programs subsidize certified sustainable menstrual products through direct consumer rebates.
- Bamboo Fiber:Natural antibacterial cellulose structure requires lower irrigation inputs than conventional cotton. Demand is accelerating fastest among health-conscious individuals in water-stressed growing regions seeking reduced agricultural footprint.
- Hemp:Durable bast fiber with high tensile strength enables extended 24-month product lifecycles. Niche positioning among eco-conscious consumers prioritizing longevity over initial softness.
- Microfiber:Synthetic absorbent layers deliver cost-competitive performance without organic certification overhead. Price-sensitive student segments in North American campus procurement programs drive adoption.
Volume sits with organic cotton; growth tilts toward bamboo fiber.
Capacity:
Absorbency tier selection correlates with usage occasion intensity and willingness to maintain separate product inventories.
- Light Flow:Slim profile designs with minimal bulk suit early-cycle days and spotting management. France's extended producer responsibility mandates immediate mono-material reformulation pressure on this tier to meet recyclability targets.
- Regular Flow:Standard multi-layer construction balances absorbency with wash-cycle durability. Broadest consumer base across eco-conscious consumers and students seeking single-product solutions.
- Heavy Flow:Reinforced core density with extended coverage zones. Postpartum mothers in hospital discharge kit partnerships drive clinical credibility adoption.
- Super Absorbent:Maximum retention engineering with overnight leak protection specifications. Premium positioning among health-conscious individuals seeking extended wear confidence.
Regular flow captures the installed base; super absorbent commands the steepest expansion trajectory among clinical channel partnerships.
Distribution Channel:
Channel choice determines packaging compliance burdens and end-of-life collection infrastructure obligations under EU Green Deal provisions.
- Online Retail:Direct-to-consumer subscription models enable plastic-free packaging and carbon-neutral shipping specifications. Campus sustainability officers in California and New York specify these criteria in institutional procurement.
- Supermarkets:Mass retail shelf space allocation limits reusable alternatives against disposable pad incumbency. Established distribution networks filter smaller entrants lacking FDA medical device documentation.
- Health Stores:Specialty retail channels prioritize certified organic and REACH-compliant product lines. Germany's municipal programs leverage these outlets for subsidy redemption infrastructure.
- Direct Sales:Community-based distribution through sewing collectives controls labor costs in East African and South Asian production networks. Localized quality consistency demands ongoing technical training investment.
Supermarkets move the volume base; direct sales channels are gaining share fastest in decentralized production regions.
Customer Type:
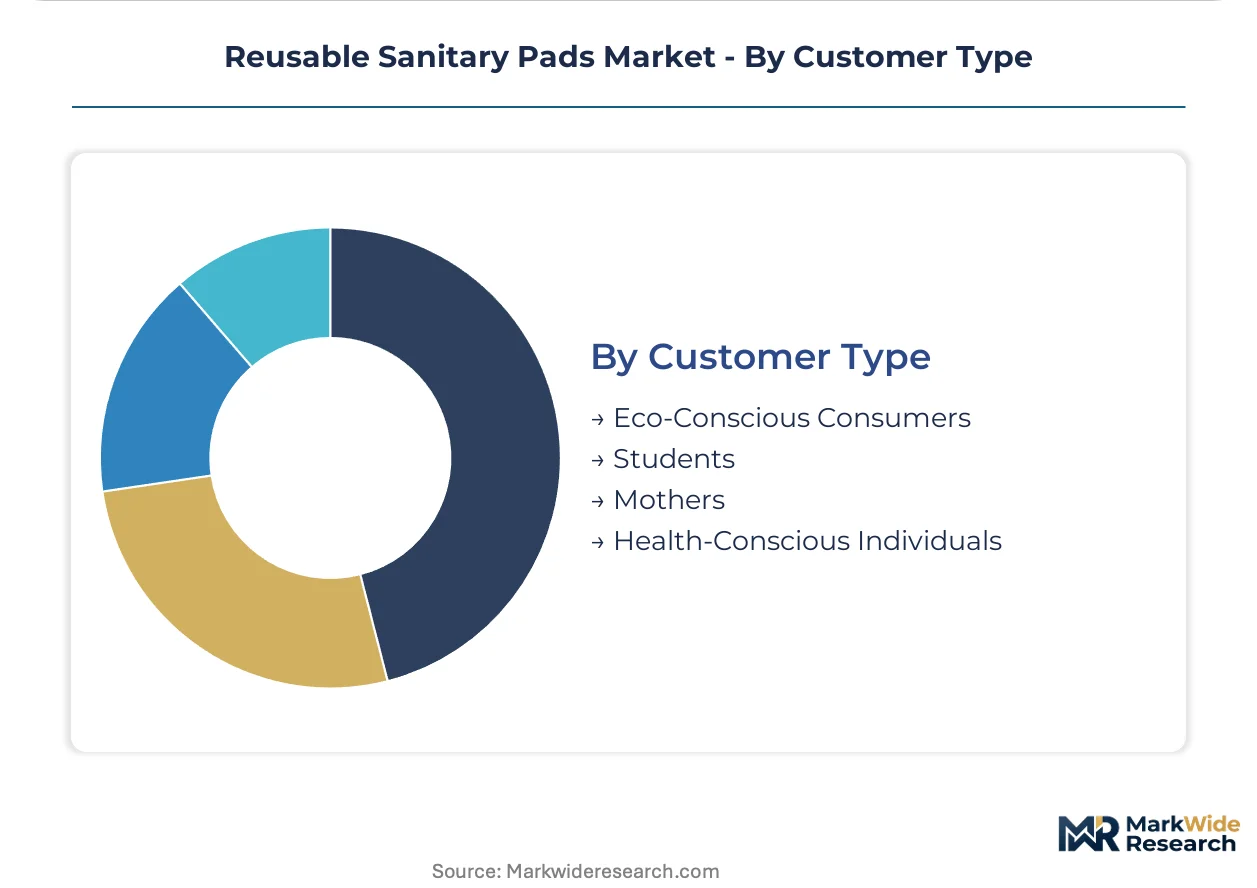
Psychographic segmentation separates buyers by environmental commitment intensity and life-stage specific absorbency requirements.
- Eco-Conscious Consumers:Certification-driven purchasing prioritizes organic cotton traceability and biodegradability claims. EU Green Deal extended producer responsibility compliance shapes product selection criteria.
- Students:North American university sustainability offices represent concentrated decision-making authority with centralized procurement budgets. Student-led menstrual equity campaigns displace traditional distributor relationships.
- Mothers:Postpartum recovery needs drive super absorbent tier adoption through midwife network distribution. Hospital discharge kit partnerships create clinical credibility pathways.
- Health-Conscious Individuals:Antibacterial fiber preferences and overnight protection specifications command premium positioning. Bamboo fiber's natural properties align with this segment's material safety priorities.
Eco-conscious consumers anchor current volume; students are climbing the fastest as campus procurement programs scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates the most intense policy-driven demand through municipal zero-waste subsidy programs. Campus procurement networks in California and New York are displacing traditional distribution channels fastest.
Germany
Municipal zero-waste programs in Berlin, Hamburg, and Munich subsidize certified sustainable menstrual products through direct consumer rebates. The EU Green Deal's extended producer responsibility mandates force domestic distributors to register waste management authorities and finance take-back infrastructure. Production clusters in North Rhine-Westphalia and Bavaria process organic cotton traceability documentation for REACH-compliant export batches.
United States
Student-led menstrual equity campaigns at University of California and State University of New York systems drive direct manufacturer contracts bypassing traditional distributors. FDA medical device classification for absorbent menstrual products filters smaller entrants from interstate commerce. California's centralized sustainability procurement offices specify plastic-free packaging and carbon-neutral shipping in institutional tenders.
India
Domestic manufacturing scale accelerates through PLI scheme incentives for textile producers meeting BIS certification standards. South Indian cooperative networks in Tamil Nadu sustain organic cotton farm-to-finished-pad traceability for European export eligibility. Karnataka's garment manufacturing corridors absorb ultrasonic bonding equipment for moisture-wicking shell automation.
France
Extended producer responsibility implementation mandates recyclability disclosures and take-back program infrastructure for textile distributors. Light flow product lines face immediate mono-material reformulation pressure ahead of heavier absorbent variants. Paris-based specialty retail channels prioritize REACH-compliant certified organic product lines for subsidy redemption infrastructure.
Uganda
East African production anchors through localized sewing collectives controlling labor costs and community distribution channels. Decentralized quality consistency demands ongoing technical training investment across Kampala-area manufacturing networks. AFRIpads exemplifies the community-based distribution archetype linking rural production to regional procurement programs.
Reusable Sanitary Pads Market Competitive Landscape
Strategic partnerships dominate the current landscape as producers secure multi-source fabric procurement and campus direct sales channels. The vendor base fragments across cooperative-based South Asian networks, East African sewing collectives, and North American direct-to-consumer specialists. Three archetypes prevail: organic cotton traceability specialists, bamboo fiber antibacterial innovators, and campus procurement direct sellers. Technology licensing for ultrasonic bonding equipment and backward integration into cooperative cotton networks constitute the dominant competitive moves.
Among cooperative-anchored producers, Eco Femme and AFRIpads exemplify the community-based manufacturing archetype linking farm-level traceability to finished goods. Rebelle occupies a position within the European regulatory compliance tier, navigating France's extended producer responsibility mandates and Germany's municipal subsidy infrastructure. These three entities represent distinct geographic and operational models rather than direct competitors, with each anchoring a regional supply configuration shaped by local certification requirements and distribution channel access.
| Leading Market Players |
|---|
| Rebelle |
| Fabpad |
| Eco Femme |
| Naari Cloth Pads |
| Rael |
| Thinx |
| Aisle |
| AFRIpads |
| Saathi |
| Others |
Value Network & Pricing Analysis
Campus sustainability procurement offices mandating plastic-free packaging and carbon-neutral shipping specifications force manufacturers to absorb premium logistics costs or forfeit institutional contracts, compressing margins on student-tier product lines while elevating certified organic cotton tiers through subsidy eligibility.
Pricing Analysis
Volume concentrates in regular flow organic cotton tiers where municipal zero-waste rebates offset consumer price sensitivity, while super absorbent variants capture margin premiums through postpartum clinical channel partnerships. Price differentiation rests on REACH certification grade and ultrasonic bonding automation level, with Germany's subsidy infrastructure amplifying certified product price elasticity. Cost compression in student-facing microfiber lines intensifies because campus procurement consolidation favors volume discounts. Students exhibit highest price sensitivity; health-conscious individuals seeking bamboo fiber antibacterial properties demonstrate lowest.
Supply Chain Analysis
Workforce availability constraints in Tamil Nadu's cooperative networks and Kampala-area sewing collectives limit production scaling despite ultrasonic bonding automation adoption in Karnataka's garment corridors. Geographic supply concentration centers on India, Uganda, and Germany's North Rhine-Westphalia processing clusters. Raw material dependencies draw from South Asian organic cotton farms, East African bamboo fiber cultivation expansion, and hemp bast fiber imports. Single-source vulnerability permeates certified organic cotton traceability documentation. Distribution runs through direct-to-consumer subscription platforms and health store subsidy redemption infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into cooperative cotton networks and campus direct sales channel capture constitutes the dominant competitive race, with subsidy eligibility and traceability certification as the decisive upstream levers.
For Market Incumbents: Deploy ultrasonic bonding equipment licensing to automate quality consistency across decentralized production networks. Secure exclusive procurement contracts with University of California and State University of New York sustainability offices before competitor saturation. Deepen backward integration into South Indian cooperative cotton networks to insulate against organic fiber price volatility and REACH compliance documentation bottlenecks. For New Entrants and Emerging Players: Campus sustainability officers represent the most penetrable channel archetype, with centralized procurement budgets and student-led menstrual equity campaigns displacing traditional distributor relationships. Target postpartum hospital discharge kit partnerships to establish clinical credibility pathways beyond saturated retail shelf space. Pursue direct manufacturer contracts with North American higher education systems specifying plastic-free packaging compliance. For Investors and Strategic Acquirers: The window for entry favors cooperative-anchored producers with established farm-to-finished-pad traceability infrastructure and EU Green Deal extended producer responsibility compliance documentation. Long-term viability hinges on subsidy program dependency durability and certification barrier sustainability. Monitor France's mono-material recyclability mandate implementation timeline as inflection indicator for light flow tier reformulation investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cooperative Networks | Eco Femme's South Indian farm partnerships secure organic cotton traceability for REACH-compliant European export batches. |
| Campus Direct Procurement Channel Capture | California and New York public university sustainability offices specify plastic-free packaging in institutional tenders. |
| Ultrasonic Bonding Equipment Deployment | Karnataka's garment manufacturing corridors automate moisture-wicking shell assembly, eliminating stitched seam leakage points. |
| Postpartum Clinical Channel Partnership | Hospital discharge kit integration creates credibility pathways for super absorbent tier premium positioning. |
| Extended Producer Responsibility Compliance | Germany's municipal zero-waste programs require waste management authority registration and take-back infrastructure financing. |
Research Methodology
Multi-period observation of municipal subsidy program enrollment rates, campus procurement contract awards, and REACH certification application volumes anchored the trend analysis, supplemented by interviews with cooperative network managers, campus sustainability officers, and health store category buyers. Secondary validation drew from EU Green Deal implementation timelines, BIS textile standard filings, FDA medical device classification guidance, and organic cotton trade flow customs data. Bottom-up production capacity assessments across Tamil Nadu, Kampala, and North Rhine-Westphalia clusters triangulated against top-down demand modeling.
Input-output matrices mapped fiber origin certification, absorbency tier specifications, and distribution channel compliance burdens across the analysis window. Segmentation dimensions modeled include material composition, capacity tier, customer psychographic archetype, and regional regulatory cluster. CAGRs derived from production volume trajectories, subsidy program budget allocations, and campus procurement pipeline conversion rates. Industry-specific forecast inputs incorporated ultrasonic bonding equipment installation counts and extended producer responsibility registration deadlines.
Caveats apply where EU Green Deal extended producer responsibility implementation delays, organic cotton climate-induced yield collapses, or campus procurement budget freezes could materially shift the outlook. Forecasts reflect documented assumptions on subsidy program continuity and certification infrastructure scalability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Safety Products
Baby Gate Market
Baby Safety Products
Forward Facing Type Child Safety Seats Market
Baby Safety Products
Global Baby Cleaning Products Market
Baby Safety Products
Baby Safety Products Market
Baby Safety Products
Baby Safety Seats Market
Baby Safety Products
Biodegradable Sanitary Napkins Market
Baby Safety Products
BRICS Disposable Hygiene Products Market
Baby Safety Products
Booster Car Seats Market
Baby Safety Products
Organic Sanitary Napkin Market
Baby Safety Products
Japan Adult Diaper Market
Baby Safety Products
North America Adult Diaper Market
Baby Safety Products
Panty Liner Market
Baby Safety Products
India Pant Type Adult Diaper Market
Baby Safety Products
Reusable/Washable Hygiene Products Market
Baby Safety Products
Global Feminine Protection Market
Baby Safety Products
United States Away from Home Tissue and Hygiene Market