
 United States Printing Inks Market | 2026-2036
United States Printing Inks Market Size, Share, and Industry Trends Forecast 2026-2036
United States Printing Inks Market Analytics
ASTM D6807 qualification for low-VOC gravure and flexographic inks is rotating the competitive field toward suppliers with certified in-house analytical laboratories. Sun Chemical sustains broad formulation libraries across solvent, water, and UV platforms. Flint Group anchors North American manufacturing through integrated pigment and resin operations. INX International Ink Co. specializes in narrow-web UV inks for pressure-sensitive label converters.
Printing inks comprise pigmented or dyed fluid systems formulated with binders, solvents or water carriers, and additives, designed for transfer onto substrates via mechanical or digital impression at controlled viscosity and cure response. Their primary purpose is to deliver durable, color-accurate, and regulatory-compliant graphics for commercial, industrial, and consumer-facing printed materials. Water-based inks hold mature volume leadership in corrugated packaging where absorption into uncoated stock eliminates energy-intensive drying. UV-curable inks represent the fastest-expanding margin pool in narrow-web labels and folding cartons where instant polymerization supports high-speed digital presses. Solvent-based formulations retain structural share in flexible film lamination where adhesion to polyolefin substrates demands aggressive surface energy modification.
EPA NESHAP standards for printing operations constrain VOC emissions and mandate capture or reformulation strategies across gravure and flexographic facilities. FDA indirect food additive regulations under 21 CFR 175.105 govern adhesive and coating components in food-contact packaging applications, directly influencing ink migration testing protocols and compliant raw material selection. OSHA permissible exposure limits for toluene and xylene in printing plant air shape worker safety investments and accelerate aqueous system transitions. Stakeholders must monitor state-level extended producer responsibility proposals in California and New York that could impose packaging material recovery obligations upstream to ink and coating suppliers.
Market Dynamics
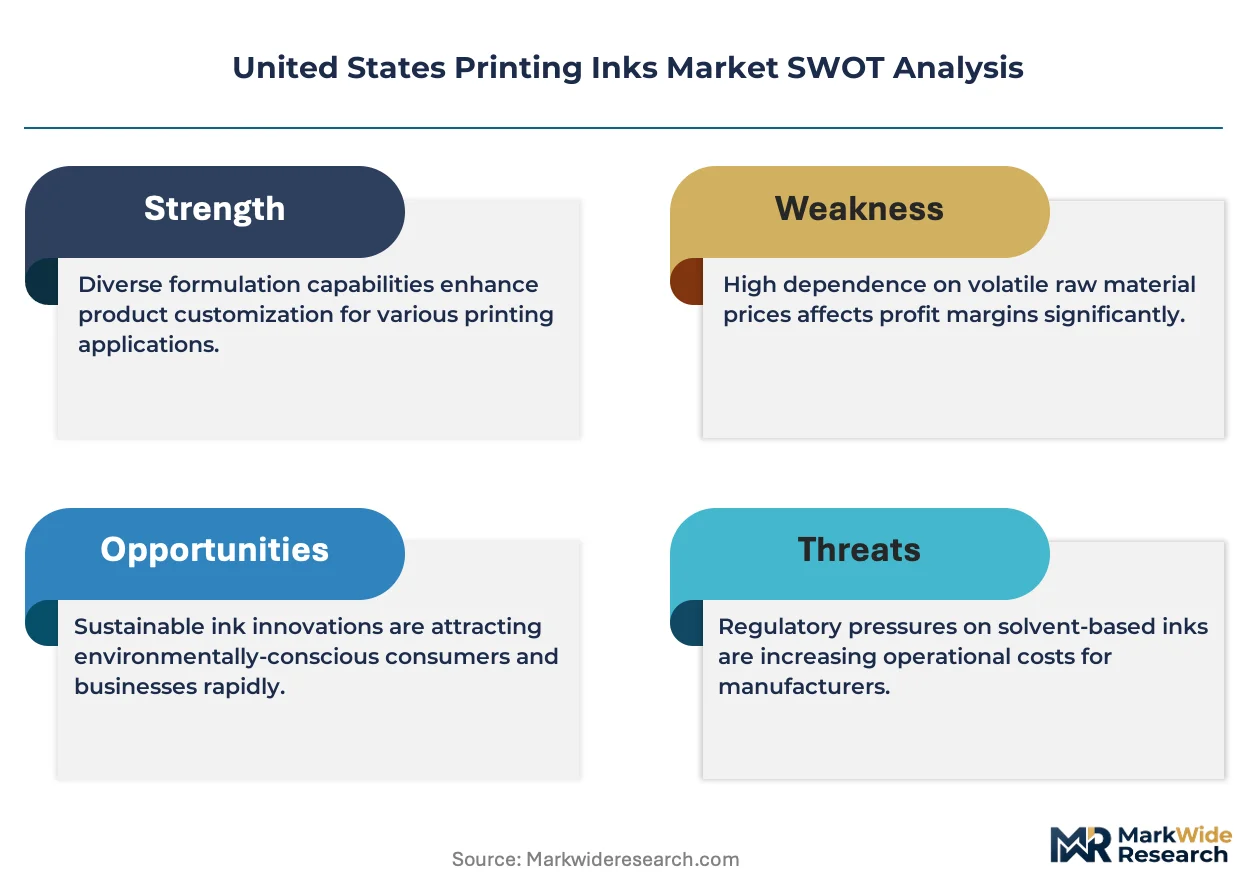
EPA NESHAP standards for hazardous air pollutants are compressing the competitive set toward suppliers with capital-intensive reformulation capabilities and certified analytical infrastructure. This regulatory tightening is forcing solvent-based gravure operations toward water-based or UV-curable alternatives while reshaping capital allocation across the Midwestern packaging corridor.
Growth Catalysts
- Low-migration ink protocols:FDA 21 CFR 175.105 compliance requirements for food-contact packaging are pulling flexible packaging converters toward certified ink systems with documented migration profiles.
- UV-curable formulation advances:Instant polymerization chemistry is displacing thermal drying in narrow-web label operations, cutting energy costs and enabling higher press speeds for pressure-sensitive converters.
- Great Lakes industrial clustering:Concentrated label and corrugated packaging infrastructure around Chicago, Milwaukee, and Detroit creates dense supplier-buyer networks with reduced logistics friction.
Market Restraints
- Pigment and resin input volatility:Petrochemical feedstock fluctuations compress margin predictability for solvent-based formulation specialists without backward integration into raw material production.
- Capital intensity of compliance infrastructure:In-house gas chromatography and mass spectrometry laboratories required for ASTM D6807 certification demand seven-figure investments that filter smaller compounders from qualified supplier pools.
- Technical adhesion limitations:Water-based systems struggle with surface energy modification on untreated polyolefin films, preserving structural demand for solvent-based lamination inks in high-barrier flexible packaging.
Strategic Opportunities
- California extended producer responsibility frameworks:Pending state-level packaging recovery mandates could create first-mover advantages for ink suppliers with recyclable and deinkable formulation portfolios.
- Digital press convergence with UV chemistry:Hybrid inkjet systems combining aqueous and UV-curable deposition modes are opening specification windows for converters serving short-run personalized packaging.
- Biobindertech integration:Soy and algae-derived resin platforms are penetrating corrugated and publication segments where renewable content certifications command procurement preference.
Industry Challenges
- Colorimetric technician scarcity:Specialized expertise in delta-E color matching and spectrophotometric quality control is concentrating among aging workforces in legacy printing regions.
- Legacy press retrofit complexity:Converting solvent-based gravure lines to electron beam or UV curing demands mechanical reengineering of impression cylinders and drying tunnels that extends downtime beyond seasonal maintenance windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Printing Inks Market |
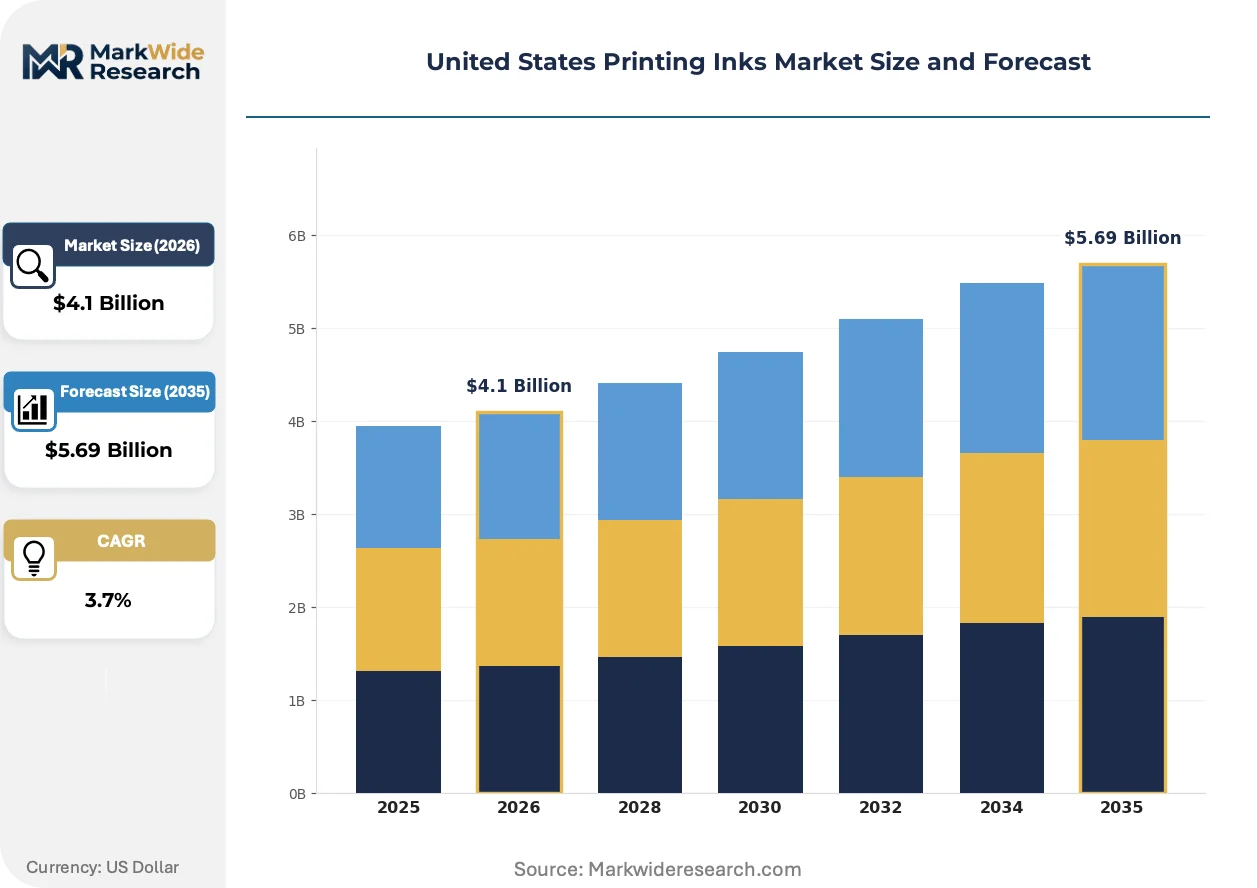
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $5.69 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent-based Inks, Water-based Inks, UV-curable Inks, Oil-based Inks Application: Packaging, Commercial Printing, Publication, Decorative Printing End User: Consumer Goods, Publishing Houses, Advertising Agencies, Textile Industry Technology: Digital Printing, Flexographic Printing, Gravure Printing, Lithographic Printing |
| Companies Covered | Sun Chemical, Flint Group, Siegwerk Druckfarben AG & Co. KGaA, DIC Corporation, hubergroup, INX International Ink Co., Sakata INX Corporation, ALTANA AG, Wikoff Color Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Printing Inks Market Evolving Landscape
Formulation chemistry and regulatory compliance infrastructure are diverging competitive capability tiers faster than hardware innovation cycles. Suppliers now compete on analytical certification depth and raw material traceability systems rather than pigment dispersion alone.
LED-UV curable inks with narrow-wavelength photoinitiator packages are displacing conventional mercury-arc UV systems in folding carton and commercial sheetfed operations. Midwestern folding carton converters serving pharmaceutical blister packs are adopting these systems to eliminate ozone generation and reduce energy draw. The structural consequence is compressing the installed base of thermal oxidizer-dependent solvent recovery systems in favor of simplified exhaust infrastructure.
EPA NESHAP Subpart KK standards for printing and publishing facilities are tightening volatile organic compound emission limits and mandating capture efficiency demonstrations. Gravure publication and packaging plants in Wisconsin and Ohio are investing in regenerative thermal oxidizers or reformulating to water-based alternatives. The corrugated segment is responding fastest due to substrate absorbency that accommodates aqueous vehicle penetration without auxiliary drying energy.
Brand-owner sustainability scorecards are unbundling ink procurement from historical converter-specified supply arrangements. Food and beverage multinationals headquartered in Chicago and Minneapolis are issuing approved substance lists that bypass traditional converter intermediaries. This pattern concentrates most visibly in organic and natural product categories where clean-label packaging claims require documented ink composition transparency.
United States Printing Inks Market Segmentation
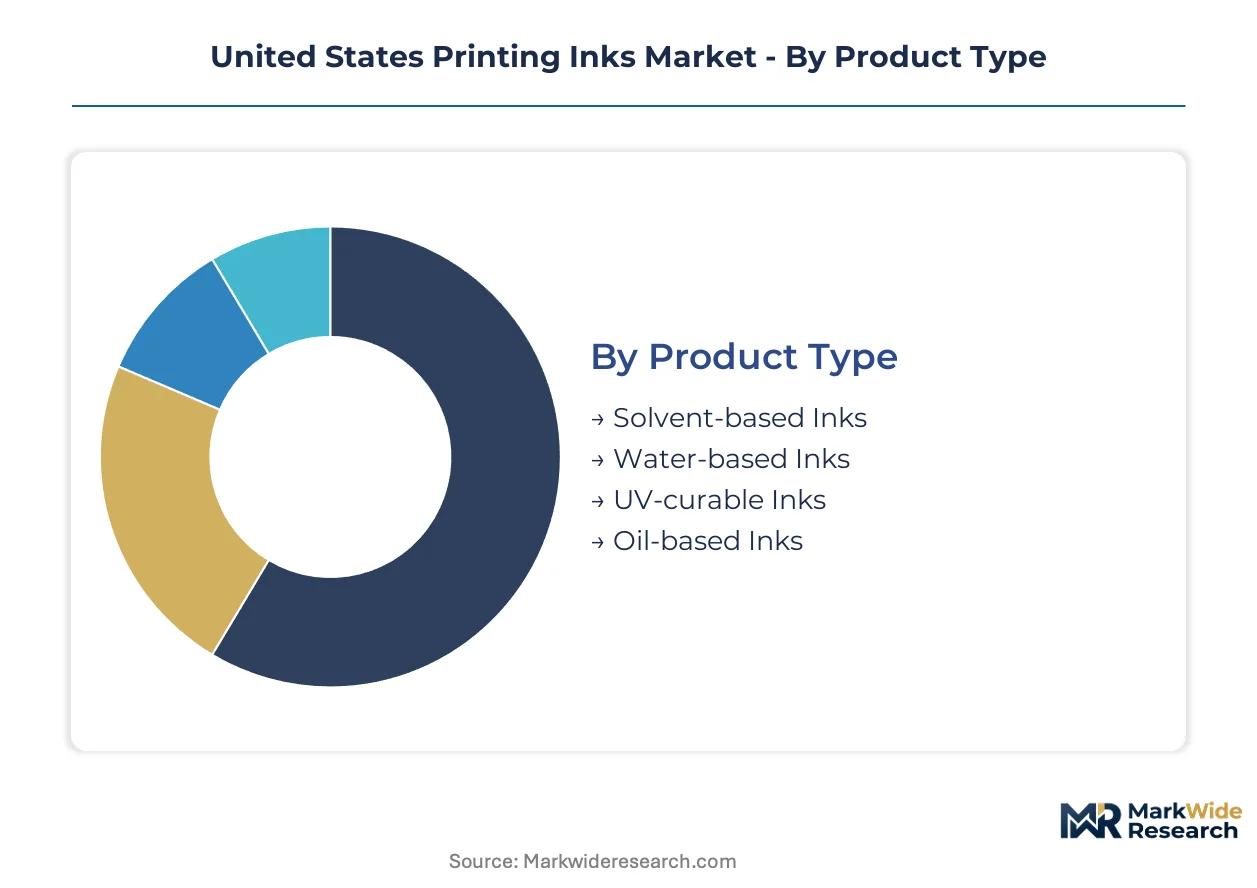
Printing ink procurement in the United States fragments across formulation chemistry, substrate compatibility, and regulatory compliance tiers. Channel flows differ sharply: corrugated packaging converters buy water-based systems through distributor networks, while narrow-web label specialists source UV-curable formulations direct from certified manufacturers with in-house analytical laboratories.
Product Type:
Water-based and UV-curable formulations dominate direct procurement channels serving food-contact packaging, while solvent-based systems flow through specialized distributors to flexible film laminators. Oil-based inks retain niche distribution through publication supply houses serving legacy newspaper operations.
- Water-based Inks:Aqueous pigment dispersions using acrylic or styrene-acrylic binders penetrate uncoated corrugated stock without auxiliary drying energy. Demand concentrates in Midwestern packaging clusters around Chicago and Milwaukee where brown-box converters serve e-commerce fulfillment networks and face tightening EPA NESHAP compliance deadlines.
- UV-curable Inks:Photoinitiator-activated oligomer systems polymerize instantly under mercury-arc or LED-UV lamps, eliminating thermal oxidation. Pressure-sensitive label converters in Ohio and Wisconsin are adopting these systems to support high-speed digital presses and reduce energy draw in folding carton operations.
- Solvent-based Inks:Toluene and ester-based vehicles with aggressive surface energy modification for untreated polyolefin films.
- Oil-based Inks:Mineral oil or vegetable oil carriers retaining structural share in heatset web offset publication printing.
By volume, water-based formulations lead. By growth pace, UV-curable systems are climbing the fastest.
Application:
Cost tier differentiation separates commodity corrugated from premium pharmaceutical blister packs, with compliance infrastructure investments scaling accordingly. Packaging applications command premium pricing for FDA 21 CFR 175.105 migration documentation, while commercial printing competes on unit economics.
- Packaging:Flexible film, folding carton, and corrugated applications requiring food-contact compliance, barrier properties, and shelf-impact graphics. Flexible packaging converters in the Great Lakes corridor are expanding orders for low-migration ink systems as FDA indirect food additive regulations tighten testing protocols.
- Commercial Printing:Direct mail, promotional materials, and general commercial sheetfed work.
- Publication:Heatset web offset for magazines, catalogs, and newspaper inserts.
- Decorative Printing:Wallcovering, laminates, and specialty decorative substrates.
Packaging commands the largest revenue pool. Digital convergence with personalized short runs is gaining share fastest in commercial applications.
End User:
Customer type determines specification authority: consumer goods brand owners increasingly bypass converters to mandate approved substance lists, while publishing houses retain traditional procurement patterns. The advertising segment shows highest price sensitivity with project-based purchasing.
- Consumer Goods:Food and beverage, personal care, and household product manufacturers requiring clean-label packaging claims and documented ink composition transparency. Brand owners headquartered in Minneapolis and Chicago are issuing approved substance lists that bypass traditional converter intermediaries.
- Publishing Houses:Magazine, catalog, and book publishers with legacy heatset web offset infrastructure.
- Advertising Agencies:Promotional and point-of-sale material procurement with short-run, quick-turn requirements.
- Textile Industry:Fabric printing applications with distinct viscosity and fixation requirements.
Consumer goods drives premium formulation demand. Advertising agencies represent the most price-elastic procurement segment.
Technology:
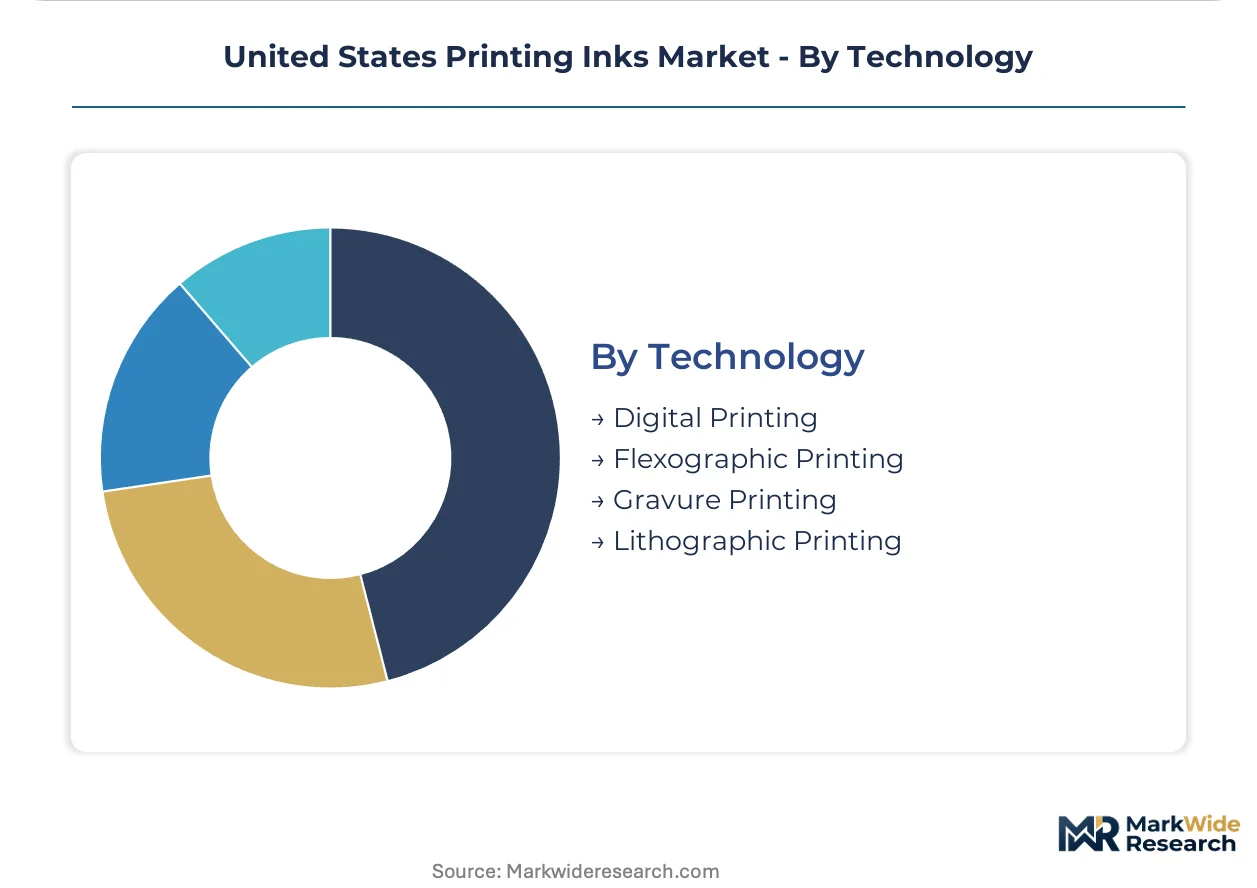
Maturity curves separate established analog processes from digital growth trajectories, with capital intensity and colorimetric expertise requirements shaping competitive entry barriers. Flexographic and gravure installations concentrate in legacy Midwestern industrial corridors.
- Flexographic Printing:Rotary relief printing with elastomer or photopolymer plates, dominant in corrugated and flexible packaging. Water-based and UV-flexo formulations are displacing solvent systems in Wisconsin and Ohio facilities responding to EPA NESHAP Subpart KK emission limits.
- Digital Printing:Inkjet and electrophotographic systems enabling variable data and short-run personalization. Hybrid aqueous-UV inkjet configurations are opening specification windows for converters serving personalized packaging in pharmaceutical and organic product categories.
- Gravure Printing:Intaglio cylinder process retaining share in high-volume flexible film lamination.
- Lithographic Printing:Offset planographic process dominant in commercial sheetfed and publication work.
Flexographic holds the largest installed base. Digital printing is expanding most quickly in narrow-web label and personalized packaging segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA NESHAP Subpart KK emission standards are compressing solvent-based operations across the Great Lakes industrial corridor while state-level extended producer responsibility frameworks in California and New York reshape procurement patterns for food-contact packaging applications.
Great Lakes Industrial Corridor
Flexible packaging converters in Wisconsin and Ohio are expanding orders for low-migration ink systems as FDA 21 CFR 175.105 compliance requirements tighten migration testing protocols. EPA NESHAP standards mandate regenerative thermal oxidizer investments or reformulation to water-based alternatives. Milwaukee and Detroit packaging clusters serve Midwestern consumer goods distribution networks with dense supplier-buyer logistics.
California
Pending extended producer responsibility proposals impose packaging material recovery obligations upstream to ink and coating suppliers. The state's air quality management districts enforce VOC limits stricter than federal baselines. Los Angeles and Bay Area converters are piloting recyclable and deinkable formulation portfolios for organic and natural product categories requiring clean-label packaging claims.
New York Metro
State-level packaging recovery mandates are creating first-mover advantages for suppliers with documented ink composition transparency. Brand owners headquartered in Manhattan and Connecticut are issuing approved substance lists that bypass traditional converter intermediaries. Narrow-web label specialists in northern New Jersey adopt UV-curable systems to support high-speed digital presses.
Southeast
Corrugated packaging demand concentrates around Atlanta and Charlotte e-commerce fulfillment networks where water-based systems dominate due to substrate absorbency. Georgia and North Carolina environmental agencies align with EPA NESHAP compliance timelines. Regional converters face capital intensity pressures for ASTM D6807 certification infrastructure.
Pacific Northwest
Seattle and Portland metropolitan areas host specialty label converters serving pharmaceutical and organic product segments with hybrid aqueous-UV inkjet configurations. Washington and Oregon state environmental regulations mirror California's VOC stringency. Regional demand favors renewable content certifications in soy and algae-derived resin platforms.
United States Printing Inks Market Competitive Landscape
Player mix skews toward integrated multinational chemical conglomerates with captive pigment and resin operations. Tiered competitive structure separates formulation specialists with certified analytical laboratories from regional compounders lacking ASTM D6807 qualification. Three archetypes dominate: backward-integrated pigment producers, UV-chemistry specialists with narrow-web focus, and water-based formulation leaders in corrugated applications. Competitive moves concentrate on portfolio diversification across solvent, water, and UV platforms alongside strategic partnerships for biobinder technology access.
Within the integrated multinational tier, Sun Chemical, Flint Group, and INX International Ink Co. exemplify contrasting strategic positions. Sun Chemical occupies the broad-formulation archetype spanning all chemistry platforms. Flint Group anchors North American manufacturing through integrated pigment and resin operations. INX International Ink Co. represents the UV-specialist vector with narrow-web concentration for pressure-sensitive label converters.
| Leading Market Players |
|---|
| Sun Chemical |
| Flint Group |
| Siegwerk Druckfarben AG & Co. KGaA |
| DIC Corporation |
| hubergroup |
| INX International Ink Co. |
| Sakata INX Corporation |
| ALTANA AG |
| Wikoff Color Corporation |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between corrugated packaging converters and water-based ink suppliers lock in pigment supply access and flatten price volatility across EPA NESHAP compliance cycles. These arrangements concentrate procurement leverage among Great Lakes converters with multi-year volume commitments.
Pricing Analysis
Certification level creates the primary spread between ASTM D6807-qualified formulations and uncertified compounder products. Three-tier pricing structure across premium certified, standard compliant, and economy non-food-contact levels governs the market. Cost compression in solvent-based gravure tiers is intensifying because regenerative thermal oxidizer investments pass through to converter pricing. Advertising agencies show highest price sensitivity with project-based spot purchasing, while pharmaceutical blister pack converters accept premium pricing for FDA 21 CFR 175.105 migration documentation.
Supply Chain Analysis
Strategic stockpiling of photoinitiators and specialty oligomers dominates UV-curable formulation procurement, contrasting with just-in-time pigment ordering in water-based corrugated operations. China, Germany, and India anchor global supply for organic pigments, photoinitiators, and acrylic resins respectively. Raw material dependencies center on petrochemical feedstocks, titanium dioxide, and nitrocellulose carriers. Single-source vulnerability in photoinitiator supply creates concentration risk for narrow-web label converters. Distribution runs through authorized distributor networks for corrugated volume accounts and direct manufacturer relationships for certified narrow-web specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA NESHAP Subpart KK emission tightening and LED-UV chemistry maturation together create a high-growth disruption window, compressing legacy solvent-based operations while rewarding reformulation-capable suppliers.
For Market Incumbents: Compound analytical certification depth to defend against ASTM D6807-qualified entrants. Expand captive resin production in the Great Lakes corridor to offset petrochemical feedstock volatility. Secure long-term offtake agreements with corrugated converters facing EPA compliance deadlines to lock in volume stability against water-based specialists. For New Entrants and Emerging Players: Lead with recyclable and deinkable formulation portfolios targeting California extended producer responsibility pilot programs. The most penetrable white-space sits in hybrid aqueous-UV inkjet configurations for pharmaceutical and organic product label converters. Establish specification authority through direct brand-owner engagement bypassing traditional converter intermediaries. For Investors and Strategic Acquirers: Formulation specialists with certified in-house gas chromatography laboratories and documented FDA migration testing protocols represent the priority acquisition archetype. Long-term viability hinges on portfolio diversification across solvent, water, and UV chemistry platforms rather than single-technology concentration. Watch for LED-UV adoption rates in folding carton operations as inflection indicator for mercury-arc displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive acrylic supply secures margin control against petrochemical volatility for corrugated specialists. |
| ASTM D6807 Certification Investment | In-house analytical laboratories qualify suppliers for food-contact flexible packaging procurement pools. |
| LED-UV Formulation Platform Launch | Narrow-wavelength photoinitiator packages eliminate ozone generation and reduce energy draw for carton converters. |
| Biobinder Technology Partnership | Soy and algae-derived resin platforms penetrate segments where renewable content certifications command procurement preference. |
| Direct Brand-Owner Specification Programs | Approved substance lists bypass converter intermediaries in organic and natural product categories requiring composition transparency. |
Research Methodology
A spread of perspectives from plant managers at flexible packaging converters, procurement leads at corrugated operations, technical R&D directors at formulation houses, and regulatory affairs specialists at brand owners converged on the working assumptions. Primary interview insights combined with secondary validation from EPA NESHAP regulatory filings, customs trade data on pigment imports, and SEC 10-K disclosures from integrated chemical conglomerates. Bottom-up volume modeling triangulated against top-down value estimates across formulation chemistry segments.
Segmentation dimensions modeled include formulation chemistry type, substrate compatibility tier, regulatory compliance grade, end-use application, and technology platform adoption patterns across the projection horizon. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection timing and technology substitution curves. Industry-specific forecast inputs incorporated EPA compliance deadline schedules and LED-UV press installation rates in narrow-web label operations.
The analysis sits within stated boundaries; outcomes outside sustained EPA enforcement intensity or accelerated LED-UV capital expenditure cycles would require recalibration. Forecasts reflect assumptions about pigment feedstock cost stability and migration testing protocol harmonization. Revision becomes warranted when biobinder cost parity thresholds cross commercial viability levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Returnable Glass Bottle Ink Market
Printing Inks
Eco-Friendly Inks Market
Printing Inks
Global Water-Based Inks Market
Printing Inks
Global Conductive Inks Market
Printing Inks
Global Digital Textile Printing Inks Market
Printing Inks
Ink Additives Market
Printing Inks
Squid Ink Market
Printing Inks
North America Printing Inks Market
Printing Inks
Specialty Printing Consumables Market
Printing Inks
Non-Conductive Ink Market
Printing Inks
Continuous Inkjet Ink Market
Printing Inks
Global Printing Toners Market
Printing Inks
UV Cured Inks Market
Printing Inks
Rapid Liquid Printing Market
Printing Inks
Waterborne Ink Market
Printing Inks
Global Ceramic Inks Market