
 Hand Eczema (HE) Treatment Market | 2026-2036
Hand Eczema (HE) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hand Eczema (HE) Treatment Market Foresight
Calcineurin inhibitors are expanding their share of first-line maintenance protocols as steroid-sparing alternatives for chronic hand eczema management. Incyte Corporation leverages JAK inhibitor platforms to sustain clinical differentiation in moderate-to-severe patient segments. Sanofi anchors European market access through established dermatology field forces and reimbursement relationships with national health systems. Regeneron Pharmaceuticals competes via IL-4/IL-13 pathway biologics that command premium positioning in recalcitrant atopic hand eczema cases.
Hand eczema treatment encompasses pharmacological and non-pharmacological interventions targeting inflammatory skin disease of the palmar and dorsal hand surfaces, with topical corticosteroids typically formulated at 0.05% to 0.1% betamethasone or equivalent potency for acute flares. The primary commercial purpose centers on interrupting the itch-scratch cycle, restoring barrier function, and enabling occupational continuity for working-age adults. Topical corticosteroids occupy the largest revenue pool among product types due to decades of clinical familiarity and broad generic availability, while immunomodulators represent the fastest-expanding segment as payer acceptance of steroid-sparing maintenance improves. Cream formulations dominate volume across distribution channels, though ointment bases command preference in severe fissured variants where occlusion enhances steroid penetration.
The FDA regulates prescription topical therapies under NDA and ANDA pathways with specific bioequivalence requirements for corticosteroid potency classification, while the EMA's Committee for Medicinal Products for Human Use assesses dermatology products under centralized procedures that influence pricing and access across EU member states. OSHA workplace exposure standards for wet work and irritant contactants indirectly shape demand by mandating protective equipment in food handling and healthcare settings. Stakeholders must monitor evolving FDA guidance on topical JAK inhibitors and corresponding EMA safety reviews, as regulatory positioning for this drug class will determine competitive sequencing across major markets.
Market Dynamics
The FDA's 505(b)(2) reformulation pathway is compressing development timelines for topical therapies, enabling faster commercialization of steroid-sparing alternatives while reshaping competitive positioning between established corticosteroid franchises and emerging immunomodulator platforms.
Growth Catalysts
- Occupational safety mandates:OSHA wet-work exposure standards in US healthcare and food-service settings sustain prescription volumes by mandating protective protocols that fail without concurrent therapeutic management.
- JAK inhibitor platforms:Oral and topical JAK-targeting mechanisms expand addressable patient populations into moderate-to-severe refractory segments previously dependent on systemic immunosuppressants.
- France:ANSM reimbursement alignment for biologic therapies in chronic atopic hand eczema accelerates specialist adoption within Paris and Lyon dermatology centers.
Market Restraints
- Active pharmaceutical ingredient concentration:European corticosteroid precursor supply depends on a limited base of specialized chemical manufacturers in Basel and Frankfurt, creating input vulnerability.
- EMA safety surveillance:Heightened pharmacovigilance requirements for topical immunomodulators extend approval timelines and inflate post-market commitment costs.
- Generic corticosteroid substitution:Commoditized 0.05% betamethasone formulations capture maintenance-phase volume, compressing branded pricing power in first-line acute care.
Strategic Opportunities
- India:CDSCO fast-track pathways for dermatology products with established US or EU approval create accelerated entry into Mumbai and Delhi prescription markets.
- Telemedicine dermatology:Remote diagnosis platforms enable rural patient capture without physical clinic infrastructure, expanding addressable geography beyond urban specialist concentration.
- Barrier repair convergence:Integration of ceramide-dominant emollients with prescription anti-inflammatory protocols creates combination therapy positioning distinct from standalone pharmaceutical or cosmetic claims.
Industry Challenges
- Clinical trial recruitment:Heterogeneous hand eczema phenotypes complicate endpoint standardization, prolonging study duration and inflating per-patient costs.
- Formulation stability:Ointment base compatibility with novel active ingredients requires specialized compounding expertise scarce among contract manufacturing organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hand Eczema (HE) Treatment Market |
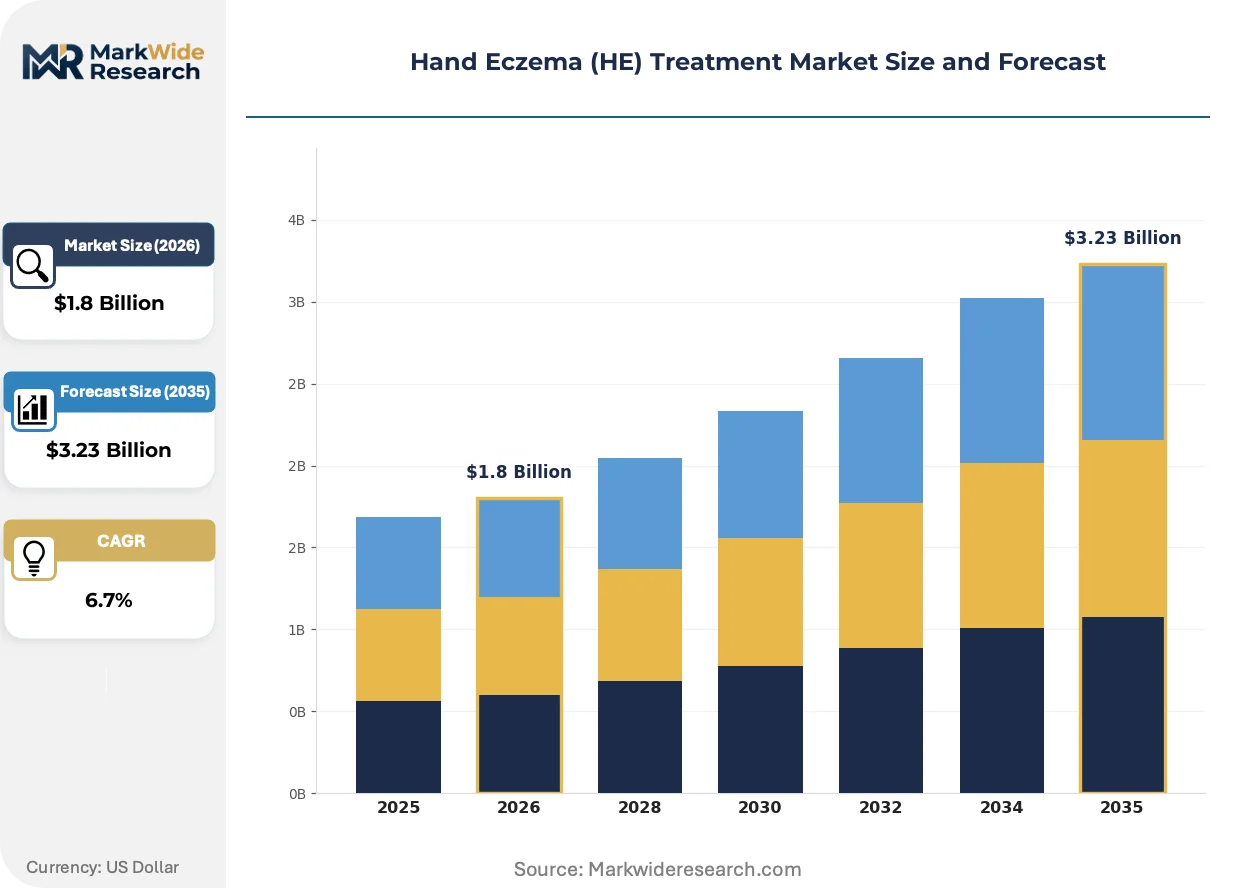
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Corticosteroids, Emollients, Immunomodulators, Antihistamines Formulation: Creams, Ointments, Lotions, Gels Patient Type: Adults, Children, Elderly, Infants Distribution Channel: Pharmacies, Hospitals, Online Stores, Dermatology Clinics |
| Companies Covered | Sanofi, Incyte Corporation, Asana Biosciences, Leo Pharma, Regeneron Pharmaceuticals, Stiefel Laboratories, Basilea Pharmaceutica, Japan Tobacco, Arcutis Biotherapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hand Eczema (HE) Treatment Market Shifts & Advancements
Biologic mechanism translation from atopic dermatology into hand-specific indications is restructuring the competitive hierarchy, with IL-4/IL-13 and JAK pathway assets displacing corticosteroid dominance in recalcitrant cases.
Microbiome-targeted topical therapies is unifying bacterial community modulation with anti-inflammatory action in next-generation hand eczema protocols. Dermatology clinics in Germany and Switzerland pilot these formulations for chronic fissured variants. The convergence is unifying previously separate cosmetic and pharmaceutical development tracks into single regulatory submissions.
EMA's MDR implementation for software-as-medical-device applications is reshaping digital therapeutics integration. Connected compliance monitors for topical application frequency now require notified body certification. The regulation most affects French and Italian markets where national health systems pilot reimbursement for adherence technologies.
Specialist referral patterns are compressing as primary care physicians in the United Kingdom adopt dermoscopy and structured severity scoring. This behavioral shift displaces traditional dermatologist gatekeeping for moderate cases. The change is most visible in NHS England regions where diagnostic hub networks centralize initial assessment.
Hand Eczema (HE) Treatment Market Segmentation
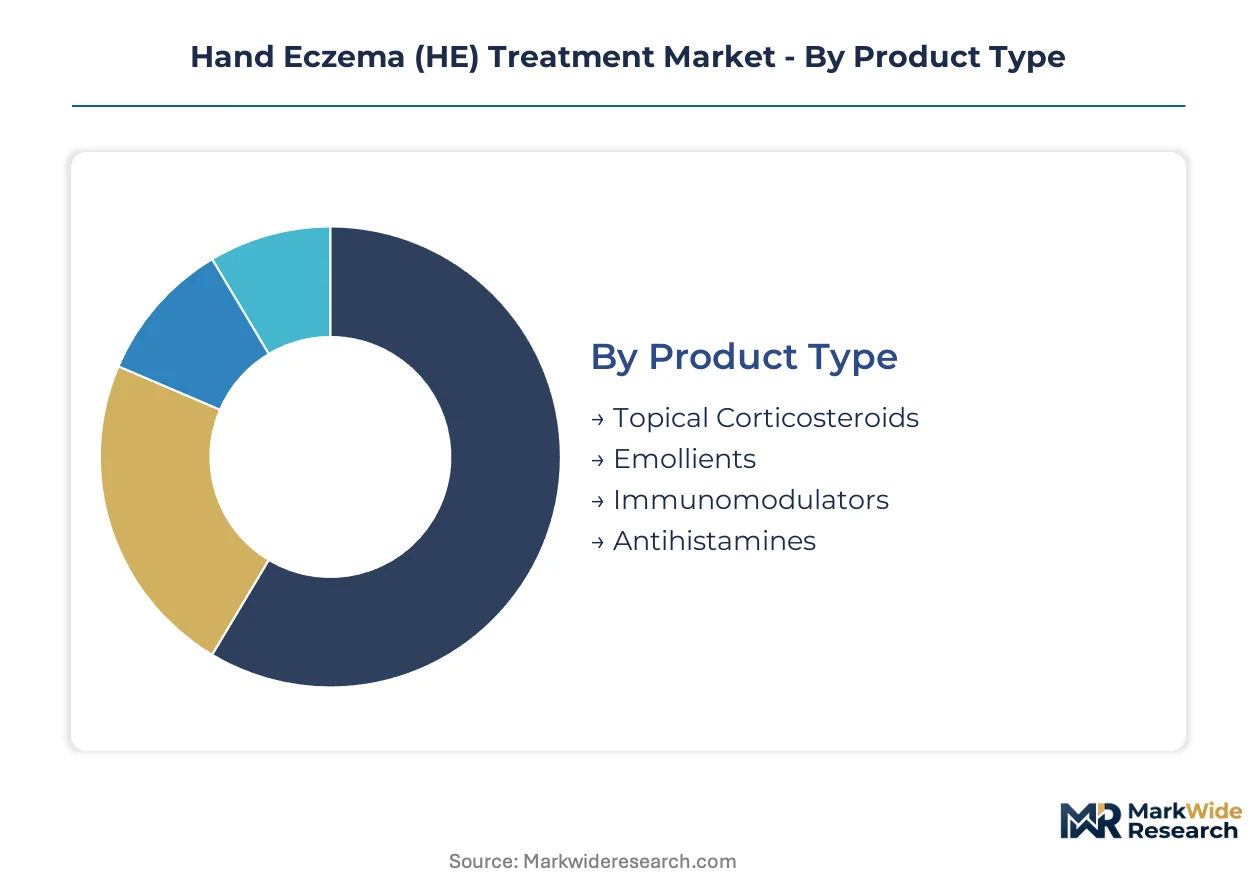
Hand eczema treatment markets fragment across therapeutic intensity, patient vulnerability, and care setting economics. Each segmentation axis reveals distinct margin structures and access pathways that determine commercial prioritization for manufacturers and distributors.
Product Type:
Standardization dominates high-volume maintenance categories while customization concentrates in refractory disease management requiring specialist oversight.
- Topical Corticosteroids:Formulations range from low-potency hydrocortisone to super-potent clobetasol propionate, classified by vasoconstrictive assay. Demand concentrates in US occupational health settings where OSHA-mandated protective protocols fail without concurrent therapeutic management of acute flares.
- Emollients:Ceramide-dominant barrier repair formulations with physiological lipid ratios matching stratum corneum composition. Growth accelerates in German and Swiss dermatology clinics piloting microbiome-targeted combination protocols for chronic fissured variants.
- Immunomodulators:Calcineurin inhibitors and JAK-targeting mechanisms for steroid-sparing maintenance.
- Antihistamines:Oral and topical formulations addressing pruritus-driven sleep disruption.
Leading the category by volume: Topical Corticosteroids. Expanding most quickly: Immunomodulators.
Formulation:
Patient compliance and lesion morphology dictate base selection, with cost tier separating hospital procurement from retail pharmacy preferences.
- Creams:Oil-in-water emulsions offering cosmetic acceptability and rapid absorption. Volume concentrates across US retail pharmacy channels where patient self-selection favors non-greasy aesthetics for daytime workplace application.
- Ointments:Occlusive petrolatum-based vehicles enhancing steroid penetration in fissured palmar disease. Preference commands premium positioning in severe variants where occlusion determines therapeutic outcome.
- Lotions:Low-viscosity vehicles for hair-bearing dorsal hand surfaces and large-area application.
- Gels:Alcohol-based or aqueous systems for interdigital spaces requiring rapid drying.
Dominant by prescription volume: Creams. Steepest expansion trajectory: Ointments in severe disease segments.
Patient Type:
Regulatory scrutiny and dosing precision requirements intensify across age-related vulnerability gradients.
- Adults:Working-age population drives prescription economics through occupational continuity requirements. US healthcare and food-service workers generate sustained demand under OSHA wet-work exposure mandates.
- Children:Pediatric formulations with reduced steroid potency and enhanced safety profiling. Growth concentrates in NHS England diagnostic hub networks where primary care dermoscopy adoption compresses specialist referral timelines.
- Elderly:Age-related barrier dysfunction and polypharmacy interaction considerations.
- Infants:Highest regulatory stringency with limited approved indications and specialized compounding requirements.
Largest addressable population: Adults. Gaining share fastest: Children via primary care diagnostic expansion.
Distribution Channel:
Channel selection determines pricing autonomy, with digital platforms disrupting traditional pharmacy gatekeeping.
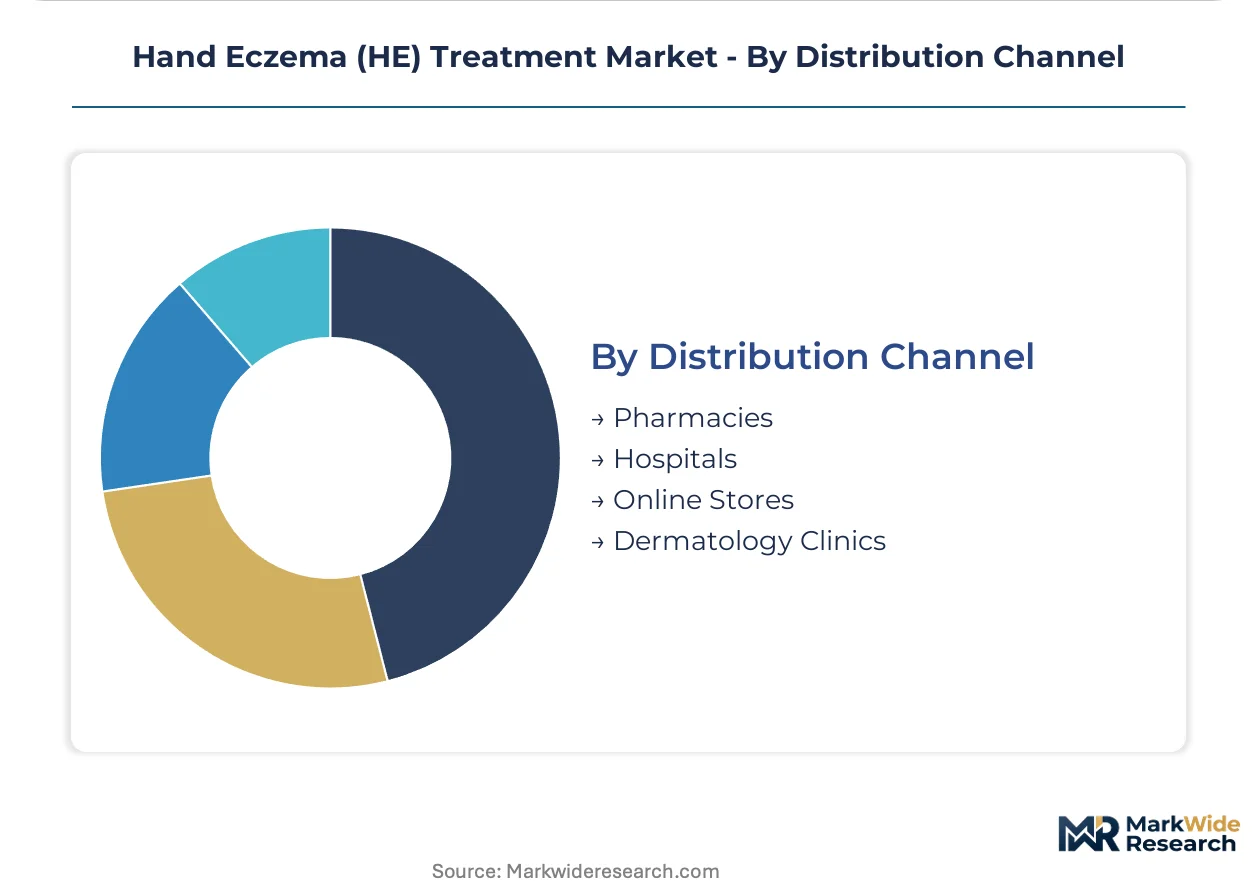
- Pharmacies:Community and hospital-based dispensing with formulary negotiation dynamics. Volume concentrates in French and Italian markets where national health systems pilot reimbursement for adherence technologies.
- Hospitals:Inpatient and emergency department initiation of severe disease protocols.
- Online Stores:Direct-to-patient platforms expanding rural access beyond urban specialist concentration.
- Dermatology Clinics:Specialist-controlled prescribing with biologic therapy integration in Paris and Lyon centers under ANSM reimbursement alignment.
Highest transaction volume: Pharmacies. Climbing the fastest: Online Stores via telemedicine dermatology integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in pharmaceutical manufacturing cluster hand eczema treatment production across tax-advantaged jurisdictions. These designated areas attract formulation specialists through accelerated regulatory timelines and reduced duty structures on active pharmaceutical ingredient imports.
United States
OSHA wet-work exposure standards in healthcare and food-service sectors sustain prescription volumes by mandating concurrent therapeutic management alongside protective equipment. FDA 505(b)(2) reformulation pathways compress development timelines for steroid-sparing alternatives. New Jersey and North Carolina pharmaceutical corridors concentrate topical corticosteroid manufacturing capacity serving domestic occupational health networks.
Germany
EMA centralized procedures for dermatology products shape pricing and reimbursement access across EU member states from Frankfurt regulatory operations. Federal Institute for Drugs and Medical Devices enforces stringent post-market surveillance extending approval timelines for novel immunomodulators. Bavaria and Baden-Württemberg dermatology centers pilot microbiome-targeted combination protocols for chronic fissured variants.
France
ANSM reimbursement alignment for biologic therapies in chronic atopic hand eczema accelerates specialist adoption within Paris and Lyon dermatology centers. National health system pilots for adherence technologies reshape pharmacy dispensing economics. Île-de-France diagnostic hub networks centralize initial assessment compressing traditional specialist referral timelines.
India
CDSCO fast-track pathways for dermatology products with established US or EU approval create accelerated entry into Mumbai and Delhi prescription markets. Production-Linked Incentive schemes for pharmaceutical manufacturing attract formulation specialists to Gujarat and Maharashtra special economic zones. Contract research organizations in Hyderabad and Bangalore support bioequivalence studies for corticosteroid potency classification.
Switzerland
Swissmedic maintains autonomous regulatory assessment parallel to EMA procedures preserving pricing differentiation for premium dermatology portfolios. Basel chemical manufacturers supply corticosteroid precursors creating input concentration vulnerability for European formulation networks. Zurich and Geneva dermatology clinics anchor specialist adoption of JAK-targeting mechanisms in moderate-to-severe refractory segments.
Hand Eczema (HE) Treatment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with established dermatology franchises defending acute-care volume while biologic platforms capture refractory-case premiums. Market structure tilts toward consolidation among systemic immunomodulator developers against fragmentation in topical generic substitution. Three archetypes dominate: legacy corticosteroid houses with decades of clinical familiarity, JAK inhibitor specialists leveraging platform differentiation, and IL pathway biologic developers commanding premium positioning. Competitive moves concentrate on M&A for novel mechanism access and strategic partnerships for microbiome-targeted formulation capabilities.
Within the biologic-specialist tier, Sanofi and Regeneron Pharmaceuticals exemplify European-US alliance structures anchoring IL-4/IL-13 pathway positioning, while Incyte Corporation occupies a distinct position among JAK platform developers targeting moderate-to-severe patient segments previously dependent on systemic immunosuppressants.
| Leading Market Players |
|---|
| Sanofi |
| Incyte Corporation |
| Asana Biosciences |
| Leo Pharma |
| Regeneron Pharmaceuticals |
| Stiefel Laboratories |
| Basilea Pharmaceutica |
| Japan Tobacco |
| Arcutis Biotherapeutics |
| Others |
Supply & Pricing Matrix
Topical JAK inhibitor manufacturing transitions from batch synthesis to continuous flow chemistry, simultaneously compressing per-unit active pharmaceutical ingredient costs and concentrating production capacity among Basel and Frankfurt chemical specialists with the capital intensity to retool.
Pricing Analysis
Volume concentrates in commoditized 0.05% betamethasone generics while margin pools in biologic maintenance protocols. Three-tier pricing structure across premium biologics, standard immunomodulators, and economy corticosteroids reflects payer reimbursement tiers and FDA potency classification. Cost compression in the generic tier intensifies as Indian CDSCO-approved manufacturers enter US pharmacy networks. Occupational health buyers exhibit lowest price sensitivity due to OSHA mandate compliance requirements.
Supply Chain Analysis
Reverse-logistics for temperature-sensitive biologics requires cold-chain refurbishment centers in Pennsylvania and Illinois to handle returns from dermatology clinics. Active pharmaceutical ingredient production draws from Switzerland, Germany, and India, with corticosteroid precursors exhibiting highest geographic concentration. Supply chain risk centers on single-source vulnerability for specialized ointment base compounding. Distribution runs through wholesale pharmacy networks with hospital procurement commanding volume discounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race, with JAK platform developers pursuing backward integration into continuous flow chemistry to secure API cost advantages.
For Market Incumbents: Cement formulary positioning through exclusive contracting with US occupational health networks threatened by emerging JAK inhibitor substitution. Anchor capacity expansion in North Carolina pharmaceutical corridors to defend against Indian CDSCO-approved import competition. Prioritize FDA 505(b)(2) pathway investments for topical reformulation lifecycle extension. For New Entrants and Emerging Players: Enter via telemedicine dermatology platforms capturing rural patient populations underserved by Paris and Lyon specialist concentration. Target the UK NHS England diagnostic hub network where primary care dermoscopy adoption compresses traditional referral gatekeeping. Pursue microbiome-targeted formulation partnerships with Bavaria pilot centers as differentiation lever. For Investors and Strategic Acquirers: Exit pathways concentrate in biologic-specialist acquisition by legacy dermatology franchises seeking mechanism diversification. Long-term viability hinges on regulatory positioning for topical JAK inhibitors across FDA and EMA surveillance frameworks. Monitor EMA safety review outcomes for JAK class as inflection indicator for competitive sequencing.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Hand-specific indication trials for IL-4/IL-13 biologics expand addressable refractory populations beyond atopic dermatology. |
| Regulatory Approval Pathway | FDA 505(b)(2) submissions for topical corticosteroid reformulations compress development timelines versus full NDA routes. |
| Manufacturing Scale-Up | Continuous flow chemistry investment in Basel chemical corridors secures JAK inhibitor API cost positions. |
| Licensing Agreement | Microbiome-targeted formulation partnerships with German pilot centers accelerate next-generation protocol adoption. |
| Pipeline Diversification | JAK platform extension into pediatric hand eczema indications captures NHS England primary care diagnostic expansion. |
Research Methodology
Independent corroboration across dermatology clinic prescribing data, FDA 505(b)(2) submission records, and EMA centralized procedure timelines underwrites the qualitative findings. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers combined with secondary validation against ClinicalTrials.gov entries, FDA Orange Book listings, and EMA EPAR documentation. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Comparable-period anchoring to historical prescription volume trends across the analysis window established baseline growth trajectories. Segmentation dimensions modeled include treatment line, dosage form, patient population, and regional regulatory cluster. CAGRs derived from least-squares trend fitting to annualized prescription data and revenue estimates. Forecast inputs incorporated OSHA wet-work mandate enforcement intensity and ANSM reimbursement alignment timelines for biologic therapies.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EMA safety surveillance escalation or generic corticosteroid substitution acceleration. Practitioners should monitor FDA guidance publication on topical JAK inhibitors and corresponding EMA PRAC review outcomes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Revitalizing Skin Wands Market
Skincare
Body Scrub Market
Skincare
Tinted Sunscreen Market
Skincare
Self-Tanning Care Market
Skincare
Encapsulated Retinol Market
Skincare
Skin Toner Market
Skincare
Global Physician Dispensed Cosmeceuticals Market
Skincare
Organic Skincare Products Market
Skincare
Hidradenitis Suppurativa Market
Skincare
Herbal Skincare Products Market
Skincare
CBD Skin Care Market
Skincare
Global Skin Rejuvenation Market
Skincare
Global Hand Lotion and Hand Cream Market
Skincare
Ampoule Cream Market
Skincare
Preoperative Skin Preparation Market
Skincare
Retinol Skincare Product Market