
 India Skin Care Products Market | 2026-2036
India Skin Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
India Skin Care Products Market Insights
Direct-to-consumer platforms and quick-commerce networks is rewriting how skin care products reach Indian households. Hindustan Unilever Ltd leverages its rural distribution muscle to sustain mass-market coverage across tier-2 and tier-3 towns. L'Oréal India Pvt Ltd anchors premium positioning through specialty store partnerships in Mumbai and Delhi. Honasa Consumer Pvt Ltd competes aggressively via digital-native branding that captures millennial and Gen-Z spend.
India skin care products comprise topical formulations including emulsions, gels, serums, and creams containing active ingredients such as niacinamide, hyaluronic acid, and botanical extracts, manufactured through cold-process emulsification or hot-melt compounding to deliver barrier protection, photoprotection, or cellular repair. These products serve consumer needs ranging from basic cleansing to dermatological-grade intervention for conditions like hyperpigmentation and eczema. Moisturizers and sunscreens command the largest revenue pools given India's tropical climate and year-round UV exposure concerns. Online retail channels represent the fastest-expanding distribution vector, while specialty stores retain margin concentration for premium and clinical-positioned lines. Anti-aging applications attract disproportionate R&D investment as India's aging affluent demographic expands.
BIS mandatory cosmetic standards and CDSCO import registration requirements govern ingredient safety, labeling, and market access for domestic and imported skin care products sold in India. FSSAI overlap on cosmeceutical claims creates compliance complexity that favors established players with dedicated regulatory affairs teams. State-level drug control administrations in Maharashtra and Tamil Nadu enforce additional inspection protocols that shape regional go-to-market timelines. Stakeholders must monitor impending BIS harmonization with ASEAN cosmetic directive standards to preempt formulation and packaging adjustments.
Market Dynamics
Quick-commerce networks and direct-to-consumer platforms are compressing traditional distributor margins while accelerating product refresh cycles across India's skin care sector. This channel shift forces incumbents to rebuild fulfillment infrastructure around 10-minute delivery promises.
Growth Catalysts
- BIS cosmetic safety standards harmonization:Alignment with ASEAN cosmetic directive protocols is reducing formulation complexity for exporters targeting Southeast Asian markets alongside domestic sales.
- Hyaluronic acid penetration:This humectant technology is expanding from premium serums into mass-market moisturizers as cold-process emulsification costs decline.
- Maharashtra specialty retail density:Mumbai's mall-based beauty corridors concentrate affluent consumers and enable clinical-positioned brand launches with lower customer acquisition spend.
Market Restraints
- Palm-derived emollient volatility:Malaysia and Indonesia supply concentration exposes formulators to input cost swings that compress gross margins on entry-level moisturizers.
- FSSAI cosmeceutical claim overlap:Dual jurisdiction with CDSCO creates registration delays that freeze product pipelines for 8-14 months.
- Import dependency for niacinamide API:China-origin active pharmaceutical ingredients create supply vulnerability during port congestion or customs enforcement waves.
Strategic Opportunities
- Tier-3 town underpenetration:Uttar Pradesh and Bihar cities below 500,000 population lack organized beauty retail, creating whitespace for rural-distribution-capable players.
- Photoprotection-moisturizer hybrid formats:SPF-infused daily wear products address year-round UV exposure concerns without adding regimen steps.
- PLI scheme for active ingredient manufacturing:Domestic production incentives could reshore niacinamide and peptide synthesis from Chinese suppliers.
Industry Challenges
- Cold-chain last-mile gaps:Temperature-sensitive probiotic and vitamin C formulations degrade in ambient delivery networks, limiting premium product reach.
- Cosmetologist certification bottlenecks:Shortage of CDSCO-recognized safety assessors extends new product registration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Skin Care Products Market |
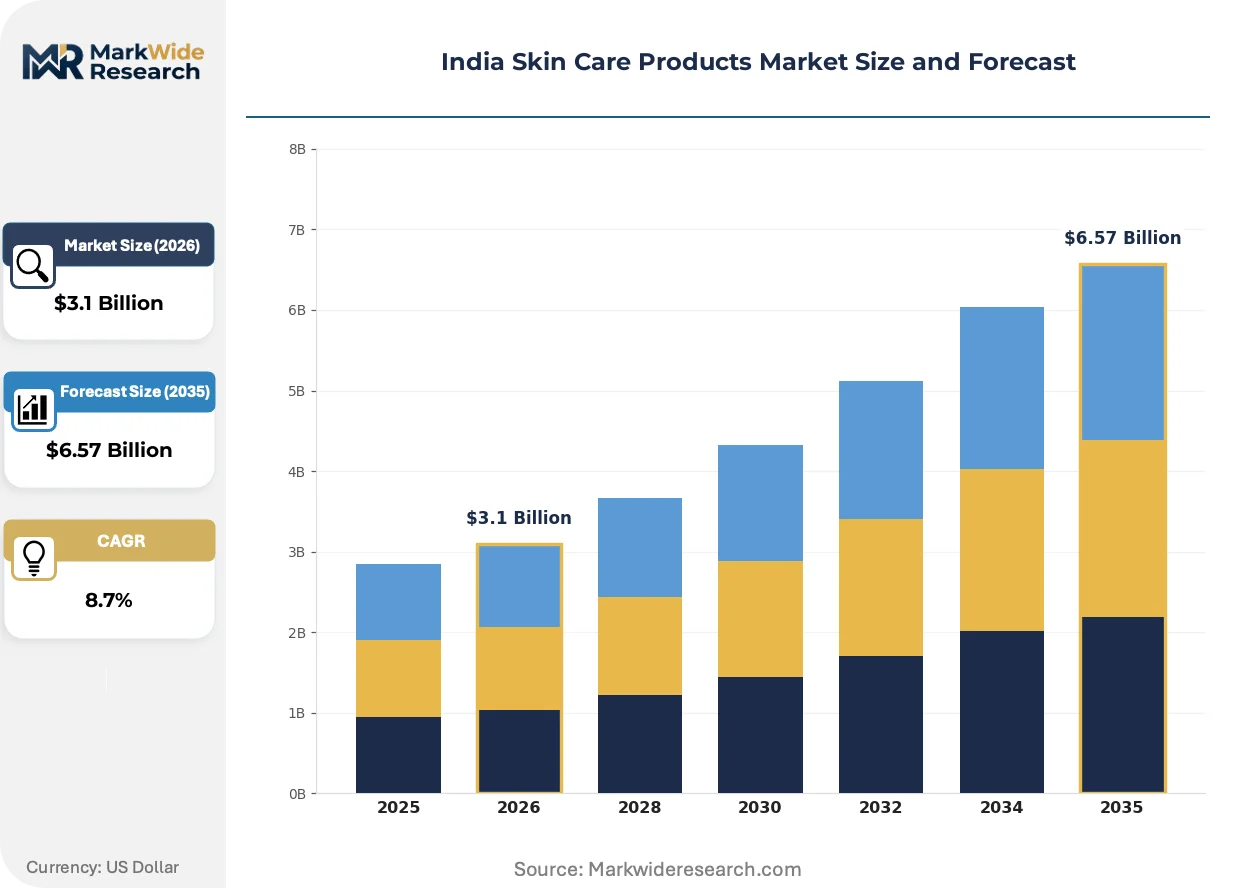
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.57 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Sunscreens, Cleansers, Exfoliators Customer Type: Teenagers, Adults, Seniors, Athletes Application: Daily Use, Sensitive Skin, Anti-Aging, Hydration Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | Lotus Herbals Pvt Ltd, Emami Ltd, Hindustan Unilever Ltd, Nivea India Pvt Ltd, Procter & Gamble Home Products Ltd, L'Oréal India Pvt Ltd, Himalaya Drug Co, Honasa Consumer Pvt Ltd, Johnson & Johnson (India) Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Skin Care Products Market Trends and Innovations
Formulation science and distribution infrastructure are converging to enable personalization at mass-market price points. Three developments are restructuring competitive advantage.
Biotechnology-derived actives are replacing petroleum-sourced emollients in mid-tier products. Domestic manufacturers in Gujarat and Telangana are adopting fermentation-based squalane and ceramide precursors. This ingredient base is migrating from premium positioning into standard-grade moisturizers, collapsing the historical price-performance gap between mass and prestige lines.
CDSCO is tightening import registration requirements for cosmetic products containing novel nanomaterials. This regulatory pressure is forcing reformulation of sunscreens using zinc oxide and titanium dioxide at sub-micron scales. Premium clinical brands with existing safety dossiers are absorbing compliance costs faster than new market entrants, consolidating shelf space in dermatologist channels.
Urban millennials are consolidating purchase decisions onto quick-commerce platforms that bypass traditional kirana and modern trade networks. Blinkit and Zepto now capture significant sunscreen and cleanser volume in Delhi NCR and Bengaluru. This channel compression is most visible in Maharashtra, where 10-minute delivery promises have reset consumer expectations for replenishment convenience.
India Skin Care Products Market Segmentation
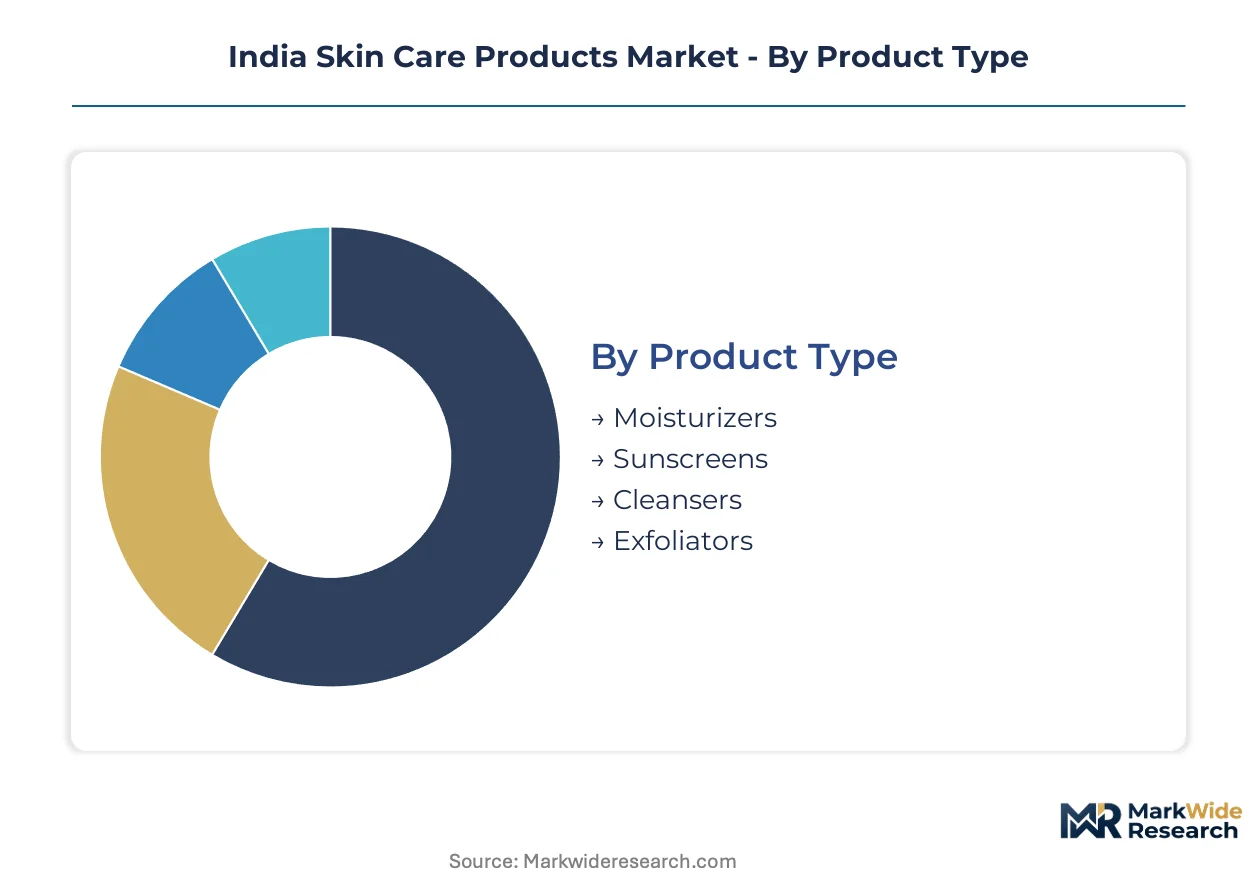
India skin care products segment along four dimensions that determine formulation priorities, channel investment, and margin architecture. Product type and customer type drive R&D allocation, while application and distribution channel shape go-to-market economics and working capital intensity.
Product Type:
After-sales service intensity varies sharply across formats, with clinical-positioned lines requiring dermatologist consultation networks and replenishment-driven categories demanding subscription infrastructure.
- Moisturizers:Emulsion-based formulations combining humectants, emollients, and occlusives in cream or lotion matrices. Maharashtra and Karnataka households with year-round air-conditioning exposure drive volume, though palm-derived emollient cost volatility compresses entry-level margins.
- Sunscreens:Photoprotection formulations spanning chemical UV filters, physical mineral blockers, and hybrid systems. CDSCO registration timelines for novel nanomaterial-containing variants extend 8-14 months, favoring incumbents with established safety dossiers.
- Cleansers:Surfactant-based solutions including foaming gels, micellar waters, and oil-based removers addressing pollution-exposed urban skin.
- Exfoliators:Acid-based chemical peels and physical scrubs targeting cell turnover, with concentration limits governed by BIS cosmetic safety standards.
By volume, moisturizers lead. By growth pace, sunscreens are climbing the fastest.
Customer Type:
Cost tier stratification separates mass-market penetration plays from premium clinical positioning, with teenagers and seniors commanding divergent marketing spend per acquisition rupee.
- Teenagers:Price-sensitive first-time buyers prioritizing acne management and basic cleansing regimens. Quick-commerce platforms in Delhi NCR and Bengaluru capture disproportionate share through impulse-driven replenishment.
- Adults:Core revenue pool spanning preventive anti-aging, daily photoprotection, and work-related stress skin management. Maharashtra working professionals in Mumbai and Pune finance premium serum adoption.
- Seniors:Dermatological-grade intervention seekers addressing hyperpigmentation, elasticity loss, and barrier repair. Specialty store penetration concentrates in Karnataka's Bengaluru and Hyderabad corridors.
- Athletes:Sweat-resistant, non-comedogenic format demand from cricket academies, marathon circuits, and gym networks across tier-1 towns.
Adults generate the largest absolute revenue. Teenagers are expanding most quickly.
Application:
Volume concentration in daily use formats contrasts with margin concentration in condition-specific applications requiring clinical validation and prescriptive positioning.
- Daily Use:Maintenance-oriented cleansers, moisturizers, and SPF-infused hybrids forming baseline regimen staples. Uttar Pradesh and Bihar underpenetration creates whitespace for rural-distribution-capable players.
- Sensitive Skin:Fragrance-free, barrier-supporting formulations with minimal ingredient lists. CDSCO-recognized safety assessor scarcity extends registration timelines for novel claims.
- Anti-Aging:Retinoid, peptide, and antioxidant concentrates targeting cellular repair. R&D investment concentrates here as India's affluent aging demographic expands.
- Hydration:Hyaluronic acid and ceramide-focused products migrating from premium to mass-market positioning as cold-process emulsification costs decline.
Daily use commands the highest shipment volumes. Anti-aging posts the steepest expansion trajectory.
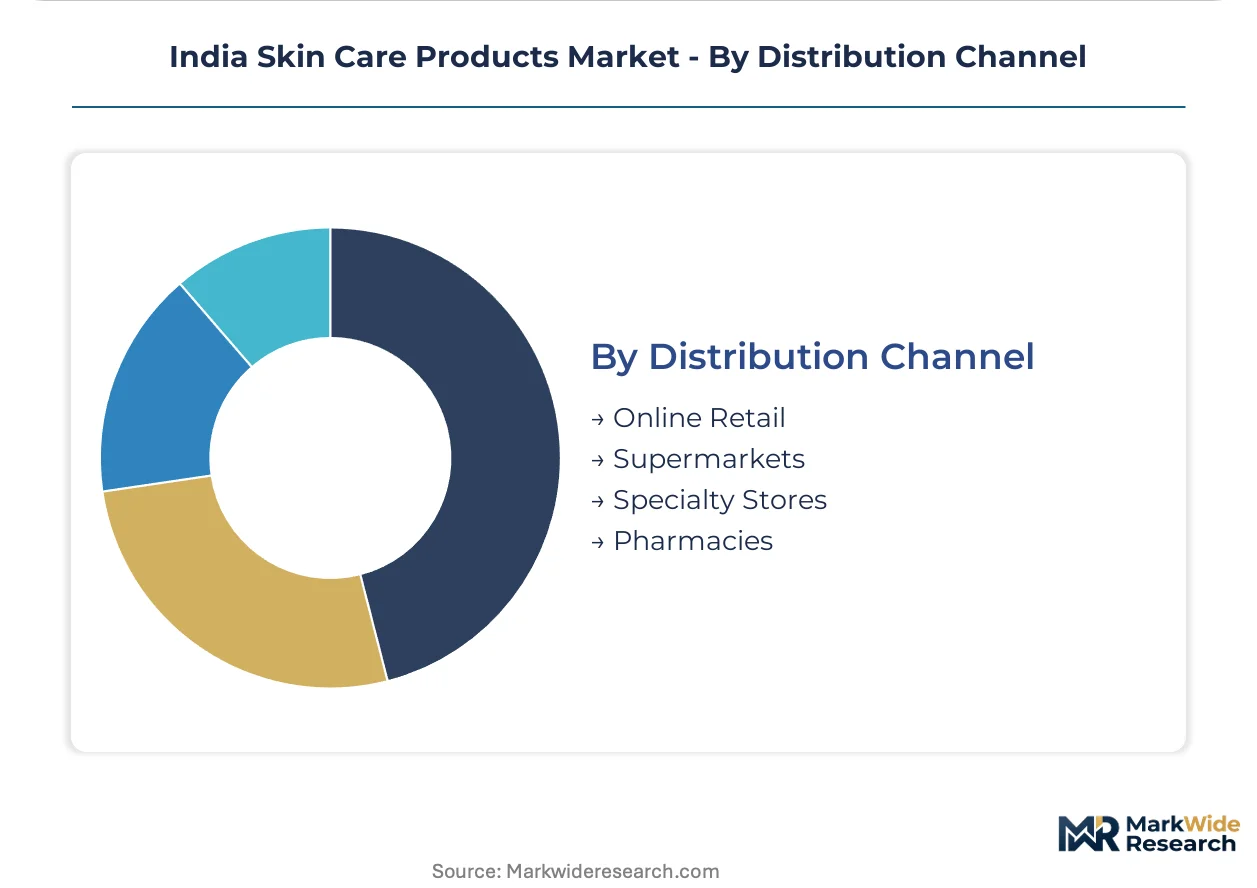
Distribution Channel:
Margin architecture inverts between high-velocity online retail and relationship-dependent specialty stores, with inventory risk and brand control trading off across formats.
- Online Retail:Direct-to-consumer platforms and quick-commerce networks compressing traditional distributor margins. Blinkit and Zepto 10-minute delivery promises reset replenishment expectations in Maharashtra.
- Supermarkets:Modern trade chains offering mass-market visibility with standardized planogram placement and promotional calendar dependency.
- Specialty Stores:Mall-based beauty corridors in Mumbai and Delhi enabling clinical-positioned launches with lower customer acquisition spend and higher basket values.
- Pharmacies:Dermatologist-recommended and FSSAI-registered cosmeceutical distribution nodes, with Tamil Nadu and Maharashtra state drug control administrations enforcing additional inspection protocols.
Online retail is gaining share fastest. Specialty stores retain margin concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jawaharlal Nehru Port Trust in Maharashtra anchors India's skin care import infrastructure, handling bulk shipments of niacinamide APIs and specialty emollients from Southeast Asian suppliers. This maritime gateway underwrites the state's dominance in formulation manufacturing and premium distribution networks.
Maharashtra
Mumbai's mall-based beauty corridors concentrate affluent consumers seeking clinical-positioned sunscreens and anti-aging serums. BIS cosmetic safety standards enforcement through the state drug control administration extends registration timelines for novel nanomaterial-containing formulations. Pune's biotechnology corridor hosts fermentation-based squalane manufacturers migrating active ingredients from premium to mass-market positioning.
Karnataka
Bengaluru's quick-commerce density resets replenishment expectations through 10-minute delivery networks capturing sunscreen and cleanser volume. CDSCO import registration requirements for novel actives create compliance bottlenecks that favor established players with dedicated regulatory affairs teams. Hyderabad's pharmaceutical cluster supplies peptide precursors and ceramide intermediates to domestic formulators.
Tamil Nadu
Chennai's specialty retail penetration enables dermatologist-recommended brand launches with lower customer acquisition spend in the anti-aging segment. State drug control administration inspection protocols exceed national baselines, freezing product pipelines for 8-14 months on cosmeceutical claims. Coimbatore's chemical processing infrastructure supports cold-process emulsification for hyaluronic acid moisturizers.
Gujarat
Surat and Ahmedabad manufacturing zones adopt fermentation-based emollient production to reduce palm-derived input dependency from Malaysian suppliers. FSSAI overlap with CDSCO on functional claims creates dual jurisdiction complexity that extends go-to-market timelines. Mundra Port's container handling capacity supports API import resilience during Nhava Sheva congestion episodes.
Delhi-NCR
Gurgaon's direct-to-consumer platform headquarters compress traditional distributor margins through quick-commerce integration with replenishment-driven categories. PLI scheme incentives for active ingredient manufacturing attract domestic niacinamide synthesis investments away from Chinese suppliers. Noida's contract research organizations support CDSCO safety dossier preparation for clinical-positioned lines.
India Skin Care Products Market Competitive Landscape
On the supply side, the industry is structured around three distinct competitive tiers anchored by divergent distribution capabilities and regulatory compliance sophistication. Mass-market penetration depends on rural distribution muscle spanning tier-2 and tier-3 towns, while premium positioning requires specialty store partnerships and dermatologist channel access. Digital-native players compete through quick-commerce integration and subscription infrastructure. Dominant competitive moves include backward integration into active ingredient manufacturing and geographic expansion into underpenetrated northern states.
Among diversified consumer goods conglomerates, Hindustan Unilever Ltd and L'Oréal India Pvt Ltd exemplify contrasting archetypes: the former leverages rural distribution density for mass-market coverage, while the latter anchors premium positioning through clinical brand portfolios. Honasa Consumer Pvt Ltd occupies a distinct digital-native position, capturing millennial and Gen-Z spend through direct-to-consumer platforms and influencer-driven marketing architecture.
| Leading Market Players |
|---|
| Lotus Herbals Pvt Ltd |
| Emami Ltd |
| Hindustan Unilever Ltd |
| Nivea India Pvt Ltd |
| Procter & Gamble Home Products Ltd |
| L'Oréal India Pvt Ltd |
| Himalaya Drug Co |
| Honasa Consumer Pvt Ltd |
| Johnson & Johnson (India) Ltd |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Gujarat fermentation facilities is compressing squalane contract prices while forcing suppliers toward long-term offtake agreements with domestic formulators, reshaping both procurement posture and margin architecture across premium and mass-market tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the market, with differentiation anchored in clinical validation depth and CDSCO registration status rather than ingredient concentration alone. Price differentiation stems from certification tier and volume scale, with FSSAI-registered cosmeceutical commands sustaining 40-60% premiums over basic cosmetic-grade equivalents. Cost compression in entry-level moisturizers is intensifying because palm-derived emollient volatility from Malaysian suppliers has compressed gross margins for formulators serving price-sensitive tier-3 towns. Teenage buyers through quick-commerce platforms exhibit highest price sensitivity, while seniors seeking dermatologist-recommended anti-aging serums show lowest elasticity.
Supply Chain Analysis
Import dependency for niacinamide API from China dominates supply chain risk exposure, with port congestion at Jawaharlal Nehru Port Trust creating inventory vulnerability for domestic formulators during customs enforcement waves. Manufacturing capacity concentrates in China, Malaysia, and Indonesia for critical inputs including hyaluronic acid precursors, palm-derived emollients, and peptide intermediates. Raw material dependencies rest on fermentation-based squalane, cold-process emulsification equipment, and zinc oxide nanoparticles for sunscreen formulations. Single-source vulnerability for China-origin APIs threatens continuity planning. Distribution runs through quick-commerce networks in Maharashtra and Karnataka alongside traditional kirana penetration in northern states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Domestic Ayurveda-inspired home remedies and unregulated gray-market imports from Southeast Asia constitute persistent substitution threats that incumbent formulators must neutralize through clinical credibility and regulatory compliance investment.
For Market Incumbents: Build regulatory affairs capabilities as a defensive moat. Deepen backward integration into niacinamide API synthesis through PLI scheme incentives to reduce China-origin dependency. Expand cold-chain fulfillment infrastructure to protect probiotic and vitamin C formulation integrity against ambient delivery degradation. Prioritize CDSCO safety assessor certification to compress registration timelines for novel nanomaterial-containing sunscreens. For New Entrants and Emerging Players: Establish a beachhead in Uttar Pradesh and Bihar tier-3 towns where organized beauty retail penetration remains below national averages. Target quick-commerce integration for replenishment-driven cleanser and sunscreen categories before incumbent distributors consolidate shelf space. Leverage influencer-driven digital-native branding to capture Gen-Z spend without bearing specialty store rental burdens. For Investors and Strategic Acquirers: Capital is best deployed toward digital-native platforms with proven subscription infrastructure and quick-commerce integration rather than legacy distributors with kirana-dependent cost structures. Long-term viability favors players with captive supply of fermentation-based actives and established CDSCO safety dossiers. Monitor BIS harmonization progress with ASEAN cosmetic directives as the critical inflection signal for export-oriented formulation investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Ingredient Manufacturing | PLI scheme incentives enable domestic niacinamide synthesis reducing China-origin API dependency. |
| Quick-Commerce Channel Expansion | Blinkit and Zepto partnerships in Maharashtra reset replenishment expectations for sunscreen and cleanser volume. |
| Clinical Validation Investment | CDSCO-recognized safety dossiers accelerate registration timelines for nanomaterial-containing photoprotection formulations. |
| Fermentation-Based Emollient Adoption | Gujarat and Telangana facilities migrate biotechnology-derived squalane from premium to mass-market positioning. |
| Regulatory Affairs Capability Buildout | Dedicated teams navigate FSSAI-CDSCO dual jurisdiction complexity that freezes pipelines for 8-14 months. |
Research Methodology
Cross-validation between primary interviews with formulation scientists, regulatory affairs directors at CDSCO-registered firms, specialty store buyers in Mumbai and Bengaluru, and quick-commerce category managers anchors the qualitative findings. Secondary validation draws from BIS cosmetic safety standard filings, CDSCO import registration databases, FSSAI cosmeceutical claim records, and Maharashtra state drug control administration inspection protocols. Bottom-up shipment data from fermentation facilities in Gujarat and Telangana triangulates against top-down retail audit coverage in modern trade and quick-commerce channels.
Calibration against historical volume trajectories in moisturizers, sunscreens, and anti-aging serums shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, customer age tier, application purpose, and distribution channel format alongside regional regulatory cluster intensity. CAGRs derive from category-level growth rate synthesis adjusted for channel shift acceleration and input cost volatility assumptions. Industry-specific forecast inputs incorporate PLI scheme uptake rates for domestic API manufacturing and quick-commerce penetration curves in metropolitan markets.
Macroeconomic conditions sit as an overlay; deviation in rupee-dollar exchange rates, palm oil futures pricing, or China port throughput would shift the trajectory for import-dependent formulators. Forecasts reflect documented assumptions regarding BIS-ASEAN harmonization timelines and CDSCO assessor certification expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Retinol Skincare Product Market
Skincare
Sheet Face Mask Market
Skincare
CBD Skincare Products Market
Skincare
Skin Toner Market
Skincare
Encapsulated Retinol Market
Skincare
Revitalizing Skin Wands Market
Skincare
Hand Eczema (HE) Treatment Market
Skincare
Sun-Care Wipes Market
Skincare
Preoperative Skin Preparation Market
Skincare
Allantoin Extract for Skincare Products Market
Skincare
Mineral Sunscreen Market
Skincare
Global Anti-Aging Market
Skincare
Skin Antiseptic Market
Skincare
Marine Retinol Market
Skincare
Global Hand Lotion and Hand Cream Market
Skincare
Non-Surgical Skin Tightening Market