
 Global Restaurant Management Software Market | 2026-2036
Global Restaurant Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Restaurant Management Software Market Foresight
Cloud-native architecture is expanding its cost advantage over legacy on-premise installations across mid-market restaurant chains. Toast, Inc. leverages integrated hardware-software bundles to anchor its position in independent full-service outlets. Oracle Corporation sustains enterprise-grade reliability for global franchise operators with complex multi-location reporting needs. Block, Inc. competes through embedded payment economics that tighten merchant retention across quick-service formats.
Restaurant management software encompasses integrated digital platforms that coordinate front-of-house ordering, kitchen display systems, inventory tracking, and financial reconciliation through API-connected modules. These systems typically process sub-second transaction latency for tableside payment terminals while maintaining PCI-DSS compliance across encrypted data streams. Cloud-based deployment leads solution uptake among multi-unit operators seeking centralized menu and pricing control without on-site server maintenance. Order management and payment processing command concentrated margin pools due to recurring interchange revenue and subscription tiers tied to transaction volume.
The EU AI Act and GDPR constrain how European platforms deploy automated customer profiling and dynamic pricing algorithms, while the FDA monitors digital food safety logging integrations in the United States. PCI-DSS certification remains a non-negotiable gateway for any vendor processing card-present transactions across major markets. Stakeholders must weigh the pace of AI-driven labor optimization against emerging algorithmic accountability requirements in their target geographies.
Market Dynamics
Cloud-native architecture is compressing total cost of ownership for mid-market chains while PCI-DSS Level 1 certification requirements are filtering vendor viability across payment-integrated platforms.
Growth Catalysts
- EU AI Act compliance mandates:Automated kitchen scheduling and dynamic pricing modules face new algorithmic accountability requirements, accelerating replacement cycles for legacy systems lacking audit trails.
- Embedded payment economics:Interchange revenue sharing models tighten merchant retention and expand addressable market for integrated hardware-software bundles.
- Tableside ordering penetration:Full-service operators in the United States deploy handheld terminals to compress turn times and lift average check sizes through suggestive selling prompts.
Market Restraints
- Input cost volatility:Semiconductor shortages and shipping constraints inflate lead times for proprietary payment terminals and kitchen display hardware.
- Technical fragmentation:API interoperability gaps between legacy POS databases and modern cloud platforms force expensive middleware development.
- Substitution threat:White-label payment apps and generic tablet-based systems capture price-sensitive independent operators with minimal feature requirements.
Strategic Opportunities
- India's FSSAI digitization push:Mandatory electronic food safety logging creates first-mover advantage for platforms integrating temperature monitoring and compliance dashboards.
- Voice-ordering convergence:Natural language processing integration with drive-thru systems opens new automation layers for quick-service formats.
- Subscription revenue expansion:Tiered SaaS models tied to transaction volume and module depth capture recurring revenue pools beyond initial hardware sales.
Industry Challenges
- PCI-DSS certification timelines:Twelve-to-eighteen month audit cycles delay product launches and inflate compliance overhead for card-present transaction modules.
- Legacy system integration friction:Proprietary data formats in installed on-premise databases resist migration to cloud-native architectures without custom engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Restaurant Management Software Market |
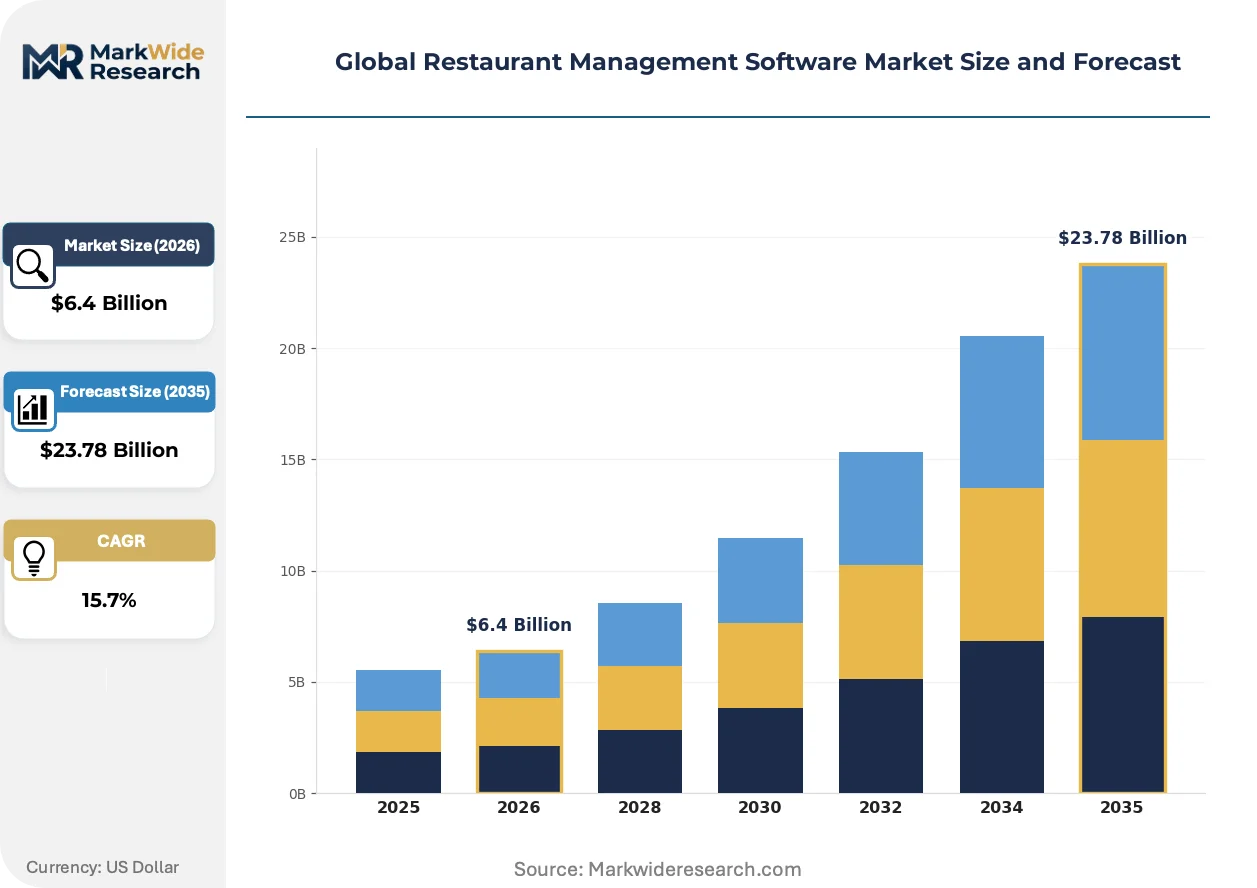
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $23.78 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Managed Services Solution Offering: Order Management, Inventory Control, Customer Relationship Management, Staff Scheduling, Payment Processing, Reporting & Analytics Use Case: Quick Service Restaurants, Fine Dining, Cafés & Bistros, Food Trucks, Catering Services, Food Courts End User: Restaurant Chains, Independent Outlets, Franchise Operators, Hotel Restaurants, Event Venues, Online Food Delivery Platforms |
| Companies Covered | Toast, Inc., Block, Inc., Oracle Corporation, NCR Corporation, Lightspeed Commerce Inc., TouchBistro, Revel Systems, PAR Technology Corporation, OpenTable, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Restaurant Management Software Market Shifts & Advancements
Kitchen automation and predictive analytics are compressing labor allocation decisions while regulatory pressure on algorithmic transparency accelerates vendor differentiation.
Edge computing nodes embedded in kitchen display systems are electrifying real-time order routing and inventory synchronization. Quick-service chains with high throughput volumes deploy these processors to eliminate cloud latency during peak hours. The technology is electrifying competitive positioning for vendors promising sub-second ticket transmission between front-of-house terminals and kitchen stations.
GDPR Article 22 restrictions on automated decision-making constrain how European platforms deploy dynamic pricing and customer profiling algorithms. Vendors must now maintain human-in-the-loop overrides and algorithmic audit trails to maintain compliance. Full-service operators in Germany and France face the steepest adaptation costs as they retrofit loyalty programs and reservation systems.
Consolidated procurement through multi-unit franchise operators is compressing vendor switching cycles and squeezing standalone software providers. Large chains now demand unified reporting across dozens of locations, favoring platforms with centralized menu management and real-time P&L visibility. This concentration is most pronounced in the United States, where private-equity-backed restaurant groups negotiate enterprise-wide contracts with steep volume discounts.
Global Restaurant Management Software Market Segmentation
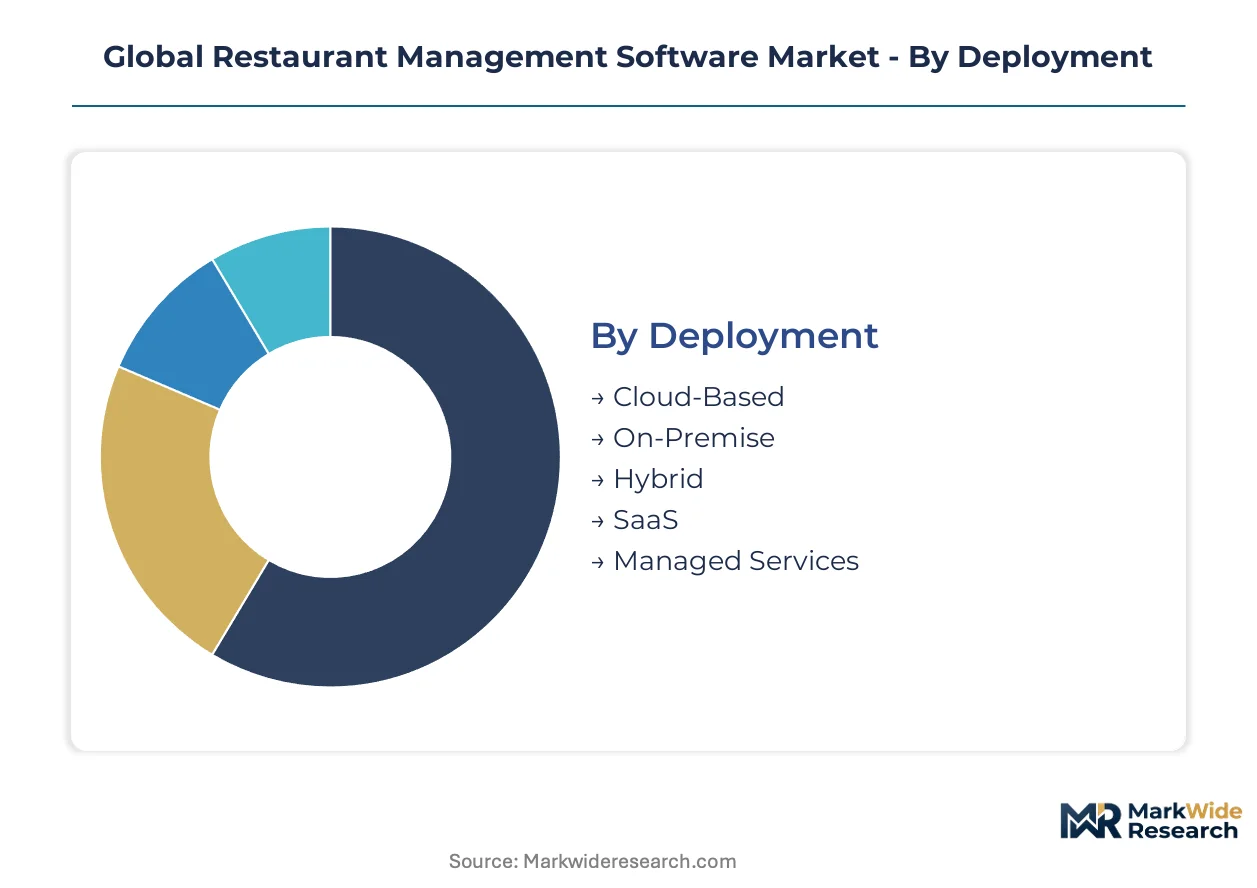
Deployment architecture determines total cost of ownership and compliance posture for restaurant operators navigating PCI-DSS certification cycles. Solution modularity and use-case specificity shape vendor switching costs across independent outlets and franchise networks.
Deployment:
Cloud-native platforms compress infrastructure overhead while hybrid architectures address data residency requirements in regulated markets.
- Cloud-Based:Multi-tenant architectures eliminate on-site server maintenance and enable centralized menu updates across dispersed locations. Demand concentrates in mid-market chains across the United States and Germany seeking real-time P&L visibility without capital expenditure.
- On-Premise:Legacy installations persist where operators require offline transaction continuity during internet outages. Operators in India and Brazil with unreliable connectivity infrastructure sustain demand despite higher total ownership costs.
- Hybrid:Edge computing nodes process transactions locally while syncing to cloud dashboards for enterprise reporting. Full-service operators in Japan and South Korea deploy this architecture to balance latency sensitivity with centralized analytics.
- SaaS:Subscription tiers tied to transaction volume and module depth create recurring revenue streams for vendors serving independent operators.
- Managed Services:Outsourced infrastructure oversight appeals to small operators lacking dedicated IT staff across fragmented European markets.
Leading the category by volume: Cloud-Based. Expanding most quickly: Hybrid.
Solution Offering:
Margin pools concentrate where modules touch payment flows and recurring interchange revenue.
- Order Management:Kitchen display system integration and tableside terminal orchestration compress ticket transmission latency. Quick-service chains in the United States deploy these modules to accelerate drive-thru throughput during peak hours.
- Payment Processing:Embedded interchange economics tighten merchant retention and expand addressable market for hardware-software bundles. PCI-DSS Level 1 certification requirements filter vendor viability across this concentrated margin pool.
- Inventory Control:Automated par-level alerts and vendor integration reduce food waste in full-service kitchens.
- Customer Relationship Management:Loyalty program architecture faces GDPR Article 22 constraints on automated profiling in European deployments.
- Staff Scheduling:EU AI Act algorithmic accountability requirements accelerate replacement cycles for legacy labor optimization tools.
- Reporting & Analytics:Real-time P&L visibility commands premium pricing from private-equity-backed restaurant groups negotiating enterprise contracts.
Capturing the deepest margins: Payment Processing. Gaining adoption fastest: Reporting & Analytics.
Use Case:
Throughput velocity and table-turn economics dictate module requirements and hardware durability specifications.
- Quick Service Restaurants:Drive-thru voice-ordering integration and kitchen automation modules address labor scarcity. Chains across the United States and Australia deploy edge computing nodes to eliminate cloud latency during rush periods.
- Fine Dining:Tableside handheld terminals enable suggestive selling prompts that lift average check sizes. Full-service operators in France and Italy prioritize reservation system integration and wine cellar inventory tracking.
- Cafés & Bistros:Compact footprint requirements favor tablet-based systems with minimal kitchen display hardware.
- Food Trucks:Mobile connectivity dependencies favor offline-capable payment terminals with cellular backup.
- Catering Services:Event-based volume spikes demand scalable cloud capacity without permanent infrastructure investment.
- Food Courts:Shared kitchen infrastructure requires vendor-agnostic API interoperability for multi-tenant environments.
Dominating procurement volume: Quick Service Restaurants. Steepest expansion trajectory: Food Trucks.
End User:
Procurement concentration and contract scale separate enterprise-grade reliability requirements from price-sensitive independent demand.
- Restaurant Chains:Consolidated procurement through multi-unit operators compresses vendor switching cycles and demands unified reporting across dozens of locations. Enterprise contracts in the United States and United Kingdom carry steep volume discounts and custom integration requirements.
- Independent Outlets:Hardware-software bundles with predictable subscription pricing anchor vendor relationships for operators lacking technical staff.
- Franchise Operators:Mandatory technology standards from franchisors limit vendor selection to approved platforms with centralized menu control.
- Hotel Restaurants:Property management system integration requirements favor vendors with hospitality-specific certification.
- Event Venues:Temporary deployment models favor rental-based pricing rather than capital purchase.
- Online Food Delivery Platforms:API-first architecture demands real-time inventory synchronization with third-party aggregator systems.
Commanding the largest contract values: Restaurant Chains. Climbing the fastest: Online Food Delivery Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States operators command the largest contract values, with private-equity-backed restaurant groups driving consolidated procurement across multi-unit portfolios.
United States
Independent full-service outlets anchor hardware-software bundle demand, while quick-service chains deploy edge computing nodes to compress drive-thru latency. FDA digital health oversight shapes compliance requirements for integrated payment modules. Dallas and Atlanta clusters concentrate mid-market chain headquarters negotiating enterprise-wide contracts.
Germany
GDPR Article 22 constraints on automated decision-making force retrofitting of loyalty programs and reservation systems. EU AI Act algorithmic accountability requirements accelerate replacement cycles for legacy labor optimization tools. Berlin and Munich host the densest concentration of full-service operators adapting compliance dashboards.
United Kingdom
Multi-unit operators seek centralized menu control without on-site server maintenance, favoring cloud-native architectures. CSRD sustainability reporting mandates extend to supply chain transparency for restaurant technology vendors. London's private-equity-backed restaurant groups drive steep volume discounts in enterprise contract negotiations.
India
FSSAI mandatory electronic food safety logging creates first-mover advantage for platforms integrating temperature monitoring. Cloud-native deployment accelerates among mid-market chains in Mumbai and Bangalore seeking real-time P&L visibility. Hyderabad's technology corridor hosts emerging vendor development for compliance-integrated modules.
Japan
Full-service operators deploy hybrid architectures to balance latency sensitivity with centralized analytics. METI digital transformation incentives support SME migration from legacy on-premise systems. Tokyo and Osaka clusters concentrate fine-dining reservation system integration with kitchen display hardware.
Global Restaurant Management Software Market Competitive Landscape
Embedded payment economics dominates the current landscape, with interchange revenue sharing models tightening merchant retention across integrated hardware-software bundles. The vendor base stratifies into three tiers: enterprise-grade reliability providers, mid-market cloud-native platforms, and price-sensitive tablet-based systems. Strategic archetypes include payment-integrated hardware bundlers, API-first modular specialists, and legacy on-premise incumbents defending installed bases. M&A activity and portfolio diversification represent the dominant competitive moves as vendors seek to span order management, payment processing, and kitchen automation modules.
Within the payment-integrated tier, Toast, Inc. and Block, Inc. exemplify the hardware-software bundle archetype anchoring independent operator relationships. Oracle Corporation occupies the enterprise-grade position serving global franchise operators with complex multi-location reporting requirements. These three entities represent the spectrum from mid-market subscription models to consolidated procurement contracts, with each archetype responding differently to PCI-DSS certification timelines and legacy system integration friction.
| Leading Market Players |
|---|
| Toast, Inc. |
| Block, Inc. |
| Oracle Corporation |
| NCR Corporation |
| Lightspeed Commerce Inc. |
| TouchBistro |
| Revel Systems |
| PAR Technology Corporation |
| OpenTable, Inc. |
| Others |
Supply & Pricing Matrix
Cloud-native software engineering talent concentrates in Bangalore and Hyderabad, compressing development cost differentials between premium enterprise suites and mid-market SaaS tiers across the global market.
Pricing Analysis
Volume concentrates in subscription-based SaaS tiers while margin pools accrue to payment-integrated hardware bundles. Three-tier pricing structure across premium, standard, and economy levels separates PCI-DSS Level 1 certified platforms from uncertified tablet-based alternatives. Price differentiation hinges on certification grade and after-sales service depth. Cost compression in the economy tier is intensifying because white-label payment apps capture price-sensitive independent operators.
Supply Chain Analysis
Semiconductor supply for payment terminals rests on Taiwanese foundries and South Korean memory producers. Proprietary kitchen display hardware draws from Chinese contract manufacturers and Mexican final assembly operations. Single-source vulnerability in advanced processor nodes threatens hardware bundle delivery timelines. Distribution runs through authorized reseller networks and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a technology-transition phase as cloud-native architectures displace legacy on-premise installations across multi-unit operators.
For Market Incumbents: Deepen API interoperability investments to defend against middleware fragmentation costs that erode switching barriers. Anchor enterprise relationships through centralized menu management and real-time P&L visibility tools. Expand PCI-DSS certification maintenance as a retention lever against emerging cloud-native challengers. For New Entrants and Emerging Players: Food truck operators represent an underserved buyer archetype with escalating mobile connectivity needs and minimal incumbent penetration. Target India's FSSAI compliance-integrated modules where mandatory electronic food safety logging creates first-mover white space. Pursue channel partnerships with cellular hardware distributors for offline-capable terminal deployment. For Investors and Strategic Acquirers: Re-rating potential sits with API-first modular specialists given EU AI Act algorithmic accountability requirements accelerating legacy replacement cycles. Long-term viability favors platforms spanning order management, payment processing, and kitchen automation modules. Watch PCI-DSS certification timeline compression as an inflection indicator for vendor viability filtering.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified order-to-payment workflows tighten merchant retention against fragmented point solutions. |
| Acquisition of Specialist Firm | Voice-ordering NLP capabilities accelerate drive-thru automation for quick-service chains. |
| Strategic Partnership | Third-party aggregator API connections expand addressable market for online food delivery platforms. |
| Geographic Expansion | FSSAI compliance module deployment captures India's mandatory food safety digitization mandate. |
| Product Launch | Edge computing kitchen nodes eliminate cloud latency during peak throughput hours. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with restaurant technology CTOs, IT procurement officers at multi-unit chains, platform integration specialists, and channel partners combined with secondary validation. FDA digital health guidance, EU AI Act implementation documents, PCI-DSS certification databases, and SEC filings from publicly traded vendors supplied bottom-up and top-down triangulation.
Data-stream reconciliation across deployment architecture, solution modularity, and end-user procurement scale shaped the analytical framework. Segmentation dimensions modeled include deployment model, organization size, use-case throughput velocity, and regional regulatory cluster. CAGRs were derived from volume-weighted trajectory analysis. Forecast inputs incorporated cloud migration velocity and interchange revenue sharing adoption curves.
Revisions become necessary when semiconductor supply constraints intensify, regulatory certification timelines extend, or white-label substitution accelerates beyond modeled thresholds. Forecasts reflect assumptions about cloud infrastructure reliability and payment network interoperability. A small set of triggers—tariff exposure on hardware components, PCI-DSS audit backlog, and API standardization delays—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
3D Printing Medical Device Software Market
Software & Services
Search and Discovery Software Market
Software & Services
RIP Software Market
Software & Services
Mobile Backend As a Service (Mbaas) Market
Software & Services
Japan IT Services Market
Software & Services
Global Demand Planning Software Market
Software & Services
Global Note Taking App Market
Software & Services
Cloud Business Process Management (BPM) Software Market
Software & Services
Global Retail Execution Software Market
Software & Services
Application Development and Modernization (ADM) Market
Software & Services
Global Decision Support Software Market
Software & Services
Data Exchange Platform Services Market
Software & Services
Predictive Dialer Software Market
Software & Services
Latin America ERP Software Market
Software & Services
Global Disclosure Management Software Market
Software & Services
Global Rapid Application Development Market