
 Europe Digital Pen Market | 2026-2036
Europe Digital Pen Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Digital Pen Market Analytics
Premium pressure-sensitivity tier is collapsing into the mid-range as electromagnetic and capacitive technologies achieve parity at lower price points. Wacom Co Ltd leverages its heritage in electromagnetic digitizer architecture to sustain margins in professional art and design segments. Apple Inc anchors consumer expectations through tight stylus-tablet integration. Microsoft Corporation competes aggressively within enterprise productivity workflows.
A digital pen is an active or passive input device that captures handwriting, sketching, or gestural commands through embedded sensors—pressure levels, tilt angles, and positional coordinates—and transmits data to computing endpoints for digitization, storage, or real-time processing. The technology serves commercial purposes spanning document annotation, creative production, remote collaboration, and accessibility interfaces. Stylus pens and smart pens currently lead volume shipments across Europe, while Bluetooth pens represent the fastest-expanding connectivity layer as cross-device pairing protocols standardize. Electromagnetic technology dominates professional-grade margin pools, whereas capacitive variants occupy broader consumer price bands.
CE marking obligations under the EU Radio Equipment Directive constrain wireless-enabled digital pen launches, while REACH compliance governs material composition in pen housings and circuit assemblies. ECHA substance restrictions are forcing reformulation of certain polymer and coating inputs. GDPR implications shape how handwriting biometric data captured by smart pens may be stored and processed across European jurisdictions. Stakeholders must monitor evolving EU AI Act implementation guidance for features incorporating real-time handwriting recognition and predictive input algorithms.
Market Dynamics
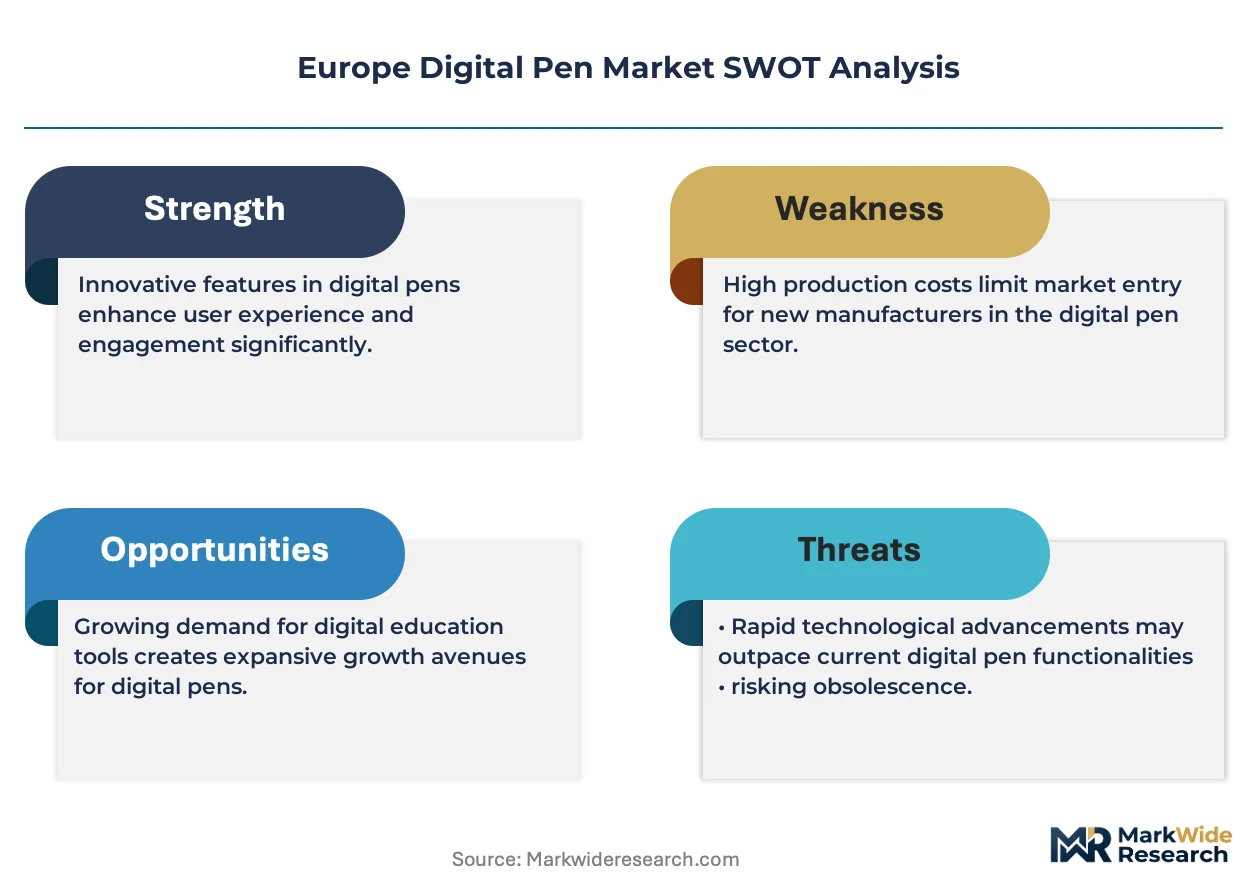
The EU AI Act's handwriting recognition provisions and updated Medical Device Regulation CE pathways are forcing hardware vendors to revalidate firmware architectures and biometric data handling protocols before market entry.
Growth Catalysts
- Healthcare digitization mandates:European hospitals are expanding electronic health record systems that require stylus-compatible clinical documentation interfaces, with procurement concentrated in Germany, France, and the United Kingdom.
- REACH compliance reformulation:ECHA substance restrictions on polymer and coating inputs are accelerating supplier transitions to compliant material alternatives, creating first-mover advantages for reformulated product lines.
- Cross-device Bluetooth standardization:Universal pairing protocols are eliminating proprietary dongle requirements, reducing friction for multi-tablet enterprise deployments in education and field services.
Market Restraints
- Electromagnetic sensor supply concentration:Professional-grade digitizer component sourcing clusters in East Asian manufacturing hubs, exposing European assemblers to geopolitical logistics volatility.
- CE marking timeline friction:EU Radio Equipment Directive certification cycles for wireless-enabled pens extend launch windows by four to eight months versus non-connected variants.
- Capacitive stylus commoditization:Passive rubber-tip substitutes priced at sub-premium tiers capture price-sensitive consumer segments, compressing margin pools for active pen vendors.
Strategic Opportunities
- Nordic education procurement:Sweden, Norway, and Finland are expanding national tablet-stylus programs for primary and secondary institutions, with multi-year framework agreements open to competitive bidding.
- GDPR-compliant biometric storage:On-device handwriting pattern processing without cloud transmission satisfies data sovereignty requirements for financial services and legal sector buyers.
- AI Act algorithmic transparency:Predictive text and handwriting recognition modules that document training data provenance gain preferential positioning in public sector tenders.
Industry Challenges
- Firmware security certification backlog:Common Criteria evaluation facilities face queue congestion for stylus-integrated secure elements, delaying enterprise credentialing.
- Legacy EMR integration complexity:Hospital information systems built on decade-old architectures require custom middleware development for pressure-sensitivity data capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Digital Pen Market |
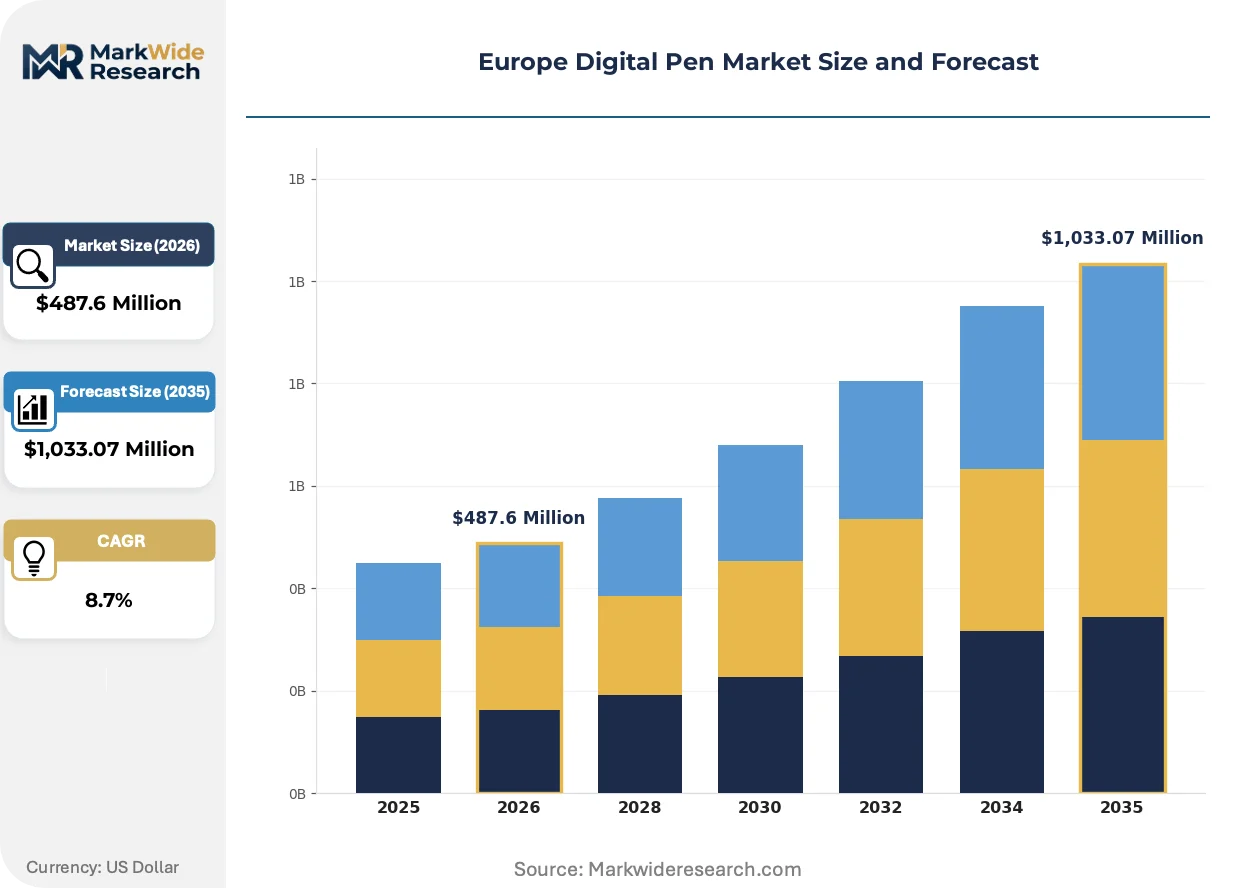
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bluetooth Pens, Smart Pens, Stylus Pens, Digital Notepads Application: Education, Art & Design, Business, Personal Use End User: Students, Professionals, Artists, Hobbyists Technology: Capacitive, Electromagnetic, Optical, Acoustic |
| Companies Covered | Wacom Co Ltd, Apple Inc, Microsoft Corporation, Livescribe, Samsung Electronics Co., Ltd., Logitech International S.A., NeoLAB Convergence Inc., Anoto Group AB, HP Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Digital Pen Market Evolving Landscape
Active pen architecture is splitting into two performance tiers as electromagnetic and capacitive technologies achieve functional parity at divergent price points, while regulatory pressure on biometric data handling reshapes firmware development priorities.
Electromagnetic resonance digitizer technology is bifurcating the professional segment from consumer markets. Wacom Co Ltd and specialist vendors retain architecture control for pressure-level precision above 4,096 levels, while mid-range electromagnetic implementations from Asian component suppliers penetrate the $80-$150 price band previously occupied by premium capacitive alternatives. This compression is collapsing the historical three-tier market structure into a dual-track configuration where professional art and design workflows sustain electromagnetic margins, while enterprise productivity and education procurement gravitate toward standardized capacitive protocols.
GDPR Article 9 special category provisions and the EU AI Act's biometric identification rules are mandating on-device processing for handwriting pattern analysis. Vendors must architect neural inference engines that execute entirely within pen-local or tablet-local memory, eliminating cloud transmission of gestural biometric templates. Healthcare and financial services procurement specifications in Germany and France now require explicit documentation of data residency boundaries, with non-compliant products excluded from public tender shortlists.
Enterprise buying committees are consolidating stylus procurement within broader device lifecycle contracts. Channel partners in the United Kingdom and Netherlands are bundling three-year stylus replacement programs with tablet refresh cycles, displacing transactional retail purchases. This servitization concentrates volume with distributors capable of inventory financing and field service logistics, marginalizing pure-play stylus vendors without enterprise IT channel relationships.
Europe Digital Pen Market Segmentation
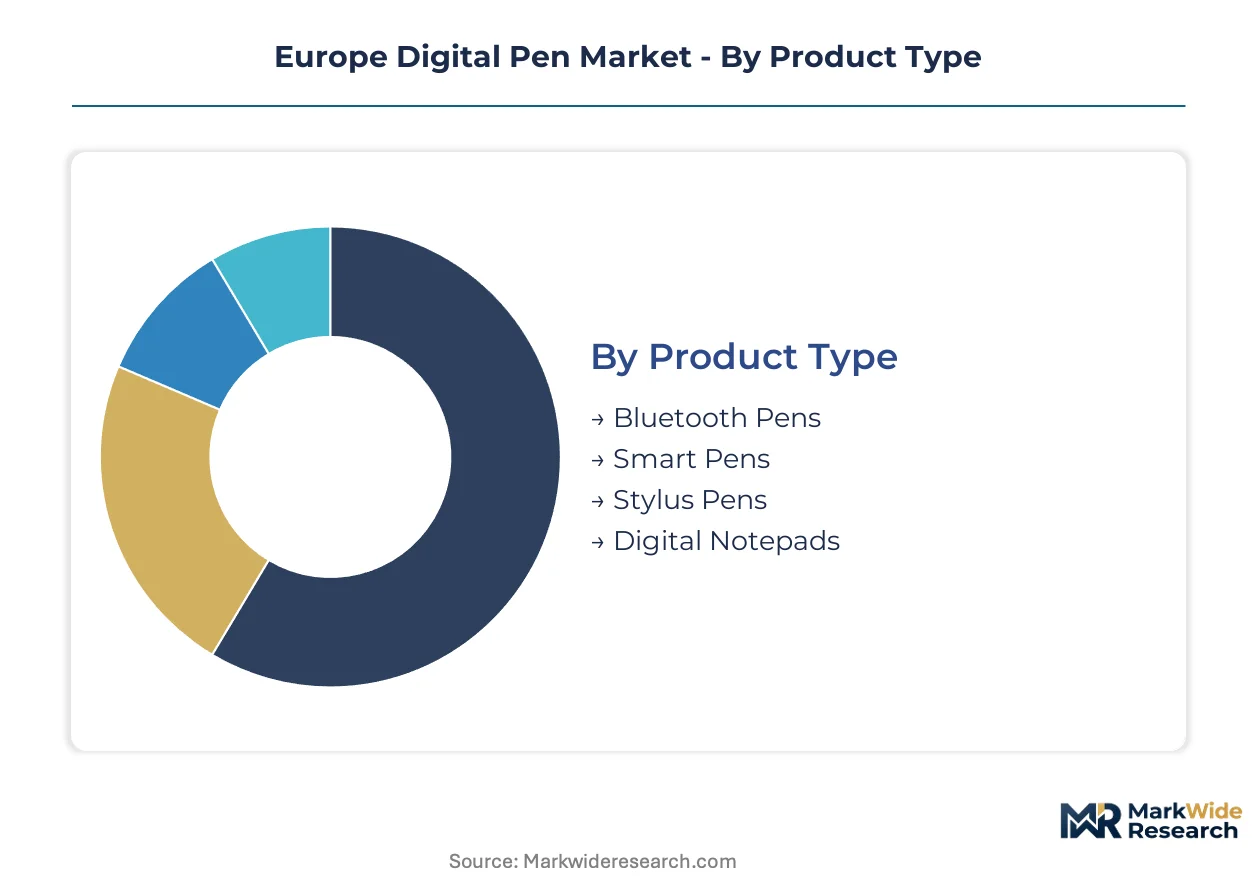
Digital pen procurement across Europe fragments along four distinct axes that determine regulatory exposure, margin capture, and channel strategy. CE marking pathways under the Radio Equipment Directive vary sharply by connectivity layer, while end-user concentration in German healthcare and Nordic education creates divergent volume pools.
Product Type:
CE marking obligations under the EU Radio Equipment Directive create tiered compliance burdens that reshape competitive positioning across hardware categories.
- Bluetooth Pens:Wireless-enabled devices incorporating Bluetooth Low Energy chipsets transmit handwritten data to paired tablets and smartphones. Procurement from United Kingdom enterprise buyers is accelerating as universal pairing protocols eliminate proprietary dongle dependencies. GDPR Article 9 biometric handling requirements are forcing on-device processing architectures that extend firmware development cycles.
- Smart Pens:Embedded camera systems and internal storage capture handwriting on proprietary or standard paper formats for subsequent digitization. German hospital information systems are expanding pilot deployments for clinical documentation workflows that integrate with electronic health record platforms. REACH compliance for polymer housings adds material reformulation costs that compress margins at volume price points.
- Stylus Pens:Passive capacitive or active electromagnetic input devices deliver positional and pressure data to host tablets without independent processing capability.
- Digital Notepads:Integrated display-and-stylus systems combining capture surface with embedded digitizer technology in a single hardware unit.
Established volume favors Stylus Pens; emerging adoption favors Bluetooth Pens.
Application:
End-use concentration in regulated sectors creates divergent margin profiles that separate enterprise procurement from consumer retail channels.
- Education:Primary and secondary institutions across Sweden, Norway, and Finland are expanding national tablet-stylus programs with multi-year framework agreements. Nordic procurement specifications prioritize cross-device compatibility and total cost of ownership over pressure-sensitivity specifications. Channel partners bundle three-year replacement cycles with device refresh programs, concentrating volume with distributors capable of inventory financing.
- Art & Design:Professional creative workflows demand pressure levels exceeding 4,096 levels and tilt-angle precision that electromagnetic architectures deliver. France and Germany host the densest concentrations of professional studios and design agencies, sustaining premium pricing tiers that resist capacitive commoditization.
- Business:Enterprise productivity deployments span document annotation, remote collaboration, and presentation workflows.
- Personal Use:Individual consumers purchase through retail channels for note-taking, journaling, and casual creative applications.
Margin concentration sits with Art & Design; volume expansion is climbing the fastest in Education.
End User:
User sophistication levels determine feature requirements and willingness to absorb premium pricing for advanced specifications.
- Students:Price-sensitive demand concentrated in compulsory education procurement frameworks across Nordic and German federal states. Volume buyers prioritize durability and standardization over advanced pressure sensitivity.
- Professionals:Enterprise employees in healthcare, financial services, and legal sectors require GDPR-compliant data handling and EMR integration capabilities.
- Artists:Professional and semi-professional creators sustain electromagnetic digitizer demand through specification requirements that capacitive alternatives cannot satisfy.
- Hobbyists:Enthusiast consumers exhibit price elasticity that passive rubber-tip substitutes exploit.
Procurement concentration favors Students; margin sustainability favors Artists.
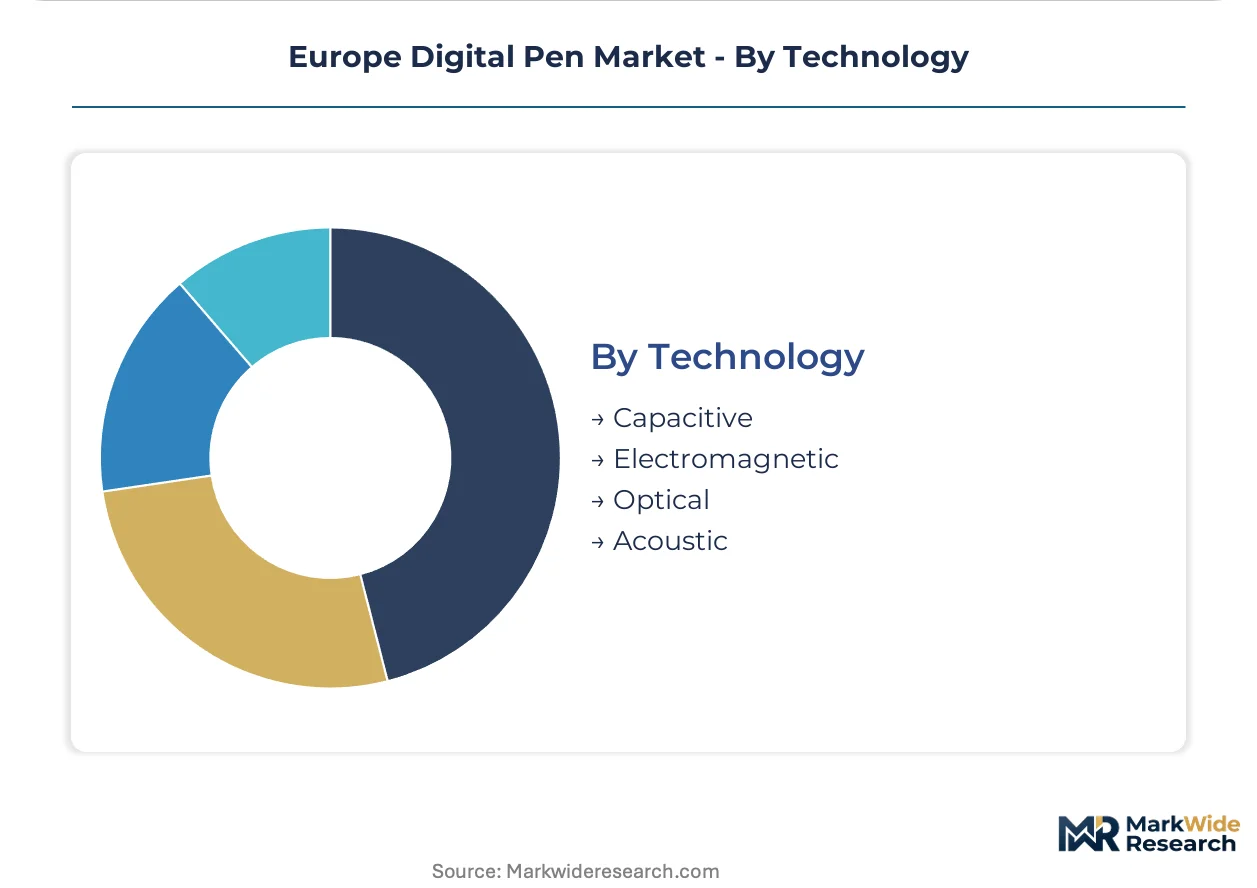
Technology:
Sensor architecture determines performance ceilings, supply chain exposure, and regulatory certification complexity for European market entry.
- Electromagnetic:Resonance-coupled digitizer systems deliver sub-millimeter positional accuracy and pressure levels above 4,096 levels through inductive coil arrays. Component sourcing clusters in East Asian manufacturing hubs expose European assemblers to logistics volatility. Professional art and healthcare documentation applications in Germany and France sustain margin pools that resist mid-range encroachment.
- Capacitive:Electrical field disruption detection enables broad device compatibility without dedicated digitizer layers. Nordic education procurement and United Kingdom enterprise deployments are gravitating toward standardized protocols that reduce vendor lock-in. Passive rubber-tip alternatives priced at sub-premium tiers compress active pen margins in consumer segments.
- Optical:Camera-based pattern recognition captures handwriting through visual analysis of surface textures or printed positional codes.
- Acoustic:Ultrasonic triangulation calculates pen position through time-of-flight measurement from embedded microphones.
Professional-grade performance favors Electromagnetic; volume scalability favors Capacitive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's digital pen trade flows reflect a structural deficit in electromagnetic sensor components, with finished device exports from Germany and France offset by East Asian digitizer imports. Regulatory divergence between EU member states fragments procurement standards despite harmonized CE marking frameworks.
Germany
Hospital information systems in Bavaria and North Rhine-Westphalia drive enterprise-grade stylus procurement for electronic health record integration. The Medical Device Regulation's updated CE pathways under BfArM guidance extend certification timelines for Bluetooth-enabled clinical documentation tools. Berlin-Brandenburg hosts dense clusters of health-tech integrators developing middleware for pressure-sensitive EMR capture.
United Kingdom
NHS digitization programs and enterprise productivity deployments sustain cross-device stylus demand across London and the Southeast. GDPR Article 9 compliance requirements from the Information Commissioner's Office mandate on-device biometric processing for handwriting recognition features. Midlands-based distributors bundle three-year replacement cycles with tablet refresh programs, concentrating procurement volume.
France
Professional design studios in Île-de-France and Auvergne-Rhône-Alpes sustain premium electromagnetic digitizer demand for creative workflows. ANSM guidance on software-as-medical-device classifications intersects with CNIL biometric data enforcement, complicating smart pen launches for healthcare applications. Paris hosts regional headquarters for major vendors targeting continental procurement frameworks.
Sweden
National tablet-stylus programs for primary and secondary education drive standardized capacitive pen procurement across Stockholm and surrounding counties. The Swedish Medical Products Agency's interpretation of MDR software provisions affects smart pen classification for clinical use. Nordic framework agreements prioritize cross-device compatibility and total cost of ownership over pressure-sensitivity specifications.
Netherlands
Randstad-based enterprise buyers consolidate stylus procurement within broader device lifecycle contracts for field services and logistics workflows. The Dutch Authority for Consumers and Markets enforces REACH compliance documentation for polymer housings and circuit assemblies. Eindhoven Region distributors leverage inventory financing capabilities to capture education and healthcare framework volumes.
Europe Digital Pen Market Competitive Landscape
Listed leaders compete with private specialists across electromagnetic architecture control, with public companies leveraging capital markets for R&D scale while private vendors retain niche positioning. The vendor base clusters around three performance tiers: premium electromagnetic specialists, mid-range protocol standardizers, and commoditized passive tip suppliers. Strategic archetypes include heritage digitizer architects, consumer electronics platforms, and enterprise productivity integrators. Competitive moves center on firmware security certification acceleration and channel partnership consolidation with IT distributors.
Within the heritage architecture tier, Wacom Co Ltd and Anoto Group AB exemplify electromagnetic resonance specialists with decades of digitizer development lineage. Microsoft Corporation and Apple Inc represent platform-integrated vendors leveraging ecosystem lock-in for enterprise and consumer segments respectively. Samsung Electronics Co., Ltd. occupies a position bridging component supply and finished device integration. These anchors illustrate how competitive positioning depends on controlling sensor architecture, platform integration depth, or volume manufacturing scale rather than any single capability alone.
| Leading Market Players |
|---|
| Wacom Co Ltd |
| Apple Inc |
| Microsoft Corporation |
| Livescribe |
| Samsung Electronics Co., Ltd. |
| Logitech International S.A. |
| NeoLAB Convergence Inc. |
| Anoto Group AB |
| HP Inc. |
| Others |
Value Network & Pricing Analysis
Capacitive sensor substitution for electromagnetic digitizer components is simultaneously shifting procurement geography toward Taiwanese and South Korean foundries and compressing unit economics across mid-range product tiers. This input transition enables European assemblers to bypass concentrated East Asian electromagnetic coil sourcing while triggering price convergence between previously distinct performance bands.
Pricing Analysis
Enterprise IT buyers anchor pricing stratification across premium electromagnetic, mid-range active capacitive, and economy passive tip tiers. CE marking tier under the EU Radio Equipment Directive and pressure-sensitivity specification serve as primary price differentiation drivers. Cost compression in the mid-range capacitive segment is intensifying because Asian component suppliers achieve functional parity at lower bill-of-materials costs. Students and compulsory education procurement committees exhibit highest price sensitivity, while professional artists and healthcare documentation specialists absorb premium electromagnetic pricing without volume elasticity.
Supply Chain Analysis
Container availability fluctuations on the Asia-North Europe trade lane periodically extend inbound component lead times for Bluetooth chipset and digitizer module deliveries. Electromagnetic sensor fabrication concentrates in Taiwan, South Korea, and Japan, while capacitive controller assembly clusters in mainland China and Vietnam. Raw material dependencies span indium tin oxide for transparent conductors, rare-earth magnets for resonance coils, and lithium polymer for onboard power storage. Single-source vulnerability in electromagnetic digitizer substrates exposes European device assemblers to geopolitical logistics disruption. Distribution runs through Netherlands-based IT distributors and German medical device channel partners serving hospital procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe digital pen market sits at a post-pandemic replacement cycle recovery phase justified by NHS and Nordic education tablet refresh programs accelerating hardware procurement. Cyclical enterprise IT spending normalization supports volume expansion across enterprise productivity and clinical documentation segments.
For Market Incumbents: Shield premium electromagnetic margin pools by accelerating CE marking certification under updated MDR guidance before mid-range capacitive alternatives achieve clinical workflow parity. Deepen backward integration into secure element firmware development to reduce Common Criteria evaluation queue exposure. Channel control through three-year replacement program bundling with Dutch and UK distributors defends against pure-play stylus vendor price aggression.
For New Entrants and Emerging Players: GDPR-compliant on-device handwriting processing without cloud transmission represents a service-layer gap where incumbents under-serve financial services and legal sector buyers. Target Swedish and Finnish education framework agreements with cross-device compatible capacitive pens priced below Wacom and Apple ecosystem premiums. Go-to-market execution through Nordic IT distributors with inventory financing capabilities bypasses direct enterprise sales force requirements.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors electromagnetic architecture specialists with health-tech channel relationships and MDR certification track records. Long-term viability over the next decade hinges on AI Act algorithmic transparency compliance for handwriting recognition modules. Acquisition target archetype: private specialist vendors with BfArM-cleared Bluetooth pen platforms and Berlin-based health-tech integrator partnerships. Signal to watch: NHS Digital procurement specification releases for pressure-sensitive EMR documentation tools.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR CE Marking Pathway Acceleration | BfArM-cleared Bluetooth pens gain preferential positioning in German hospital tenders ahead of regulatory backlog resolution. |
| On-Device Biometric Processing Architecture | GDPR Article 9-compliant neural inference engines satisfy CNIL enforcement without cloud transmission infrastructure. |
| Nordic Education Framework Capture | Swedish national tablet-stylus program volumes concentrate procurement with distributors offering inventory financing. |
| Secure Element Firmware Certification | Common Criteria evaluation completion differentiates enterprise credentialing capabilities against uncertified competitors. |
| Health-Tech Channel Partnership Consolidation | Berlin-Brandenburg integrator relationships unlock middleware development for legacy EMR pressure-sensitivity integration. |
Research Methodology
Operator-level perspectives from hospital biomedical engineers, IT procurement officers at NHS trusts, Nordic education framework managers, health-tech integration specialists, and distributor channel partners anchored the qualitative base. Primary interview insights combined with secondary validation from EMA MDR guidance documents, BfArM software-as-medical-device classifications, NHS Digital procurement databases, and ECHA REACH substance restriction updates. Bottom-up volume modeling across product type, application, and technology segments triangulated against top-down European electronics trade flow analysis.
Sensitivity analysis tested forecast robustness across alternative Bluetooth adoption trajectories and electromagnetic sensor supply disruption scenarios. Segmentation dimensions modeled encompass connectivity protocol, end-use sector, pressure-sensitivity tier, and national procurement framework alignment across the projection horizon. CAGRs derived from historical shipment correlations with tablet refresh cycles and healthcare digitization mandate implementation timelines. Industry-specific inputs include NHS Long Term Plan deployment schedules and Swedish National Agency for Education hardware standardization roadmaps.
Underlying assumptions cover sustained NHS funding for digital documentation tools, stable Asia-Europe container shipping capacity, and gradual EU AI Act implementation guidance clarification, with deviation risk concentrated in electromagnetic component sourcing geopolitics and MDR certification timeline extensions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Model Based Enterprise Market
Digital Solutions
North America Product Design and Development Services Market
Digital Solutions
Global Space Planning Software Market
Digital Solutions
Mock Interview Platforms Market
Digital Solutions
Virtual Client Computing Market
Digital Solutions
Utility App Market
Digital Solutions
Global Network Engineering Service Market
Digital Solutions
Global Asset Reliability Software Market
Digital Solutions
Middle East Smart Card Market
Digital Solutions
Customer-To-Customer (C2C) Community Market
Digital Solutions
Morocco ICT Market
Digital Solutions
AI Infrastructure Solutions Market
Digital Solutions
Latin America IT Market
Digital Solutions
Global Logistics Software Market
Digital Solutions
United States Contract Manufacturing Services Market
Digital Solutions
Location As a Service Market