
 Global Vitamin Supplements Market | 2026-2036
Global Vitamin Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vitamin Supplements Market Foresight
ISO 22000 certification is bifurcating the competitive landscape into qualified mass manufacturers and excluded fringe suppliers. Nestlé leverages its vertically integrated supply chain to control ingredient sourcing from farm to finished tablet. Bayer AG sustains competitive position through pharmaceutical-grade manufacturing protocols originally developed for its drug operations.
Vitamin supplements encompass single-nutrient and multi-nutrient formulations synthesized or extracted for oral consumption, typically containing active compounds such as retinol, ascorbic acid, or cholecalciferol in standardized international unit dosages for physiological supplementation. These products serve industrial purposes ranging from deficiency correction in clinical settings to preventive wellness in consumer self-care regimes. Multivitamins dominate volume due to convenience-driven purchasing, while Vitamin D commands premium positioning following expanded clinical recognition of insufficiency prevalence. Softgel and liquid forms capture accelerating share as bioavailability concerns drive consumers away from compressed tablet matrices.
FDA's Current Good Manufacturing Practice regulations, the EU's Food Supplements Directive, and India's FSSAI standards collectively enforce potency accuracy, contaminant limits, and label claim substantiation across major supply jurisdictions. Compliance costs favor scaled operators with dedicated regulatory affairs departments over emerging market entrants. Stakeholders must monitor evolving probiotic-vitamin combination classifications as regulators reconsider whether synbiotic formulations belong under food supplement or novel food frameworks.
Market Dynamics
ISO 22000 certification requirements are bifurcating the competitive landscape into qualified mass manufacturers and excluded fringe suppliers, reshaping procurement patterns across pharmaceutical and consumer health channels.
Growth Catalysts
- Sports nutrition end-use expansion:Athletes and active consumers prioritize performance-oriented micronutrient protocols, driving specialized formulation demand.
- Emerging middle-class preventive spending:China, India, and Brazil concentrate demand growth as consumers expand health expenditure beyond deficiency correction.
- EFSA substantiation frameworks:The EU's Nutrition and Health Claims Regulation tightens label claim requirements, elevating clinically validated products above commodity alternatives.
Market Restraints
- Active compound input volatility:Retinol and cholecalciferol feedstock prices fluctuate with petrochemical and agricultural commodity cycles, compressing margin predictability.
- Regulatory friction from dual classification:Synbiotic formulations face uncertainty between food supplement and novel food frameworks, delaying product launches.
- Compressed tablet substitution threat:Softgel and liquid bioavailability advantages are displacing traditional matrices, stranding legacy manufacturing assets.
Strategic Opportunities
- Brazilian preventive health penetration:Underdeveloped professional recommendation channels present whitespace for pharmacy-led vitamin protocols.
- Liposomal delivery convergence:Nanotechnology integration with standard vitamin synthesis enables premium positioning in clinical nutrition segments.
- Direct-to-practitioner channel innovation:Functional medicine networks bypass retail intermediaries, capturing higher-margin professional-grade sales.
Industry Challenges
- ISO 22000 certification timeline compression:Emerging market entrants face extended compliance periods that delay market access against scaled competitors.
- Regulatory affairs talent scarcity:Cross-jurisdictional expertise spanning FDA, EFSA, and FSSAI frameworks commands premium compensation, constraining mid-tier hiring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vitamin Supplements Market |
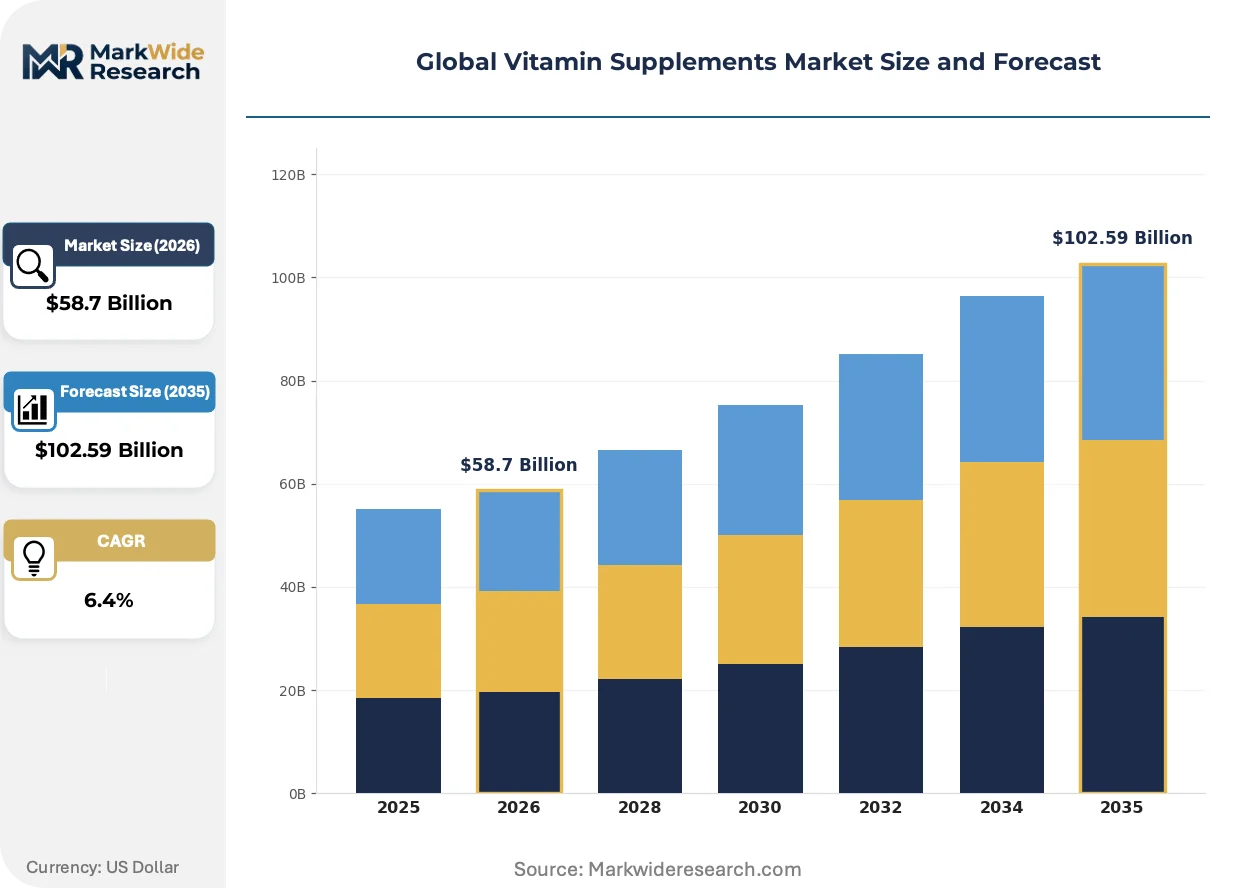
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $102.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multivitamins, Vitamin D, Vitamin C, Vitamin B Complex, Vitamin E, Folic Acid Form: Tablet, Capsule, Powder, Liquid, Softgel, Chewable Application: Child Nutrition, Adult Wellness, Sports Nutrition, Prenatal Care, Geriatric Health, Immune Support Customer Type: Health Enthusiasts, Fitness Centers, Wellness Clinics, Pharmacies, E-commerce Platforms |
| Companies Covered | Nestlé, Abbott, Amway Corp, Bayer AG, Glanbia PLC, Herbalife Nutrition, Pfizer Inc., Otsuka Holdings Co., Ltd, GNC Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vitamin Supplements Market Shifts & Advancements
Liposomal encapsulation technology is reshaping bioavailability standards across premium segments, while regulatory convergence and channel disintermediation simultaneously compress traditional competitive advantages.
Liposomal vitamin delivery systems enhance cellular absorption rates through phospholipid bilayer protection. Sports nutrition formulators and clinical nutrition specialists adopt these technologies fastest. Conventional tablet and softgel formats are displacing commodity positioning in performance-oriented consumer segments.
EFSA's evolving guidance on health claim substantiation tightens clinical evidence requirements for immune and cognitive function claims. Manufacturers must redesign label architectures and reformulate marketing strategies. Multivitamin and Vitamin D categories face the steepest compliance recalibration across European markets.
Subscription-based replenishment models bypass traditional retail pharmacy and mass-market channels. Direct-to-consumer platforms capture recurring revenue from wellness-focused demographics. This behavioral shift concentrates most visibly in North American and Western European urban consumer clusters with established e-commerce infrastructure.
Global Vitamin Supplements Market Segmentation
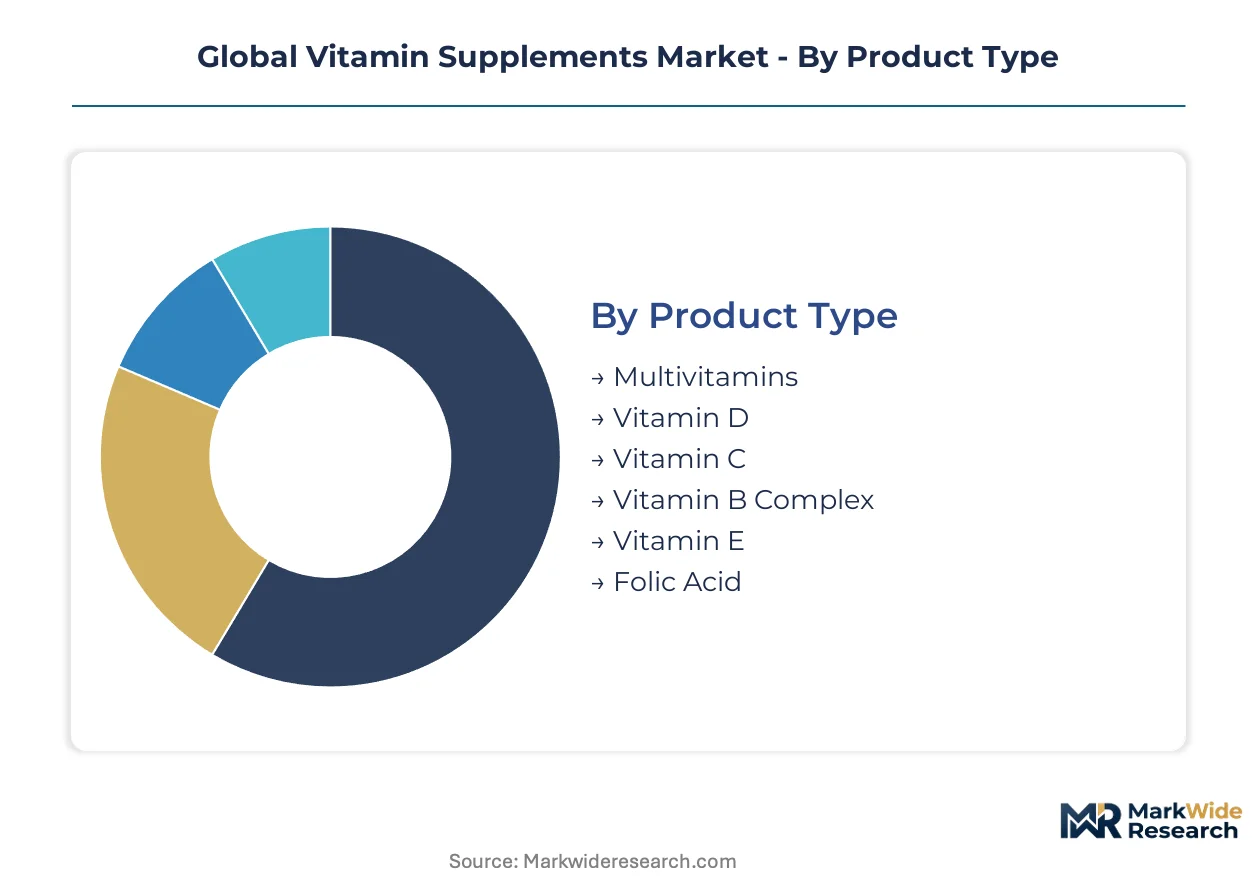
Vitamin supplement segmentation reveals distinct procurement patterns across consumer self-care and clinical nutrition channels. Product form and application context determine pricing architecture, while customer type distribution shapes regional go-to-market requirements.
Product Type:
Domestic manufacturing dominates multivitamin and B complex production, while Vitamin D and specialty isolates concentrate in export-led supply corridors serving European and North American markets.
- Multivitamins:Broad-spectrum formulations combine retinol, ascorbic acid, tocopherol, and B-complex compounds in standardized ratios. Demand concentrates in adult wellness and geriatric applications across Brazil, India, and China as middle-class consumers adopt preventive protocols. Convenience-driven purchasing sustains volume leadership despite margin compression from commoditization.
- Vitamin D:Cholecalciferol and ergocalciferol isolates address documented insufficiency prevalence in clinical and consumer settings. European markets under EFSA substantiation frameworks drive premium positioning for cholecalciferol variants with verified bioavailability claims. Sports nutrition and immune support applications command formulation premiums.
- Vitamin C:Ascorbic acid in immediate and sustained-release matrices serves antioxidant and immune protocols.
- Vitamin B Complex:Thiamine, riboflavin, niacin, and cobalamin combinations target energy metabolism and neurological function.
- Vitamin E:Tocopherol isolates and mixed tocopherols address oxidative stress management in dermatological and cardiovascular applications.
- Folic Acid:Synthetic pteroylglutamic acid concentrates in prenatal care formulations with mandated fortification in multiple jurisdictions.
Multivitamins command the established base. The steepest expansion runs through Vitamin D.
Form:
Tablet and capsule production localizes near raw material synthesis hubs, while liquid and softgel manufacturing clusters in markets with advanced encapsulation infrastructure serving export demand.
- Tablet:Compressed matrices using direct compression or wet granulation binders remain the cost-optimized default for mass-market distribution. Indian and Chinese manufacturers leverage API synthesis proximity to supply price-sensitive pharmacy channels across Southeast Asia and Africa.
- Softgel:Gelatin or plant-based shells encasing oil-based or suspension fills deliver enhanced bioavailability for lipid-soluble vitamins. North American and Western European consumers drive accelerating share capture as clinical nutrition specialists recommend phospholipid delivery systems.
- Capsule:Two-piece hard shells accommodate powder, granule, or pellet fills with flexible dosing adjustment.
- Liquid:Aqueous or oil-based solutions with emulsification enable pediatric and geriatric administration where swallowing barriers exist.
- Powder:Bulk active compounds or effervescent bases support compounding pharmacies and sports nutrition customization.
- Chewable:Flavored matrices with modified mouthfeel target pediatric compliance and adult preference segments.
Tablets retain volume dominance. Softgels are climbing the fastest on bioavailability differentiation.
Application:
Child nutrition and prenatal care align with domestic regulatory frameworks, while sports nutrition and immune support formulations concentrate in cross-border e-commerce and practitioner channels.
- Sports Nutrition:Performance-oriented micronutrient protocols combine Vitamin D, B complex, and antioxidants with timing-optimized delivery. Athletes and active consumers in Germany, Australia, and the United States drive specialized formulation demand through fitness center and direct-to-practitioner procurement.
- Immune Support:Vitamin C, D, and zinc combinations address post-pandemic sustained interest in respiratory resilience. Chinese and Brazilian consumers expand preventive spending beyond seasonal patterns into year-round supplementation protocols.
- Adult Wellness:General preventive supplementation targets working-age consumers with convenience-oriented multivitamin protocols.
- Prenatal Care:Folic acid, iron, and DHA combinations follow obstetric guideline adherence in regulated pharmacy distribution.
- Geriatric Health:B12, D, and calcium formulations address absorption decline and bone density maintenance in aging populations.
- Child Nutrition:Palatable formats with age-appropriate dosing support developmental requirements in pediatric segments.
Adult wellness anchors current revenue. Sports nutrition is gaining share fastest on performance positioning.
Customer Type:
Pharmacy and wellness clinic procurement remains domestically regulated, while e-commerce platforms and fitness centers operate through hybrid local-fulfillment and cross-border models.
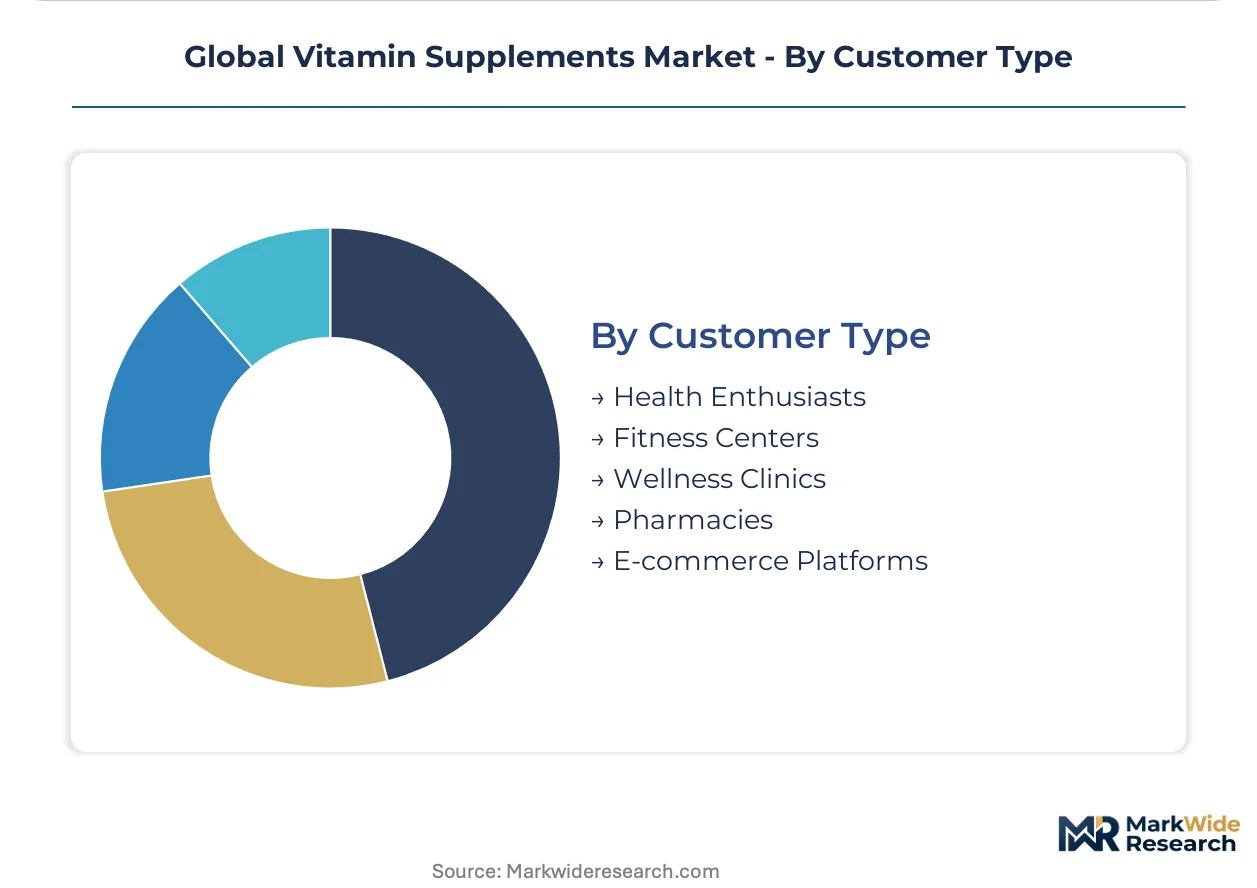
- E-commerce Platforms:Direct-to-consumer channels bypass traditional retail intermediaries through subscription replenishment and algorithmic personalization. Urban clusters in the United States, United Kingdom, and South Korea concentrate recurring revenue capture with established logistics infrastructure.
- Wellness Clinics:Functional medicine practitioners prescribe professional-grade formulations with verified potency and third-party testing. Germany, Switzerland, and Australia host dense networks capturing higher-margin sales through diagnostic-protocol integration.
- Health Enthusiasts:Self-directed consumers researching bioavailability and sourcing transparency drive premium segment demand.
- Fitness Centers:On-site retail and affiliated e-commerce extend sports nutrition reach through trainer recommendation networks.
- Pharmacies:Regulated OTC and pharmacist-recommended products serve deficiency correction and preventive care transitions.
Pharmacies retain the established base. E-commerce platforms show the steepest expansion trajectory on behavioral shift acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Preventive health spending concentrates among middle-class consumers in emerging economies, while regulatory stringency shapes mature market procurement patterns. Germany, China, India, Brazil, and the United States collectively concentrate demand growth and supply-side innovation across distinct buyer archetypes.
United States
Sports nutrition protocols drive specialized vitamin demand among athletes and fitness enthusiasts through direct-to-consumer platforms and practitioner channels. FDA Current Good Manufacturing Practice regulations enforce potency accuracy and contaminant limits across domestic manufacturing. Los Angeles and Austin host dense clusters of subscription-based wellness brands capturing recurring revenue from urban health-conscious demographics.
Germany
Functional medicine networks expand professional-grade vitamin sales through diagnostic-protocol integration and verified third-party testing. EFSA substantiation frameworks under the EU's Nutrition and Health Claims Regulation tighten clinical evidence requirements for immune and cognitive function claims. Munich and Hamburg anchor dense wellness clinic networks prescribing premium formulations with documented bioavailability.
China
Middle-class consumers expand preventive health expenditure beyond deficiency correction into year-round supplementation protocols. SAMR and NMPA standards govern food supplement classifications and novel food frameworks, creating compliance complexity for synbiotic formulations. Shanghai and Beijing concentrate cross-border e-commerce platforms serving domestic demand for imported premium vitamins.
India
Pharmacy-led vitamin protocols penetrate underdeveloped professional recommendation channels across tier-2 and tier-3 cities. FSSAI standards enforce label claim substantiation and manufacturing quality across domestic production. Mumbai and Ahmedabad host API synthesis hubs supplying cost-optimized multivitamin tablets to Southeast Asian and African markets.
Brazil
ANVISA regulations align with international standards while permitting pharmacy-led preventive health expansion into underserved recommendation channels. São Paulo and Rio de Janeiro concentrate sports nutrition demand from fitness center procurement and trainer recommendation networks.
Global Vitamin Supplements Market Competitive Landscape
Player mix skews toward pharmaceutical-grade manufacturers with captive regulatory affairs capabilities and scaled consumer health operators with vertically integrated supply chains. Market structure concentrates around three strategic archetypes: pharmaceutical-grade producers leveraging drug-operation protocols, vertically integrated nutrition conglomerates controlling farm-to-tablet sourcing, and specialist sports nutrition formulators targeting performance-oriented segments. Dominant competitive moves include ISO 22000 certification acquisition and liposomal delivery technology licensing.
Among diversified nutrition conglomerates, Nestlé exemplifies upstream supply chain control through integrated ingredient sourcing operations. Bayer AG occupies a position representing pharmaceutical-grade manufacturing discipline transferred from drug operations. Within the specialist channel, GNC Holdings Inc. and Herbalife Nutrition sit within the direct-to-consumer and practitioner-facing tier respectively, capturing recurring revenue through subscription and network-based distribution models.
| Leading Market Players |
|---|
| Nestlé |
| Abbott |
| Amway Corp |
| Bayer AG |
| Glanbia PLC |
| Herbalife Nutrition |
| Pfizer Inc. |
| Otsuka Holdings Co., Ltd |
| GNC Holdings Inc. |
| Others |
Supply & Pricing Matrix
Ninety-day cholecalciferol feedstock lead times concentrate pricing power with Indian and Chinese API manufacturers who index contracts to petrochemical commodity baskets, while downstream formulators absorb margin volatility through inventory buffers and flexible sourcing protocols.
Pricing Analysis
Cost-plus contracts with retinol and ascorbic acid indexation to agricultural and petrochemical benchmarks dominate raw material procurement between API suppliers and finished goods manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 22000-certified pharmaceutical-grade products from commodity tablet alternatives. Pricing pressure stems from softgel and liquid bioavailability advantages displacing compressed tablet matrices in performance-oriented segments. Pharmacy channels exhibit highest price sensitivity due to reimbursement constraints, while direct-to-practitioner professional-grade sales sustain premium tolerance through diagnostic-protocol integration.
Supply Chain Analysis
Inventory compression to 45-60 days of finished goods coverage reflects just-in-time pressures from e-commerce replenishment models and subscription-based demand forecasting. Active compound synthesis concentrates in India and China, with gelatin and plant-based encapsulation materials sourcing from Brazil and Southeast Asian markets. Retinol feedstock draws from petrochemical derivatives and palm oil agricultural cycles, creating dual commodity exposure. Single-source vulnerability runs through concentrated API manufacturing hubs facing export license volatility. Distribution runs through pharmacy-led domestic channels, cross-border e-commerce platforms, and direct-to-practitioner functional medicine networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against whole-food nutrition and personalized microbiome testing substitutes that capture preventive health spending through alternative delivery modalities.
For Market Incumbents: Fortify regulatory affairs capabilities spanning FDA, EFSA, and FSSAI frameworks to accelerate product launch timelines against scaled competitors. Deepen backward integration into cholecalciferol and ascorbic acid API synthesis to insulate margins from agricultural commodity cycles. Capture subscription replenishment infrastructure to lock recurring revenue from wellness-focused urban demographics. For New Entrants and Emerging Players: Direct-to-practitioner channel underperformance in Brazil and India creates whitespace for pharmacy-led vitamin protocol development through trainer and clinician recommendation networks. Liposomal delivery technology licensing gaps among mid-tier manufacturers enable premium positioning in clinical nutrition segments. Target sports nutrition formulators in Germany and Australia with timing-optimized micronutrient protocols bypassing retail intermediaries. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified nutrition conglomerates seeking to divest non-core supplement portfolios with captive regulatory affairs departments and established practitioner channels. Long-term viability hinges on synbiotic classification resolution and EFSA substantiation framework evolution. Watch for ANVISA and SAMR guidance convergence on novel food versus food supplement boundaries as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 22000 Certification Acquisition | EFSA substantiation requirements bifurcate qualified mass manufacturers from excluded fringe suppliers reshaping procurement. |
| Liposomal Delivery Technology Licensing | Phospholipid bilayer protection enhances cellular absorption rates for premium clinical nutrition positioning. |
| Direct-to-Practitioner Channel Development | Functional medicine networks in Germany and Switzerland capture higher-margin professional-grade sales through diagnostic integration. |
| Subscription Replenishment Platform Buildout | Urban clusters in the United States and South Korea concentrate recurring revenue with established logistics infrastructure. |
| Backward Integration into API Synthesis | Indian and Chinese feedstock proximity insulates margin predictability from agricultural and petrochemical commodity cycles. |
Research Methodology
Desk research of FDA 483 observations, EFSA health claim registers, and FSSAI manufacturing compliance records preceded structured interviews with regulatory affairs directors, sports nutrition formulators, pharmacy procurement managers, and functional medicine practitioners. Primary fieldwork combined with secondary validation from customs trade data, clinical trial registries, and GMP inspection databases. Bottom-up volume modeling and top-down value triangulation anchored forecast construction.
Variance decomposition across product type, form, application, and customer type segmentation dimensions shaped analytical framework development across the projection horizon. CAGRs derived from historical trajectory analysis and forward-looking demand elasticity assessment for sports nutrition and immune support applications. Modeling incorporated EFSA substantiation timeline assumptions and SAMR novel food classification evolution.
Forecasts assume regulatory continuity in FDA, EFSA, and FSSAI regimes; material policy shifts on synbiotic classification or health claim substantiation would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Choline Bitartrate Market
Nutritional Supplements
Bone Meal Supplement Market
Nutritional Supplements
Fitness Cookies Market
Nutritional Supplements
Dysphagia Supplements Market
Nutritional Supplements
France Whey Protein Market
Nutritional Supplements
Fish Collagen Peptides Market
Nutritional Supplements
Heart Health Supplement Market
Nutritional Supplements
Natural Colostrum Supplements Market
Nutritional Supplements
Tongkat Ali Extract Market
Nutritional Supplements
Spirulina Purple Blend Market
Nutritional Supplements
Inositol Market
Nutritional Supplements
Concentrate Protein Market
Nutritional Supplements
Ketogenic Diet Food Market
Nutritional Supplements
US Nutraceuticals Market
Nutritional Supplements
Garlic Extract Supplement Market
Nutritional Supplements
Liquid Dietary Supplements Market