
 Zinc Supplement Market | 2026-2036
Zinc Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
Zinc Supplement Market Insights
Direct-to-consumer channels is fragmenting as Amazon and brand-owned storefronts erode traditional pharmacy dominance. NOW Foods leverages its vertically integrated manufacturing to sustain cost leadership across multiple zinc salt variants. Thorne Research differentiates through practitioner-exclusive distribution, while Garden of Life anchors its position with third-party certified organic formulations. Amway competes through multi-level marketing networks that control end-user relationships in emerging Asian markets.
Zinc supplements provide elemental zinc in bioavailable forms including zinc gluconate, zinc picolinate, and zinc citrate, typically manufactured through chelation or crystallization processes to achieve 15-50 mg doses per serving for immune support, wound healing, and enzymatic function. Tablets dominate volume sales due to manufacturing scalability and shelf stability, though gummies capture disproportionate margin pools through pediatric and senior palatability premiums. Online channels represent the fastest-expanding distribution vector, while pharmacies retain trust-dependent segments such as prenatal zinc formulations for pregnant women.
The U.S. FDA enforces Current Good Manufacturing Practices for dietary supplements, mandating identity, purity, and composition verification that elevates compliance costs for new entrants. The European Food Safety Authority sets maximum permitted zinc levels in fortified foods and supplements, directly capping per-serving formulations across EU member states. India's Food Safety and Standards Authority requires product registration and label disclosure of elemental zinc content, creating a documentation barrier for imported brands. Stakeholders must monitor evolving maximum-level regulations and channel-specific certification requirements to align portfolio investments with jurisdictional compliance thresholds.
Market Dynamics
Direct-to-consumer channel fragmentation is compressing traditional pharmacy margins while elevating compliance burdens across multiple jurisdictions. The FDA's Current Good Manufacturing Practices enforcement and EFSA's maximum permitted zinc levels are forcing simultaneous quality investments and formulation recalibration.
Growth Catalysts
- Immune-conscious adult demand:Post-pandemic consumer retention of preventive health habits sustains zinc gluconate and zinc picolinate uptake in self-directed wellness regimens across North American and European households.
- EFSA fortification frameworks:Permitted health claims for zinc's contribution to normal immune function and cognitive performance enable differentiated positioning in EU member state markets.
- Direct-to-consumer channel expansion:Amazon marketplace infrastructure and brand-owned storefronts reduce customer acquisition costs while capturing repeat purchase data for personalization.
Market Restraints
- Elemental zinc raw material volatility:Mining concentration in Australia and Peru exposes contract manufacturers to concentrate price swings that compress margin on standard-dose formulations.
- EFSA maximum level caps:The 25 mg per day upper limit for supplements in fortified foods and standalone products constrains high-dose immune positioning in EU markets.
- Plant-based capsule substitution:Consumer preference migration from gelatin to hydroxypropyl methylcellulose shells requires capital retooling without commensurate price capture.
Strategic Opportunities
- Pediatric gummy white space:Palatability-driven zinc citrate gummies for children ages 4-12 remain underdeveloped relative to adult tablet saturation in US and German markets.
- FSSAI registration arbitrage:India's mandatory product registration and elemental zinc disclosure requirements create first-mover advantage for compliant imported brands against informal domestic competition.
- Practitioner channel digitization:Telehealth platform integration enables Thorne Research-style practitioner-exclusive distribution to scale beyond geographic concentration of integrative medicine clinics.
Industry Challenges
- Chelation chemistry talent scarcity:Formulation scientists capable of optimizing zinc amino acid chelate bioavailability command premium compensation that elevates R&D overhead for mid-tier manufacturers.
- Multi-jurisdiction label compliance:Simultaneous FDA structure-function claim rules, EFSA health claim authorization requirements, and FSSAI elemental disclosure mandates fragment packaging runs and elevate obsolescence risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zinc Supplement Market |
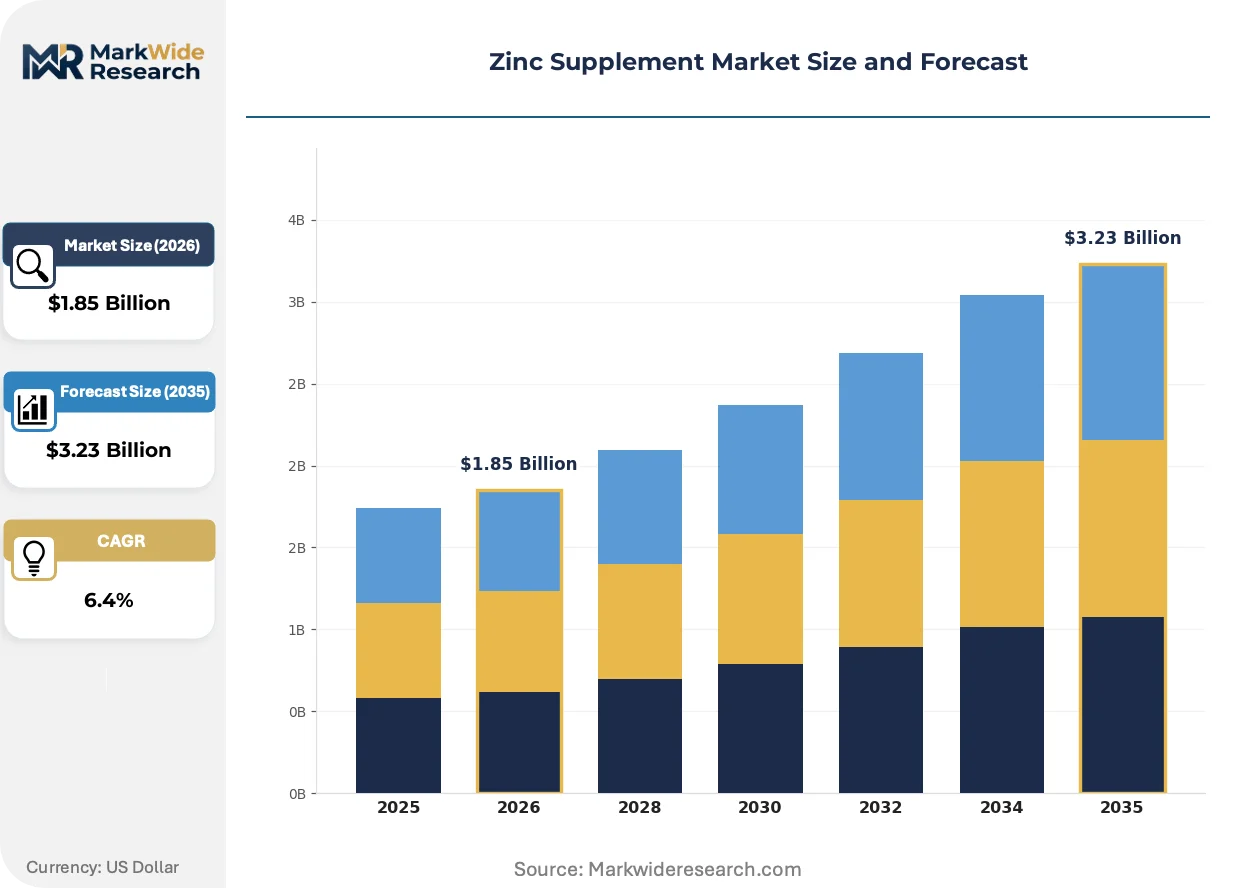
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Powders, Gummies Form: Chewable, Liquid, Spray, Effervescent Distribution Channel: Online, Pharmacies, Supermarkets, Health Stores End User: Adults, Children, Seniors, Pregnant Women |
| Companies Covered | Nature's Way, NOW Foods, Garden of Life, Solgar, Thorne Research, Amway, Herbalife Nutrition Ltd., Haleon plc, Nestlé Health Science, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zinc Supplement Market Trends and Innovations
Formulation science and distribution infrastructure are converging to compress development cycles while fragmenting channel control. Three developments are restructuring competitive position.
Liposomal encapsulation technology is digitizing bioavailability testing protocols through real-time dissolution monitoring and predictive absorption modeling. Premium positioning brands in California and Bavaria are adopting these in-house capabilities to justify 40-60% price premiums over standard zinc oxide. The technology is digitizing quality assurance workflows that previously required third-party laboratory outsourcing.
EFSA's 2023 updated guidance on zinc maximum levels in food supplements is forcing portfolio rationalization across EU-based manufacturers. Products exceeding the 25 mg threshold face reformulation or market withdrawal, compressing revenue on high-dose immune SKUs. German and Dutch brands are responding with split-dose regimens and combination formulations that distribute elemental zinc across multiple permitted delivery vehicles.
Subscription commerce models are displacing single-transaction pharmacy purchases among chronic immune support users. Direct-to-consumer brands in the United States and United Kingdom are capturing 12-month commitments through auto-replenishment interfaces that bypass retail markup structures. This behavioral shift is most visible among urban millennials managing recurring supplementation for athletic recovery and seasonal immune preparation.
Zinc Supplement Market Segmentation
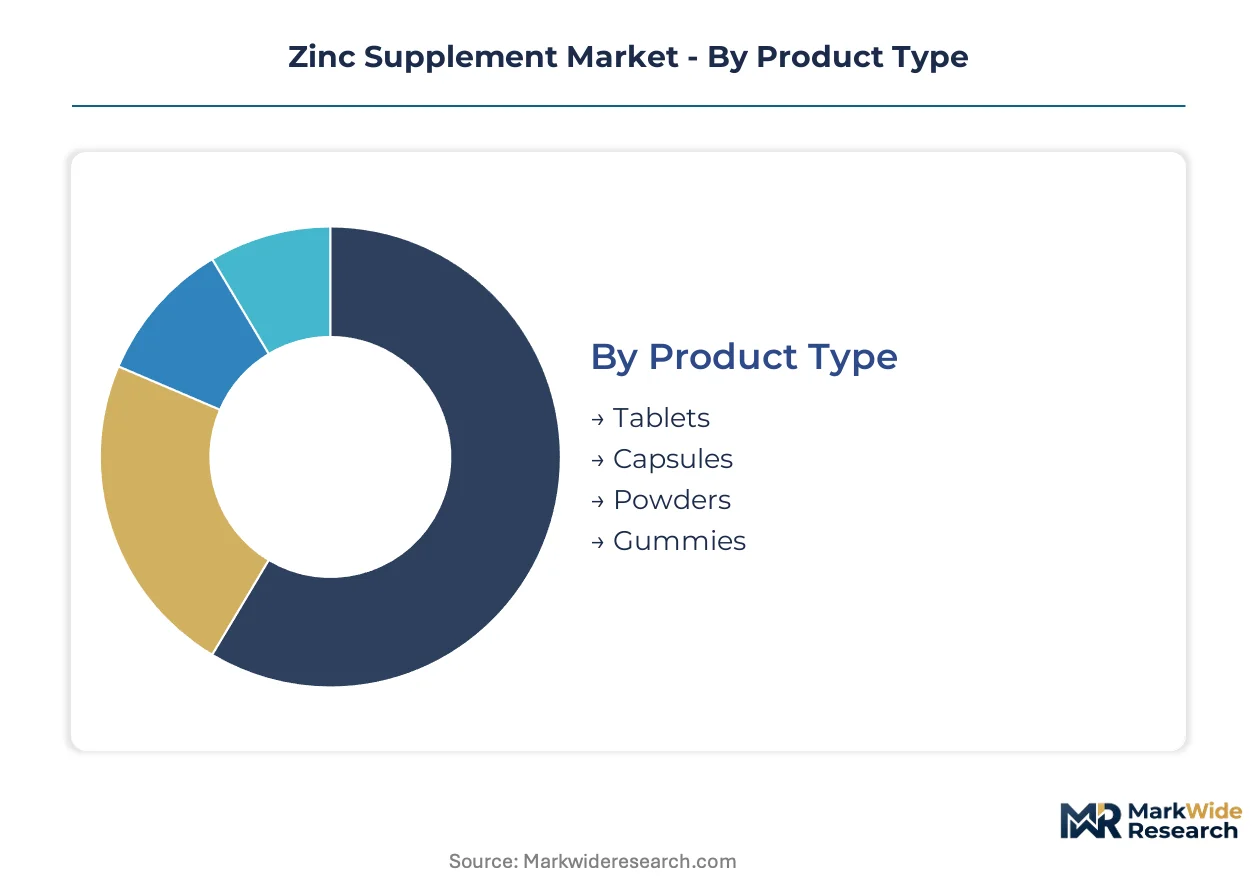
Zinc supplement segmentation reveals divergent manufacturing economics and channel economics across delivery formats. Each category carries distinct regulatory burdens, shelf-life requirements, and margin profiles that shape portfolio allocation decisions.
Product Type:
The use-case spectrum spans acute immune support through chronic maintenance regimens, with format choice driven by swallowing capability, dose precision needs, and palatability preferences.
- Tablets:Compressed zinc gluconate or zinc oxide with binders and lubricants enable high-speed rotary press manufacturing at 15-50 mg elemental zinc per unit. Demand concentrates in US pharmacy chains and German drugstores where trust in solid-dose consistency outweighs absorption rate concerns among cost-conscious immune support seekers.
- Gummies:Zinc citrate suspended in pectin or gelatin matrices delivers palatable dosing for pediatric and senior segments unable or unwilling to swallow pills. US and UK direct-to-consumer channels capture disproportionate margin premiums through subscription models targeting seasonal immune preparation.
- Capsules:Two-piece gelatin or HPMC shells containing zinc picolinate powder offer faster dissolution than tablets with reduced excipient load.
- Powders:Bulk zinc sulfate or zinc bisglycinate enables flexible dosing for athletic recovery and clinical repletion protocols.
The dominant share belongs to Tablets, while Gummies is closing the gap fastest.
Form:
Manufacturing cost tiers separate high-capital effervescent production from low-barrier liquid compounding.
- Liquid:Aqueous zinc sulfate solutions with flavor masking and preservatives achieve rapid absorption for pediatric populations and bariatric patients with compromised gastric emptying. US functional beverage brands and Indian Ayurvedic manufacturers compete on taste profile and packaging portability.
- Effervescent:Sodium bicarbonate and citric acid matrices with zinc carbonate generate controlled carbonation upon water contact, creating premium positioning through ritualistic consumption experience. German and Swiss pharmacy channels sustain 3-4x tablet price multiples for this format.
- Chewable:Compressed granules with zinc gluconate and sweeteners bridge tablet efficiency with gummy palatability.
- Spray:Micronized zinc in aqueous or oil-based carriers targets buccal absorption claims and travel convenience.
Liquid commands volume leadership in pediatric applications, yet Effervescent generates the steepest expansion trajectory among adult wellness segments.
Distribution Channel:
Customer acquisition economics vary sharply between trust-dependent pharmacy consultations and data-rich digital direct relationships.
- Online:Amazon marketplace infrastructure and Shopify-powered brand storefronts reduce customer acquisition costs while capturing repeat purchase data for personalization algorithms. US and UK urban millennials drive subscription commerce for athletic recovery and seasonal immune protocols.
- Pharmacies:Pharmacist consultation dependency sustains premium pricing for prenatal zinc formulations and clinically positioned immune support. German and French pharmacy networks retain loyalty through professional recommendation authority.
- Supermarkets:Mass merchandiser shelf placement achieves impulse purchase capture at compressed margins.
- Health Stores:Specialty retailer curation targets ingredient-conscious consumers seeking third-party certified organic or non-GMO formulations.
Pharmacies retain the largest transaction value per customer, though Online is expanding most quickly through auto-replenishment interfaces.
End User:
Physiological requirements and regulatory constraints fragment dosing protocols across life stages.
- Adults:Self-directed immune maintenance and athletic recovery drive 15-25 mg daily dosing with format flexibility from tablets to powders. US and UK direct-to-consumer brands dominate this segment through influencer marketing and subscription mechanics.
- Pregnant Women:Prenatal formulation requirements elevate trust dependencies toward pharmacy and obstetrician-recommended brands with third-party purity verification. EFSA and FDA pregnancy category considerations constrain marketing claims.
- Children:Palatability-driven gummy and liquid formats with age-appropriate dosing (5-10 mg) target parental convenience.
- Seniors:Swallowing difficulty and polypharmacy interactions favor liquid and effervescent options with drug-absorption timing guidance.
Adults generate the dominant revenue pool, while Pregnant Women commands the highest per-capita expenditure through medical channel premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmacy channels command 40-60% price premiums over US mass-market equivalents, while Chinese direct-to-consumer platforms compress margins through aggressive subsidy models. This pricing-power asymmetry reflects divergent regulatory density and channel control mechanisms across developed and emerging markets.
United States
Immune-conscious millennials and athletic recovery segments drive 15-25 mg daily dosing demand through subscription commerce models. The FDA enforces Current Good Manufacturing Practices mandating identity, purity, and composition verification that elevates compliance costs for new entrants. California-based premium positioning brands adopt liposomal encapsulation technology to justify price premiums over standard zinc oxide formulations.
Germany
Pharmacy network loyalty and professional recommendation authority sustain trust-dependent prenatal and clinically positioned immune support segments. EFSA maximum permitted zinc levels cap supplements at 25 mg per day, forcing reformulation or withdrawal of high-dose immune SKUs. Bavarian and Dutch manufacturers respond with split-dose regimens and combination formulations distributing elemental zinc across multiple permitted delivery vehicles.
China
Expanding direct-to-consumer channels concentrate volume demand through Alibaba and brand-owned storefronts reducing customer acquisition costs. The National Medical Products Administration and State Administration for Market Regulation enforce dual carbon goals and quality standards shaping manufacturing investments. Yangtze River Delta and Pearl River Delta clusters host contract manufacturers serving both domestic consumption and export markets.
India
Ayurvedic manufacturers and functional beverage brands compete on taste profile and packaging portability for pediatric and bariatric patient populations. The Food Safety and Standards Authority requires product registration and label disclosure of elemental zinc content, creating documentation barriers for imported brands. Maharashtra and Gujarat-based domestic producers face first-mover pressure from compliant imported brands against informal competition.
United Kingdom
Urban millennials managing recurring supplementation for athletic recovery and seasonal immune preparation drive subscription commerce adoption. The Medicines and Healthcare products Regulatory Agency aligns with EFSA frameworks on maximum permitted levels and health claim authorization. London and Southeast England direct-to-consumer brands capture 12-month commitments through auto-replenishment interfaces bypassing retail markup structures.
Zinc Supplement Market Competitive Landscape
Vertically integrated manufacturers and practitioner-exclusive distributors split the market between cost leadership and clinical credibility positioning. The vendor base fragments across multi-level marketing networks, third-party certified organic specialists, and mass-market private label suppliers. Three strategic archetypes dominate: vertically integrated cost leaders controlling multiple zinc salt variants, practitioner-channel exclusivists leveraging telehealth platform integration, and certified organic formulators targeting ingredient-conscious consumers. Dominant competitive moves include backward integration into elemental zinc sourcing and geographic expansion through FSSAI registration arbitrage in emerging Asian markets.
Among US-based manufacturers, NOW Foods exemplifies the vertically integrated cost leadership archetype through captive production of multiple zinc salt variants. Thorne Research occupies the practitioner-exclusive distribution position, while Garden of Life anchors the third-party certified organic tier with non-GMO and organic formulation credentials. These three represent the strategic spectrum from manufacturing scale to clinical channel control to certification-based differentiation.
| Leading Market Players |
|---|
| Nature's Way |
| NOW Foods |
| Garden of Life |
| Solgar |
| Thorne Research |
| Amway |
| Herbalife Nutrition Ltd. |
| Haleon plc |
| Nestlé Health Science |
| Others |
Pricing and Supply Chain Analysis
Yangtze River Delta contract manufacturing clusters concentrate zinc salt production capacity, translating upstream mineral processing scale into downstream pricing leverage for brands commanding pharmacy and direct-to-consumer channels. Australian and Peruvian mining concentration for elemental zinc feedstock exposes finished goods pricing to concentrate volatility, while German pharmacy networks sustain 40-60% premiums through professional recommendation authority.
Pricing Analysis
The customization-premium spread separates liposomal encapsulation formulations commanding 40-60% markups over standard zinc oxide from commodity tablets competing on manufacturing scale. Pricing stratifies across premium, standard, and economy tiers driven by bioavailability certification and third-party organic verification. Cost compression in standard-dose tablets is intensifying because Amazon marketplace infrastructure erodes traditional pharmacy markup structures. Mass-market consumers exhibit highest price sensitivity, while practitioner-channel buyers and prenatal segments tolerate premium positioning for clinical credibility.
Supply Chain Analysis
Contract manufacturing concentration rests with Yangtze River Delta and Pearl River Delta facilities serving both domestic Chinese consumption and export markets, supplemented by Indian Ayurvedic manufacturers and US vertically integrated brands. Raw material dependencies draw from Australian and Peruvian zinc concentrate, gelatin and HPMC capsule shells, and pectin matrices for gummy formulations. Single-source vulnerability in elemental zinc mining exposes margin compression during commodity price swings. Distribution runs through Amazon marketplace infrastructure and brand-owned storefronts displacing pharmacy intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents early-cycle expansion as post-pandemic immune-conscious consumer habits sustain preventive supplementation adoption across North American and European households.
For Market Incumbents: Insulate margin position through backward integration into elemental zinc sourcing and captive production of multiple salt variants. NOW Foods-style manufacturing scale and Thorne Research-style practitioner channel control defend against Amazon private label encroachment and direct-to-consumer brand disruption. For New Entrants and Emerging Players: Build out pediatric gummy white space in US and German markets where palatability-driven zinc citrate formulations remain underdeveloped relative to adult tablet saturation. FSSAI registration arbitrage in India offers first-mover advantage against informal domestic competition through compliant imported positioning. For Investors and Strategic Acquirers: Carve-out targets emerge from multi-level marketing networks seeking exit from end-user relationship control in emerging Asian markets. Long-term viability hinges on subscription commerce retention mechanics and telehealth platform integration scaling practitioner-exclusive distribution. Watch auto-replenishment interface adoption rates as inflection indicator for channel shift durability.| Strategic Initiative | Industry Significance |
|---|---|
| Liposomal Encapsulation Adoption | California and Bavarian brands justify bioavailability premiums through real-time dissolution monitoring capabilities. |
| FSSAI Registration Arbitrage | Compliant imported brands capture first-mover advantage against informal Indian domestic competition. |
| Practitioner Channel Digitization | Telehealth platform integration scales Thorne Research-style distribution beyond integrative medicine clinic geography. |
| Subscription Commerce Infrastructure | Auto-replenishment interfaces capture 12-month commitments bypassing retail markup structures. |
| Split-Dose Formulation Development | German and Dutch manufacturers circumvent EFSA 25 mg caps through multi-vehicle zinc distribution. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with formulation scientists, dietary supplement brand managers, pharmacy procurement leads, and contract manufacturing executives; and secondary validation through FDA cGMP enforcement records, EFSA health claim authorization databases, FSSAI registration filings, and customs trade data. Bottom-up volume modeling triangulated against top-down market sizing across product type, distribution channel, and end-user segmentation dimensions.
Forecast inputs considered immune-conscious adult demand retention, direct-to-consumer channel expansion velocity, and EFSA maximum level compliance costs across the analysis window. Segmentation modeling spanned delivery format, elemental zinc dosage tier, certification grade, and regional regulatory cluster. CAGRs derived from trend extrapolation of subscription commerce adoption and practitioner channel digitization patterns, cross-referenced with elemental zinc raw material price cycle assumptions.
Sensitivities concentrate around EFSA maximum level enforcement stringency, Amazon marketplace fee structure changes, and elemental zinc concentrate price volatility. Forecasts reflect documented assumptions on consumer habit persistence and channel shift velocity. Quarterly review of FSSAI registration timelines, liposomal technology patent filings, and auto-replenishment churn rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Isolate Whey Protein Market
Nutritional Supplements
Bee Pollen Supplements Market
Nutritional Supplements
Hydroxymethylbutyrate (HMB) Market
Nutritional Supplements
Green Supplement Market
Nutritional Supplements
Sleep Gummies Market
Nutritional Supplements
Water Soluble Vitamin and Mineral Feed Supplements Market
Nutritional Supplements
Nutritional Analysis Service Market
Nutritional Supplements
Psyllium-Based Supplement Market
Nutritional Supplements
Microencapsulated Fish Oil Market
Nutritional Supplements
Elderberry Extract Market
Nutritional Supplements
Micronutrient Powders (Mnps) Market
Nutritional Supplements
Apo-8 Carotenal Market
Nutritional Supplements
Mediterranean Citrus Nutricosmetic Complex Market
Nutritional Supplements
Marine Collagen Market
Nutritional Supplements
Selenium Yeast Market
Nutritional Supplements
Food Supplement OEM and ODM Market