
 Egypt Mobile Payments Market | 2026-2036
Egypt Mobile Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Mobile Payments Market Foresight
The Central Bank of Egypt's instant payment infrastructure mandate is broadening the cost-of-entry calculus for new wallet providers. Paymob leverages its developer-first API architecture to sustain merchant acquisition momentum across tier-two Egyptian cities. Vodafone Cash anchors its position through telecom-integrated subscriber lock-in and extensive agent networks. Fawry competes by dominating bill aggregation and government payment corridors that require specialized regulatory navigation.
Egypt mobile payments encompass digitally initiated fund transfers executed through smartphones, typically employing NFC contactless protocols, QR code scanning, or USSD channels on feature phones, with primary commercial purpose of replacing cash and card transactions across consumer and merchant interactions. Mobile wallets lead transaction volume due to their interoperability with Egypt's national instant payment network and minimal hardware requirements for merchants. QR code payments represent the fastest-growing technology segment as micro-merchants adopt zero-cost acceptance infrastructure. E-commerce transactions concentrate margin pools through higher interchange rates and cross-selling of credit products.
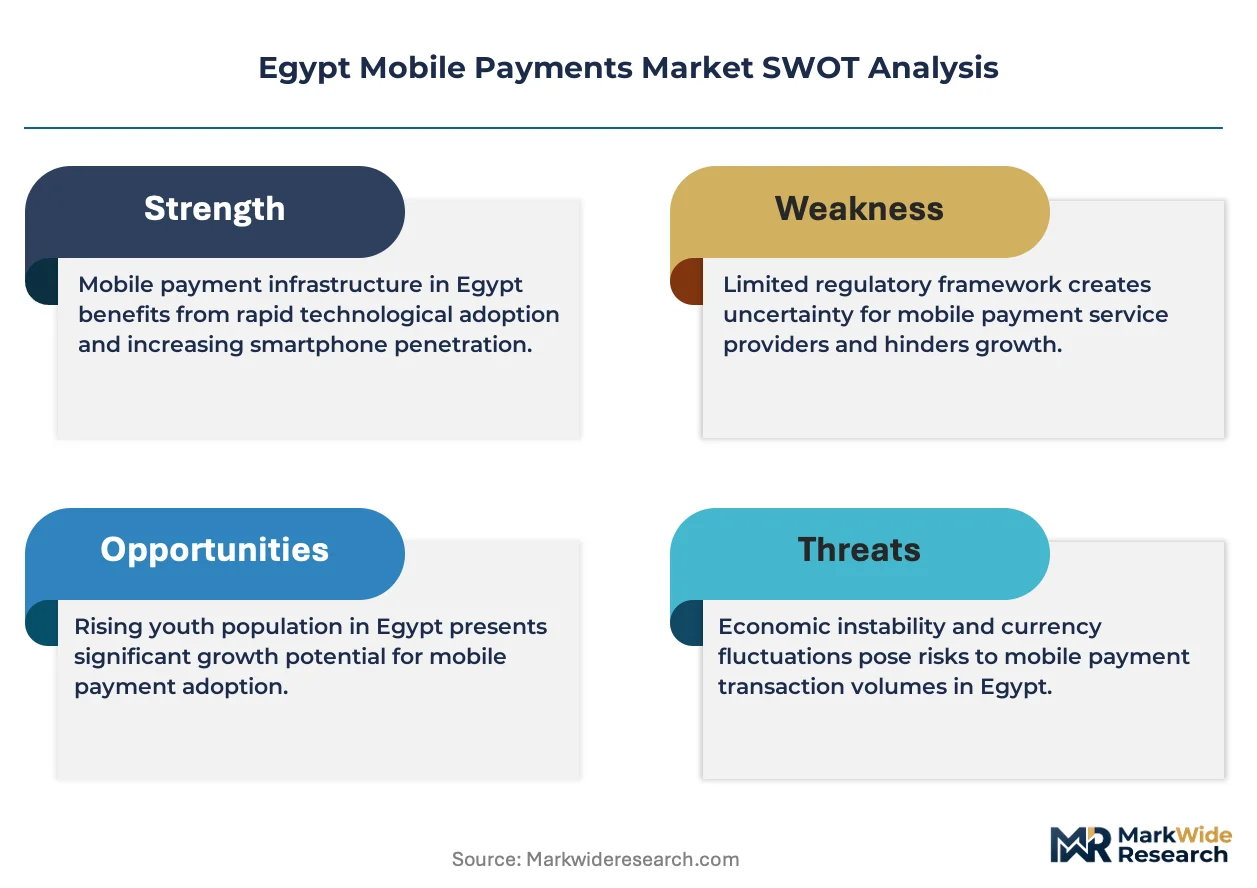
The Central Bank of Egypt governs licensing and capital requirements for payment service providers, while the Egyptian Banking Law and Financial Regulatory Authority frameworks shape consumer protection and data localization obligations that dictate product architecture decisions. Compliance with these layered standards demands significant legal and technical investment, filtering out undercapitalized entrants. Stakeholders must monitor regulatory evolution around open banking APIs and potential central bank digital currency integration that could recast competitive dynamics.
Market Dynamics
The Central Bank of Egypt's instant payment infrastructure mandate is compressing interoperability timelines and forcing wallet providers to recalibrate their technical roadmaps around API standardization and merchant onboarding velocity.
Growth Catalysts
- Central Bank Regulatory Modernization:The Central Bank of Egypt's instant payment network mandate is dissolving silos between competing wallet ecosystems and enabling seamless fund routing across previously incompatible platforms.
- QR Code Infrastructure:Zero-cost merchant acceptance hardware is electrifying adoption among Cairo and Alexandria micro-merchants who previously rejected traditional POS terminal investments.
- Smartphone Penetration Clusters:Urban corridor density in Greater Cairo and Alexandria is creating network effects that accelerate both consumer wallet downloads and merchant digitization simultaneously.
Market Restraints
- Cash Transaction Persistence:Informal sector preference for physical currency in Egypt's delta agricultural zones and Upper Egypt governorates creates friction for digital-first business models.
- Agent Network Concentration:Last-mile cash-in/cash-out infrastructure depends heavily on telecom-affiliated agent density, creating single-point-of-failure risks in rural expansion corridors.
- Data Localization Compliance:Egyptian Banking Law and Financial Regulatory Authority frameworks impose server location requirements that inflate cloud infrastructure costs for foreign-licensed payment service providers.
Strategic Opportunities
- Upper Egypt Penetration:Minya, Sohag, and Aswan governorates exhibit smartphone penetration growth without corresponding wallet saturation, presenting first-mover terrain for specialized merchant acquisition teams.
- Government Payment Digitization:Tax authority and utility billing integration creates sticky recurring transaction volumes that reduce customer churn and cross-sell lending products.
- Open Banking API Convergence:Regulatory evolution toward standardized account information services is enabling wallet providers to aggregate multi-bank balances and initiate direct account debits without card rails.
Industry Challenges
- Merchant Education Intensity:Micro-merchant digital literacy gaps in tier-two Egyptian cities require sustained field training investment that compresses unit economics during geographic expansion.
- Legacy Core Banking Integration:State-owned banks' decades-old mainframe architectures create API latency and reconciliation failures that degrade real-time payment experiences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Mobile Payments Market |
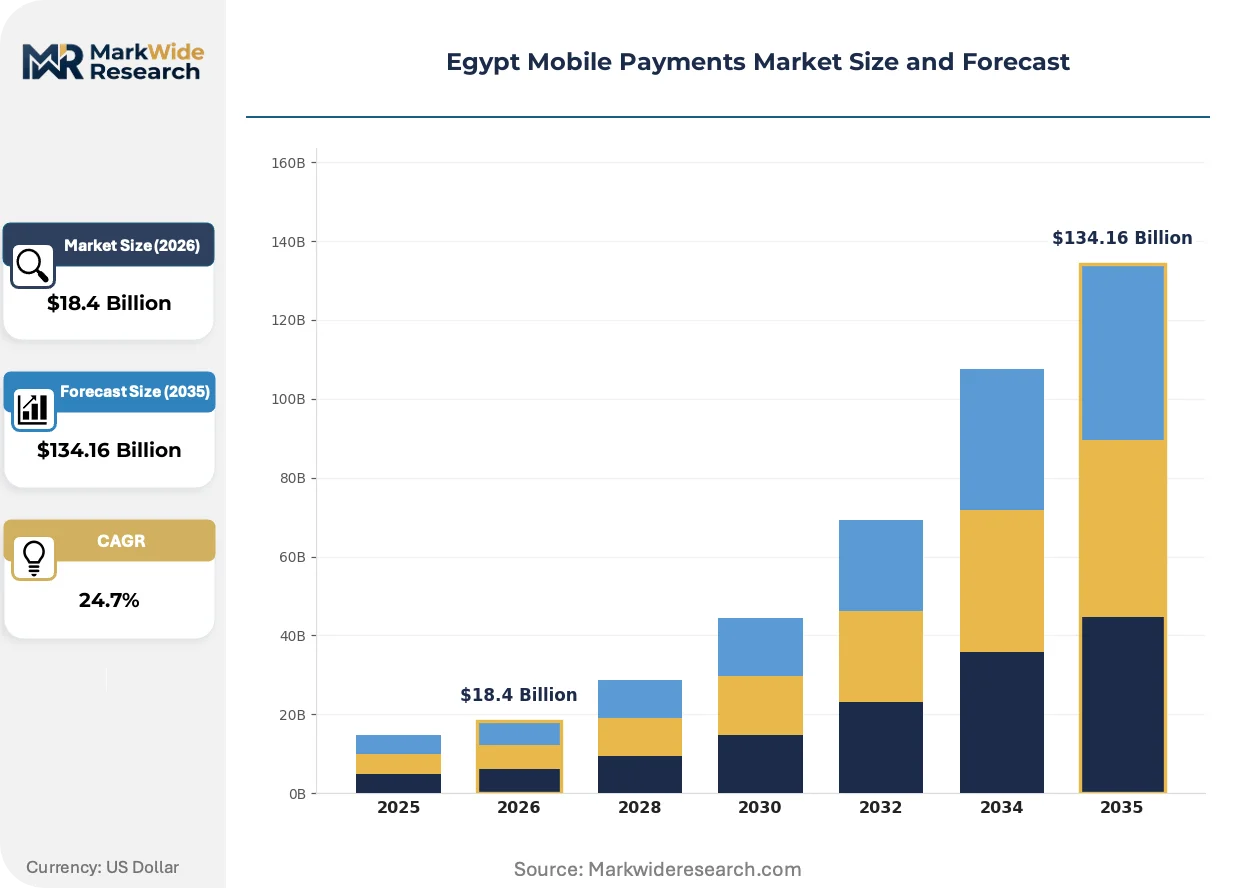
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $134.16 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Near Field Communication, QR Code Payments, Mobile Wallets, SMS Payments Customer Type: Retail Consumers, Small Businesses, Service Providers, Corporates Use Case: E-commerce Transactions, Utility Payments, Remittances, In-store Purchases Service Type: Payment Processing, Fund Transfer, Bill Payment, Mobile Banking |
| Companies Covered | WE Pay, Phone Cash, Vodafone Cash, Paymob, BM Wallet, Orange Cash, Fawry, PayTabs Egypt, Etisalat Cash, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Mobile Payments Market Shifts & Advancements
Technology convergence between instant payment rails and merchant-facing software is dissolving traditional boundaries between payment acceptance and business management tools.
Biometric authentication protocols are electrifying security architecture across Egyptian mobile wallets. Fingerprint and facial recognition modules embedded in mid-tier smartphones are displacing PIN-based verification for transactions above threshold limits. Cairo-based fintech developers are integrating liveness detection APIs that compress fraud rates while accelerating checkout completion speeds for e-commerce merchants.
The Central Bank of Egypt's open banking framework is mandating standardized API disclosure requirements for licensed deposit-taking institutions. This regulatory architecture is forcing traditional banks to expose account data and payment initiation capabilities to third-party providers. Wallet operators are responding by building account aggregation layers that position their applications as primary financial interfaces.
Merchant procurement of payment acceptance infrastructure is rotating toward software-embedded solutions rather than standalone hardware purchases. Cairo and Alexandria restaurant and retail operators are selecting POS systems where payment processing represents one module within inventory and staff management suites. This behavioral shift is compressing pure-play payment terminal vendors into component suppliers rather than relationship owners.
Egypt Mobile Payments Market Segmentation
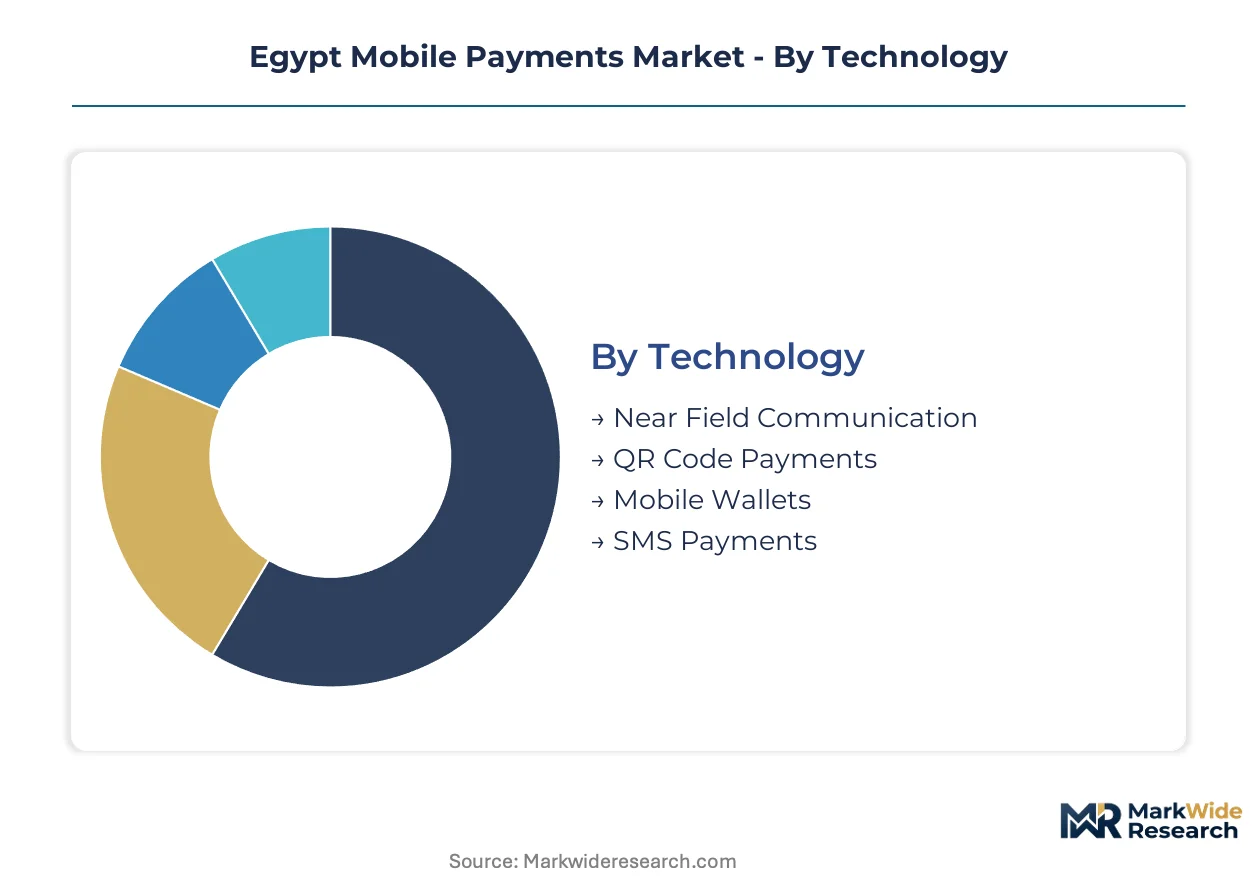
Egypt's mobile payments landscape fragments across four critical dimensions that determine provider architecture and go-to-market strategy. Technology choices dictate hardware requirements and merchant onboarding economics. Customer type shapes transaction frequency, average ticket size, and churn profiles. Use case concentration directs regulatory navigation and partnership priorities.
Technology:
Merchant infrastructure investment thresholds and smartphone penetration gradients differentiate adoption patterns across Egyptian governorates.
- Near Field Communication:Contactless protocols embedded in premium Android and iOS devices enable tap-to-pay at equipped terminals. Cairo and Alexandria supermarket chains and fuel stations concentrate deployment where consumer device refresh cycles accelerate.
- QR Code Payments:Static and dynamic matrix codes eliminate terminal hardware costs entirely. Micro-merchants across Giza, Qalyubia, and Sharqia governorates electrify adoption through zero upfront investment and instant activation via banking apps.
- Mobile Wallets:Stored-value applications integrate with Egypt's national instant payment network for seamless fund routing. Vodafone Cash and Fawry dominate transaction volume through telecom subscriber lock-in and bill aggregation specialization.
- SMS Payments:USSD channels serve feature phone users in Upper Egypt agricultural zones where smartphone penetration lags. Limited functionality constrains use to basic remittances and airtime purchases.
Volume sits with Mobile Wallets; growth tilts toward QR Code Payments.
Customer Type:
Transaction scale and documentation requirements fragment service provider economics across Egyptian economic strata.
- Retail Consumers:Individual users executing peer-to-peer transfers and everyday purchases drive aggregate transaction count. Cairo and Alexandria urban corridors concentrate wallet downloads where smartphone density and merchant acceptance networks reinforce adoption.
- Small Businesses:Micro-merchants and informal sector operators demand simplified onboarding and minimal compliance overhead. QR code acceptance dominates this tier through elimination of documentation barriers and hardware costs.
- Service Providers:Delivery platforms, ride-hailing operators, and freelance professionals require embedded payment collection and instant settlement. API-integrated solutions from Paymob and similar developers capture this segment through developer-first architecture.
- Corporates:Large enterprises necessitate bulk disbursement capabilities, payroll integration, and multi-user authorization workflows. Higher compliance thresholds and customized reporting requirements filter provider options to bank-affiliated platforms.
Revenue per transaction peaks with Corporates; wallet adoption velocity concentrates among Small Businesses.
Use Case:
Payment frequency and interchange rate structures determine margin pool distribution across transaction categories.
- E-commerce Transactions:Online purchases through merchant websites and marketplace applications generate elevated interchange revenue and cross-sell opportunities for credit products. Cairo-based fashion and electronics retailers anchor volume through checkout integration.
- Utility Payments:Recurring electricity, water, and gas settlements create sticky transaction habits with predictable monthly cadence. Fawry's dominance in government and utility billing corridors stems from specialized regulatory navigation and direct agency integrations.
- Remittances:Cross-border fund flows from Egyptian workers in Gulf states and Europe demand foreign exchange handling and compliance with Central Bank of Egypt outward remittance frameworks. High-value tickets compensate for lower frequency.
- In-store Purchases:Physical retail transactions at supermarkets, pharmacies, and restaurants constitute the volume base for merchant acceptance networks. QR code penetration accelerates fastest in this category among informal sector merchants.
Margin density clusters in E-commerce Transactions; transaction frequency concentrates in Utility Payments.
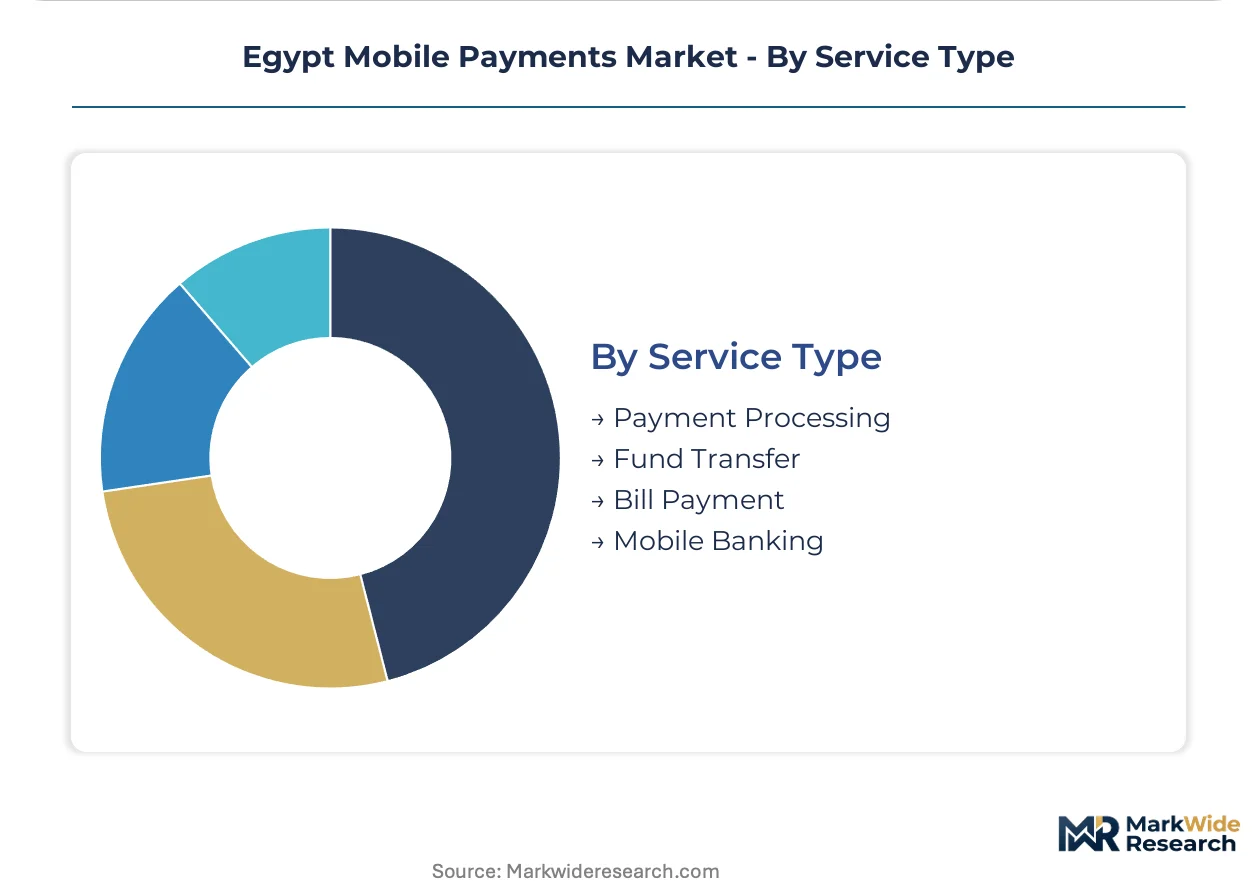
Service Type:
Technical integration depth and regulatory licensing tiers separate provider capabilities across service categories.
- Payment Processing:Merchant-facing transaction authorization and settlement infrastructure requires PCI-DSS compliance and direct connection to card networks or instant payment rails. Paymob and similar fintechs compete through API flexibility and onboarding velocity.
- Fund Transfer:Peer-to-peer and account-to-account movement of funds leverages Egypt's national instant payment network for real-time settlement. Wallet providers differentiate through interoperability breadth and fee structure simplicity.
- Bill Payment:Aggregation of government, utility, and commercial billing obligations demands direct Biller integrations and regulatory approval for collection services. Fawry maintains defensive positioning through decade-long agency relationship accumulation.
- Mobile Banking:Full-service digital banking through licensed bank applications encompasses account management, lending, and investment products. State-owned and private banks compete with independent wallets through deposit insurance and credit access.
Transaction throughput dominates Payment Processing; customer lifetime value concentrates in Mobile Banking.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Suez Canal Economic Zone's fintech incentives are concentrating payment infrastructure investment in Egypt's corridor cities. Cairo and Alexandria anchor transaction volume through superior smartphone penetration and merchant digitization density.
Greater Cairo
Urban wallet adoption accelerates through QR code penetration at micro-merchants and government payment digitization. The Central Bank of Egypt's instant payment network mandate dissolves interoperability barriers between competing platforms. New Cairo and 6th of October City clusters concentrate fintech developer talent and API-first payment providers.
Alexandria
Mediterranean port commerce drives corporate disbursement and logistics payment digitization. Egyptian Banking Law frameworks impose data localization requirements that shape cloud infrastructure decisions. The Alexandria Business Association corridor exhibits dense merchant acceptance network effects.
Giza and Qalyubia
Informal sector micro-merchants electrify QR code adoption through zero-cost acceptance infrastructure. Smartphone penetration growth in Shubra El-Kheima and Imbaba outpaces legacy POS terminal deployment. Delta agricultural supply chains create seasonal remittance corridors.
Upper Egypt
Minya, Sohag, and Aswan governorates present first-mover terrain with smartphone growth unmatched by wallet saturation. USSD channels serve feature phone users in rural agricultural zones. Telecom-affiliated agent networks concentrate cash-in/cash-out infrastructure in corridor cities.
Red Sea and Sinai
Tourism-dependent merchant ecosystems in Hurghada and Sharm El-Sheikh demand multi-currency acceptance and instant settlement. Central Bank regulatory frameworks govern foreign exchange handling for inbound visitor transactions. Resort and hospitality clusters drive contactless payment terminal deployment.
Egypt Mobile Payments Market Competitive Landscape
Cairo-based fintech developers anchor the developer-first API tier; telecom-affiliated operators hold subscriber lock-in advantages through extensive agent networks. The market structures around three strategic archetypes: API-native payment infrastructure builders, telecom-integrated wallet providers with captive subscriber bases, and bill aggregation specialists with regulatory navigation expertise. Competitive moves concentrate on merchant onboarding velocity acceleration and interoperability certification with Egypt's instant payment rails.
Within the API-native tier, Paymob exemplifies developer-first architecture positioning. Among telecom-integrated operators, Vodafone Cash and Orange Cash occupy positions leveraging subscriber density and agent network coverage. Fawry anchors the bill aggregation archetype through specialized regulatory relationships and government payment corridor dominance.
| Leading Market Players |
|---|
| WE Pay |
| Phone Cash |
| Vodafone Cash |
| Paymob |
| BM Wallet |
| Orange Cash |
| Fawry |
| PayTabs Egypt |
| Etisalat Cash |
| Others |
Supply & Pricing Matrix
Cairo-based fintech engineering talent pools compress development cost differentials between premium API-native platforms and standard merchant-acquisition services. Labor-cost arbitrage across Egypt's urban corridors enables pricing-tier spreads that separate developer-first infrastructure from agent-network-dependent wallets.
Pricing Analysis
Short lead-time merchant onboarding commands premium pricing from micro-businesses seeking instant QR code activation, while spot inventory availability on legacy POS terminals trades at discounts. The dominant model runs per-unit transactional fees scaled to ticket size, with price differentiation hinging on API integration depth and real-time settlement speed. Pricing pressure stems from Central Bank interoperability mandates dissolving wallet-specific captive economics. Small businesses in Giza and Qalyubia exhibit highest price sensitivity; corporate disbursement clients in New Cairo show lowest.
Supply Chain Analysis
Direct-to-merchant channels handle hyperscale onboarding demand across Cairo and Alexandria's micro-business corridors, bypassing traditional banking intermediaries. Hardware supply concentrates in China for POS terminals, Taiwan for NFC chipsets, and domestic Egyptian assembly for low-cost QR display materials. Cloud infrastructure draws from AWS Dubai, Azure UAE, and local data centers compliant with Egyptian Banking Law localization rules. Single-source vulnerability sits with telecom-affiliated agent networks controlling last-mile cash liquidity. Distribution runs through API-first developer platforms and banking app marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's mobile payments sector sits in a technology-transition phase as QR code infrastructure displaces legacy POS terminal dependence across informal merchant segments.
For Market Incumbents: Hedge against API-native fintech erosion by deepening direct merchant relationships through embedded software partnerships. Prioritize interoperability certification with Central Bank instant payment rails to neutralize developer-first challengers. Vertical integration into cloud infrastructure within Egyptian data centers addresses localization compliance cost pressures. For New Entrants and Emerging Players: Biometric authentication modules offer a technology-first wedge into security-conscious e-commerce merchant segments. Upper Egypt governorates present penetrable white-space with smartphone growth unmatched by wallet saturation. Developer-first API documentation and instant sandbox activation provide the sharpest go-to-market angle against incumbent onboarding friction. For Investors and Strategic Acquirers: Re-rating potential sits with account-aggregation platforms given Central Bank open banking API convergence as catalyst. Long-term viability favors providers controlling both merchant acceptance infrastructure and consumer wallet interfaces. Monitor biometric authentication adoption rates among Cairo e-commerce merchants as inflection indicator for security-architecture competitive shifts.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Launch | Paymob's developer-centric architecture accelerates merchant acquisition velocity across tier-two cities. |
| Interoperability Certification | Central Bank instant payment rail integration dissolves wallet silos and enables seamless fund routing. |
| Biometric Security Integration | Fingerprint and facial recognition modules embedded in mid-tier smartphones displace PIN-based verification. |
| Upper Egypt Geographic Expansion | Minya and Sohag governorates present first-mover terrain with unmatched smartphone penetration growth. |
| Government Payment Partnership | Tax authority and utility billing integration creates sticky recurring transaction volumes reducing churn. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Egypt mobile payments analysis. Primary interviews with payment service provider executives, Central Bank regulatory affairs officers, merchant acquisition managers, and fintech platform engineers combined with secondary validation from Egyptian Banking Law documentation, Financial Regulatory Authority circulars, and instant payment network technical specifications. Bottom-up transaction volume modeling and top-down smartphone penetration forecasts underwent triangulation against telecom subscriber disclosure data.
Data-stream reconciliation across merchant onboarding velocity metrics, wallet download trajectories, and instant payment rail transaction volumes shaped the analytical framework. Segmentation dimensions modeled include technology protocol, customer type, use case concentration, and service integration depth across the projection horizon. CAGRs derived from smartphone penetration gradients, merchant digitization curves, and regulatory interoperability timeline assumptions. Industry-specific forecast inputs encompassed QR code adoption rates among micro-merchants and biometric authentication module shipment data.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Central Bank digital currency launch scenarios or abrupt data localization enforcement shifts. Periodic stress-testing of base assumptions is recommended given regulatory evolution around open banking APIs and potential central bank digital currency integration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Asia Pacific POS Terminal Market
Payments
France Buy Now Pay Later Services Market
Payments
Payment Processing Solutions Market
Payments
Australia Buy Now Pay Later Services Market
Payments
Mobile Money Market
Payments
Estonia POS Terminal Market
Payments
South Korea Digital Payments Market
Payments
Saudi Arabia Buy Now Pay Later Services Market
Payments
QR Codes Payment Market
Payments
Global Smart Payment Systems Market
Payments
Latin America Retail Cash Management Market
Payments
NFC Payments Market
Payments
Electronic Bill Presentment and Payment (EBPP) Market
Payments
China Forex Cards Market
Payments
Japan Retail Cash Management Market
Payments
Middle East Gift Card and Incentive Card Market