
 Protein Supplements Market | 2026-2036
Protein Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Protein Supplements Market Analysis
Asset-light contract manufacturing and white-label financing is narrowing the capital barrier for new entrants in protein supplements. Glanbia PLC leverages its integrated dairy supply chain to sustain cost advantages in whey protein sourcing. Abbott Laboratories anchors its position through medical nutrition credibility that extends into mainstream performance products. Quest Nutrition LLC competes through flavor technology leadership that differentiates its bar and powder portfolios.
Protein supplements are concentrated or hydrolyzed protein preparations, typically delivering 15-30 grams of protein per serving through spray-dried or extruded processes, designed to augment dietary intake for muscle protein synthesis and recovery. Whey protein dominates value capture due to its complete amino acid profile and rapid absorption kinetics, while pea protein represents the fastest-growing source as plant-based formulations gain formulation sophistication. Powder formulations occupy the largest volume share, though ready-to-drink formats command premium positioning through convenience-driven channel placement in gyms and convenience retail.
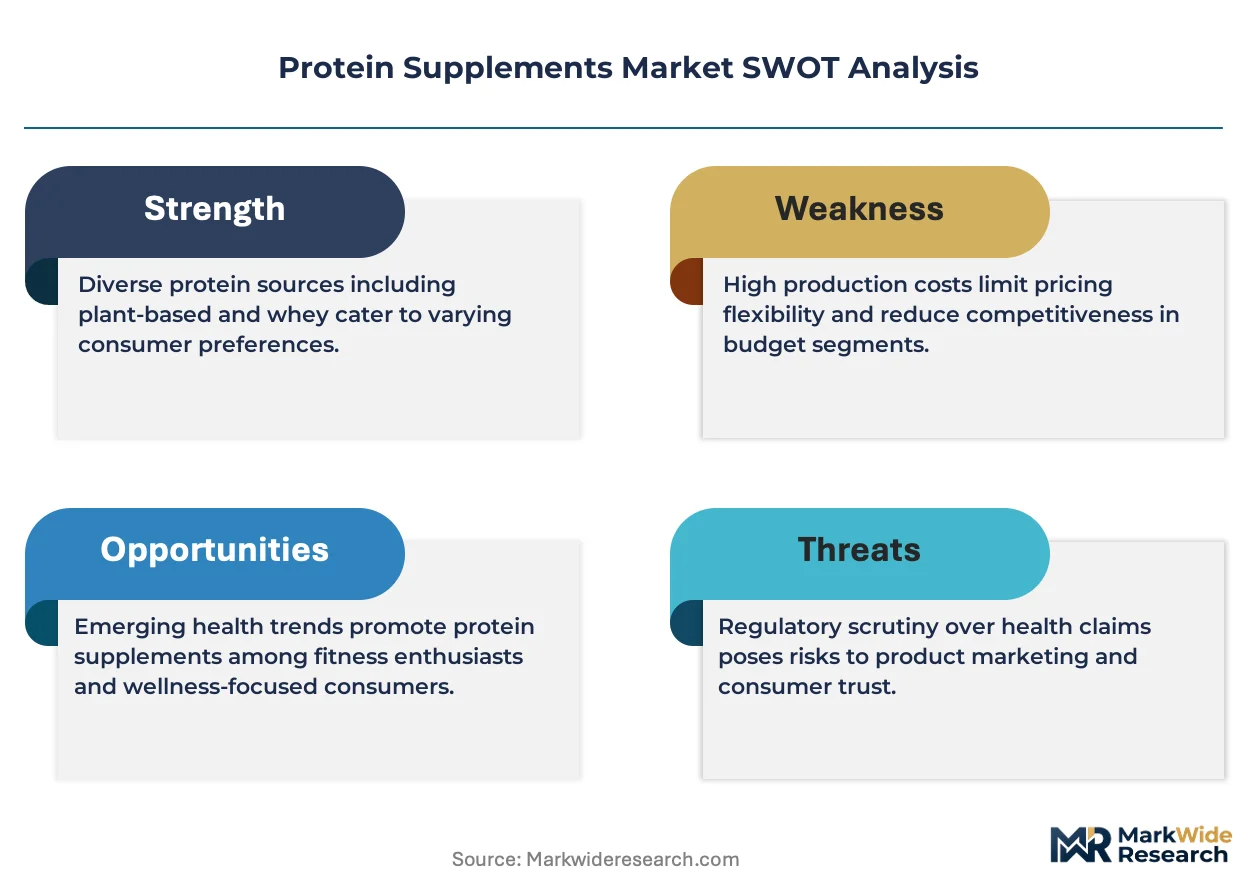
The FDA exercises oversight through Current Good Manufacturing Practice regulations and New Dietary Ingredient notifications, while the USDA governs organic certification claims that command shelf price premiums. In Europe, EFSA health claim regulations constrain marketing language and shape product development priorities for companies seeking cross-border market access. Stakeholders must monitor evolving protein quality scoring methodologies and emerging precision fermentation alternatives that could disrupt traditional extraction economics.
Market Dynamics
Home-based workout culture has permanently altered purchase patterns, shifting volume from gym-centric impulse buys toward subscription-driven direct-to-consumer replenishment models that reward formulation consistency and flavor loyalty over novelty.
Growth Catalysts
- FDA New Dietary Ingredient pathway:Streamlined notification procedures accelerate novel protein source commercialization, compressing time-to-shelf for fermentation-derived and insect-based alternatives.
- Fitness enthusiast segment expansion:Sustained remote work flexibility extends training windows, elevating per-capita consumption frequency among 25-40 year-old urban professionals.
- Pea protein extraction advances:Wet-fractionation improvements eliminate beany off-notes and solubility limitations, unlocking beverage applications previously restricted to dairy isolates.
Market Restraints
- Whey concentrate input volatility:Dairy commodity price swings tied to New Zealand and EU milk powder auctions compress margin predictability for mid-tier brands lacking forward-contract coverage.
- EFSA health claim enforcement:Strict substantiation requirements for muscle recovery claims force reformulation or label language retreats, increasing compliance spend for European market entry.
- Soy protein substitution pressure:Allergen labeling mandates and phytoestrogen concerns drive brand owners toward costlier alternative isolates in pediatric and women's health positioning.
Strategic Opportunities
- India urban middle-class penetration:Protein awareness campaigns by gym chains and sports leagues in Mumbai, Delhi, and Bangalore outpace organized retail shelf expansion, creating e-commerce-first entry paths.
- Medical nutrition convergence:Sarcopenia screening protocols in Japanese geriatric care settings create institutional demand for high-leucine formulations at reimbursement-adjacent price points.
- Precision fermentation scale-up:Whey-identical proteins from microbial hosts bypass agricultural land use and lactose contamination, appealing to sustainability-committed performance nutrition buyers.
Industry Challenges
- Flavor chemist talent scarcity:Masking technologies for plant-protein bitterness require specialized formulation expertise concentrated among a handful of ingredient houses, extending NPD timelines.
- Co-manufacturer capacity bottlenecks:Spray-drying and extrusion assets for bar production face 12-18 month booking queues, constraining launch velocity for venture-backed entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protein Supplements Market |
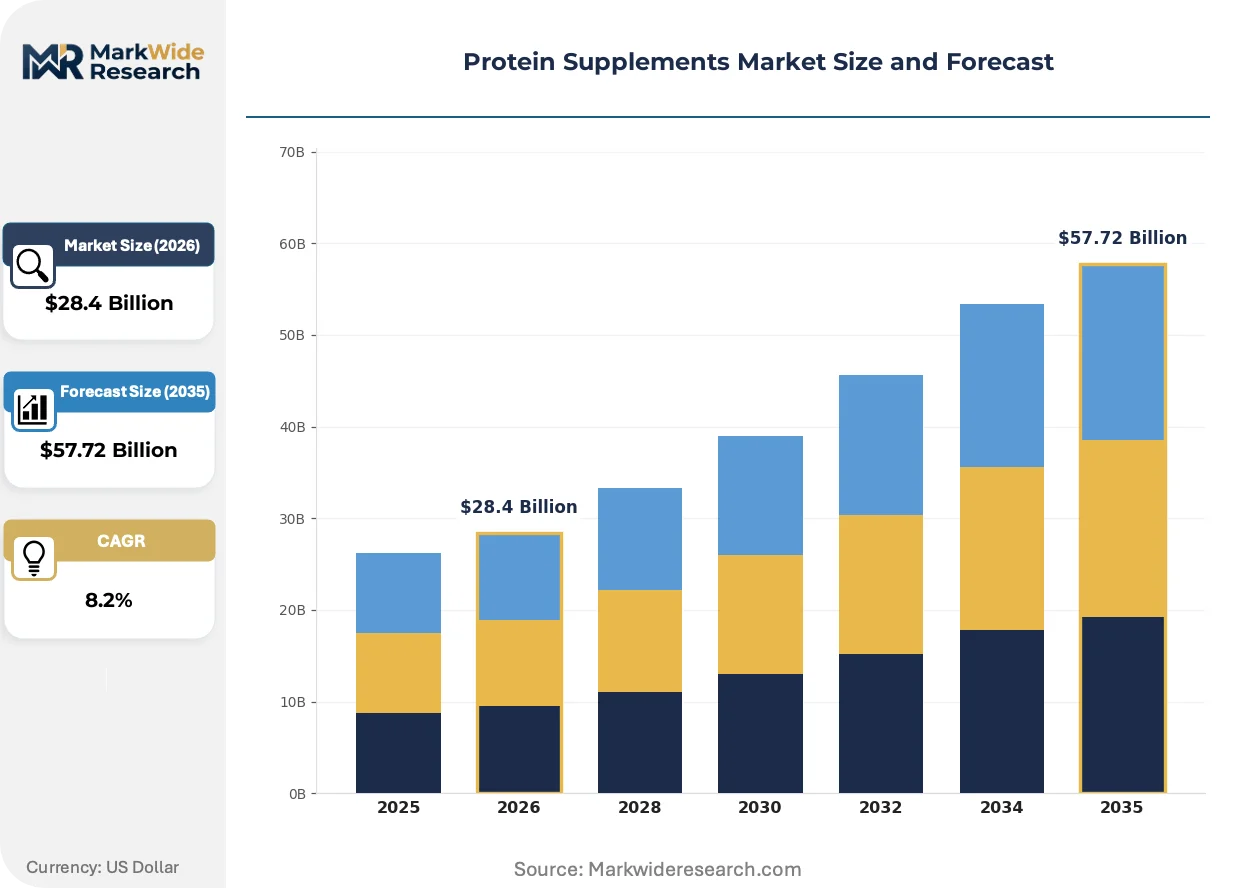
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $57.72 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein Protein, Soy Protein, Pea Protein End User: Bodybuilders, Athletes, Fitness Enthusiasts, Health-Conscious Consumers Form: Powders, Bars, Ready-to-Drink, Capsules Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Gyms |
| Companies Covered | PepsiCo Inc., Amway Corporation, Glanbia PLC, Quest Nutrition LLC, Herbalife International of America Inc., Abbott Laboratories, Post Holdings Inc., CytoSport Inc., Nestlé S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protein Supplements Market Emerging Trajectories
Formulation science and production biotechnology are compressing the performance gap between plant and animal proteins, while regulatory clarity and channel fragmentation reshape how products reach end users.
Precision fermentation platforms producing whey and casein without cattle are rendering obsolete the land-use and methane accounting disadvantages that constrained dairy protein growth narratives. Performance nutrition brands in Germany and the Netherlands are piloting these ingredients for 2025 launches, positioning supply chain transparency as a premium justification independent of organic certification.
EFSA's 2023 guidance on protein quality scoring methodologies is forcing recalculation of PDCAAS and DIAAS values across blended formulations, compelling manufacturers to reformulate amino acid ratios or abandon certain positioning claims. European brands targeting cross-border distribution are consolidating SKU architectures around the most defensible scoring outcomes, accepting higher raw material costs to preserve marketing latitude.
Subscription-based replenishment via owned digital channels is displacing traditional retail velocity dependence for powder and RTD categories, rewarding brands that invest in flavor consistency and personalization algorithms. This shift concentrates most visibly in the United States, where gym closures during 2020-2021 habituated core buyers to home delivery and direct feedback loops with formulation teams.
Protein Supplements Market Segmentation
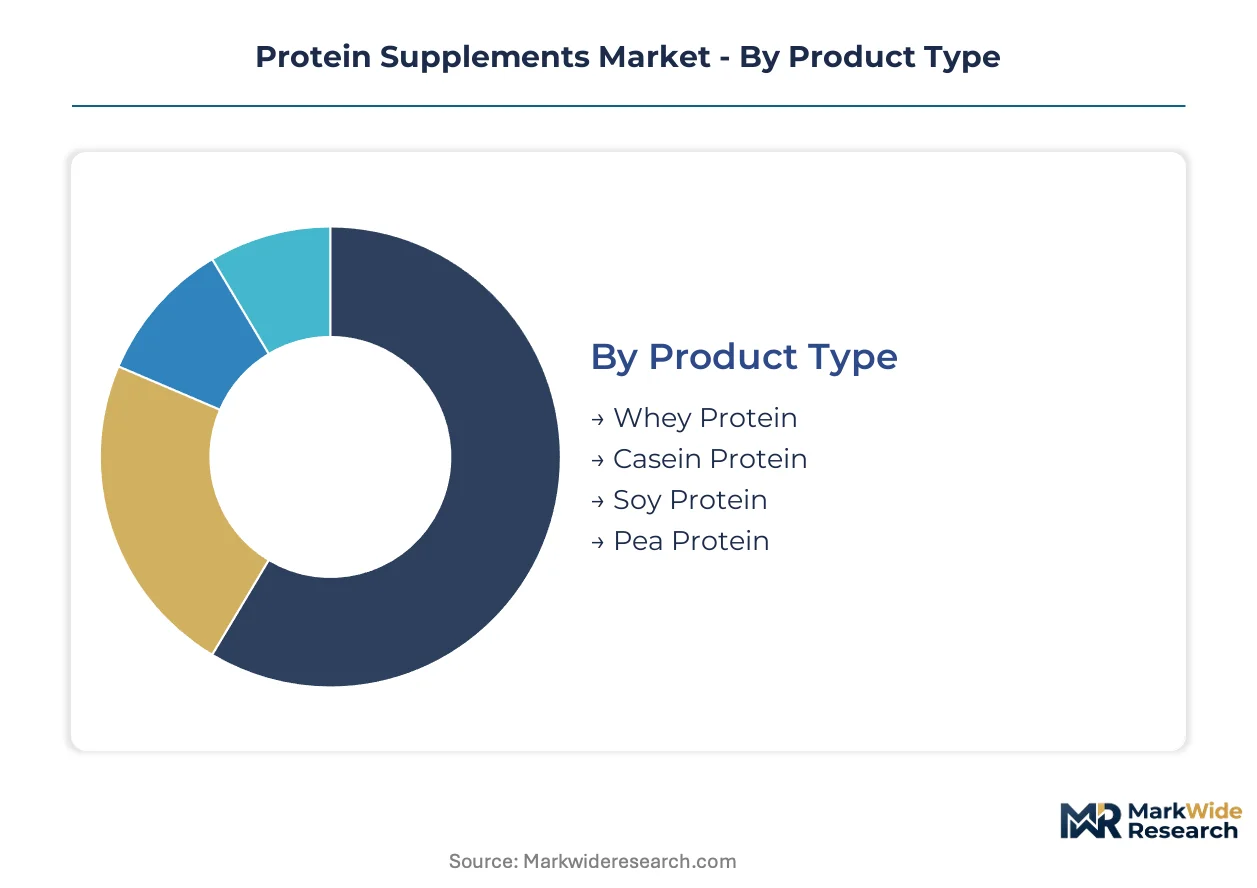
Protein supplement segmentation reveals how formulation choices, consumption occasions, and channel access fragment demand across distinct buyer workflows. Each dimension carries unique margin profiles and regulatory exposure that shape portfolio construction decisions.
Product Type:
Use-case spectrum spans rapid post-workout recovery through overnight muscle maintenance, with dairy-derived and plant-based sources occupying divergent cost and functionality positions.
- Whey Protein:Complete amino acid profile with rapid absorption kinetics dominates sports nutrition formulations. Demand concentrates among bodybuilders and competitive athletes in the United States where sports nutrition retail infrastructure remains dense, though whey concentrate input volatility tied to New Zealand and EU milk powder auctions compresses margin predictability for mid-tier brands.
- Pea Protein:Wet-fractionation advances have eliminated beany off-notes and solubility limitations, unlocking beverage applications previously restricted to dairy isolates. German and Dutch performance nutrition brands are piloting precision fermentation alternatives, positioning supply chain transparency as a premium justification.
- Casein Protein:Slow-digesting micellar structure supports overnight muscle protein synthesis applications. Night-time recovery positioning targets sleep-conscious fitness enthusiasts seeking sustained amino acid release.
- Soy Protein:Allergen labeling mandates and phytoestrogen concerns drive substitution toward costlier alternative isolates in pediatric and women's health positioning, constraining growth in premium segments.
The dominant share belongs to Whey Protein, while Pea Protein is closing the gap fastest.
End User:
Customer maturity and training intensity create four distinct purchasing behaviors with divergent price sensitivity and loyalty patterns.
- Bodybuilders:High-volume consumers prioritizing leucine content and protein-per-dollar metrics. Sustained remote work flexibility extends training windows, elevating per-capita consumption frequency among 25-40 year-old urban professionals.
- Fitness Enthusiasts:Subscription-driven replenishment models reward formulation consistency and flavor loyalty over novelty. Home-based workout culture has permanently shifted volume from gym-centric impulse buys toward direct-to-consumer channels.
- Athletes:Institutional procurement through teams and leagues with batch-tested certification requirements. EFSA health claim enforcement forces reformulation or label language retreats, increasing compliance spend for European market entry.
- Health-Conscious Consumers:Wellness positioning seekers responsive to organic certification claims that command shelf price premiums. USDA organic governance shapes product development priorities for mainstream retail placement.
Bodybuilders command the highest per-capita volume, though Fitness Enthusiasts are expanding most quickly as the addressable base broadens.
Form:
Manufacturing capital intensity and convenience trade-offs stratify the market across production technologies with divergent barrier-to-entry profiles.
- Powders:Spray-dried formulations occupy the largest volume share with lowest per-serving production costs. Co-manufacturer capacity bottlenecks face 12-18 month booking queues, constraining launch velocity for venture-backed entrants.
- Ready-to-Drink:Aseptic filling requirements and cold-chain logistics command premium positioning through convenience-driven channel placement in gyms and convenience retail. Flavor chemist talent scarcity for masking technologies extends NPD timelines.
- Bars:Extrusion and coating processes require specialized equipment with limited contract manufacturing availability. Texture stability challenges differentiate established players from new entrants.
- Capsules:Encapsulation of amino acid isolates targets medical nutrition and travel-convenience segments. Limited payload capacity restricts protein per serving, constraining athletic applications.
Powders retain volume leadership, while Ready-to-Drink formats are gaining share fastest through gym and convenience retail penetration.
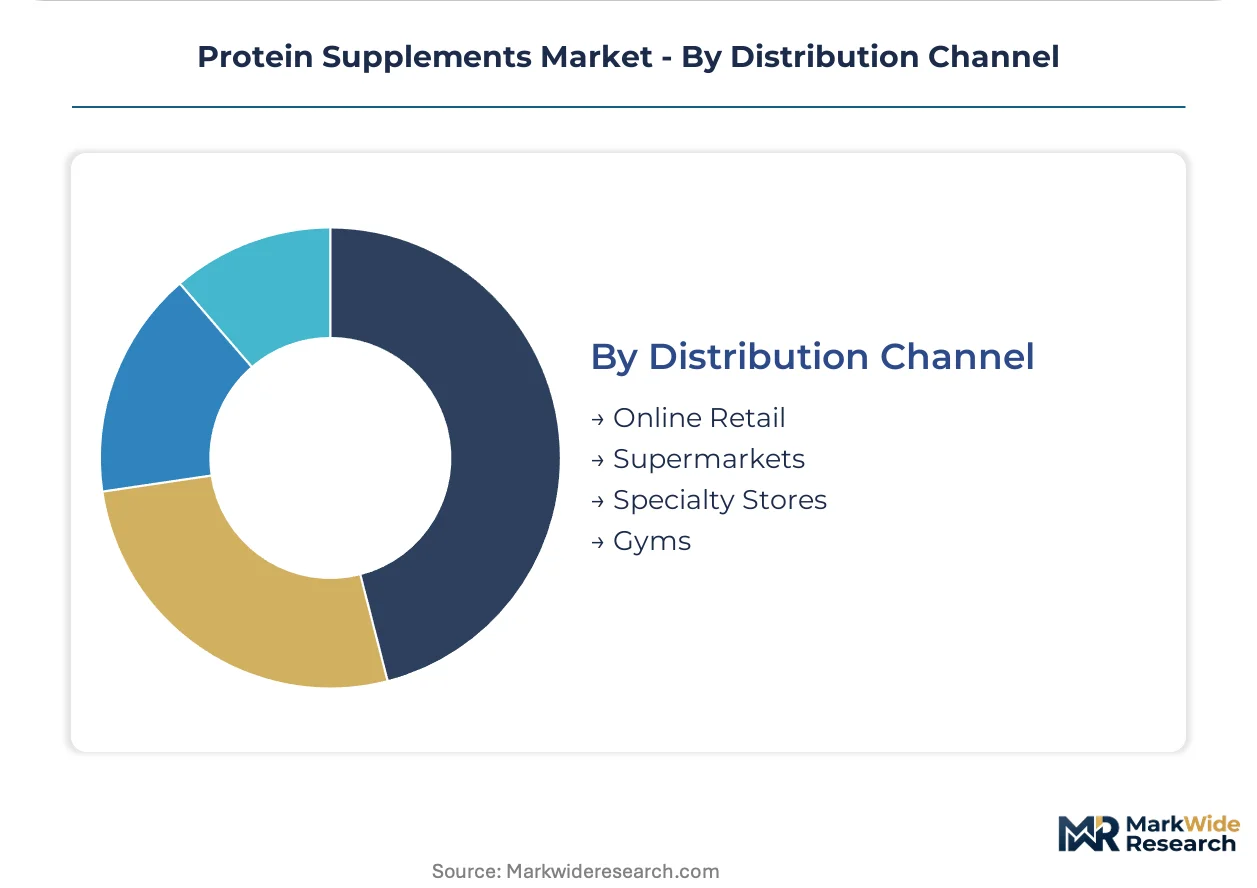
Distribution Channel:
Channel fragmentation reflects the post-pandemic permanence of digital purchasing habits alongside resilient physical touchpoints for trial and replenishment.
- Online Retail:Owned digital channels and marketplace platforms concentrate subscription-based replenishment. Personalization algorithms and direct feedback loops with formulation teams reward technology investment.
- Gyms:Impulse purchase occasions at point-of-exertion with trained staff recommendation influence. Post-2020 habituation to home delivery has reduced but not eliminated this channel's role in trial generation.
- Specialty Stores:Curated assortments with staff expertise supporting premium positioning and novel ingredient education. Independent retailers in India urban centers outpace organized retail shelf expansion.
- Supermarkets:Mass-market penetration for mainstream wellness positioning with price-promotion dependency. USDA organic certification claims support shelf price premiums in conventional grocery.
Online Retail captures the dominant transaction volume, while Specialty Stores are climbing the fastest as premium positioning and ingredient education gain importance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA organic certification subsidies and FDA streamlined notification pathways are accelerating novel protein source commercialization across mature markets, while urban middle-class expansion in emerging economies creates parallel demand formation channels.
United States
Fitness enthusiast segment expansion and subscription-driven direct-to-consumer replenishment models concentrate demand among 25-40 year-old urban professionals. FDA Current Good Manufacturing Practice regulations and New Dietary Ingredient notification requirements shape product formulation pathways and compliance spend. Sports nutrition retail infrastructure remains dense in metropolitan clusters across California, Texas, and the Northeast Corridor.
Germany
Precision fermentation platform adoption and sustainability-committed performance nutrition buyers drive demand for whey-identical proteins from microbial hosts. EFSA health claim enforcement and protein quality scoring methodology recalculations force reformulation decisions across blended formulations. Performance nutrition brands in Berlin and Hamburg pilot fermentation-derived ingredients for commercial launches.
India
Protein awareness campaigns by gym chains and sports leagues in Mumbai, Delhi, and Bangalore outpace organized retail shelf expansion, creating e-commerce-first entry paths. FSSAI food safety standards and labeling requirements govern import and domestic manufacturing compliance. Maharashtra and Karnataka host the largest concentration of contract manufacturing capacity for powder formulations.
Japan
Sarcopenia screening protocols in geriatric care settings create institutional demand for high-leucine formulations at reimbursement-adjacent price points. METI industrial policy supports functional food ingredient innovation through targeted R&D subsidies. Tokyo and Osaka metropolitan areas concentrate medical nutrition distribution networks and specialty retail channels.
Brazil
Health-conscious consumer segment expansion and wellness positioning seekers responsive to organic certification claims drive mainstream retail penetration. ANVISA sanitary surveillance requirements govern dietary supplement registration and marketing authorization. São Paulo and Rio de Janeiro anchor sports nutrition retail infrastructure and gym chain expansion.
Protein Supplements Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. The vendor base spans integrated dairy processors, medical nutrition conglomerates, flavor-technology specialists, and venture-backed direct-to-consumer entrants. Three archetypes dominate: supply-chain-integrated commodity processors, clinical-credibility medical nutrition extenders, and digital-native formulation innovators. Competitive moves concentrate on co-manufacturer capacity booking and subscription platform technology acquisition.
Within the supply-chain-integrated tier, Glanbia PLC exemplifies upstream dairy control, while Abbott Laboratories anchors medical nutrition credibility extension. Quest Nutrition LLC occupies the flavor-technology specialist position. These three entities represent divergent competitive vectors: captive whey sourcing, clinical trial substantiation, and sensory differentiation.
| Leading Market Players |
|---|
| PepsiCo Inc. |
| Amway Corporation |
| Glanbia PLC |
| Quest Nutrition LLC |
| Herbalife International of America Inc. |
| Abbott Laboratories |
| Post Holdings Inc. |
| CytoSport Inc. |
| Nestlé S.A. |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific container rates from New Zealand and EU dairy export corridors feed directly into whey concentrate landed costs, amplifying margin compression for brands lacking forward-contract coverage while enabling price differentiation between integrated processors and spot-market dependent formulators.
Pricing Analysis
Certification level creates the primary spread between USDA organic, conventional dairy-derived, and plant-based isolates. Three-tier pricing structure across premium, standard, and economy levels stratifies by protein quality scoring and leucine density. Cost compression in mid-tier whey concentrates is intensifying because New Zealand milk powder auction volatility transmits rapidly to spot buyers. Health-conscious consumers exhibit highest price tolerance for organic-certified positioning, while fitness enthusiasts prioritize protein-per-dollar metrics over premium tiers.
Supply Chain Analysis
Export-control restrictions on precision fermentation bioreactor technology limit capacity expansion outside established biotechnology hubs. Supply concentrates in Ireland and New Zealand for whey isolates, with pea protein extraction scaling in Canada and France. Raw material flows draw from dairy commodity auctions, yellow pea wet-fractionation facilities, and microbial host cultivation platforms. Single-source vulnerability runs through spray-drying asset bottlenecks facing 12-18 month booking queues. Distribution runs through direct-to-consumer subscription platforms, gym impulse channels, and specialty retail with trained staff.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around FDA New Dietary Ingredient notifications and EFSA health claim substantiation creates durable moats for incumbents with established compliance infrastructure and clinical trial portfolios.
For Market Incumbents: Entrench position through captive whey sourcing from integrated dairy processing assets in Ireland and New Zealand. Add spray-drying capacity in Maharashtra and Karnataka to preempt co-manufacturer bottlenecks. Defend against precision fermentation disruptors by securing exclusive offtake agreements with microbial protein developers.
For New Entrants and Emerging Players: Pursue white-space opportunity in India's e-commerce-first protein supplement penetration, where gym chain awareness campaigns outpace organized retail shelf expansion. Target ready-to-drink formats in Japanese geriatric medical nutrition channels. Launch through subscription-driven direct-to-consumer platforms with flavor personalization algorithms.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates with underoptimized sports nutrition divisions lacking digital channel infrastructure. Five-to-ten year viability hinges on precision fermentation scale-up economics displacing agricultural extraction. Monitor FDA novel protein source notification approvals as inflection indicator for fermentation-derived ingredient commercialization velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Whey-identical proteins from microbial hosts bypass agricultural land use and lactose contamination risks. |
| Co-Manufacturer Capacity Booking | Advance spray-drying and extrusion asset reservations secure 12-18 month production slots. |
| Subscription Platform Technology | Owned digital channels with personalization algorithms displace retail velocity dependence. |
| EFSA Health Claim Substantiation | Clinical trial investment preserves marketing latitude across European cross-border distribution. |
| Flavor Chemist Talent Acquisition | Specialized formulation expertise compresses NPD timelines for plant-protein bitterness masking. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with sports nutrition brand managers, contract manufacturing procurement leads, flavor technology R&D directors, and gym chain category buyers. Secondary validation drew from FDA New Dietary Ingredient notification filings, EFSA health claim registers, USDA organic certification databases, and customs trade records for whey concentrate and pea protein isolate flows. Bottom-up SKU-level volume aggregation and top-down macroeconomic calibration were triangulated for convergence.
Calibration across the analysis window applied segment-specific growth assumptions to protein source, end-user archetype, formulation format, and distribution channel dimensions. CAGRs were derived from historical trajectory analysis adjusted for structural shifts in home-based workout culture and precision fermentation commercialization timelines. Forecast inputs incorporated dairy commodity auction price elasticity and subscription platform customer lifetime value metrics.
Sensitivities concentrate around FDA notification pathway delays, EFSA protein quality scoring methodology revisions, and precision fermentation scale-up economics. Forecasts reflect documented assumptions on consumer habit persistence and regulatory enforcement intensity. Material shifts in novel protein source approval velocity or co-manufacturer capacity expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Europe Protein Bar Market
Sports Nutrition
Japan Sports Drink Market
Sports Nutrition
Energy and Protein Bars Market
Sports Nutrition
Androstenedione Market
Sports Nutrition
United Kingdom Sports Drink Market
Sports Nutrition
Asia-Pacific Sports Drink Market
Sports Nutrition
Pre-Workout Supplements Market
Sports Nutrition
Medicated Fitness Supplements Market
Sports Nutrition
Creatine Market
Sports Nutrition
Asia-Pacific Sports Nutrition Market
Sports Nutrition
North America Sports Drink Market
Sports Nutrition
B2B Sports Nutrition Market
Sports Nutrition
GCC Sports Nutrition Market
Sports Nutrition
L-Carnitine Supplements Market
Sports Nutrition
Sports Supplement Market
Sports Nutrition
Germany Sports Nutrition Market