
 Programmable Automation Controller (PAC) Programming Software Market | 2026-2036
Programmable Automation Controller (PAC) Programming Software Market Size, Share, and Industry Trends Forecast 2026-2036
Programmable Automation Controller (PAC) Programming Software Market Analytics
High-performance deterministic control tier is reorganizing competitive dynamics in industrial software. Siemens AG leverages its TwinCAT integration to anchor premium positioning across European machine tool builders. Rockwell Automation, Inc. competes through FactoryTalk Design Studio, sustaining deep penetration in North American automotive assembly ecosystems. Beckhoff Automation GmbH specializes in PC-based control architectures, dominating precision motion applications where real-time synchronization exceeds traditional PLC capability.
Programmable Automation Controller programming software constitutes engineering environments that compile, debug, and deploy deterministic control logic across hybrid processor architectures combining PLC reliability with PC computational throughput. These platforms execute IEC 61131-3 structured text and function block diagrams with sub-millisecond cycle determinism while hosting Windows-based analytics and visualization layers on shared hardware. Integrated Development Environment deployments command the largest revenue pool as OEMs consolidate design, simulation, and commissioning workflows within unified vendor stacks. Cloud-Based deployment models represent the fastest-expanding segment, though On-Premises installations retain margin concentration in defense and critical infrastructure sectors where air-gapped operation remains mandatory. Edge Computing configurations are gaining traction in Oil & Gas distributed asset monitoring where latency constraints preclude centralized cloud architectures.
FDA 21 CFR Part 11 validation requirements shape pharmaceutical manufacturing software procurement, compelling PAC vendors to embed electronic signature and audit trail functionality. IEC 62443 cybersecurity standards for industrial automation systems are tightening product certification burdens, particularly in Utilities sector deployments where NERC CIP compliance overlays federal mandates. Stakeholders must monitor convergence between IT security frameworks and operational technology runtime certification as procurement criteria shift from feature comparison toward verifiable resilience architecture.
Market Dynamics
Deterministic control architectures are consolidating around hybrid processor platforms that merge PLC-grade reliability with PC-class computational throughput, compressing vendor differentiation toward real-time performance benchmarks and cybersecurity certification depth.
Growth Catalysts
- IEC 61131-3 Compliance Mandates:European manufacturing hubs enforce unified programming environments, compelling legacy PLC migrations toward PAC platforms with standardized structured text and function block diagram support.
- Automotive Robotic Cell Coordination:Production line builders specify PAC suites to synchronize multi-vendor robotic cells, eliminating proprietary controller fragmentation across assembly ecosystems.
- Oil & Gas Edge Deployments:Distributed asset monitoring in remote extraction sites drives demand for edge computing configurations where latency constraints preclude centralized cloud architectures.
Market Restraints
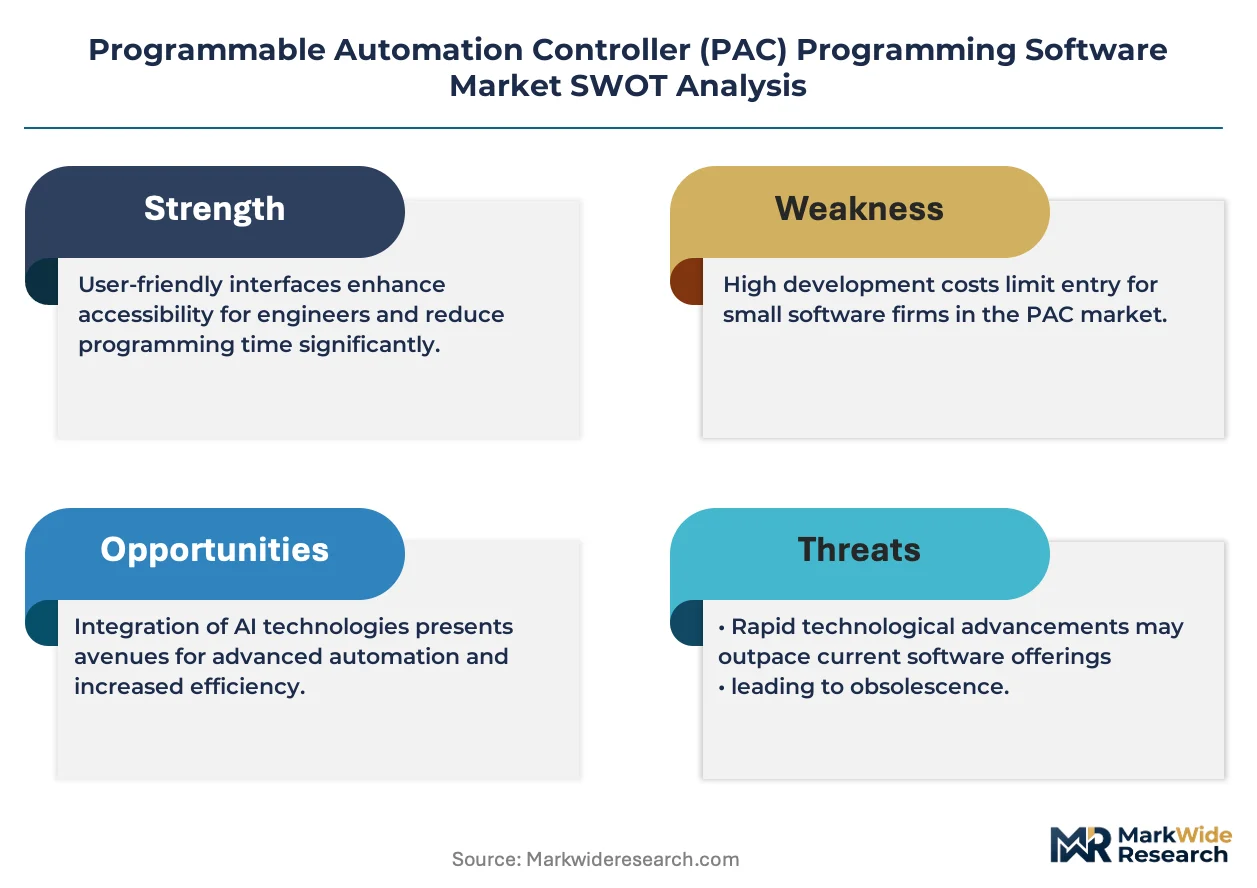
- Semiconductor Supply Concentration:Real-time processor fabrication concentrates in East Asian foundries, exposing PAC hardware vendors to geopolitical disruption and allocation constraints.
- IEC 62443 Certification Burden:Industrial cybersecurity standard compliance extends product development timelines and elevates engineering overhead for mid-tier software vendors.
- Legacy PLC Substitution Inertia:Installed base of proprietary ladder logic systems in mature manufacturing facilities resists migration despite PAC performance advantages.
Strategic Opportunities
- Pharmaceutical FDA 21 CFR Part 11 Validation:Electronic signature and audit trail functionality embedded in PAC platforms captures regulated manufacturing procurement budgets in life sciences verticals.
- Cloud-Based Deployment Models:Engineering environment virtualization enables SaaS pricing penetration among small machine builders previously excluded from perpetual license economics.
- Utilities NERC CIP Overlay:Federal critical infrastructure protection mandates create premium positioning for air-gapped PAC installations with verifiable resilience architecture.
Industry Challenges
- Deterministic Control Engineering Talent Scarcity:Sub-millisecond cycle programming expertise concentrates among aging specialist cohorts, constraining OEM deployment velocity.
- Multi-Protocol Integration Complexity:Fieldbus convergence with industrial Ethernet standards fragments commissioning workflows, extending system integration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Programmable Automation Controller (PAC) Programming Software Market |
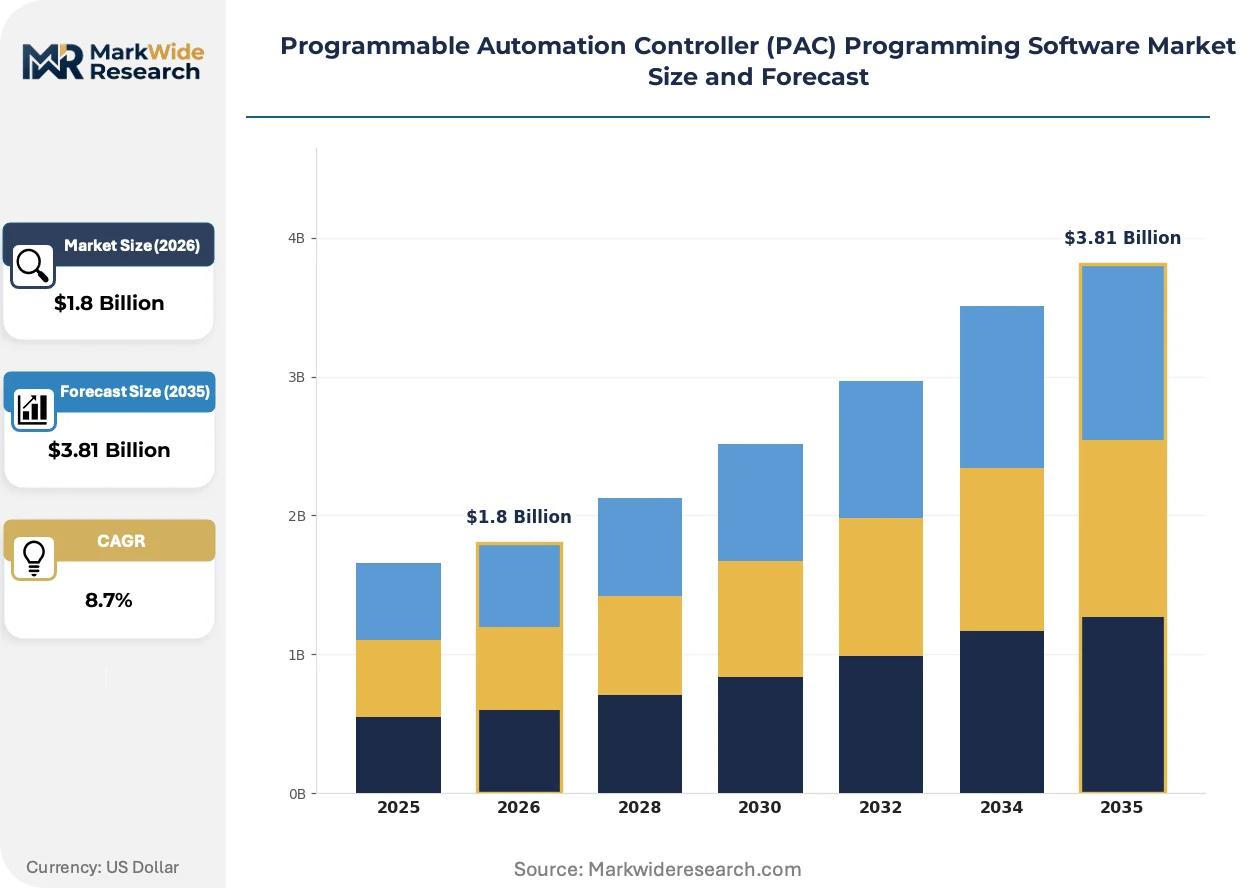
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Software Type: Integrated Development Environment, PLC Programming Software, Visual Programming Tools, Simulation Tools Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Manufacturing, Oil & Gas, Automotive, Utilities Functionality: Real-Time Monitoring, Process Automation, Data Analytics, Remote Access |
| Companies Covered | Emerson Electric Co., Mitsubishi Electric Corporation, Schneider Electric SE, Phoenix Contact GmbH, Opto 22, Rockwell Automation, Inc., ABB Ltd, Beckhoff Automation GmbH, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Programmable Automation Controller (PAC) Programming Software Market Evolving Landscape
Software-defined control architectures are compressing hardware lifecycle value capture toward runtime licensing and predictive analytics subscription layers, displacing traditional perpetual license monetization.
Containerized deterministic runtimes are displacing monolithic PAC firmware deployments by enabling modular control logic updates without production line interruption. Automotive tier-one suppliers pilot microservice-based motion control in battery assembly, compressing commissioning cycles from weeks to days. This architecture is displacing vendor-locked programming environments with portable IEC 61131-3 code repositories.
EU AI Act risk classification requirements are tightening algorithmic transparency obligations for PAC-hosted machine learning inference in safety-critical manufacturing stages. Industrial software vendors embed explainability logging and bias detection modules to preempt regulatory enforcement. German automotive OEMs now mandate AI Act documentation packages in supplier qualification questionnaires.
Machine builders are unbundling engineering software from hardware procurement, forcing PAC vendors toward standalone IDE licensing and simulation-as-a-service revenue models. North American automotive assembly ecosystems lead this disintermediation, with procurement teams separating design tool budgets from controller hardware capital expenditure. Tier-two suppliers in Michigan and Ohio now evaluate PAC platforms purely on simulation fidelity and code portability metrics.
Programmable Automation Controller (PAC) Programming Software Market Segmentation
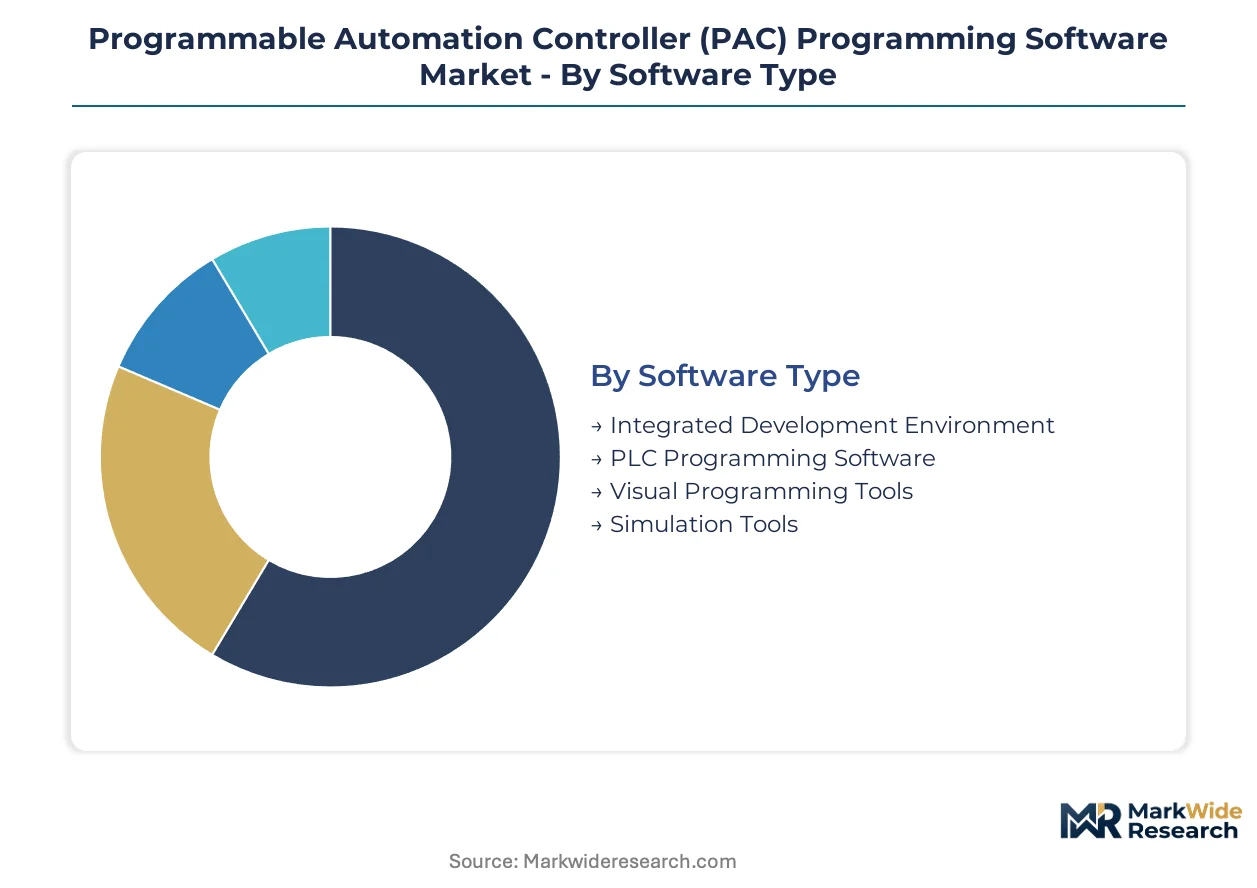
PAC programming software segmentation reveals how engineering workflows, infrastructure constraints, and regulatory environments reshape procurement patterns. Understanding these divides exposes where vendors capture margin versus where commoditization pressures concentrate.
Software Type:
Geographic demand spreads unevenly across software categories. Integrated Development Environments dominate German machine builder specifications for modular production architectures. PLC Programming Software retains strongholds in North American automotive assembly ecosystems where legacy ladder logic expertise pools. Visual Programming Tools and Simulation Tools show more export-led profiles, penetrating Asian markets lacking deep deterministic control engineering benches.
- Integrated Development Environment:Unified engineering environments compile, debug, and deploy deterministic control logic across hybrid processor architectures. German automotive OEMs mandate these platforms for coordinating multi-vendor robotic cells, compressing commissioning timelines through consolidated vendor stacks.
- PLC Programming Software:Legacy-compatible environments translate ladder logic into structured text for hybrid PAC deployments. North American automotive assembly plants specify these tools to bridge proprietary controller fragmentation without retraining maintenance crews.
- Visual Programming Tools:Drag-and-drop function block diagram interfaces lower deterministic programming barriers for small machine builders.
- Simulation Tools:Virtual commissioning environments validate control logic against digital twins before physical deployment.
Integrated Development Environment commands the established base. The steepest expansion runs through Simulation Tools.
Deployment Model:
Cost tier stratification separates deployment preferences sharply. On-Premises installations command premium pricing in defense and critical infrastructure sectors. Cloud-Based models penetrate small machine builders through SaaS economics previously inaccessible. Edge Computing configurations occupy a mid-tier position, balancing latency constraints against capital efficiency.
- On-Premises:Air-gapped installations host Windows-based analytics and visualization layers on dedicated hardware without external connectivity. Utilities sector procurement teams specify these deployments where NERC CIP compliance overlays federal mandates for verifiable resilience architecture.
- Edge Computing:Distributed processing nodes execute deterministic control with sub-millisecond cycle determinism while filtering data for cloud transmission. Oil & Gas extraction sites in remote locations deploy these configurations where latency constraints preclude centralized architectures.
- Cloud-Based:Virtualized engineering environments enable subscription pricing penetration among capital-constrained OEMs.
- Hybrid:Split architectures retain deterministic runtime on local hardware while offloading analytics to cloud infrastructure.
On-Premises retains margin concentration. Cloud-Based gains share fastest among new entrants.
End User:
Application maturity drives segment differentiation. Manufacturing and Automotive represent volume-heavy, specification-driven procurement with entrenched vendor relationships. Oil & Gas and Utilities exhibit more emergent demand profiles, where edge deployments and cybersecurity certification reshape competitive dynamics.
- Automotive:Production line builders specify PAC suites to synchronize multi-vendor robotic cells across battery assembly and powertrain manufacturing. Tier-one suppliers pilot containerized deterministic runtimes, compressing commissioning cycles from weeks to days through microservice-based motion control.
- Utilities:Federal critical infrastructure protection mandates create premium positioning for air-gapped installations with embedded electronic signature and audit trail functionality. Procurement criteria shift from feature comparison toward verifiable resilience architecture under NERC CIP compliance overlays.
- Manufacturing:Machine builders consolidate design, simulation, and commissioning workflows within unified vendor stacks.
- Oil & Gas:Distributed asset monitoring in remote extraction sites drives edge computing adoption.
Manufacturing holds the volume base. Utilities climbs fastest on regulatory tailwinds.
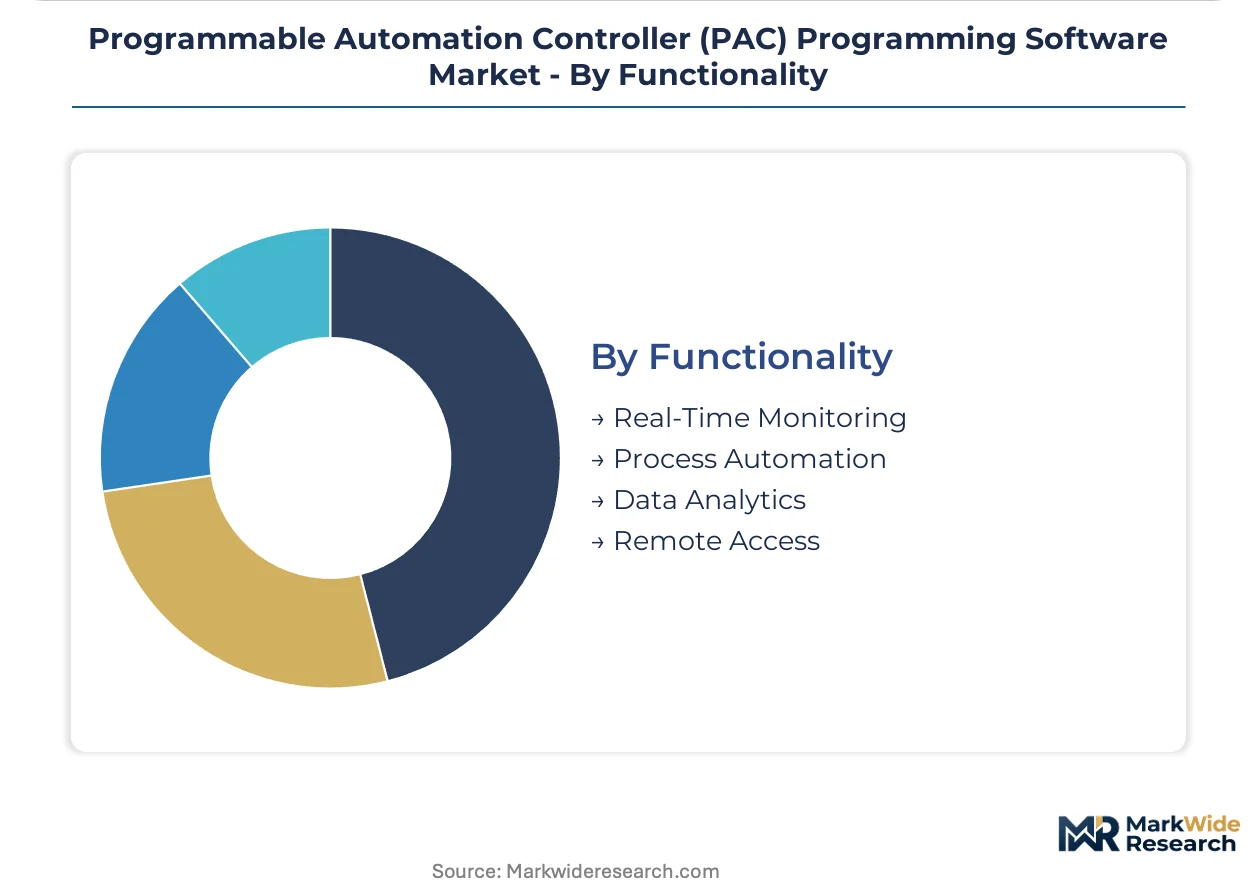
Functionality:
Customer type splits functionality demand. Process Automation and Real-Time Monitoring serve established OEMs with deterministic control expertise. Data Analytics and Remote Access attract newer entrants seeking predictive maintenance capabilities without deep engineering benches.
- Process Automation:Deterministic control logic execution with IEC 61131-3 structured text and function block diagram support. European manufacturing hubs enforce unified programming environments, compelling legacy PLC migrations toward PAC platforms with standardized code repositories.
- Data Analytics:Windows-based computational layers host machine learning inference and predictive maintenance algorithms on shared PAC hardware. EU AI Act risk classification requirements tighten algorithmic transparency obligations, compelling vendors to embed explainability logging and bias detection modules.
- Real-Time Monitoring:Sub-millisecond cycle visualization of control system states for operator decision support.
- Remote Access:Secure connectivity for distributed asset management and vendor support interventions.
Process Automation anchors installed revenue. Data Analytics expands most quickly on AI Act compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Real-time processor fabrication concentrates in East Asian foundries, exposing PAC hardware vendors to geopolitical disruption. European manufacturing hubs enforce IEC 61131-3 compliance mandates. North American automotive assembly ecosystems sustain deep vendor penetration through legacy integration requirements.
Germany
Machine builders in Bavaria and Baden-Württemberg specify PAC software for modular production architectures. The EU AI Act risk classification requirements tighten algorithmic transparency obligations for PAC-hosted machine learning inference. Stuttgart's automotive OEMs now mandate AI Act documentation packages in supplier qualification questionnaires.
United States
Tier-two suppliers in Michigan and Ohio evaluate PAC platforms purely on simulation fidelity and code portability metrics. FDA 21 CFR Part 11 validation requirements shape pharmaceutical manufacturing software procurement in New Jersey and Massachusetts clusters. Detroit's automotive assembly plants specify PLC programming software to bridge proprietary controller fragmentation.
China
MIIT industrial internet initiatives accelerate edge computing adoption in Yangtze River Delta manufacturing zones. GB standards for industrial automation systems create localization requirements for foreign PAC vendors. Shenzhen's electronics assembly ecosystems drive demand for visual programming tools among small machine builders.
Japan
METI digital manufacturing roadmaps push precision motion applications toward PC-based control architectures. JIS standards for industrial software certification elevate engineering overhead for mid-tier vendors. Nagoya's automotive component suppliers pilot containerized deterministic runtimes in battery assembly lines.
South Korea
Seoul Capital Area semiconductor fabrication facilities demand sub-millisecond cycle determinism exceeding traditional PLC capability. MFDS pharmaceutical manufacturing regulations mirror FDA validation frameworks for electronic signature functionality. Busan's shipbuilding automation sector specifies air-gapped PAC installations for cyber-resilient operations.
Programmable Automation Controller (PAC) Programming Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the PAC programming software market. European industrial conglomerates anchor premium positioning through unified engineering environments, while specialized automation houses compete on deterministic performance benchmarks. Three archetypes dominate: diversified industrial technology groups, pure-play automation specialists, and emerging cloud-native entrants. Competitive moves concentrate on strategic partnerships for protocol convergence and portfolio diversification into simulation-as-a-service revenue models.
Among diversified industrial technology groups, Siemens AG and Rockwell Automation, Inc. exemplify scale-driven archetypes with deep entrenchment in automotive assembly ecosystems. Beckhoff Automation GmbH occupies a specialist position representing PC-based control architecture purity. These three companies anchor the competitive structure, with European-based conglomerates leveraging IEC compliance mandates and North American players sustaining advantage through legacy integration depth.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Mitsubishi Electric Corporation |
| Schneider Electric SE |
| Phoenix Contact GmbH |
| Opto 22 |
| Rockwell Automation, Inc. |
| ABB Ltd |
| Beckhoff Automation GmbH |
| Siemens AG |
| Others |
Value Network & Pricing Analysis
Ninety-day component lead times for real-time processors compress inventory buffers and amplify pricing power for East Asian foundries serving PAC hardware vendors. This supply concentration shapes tiered software licensing structures, with premium deterministic control suites commanding sustained margins while mid-market offerings face cost compression.
Pricing Analysis
IEC 62443 cybersecurity certification dictates the pricing tier structure across PAC programming software, separating premium-validated suites from uncertified alternatives. Three-tier pricing stratifies across enterprise-grade platforms with full audit trails, professional editions with limited compliance features, and entry-level tools lacking deterministic runtime guarantees. Price differentiation rests on certification depth and after-sales engineering support intensity. Pricing pressure stems from cloud-native entrants undercutting perpetual license economics with subscription models. Small machine builders in Asian markets exhibit highest price sensitivity, while utilities and defense procurement teams prioritize certified resilience over cost.
Supply Chain Analysis
Strategic stockpiling of industrial-grade processors has displaced just-in-time preferences among PAC hardware vendors confronting geopolitical allocation risks. Semiconductor fabrication concentrates in Taiwan, South Korea, and China, with advanced node real-time processors sourcing from TSMC and Samsung foundries. Supply chains draw from rare earth elements for magnetic components, specialized industrial DRAM, and precision analog chips. Single-source vulnerability in advanced node capacity creates structural exposure to export control restrictions. Distribution runs through authorized industrial automation distributors with embedded application engineering capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Simulation-as-a-service revenue layers expand faster than hardware procurement cycles, transforming PAC programming software into a recurring-revenue service attach opportunity. Runtime licensing and predictive analytics subscriptions now outpace perpetual license growth in new customer acquisitions.
For Market Incumbents: Compound defensive positioning through IEC 62443 certification depth and unified engineering environment stickiness. Cloud-native entrants threaten mid-market share with containerized deterministic runtimes; counter through backward integration into edge hardware to tighten runtime control. Prioritize simulation-as-a-service capacity expansion in German automotive corridors where digital twin fidelity drives procurement decisions.
For New Entrants and Emerging Players: Lead with cloud-based deployment models targeting capital-constrained small machine builders in Shenzhen and Yangtze River Delta zones. Visual programming tools for electronics assembly ecosystems offer lowest competitive density. Go-to-market through industrial automation distributors lacking native software capabilities, embedding commission structures that displace incumbent maintenance contract renewals.
For Investors and Strategic Acquirers: Long-term, this sits as a vertical software consolidation play because deterministic control engineering talent scarcity creates durable moats around specialized platforms. Acquisition targets cluster around PC-based control architecture specialists with precision motion expertise and established pharmaceutical validation track records. Watch FDA 21 CFR Part 11 enforcement intensity as inflection signal—accelerated validation requirements compress vendor qualification timelines and favor pre-certified assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies IEC 61131-3 compilation with Windows-based analytics layers for German automotive OEMs. |
| Acquisition of Specialist Firm | Captures containerized deterministic runtime expertise from battery assembly pilot programs in Nagoya. |
| Strategic Partnership | Links PAC vendors with industrial Ethernet protocol consortia to reduce multi-protocol integration friction. |
| Product Launch | Introduces AI Act-compliant explainability modules for EU pharmaceutical manufacturing deployments. |
| Geographic Expansion | Establishes edge computing configurations in remote Oil & Gas extraction sites across South Korean shipbuilding zones. |
Research Methodology
Operator-level perspectives from control systems engineers, OEM procurement managers, industrial automation distributors, and aftermarket service heads anchored the qualitative base. Primary interviews combined with secondary validation from IEC standards documentation, SEC filings of listed industrial conglomerates, customs trade data for automation equipment, and hyperscaler edge computing capex disclosures. Bottom-up deployment modeling across software type, deployment model, and end-use vertical triangulated against top-down market sizing from vendor revenue disclosures.
Sensitivity analysis tested forecast robustness across semiconductor supply disruption scenarios, regulatory enforcement intensity variations, and cloud adoption acceleration curves. Segmentation dimensions modeled span software type, deployment model, end-use industry, and regional regulatory cluster complexity. CAGRs derived from installed base migration rates, new license bookings trajectory, and recurring revenue expansion patterns. Industry-specific inputs include IEC 61131-3 compliance mandate enforcement timelines and FDA 21 CFR Part 11 validation requirement adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained semiconductor supply availability, stable regulatory enforcement patterns, or continued deterministic control talent scarcity would require recalibration. Forecasts reflect documented assumptions about migration inertia from legacy PLC systems and cloud security certification maturation. Revision becomes warranted when geopolitical disruption in East Asian foundry capacity crosses allocation threshold triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Software Construction Components Market
Software & Services
Metal Fabrication Software Market
Software & Services
Auto Software Market
Software & Services
Software As a Service (Saas) Market
Software & Services
North America IT Services Market
Software & Services
Intellectual Property Software Market
Software & Services
Global Storm Tracking Apps Market
Software & Services
CAD Modeling Software Market
Software & Services
Account-Based Direct Mail Software Market
Software & Services
Pay-Per-Click (PPC) Software Market
Software & Services
Global Electronic Data Capture Software Market
Software & Services
Application Development and Deployment Software Market
Software & Services
Drone Mapping Software Market
Software & Services
Audio and Video Editing Software Market
Software & Services
UI Design Software Market
Software & Services
Global Content Management Software Market