
 PAC Programming Software Market | 2026-2036
PAC Programming Software Market Size, Share, and Industry Trends Forecast 2026-2036
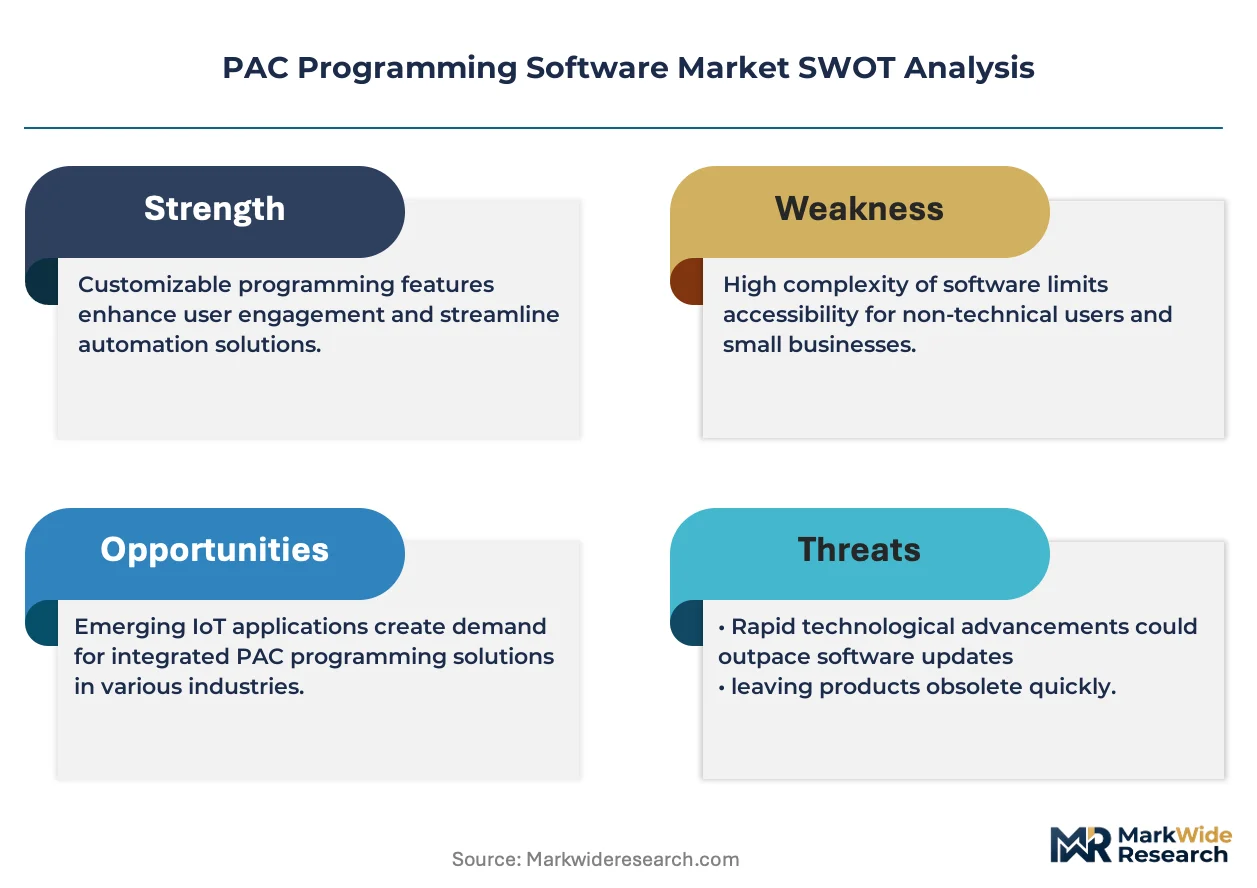
PAC Programming Software Market Analysis
Cloud-native runtime environments are consolidating control-system architectures across process industries. Schneider Electric SE leverages its EcoStruxure platform to anchor hybrid deployment pipelines for multi-site manufacturing clients. Rockwell Automation, Inc. competes through FactoryTalk Design Studio, which sustains deep integration with its Logix hardware ecosystem. Siemens AG dominates European energy management accounts through TIA Portal, extending PAC programming into grid-edge automation workflows.
PAC programming software comprises integrated development environments, runtime engines, and communication protocol stacks that configure programmable automation controllers for deterministic industrial control. These tools execute ladder logic, structured text, and function block diagrams with cycle times measured in milliseconds to orchestrate motors, valves, and sensors across distributed processes. Advanced development tools command the widest installed base as legacy migration projects accumulate, while simulation software captures the fastest expansion as virtual commissioning reduces physical prototype costs. Cloud-based deployment attracts new utility sector entrants seeking centralized fleet management without on-premise infrastructure overhead.
The US EPA enforces cybersecurity standards for water treatment SCADA systems, compelling PAC software vendors to embed encrypted firmware signing and access logging. Germany's BSI IT-Grundschutz framework shapes product certification requirements for industrial control software sold into critical infrastructure. The EU Cyber Resilience Act mandates automated patch delivery and vulnerability disclosure timelines, forcing vendors to rearchitect update mechanisms. Stakeholders must evaluate whether their PAC programming roadmaps accommodate mandatory security-by-design mandates before procurement cycles harden around compliant supplier shortlists.
Market Dynamics
Cloud-native runtime environments are consolidating control-system architectures across process industries, compressing deployment cycles from months to weeks while forcing vendors to rearchitect legacy codebases for containerized orchestration.
Growth Catalysts
- EPA Cybersecurity Mandates:The US EPA enforces encrypted firmware signing for water treatment SCADA systems, compelling utilities to upgrade PAC software stacks and expand procurement budgets for compliant solutions.
- Digital Twin Adoption:German water treatment utilities are expanding PAC software deployment as EPA-aligned digital twin requirements tighten operational visibility standards.
- Cloud Migration:Cloud-based deployment models concentrate procurement attention in the United States industrial corridor, attracting new utility sector entrants seeking centralized fleet management without on-premise infrastructure overhead.
Market Restraints
- Legacy Codebase Inertia:Deep integration with proprietary hardware ecosystems creates switching costs that lock manufacturing clients into incumbent vendor relationships.
- Certification Timeline Friction:Germany's BSI IT-Grundschutz framework shapes product certification requirements, extending time-to-revenue for industrial control software sold into critical infrastructure.
- Skill Concentration:Deterministic programming expertise in ladder logic and structured text concentrates among aging technician populations in Midwestern US manufacturing clusters.
Strategic Opportunities
- EU Cyber Resilience Act:Automated patch delivery mandates create service revenue streams for vendors who rearchitect update mechanisms before procurement cycles harden around compliant supplier shortlists.
- Virtual Commissioning:Simulation software captures expansion as virtual commissioning reduces physical prototype costs across automotive and aerospace manufacturing workflows.
- Grid-Edge Automation:Siemens AG's extension of PAC programming into European energy management accounts reveals whitespace for grid-edge orchestration tools in distributed renewable integration.
Industry Challenges
- Millisecond-Cycle Talent Scarcity:Programming expertise for deterministic cycle times measured in milliseconds concentrates among specialists nearing retirement in Rust Belt manufacturing corridors.
- Protocol Stack Fragmentation:Communication protocol heterogeneity across distributed processes forces integration engineering that extends deployment timelines and strains project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PAC Programming Software Market |
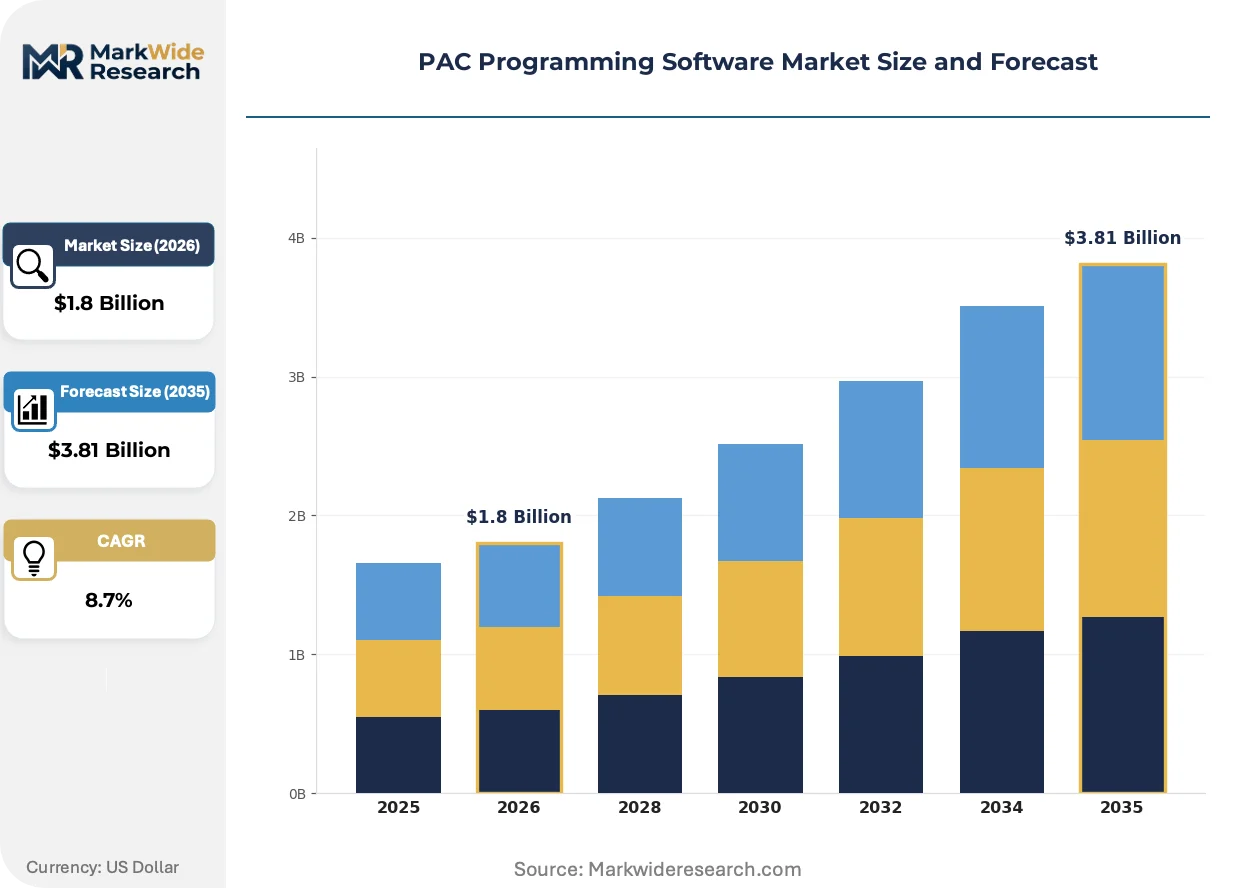
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basic Programming Software, Advanced Development Tools, Simulation Software, Debugging Software Application: Industrial Automation, Building Management, Water Treatment, Energy Management End User: Agriculture, Manufacturing, Transportation, Utilities Deployment: On-Premise, Cloud-Based, Hybrid, Remote Access |
| Companies Covered | Schneider Electric SE, Rockwell Automation, Inc., Siemens AG, Mitsubishi Electric Corporation, Emerson Electric Co., ABB Ltd, Opto22, Phoenix Contact Pvt Ltd, National Instruments Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PAC Programming Software Market Emerging Trajectories
Deterministic control architectures are fragmenting as software-defined automation redefines how industrial processes are orchestrated, commissioned, and maintained across distributed manufacturing footprints.
Containerized runtime engines are overtaking monolithic PAC operating systems in greenfield deployments. These engines package control logic with dependencies for consistent execution across edge, on-premise, and cloud substrates. Automotive OEMs in Stuttgart and Wolfsburg are adopting them for flexible line reconfiguration. The technology is overtaking traditional bare-metal installations by collapsing commissioning timelines from eighteen months to under ninety days.
The EU Cyber Resilience Act mandates automated patch delivery and vulnerability disclosure timelines for industrial control software sold into European critical infrastructure. Vendors must rearchitect update mechanisms to comply with mandatory security-by-design mandates before procurement cycles harden. German energy utilities and French water treatment operators are responding by pre-qualifying suppliers with demonstrated automated firmware pipelines.
Subscription-based licensing is displacing perpetual seat purchases among mid-cap manufacturing clients seeking to convert capital expenditure into operational expenditure. Industrial software distributors in the US Great Lakes region are unbundling implementation services from license fees to capture recurring revenue. This shift is most visible among precision machining shops in Michigan and Ohio that prioritize cash flow flexibility over long-term asset ownership.
PAC Programming Software Market Segmentation
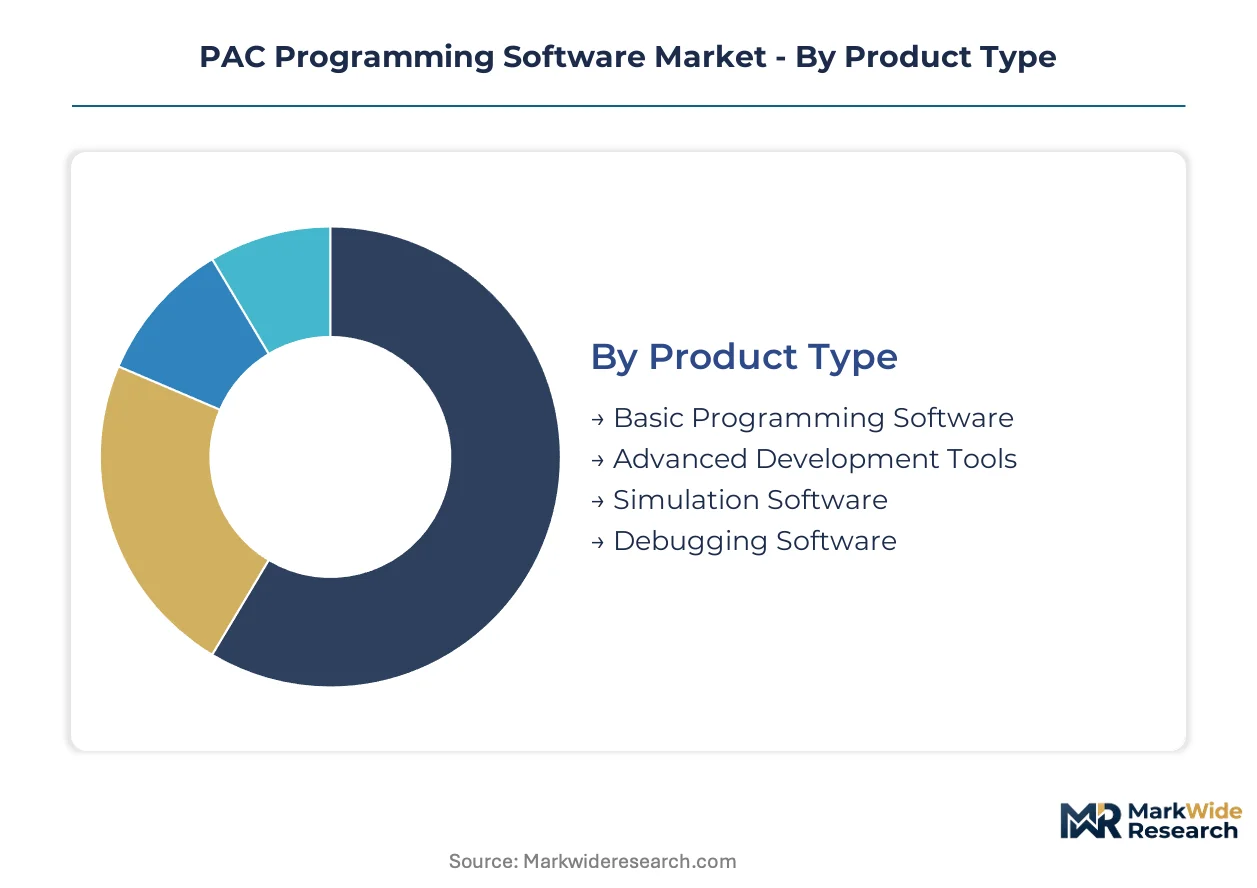
PAC programming software segments reflect divergent buyer priorities across deterministic control requirements, infrastructure maturity, and regulatory exposure. Procurement patterns split between legacy migration projects demanding deep hardware integration and greenfield deployments prioritizing cloud-native orchestration.
Product Type:
Volume concentrates in entry-level tools, while premium pricing attaches to integrated simulation and debugging suites.
- Basic Programming Software:Ladder logic editors and simple configuration wizards dominate small-to-mid manufacturing accounts in Ohio and Michigan. Rust Belt machining shops prioritize low upfront cost over advanced features, though EPA cybersecurity mandates are forcing upgrade cycles.
- Advanced Development Tools:Structured text compilers, integrated version control, and multi-vendor protocol gateways anchor enterprise automation portfolios. German automotive OEMs in Stuttgart and Wolfsburg specify these for flexible line reconfiguration and digital twin integration.
- Simulation Software:Virtual commissioning environments reduce physical prototype costs across aerospace supply chains.
- Debugging Software:Runtime diagnostics and deterministic cycle analyzers serve millisecond-precision applications in semiconductor fabrication.
Today's leader: Advanced Development Tools. Tomorrow's challenger: Simulation Software.
Application:
End-use demand fragments across process intensity, regulatory scrutiny, and integration complexity.
- Industrial Automation:Assembly line orchestration, robotic workcell coordination, and material handling systems consume the largest license volume. Discrete manufacturing in the US Great Lakes region drives perpetual seat purchases despite subscription momentum elsewhere.
- Building Management:HVAC control, lighting automation, and energy optimization integrate PAC logic with BMS protocols. Commercial real estate developers in Frankfurt specify these for CE-marked smart building certifications under EU Green Deal efficiency mandates.
- Water Treatment:SCADA-integrated PAC stacks face EPA encrypted firmware requirements for municipal utilities.
- Energy Management:Grid-edge automation and renewable integration expand fastest among European distribution operators.
Industrial Automation holds installed base dominance. Water Treatment is climbing the fastest on regulatory compulsion.
End User:
Customer sophistication determines pricing tolerance and service attachment rates.
- Manufacturing:Automotive, aerospace, and precision machining operations generate the deepest per-seat revenue. Tier-1 suppliers in Stuttgart demand 24/7 vendor support contracts bundled with TIA Portal and FactoryTalk licenses.
- Utilities:Electric, gas, and water infrastructure operators prioritize cybersecurity certification and automated patch pipelines. German BSI IT-Grundschutz compliance pre-qualifies vendor shortlists for critical infrastructure procurement.
- Transportation:Rail signaling and port automation specify deterministic cycle guarantees.
- Agriculture:Irrigation control and livestock climate systems represent emerging demand with price-sensitive procurement.
Manufacturing commands margin premiums. Utilities are gaining share fastest on infrastructure hardening budgets.
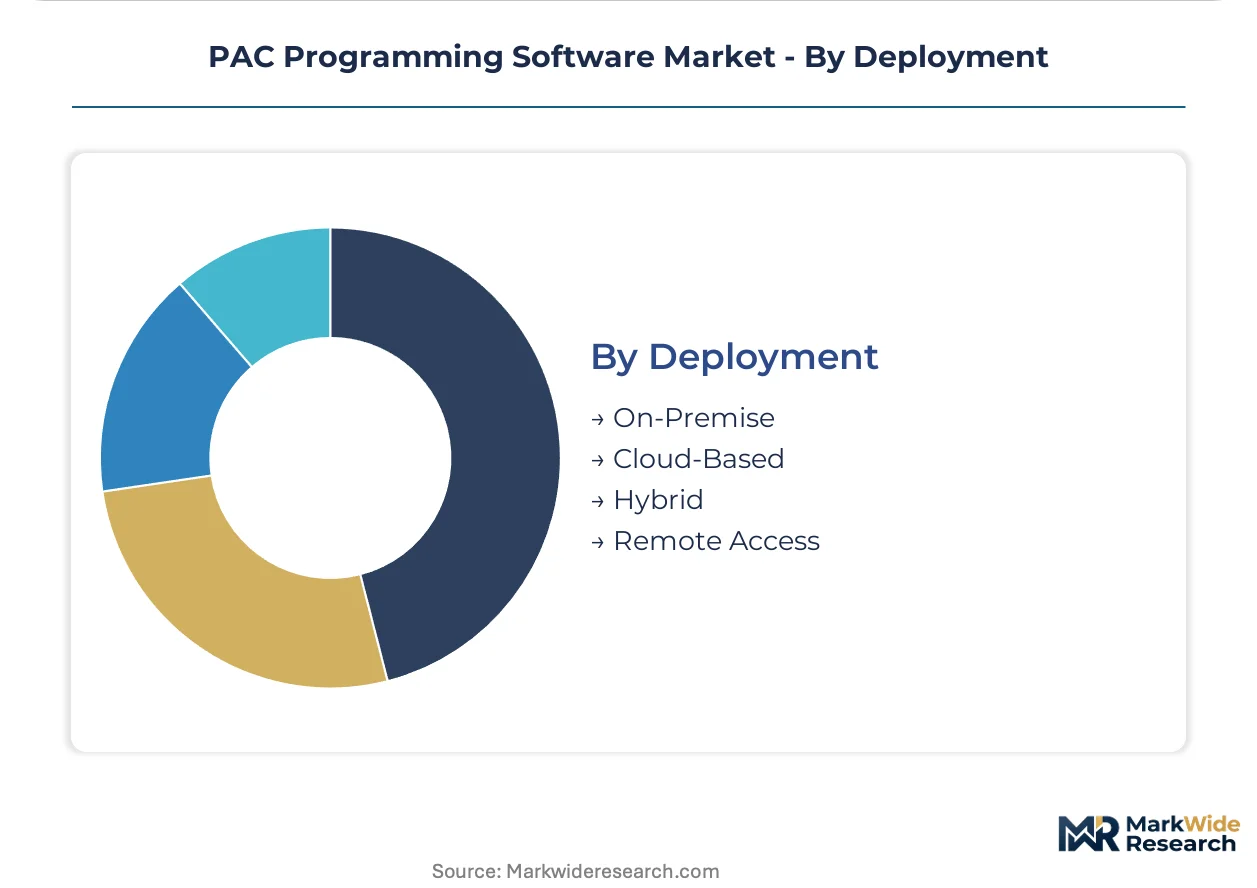
Deployment:
Infrastructure ownership preferences split capital expenditure conversion from control retention.
- Cloud-Based:Containerized runtime engines enable centralized fleet management without on-premise overhead. US water utilities expanding EPA-aligned digital twins favor this model for scalable cybersecurity monitoring.
- Hybrid:Edge-orchestrated control logic with cloud-based analytics satisfies German manufacturing clients requiring local determinism plus remote visibility. Siemens EcoStruxure deployments in Wolfsburg automotive plants exemplify this architecture.
- On-Premise:Bare-metal installations persist where air-gapped security or sub-millisecond latency is non-negotiable.
- Remote Access:VPN-secured programming terminals support distributed maintenance for multi-site operations.
Hybrid architectures dominate greenfield specifications. Cloud-Based is expanding most quickly among utility sector entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive manufacturing clusters in Stuttgart and Wolfsburg anchor European PAC software procurement intensity. German water treatment utilities are expanding adoption as EPA-aligned digital twin requirements tighten operational visibility standards. Cloud-based deployment models concentrate procurement attention in the United States industrial corridor.
United States
Water treatment utilities across the Great Lakes and Ohio River basins are modernizing SCADA-integrated PAC stacks. EPA cybersecurity mandates enforce encrypted firmware signing for municipal infrastructure operators. Precision machining shops in Michigan and Ohio prioritize subscription licensing to convert capital expenditure into operational expenditure.
Germany
Automotive OEMs in Stuttgart and Wolfsburg specify advanced development tools for flexible line reconfiguration and digital twin integration. BSI IT-Grundschutz framework shapes product certification requirements for critical infrastructure procurement. Energy management accounts in Bavaria and North Rhine-Westphalia extend PAC programming into grid-edge automation workflows.
China
Process industries along the Yangtze River Delta are consolidating control-system architectures through cloud-native runtime environments. National cybersecurity standards for industrial control systems compel vendors to embed automated patch delivery mechanisms. Manufacturing clients in Shenzhen and Shanghai demand containerized orchestration for greenfield deployments.
Japan
Semiconductor fabrication facilities in Kyushu and Chubu require deterministic cycle analyzers for millisecond-precision applications. METI industrial digitalization initiatives accelerate virtual commissioning adoption across automotive supply chains. Robotics integrators in Nagoya and Osaka specify PAC software with deep hardware ecosystem integration.
India
Automotive component suppliers in Maharashtra and Tamil Nadu are migrating from basic ladder logic editors to structured text compilers. PLI scheme incentives for advanced manufacturing equipment expand procurement budgets for integrated development environments. Industrial automation distributors in Pune and Chennai unbundle implementation services from license fees to capture recurring revenue.
PAC Programming Software Market Vendor Landscape
Global majors compete with regional champions across hardware-software integration depth and cloud-native orchestration capabilities. The vendor base splits between consolidated platform providers with end-to-end automation portfolios and specialized developers serving discrete protocol requirements. Three archetypes dominate: ecosystem-anchored incumbents with captive hardware lines, cloud-native challengers with containerized runtime engines, and regional specialists with deep local certification expertise. Competitive moves center on strategic partnerships for multi-vendor protocol gateways and portfolio diversification into simulation and virtual commissioning suites.
Within the ecosystem-anchored tier, Schneider Electric SE, Rockwell Automation, Inc., and Siemens AG exemplify divergent geographic positioning. The French multinational leverages its EcoStruxure platform to anchor hybrid deployment pipelines for multi-site manufacturing clients. The Milwaukee-based automation supplier competes through FactoryTalk Design Studio with deep integration into its Logix hardware ecosystem. The German industrial conglomerate dominates European energy management accounts through TIA Portal, extending PAC programming into grid-edge automation workflows.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Rockwell Automation, Inc. |
| Siemens AG |
| Mitsubishi Electric Corporation |
| Emerson Electric Co. |
| ABB Ltd |
| Opto22 |
| Phoenix Contact Pvt Ltd |
| National Instruments Corporation |
| Others |
Supply Flow & Price Mechanics
Containerized runtime engines are compressing deployment economics while redistributing value capture toward orchestration-layer vendors. The shift from perpetual licensing to subscription consumption simultaneously flattens upfront revenue curves and concentrates procurement leverage among cloud-native platform providers.
Pricing Analysis
Input-cost pass-through from embedded security modules and certified firmware pipelines is reshaping tier boundaries. Three-tier pricing structure across premium, standard, and economy levels segments by certification depth and after-sales service bundling. Cost compression in the economy tier is intensifying because Rust Belt machining shops prioritize cash flow flexibility over feature depth. Manufacturing commands the least price sensitivity due to 24/7 support requirements, while agriculture irrigation operators exhibit the highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements for critical infrastructure procurement are fragmenting vendor concentration across Germany, the United States, and Japan. Semiconductor fabrication equipment and encrypted firmware signing modules draw from Taiwan, South Korea, and specialized German foundries. Single-source vulnerability in deterministic cycle analyzer components creates exposure for millisecond-precision applications. Distribution runs through industrial software distributors in the US Great Lakes region and certified system integrators in Stuttgart and Wolfsburg.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PAC programming software has entered a late-cycle quality phase where EPA cybersecurity mandates and EU Cyber Resilience Act compliance separate premium vendors from commodity suppliers. Buyers now pre-qualify automated patch delivery capabilities before issuing RFPs.
For Market Incumbents: Lock in certification moats by accelerating BSI IT-Grundschutz and EPA-aligned firmware signing investments before procurement cycles harden. Vertical integration into containerized runtime engines preserves margin structure against cloud-native challengers. Channel control through certified system integrator networks in German automotive clusters defends against direct SaaS disintermediation. For New Entrants and Emerging Players: Cloud-native runtime marketplaces offer the lowest friction entry path for containerized orchestration tools targeting US water utilities. White-space concentrates in grid-edge automation for European renewable integration and virtual commissioning suites for aerospace supply chains. Partner with industrial software distributors in Michigan and Ohio to unbundle implementation from license fees. For Investors and Strategic Acquirers: Roll-up economics work for specialized debugging and simulation developers because deterministic programming expertise concentrates among aging specialists in Rust Belt corridors. Five-to-ten year viability hinges on automated patch delivery infrastructure and multi-vendor protocol gateway portfolios. Watch for EPA enforcement actions against non-compliant municipal utilities as the inflection signal for accelerated replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | EcoStruxure and TIA Portal consolidation captures multi-site manufacturing accounts in Wolfsburg. |
| Acquisition of Specialist Firm | Virtual commissioning developers reduce automotive prototype costs for Stuttgart OEMs. |
| Geographic Expansion | Cloud-native entrants target EPA-mandated water treatment utilities across Ohio River basins. |
| Strategic Partnership | Multi-vendor protocol gateways address fragmentation across distributed process industries. |
| Product Launch | Deterministic cycle analyzers serve semiconductor fabrication in Kyushu and Chubu regions. |
Methodological Framework
Coverage spans the United States, Germany, China, Japan, and India, with primary inputs from each regional cluster. The analysis combines structured interviews with automation engineering directors, plant IT managers, industrial software procurement leads, and certified system integrators with secondary validation through SEC filings, EPA enforcement databases, BSI certification registries, and EIA industrial power consumption data. Bottom-up license volume estimates triangulate against top-down infrastructure spending projections.
Rate-of-change decomposition separates volume effects from value mix shifts across the projection horizon. The framework models deployment model, end-user sophistication tier, application intensity, and regional regulatory cluster as primary segmentation dimensions. CAGRs derive from license shipment trajectories, subscription conversion rates, and certified product premium capture. Forecast inputs include EPA cybersecurity mandate implementation pace and EU Cyber Resilience Act compliance timelines.
The model assumes a particular technology adoption path; alternative pathways for bare-metal deterministic controllers versus containerized runtimes would alter the outlook. Forecasts reflect assumptions about regulatory enforcement continuity and cloud migration willingness among Midwestern manufacturers. Deviation in EPA penalty severity or BSI certification timeline compression would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Data Discovery Software Market
Software & Services
Global Electrical Computer-Aided Design (ECAD) Market
Software & Services
Enterprise Search Software Market
Software & Services
Customs Declaration Software Market
Software & Services
Software Licensing Market
Software & Services
Programmable Automation Controller Software Market
Software & Services
Salesforce Services Market
Software & Services
Web Scraping Software Market
Software & Services
US Digital Marketing Software Market
Software & Services
System Infrastructure Software Market
Software & Services
Global Document Management Software Market
Software & Services
Global Headless CMS Software Market
Software & Services
Weather Forecast Software Market
Software & Services
Photobooth Software Market
Software & Services
Global Desktop As a Service Market
Software & Services
Global Fixed Asset Management Software Market