
 Metal Fabrication Software Market | 2026-2036
Metal Fabrication Software Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Fabrication Software Market Foresight
The EU Green Deal is hardening carbon accounting mandates for industrial software vendors serving European metal fabricators. Autodesk leverages generative design capabilities to help manufacturers optimize material yield and scrap reduction. Siemens anchors its position through deep integration between PLM and CNC programming environments. Dassault Systèmes competes on digital twin fidelity for complex sheet metal forming simulations.
Metal fabrication software encompasses CAD, CAM, ERP, and estimation platforms that govern design-to-production workflows for cutting, bending, welding, and assembling metal components. These systems integrate 3D modeling engines with CNC post-processors to translate digital geometries into machine-executable instructions, typically supporting ISO 6983 G-code standards and native controller dialects. Cloud-based deployment is gaining share fastest as job shops seek to eliminate on-premises server maintenance and enable remote quoting capabilities. CAM software occupies the deepest margin pools due to tight vendor concentration in advanced nesting and toolpath optimization.
EPA enforcement of hazardous air pollutant standards under NESHAP shapes software requirements for emissions tracking in US fabrication facilities. OSHA lockout/tagout regulations drive demand for safety-integrated workflow modules that synchronize maintenance calendars with production schedules. Stakeholders must monitor how emerging SEC climate disclosure rules will cascade into supplier-facing carbon reporting obligations for metal service centers.
Market Dynamics
Cloud-native CAM architectures are compressing deployment timelines for job shops while EU carbon disclosure mandates force software vendors to embed emissions tracking directly into production planning modules.
Growth Catalysts
- NESHAP compliance automation:EPA enforcement of hazardous air pollutant standards requires fabrication facilities to maintain granular emissions logs, driving demand for integrated environmental reporting modules.
- Automotive OEM workflow modernization:Tier-1 suppliers in Michigan and Ohio are replacing disconnected CAD-to-CNC handoffs with unified PLM-CAM pipelines to reduce tooling changeover delays.
- Generative design adoption:Aerospace manufacturers are deploying topology optimization engines to minimize material waste in titanium structural components, accelerating software refresh cycles.
Market Restraints
- Legacy controller dialect fragmentation:Proprietary G-code extensions from Fanuc, Siemens, and Heidenhain force CAM vendors to maintain expensive post-processor libraries that inflate R&D overhead.
- Skilled CNC programmer scarcity:The retirement wave of machinists trained on manual G-code editing creates bottlenecks for shops attempting to deploy advanced nesting algorithms.
- On-premises data gravity:Job shops with 15-year-old ERP investments face sunk-cost resistance when evaluating cloud-native fabrication platforms despite lower total cost of ownership.
Strategic Opportunities
- Remote quoting capabilities:Cloud-based estimation platforms enable metal service centers to turn around complex bending and welding quotes without physical site visits, penetrating construction and agricultural equipment verticals.
- CSRD-aligned carbon accounting:The EU Corporate Sustainability Reporting Directive creates mandatory scope 3 disclosure requirements that fabrication software can address through embedded supply chain emissions calculators.
- Digital twin convergence:Sheet metal forming simulations that couple Dassault Systèmes' Abaqus solvers with real-time press force data open predictive maintenance revenue streams for software vendors.
Industry Challenges
- ISO 6983 standardization gaps:Inconsistent G-code interpreter implementations across CNC controller generations force fabricators to maintain parallel post-processor testing environments.
- Lockout/tagout workflow integration:OSHA-mandated safety protocols require software vendors to synchronize maintenance calendars with production schedules, adding complexity to ERP-CAM integrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Fabrication Software Market |
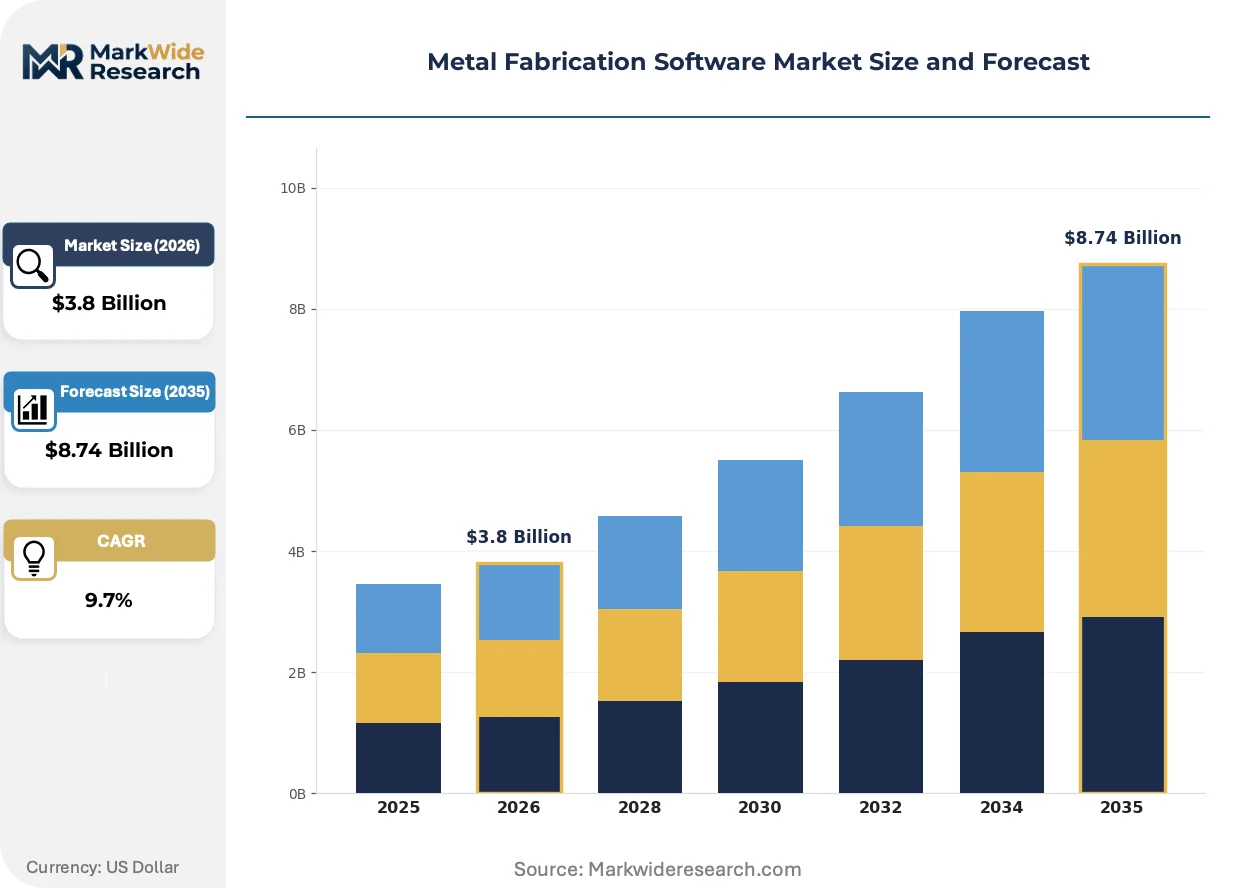
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CAD Software, CAM Software, ERP Software, Estimation Software End User: Fabricators, OEMs, Contractors, Consultants Deployment: On-Premises, Cloud-Based, Hybrid, SaaS Feature: 3D Modeling, CNC Programming, Workflow Automation, Inventory Management |
| Companies Covered | Global Shop Solutions, Fishbowl Manufacturing, Realtrac, Autodesk, Dassault Systèmes, Siemens, SigmaNEST, JobBOSS², MIE Trak Pro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Fabrication Software Market Shifts & Advancements
Artificial intelligence is penetrating nesting and toolpath generation while regulatory pressure hardens emissions traceability requirements across supply chains.
AI-powered nesting engines are electrifying material yield optimization by analyzing remnant inventory geometries against incoming job queues. Mid-size job shops in Indiana and Pennsylvania are piloting these systems to reduce aluminum scrap rates. The technology is compressing quoting-to-cutting timelines from hours to minutes for complex multi-part assemblies.
The EU Green Deal is hardening carbon accounting mandates that cascade into software procurement specifications for metal fabricators serving automotive and construction OEMs. Vendors must now demonstrate embedded emissions tracking across scope 1, 2, and 3 categories to qualify for enterprise contracts. German aerospace suppliers are requiring ISO 14064-aligned carbon calculation modules as standard evaluation criteria.
Subscription pricing models are displacing perpetual license structures among job shops with irregular capital expenditure cycles. Cloud-native CAM vendors are capturing share from on-premises incumbents by eliminating server maintenance burdens and enabling remote programmer access. This shift concentrates in the United States where automotive supplier consolidation has reduced the number of independent fabrication facilities willing to absorb large upfront software investments.
Metal Fabrication Software Market Segmentation
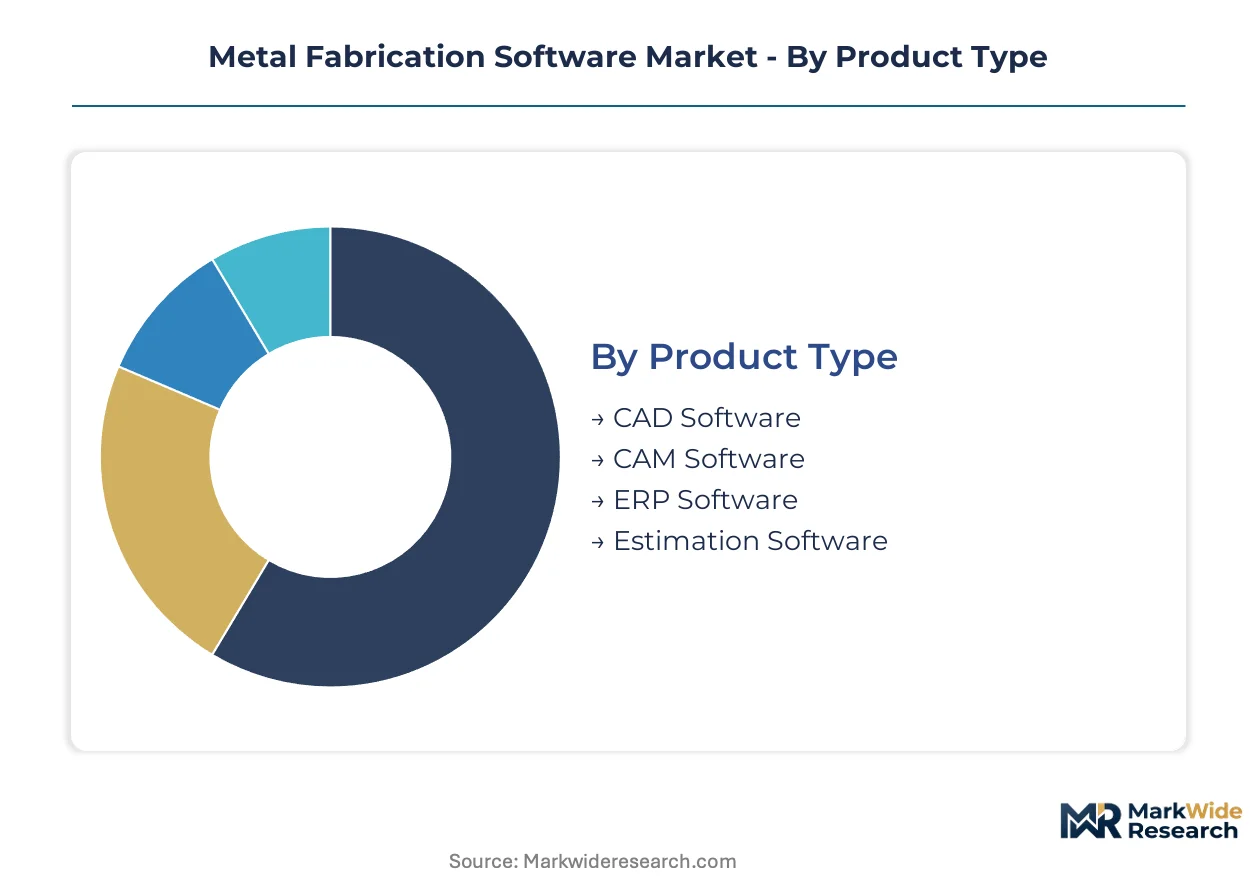
Segmentation reveals how metal fabrication software purchasing decisions cluster around upgrade cycles, with cloud migration and compliance mandates driving replacement timelines. Understanding these patterns exposes where vendors can compress sales cycles and where procurement friction persists.
Product Type:
Upgrade cycles vary dramatically across product categories, with cloud-native architectures compressing replacement timelines from decade-long ERP investments to annual CAM refreshes.
- CAD Software:Platforms govern 3D geometry creation and parametric design for sheet metal, structural steel, and aluminum assemblies. Automotive OEMs in Michigan and Ohio are modernizing legacy CAD-to-CAM handoffs to eliminate tooling changeover delays. CAD sits at the top of the volume ranking, with CAM Software climbing the fastest.
- CAM Software:Systems translate digital models into CNC-executable G-code while optimizing toolpaths, nesting patterns, and post-processor configurations for specific controller dialects. German aerospace manufacturers are accelerating adoption of cloud-based CAM platforms to enable remote programmer access and reduce on-premises server maintenance. Tight vendor concentration in advanced nesting algorithms protects margin pools here.
- ERP Software:Platforms integrate production scheduling, job costing, and inventory control across fabrication workflows.
- Estimation Software:Tools automate quoting for complex bending, welding, and cutting operations based on material, labor, and machine time calculations.
CAM Software commands premium pricing through specialized nesting engines, while ERP replacement cycles lag due to data migration complexity.
End User:
Customer type determines feature prioritization, with fabricators seeking workflow efficiency while OEMs demand supply chain emissions traceability.
- Fabricators:Job shops and metal service centers prioritize quoting speed, remnant inventory utilization, and CNC programming efficiency. Mid-size operators in Indiana and Pennsylvania are piloting AI-powered nesting to compress quoting-to-cutting timelines for multi-part aluminum assemblies.
- OEMs:Original equipment manufacturers require PLM-CAM integration, generative design capabilities, and embedded carbon accounting for scope 3 disclosure. Automotive OEMs face EU Green Deal mandates hardening emissions disclosure requirements for industrial software procurement.
- Contractors:Construction and agricultural equipment fabricators value remote quoting capabilities that eliminate physical site visits.
- Consultants:Engineering service providers need multi-tenant platforms supporting simultaneous client projects with isolated data environments.
Fabricators generate the highest transaction volume, though OEMs are expanding most quickly as compliance mandates cascade through supply chains.
Deployment:
Infrastructure choices reflect capital expenditure constraints and cybersecurity postures, with subscription models displacing perpetual licenses among irregular spenders.
- On-Premises:Legacy installations persist where data residency requirements or controller connectivity limitations prevent cloud migration.
- Cloud-Based:Architectures eliminate server maintenance burdens and enable remote access for programmers and estimators. Job shops with 15-year-old ERP investments face sunk-cost resistance despite lower total cost of ownership.
- Hybrid:Configurations maintain sensitive CAM data locally while pushing estimation and collaboration tools to cloud environments.
- SaaS:Subscription pricing captures share from perpetual licenses among fabrication facilities unwilling to absorb large upfront software investments.
Cloud-Based deployment sits at the top of the volume ranking, with SaaS gaining share fastest as vendor pricing models adapt to irregular capital cycles.
Feature:
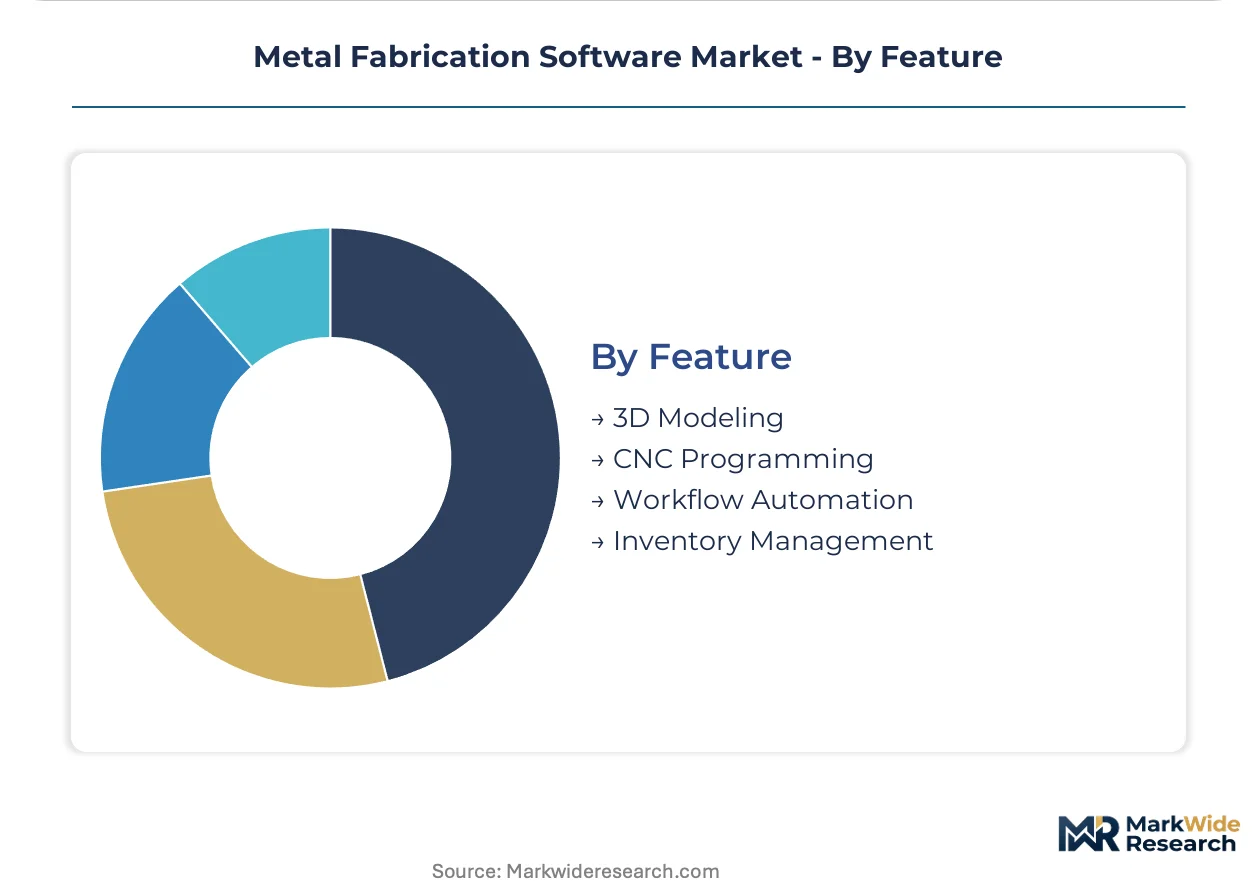
Capability prioritization follows regulatory pressure and labor scarcity, with automation modules commanding premium positioning.
- 3D Modeling:Engines support parametric design, sheet metal unfolding, and structural member libraries. Topology optimization functions help aerospace manufacturers minimize titanium waste in structural components.
- CNC Programming:Modules generate ISO 6983 G-code and proprietary controller dialects for cutting, milling, turning, and additive operations. The retirement wave of machinists trained on manual G-code editing creates bottlenecks for shops deploying advanced algorithms.
- Workflow Automation:Capabilities synchronize maintenance calendars with production schedules to satisfy OSHA lockout/tagout regulations.
- Inventory Management:Functions track remnant geometries and automate material allocation against incoming job queues.
CNC Programming anchors revenue concentration, with Workflow Automation expanding most quickly as safety-integrated modules become procurement requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The metal fabrication software industry traces its commercial roots to post-war industrial automation in the United States, where early CAD systems emerged from aerospace manufacturing clusters before diffusing to European machine tool centers and Asian electronics fabrication hubs.
United States
Automotive OEMs in Michigan and Ohio are modernizing legacy CAD-to-CAM handoffs to eliminate tooling changeover delays. EPA enforcement of NESHAP hazardous air pollutant standards requires fabrication facilities to maintain granular emissions logs, driving demand for integrated environmental reporting modules. Tier-1 suppliers around Detroit are replacing disconnected workflows with unified PLM-CAM pipelines.
Germany
Aerospace manufacturers are accelerating adoption of cloud-based CAM platforms to enable remote programmer access and reduce on-premises server maintenance. The EU Green Deal hardens emissions disclosure requirements for industrial software procurement, forcing vendors to embed carbon tracking into production planning. Industrial clusters in Bavaria and Baden-Württemberg anchor precision metalworking demand.
China
Dual carbon goals under the national climate commitment are reshaping software procurement specifications for metal fabricators serving construction and automotive OEMs. MIIT industrial digitization programs subsidize cloud migration for mid-size job shops. Manufacturing concentrations in the Yangtze River Delta and Pearl River Delta are piloting AI-powered nesting engines to compress quoting-to-cutting timelines.
Japan
Machine tool builders in the Chubu region around Nagoya are integrating digital twin capabilities into legacy controller architectures to maintain export competitiveness. METI smart manufacturing initiatives fund software interoperability standards for multi-vendor CNC environments. Automotive suppliers in Toyota City are deploying topology optimization engines to minimize material waste in structural components.
India
PLI scheme incentives for automotive and electronics manufacturing are accelerating software refresh cycles among tier-2 fabricators in Gujarat and Tamil Nadu. BIS standardization efforts for industrial software interoperability reduce integration friction for cloud-native platforms. Job shops in Pune and Chennai are piloting remote quoting capabilities to penetrate construction equipment verticals without physical site visits.
Metal Fabrication Software Market Competitive Landscape
Capital-heavy platform vendors compete with asset-light specialists across the metal fabrication software stack. The market structure concentrates in CAM software where tight vendor concentration protects margin pools, while ERP and estimation segments fragment across regional specialists. Three archetypes dominate: diversified industrial software conglomerates with PLM-CAM integration depth; pure-play CAM vendors with specialized nesting engines; and vertical ERP providers serving job shop workflows. Competitive moves center on cloud-native architecture migration and embedded carbon accounting capabilities to satisfy EU procurement mandates.
Within the diversified industrial software tier, Autodesk and Dassault Systèmes exemplify platform breadth spanning design through production. Siemens anchors the European contingent with deep integration between PLM and CNC programming environments. Among specialized vendors, SigmaNEST occupies a position representing pure-play CAM optimization. These companies sit within an ecosystem where cloud deployment timelines compress and regulatory compliance features become procurement gatekeepers.
| Leading Market Players |
|---|
| Global Shop Solutions |
| Fishbowl Manufacturing |
| Realtrac |
| Autodesk |
| Dassault Systèmes |
| Siemens |
| SigmaNEST |
| JobBOSS² |
| MIE Trak Pro |
| Others |
Supply & Pricing Matrix
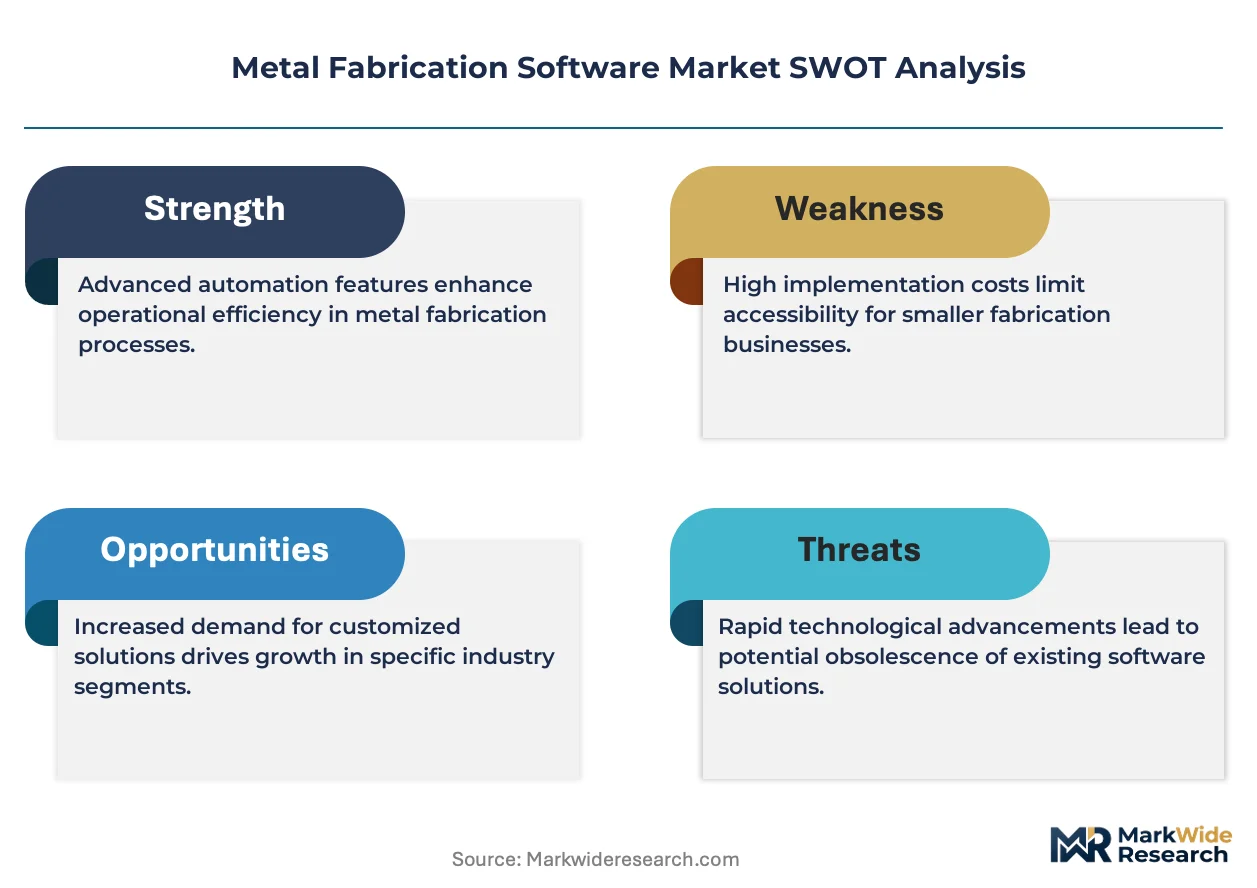
Cloud-native CAM architectures are compressing deployment timelines while simultaneously fragmenting pricing power across vendor tiers, as subscription models displace perpetual licenses and force incumbents to absorb server maintenance costs previously borne by job shops. This technology transition concentrates margin pressure on established ERP vendors with decade-old on-premises installed bases, while enabling asset-light specialists to capture share through lower entry points.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the metal fabrication software stack, with differentiation anchored in nesting algorithm sophistication and ISO 14064-aligned carbon accounting modules. Price differentiation hinges on controller dialect coverage breadth and embedded emissions tracking capabilities. Cost compression in the standard tier is intensifying because cloud-native entrants are undercutting legacy maintenance contracts. Job shops with irregular capital expenditure cycles exhibit the highest price sensitivity, while aerospace OEMs prioritize compliance features over license costs.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for PLM-CAM integration suites, while value-added resellers serve fragmented job shop segments across the United States, Germany, and China. Software development draws from specialized machine tool controller expertise concentrated in Japan and Germany, alongside cloud infrastructure provision anchored in US hyperscaler regions. Single-source vulnerability in post-processor libraries for proprietary Fanuc and Heidenhain dialects creates supply chain risk. Distribution runs through a hybrid model combining direct enterprise sales with regional implementation partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metal fabrication software represents a late-cycle quality story where procurement specifications are hardening around EU Green Deal compliance, forcing buyers toward premium platforms with embedded scope 3 carbon calculators.
For Market Incumbents: Anticipate margin erosion from cloud-native CAM specialists by accelerating subscription pricing transitions and deepening backward integration into nesting algorithm development. Defensive consolidation of post-processor libraries addresses the threat of controller dialect fragmentation, while certification investment in ISO 14064-aligned modules secures European automotive OEM procurement eligibility. For New Entrants and Emerging Players: Enter via white-space targeting of mid-size Indiana and Pennsylvania job shops piloting AI-powered nesting for aluminum scrap reduction. The most penetrable segment comprises fabrication facilities with 15-year-old ERP investments facing sunk-cost resistance to cloud migration. A remote quoting capability-first go-to-market angle bypasses incumbent workflow integration advantages. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play CAM vendors with specialized nesting engines but limited PLM integration breadth. Long-term viability over the medium-term horizon hinges on carbon accounting feature completeness as EU CSRD mandates cascade through supply chains. The signal to watch is German aerospace supplier procurement specifications elevating ISO 14064 modules to standard evaluation criteria.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified PLM-CAM pipelines eliminate tooling changeover delays for Tier-1 automotive suppliers. |
| Acquisition of Specialist Firm | Post-processor library consolidation addresses controller dialect fragmentation across CNC generations. |
| Product Launch | AI-powered nesting engines compress quoting-to-cutting timelines from hours to minutes. |
| Strategic Partnership | Cloud infrastructure alliances enable remote programmer access for German aerospace manufacturers. |
| Geographic Expansion | EU market entry requires embedded scope 3 emissions calculators to satisfy CSRD-aligned procurement. |
Research Methodology
Coverage spans the United States, Germany, China, and Japan, with primary inputs from each region combining structured interviews with CAM software product managers, CNC programming directors at Tier-1 automotive suppliers, metal service center operations heads, and cloud platform engineering leads. Secondary validation draws from SEC 10-K filings, EPA NESHAP enforcement records, EU Green Deal implementation guidance, and MIIT industrial digitization program disclosures. Bottom-up and top-down triangulation reconciles vendor shipment data with end-user procurement patterns.
Rate-of-change decomposition separates volume expansion from value capture across deployment model transitions, with CAGRs derived from segmented growth trajectory analysis. The analytical framework models product type, end user category, deployment architecture, and feature module adoption across the projection horizon. Industry-specific forecast inputs include automotive OEM workflow modernization timelines and EU carbon disclosure mandate implementation phases.
Inputs from regulatory filing databases and vendor financial disclosures were available through the study window; gaps in privately held job shop software expenditure data introduce uncertainty bands around cloud migration velocity assumptions. Forecasts reflect documented assumptions regarding NESHAP enforcement intensity and CSRD scope 3 disclosure finalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Construction Software Market
Software & Services
Embedded Graphical User Interface (GUI) Development Software Market
Software & Services
Global Desktop As a Service Market
Software & Services
MEP Software Market
Software & Services
Clinical Communication and Collaboration Software Market
Software & Services
Sales Training Software Market
Software & Services
Enterprise Resource Planning Market
Software & Services
Artwork Management Software Market
Software & Services
Vehicle Embedded Software Market
Software & Services
Sourcing Software Market
Software & Services
Global License Management Market
Software & Services
Performance Management Software Market
Software & Services
Global UIUX Software Market
Software & Services
Recruitment Software Market
Software & Services
Equipment Management Software Market
Software & Services
Global Qualitative Data Analysis Software Market