
 Global Physician Dispensed Cosmeceuticals Market | 2026-2036
Global Physician Dispensed Cosmeceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Physician Dispensed Cosmeceuticals Market Foresight
The EU Green Deal is rebalancing ingredient sourcing priorities across cosmeceutical supply chains, compelling manufacturers toward cleaner label portfolios. Galderma leverages its dermatology heritage to sustain clinic-exclusive distribution across European markets. ZO Skin Health anchors its competitive position through physician training programs that lock in prescriber loyalty. Obagi Cosmeceuticals differentiates via concentration-strength protocols that require medical supervision.
Physician dispensed cosmeceuticals comprise bioactive topical formulations containing clinically proven ingredients such as retinoids, hydroquinone, and alpha hydroxy acids, manufactured under pharmaceutical-grade standards for distribution exclusively through licensed medical practitioners. These products bridge cosmetic aesthetics and therapeutic outcomes, requiring professional diagnosis to match potency with patient skin pathology. Anti-aging serums command the largest revenue pool within product type segmentation, while acne treatment gels represent the fastest-growing category as post-adolescent patient volumes expand. Dermatology clinics dominate end-user channels, though medical spas are capturing incremental share through hybrid aesthetic-therapeutic service models.
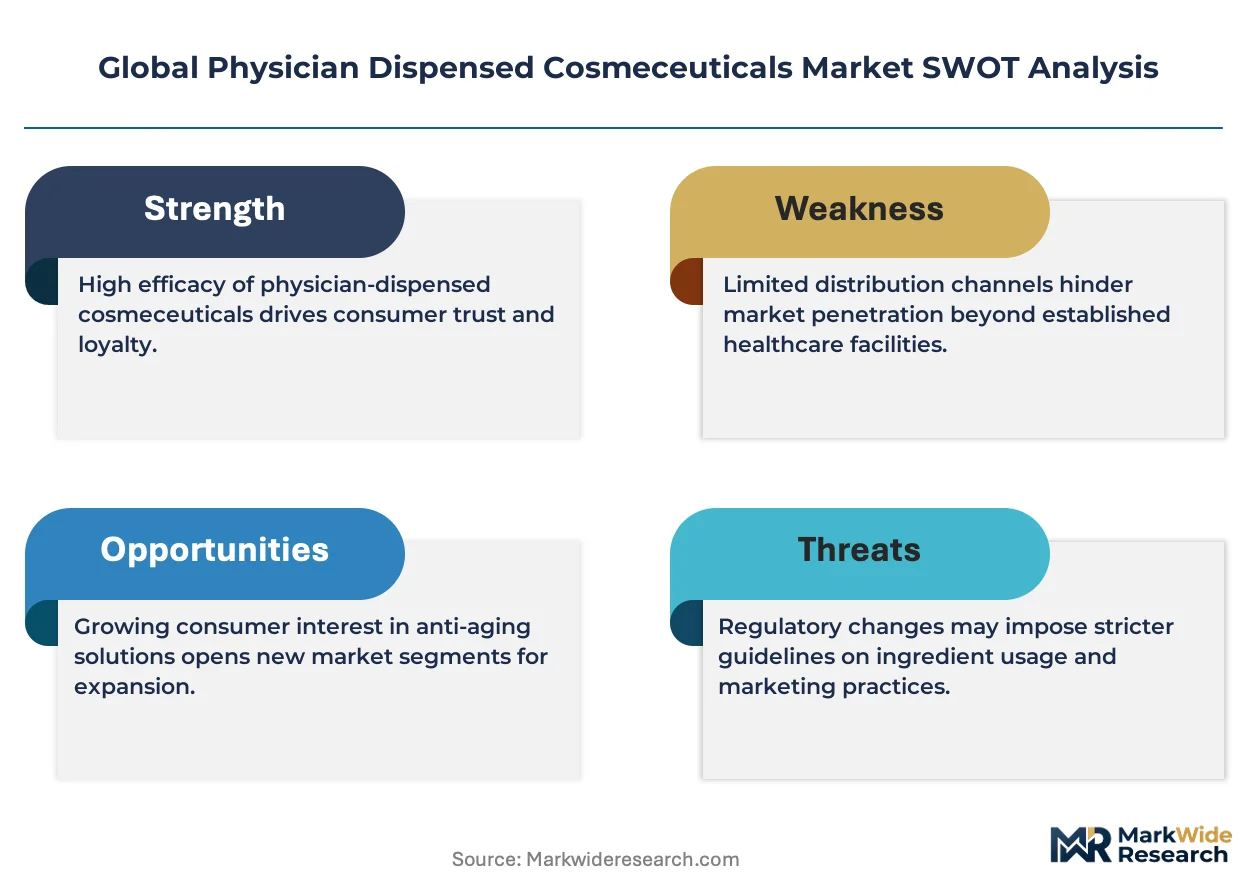
FDA oversight of cosmeceutical claims enforcement and the EU MDR framework for borderline medical devices are tightening market access standards on both sides of the Atlantic. REACH compliance in Europe and state-level pharmacy board regulations in the US collectively elevate documentation burdens for new entrants. Stakeholders must monitor evolving classification boundaries between cosmetics and drugs, as regulatory reclassification could force reformulation or channel restrictions without warning.
Market Dynamics
The EU Green Deal's tightening ingredient safety protocols are forcing manufacturers to rebuild supply chains around REACH-compliant bioactives, while dermatology clinics consolidate purchasing power through group procurement networks.
Growth Catalysts
- Medical Spa Expansion:Hybrid aesthetic-therapeutic service models in the United States are creating new dispensing nodes that bypass traditional pharmacy channels entirely.
- REACH-Driven Reformulation:European manufacturers are accelerating investment in green chemistry portfolios to preempt regulatory exclusion from core markets.
- Post-Adolescent Acne Volumes:Rising patient cohorts aged 25-40 are expanding the addressable base for prescription-strength retinoid protocols.
Market Restraints
- API Supply Concentration:Pharmaceutical-grade retinoid and hydroquinone production clusters in India and China, creating single-source vulnerability for formulators.
- State-Level Pharmacy Board Variability:Inconsistent supervision requirements across US jurisdictions complicate national distribution strategies.
- Clinical-Grade Packaging Costs:Glass ampoule and airless pump systems command 3-4x the unit cost of mass-market alternatives, compressing margin at volume.
Strategic Opportunities
- Brazilian Regulatory Opening:ANVISA's streamlined pathway for borderline cosmetic-drug products is lowering market entry barriers for clinic-exclusive brands.
- Telemedicine Integration:Remote dermatology platforms are creating direct-to-patient subscription models that preserve physician oversight while expanding geographic reach.
- Biometric Personalization:Convergence of at-home skin analysis devices with AI-formulation matching is enabling bespoke potency calibration at scale.
Industry Challenges
- Formulation Stability Expertise:Shortage of cosmetic chemists trained in pharmaceutical-grade GMP environments extends product development timelines.
- Legacy ERP Integration:Clinic management software lacks native inventory tracking for serialized prescription products, forcing manual reconciliation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Physician Dispensed Cosmeceuticals Market |
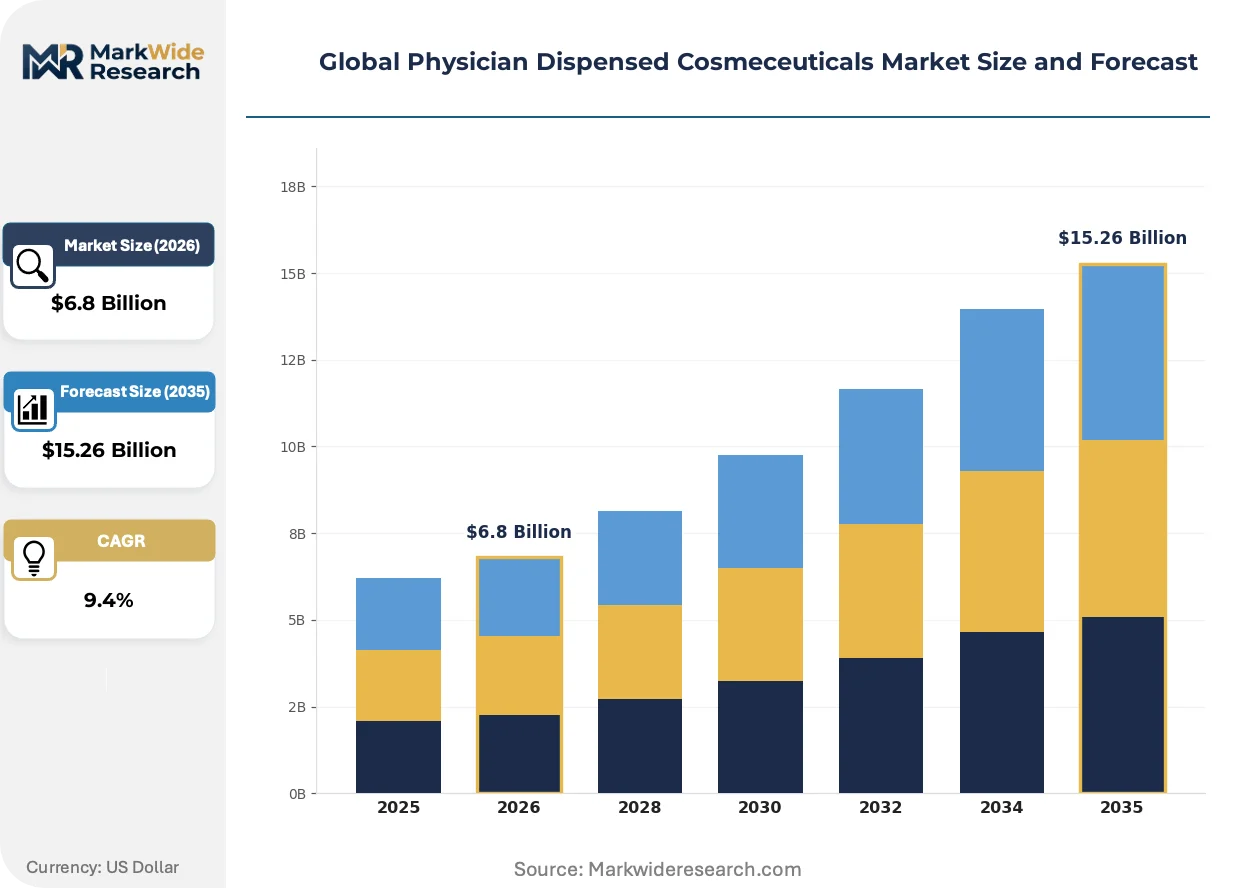
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-Aging, Skin Brightening, Acne Treatment, Hydration Formulation: Serums, Creams, Gels, Lotions End User: Dermatology Clinics, Medical Spas, Aesthetic Centers, Hospitals Distribution Channel: Online, Direct Sales, Retail Pharmacies, Clinics |
| Companies Covered | SkinCeuticals, Obagi Cosmeceuticals, Merz Pharma, Abbvie, Alastin Skincare, ZO Skin Health, Innovative Skincare, Galderma, Jan Marini Skin Research, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Physician Dispensed Cosmeceuticals Market Shifts & Advancements
Formulation science and distribution architecture are converging to reshape how clinically active topicals reach supervised end-users, with implications for manufacturing scale and channel economics.
Encapsulated delivery systems using lipid nanoparticle and microsphere architectures are modularizing how retinoids and hydroxy acids release into skin tissue. Dermatology clinics in Germany and South Korea are adopting these platforms to reduce irritation incidence and extend treatment adherence. The technology is modularizing competitive positioning around tolerability metrics rather than raw concentration claims.
The EU MDR framework for borderline medical devices is reclassifying certain microneedling and energy-device companion topicals as Class IIa products. Manufacturers serving European markets must now maintain technical documentation and clinical evidence packages previously unnecessary for cosmetic-grade formulations. Anti-aging serum categories with device-coupled protocols face the steepest compliance burden.
Patients are consolidating purchase decisions through clinic-anchored subscription programs that bundle professional consultation with automated replenishment. Medical spas in California and Florida are displacing traditional retail discovery with membership models that lock in 12-month product commitments. This pattern concentrates most visibly in sun-damage correction segments where treatment continuity determines outcome.
Global Physician Dispensed Cosmeceuticals Market Segmentation
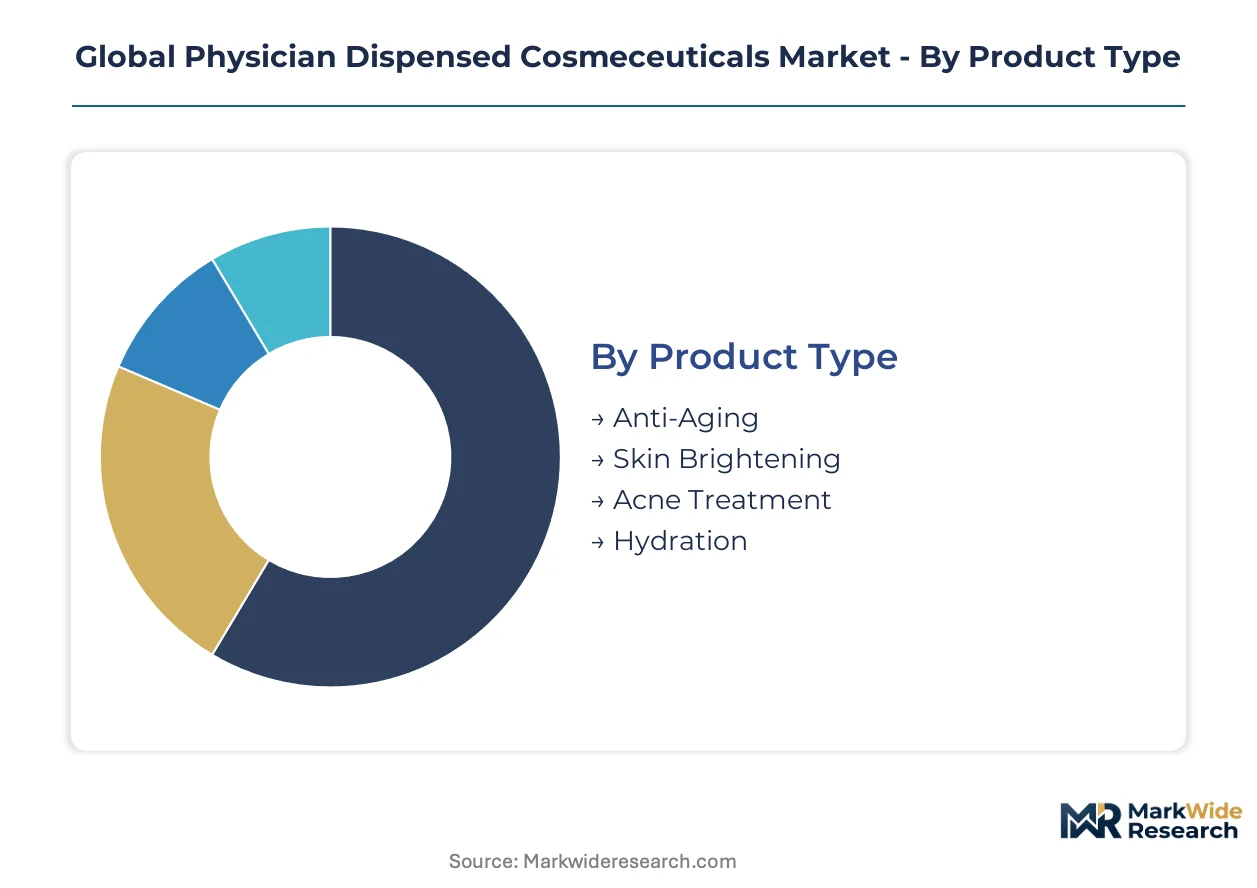
Segmentation in physician dispensed cosmeceuticals determines formulation potency, channel access, and regulatory pathway. Product type and end-user channel together dictate pricing architecture and prescriber training requirements across markets.
Product Type:
Customization intensity varies from protocol-driven therapeutic categories to maintenance-oriented aesthetic segments, reshaping how manufacturers allocate R&D and clinical education resources.
- Anti-Aging:Concentration-variable retinoid and peptide formulations targeting collagen degradation and photodamage. Demand concentrates in United States medical spas where membership models lock in 12-month replenishment cycles for sun-damage correction protocols.
- Acne Treatment:Prescription-strength benzoyl peroxide and adapalene gels manufactured under pharmaceutical-grade GMP standards. Post-adolescent patient volumes aged 25-40 in Germany and South Korea are expanding addressable base for supervised retinoid escalation protocols.
- Skin Brightening:Hydroquinone and arbutin-based formulations for hyperpigmentation management.
- Hydration:Ceramide and hyaluronic acid barrier repair products for compromised skin states.
Leading the category by volume: Anti-Aging. Expanding most quickly: Acne Treatment.
Formulation:
Cost tier stratification separates premium encapsulated delivery systems from standard emulsion bases, with packaging format determining clinic dispensing workflow efficiency.
- Serums:High-bioavailability aqueous or lipid-based vehicles with molecular weight optimization for dermal penetration. Airless pump and glass ampoule packaging commands 3-4x unit cost premium over mass-market alternatives, compressing margin at volume for European manufacturers facing REACH compliance investments.
- Creams:Emulsion-based occlusive formulations for barrier repair and retinoid tolerance building. Dermatology clinics in California and Florida prefer airless dispensers for membership-model replenishment programs.
- Gels:Alcohol-aqueous bases for acne and oil-control protocols.
- Lotions:Lower-viscosity vehicles for large-surface-area application.
Steepest expansion trajectory: Serums. Highest volume concentration: Creams.
End User:
Customer type determines prescriber credential requirements and inventory serialization protocols, with hybrid aesthetic-therapeutic venues capturing incremental share from traditional channels.
- Dermatology Clinics:Physician-supervised dispensing nodes requiring board certification for prescription-strength protocols. Group procurement networks in Germany are consolidating purchasing power and forcing manufacturers toward exclusive distribution contracts.
- Medical Spas:Hybrid venues blending aesthetic services with clinically supervised topical regimens. United States expansion in Texas and New York is creating dispensing nodes that bypass traditional pharmacy channels entirely.
- Aesthetic Centers:Procedure-focused facilities with limited prescriptive authority.
- Hospitals:Institutional settings for post-surgical and dermatology department protocols.
Fastest channel growth: Medical Spas. Largest revenue pool: Dermatology Clinics.
Distribution Channel:
Supply concentration in direct-clinic networks versus third-party retail determines margin retention and patient data ownership for subscription replenishment models.
- Direct Sales:Manufacturer-to-clinic relationships preserving prescriber loyalty through training programs and exclusive formulary access. ZO Skin Health and Galderma leverage this channel to lock in European and United States dermatology networks.
- Online:Telemedicine-integrated platforms enabling remote dermatology consultations with automated replenishment. Brazil's ANVISA streamlined pathway is lowering entry barriers for clinic-exclusive brands seeking Latin American expansion.
- Retail Pharmacies:Traditional dispensing nodes with state-level pharmacy board variability complicating national distribution strategies.
- Clinics:On-site dispensing integrated with consultation workflows.
Fastest-growing channel: Online. Dominant volume share: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors the densest concentration of medical spa dispensing nodes, where hybrid aesthetic-therapeutic venues bypass traditional pharmacy channels entirely. The metropolitan corridor from Santa Monica to Newport Beach generates disproportionate subscription program enrollment for sun-damage correction protocols. This pattern repeats across four additional national markets with distinct regulatory and channel characteristics.
United States
Medical spa expansion in Texas and Florida creates dispensing infrastructure that circumvents retail pharmacy entirely. FDA oversight of cosmeceutical claims enforcement tightens market access standards, particularly for concentration-strength protocols requiring medical supervision. The California corridor from San Diego to San Francisco leads membership-model adoption, locking patients into 12-month replenishment cycles.
Germany
Dermatology clinics in Munich and Hamburg consolidate purchasing power through group procurement networks, forcing manufacturers toward exclusive distribution contracts. REACH compliance obligations elevate documentation burdens for new entrants seeking European market access. The Baden-Württemberg region concentrates formulation science expertise around pharmaceutical-grade GMP manufacturing.
South Korea
Post-adolescent acne patient volumes aged 25-40 in Seoul expand the addressable base for supervised retinoid escalation protocols. MFDS classification standards for borderline cosmetic-drug products create regulatory clarity that accelerates clinic-exclusive brand entry. The Gangnam district anchors premium dermatology clinic density with integrated dispensing workflows.
Brazil
ANVISA's streamlined pathway for borderline cosmetic-drug products lowers market entry barriers for clinic-exclusive brands seeking Latin American expansion. São Paulo's medical aesthetic corridor concentrates demand for physician-supervised hyperpigmentation management. Rio de Janeiro's coastal clinic networks adopt subscription replenishment models adapted from US patterns.
United Kingdom
London's Harley Street medical district sustains demand for concentration-variable peptide formulations targeting collagen degradation. The Medicines and Healthcare products Regulatory Agency maintains strict oversight of prescription-strength hydroquinone distribution. Manchester and Birmingham emerge as secondary hubs for telemedicine-integrated dispensing platforms.
Global Physician Dispensed Cosmeceuticals Market Competitive Landscape
The competitive structure tilts toward dermatology heritage specialists with captive clinic networks. Consolidation pressure concentrates around manufacturers maintaining pharmaceutical-grade GMP certification and exclusive prescriber training programs. Three archetypes dominate: heritage dermatology houses with legacy formulation libraries, venture-backed clinical brands scaling through subscription economics, and diversified pharma portfolios treating skin as an adjacent therapeutic area. Dominant competitive moves include exclusive distribution contracting with clinic groups and backward integration into active pharmaceutical ingredient sourcing.
Within the heritage dermatology tier, Galderma and ZO Skin Health exemplify contrasting geographic anchoring strategies. Galderma occupies a position representing European clinic-exclusive distribution, leveraging Swiss pharmaceutical lineage to sustain prescriber loyalty across German and French markets. ZO Skin Health exemplifies the US-centric training-program model, locking in physician allegiance through protocol certification rather than formulary exclusivity. Obagi Cosmeuticals sits within the concentration-strength differentiation archetype, where medical supervision requirements themselves become competitive moats. These three patterns—geographic heritage, prescriber education investment, and regulatory-dependent positioning—collectively define the competitive space.
| Leading Market Players |
|---|
| SkinCeuticals |
| Obagi Cosmeceuticals |
| Merz Pharma |
| Abbvie |
| Alastin Skincare |
| ZO Skin Health |
| Innovative Skincare |
| Galderma |
| Jan Marini Skin Research |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up dermatology brands anchor supply discipline through captive clinic networks, translating prescriber loyalty into pricing power that resists mass-market commoditization. Their ownership structures prioritize recurring subscription revenue over transactional volume, reinforcing investment in pharmaceutical-grade manufacturing capacity that smaller formulators cannot replicate.
Pricing Analysis
Outcome-based pricing tied to visible skin correction anchors the premium tier, with dermatology clinics commanding three to four times mass-market unit economics for airless-packaged serums. Price differentiation separates GMP-certified formulations from cosmetic-grade alternatives, while REACH compliance investments in Europe compress margins for non-integrated manufacturers. Pricing pressure stems from medical spa membership models demanding volume discounts for 12-month replenishment commitments. Large clinic procurement networks exhibit lowest price sensitivity; independent aesthetic centers face highest cost compression.
Supply Chain Analysis
Reverse-logistics flows remain minimal given the consumable nature of topical formulations, though clinic returns of expired inventory create localized disposal costs concentrated in California and Florida. Active pharmaceutical ingredient production clusters in India and China, with retinoid and hydroquinone supply resting on single-source fermentation and chemical synthesis facilities. Supply chain risk centers on tariff exposure for imported bioactives entering US and European compounding facilities. Distribution runs through direct manufacturer-to-clinic relationships that preserve prescriber training control and patient data ownership.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cosmetic chemist scarcity in pharmaceutical-grade GMP environments constrains formulation throughput, propping pricing for manufacturers with captive technical talent. Capacity bottlenecks at contract manufacturing organizations extend lead times, reinforcing subscription-model economics that lock patients into predictable replenishment.
For Market Incumbents: Lock in prescriber loyalty through exclusive protocol certification programs that emerging brands cannot resource. Secure backward integration into retinoid API sourcing to neutralize Indian and Chinese supply concentration risk. Expand group procurement contracting with German dermatology networks before competitors replicate the model.
For New Entrants and Emerging Players: AI-formulation matching platforms offer a technology-first wedge into telemedicine-integrated dispensing, bypassing capital-intensive clinic network buildout. Target Brazil's ANVISA-streamlined pathway for fastest regulatory clearance among major markets. Pursue white-label manufacturing partnerships with South Korean GMP facilities to accelerate market entry.
For Investors and Strategic Acquirers: Distressed-cycle entries favor European manufacturers facing REACH compliance cost overruns in Germany and France. Long-term viability hinges on subscription-model retention rates rather than one-time product margins. Monitor FDA enforcement actions on concentration-strength claims as signal for regulatory reclassification risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Distribution Contracting | Galderma's clinic-exclusive European networks demonstrate prescriber lock-in through formulary control. |
| Backward Integration into API Sourcing | Captive retinoid supply chains neutralize single-source vulnerability from Indian and Chinese manufacturers. |
| Telemedicine Platform Integration | Remote dermatology subscriptions expand geographic reach while preserving physician oversight requirements. |
| REACH Compliance Investment | Green chemistry portfolios preempt regulatory exclusion from core European markets under EU Green Deal timelines. |
| Physician Training Program Expansion | ZO Skin Health's protocol certification builds prescriber allegiance that transcends product switching. |
Research Methodology
Multi-period observation of clinic procurement patterns and regulatory filing trajectories anchored the trend analysis, supplemented by interviews with dermatology practice owners, cosmetic chemists at GMP manufacturing facilities, medical spa operators, and pharmaceutical regulatory consultants. Secondary validation drew from FDA cosmeceutical enforcement letters, ECHA REACH registration databases, ANVISA borderline product rulings, and MFDS classification guidelines. Bottom-up clinic dispensing volume estimates triangulated against top-down manufacturer revenue disclosures.
Segment-weighting across product type, formulation, end-user channel, and distribution model shaped the analytical framework throughout the projection horizon. CAGRs derived from patient volume elasticity models calibrated to post-adolescent acne demographics and medical spa expansion rates. Forecast inputs incorporated REACH-driven reformulation cost curves and telemedicine platform penetration assumptions.
Several conditions sit outside the modeled scope, including sudden FDA reclassification of retinoid concentrations as prescription-only and catastrophic API facility disruptions in India or China. Forecasts reflect documented assumptions about regulatory stability and clinician prescribing continuity. Practitioners should monitor EU MDR borderline device rulings and state-level pharmacy board harmonization efforts for early signals of channel restriction.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Hand Eczema (HE) Treatment Market
Skincare
Body Scrub Market
Skincare
Peel Off Face Mask Market
Skincare
Skin Boosters Market
Skincare
Skin Resurfacing Market
Skincare
Skin Barrier Market
Skincare
Revitalizing Skin Wands Market
Skincare
ASEAN Sensitive Skin Care Market
Skincare
Sun-Care Wipes Market
Skincare
Exfoliators and Scrubs Market
Skincare
Herbal Skincare Products Market
Skincare
Global Hand Lotion and Hand Cream Market
Skincare
Personalized Skin Care Products Market
Skincare
Organic Skincare Products Market
Skincare
Algae Skincare Products Market
Skincare
US Acne Treatment Market