
 Solidified Yogurt Market | 2026-2036
Solidified Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
Solidified Yogurt Market Insights
Plant-based stabilizers and alternative proteins is consolidating share from traditional gelatin formulations in solidified yogurt production. Yili leverages its integrated dairy supply chain across Inner Mongolia to control raw milk quality from farm to cup. Mengniu competes through R&D intensity in probiotic strain development, while Junlebao anchors its position with specialized A2 milk sourcing for premium set yogurt lines.
Solidified yogurt denotes a cultured dairy product where milk proteins coagulate through controlled fermentation with Lactobacillus bulgaricus and Streptococcus thermophilus, typically achieving a firm gel structure with total solids above 15% and pH ranging 4.0 to 4.6. The product serves commercial foodservice and retail channels requiring spoonable texture and extended shelf stability under refrigerated distribution. Greek yogurt commands the deepest margin pools due to straining processes that concentrate protein and justify premium positioning. Set yogurt retains volume leadership in Asian markets where firm texture aligns with traditional dairy preferences. Pouch packaging represents the fastest-growing format, driven by convenience-store channel expansion and single-serve consumption occasions.
China's SAMR enforces GB 19302 dairy standards that specify microbial limits and additive permissions for fermented milk products, directly shaping formulation choices for domestic manufacturers. The EU's EFSA evaluates novel probiotic health claims under Regulation 1924/2006, creating compliance barriers for functional positioning in European retail. India's FSSAI mandates licensing under the Food Safety and Standards Act for all dairy processing facilities, affecting market entry timelines for new entrants. Stakeholders must monitor evolving clean-label regulations and probiotic claim substantiation requirements as determinants of competitive access across priority markets.
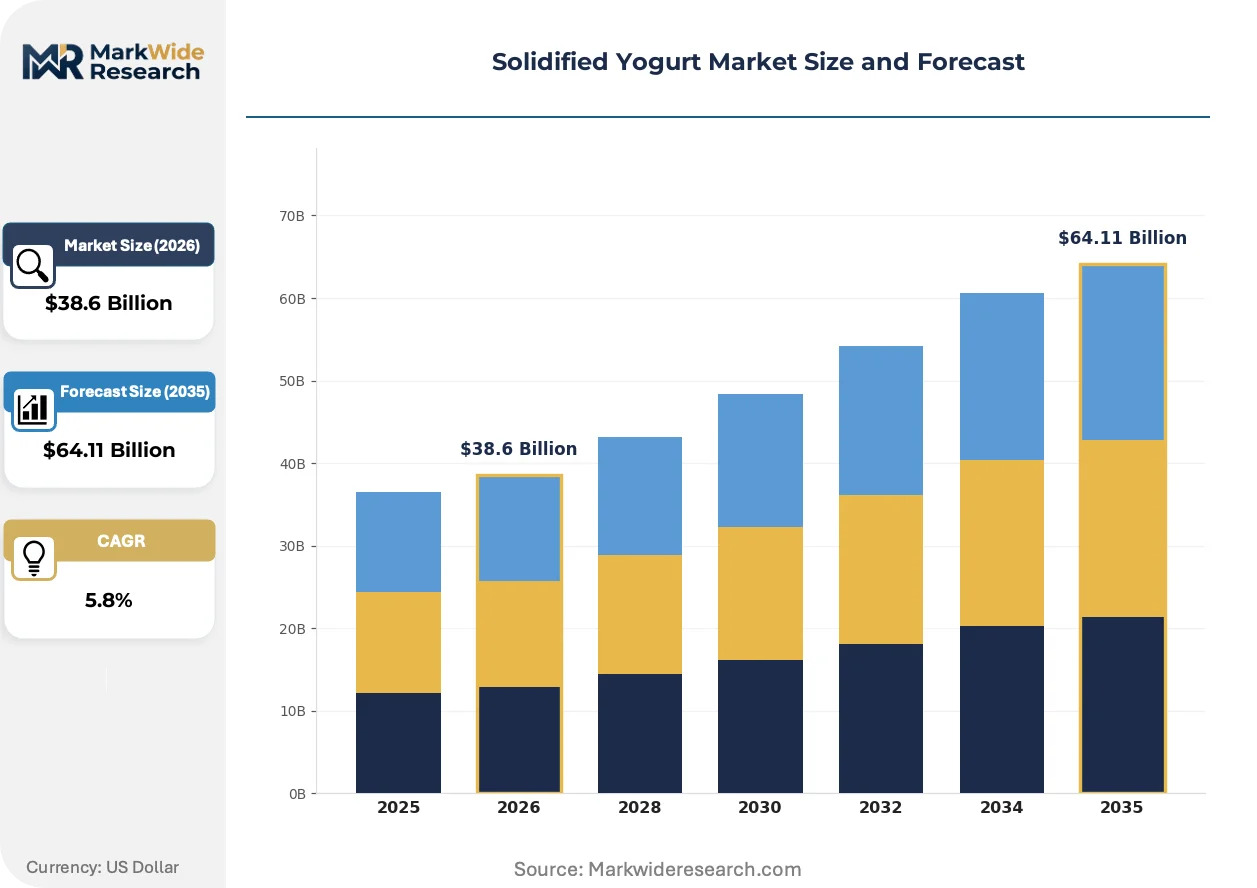
Market Dynamics
Clean-label regulatory mandates from EFSA and China's SAMR are forcing simultaneous reformulation of stabilizer systems and probiotic strain selections across solidified yogurt manufacturing.
Growth Catalysts
- Functional positioning:Health-conscious consumers in China's tier-one cities prioritize protein density and live culture counts, pulling premium set yogurt volumes upward.
- GB 19302 alignment:China's SAMR standards clarify additive permissions, reducing compliance uncertainty for domestic fermented milk producers.
- Pouch packaging automation:Convenience-store channel expansion accelerates single-serve format adoption with extended ambient stability requirements.
Market Restraints
- Milk powder price volatility:Skim milk solids represent 35-45% of input costs; New Zealand and EU dairy auction fluctuations compress margin predictability.
- Probiotic claim substantiation:EFSA Regulation 1924/2006 creates multi-year evidentiary barriers for European functional positioning.
- Cold chain infrastructure gaps:India's refrigerated distribution network remains underdeveloped outside metropolitan corridors, limiting shelf-life realization.
Strategic Opportunities
- Plant-based stabilizer convergence:Pectin and tapioca starch systems are displacing gelatin in halal and vegetarian-certified product lines.
- A2 milk sourcing:Specialized beta-casein protein streams command premium positioning in digestive-sensitive consumer segments.
- Direct-to-cold-chain logistics:Urban micro-fulfillment centers enable same-day delivery of high-live-count products in Shanghai and Shenzhen.
Industry Challenges
- Strain banking expertise:Qualified industrial microbiologists capable of maintaining Lactobacillus bulgaricus and Streptococcus thermophilus master cultures remain scarce across Asian manufacturing hubs.
- Clean-label timeline compression:FSSAI licensing procedures in India extend facility approval cycles, delaying reformulated product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solidified Yogurt Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $64.11 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Set Yogurt, Drinking Yogurt, Greek Yogurt, Frozen Yogurt Flavor: Vanilla, Strawberry, Blueberry, Plain Packaging Type: Pots, Tubs, Pouches, Cups Sales Channel: Supermarkets, Online Retail, Convenience Stores, Health Food Stores |
| Companies Covered | Yili, Mengniu, SANYUAN, Bright Dairy & Food Co., Ltd., SIMPLE LOVE, Junlebao, Huishan, Huaming Ranch, Langege, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solidified Yogurt Market Trends and Innovations
Bioprocessing advances and packaging material science are converging to extend probiotic viability windows while reducing synthetic additive dependence in solidified yogurt production.
High-pressure processing technology is expanding into ambient-stable set yogurt manufacturing. Mid-tier Asian processors adopt HPP systems to eliminate post-fermentation heat treatment, preserving live culture counts through 45-day shelf lives. This capability is expanding into private-label contract manufacturing, compressing the technical gap between regional brands and multinational refrigerated portfolios.
EFSA's evolving guidance on novel probiotic health claims under Regulation 1924/2006 tightens evidentiary standards for immune and digestive positioning. European manufacturers redirect R&D expenditure toward strain-specific clinical trials rather than generic fermentation efficiency improvements. Greek yogurt and strained set variants face the steepest compliance costs given their premium price architecture and explicit functional marketing.
Single-serve pouch consumption is rotating demand toward impulse-purchase occasions in convenience retail. Chinese urban consumers aged 22-35 replace traditional family-size tub purchases with grab-and-go formats during commutes. This behavioral shift pressures manufacturers to reformulate for mechanical filling compatibility and puncture resistance without gelatin-based film structures.
Solidified Yogurt Market Segmentation
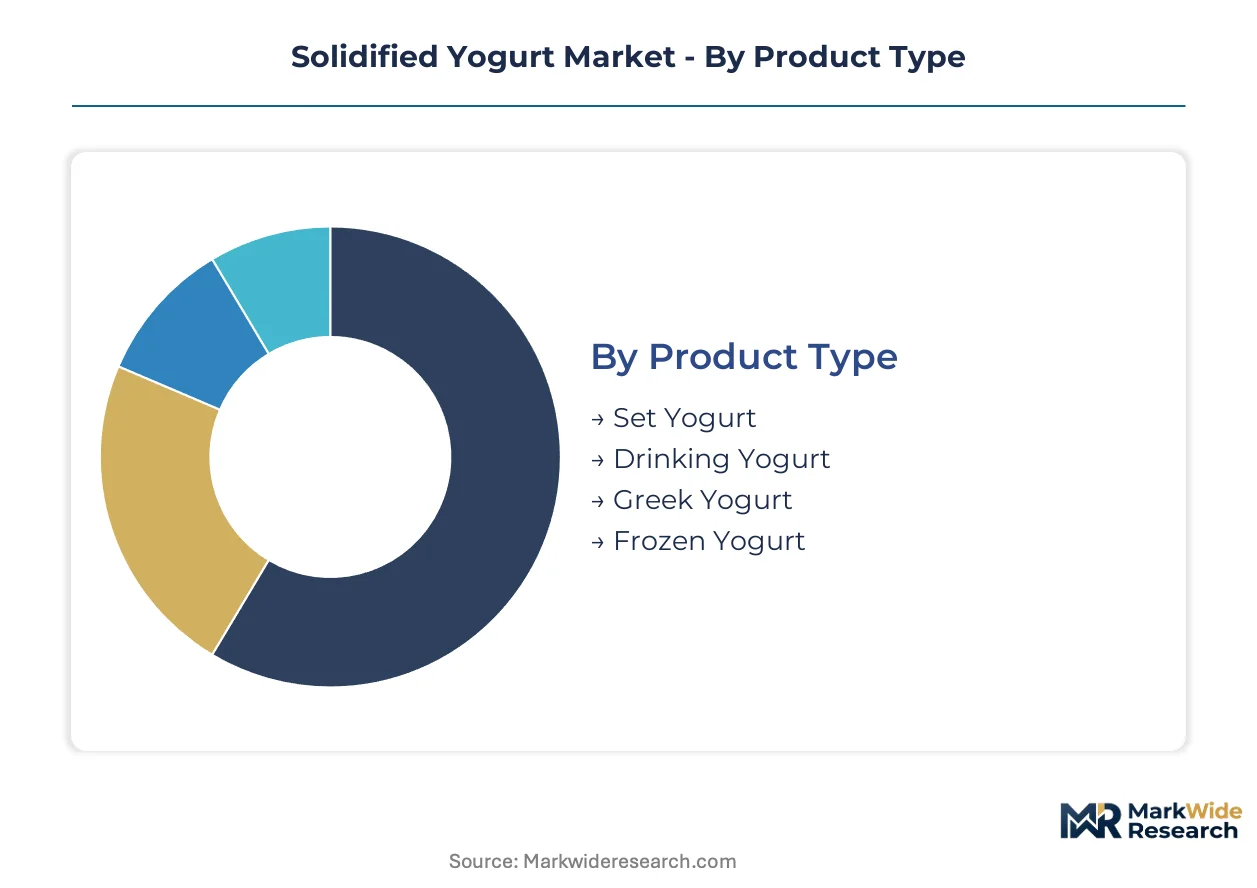
Segmentation in solidified yogurt production reveals how texture specifications, thermal stability requirements, and distribution channel constraints fragment manufacturing investment across incompatible equipment lines. Product viscosity and pH targets determine fermenter design, while packaging format selection locks processors into specific filling speeds and shelf-life engineering.
Product Type:
Supply concentration clusters around fermentation technology tiers, with high-capacity stirred-tank systems serving distinct viscosity endpoints versus specialized straining equipment for protein concentration.
- Set Yogurt:Milk proteins coagulate in final-package fermentation, achieving firm gel structures above 15% total solids with pH 4.0-4.6. China's tier-one cities concentrate demand where traditional spoonable texture aligns with breakfast consumption rituals. SAMR's GB 19302 standards directly specify microbial limits for this unstrained format.
- Greek Yogurt:Centrifugal or membrane straining removes whey to concentrate protein above 10%, creating viscosity that commands premium positioning. European retailers under EFSA Regulation 1924/2006 impose the steepest claim substantiation costs for its functional marketing. Straining infrastructure requires capital outlays that exclude smaller processors.
- Drinking Yogurt:Lower viscosity achieved through reduced fermentation time or post-fermentation homogenization enables bottle-based distribution.
- Frozen Yogurt:Overrun control and ice crystal management distinguish soft-serve equipment from retail hard-pack lines.
Set yogurt absorbs the bulk of installed capacity; Greek yogurt is expanding most quickly.
Flavor:
Cost tier stratification separates commodity fruit preparations from clean-label natural extracts and unflavored base formulations.
- Plain:Unflavored base serves both direct consumption and foodservice ingredient applications where downstream flavor control matters. India's metropolitan corridors show concentrated demand for plain set yogurt in traditional meal accompaniment roles. FSSAI licensing requirements for flavor additive handling make plain formulations attractive to new market entrants.
- Strawberry:Fruit preparation costs dominate bill-of-materials for this volume-leading flavor, with supply security tied to seasonal procurement calendars.
- Blueberry:Premium positioning relies on named-variety sourcing and reduced sugar declarations.
- Vanilla:Extract versus natural flavoring compliance creates formulation complexity under EFSA additive permissions.
Plain absorbs the bulk of installed capacity; strawberry is expanding most quickly.
Packaging Type:
Volume throughput and cold-chain dependency diverge sharply between ambient-stable pouch systems and refrigerated pot formats.
- Pouches:Flexible film structures with spout or straw attachments enable convenience-store channel expansion and commuter consumption. China's 22-35 urban demographic concentrates demand where grab-and-go occasions replace family-size tub purchases. Puncture resistance requirements without gelatin-based films force material science investment.
- Pots:Rigid polystyrene or polypropylene containers dominate retail dairy cases with established recycling infrastructure.
- Tubs:Multi-serve formats retain volume in household replenishment channels with lower per-gram packaging cost.
- Cups:Single-serve portion control aligns with foodservice and institutional distribution requirements.
Pots absorb the bulk of installed capacity; pouches are expanding most quickly.
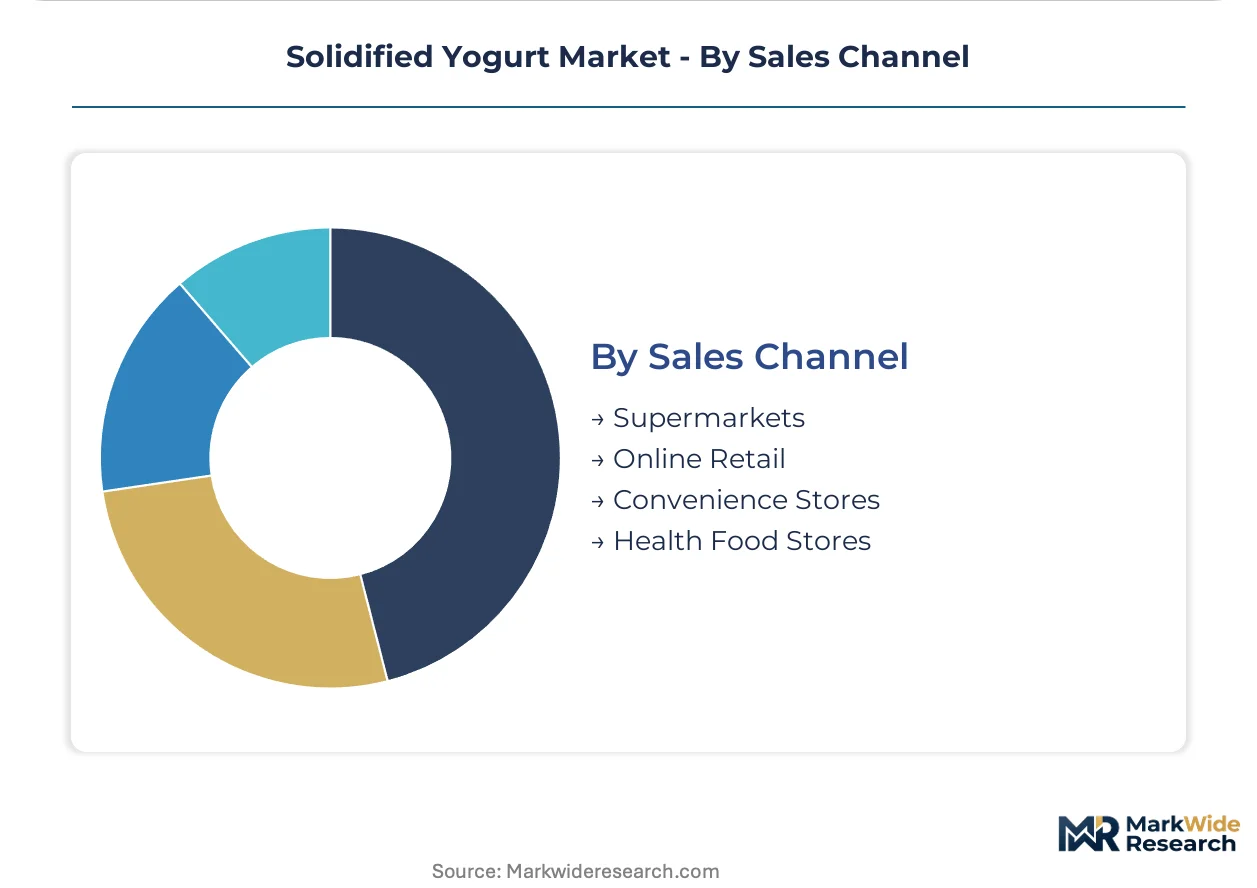
Sales Channel:
Customer type fragmentation separates high-frequency convenience purchasing from planned stock-up trips and subscription-based replenishment.
- Convenience Stores:Refrigerated display space constraints favor single-serve pouches with rapid inventory turns. Shanghai and Shenzhen micro-fulfillment networks enable same-day delivery of high-live-count products to this channel. Shelf-life compression requires reformulation for extended ambient stability.
- Supermarkets:Multi-temperature zone layouts accommodate full product range from frozen to ambient-stable lines.
- Online Retail:Direct-to-consumer logistics demand insulated packaging investment for cold-chain maintenance.
- Health Food Stores:Certification requirements for organic or probiotic claims create margin premiums offset by smaller throughput.
Supermarkets absorb the bulk of installed capacity; convenience stores are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate solidified yogurt manufacturing through tax incentives and cold-chain infrastructure subsidies. Inner Mongolia's dairy corridor anchors raw milk supply integration. India's Gujarat and Maharashtra clusters drive South Asian fermentation capacity expansion.
China
Tier-one city demand for functional set yogurt pulls premium volumes through Shanghai and Shenzhen convenience networks. SAMR's GB 19302 standards enforce microbial limits and additive permissions that reshape domestic formulation choices. Inner Mongolia's Hohhot-Ordos corridor houses integrated dairy operations controlling farm-to-cup quality pipelines.
India
Metropolitan corridors in Mumbai and Delhi-NCR concentrate demand for traditional plain set yogurt in meal accompaniment roles. FSSAI licensing under the Food Safety and Standards Act extends facility approval timelines for new market entrants. Gujarat's Anand district clusters cooperative dairy processing infrastructure with established cold-chain distribution to western urban markets.
United States
Greek yogurt protein concentration commands premium positioning in East Coast and California retail channels. FDA dairy standards govern pathogen control and labeling requirements for interstate commerce. Upstate New York's Finger Lakes region anchors straining infrastructure investment serving Northeast metropolitan demand.
Germany
Clean-label probiotic positioning faces EFSA Regulation 1924/2006 evidentiary barriers for immune and digestive health claims. Bavaria's Munich-Stuttgart corridor concentrates organic dairy processing with established retailer certification relationships. Strained yogurt variants absorb compliance costs through premium price architecture.
Australia
High-live-count drinking yogurt formats expand through Sydney and Melbourne convenience retail. FSANZ standards govern probiotic count declarations and health claim substantiation requirements. Victoria's Goulburn Valley clusters dairy processing with direct-to-cold-chain logistics serving southeastern urban markets.
Solidified Yogurt Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated dairy conglomerates controlling raw material pipelines and regional processors competing on format innovation. Market structure tilts toward consolidation among entities with captive milk supply, while private-label operators expand through HPP-equipped contract manufacturing. Three archetypes dominate: vertically integrated dairy majors with strain banking capabilities, mid-tier regional brands with localized distribution, and technology-focused specialists in ambient-stable processing. Competitive moves concentrate on A2 milk sourcing partnerships and pouch packaging automation investments.
Within the integrated dairy tier, Yili and Mengniu occupy positions defined by upstream supply control and R&D infrastructure scale. Junlebao exemplifies the specialized sourcing archetype through beta-casein protein stream differentiation. These three entities represent distinct competitive vectors: Yili anchors farm-to-cup integration across Inner Mongolia, Mengniu directs probiotic strain development expenditure, and Junlebao secures premium positioning through digestive-sensitive consumer targeting.
| Leading Market Players |
|---|
| Yili |
| Mengniu |
| SANYUAN |
| Bright Dairy & Food Co., Ltd. |
| SIMPLE LOVE |
| Junlebao |
| Huishan |
| Huaming Ranch |
| Langege |
| Others |
Pricing and Supply Chain Analysis
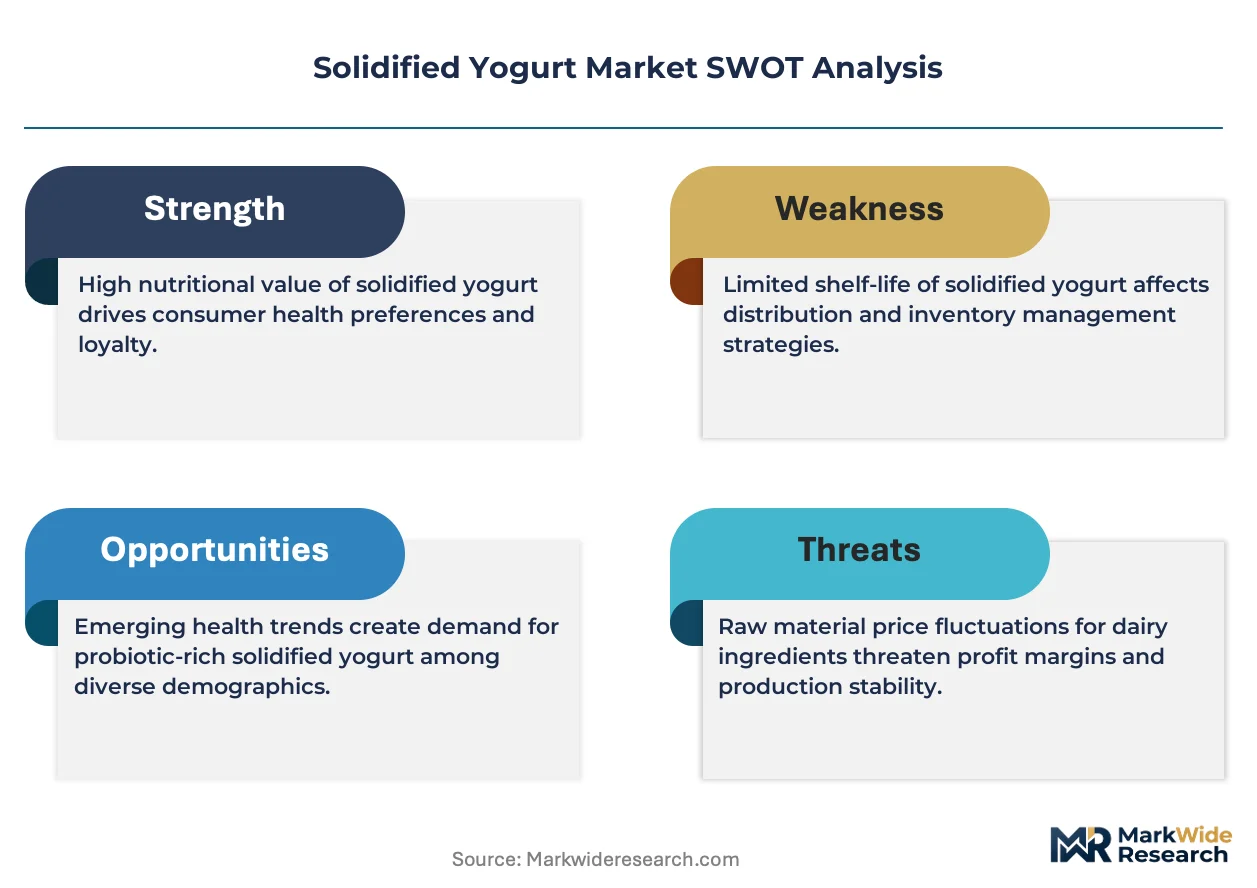
High-pressure processing technology adoption is simultaneously compressing per-unit production costs for ambient-stable lines while concentrating manufacturing capacity among processors with capital access for HPP system deployment. This equipment transition reshapes competitive economics by extending shelf-life windows without gelatin-based stabilizers, enabling premium positioning in convenience-store channels where single-serve pouches command price premiums over traditional pot formats.
Pricing Analysis
Volume leadership in plain set yogurt absorbs the bulk of commodity-grade capacity at thin margins, while Greek yogurt and A2 milk-sourced variants capture premium pools through protein concentration and digestive-sensitive positioning. Three-tier pricing structure across premium, standard, and economy levels separates certified organic lines with EFSA-compliant probiotic claims from conventional set yogurt and private-label economy offerings. Price differentiation hinges on clean-label certification status and captive A2 milk supply control. Cost compression in standard-tier products is intensifying because New Zealand skim milk powder auction volatility feeds directly into 35-45% of input costs. Economy-tier buyers exhibit highest price sensitivity, while health-food channel consumers accept 40-60% premiums for strain-specific clinical substantiation.
Supply Chain Analysis
Refrigerated freight costs from Inner Mongolia's Hohhot-Ordos corridor to Shanghai and Shenzhen distribution centers represent a structural margin drag for live-culture products requiring cold-chain maintenance. Supply concentrates in China's Yangtze River Delta special economic zones, India's Gujarat and Maharashtra clusters, and Germany's Bavaria organic processing corridor. Raw material flows draw from New Zealand skim milk powder auctions, Inner Mongolia raw milk collection networks, and specialized pectin stabilizer suppliers replacing gelatin systems. Single-source vulnerability in qualified industrial microbiologist talent pools across Asian manufacturing hubs threatens strain banking continuity. Distribution runs through convenience-store micro-fulfillment networks in Chinese tier-one cities, supermarket multi-temperature zones in Europe, and cooperative dairy federations in western India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over A2 milk sourcing and probiotic strain banking capabilities determines margin capture. Players are pursuing backward integration into captive raw milk supply to secure quality pipelines and reduce auction-price exposure.
For Market Incumbents: Deploy strain banking infrastructure investments to lock in Lactobacillus bulgaricus and Streptococcus thermophilus master culture capabilities before qualified industrial microbiologist scarcity intensifies. Consolidate position through pouch packaging automation partnerships with convenience-store channel operators in Shanghai and Shenzhen. Counter emerging HPP-equipped contract manufacturers by accelerating clean-label reformulation timelines ahead of SAMR GB 19302 enforcement expansion.
For New Entrants and Emerging Players: FSSAI licensing timeline compression in India opens a window for facility approvals ahead of anticipated regulatory harmonization with stricter SAMR standards. White-space exists in direct-to-cold-chain logistics for high-live-count products serving health-food store channels with organic certification requirements. Penetrate through specialized A2 milk sourcing partnerships with Gujarat cooperative dairies, leveraging existing cold-chain distribution to Mumbai and Delhi-NCR metropolitan corridors.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier regional brands possessing HPP-equipped contract manufacturing capacity given convenience-store channel expansion acceleration. Long-term viability favors entities with demonstrated strain-specific clinical trial expenditure and EFSA Regulation 1924/2006 claim substantiation capabilities. Monitor probiotic health claim approval velocity at EFSA as the critical inflection signal for European premium positioning sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| A2 Milk Supply Partnership | Captive beta-casein protein streams command 25-35% premiums in digestive-sensitive segments. |
| HPP System Deployment | Eliminates post-fermentation heat treatment, preserving live counts through 45-day ambient shelf lives. |
| Pouch Packaging Automation | Enables mechanical filling compatibility for convenience-store single-serve consumption occasions. |
| Strain Banking Infrastructure | Secures qualified microbiologist talent pools for Lactobacillus bulgaricus master culture maintenance. |
| Clean-Label Reformulation | Pectin and tapioca starch systems displace gelatin to meet halal and vegetarian certification requirements. |
Research Methodology
Document review covered SAMR GB 19302 regulatory filings, EFSA novel food opinion databases, FSSAI licensing registers, and New Zealand dairy auction price series, complemented by interviews with fermentation technology directors at integrated dairy majors, probiotic strain development leads, convenience-store category buyers in Shanghai and Shenzhen, and cold-chain logistics operators. Secondary validation drew from customs records tracking skim milk powder trade flows, Nielsen retail audit data for pouch format adoption rates, and hospital procurement databases for functional dairy ingredient applications. Bottom-up capacity modeling triangulated against top-down consumption estimates across the analysis window.
Cross-referencing historical price-cost relationships with panel input from plant managers and procurement directors anchored the analytical framework across product type, flavor tier, packaging format, and sales channel dimensions. CAGRs were derived from segmented volume trajectory modeling incorporating HPP adoption curves, A2 milk supply expansion timelines, and convenience-store channel penetration rates. Forecast inputs included strain banking capacity buildout schedules, EFSA claim substantiation pipeline visibility, and refrigerated distribution network development in Indian metropolitan corridors.
The model assumes a particular technology adoption path for high-pressure processing deployment; alternative pathways involving thermal treatment optimization or novel stabilizer systems would alter the outlook for ambient-stable product viability. Forecasts reflect assumptions regarding regulatory harmonization timelines, raw material auction price volatility persistence, and cold-chain infrastructure investment trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Dairy Based Dressings Market
Dairy Products
Goat Milk Market
Dairy Products
Lactose Market
Dairy Products
Global Butter Market
Dairy Products
Condensed Milk Market
Dairy Products
Russia Whey Protein Market
Dairy Products
Drinkable Yogurt Market
Dairy Products
United Kingdom Dairy Market
Dairy Products
Africa Yogurt Market
Dairy Products
Reduced Fat Dairy Market
Dairy Products
Enzyme Modified Cheese Market
Dairy Products
Organic Milk Market
Dairy Products
Fat-Filled Milk Powder Market
Dairy Products
Sheep Milk Cheese Market
Dairy Products
Organic Milk Protein Market
Dairy Products
Milk Protein Hydrolysate Market