
 Apparel and Leather Products Market | 2026-2036
Apparel and Leather Products Market Size, Share, and Industry Trends Forecast 2026-2036
Apparel and Leather Products Market Insights
Capital-intensity divergence between artisanal ateliers and industrial-scale manufacturers is rotating competitive dynamics across the value chain. LVMH Moët Hennessy Louis Vuitton SE leverages vertical integration from tanneries to retail boutiques, sustaining margin capture that smaller rivals cannot replicate. Nike Inc. anchors its position through advanced synthetic material R&D, while Adidas AG competes via direct-to-consumer channel control and localized production networks.
Apparel and leather products encompass garments, footwear, and accessories crafted from animal hides, woven textiles, or engineered polymers through processes including chrome tanning, pattern cutting, and automated stitching, serving functional, aesthetic, and status-signaling purposes for consumers. Leather material commands premium pricing due to durability perception and supply constraints from hide processing cycles, whereas synthetic fabric segments expand fastest through performance innovations in moisture-wicking and recyclability. Clothing dominates volume across all customer type segments, though accessories concentrate margin pools where brand equity translates to pricing power.
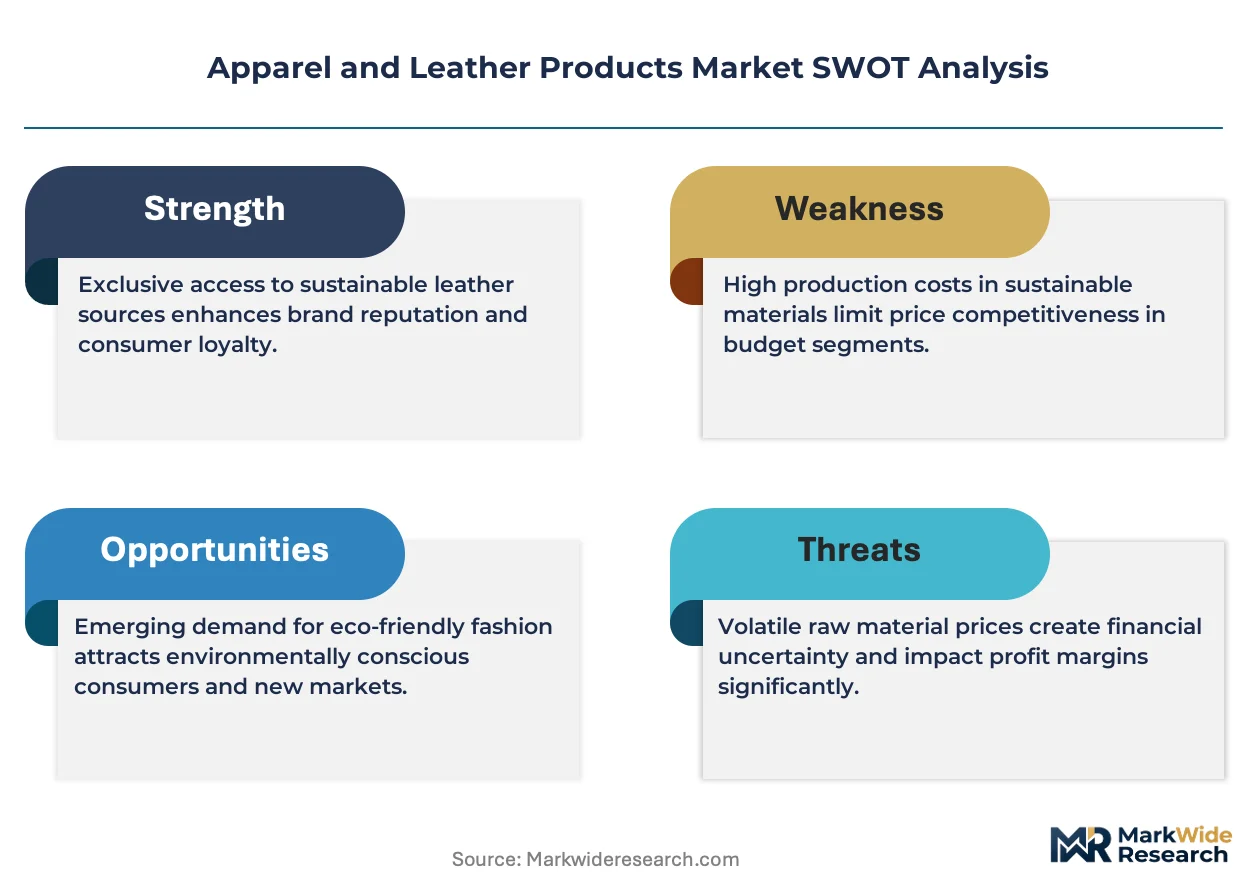
EU REACH restrictions on chromium VI in leather tanning reshape product standards, compelling reformulation investments across European supply chains. The EU Green Deal's textile sustainability requirements and California's Proposition 65 chemical disclosure rules add compliance layers affecting market access for imported goods. Stakeholders must monitor regulatory fragmentation between jurisdictions while deciding whether to standardize formulations globally or maintain region-specific product lines.
Market Dynamics
EU REACH chromium VI restrictions and the EU Green Deal's textile sustainability mandates are forcing wholesale reformulation of European leather tanning processes, while synthetic material R&D races to capture displaced premium demand.
Growth Catalysts
- EU Green Deal Textile Requirements:Mandatory circularity standards for garment recycling and fiber traceability are accelerating investment in closed-loop production systems across Italian and Spanish manufacturing clusters.
- China Tier-One City Demand:Shanghai, Beijing, and Shenzhen consumers are driving double-digit volume expansion in domestic luxury apparel brands competing directly with European heritage labels for wallet share.
- Advanced Synthetic Polymers:Moisture-wicking and recyclability innovations in engineered fabrics are capturing performance-oriented segments previously dominated by natural leather and cotton textiles.
Market Restraints
- Hide Supply Volatility:Cattle hide availability fluctuates with meat industry cycles, creating input cost instability for chrome-tanning operations concentrated in Northern Italy and Southern France.
- Regulatory Fragmentation:Divergent chemical disclosure rules between California's Proposition 65 and EU REACH compliance timelines force dual-track product development, elevating overhead for exporters.
- Biomaterial Substitution:Mushroom-derived mycelium leather and lab-grown collagen alternatives are eroding pricing power in mid-tier accessories where durability claims once justified premiums.
Strategic Opportunities
- India PLI Scheme for Textiles:Production-linked incentives for man-made fiber and technical textiles are drawing contract manufacturing investment away from Bangladesh and Vietnam.
- Direct-to-Consumer Channel Control:Owned retail networks and localized micro-factories enable margin capture and rapid SKU rotation responsive to TikTok-driven trend cycles.
- Blockchain Traceability Convergence:Integration of distributed ledger verification with RFID tagging satisfies EU digital product passport requirements while commanding price premiums from transparency-seeking buyers.
Industry Challenges
- Artisanal Skill Scarcity:Master pattern-cutters and hand-finishers in Paris and Florence ateliers are retiring faster than apprenticeship pipelines replenish, threatening small-batch production capacity.
- Legacy System Integration:ERP modernization for multi-brand conglomerates requires reconciling decades-old inventory databases with real-time demand forecasting platforms, delaying omnichannel rollout timelines.
- Certification Timeline Compression:OEKO-TEX and Leather Working Group audit backlogs extend compliance verification to 14-18 months, blocking market access for reformulated product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Apparel and Leather Products Market |
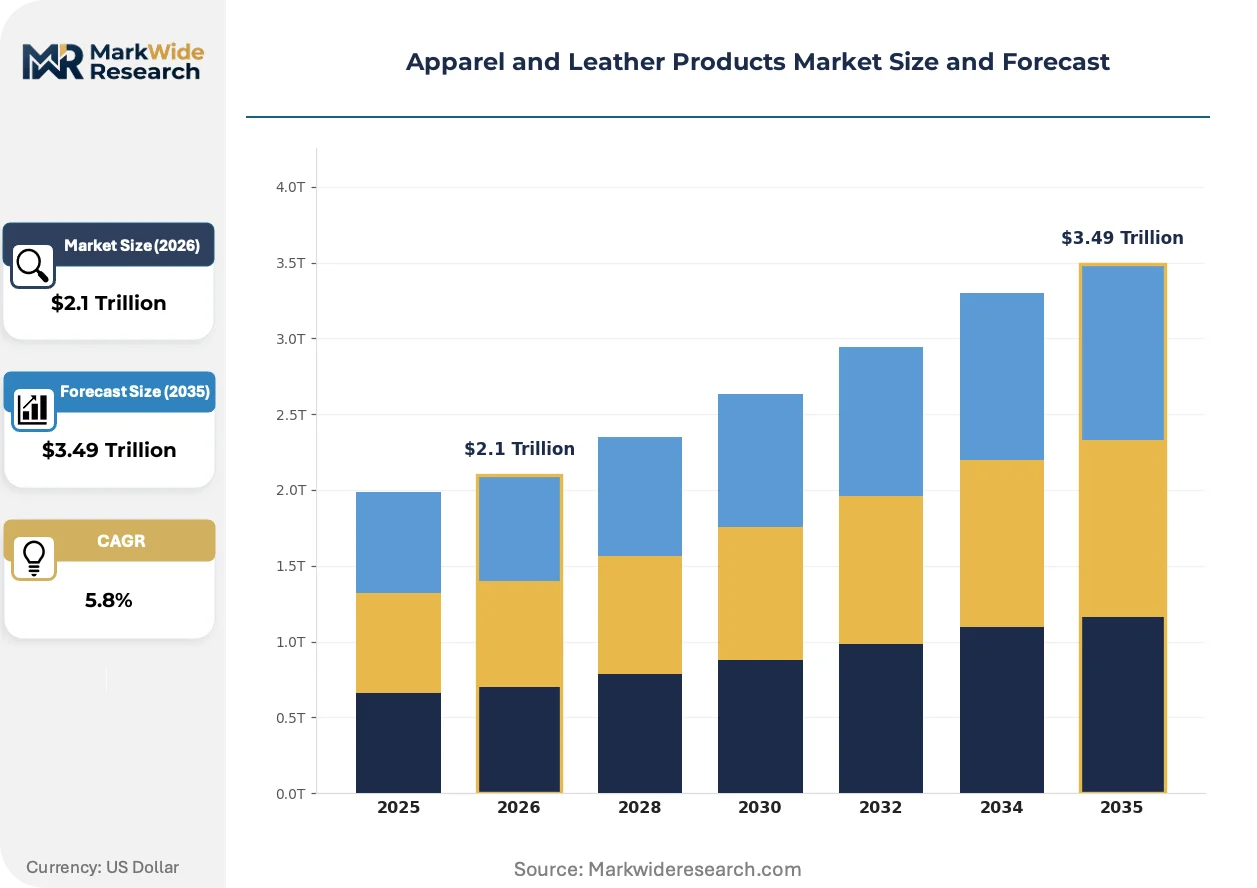
| Market Size in 2026 | $2.1 Trillion |
| Market Size in 2035 | $3.49 Trillion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Footwear, Bags, Clothing, Accessories Material: Leather, Synthetic Fabric, Cotton, Denim Customer Type: Men, Women, Children, Unisex Sales Channel: Online Retail, Brick-and-Mortar, Wholesale, Direct-to-Consumer |
| Companies Covered | LVMH Moët Hennessy Louis Vuitton SE, Kering SA, Hermès International SA, Adidas AG, Nike Inc., Capri Holdings Limited, Tapestry Inc., Prada SpA, VF Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Apparel and Leather Products Market Trends and Innovations
Material science breakthroughs and regulatory digitization are converging to reshape how apparel and leather products are designed, verified, and sold across fragmented consumer markets.
Regenerative agriculture-certified wool and traceable cashmere are supplanting conventional fiber sourcing as luxury houses respond to Scope 3 emissions disclosure requirements. Burberry and Stella McCartney are accelerating procurement from Mongolian herding cooperatives with satellite-verified pasture management. This shift is compressing margins for untraceable commodity fiber traders while rewarding vertically integrated ranch-to-retail operators.
REACH authorization procedures for chromium VI compounds are tightening allowable limits in leather finishing, compelling tanneries in Veneto and Alcanena to adopt vegetable-tanning and metal-free alternatives. The regulatory burden falls heaviest on small-batch artisan producers lacking capital for wet-green chemistry conversion. Spanish and Portuguese suppliers are consolidating to share compliance infrastructure and audit costs.
Resale platform integration is fragmenting primary market control as Vestiaire Collective and The RealReal embed authentication services into brand-owned channels. Younger demographics in Seoul and Tokyo increasingly initiate luxury purchases through pre-owned marketplaces, forcing heritage labels to launch certified secondhand programs or cede customer relationship data to intermediaries.
Apparel and Leather Products Market Segmentation
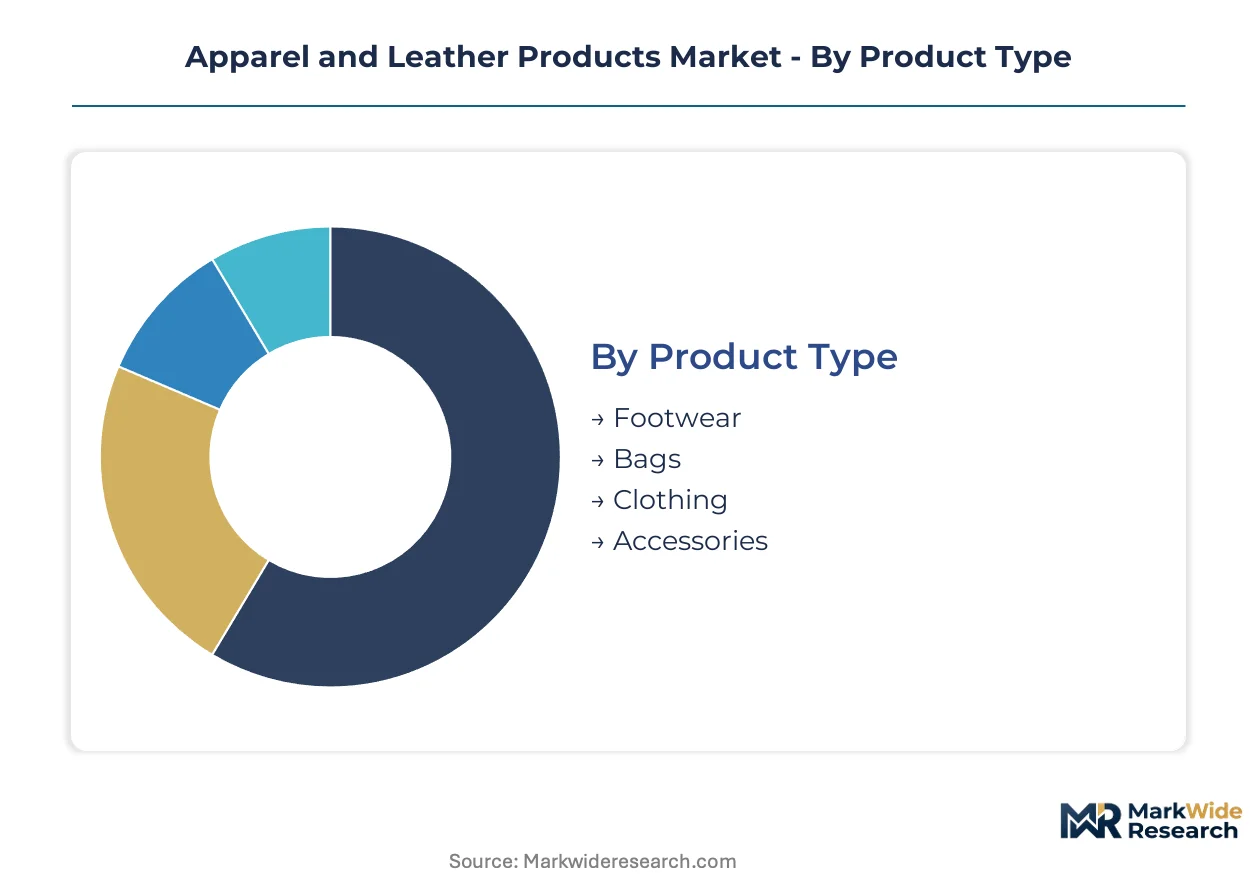
Segmentation in apparel and leather products reveals where pricing power concentrates and how regulatory pressure reshapes material choices. Manufacturers configure production lines around margin-differentiated categories rather than volume alone.
Product Type:
Margin pools concentrate in accessories and leather goods where brand equity sustains premium multiples over cost of goods.
- Accessories:Small leather goods, belts, and jewelry command the highest margin-to-weight ratios in luxury portfolios. Demand clusters in China's tier-one cities where heritage European labels compete with domestic upstarts for wallet share among high-net-worth consumers.
- Clothing:Garments dominate absolute volume across all customer segments but compress margins through inventory risk and seasonal obsolescence. Italian and Spanish manufacturing clusters are investing in closed-loop recycling systems to meet EU Green Deal circularity mandates while defending price positioning.
- Footwear:Athletic and fashion footwear segments absorb disproportionate R&D spending on engineered polymers and sustainable midsole foams.
- Bags:Handbags and luggage concentrate brand storytelling investment, with artisanal construction justifying entry price points above mass-market alternatives.
The dominant share belongs to Clothing, while Accessories is closing the gap fastest.
Material:
Cost tier stratification separates premium natural materials from performance-engineered synthetics targeting divergent end-use requirements.
- Leather:Animal hides processed through chrome or vegetable tanning deliver durability perception that supports pricing premiums. REACH chromium VI restrictions are forcing tanneries in Veneto and Alcanena to reformulate finishing processes, elevating compliance costs for small-batch producers.
- Synthetic Fabric:Engineered polymers with moisture-wicking and recyclability properties are capturing performance apparel segments previously dominated by natural fibers. Nike's advanced synthetic R&D programs anchor competitive positioning in athletic applications.
- Cotton:Conventional and organic cotton varieties face margin pressure from fiber traceability requirements and water-use scrutiny.
- Denim:Indigo-dyed cotton twill maintains volume dominance in casual wear despite environmental challenges from dyehouse effluent regulations.
Synthetic Fabric is expanding most quickly through performance innovation, though Leather retains the premium pricing tier.
Customer Type:
Application focus shifts from demographic targeting toward occasion-based wardrobe building across gender lines.
- Women:Higher purchase frequency and broader category participation concentrate marketing investment and retail floor space allocation. Seoul and Tokyo resale platform activity disproportionately involves women's luxury goods, fragmenting primary market control.
- Men:Slower replacement cycles and brand loyalty patterns favor heritage label retention, with tailored clothing and leather goods sustaining margin concentration.
- Children:Growth-contingent sizing creates inventory complexity and return-rate challenges that suppress margin profiles relative to adult segments.
- Unisex:Gender-neutral styling reduces SKU proliferation costs while capturing younger demographic preferences in urban markets.
The dominant share belongs to Women, while Unisex is gaining share fastest among under-35 consumers.
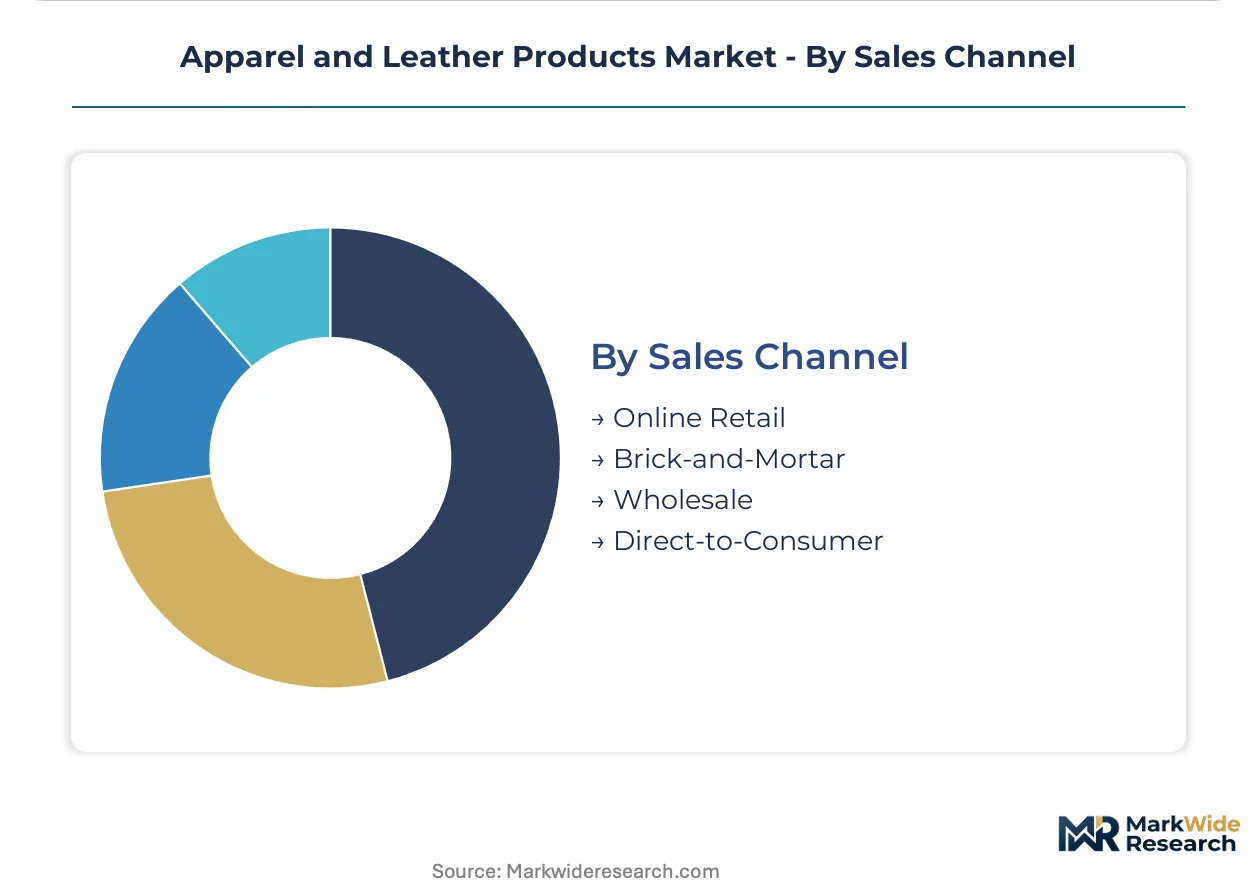
Sales Channel:
Volume distribution runs through fragmented wholesale networks while margin capture concentrates in owned retail and digital direct relationships.
- Direct-to-Consumer:Owned retail networks and localized micro-factories enable rapid SKU rotation responsive to TikTok-driven trend cycles. Adidas competes via channel control investments that bypass wholesale margin sharing.
- Online Retail:Third-party marketplace presence expands reach but cedes customer data and pricing autonomy to platform operators.
- Brick-and-Mortar:Flagship boutiques in Shanghai, Beijing, and Shenzhen serve brand storytelling functions beyond transaction volume.
- Wholesale:Department store and specialty retail partnerships retain importance for market entry but compress margins through discounting pressure and inventory risk transfer.
The dominant share still sits with Wholesale, though Direct-to-Consumer is climbing the fastest as brands reclaim customer relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity diverges sharply across geographies, with Chinese tier-one city buyers absorbing premium pricing while Southeast Asian consumers drive volume through value-tier purchases. European heritage markets exhibit inelastic demand for artisanal leather goods, whereas North American athletic segments prioritize performance-per-dollar metrics.
China
Shanghai, Beijing, and Shenzhen consumers are driving double-digit expansion in domestic luxury brands competing with European heritage labels. MIIT's dual carbon goals and GB standards for textile emissions are tightening manufacturing compliance requirements. The Yangtze River Delta manufacturing cluster is absorbing technology transfers from Italian tanneries to meet EU export specifications.
United States
Athleisure demand and resale platform adoption are fragmenting primary market control among younger demographics. California's Proposition 65 chemical disclosure rules and EPA effluent guidelines are elevating compliance costs for imported leather goods. The Southeast apparel manufacturing corridor spanning Georgia and the Carolinas is reshoring cut-and-sew operations to bypass tariff exposure.
Italy
Heritage leather goods and artisanal construction command persistent pricing premiums from Asian tourists and domestic collectors. EU REACH chromium VI restrictions and the EU Green Deal's textile circularity mandates are forcing Veneto tanneries to reformulate finishing processes. The Tuscan leather district around Santa Croce sull'Arno is consolidating wet-green chemistry investments to share compliance infrastructure.
India
Domestic apparel consumption and export-oriented contract manufacturing are expanding in parallel. The PLI scheme for textiles is drawing man-made fiber investment away from Bangladesh and Vietnam. The Tamil Nadu leather cluster near Ambur and Vaniyambadi is modernizing effluent treatment to meet European retail buyer audit requirements.
Japan
Resale platform penetration and vintage luxury demand are compressing primary market volumes for heritage accessories. METI's resource circulation policies and JIS standards for textile recycling are accelerating closed-loop fiber development. The Osaka-Kobe manufacturing corridor is specializing in technical textiles for performance outerwear exports.
Apparel and Leather Products Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where scale-driven synthetics specialists coexist with artisanal heritage houses. The market consolidates around conglomerate portfolios at the premium tier and fragments across specialized athletic and fast-fashion operators. Three archetypes dominate: vertically integrated luxury groups, R&D-intensive performance brands, and direct-to-consumer challengers. Competitive moves concentrate on backward integration into tanneries and fiber production, alongside owned-retail network expansion to reclaim margin from wholesale intermediaries.
Within the luxury conglomerate tier, LVMH Moët Hennessy Louis Vuitton SE and Kering SA exemplify vertical control from raw material sourcing through flagship retail. Nike Inc. anchors the performance-technology archetype through advanced synthetic material development. These three entities represent the structural poles around which mid-cap specialists and regional challengers position their differentiation strategies.
| Leading Market Players |
|---|
| LVMH Moët Hennessy Louis Vuitton SE |
| Kering SA |
| Hermès International SA |
| Adidas AG |
| Nike Inc. |
| Capri Holdings Limited |
| Tapestry Inc. |
| Prada SpA |
| VF Corporation |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between Italian tanneries and French luxury houses lock in hide supply visibility while insulating artisanal producers from spot-market volatility in cattle hide pricing. These contracts embed volume commitments and quality-grade specifications that cascade through Veneto and Alcanena processing clusters, reinforcing pricing power for heritage brands while compressing margins for uncontracted mid-tier competitors.
Pricing Analysis
After-sales service revenue from repair, refurbishment, and authentication programs drives lifetime value capture for luxury leather goods manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates heritage atelier products from industrial-scale manufacturers and fast-fashion alternatives. Cost compression in mid-tier accessories is intensifying because mushroom-derived mycelium alternatives erode durability-based pricing premiums. Value-conscious buyers in Southeast Asian markets exhibit highest price sensitivity, while collectors in China's tier-one cities demonstrate lowest elasticity for limited-edition artisanal pieces.
Supply Chain Analysis
Inventory cycles spanning 12-18 months from hide procurement to finished goods delivery create working capital intensity that favors well-capitalized conglomerates over independent ateliers. Raw material sourcing draws from cattle hide suppliers in Brazil, Argentina, and the United States, with finishing chemicals anchored in German and Italian specialty chemical production. Single-source vulnerability concentrates in chrome-tanning chemical supply chains subject to REACH authorization delays. Distribution runs through owned flagship boutiques in Shanghai, Beijing, and Shenzhen alongside wholesale partnerships with department store networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The apparel and leather products market exhibits cyclical recovery characteristics as post-pandemic wardrobe replenishment and return-to-office dress codes stimulate replacement demand for formal and accessories categories.
For Market Incumbents: Fortify captive tannery capacity in Veneto and Alcanena to secure leather supply amid REACH chromium VI reformulation requirements. Deepen backward integration into regenerative wool sourcing from Mongolian herding cooperatives to satisfy Scope 3 disclosure mandates from European retail buyers. These moves defend margin pools against biomaterial substitutes eroding mid-tier pricing power.
For New Entrants and Emerging Players: Anchor in India's Tamil Nadu leather cluster near Ambur and Vaniyambadi to capture PLI scheme incentives for man-made fiber and technical textile manufacturing. Target white-space opportunity in blockchain-verified traceability services for EU digital product passport compliance. Deploy direct-to-consumer micro-factory networks in tier-two Chinese cities to bypass wholesale margin sharing with established intermediaries.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialty tanneries with wet-green chemistry conversion capabilities and established Leather Working Group certification. Long-term viability over the coming decade hinges on regulatory compliance infrastructure rather than volume scale alone. Monitor OEKO-TEX and LWG audit backlog clearance rates as inflection indicator for reformulated product line market access timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tanneries | Captive hide processing secures margin pools against REACH reformulation cost pass-through to independent suppliers. |
| Blockchain Traceability Deployment | Distributed ledger verification satisfies EU digital product passport requirements while commanding transparency premiums from Seoul and Tokyo buyers. |
| Direct-to-Consumer Channel Expansion | Owned retail networks enable rapid SKU rotation responsive to TikTok-driven trend cycles without wholesale margin dilution. |
| Sustainability Repositioning | Regenerative agriculture certification and metal-free tanning alternatives defend pricing power against mycelium leather substitution. |
| Regional Manufacturing Footprint | Localized micro-factories in Georgia and the Carolinas bypass tariff exposure while shortening lead times for North American athleisure demand. |
Research Methodology
A spread of perspectives from brand managers at heritage houses, category buyers at European department stores, tannery operations directors in Veneto, and supply planners at athletic footwear manufacturers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against customs records, SEC 10-K filings, and Leather Working Group audit disclosures. Bottom-up triangulation across material input costs and finished goods pricing was cross-checked against top-down market sizing from trade association data.
Segmentation dimensions modeled include product type, material composition, customer demographic, and sales channel across the projection horizon. CAGRs were derived from regression analysis of historical volume trajectories adjusted for regulatory intervention effects. Forecast inputs incorporated hide supply cycle patterns, REACH authorization timeline assumptions, and resale platform penetration rates in Seoul and Tokyo.
Material uncertainties — cattle hide availability fluctuations, REACH enforcement intensity variations, and biomaterial substitution acceleration — sit outside the modeled envelope. Outputs reflect documented assumptions about regulatory compliance cost pass-through and consumer willingness-to-pay for traceability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Maternity Apparels Market
Apparel & Footwear
North America E-Commerce Apparel Market
Apparel & Footwear
Designer Sneaker Market
Apparel & Footwear
Official Football Kits Market
Apparel & Footwear
Golf Outfit Market
Apparel & Footwear
France Denim Jeans Market
Apparel & Footwear
Mister Cap Market
Apparel & Footwear
Brazil Pet Clothing Market
Apparel & Footwear
Men's Underwear Market
Apparel & Footwear
Fast Fashion Market
Apparel & Footwear
Multiple Toe Socks Market
Apparel & Footwear
Streetwear Market
Apparel & Footwear
Compression Wear and Shapewear Market
Apparel & Footwear
Women's Night and Underwear Market
Apparel & Footwear
Global Swimwear (Swimsuit) Market
Apparel & Footwear
Outdoor Sports Apparel Market