
 South Africa Denim Jeans Market | 2026-2036
South Africa Denim Jeans Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Denim Jeans Market Insights
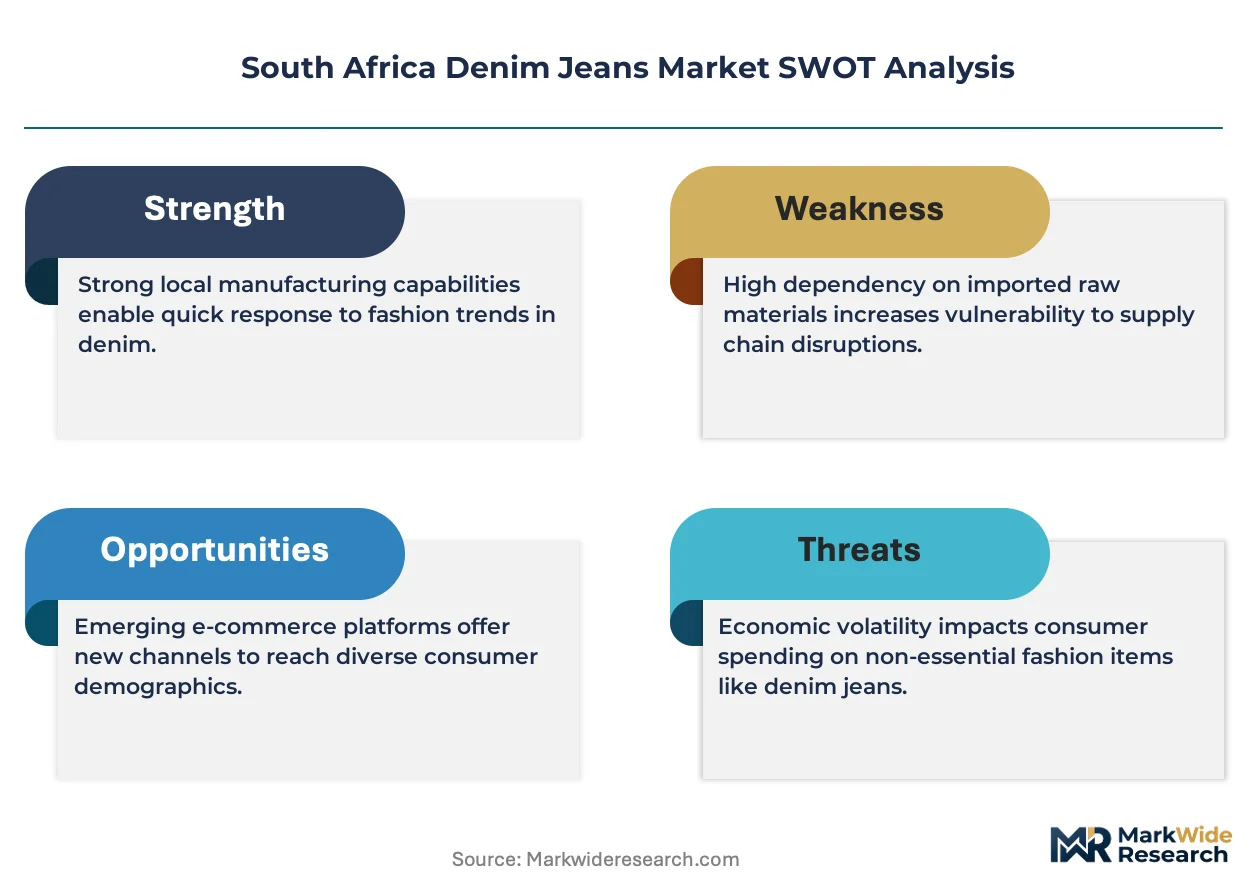
South Africa's domestic denim manufacturing base is tilting toward greater localization as import substitution pressures mount. Levi Strauss & Co leverages its heritage positioning to sustain premium pricing across major South African metros. Tshepo Jeans anchors its competitive stance through artisanal craftsmanship and patriotic brand storytelling. Me&B specializes in size-inclusive fits that differentiate its offering from international mass-market labels.
Denim jeans are twill-woven cotton trousers with warp-faced construction, typically weighing 12 to 14 ounces per square yard, engineered for durability and aesthetic aging through indigo dyeing and finishing treatments. They serve as foundational casual and semi-formal apparel across consumer wardrobes. Skinny jeans and straight leg cuts dominate unit volume, while stretch denim fabric technology commands the fastest expansion as consumers prioritize comfort mobility. Distribution through branded stores captures the highest margin pools, whereas online retailers experience the steepest trajectory as digital payment infrastructure matures.
SABS textile standards and the National Regulator for Compulsory Specifications (NRCS) shape product compliance costs, forcing importers and local producers alike to adapt labeling, chemical content, and flammability protocols. The Consumer Protection Act reinforces warranty and return obligations that influence inventory and pricing strategies. Stakeholders must monitor evolving eco-labeling requirements and water stewardship benchmarks as sustainability credentials increasingly filter purchase decisions.
Market Dynamics
Stretch denim fabric technology is compressing traditional rigid cotton demand as Gauteng's fashion-conscious urban consumers prioritize comfort mobility over heritage construction.
Growth Catalysts
- SABS Textile Labeling Mandates:Compliance requirements are filtering out informal importers and consolidating shelf space for certified domestic producers.
- Young Adult Cohort Expansion:Urban consumers under 35 in Johannesburg and Pretoria are driving premium denim trial through social commerce discovery.
- Digital Payment Maturation:Mobile wallet penetration is unlocking e-commerce velocity for denim brands previously constrained by cash-on-delivery friction.
Market Restraints
- Cotton Price Volatility:Raw fiber input costs swing with global commodity markets, compressing margin buffers for mid-tier local manufacturers.
- Import Concentration Risk:Bulk finished denim arrives through Durban port, creating single-point vulnerability during labor disruptions or customs delays.
- NRCS Chemical Content Protocols:Heavy metal and azo dye testing requirements add 6-8 week certification timelines for new product introductions.
Strategic Opportunities
- Western Cape Underpenetration:Cape Town's premium fashion corridor shows whitespace for size-inclusive and artisanal positioning absent from current retail mix.
- Water Stewardship Benchmarks:Emerging eco-labeling requirements favor producers investing in closed-loop dyeing systems ahead of mandatory disclosure.
- Direct-to-Consumer Platforms:Social commerce integration with Instagram and TikTok shops is bypassing traditional wholesale markups for digitally native brands.
Industry Challenges
- Technical Pattern-Making Talent Scarcity:Local apparel institutes produce insufficient graders and technical designers versed in stretch fabric behavior.
- Legacy ERP Integration Friction:Established manufacturers struggle to synchronize inventory visibility between factory floor systems and emerging marketplace APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Denim Jeans Market |
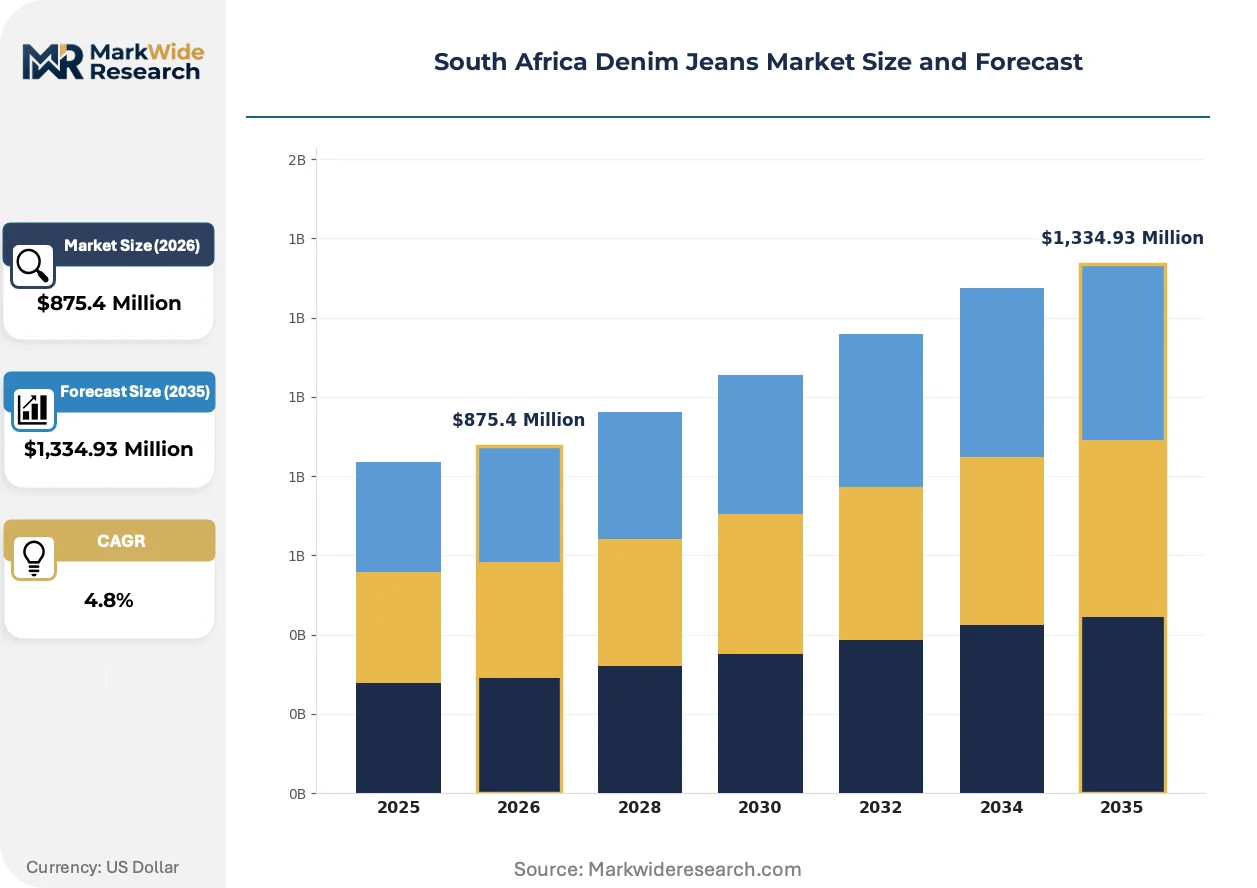
| Market Size in 2026 | $875.4 Million |
| Market Size in 2035 | $1,334.93 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skinny Jeans, Straight Leg, Bootcut, Relaxed Fit, Flared, Tapered End User: Young Adults, Working Professionals, Students, Retail Shoppers, Tourists Distribution Channel: Branded Stores, Online Retailers, Department Stores, Specialty Boutiques, Wholesale Markets Fabric Technology: Stretch Denim, Organic Cotton, Heavyweight Denim, Lightweight Denim, Eco-Friendly Dyes |
| Companies Covered | Denim Jeans, Pepe Jeans, Levi Strauss & Co, VF Corp, Bestseller, Tshepo Jeans, Me&B, Gap Inc, Rhysley, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Denim Jeans Market Trends and Innovations
Digital infrastructure and sustainability credentialing are simultaneously rewiring how denim reaches South African consumers and how it is manufactured before arrival.
Laser finishing equipment is digitizing traditional hand-sanding and potassium permanganate spray processes in Cape Town and Johannesburg finishing facilities. Mid-tier producers are retrofitting aging plants with automated distressing systems to reduce chemical exposure and water consumption. This capital deployment is digitizing labor-intensive surface treatment work previously outsourced to informal workshops.
The Consumer Protection Act's warranty and return obligations are forcing inventory strategy recalibration across branded retail networks. Retailers must now provision for 6-month defect liability coverage, compressing initial order quantities and accelerating replenishment cycle frequency. Premium positioned stores in Sandton and Menlyn Park are responding with RFID-enabled stock visibility to balance compliance exposure against availability targets.
Size-inclusive fit specialization is fragmenting the standard five-size run that dominated mass-market denim for decades. Independent labels are capturing defecting consumers from international chains through customized measurement protocols and local body-shape data. This preference rotation is most visible among professional women in Pretoria's corporate corridors who previously accepted compromised fits from global fast-fashion imports.
South Africa Denim Jeans Market Segmentation
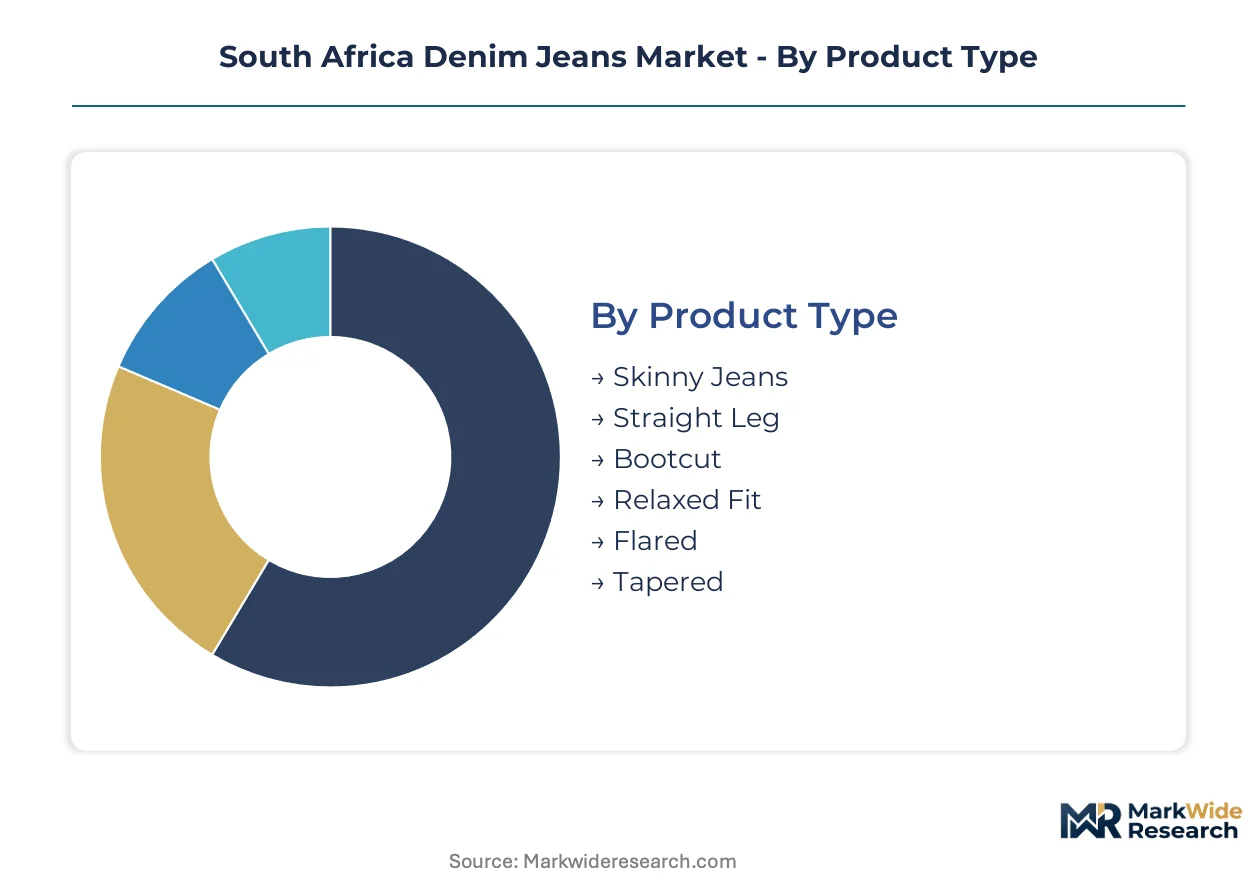
Denim segmentation in South Africa reflects divergent velocity patterns across fit preferences, fabric technologies, and channel economics. Understanding turnover speed by segment enables inventory positioning that matches Gauteng's premium consumption rhythm against wholesale market bulk throughput.
Product Type:
Skinny and straight leg cuts rotate through retail fastest, while bootcut and flared silhouettes sit longer on racks awaiting cyclical fashion revival.
- Skinny Jeans:Body-hugging silhouette constructed with high elastane content (2-4%) for recovery and shape retention. Johannesburg's young adult professionals in Sandton and Rosebank drive repeat purchase frequency through workplace-casual versatility.
- Straight Leg:Uniform width from thigh to ankle accommodating broader body types without tapering. Pretoria's government sector employees favor this cut for its conservative profile that bridges formal and informal dress codes.
- Bootcut:Subtle flare from knee downward designed to accommodate footwear stacking. Heritage denim collectors in Cape Town's Atlantic Seaboard sustain niche demand.
- Relaxed Fit:Generous cut through seat and thigh prioritizing unrestricted movement. Weekend and leisure contexts in Durban's coastal suburbs absorb volume.
- Flared:Dramatic widening from knee recalling 1970s silhouettes. Vintage-inspired consumers in Johannesburg's Maboneng precinct trial periodically.
- Tapered:Narrowing leg opening contrasting with roomier thigh construction. Transitional buyers migrating from skinny cuts experiment here.
Straight leg dominates installed base. Skinny jeans is where expansion concentrates.
End User:
Working professionals and students generate predictable replenishment cycles, while tourist demand fluctuates with seasonal arrival patterns.
- Young Adults:Fashion-forward cohort aged 18-30 prioritizing trend responsiveness over durability. Social commerce discovery on Instagram and TikTok accelerates trial rates in Johannesburg's northern suburbs.
- Working Professionals:Corporate and public sector employees requiring polished casual options. Pretoria's administrative corridors sustain consistent premium denim procurement with quality-over-price preference.
- Students:Price-sensitive segment accepting trade-offs in fabric weight and finishing detail. University towns Stellenbosch and Grahamstown concentrate volume.
- Retail Shoppers:Transactional buyers responding to promotion and visual merchandising. Mall-based conversion in Menlyn Park and Gateway shopping centres.
- Tourists:International visitors seeking locally manufactured souvenirs or duty-advantaged international brands. Cape Town International Airport corridor captures this flow.
Working professionals dominate installed base. Young adults is where expansion concentrates.
Distribution Channel:
Online retailers compress cycle times through algorithmic restocking, whereas wholesale markets operate on extended credit terms and slower inventory turns.
- Branded Stores:Flagship and mall-based company-owned locations controlling presentation and pricing. Sandton City and V&A Waterfront flagships capture Gauteng and Western Cape premium spend.
- Online Retailers:E-commerce platforms and brand-direct websites leveraging mobile wallet penetration. Takealot and Superbalist infrastructure enables next-day delivery to Johannesburg and Pretoria addresses.
- Department Stores:Edgars and Woolworths floor space providing discovery for undecided shoppers. Mid-tier price positioning with promotional calendar dependency.
- Specialty Boutiques:Curated independent retailers emphasizing local design and limited runs. Kloof Street and Long Street in Cape Town anchor this channel.
- Wholesale Markets:Bulk procurement hubs serving informal traders and rural retailers. Johannesburg's Fashion District and Durban's Warwick Junction sustain this tier.
Branded stores dominate installed base. Online retailers is where expansion concentrates.
Fabric Technology:
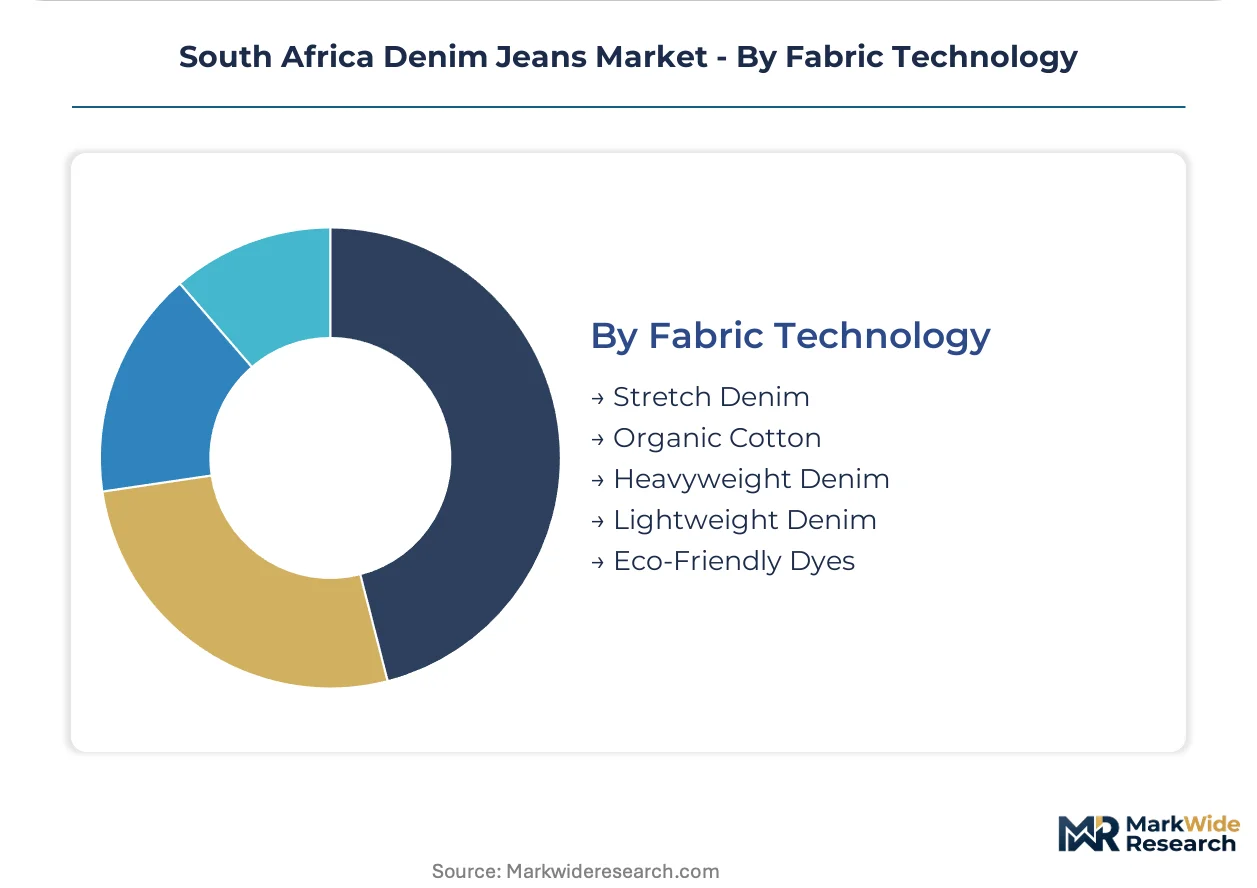
Stretch denim commands production priority due to consumer comfort expectations, while organic cotton and eco-friendly dyes face longer adoption curves.
- Stretch Denim:Warp-faced twill integrating elastane or Lycra for multidirectional give. Gauteng's urban commuters prioritize seated comfort during extended travel times.
- Organic Cotton:Fiber grown without synthetic pesticides or fertilizers, certified through third-party audit. Environmentally conscious consumers in Cape Town's Atlantic Seaboard absorb price premiums.
- Heavyweight Denim:Fabric exceeding 14 ounces per square yard for durability and structured drape. Heritage workwear enthusiasts and motorcycle riders in Johannesburg seek this specification.
- Lightweight Denim:Sub-10 ounce constructions for warm climate wearability. Durban and coastal KwaZulu-Natal markets favor breathability.
- Eco-Friendly Dyes:Reduced-water or plant-based indigo alternatives minimizing chemical discharge. Emerging SABS-aligned labeling requirements favor early adopters.
Stretch denim dominates installed base. Eco-friendly dyes is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The South African Bureau of Standards anchors compliance frameworks across the national denim value chain. Provincial consumption clusters diverge sharply between Gauteng's premium corridor and underpenetrated secondary markets.
Gauteng
Johannesburg and Pretoria generate the bulk of premium denim purchases through Sandton City and Menlyn Park flagships. The National Regulator for Compulsory Specifications enforces chemical content protocols that filter informal imports from formal retail channels. Rosebank's design district concentrates social commerce-enabled brands targeting young adult professionals.
Western Cape
Cape Town's Atlantic Seaboard sustains demand for organic cotton and artisanal finishing among environmentally conscious consumers. Municipal water stewardship benchmarks are accelerating adoption of closed-loop dyeing systems in local finishing facilities. Kloof Street specialty boutiques capture whitespace for size-inclusive positioning absent from mall-based retail mix.
KwaZulu-Natal
Durban's coastal suburbs absorb lightweight denim volumes prioritizing warm-climate breathability. Warwick Junction wholesale markets serve informal traders extending distribution into rural KwaZulu-Natal. Port congestion at Durban Harbor creates single-point vulnerability for import-dependent retailers.
Eastern Cape
University towns Grahamstown and Port Elizabeth concentrate student-segment price-sensitive demand. Local apparel institutes in the region produce insufficient technical pattern-making talent versed in stretch fabric behavior. Retail infrastructure gaps force consumers toward online platforms with next-day delivery limitations.
South Africa Denim Jeans Market Competitive Landscape
Capability concentration sits with heritage-positioned multinationals; scale advantage sits with vertically integrated global apparel conglomerates. The market structures around three tiers: international heritage brands commanding premium pricing, local artisanal labels capturing patriotic sentiment, and fast-fashion imports filling volume gaps. Dominant competitive moves include direct-to-consumer platform expansion bypassing wholesale markups, and sustainability credentialing investments anticipating mandatory eco-labeling disclosure.
Within the heritage multinational tier, Levi Strauss & Co exemplifies brand equity monetization through flagship retail presence. Among locally anchored artisanal specialists, Tshepo Jeans occupies a position emphasizing patriotic narrative and craftsmanship positioning. Me&B represents the size-inclusive specialization archetype, capturing defecting consumers from international mass-market labels through customized fit protocols.
| Leading Market Players |
|---|
| Denim Jeans |
| Pepe Jeans |
| Levi Strauss & Co |
| VF Corp |
| Bestseller |
| Tshepo Jeans |
| Me&B |
| Gap Inc |
| Rhysley |
| Others |
Pricing and Supply Chain Analysis
Durban Harbor's import concentration anchors finished denim throughput, with port congestion and labor disruptions amplifying pricing volatility for Gauteng retailers dependent on Asian manufacturing. This geographic chokepoint compresses margin buffers when container delays extend inventory cycles, forcing mid-tier brands to absorb cost spikes or sacrifice shelf availability.
Pricing Analysis
Johannesburg-to-Cape Town price spreads reflect transport cost layering onto landed import values, with Sandton City flagships commanding premiums over Warwick Junction wholesale tiers. Pricing stratifies across premium heritage positioning, mid-tier local craftsmanship, and economy bulk imports, with stretch denim fabric technology sustaining margin expansion against rigid cotton commoditization. Cotton price volatility from global commodity markets is intensifying cost compression for domestic manufacturers lacking forward-contract coverage. Students in university towns exhibit highest price sensitivity, while young adult professionals in Rosebank demonstrate lowest elasticity for trend-responsive fits.
Supply Chain Analysis
Bangladesh, Vietnam, and China contract manufacturers hold dominant capacity for finished denim bound through Durban Harbor, with Tshepo Jeans and Me&B representing localized exceptions. Raw material dependencies center on Pakistani and Indian cotton fiber, Indonesian and Chinese elastane for stretch constructions, and Indian or Turkish indigo dye concentrates. Single-port vulnerability at Durban Harbor creates structural risk during customs delays or labor actions. Distribution runs through branded flagships in Sandton and Menlyn Park, online platforms leveraging Takealot infrastructure, and wholesale markets serving informal rural traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stretch denim fabric technology and SABS eco-labeling mandates are converging to disrupt competitive positioning, rewarding early movers in water-stewardship certification and digital direct-to-consumer infrastructure.
For Market Incumbents: Pre-empt margin erosion from fast-fashion imports by deepening artisanal craftsmanship differentiation and securing closed-loop dyeing certification ahead of mandatory SABS disclosure requirements. Lock in cotton forward contracts to buffer commodity volatility, and deploy RFID-enabled inventory systems to balance Consumer Protection Act warranty obligations against stock availability targets. For New Entrants and Emerging Players: Cape Town's Atlantic Seaboard underpenetration offers whitespace for size-inclusive specialization and organic cotton positioning absent from current mall-based retail mix. Target young adult professionals through Instagram and TikTok shop integration, bypassing traditional wholesale markups with social commerce-native customer acquisition. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated local brands with captive finishing capabilities and sustainability credentialing ahead of regulatory inflection. Acquisition focus should center on pattern-making talent pools and laser-finishing equipment deployments. Monitor NRCS chemical content protocol enforcement intensity as signal for compliance cost barriers rising against import-dependent competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Dyeing System Investment | Positions producers ahead of SABS water stewardship benchmark mandates. |
| Direct-to-Consumer Platform Launch | Bypasses Edgars and Woolworths wholesale markups via Instagram Shop integration. |
| Size-Inclusive Fit Protocol Development | Captures defecting professional women from international fast-fashion labels. |
| Stretch Denim R&D Expansion | Addresses Gauteng commuter comfort demands and technical talent scarcity. |
| Western Cape Flagship Expansion | Establishes presence in Cape Town's premium fashion corridor whitespace. |
Research Methodology
Cross-validation between brand manager interviews and customs import data anchors the qualitative findings for this analysis. Primary fieldwork engaged denim brand executives, textile procurement leads at major retailers, SABS compliance officers, and finishing facility operators across Johannesburg and Cape Town. Secondary sources included South African Revenue Service trade statistics, SABS textile standard documentation, and Takealot marketplace transaction patterns. Bottom-up channel volume estimates triangulate against top-down consumer expenditure surveys.
Calibration against historical CAGRs and elasticity assumptions shapes the projection framework across the analysis window. Segmentation modeling incorporates fit preference, fabric technology, end-user cohort, and distribution channel dimensions. Stretch denim adoption curves and mobile wallet penetration rates serve as category-specific demand drivers. Value projections derive from unit volume trajectories multiplied by channel-specific price realizations.
Practitioners should monitor cotton futures volatility, Durban Harbor throughput metrics, and NRCS enforcement intensity for early signals of forecast revision. Cross-checking against South African Retailers Association sales benchmarks and SABS certification issuance data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Men Shirts Market
Apparel & Footwear
Gymnastic Leotards Market
Apparel & Footwear
Compression Wear and Shapewear Market
Apparel & Footwear
Asia-Pacific Lingerie Market
Apparel & Footwear
Women's Sports and Swimwear Market
Apparel & Footwear
Yoga Clothing Market
Apparel & Footwear
Golf Apparel Market
Apparel & Footwear
Children's Dresses and Skirts Market
Apparel & Footwear
Asia-Pacific Sports Apparel Market
Apparel & Footwear
Women's Blazer Market
Apparel & Footwear
Sports Apparel Market
Apparel & Footwear
Global Women Pajamas Suits Market
Apparel & Footwear
Custom Cycling Clothing Market
Apparel & Footwear
Global Leggings Market
Apparel & Footwear
Sequins Apparels Market
Apparel & Footwear
Europe Jeans Market