
 Asia Pacific Swimwear Market | 2026-2036
Asia Pacific Swimwear Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Swimwear Market Outlook
Competitive aquatics is broadening the Asia Pacific Swimwear Market's end-use vertical mix beyond leisure tourism into institutional team procurement and training academies. Arena Italia S.p.A. leverages its technical racing suit heritage to anchor elite swimmer loyalty across Japan and South Korea. Wacoal Holdings competes through specialized fit engineering that dominates the women's performance segment in domestic Japanese channels. Seafolly Australia extends its coastal brand strength into Southeast Asian resort retail, controlling premium placement in Thai and Indonesian beach destinations.
Asia Pacific swimwear comprises engineered garments constructed from chlorine-resistant synthetic knits, typically incorporating elastane blends that deliver stretch recovery above 200 percent and UPF ratings exceeding 50 for solar protection. These specifications serve both recreational consumers and competitive athletes requiring hydrodynamic compression and durability against pool chemicals. The women's end user segment leads absolute volume, while the online retail distribution channel represents the fastest-growing structural outlet as direct-to-consumer platforms reshape inventory cycles. Polyester fabric types occupy the largest share of mass-market production, though Lycra and Spandex blends command higher margin pools in performance and fashion-positioned lines.
Japan's METI enforces textile quality standards that govern fiber content accuracy and stretch performance claims, while Australia's ACCC monitors consumer protection compliance for sun protection labeling across swimwear sold domestically. India's BIS certification requirements for imported textiles create procedural barriers that filter smaller foreign suppliers from formal retail channels. Stakeholders must monitor how evolving ESG disclosure rules across ASEAN markets reshape supplier qualification criteria and sourcing transparency obligations.
Market Dynamics
Institutional procurement from competitive swimming programs is rewriting demand composition across Asia Pacific, compressing seasonal leisure cycles into year-round volume commitments while elevating technical specifications above aesthetic positioning.
Growth Catalysts
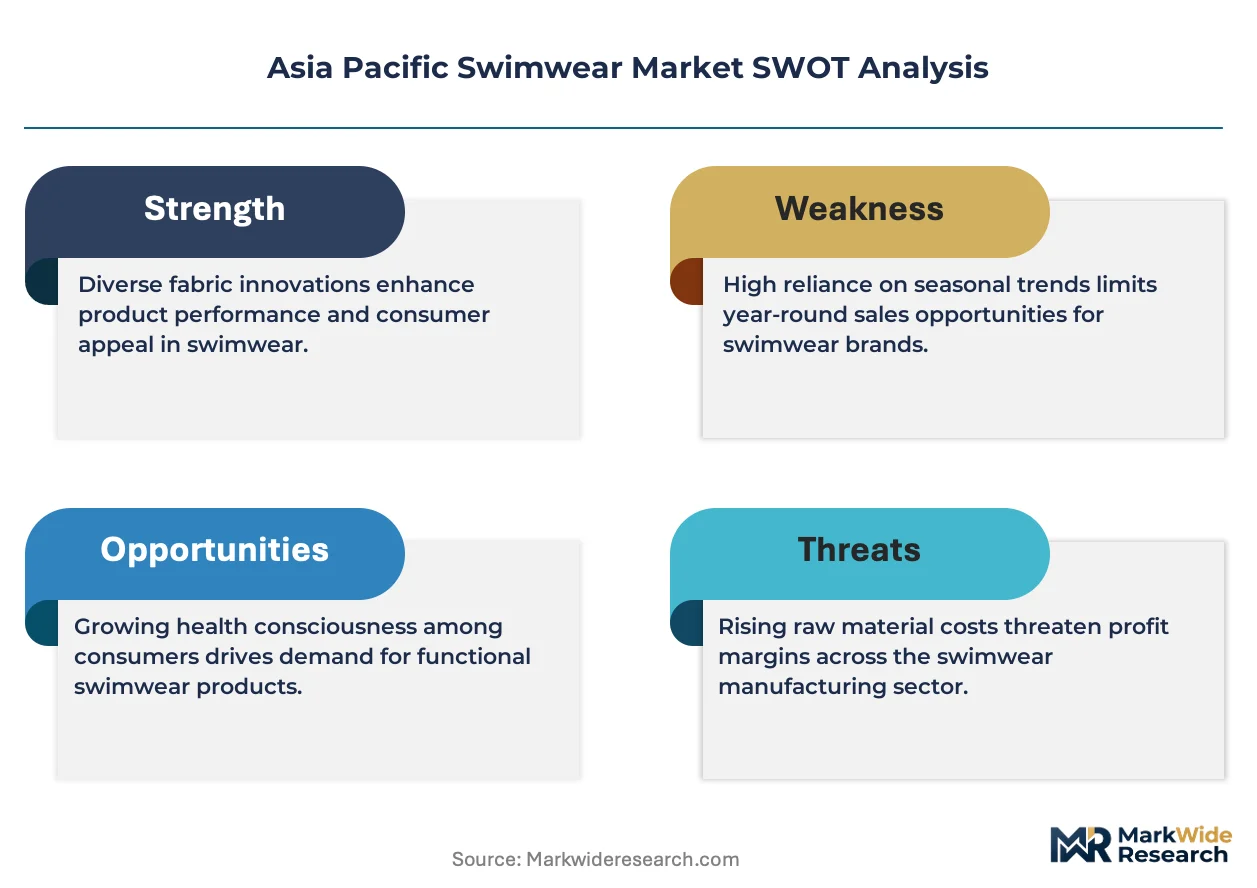
- Japan's METI textile standards:Mandated stretch performance testing elevates certified suppliers above uncertified competitors, creating qualified vendor pools for institutional buyers.
- Competitive aquatics infrastructure:Training academy construction across Australia and Southeast Asia generates recurring team uniform and equipment orders at contracted volumes.
- Elastane blend engineering:Chlorine-resistant knits with recovery above 200 percent extend garment lifecycles, reducing total cost of ownership for pool operators.
Market Restraints
- Petrochemical input volatility:Polyester and elastane feedstock costs fluctuate with crude derivatives, compressing margin stability for synthetic-focused manufacturers.
- India's BIS certification barriers:Mandatory fiber content disclosure and testing timelines filter smaller foreign suppliers from formal retail channels.
- Technical limitation in natural fiber substitution:Cotton and viscose alternatives lack chlorine resistance and UPF ratings required for performance segments.
Strategic Opportunities
- Vietnam and Indonesia resort retail expansion:Underpenetrated coastal tourism corridors offer premium placement potential for brands with established Australian beach retail credentials.
- Direct-to-consumer platform development:Inventory cycle compression through owned digital channels enables made-to-order production and reduced markdown exposure.
- Australia's ACCC sun protection labeling:Verified UPF 50+ claims create defensible premium positioning against uncertified competitors in domestic and export markets.
Industry Challenges
- Technical textile engineering talent scarcity:Specialized knowledge in elastane knit construction and compression patterning concentrates in Japanese and South Korean supplier bases.
- Multi-jurisdiction certification complexity:Simultaneous compliance with Japan's METI standards, India's BIS requirements, and Australia's ACCC labeling demands extended product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Swimwear Market |
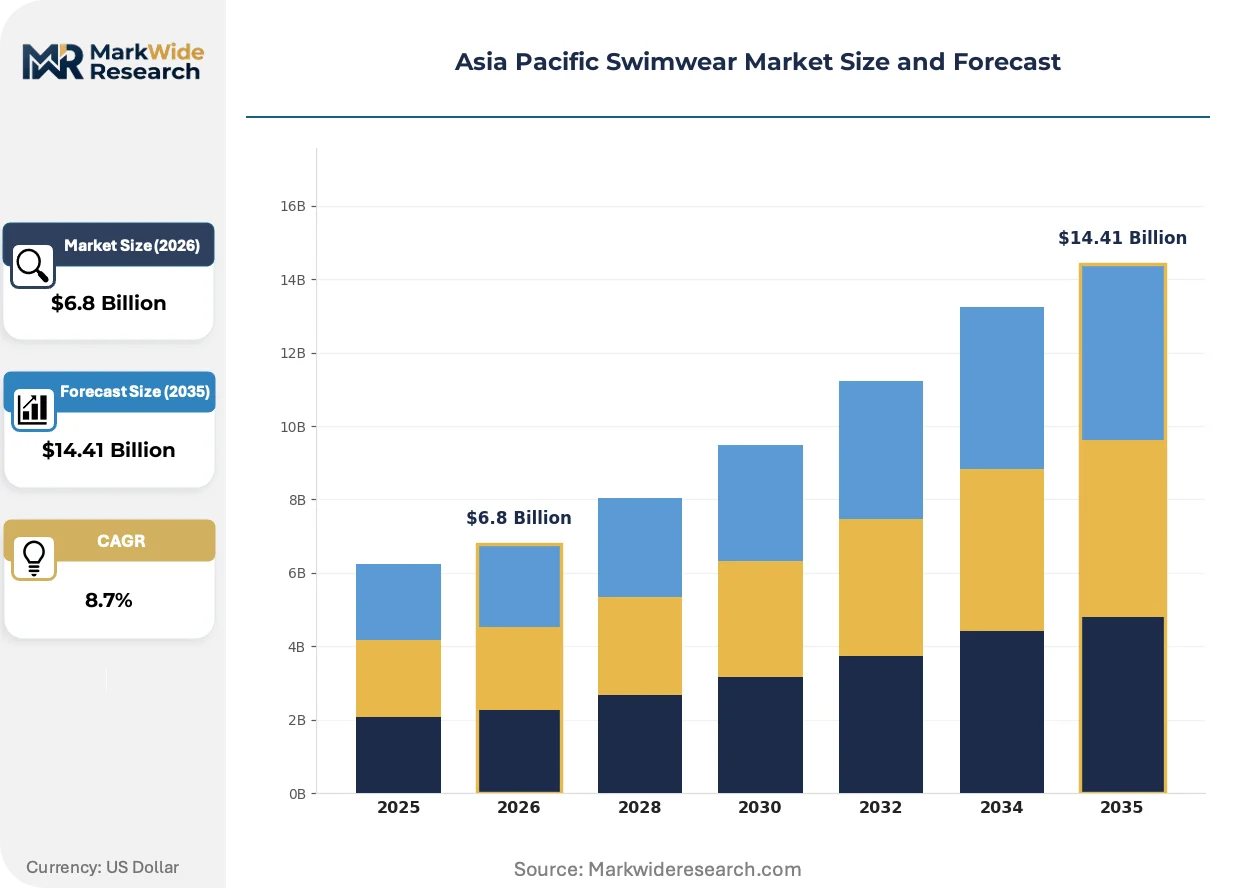
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: One-Piece, Bikini, Tankini, Swim Trunks Fabric Type: Polyester, Nylon, Lycra, Spandex End User: Men, Women, Children, Teens Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Department Stores |
| Companies Covered | Arena Italia S.p.A., Wacoal Holdings, Adidas AG, TYR Sport Inc., Boardriders, Nike Inc., Seafolly Australia, Bali Swim Ltd, Pentland Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Swimwear Market Strategic Shifts
Digital fabrication and regulatory disclosure requirements are compressing traditional design-to-retail cycles while elevating performance verification above marketing claims across Asia Pacific swimwear.
Seamless knitting technology is rewriting production economics for compression-grade racing suits. Japanese performance brands deploy 3D body scanning to eliminate panel seams and reduce hydrodynamic drag. Elite swimming federations in South Korea and Australia now specify seamless construction in technical procurement tenders.
India's BIS textile labeling rules mandate fiber content disclosure for all imported swimwear, forcing reformulation toward certified synthetic blends. Brands must maintain parallel supply chains: BIS-compliant lines for Indian formal retail and flexible compositions for other Asia Pacific markets. This regulatory divergence increases SKU complexity but creates compliance-based competitive moats.
Resort retail buyers in Thailand and Indonesia now demand shorter replenishment cycles with smaller minimum order quantities. Direct-to-consumer platforms enable domestic Japanese and Australian brands to bypass wholesale intermediaries and capture margin previously allocated to distributor networks. This channel shift concentrates in premium positioning where brand recognition justifies shipping cost absorption.
Asia Pacific Swimwear Market Segmentation
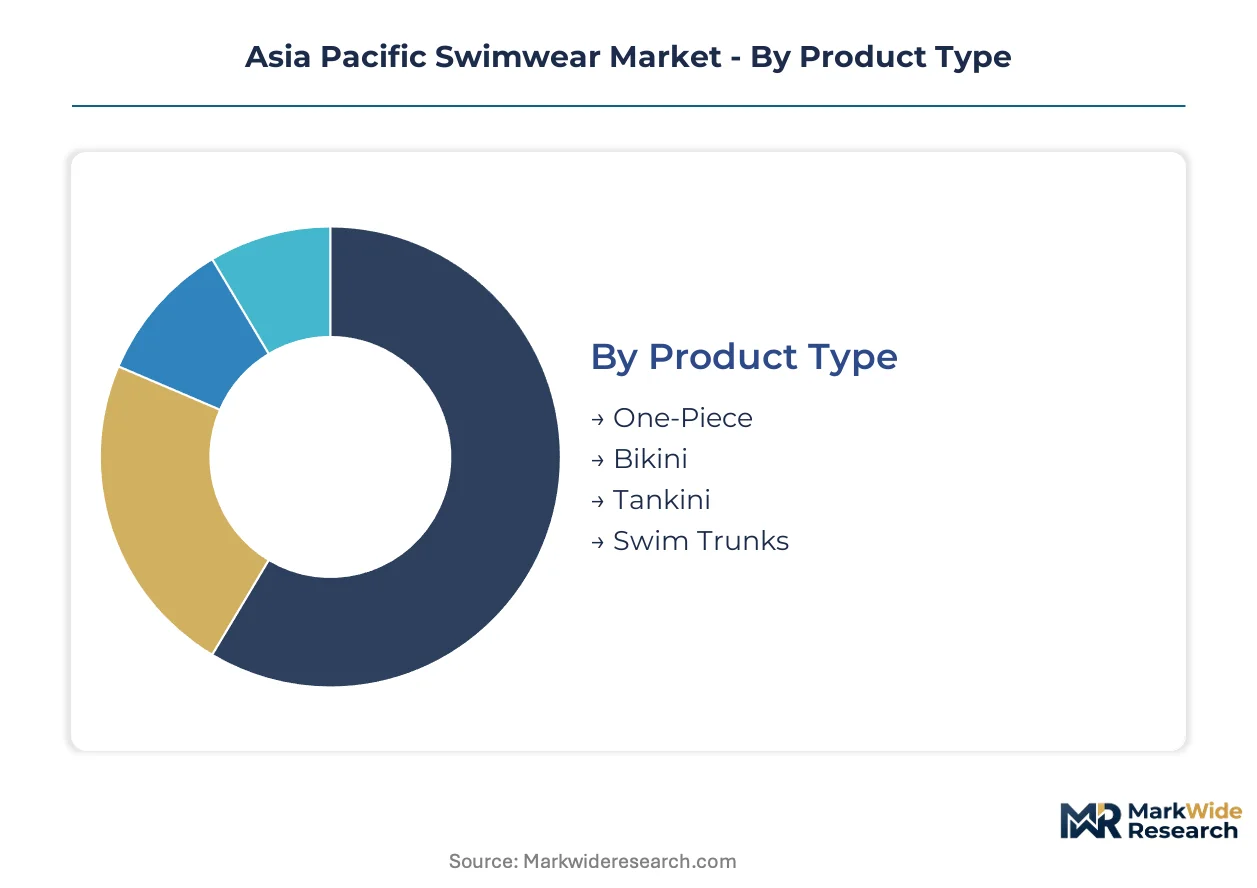
Segmentation in Asia Pacific swimwear reveals divergent technical requirements between recreational beach tourism and institutional competitive aquatics. Product specifications, fabric engineering, and channel economics vary sharply across these use cases, creating distinct margin pools and certification obligations for suppliers.
Product Type:
Competitive swimmers prioritize hydrodynamic compression while resort tourists emphasize aesthetic versatility and coverage options.
- One-Piece:Technical racing suits incorporate bonded seams and compression-grade elastane knits that reduce drag coefficients for competitive swimmers across Australia's training academies. Institutional procurement contracts in Japan and South Korea specify one-piece construction for federation-sanctioned events, locking in recurring volume commitments.
- Bikini:Two-piece configurations dominate Southeast Asian resort retail, where Thai and Indonesian beach destinations drive premium inventory turnover through seasonal tourism cycles. Fashion-positioned lines command higher markups but face compressed design-to-shelf timelines as direct-to-consumer platforms reshape replenishment expectations.
- Tankini:Hybrid coverage appeals to family-oriented beach tourism segments seeking modest alternatives without sacrificing swim functionality.
- Swim Trunks:Men's recreational and competitive boardshorts utilize quick-dry polyester weaves for casual aquatic activity across Australian Gold Coast retail corridors.
One-piece suits anchor institutional procurement volumes; bikini configurations are gaining share fastest through resort retail expansion.
Fabric Type:
Raw material selection determines chlorine resistance, stretch recovery performance, and compliance with Japan's METI textile standards.
- Polyester:Chlorine-resistant synthetic knits with inherent colorfastness properties occupy the largest production share across mass-market lines. India's BIS certification requirements favor polyester blends for formal retail import channels, filtering smaller suppliers unable to document fiber content accuracy.
- Spandex:Elastane blends delivering stretch recovery above 200 percent command premium positioning in performance and racing-grade applications. Japanese and South Korean supplier bases concentrate specialized knowledge in compression patterning for these technical constructions.
- Nylon:Lightweight alternatives with superior drape characteristics serve fashion-positioned resort lines where aesthetic flexibility outweighs durability specifications.
- Lycra:Branded elastane variants maintain defensible margin pools through trademark recognition in premium distribution channels.
Polyester leads absolute production volumes; spandex blends climb fastest as competitive aquatics infrastructure expands.
End User:
Demographic targeting shapes everything from fit engineering complexity to sun protection labeling requirements under Australia's ACCC.
- Women:Specialized fit engineering concentrates in domestic Japanese channels, where Wacoal Holdings dominates performance segment positioning through technical pattern development. Women's lines absorb the majority of UPF 50+ certification investments to satisfy Australian sun protection labeling mandates.
- Men:Competitive swimming programs across Australia generate institutional demand for technical racing suits with hydrodynamic compression specifications. Men's procurement concentrates in team uniform contracts with compressed seasonal variation compared to leisure-oriented segments.
- Children:Rapid growth intervals necessitate lower price points and simplified construction, with safety labeling requirements adding compliance overhead.
- Teens:Fashion-driven purchasing patterns align with social media-influenced trends, shortening product lifecycles and increasing SKU proliferation risks.
Women's segments generate the highest revenue concentration; men's competitive lines show steepest expansion trajectory through institutional procurement growth.
Distribution Channel:
Channel economics determine inventory risk allocation, margin capture, and direct consumer relationship depth.
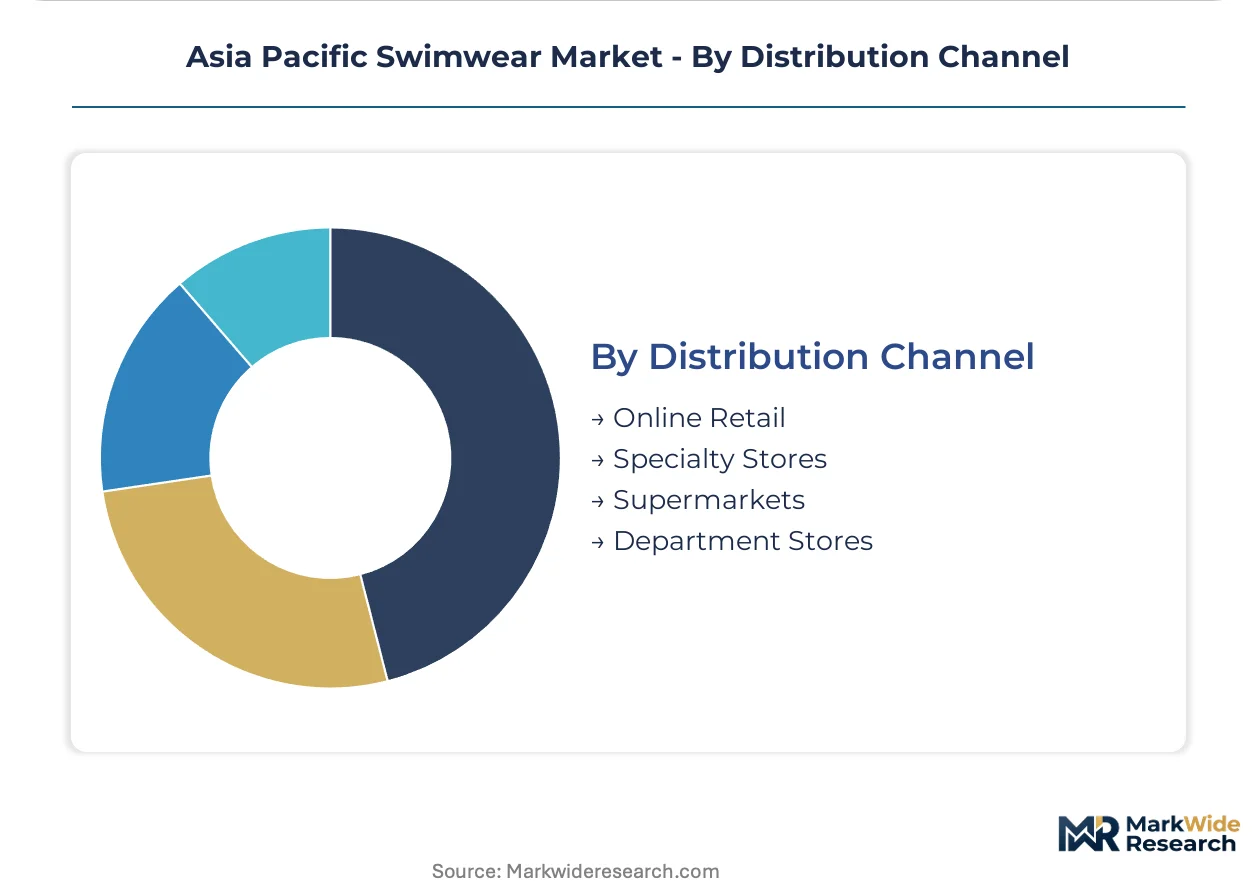
- Online Retail:Direct-to-consumer platforms enable domestic Japanese and Australian brands to bypass wholesale intermediaries and compress inventory cycles through made-to-order production. This channel absorbs shipping cost premiums where brand recognition justifies consumer willingness to pay.
- Specialty Stores:Curated swimwear boutiques in Sydney and Australia's Gold Coast beach retail corridors sustain premium placement and educated sales support for technical product specifications.
- Supermarkets:Mass-market volume concentrates in price-sensitive family purchasing occasions with limited technical differentiation.
- Department Stores:Multi-brand environments in urban Japanese and Australian centers balance discovery browsing with established brand trust signals.
Specialty stores retain margin leadership today; online retail is expanding most quickly as platform infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward Vietnam and Indonesia where labor costs and certification timelines undercut Japanese and Australian manufacturing economics. This regulatory-arbitrage dynamic reshapes supplier qualification across the region.
Australia
Year-round aquatic tourism sustains premium inventory turnover in Sydney and Gold Coast beach retail corridors. The ACCC enforces sun protection labeling mandates that filter uncertified competitors from domestic distribution. Melbourne and Brisbane specialty stores anchor technical racing suit procurement for competitive swimming programs.
Japan
Domestic channels absorb specialized fit engineering investments from women's performance segment leaders. METI textile standards mandate stretch performance testing that elevates certified suppliers above import alternatives. Osaka and Nagoya retail clusters concentrate technical pattern development capabilities.
India
BIS certification requirements for imported textiles create procedural barriers filtering smaller foreign suppliers from formal retail channels. Mandatory fiber content disclosure rules push brands toward certified synthetic blends. Mumbai and Delhi-NCR distribution hubs absorb compliance overhead for mass-market polyester lines.
South Korea
Elite swimming federations specify seamless construction in technical procurement tenders for training academies. National performance standards align with Japanese METI benchmarks for compression-grade specifications. Seoul and Busan manufacturing bases concentrate elastane knit engineering talent.
Vietnam
Resort retail expansion across underpenetrated coastal tourism corridors attracts premium placement from established Australian beach brands. Shorter replenishment cycles with smaller minimum order quantities reshape wholesale expectations. Da Nang and Phu Quoc hospitality corridors drive seasonal inventory commitments.
Asia Pacific Swimwear Market Competitive Environment
Portfolio diversification dominates the current landscape as incumbents extend technical racing heritage into resort retail and direct-to-consumer channels. The vendor base stratifies across three tiers: heritage sports equipment conglomerates with multi-category scale, specialized swimwear houses with compression engineering depth, and regional resort-fashion labels with coastal placement control. Strategic archetypes include technical performance specialists, lifestyle-positioned resort brands, and vertically integrated textile-to-garment operators. Geographic expansion and technology licensing represent the dominant competitive moves as players seek compliance arbitrage across METI, BIS, and ACCC jurisdictions.
Among heritage performance specialists, Arena Italia S.p.A. and TYR Sport Inc. occupy positions defined by elite athlete endorsement and federation procurement relationships. Wacoal Holdings exemplifies the technical fit engineering archetype through domestic Japanese channel dominance. Seafolly Australia anchors the resort-retail vector with coastal brand strength extending into Southeast Asian beach destinations.
| Leading Market Players |
|---|
| Arena Italia S.p.A. |
| Wacoal Holdings |
| Adidas AG |
| TYR Sport Inc. |
| Boardriders |
| Nike Inc. |
| Seafolly Australia |
| Bali Swim Ltd |
| Pentland Group |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap textile specialists concentrated in Japan's Osaka industrial belt anchor premium elastane engineering capacity, translating technical scarcity into sustained pricing power for compression-grade knits while constraining cost-down flexibility for mass-market polyester lines.
Pricing Analysis
Distributor margin layers compress as direct-to-consumer platforms capture share, with three-tier pricing structure across premium, standard, and economy levels stratifying by certification grade and stretch recovery performance. Japan's METI compliance tier commands 15-25 point markups over uncertified alternatives, while Australia's ACCC UPF 50+ verification creates defensible premium positioning. Price erosion runs through mass-market polyester segments as Vietnamese manufacturing scales, though institutional buyers show lowest price sensitivity due to total cost-of-ownership calculations.
Supply Chain Analysis
Dual-sourcing requirements mandated by Australian training academies and Japanese federation procurement contracts force qualification across Japanese, South Korean, and emerging Vietnamese supplier bases. Raw material flows draw from petrochemical feedstocks in South Korea and Thailand, with elastane polymer engineering concentrating in Osaka and Busan manufacturing clusters. Tariff exposure through India's BIS certification timelines creates procedural delays that favor pre-qualified incumbent suppliers. Distribution runs through specialty retail corridors in Sydney and Gold Coast, with direct-to-consumer platforms reshaping downstream economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in elastane blend premiumization and compliance-based vendor consolidation, with seamless knitting technology reducing unit production costs for technical racing lines.
For Market Incumbents: Deepen vertical integration into elastane polymer engineering through captive South Korean or Japanese supplier relationships, defending against Vietnamese cost-based entrants. Reinforce METI and BIS certification portfolios as competitive moats that filter smaller competitors from institutional procurement channels. Prioritize seamless knitting capacity expansion to capture federation-specified tender requirements. For New Entrants and Emerging Players: Specialty resort retailers in Vietnam's Da Nang and Indonesia's Bali corridors represent the most penetrable channel entry point, bypassing established wholesale relationships in mature Australian and Japanese markets. White-space exists in BIS-compliant synthetic blends for India's formal retail expansion. Direct-to-consumer platform launches targeting Southeast Asian coastal tourism enable margin capture without distributor overhead. For Investors and Strategic Acquirers: Valuations sit cheapest among Vietnamese manufacturing specialists with Australian brand licensing relationships, offering compliance arbitrage upside. Long-term viability frames around technical textile engineering talent scarcity concentrating in Japanese and South Korean supplier bases. Acquisition target archetypes include seamless knitting technology holders and BIS-certified polyester blend specialists. Watch India's enforcement intensity against uncertified imports as inflection signal for compliance-premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Seamless Knitting Technology Investment | Captures federation procurement specifications across Australian and South Korean training academies. |
| BIS Certification Compliance Program | Unlocks formal retail channels in India's Mumbai and Delhi-NCR distribution hubs. |
| Direct-to-Consumer Platform Launch | Bypasses wholesale margin layers in premium Japanese and Australian domestic channels. |
| Resort Retail Expansion | Secures premium placement in Vietnam's underpenetrated Da Nang and Phu Quoc corridors. |
| Elastane Blend Engineering Partnership | Accesses Osaka and Busan technical talent pools for compression-grade specifications. |
Study Parameters
Coverage spans Australia, Japan, India, South Korea, Vietnam, and Indonesia, with primary inputs from each market's competitive swimming federation procurement officers, specialty retail buyers in Sydney and Gold Coast, textile plant managers in Osaka and Busan, and brand marketing directors at regional headquarters. Secondary validation draws from BIS certification registries, METI textile standard filings, ACCC consumer protection databases, and customs trade records for elastane and polyester imports. Bottom-up channel volume estimates triangulate against top-down apparel market sizing.
Rate-of-change decomposition separates volume expansion from value premiumization across the analysis window, modeling product type, fabric grade, end-user demographic, and distribution channel dimensions. CAGRs derive from trend extrapolation of institutional procurement contract values, resort retail inventory turns, and direct-to-consumer platform growth trajectories. Forecast inputs incorporate elastane feedstock cost indices, coastal tourism arrival patterns, and regulatory enforcement intensity variations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to India's BIS enforcement consistency and petrochemical input volatility. Deviation in seamless knitting technology adoption rates among Australian and South Korean federations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Europe Headwear Market
Apparel & Footwear
Chest Bags Market
Apparel & Footwear
Touchscreen Gloves Market
Apparel & Footwear
Sports Apparel Embellishment Market
Apparel & Footwear
Ballet Pointe Shoes Market
Apparel & Footwear
North America Jeans Market
Apparel & Footwear
Fitness Apparel Market
Apparel & Footwear
Australia Denim Jeans Market
Apparel & Footwear
Mister Cap Market
Apparel & Footwear
Streetwear Market
Apparel & Footwear
Southeast Asia Lingerie Market
Apparel & Footwear
Luxury Vegan Men's Fashion Market
Apparel & Footwear
Smart Wardrobe Market
Apparel & Footwear
Men Shirts Market
Apparel & Footwear
Compression and Shapewear Market
Apparel & Footwear
Europe Jeans Market