
 North America E-Commerce Apparel Market | 2026-2036
North America E-Commerce Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
North America E-Commerce Apparel Market Insights
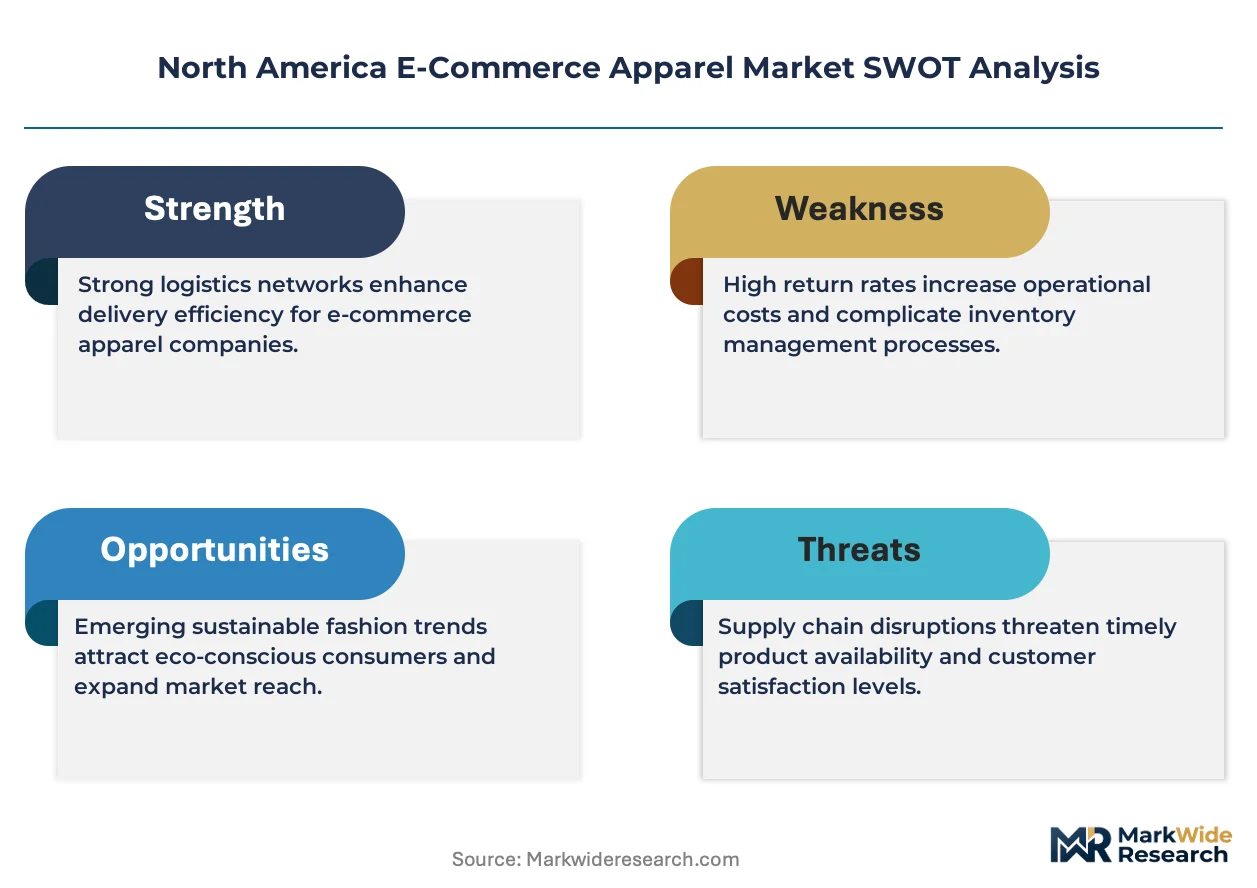
AI-powered size recommendation engines and virtual try-on tools is reconfiguring how apparel retailers reduce return rates and improve conversion funnels. Amazon Fashion leverages its proprietary logistics infrastructure to control last-mile delivery economics across the United States and Canada. Walmart anchors its position through backward integration into fulfillment centers positioned within miles of major population clusters. Lululemon differentiates through community-driven digital engagement that bridges online browsing with in-store appointment scheduling.
The North America E-Commerce Apparel sector encompasses digitally transacted garments spanning woven and knit constructions, with cotton, polyester, and regenerated cellulose fibers constituting the dominant material base; these products serve consumer wardrobes through direct-to-consumer platforms and third-party marketplaces, replacing traditional brick-and-mortar discovery with algorithmic personalization and on-demand inventory visibility. Shirts and outerwear command the largest revenue pools within product type segmentation, though dresses exhibit faster velocity among mobile-first purchasers. Brand websites capture premium margin retention, while marketplaces dominate volume throughput by aggregating comparison shoppers across price tiers.
The FTC's Textile Fiber Products Identification Act and California's Transparency in Supply Chains Act impose disclosure mandates that filter out non-compliant sellers from major platform access. The EPA's emerging frameworks around textile waste and chemical management in dyeing processes will tighten operational standards for fulfillment-dependent retailers. Stakeholders must monitor how state-level extended producer responsibility proposals reshape inventory planning and reverse logistics investment priorities.
Market Dynamics
Algorithmic personalization engines and same-day fulfillment infrastructure are compressing the traditional seasonal inventory cycle, forcing retailers to abandon quarterly buying patterns in favor of continuous replenishment systems calibrated to real-time demand signals.
Growth Catalysts
- California's SB 657 Transparency Mandate:Supply chain disclosure requirements are filtering out non-compliant sellers from major platform access, concentrating volume among verified vendors with documented labor practices.
- Sportswear End-Use Acceleration:Athleisure demand across the United States and Canada is expanding addressable market boundaries beyond traditional occasion-based apparel categories.
- Metropolitan Fulfillment Density:Texas, California, and New York distribution clusters are anchoring same-day delivery expectations that drive repeat purchase behavior and basket size expansion.
Market Restraints
- Polyester Feedstock Volatility:Petrochemical input cost swings compress margin predictability for mid-market synthetic apparel lines dependent on stable material pricing.
- Cross-Border Customs Friction:United States-Mexico-Canada Agreement compliance complexity adds processing overhead to nearshored manufacturing strategies.
- FTC Textile Labeling Enforcement:Fiber content verification requirements create compliance drag for marketplace sellers sourcing from fragmented supplier bases.
Strategic Opportunities
- Canadian Market Underpenetration:Digital apparel adoption lags south-of-border benchmarks, creating whitespace for platform expansion and localized fulfillment investment.
- Extended Producer Responsibility Tailwinds:State-level textile waste frameworks in California and New York are mandating reverse logistics infrastructure that first-movers can monetize.
- AI-Virtual Try-On Convergence:Computer vision and generative rendering technologies are collapsing the fit uncertainty barrier that historically suppressed online apparel conversion rates.
Industry Challenges
- Size Algorithm Training Data Scarcity:Apparel brands lack sufficient body-scan datasets to calibrate recommendation engines across diverse demographic segments.
- Legacy Warehouse Management Integration:Continuous replenishment systems require real-time inventory visibility that conflicts with batch-updated enterprise resource planning architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America E-Commerce Apparel Market |
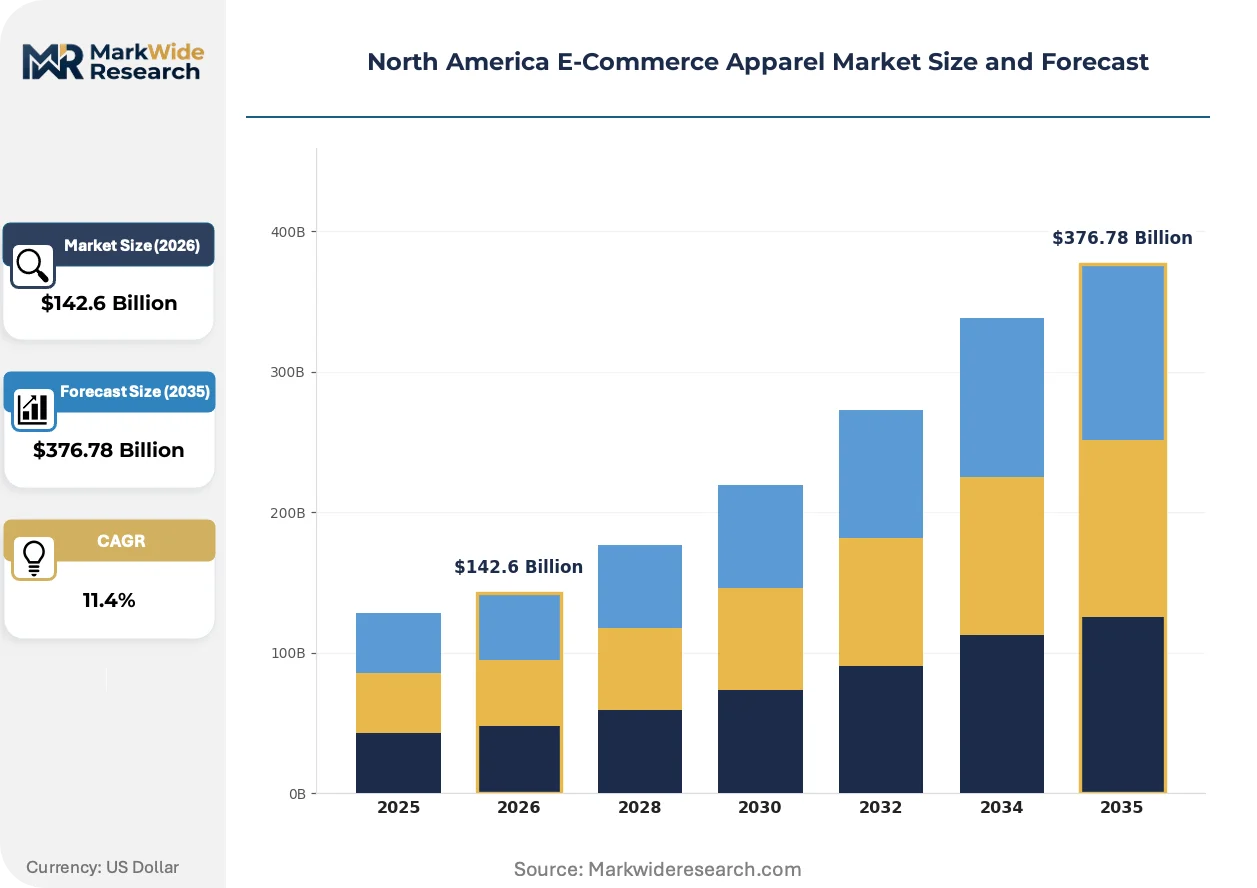
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $376.78 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shirts, Pants, Dresses, Outerwear End User: Men, Women, Kids, Sportswear Enthusiasts Distribution Channel: Brand Websites, Marketplaces, Social Media, Mobile Apps Price Tier: Luxury, Mid-range, Discount, Fast Fashion |
| Companies Covered | Amazon Fashion, Walmart, Ralph Lauren Corporation, VF Corporation, Inditex, PVH Corp, Fast Retailing, Hennes & Mauritz, Lululemon, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America E-Commerce Apparel Market Trends and Innovations
Generative artificial intelligence and circular economy mandates are simultaneously reconfiguring how apparel is designed, produced, and recovered, collapsing the traditional linear value chain into closed-loop systems that reward data-rich operators.
Virtual try-on technology powered by three-dimensional body modeling is rendering obsolete the fitting-room-dependent purchase journey that historically constrained online apparel penetration. Mobile-first purchasers in the dresses and activewear categories are adopting these tools at the fastest clip, compressing return rates and enabling brands to reduce safety stock buffers previously maintained to cover size-related exchanges.
California's Transparency in Supply Chains Act enforcement expansion is compelling platform sellers to document tier-two and tier-three supplier relationships or face delisting from major marketplace access. The FTC's parallel emphasis on substantiated environmental claims is squeezing greenwashing practices from product descriptions, with regenerated cellulose fiber categories facing the most intensive documentation scrutiny as brands scramble to verify closed-loop chemical recovery claims.
Subscription-based wardrobe rotation services are displacing ownership models among urban millennial and Gen Z cohorts, particularly in metropolitan corridors where storage constraints and sustainability preferences intersect. Rental platforms and peer-to-peer resale channels are capturing garment utilization hours that previously accumulated in closet inventory, forcing traditional retailers to develop trade-in and refurbishment capabilities or cede customer lifetime value to circular specialists operating in New York, Los Angeles, and Toronto density zones.
North America E-Commerce Apparel Market Segmentation
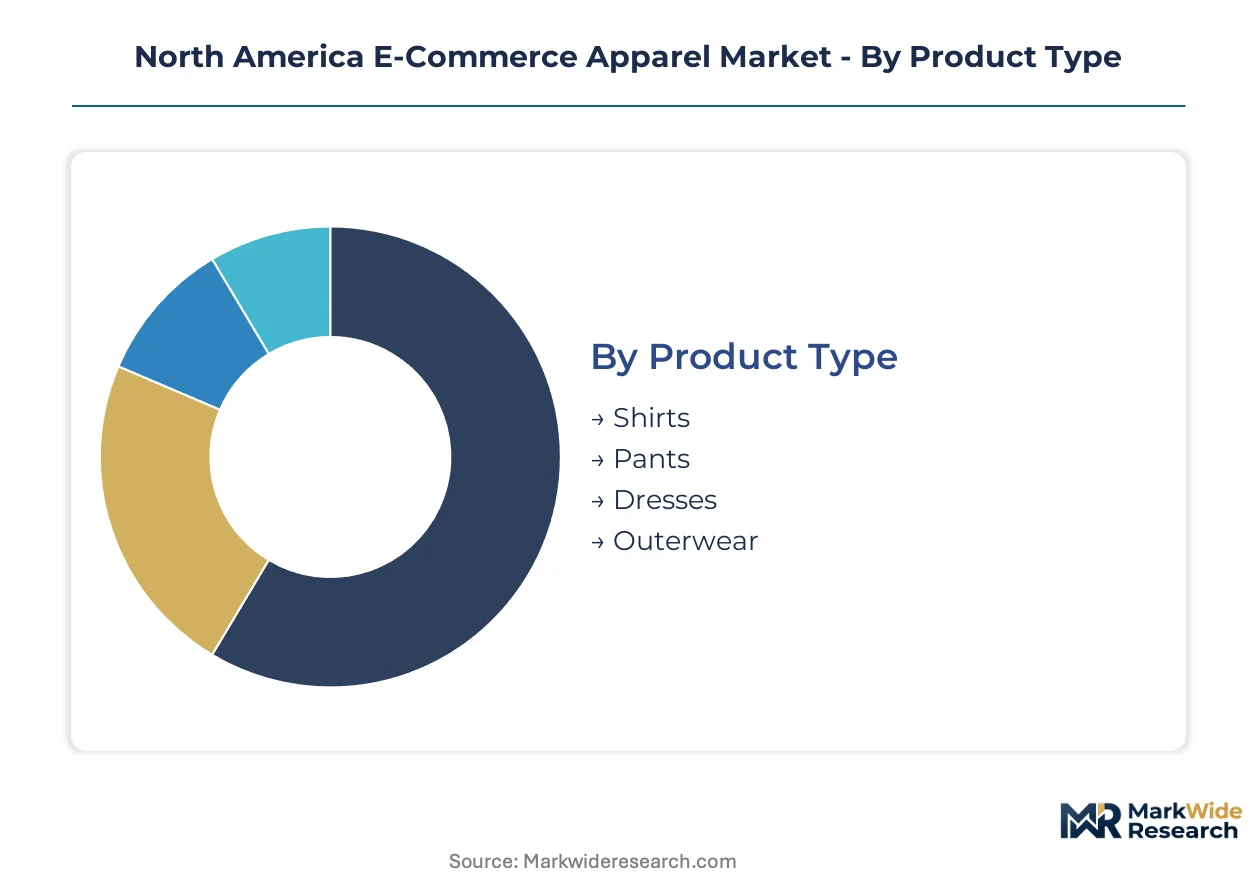
Segmentation in North American e-commerce apparel reveals how inventory velocity, margin structure, and channel economics diverge across product and customer dimensions. Understanding these fault lines allows retailers to calibrate fulfillment infrastructure and marketing spend against actual purchase behavior rather than aggregated demand assumptions.
Product Type:
Shirts and outerwear operate on extended replenishment cycles with lower return rates, while dresses and pants turn faster but generate higher size-related exchange volumes that strain reverse logistics networks.
- Shirts:Cotton-poplin and performance-knit constructions dominate this category, with casual button-downs and graphic tees capturing the highest mobile conversion rates. Demand concentrates in Texas and California metropolitan zones where same-day delivery expectations have compressed the traditional weekly restock cycle into daily replenishment from regional fulfillment nodes.
- Outerwear:Insulated jackets and technical shells carry the highest average order values in the apparel matrix, though seasonal concentration creates acute working capital pressure during Q3 inventory build. Canadian markets show pronounced underpenetration relative to United States benchmarks, creating whitespace for thermal-weight specialization.
- Pants:Denim and chino categories face persistent fit uncertainty that elevates return processing costs above the category mean.
- Dresses:Occasion-wear and day-dress segments exhibit the steepest mobile-first purchase velocity, particularly among urban millennial cohorts in New York and Los Angeles density corridors.
Shirts anchor the volume base while dresses gain share at the steepest rate.
End User:
Cost tier differentiation separates premium positioning strategies from volume-driven discount plays across gender and age cohorts.
- Men:Simplified size matrices and lower return propensity make this segment the most profitable for automated fulfillment systems, with casual workwear and athleisure hybrids driving basket expansion in United States suburban markets.
- Sportswear Enthusiasts:Technical fabric demand and community-driven discovery patterns are expanding addressable market boundaries beyond traditional occasion-based categories across both United States and Canadian jurisdictions.
- Women:Higher browsing intensity and size-variation sensitivity elevate customer acquisition costs relative to male counterparts.
- Kids:Rapid size-turnover creates subscription-friendly purchase patterns with strong parental loyalty stickiness.
Women's segment captures the largest revenue pool while sportswear enthusiasts climb the fastest.
Distribution Channel:
Customer acquisition economics vary dramatically by discovery mechanism, with algorithmic channels extracting margin through platform fees that brand-direct sites avoid.
- Brand Websites:Proprietary data capture and margin retention define this channel, with Lululemon-style community integration bridging digital browsing with physical appointment scheduling. United States-based direct-to-consumer operators invest heavily in first-party data infrastructure to reduce dependency on paid acquisition.
- Marketplaces:Amazon Fashion's logistics control and Walmart's backward integration into fulfillment centers position these platforms to dominate volume throughput by aggregating price-comparison shoppers.
- Social Media:Influencer-driven discovery converts at lower rates but generates higher lifetime value through community affiliation effects.
- Mobile Apps:Push-notification re-engagement and streamlined checkout reduce cart abandonment versus mobile web experiences.
Marketplaces dominate transaction volume while brand websites expand margin capture most aggressively.
Price Tier:
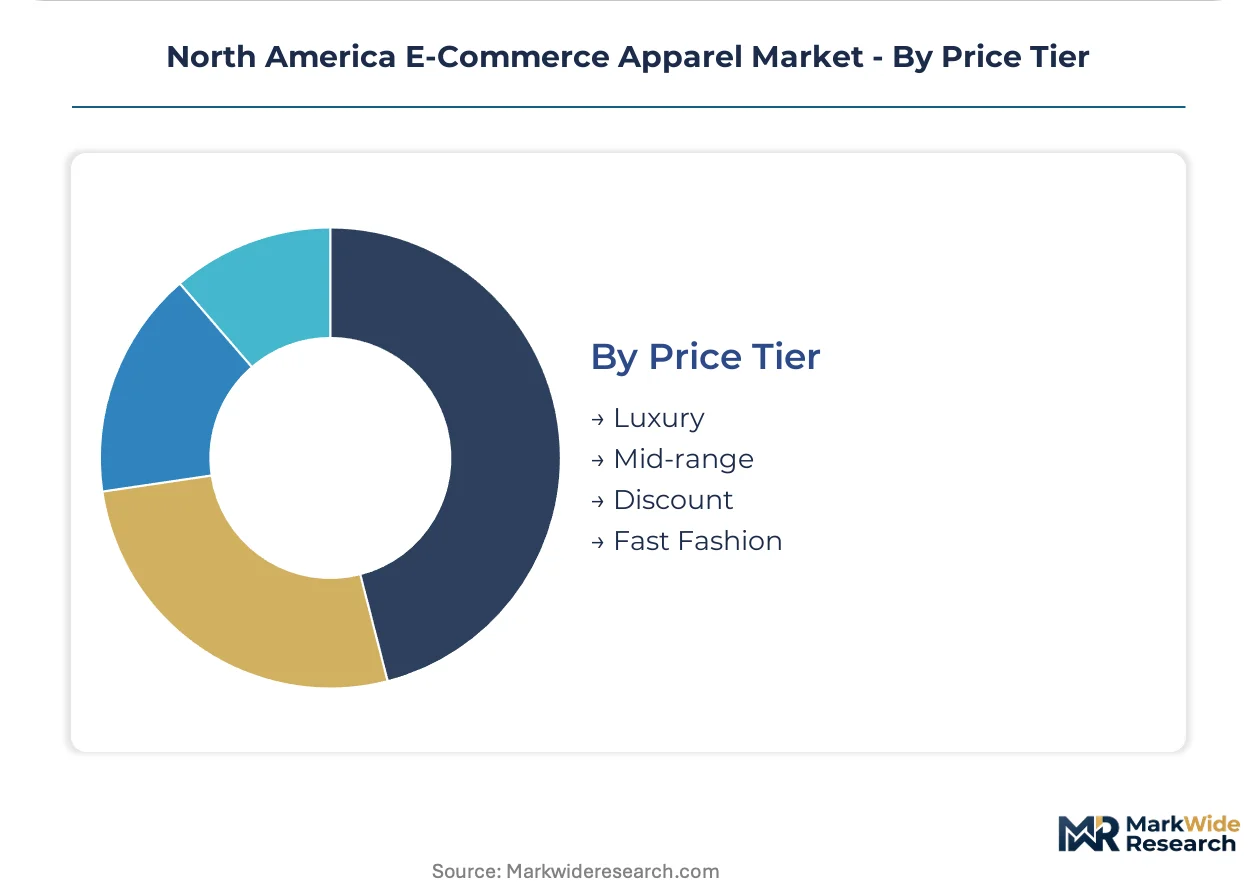
Maturity gradients separate established luxury positioning from fast-fashion's velocity-driven model, with mid-range operators caught between margin pressure and brand equity investment requirements.
- Luxury:Authentication services and white-glove delivery justify premium positioning, with resale platform integration extending garment lifecycle value. California's SB 657 disclosure mandates filter non-compliant sellers from this tier's platform access, concentrating volume among verified vendors.
- Fast Fashion:Shein-style ultra-rapid response systems compress design-to-door timelines below traditional seasonal cycles, though EPA-emerging textile waste frameworks threaten operational economics.
- Mid-range:J.Crew and Banana Republic heritage operators face margin compression from both luxury aspiration and discount accessibility.
- Discount:Off-price digital channels capture clearance inventory that would otherwise strain primary brand positioning.
Fast fashion commands transaction velocity while luxury deepens customer lifetime value most effectively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian apparel exporters supply United States digital channels through integrated cross-border fulfillment corridors, while Mexican nearshoring operations feed Texas and California distribution nodes with compressed lead times.
United States
Metropolitan fulfillment clusters in Texas, California, and New York anchor same-day delivery infrastructure that drives repeat purchase behavior. The FTC enforces textile fiber labeling rules that filter non-compliant marketplace sellers from platform access. Los Angeles and New York density corridors concentrate virtual try-on technology deployment and mobile-first dress category velocity.
Canada
Digital apparel adoption trails United States benchmarks, creating whitespace for platform expansion and localized fulfillment investment. Health Canada coordinates with the EPA on emerging textile chemical management frameworks that affect cross-border inventory flows. Toronto and Vancouver anchor distribution networks serving underpenetrated sportswear enthusiast segments.
Mexico
Nearshored manufacturing strategies supply United States e-commerce channels through compressed design-to-door timelines. United States-Mexico-Canada Agreement compliance complexity adds customs processing overhead to border-crossing operations. Nuevo León and Baja California concentration zones feed Texas fulfillment nodes with activewear and casual apparel production.
North America E-Commerce Apparel Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a bifurcated structure where logistics scale separates volume leaders from margin-focused operators. The market exhibits tiered concentration with platform aggregators, heritage brand direct-to-consumer operators, and fast-fashion velocity specialists occupying distinct competitive zones. Dominant strategic moves include backward integration into captive fulfillment networks and algorithmic personalization infrastructure deployment.
Among platform-scale operators, Amazon Fashion and Walmart exemplify logistics-controlled channel archetypes, while Lululemon occupies a position within the community-integrated specialist tier. These three companies represent contrasting competitive vectors: Amazon Fashion anchors proprietary last-mile infrastructure, Walmart leverages backward integration into population-proximate fulfillment centers, and Lululemon bridges digital engagement with physical appointment scheduling. Each sits within a distinct margin-capture model—volume aggregation versus premium community retention—reflecting the sector's structural segmentation between throughput dominance and customer lifetime value depth.
| Leading Market Players |
|---|
| Amazon Fashion |
| Walmart |
| Ralph Lauren Corporation |
| VF Corporation |
| Inditex |
| PVH Corp |
| Fast Retailing |
| Hennes & Mauritz |
| Lululemon |
| Others |
Pricing and Supply Chain Analysis
California-Texas freight corridors anchor cost dynamics that concentrate supply among operators with population-proximate fulfillment nodes, compressing price differentiation between premium and discount tiers as last-mile efficiency becomes the dominant margin lever.
Pricing Analysis
Legacy warehouse management systems versus AI-enabled continuous replenishment versus generative design-to-shelf platforms define a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on fulfillment speed certification and virtual try-on integration depth, with California's SB 657 compliance costs accelerating margin compression in the mid-market. Cost compression in synthetic apparel lines intensifies because petrochemical feedstock volatility transmits directly to landed costs. Fast-fashion purchasers exhibit highest price sensitivity while luxury authentication-service buyers demonstrate lowest elasticity.
Supply Chain Analysis
Petrochemical derivatives and cotton futures and regenerated cellulose pulp constitute upstream dependencies that expose North American e-commerce apparel to commodity price swings. Manufacturing concentrates in Vietnam, Bangladesh, and Mexico, with nearshored Mexican operations feeding Texas distribution nodes through United States-Mexico-Canada Agreement corridors. Single-source vulnerability in synthetic fiber supply creates exposure to energy cost shocks. Distribution runs through captive fulfillment networks controlled by platform-scale operators and third-party logistics aggregators serving brand-direct channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algorithmic personalization and virtual try-on convergence constitute a technological inflection that rewards data-rich operators while filtering out legacy inventory planners.
For Market Incumbents: Entrench position through backward integration into metropolitan fulfillment centers within ten miles of major population clusters, countering Amazon Fashion's proprietary last-mile infrastructure advantage. Invest in first-party body-scan datasets to calibrate size recommendation engines across diverse demographic segments, addressing the algorithm training data scarcity that constrains conversion rate optimization. Prioritize California SB 657 tier-two supplier documentation to maintain platform access as transparency enforcement tightens. For New Entrants and Emerging Players: Pursue Canadian market whitespace where digital apparel adoption trails United States benchmarks, particularly in sportswear enthusiast segments concentrated around Toronto and Vancouver density zones. Target extended producer responsibility infrastructure mandates in California and New York as first-mover monetization opportunities in reverse logistics. Deploy mobile-native virtual try-on as the primary go-to-market wedge to collapse fit uncertainty barriers that suppress online apparel conversion. For Investors and Strategic Acquirers: Carve-out targets emerge from heritage mid-range operators caught between luxury aspiration and discount accessibility, with J.Crew-archetype brands possessing customer databases but lacking fulfillment modernization. Long-term viability over the next decade hinges on AI-virtual try-on convergence adoption velocity and circular economy infrastructure deployment. Monitor state-level textile waste framework implementation timelines as the signal indicating when reverse logistics capabilities transition from cost center to profit engine.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Size Recommendation Deployment | Lululemon-style community data capture reduces return rates and compresses safety stock requirements. |
| Metropolitan Fulfillment Center Expansion | Walmart's backward integration into population-proximate nodes anchors same-day delivery economics. |
| Virtual Try-On Technology Integration | Computer vision adoption in New York and Los Angeles corridors collapses fit uncertainty barriers. |
| Supply Chain Transparency Certification | California SB 657 tier-three documentation filters non-compliant sellers from Amazon Fashion access. |
| Circular Economy Infrastructure Buildout | Extended producer responsibility mandates in California monetize reverse logistics for first-movers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with e-commerce platform executives, apparel brand supply chain directors, third-party logistics operators, and FTC regulatory affairs specialists. Secondary validation drew from United States Census Bureau trade data, EPA textile waste framework disclosures, California Department of Justice SB 657 enforcement records, and SEC 10-K filings from publicly traded apparel retailers. Bottom-up SKU-level demand modeling and top-down macroeconomic consumption trend analysis were triangulated to ensure convergence.
Calibration against historical fulfillment cost trajectories and virtual try-on adoption curves anchored projections across the analysis window. Segmentation dimensions modeled include product type, end-user demographic, distribution channel architecture, and price tier positioning. CAGRs were derived from trend-line extrapolation adjusted for regulatory inflection points and technology S-curve penetration rates. Polyester feedstock volatility indices and same-day delivery coverage expansion timelines served as industry-specific forecast inputs.
Sensitivities concentrate around EPA textile waste rule finalization timing and United States-Mexico-Canada Agreement customs processing friction evolution. Forecasts reflect assumptions regarding algorithmic personalization adoption velocity and metropolitan fulfillment density expansion. Cross-checking against Nielsen retail audit data and customs import volume statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Sports Inspired Clothing Market
Apparel & Footwear
School Shoes Market
Apparel & Footwear
Women's Night and Underwear Market
Apparel & Footwear
Golf Outfit Market
Apparel & Footwear
Maternity Apparels Market
Apparel & Footwear
Outdoor Sports Apparel Market
Apparel & Footwear
Ice Hockey Apparel Market
Apparel & Footwear
Men Jeans Market
Apparel & Footwear
Global Swimwear (Swimsuit) Market
Apparel & Footwear
Global Apparel and Footwear Market
Apparel & Footwear
Tennis (Apparel and Footwear) and Golf (Apparel and Footwear) Market
Apparel & Footwear
Sleepwear Market
Apparel & Footwear
Bra Market
Apparel & Footwear
Ethnic Wear Market
Apparel & Footwear
Women's Trousers Market
Apparel & Footwear
Body Shaper Market