
 Premium Denim Jeans Market | 2026-2036
Premium Denim Jeans Market Size, Share, and Industry Trends Forecast 2026-2036
Premium Denim Jeans Market Intelligence
Younger professional women are redrawing demand patterns in premium denim, shifting volume from traditional department stores toward direct-to-consumer platforms and specialty boutiques. Levi Strauss & Co. leverages its heritage archive and wholesale reform strategy to sustain pricing power across North American and European doors. Kaihara anchors Japanese selvedge supply through proprietary rope-dyeing capacity that commands premium placement in artisanal collections. Arvind Limited dominates South Asian manufacturing scale while competing on sustainable waterless finishing technologies that attract ESG-conscious Western brands.
Premium denim jeans denote trousers constructed from twill-woven cotton denim with warp-faced indigo dyeing, typically weighing 12–16 oz per square yard, engineered for durability, aesthetic aging, and elevated fit precision in fashion and casual apparel. Selvedge fabric occupies the highest margin tier due to narrow-loom heritage construction and scarcity positioning, while stretch denim blends with elastane capture expanding share among women seeking comfort without silhouette compromise. Organic cotton sourcing is accelerating fastest among sustainability-driven brands, though raw denim maintains cult status in Japanese and Italian maker communities.
REACH and the EU Green Deal impose chemical disclosure and circularity obligations on European-sold denim, while EPA wastewater standards constrain North American finishing operations. Japan's METI promotes textile innovation through JIS quality benchmarks that reinforce domestic premium positioning. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to absorb compliance costs or redirect sourcing toward jurisdictions with lighter regulatory burden.
Market Dynamics
REACH chemical disclosure mandates and EU Green Deal circularity obligations are forcing material substitutions across premium denim supply chains, compressing lead times for organic fiber certification while elevating compliance costs for European-bound production.
Growth Catalysts
- REACH and EU Green Deal mandates:Chemical restriction frameworks compel brands toward organic cotton and recycled fiber blends, creating certified premium tier differentiation that commands shelf space in European specialty retail.
- Direct-to-consumer channel acceleration:Millennial and Gen Z purchase frequency through brand-owned digital platforms reduces wholesale margin dilution and captures first-party consumer data for fit personalization.
- Japanese selvedge heritage positioning:Kaihara's proprietary rope-dyeing capacity and Okayama manufacturing cluster scarcity reinforce artisanal pricing power in United States and Italian boutique doors.
Market Restraints
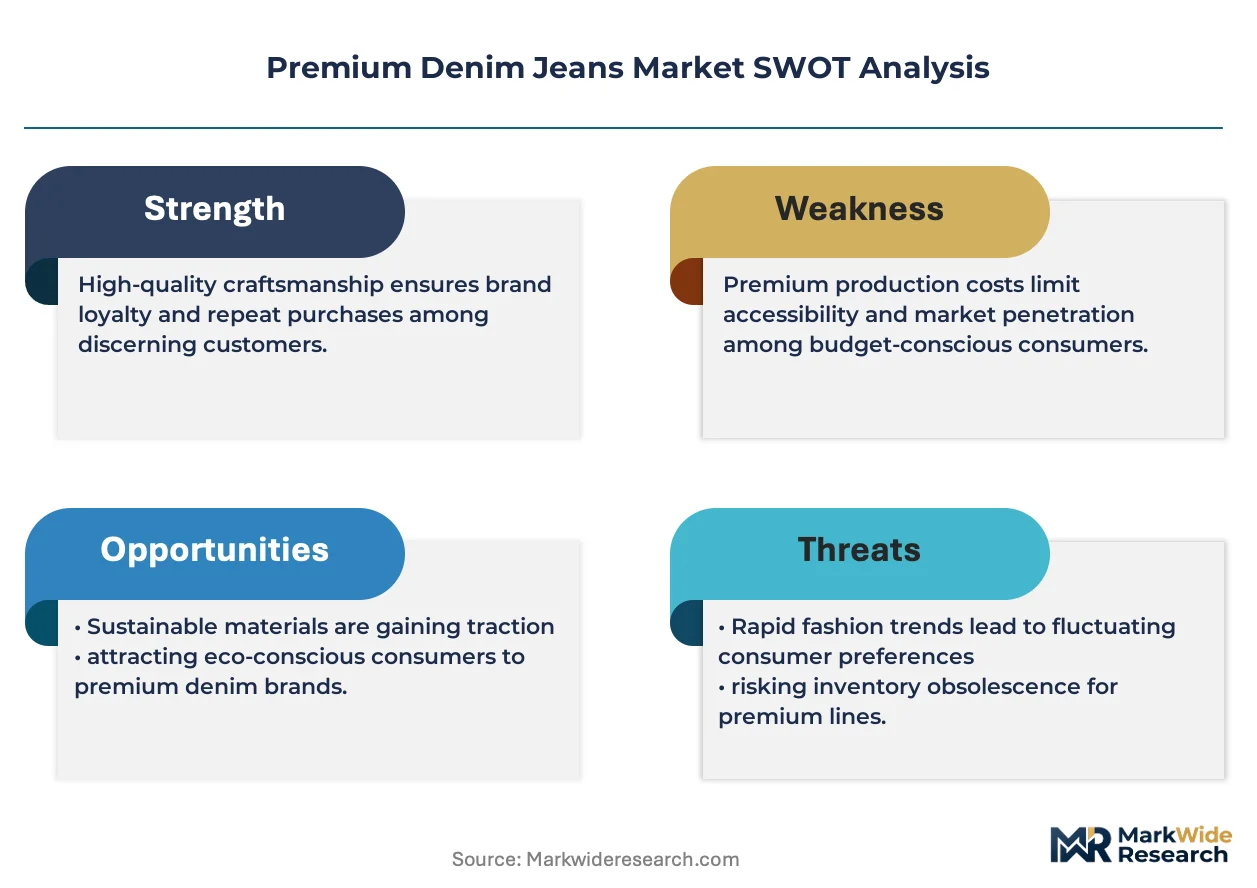
- Organic cotton input cost volatility:Weather-dependent yield fluctuations and certified acreage constraints elevate raw material premiums versus conventional fiber, compressing gross margins at entry-premium price points.
- South Asian supply concentration:Arvind Limited and comparable integrated mills dominate waterless finishing scale, creating bottleneck risk for Western brands seeking ESG-compliant volume commitments.
- Stretch denim technical ceiling:Elastane blend degradation through repeated laundering limits product lifespan claims, constraining warranty positioning against raw selvedge alternatives.
Strategic Opportunities
- Underpenetrated Japanese domestic DTC:Heritage brands capture limited share of domestic online premium denim purchases, leaving white space for localized fit algorithms and same-day alteration services.
- Extended producer responsibility tailwinds:EU textile circularity frameworks incentivize take-back program infrastructure, enabling subscription-rental hybrid models with residual value capture.
- Laser finishing convergence with AI patterning:Computer-vision-guided distressing automation reduces water-intensive manual processes while accelerating style-cycle responsiveness for trend-driven collections.
Industry Challenges
- Rope-dyeing master craftsman scarcity:Narrow-loom selvedge production depends on retiring artisan expertise, constraining capacity expansion for heritage-tier Japanese and Italian mills.
- Multi-jurisdiction certification timeline compression:Simultaneous GOTS organic, OEKO-TEX, and EU PEF tracking demands dedicated compliance personnel that mid-tier brands struggle to retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Premium Denim Jeans Market |
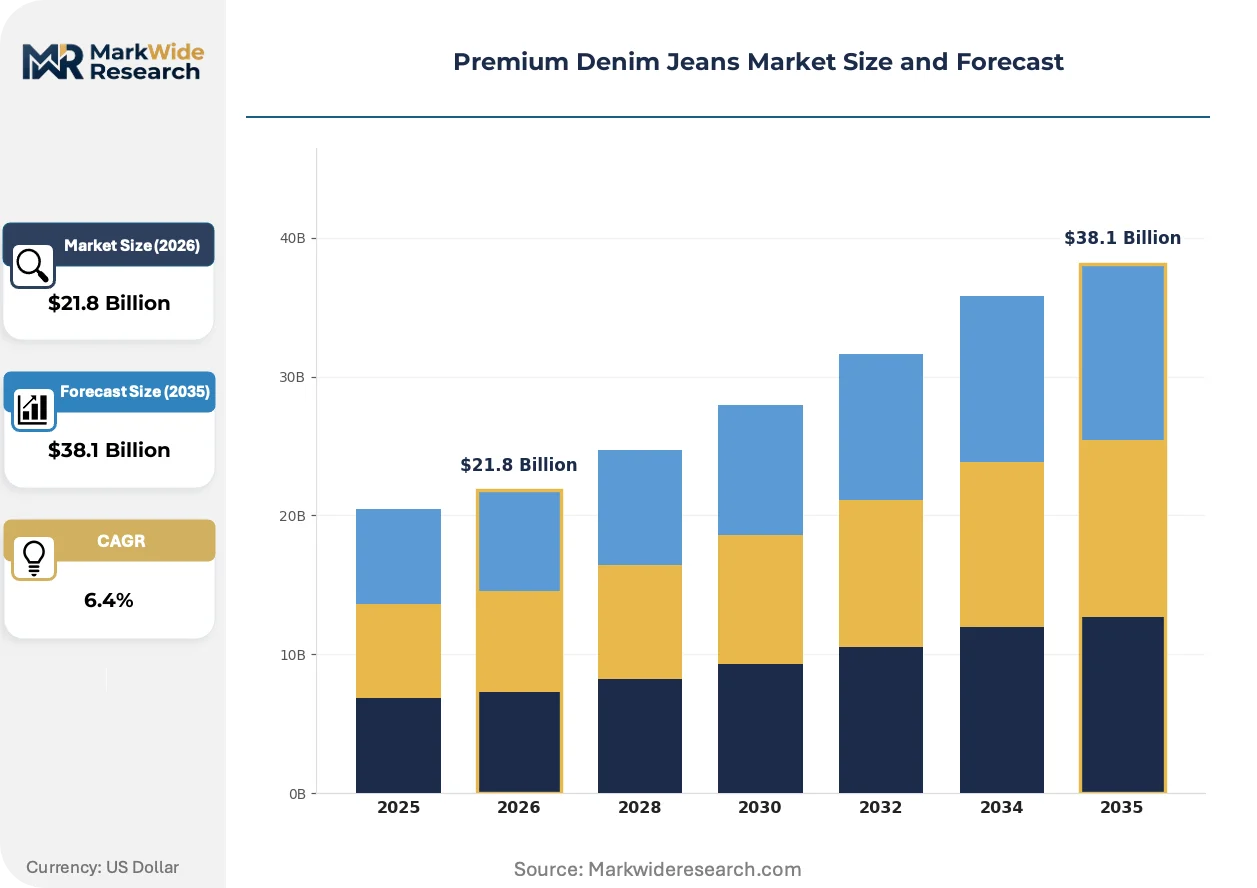
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $38.1 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skinny, Bootcut, Straight Leg, Wide Leg Fabric Type: Organic Cotton, Stretch Denim, Selvedge, Raw Denim Customer Type: Men, Women, Children, Unisex Price Tier: Luxury, Mid-Range, Affordable, Discounted |
| Companies Covered | ISKO, Kaihara, Levi Strauss & Co., Blue Age Denim, Grupo Denim, Diesel, Arvind Limited, Steve Apparel, Wrangler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Premium Denim Jeans Market Strategic Shifts & Innovations
Laser-based finishing systems and AI-driven pattern recognition are compressing traditional wet-processing timelines while enabling micro-batch responsiveness. Three developments are restructuring competitive capability requirements.
Laser distressing technology employs concentrated CO2 beams to abrade indigo surfaces without potassium permanganate sprays or stone washing. Premium women's lines targeting comfort-stretch silhouettes are adopting this equipment fastest to meet 48-hour sample turnaround demands. Manual wet-finishing labor is supplanting capital-intensive automation in facilities serving fast-fashion adjacent price tiers.
REACH Annex XVII restrictions on azo dyes and chromium-tanned leather patches impose reformulation deadlines on European-sold denim collections. Brands must submit SCIP database entries for articles containing SVHCs above threshold concentrations, elevating traceability system investments. Italian heritage manufacturers with vertically controlled chemical management are capturing displaced volume from suppliers lacking disclosure infrastructure.
Specialty boutique buyers are consolidating purchase authority into fewer direct relationships, bypassing traditional showroom intermediaries. United States coastal metropolitan markets exhibit this concentration most acutely, with multi-brand curators demanding exclusive colorway allocations and accelerated replenishment terms. Regional wholesale agents are losing placement influence to brand-owned field teams with localized inventory visibility.
Premium Denim Jeans Market Segmentation
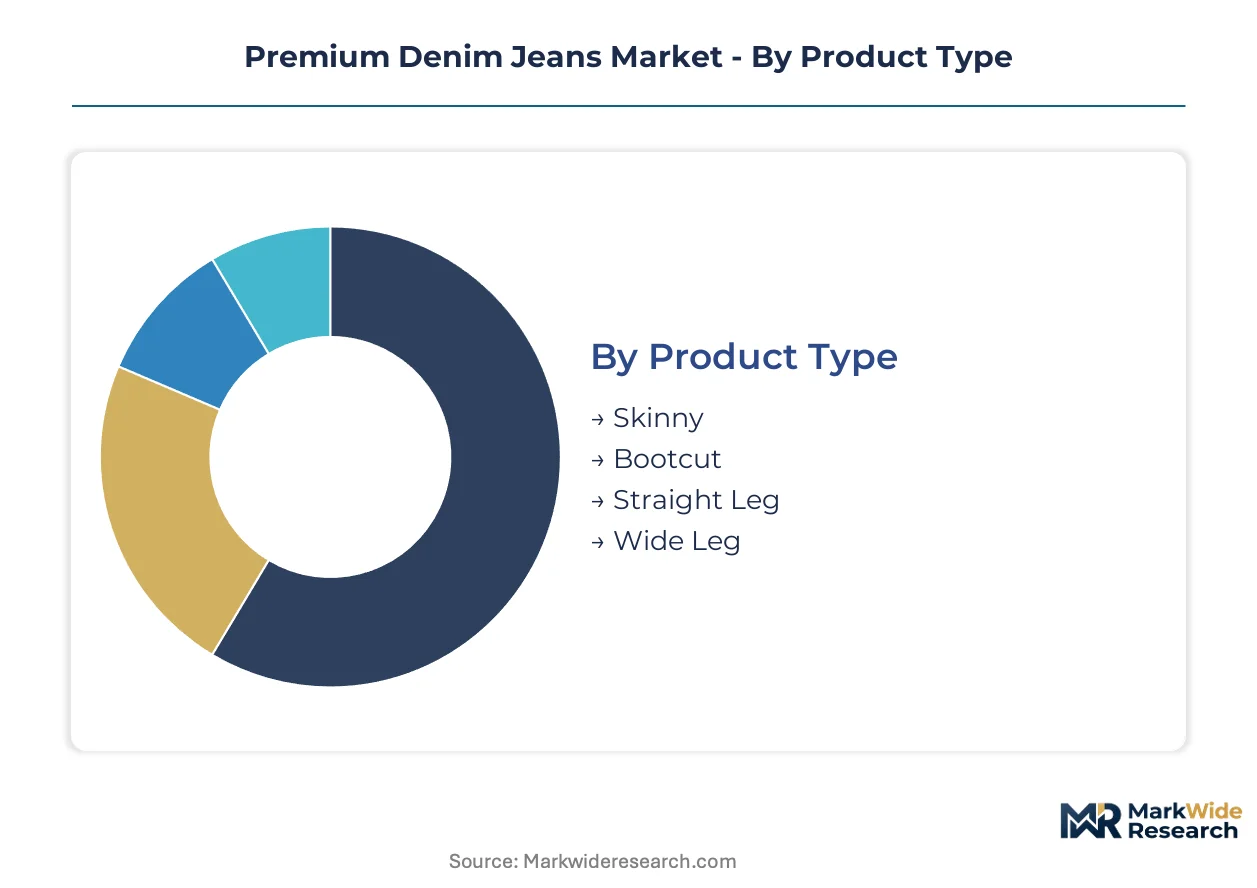
Premium denim segmentation determines channel strategy and margin architecture. Product and fabric categories command distinct placement in specialty retail versus direct-to-consumer platforms, while price tiers filter access to heritage manufacturing provenance.
Product Type:
Channel placement varies sharply by silhouette, with skinny and straight leg dominating digital-first distribution while wide leg captures boutique floor space.
- Skinny:Form-fitting leg taper from hip to ankle, typically constructed with elastane blends for recovery. Demand concentrates among women aged 25-34 in United States metropolitan markets, driven by office-to-casual versatility requirements.
- Straight Leg:Uniform width from thigh to hem, historically constructed from rigid 14-16 oz selvedge. Heritage Japanese and Italian makers anchor supply for United States and European specialty doors, constrained by narrow-loom capacity scarcity.
- Bootcut:Subtle flare from knee to hem accommodating footwear stacks. Regional preference persists in Southwestern United States markets.
- Wide Leg:Relaxed silhouette with pronounced volume through thigh and calf. Fashion-cycle positioning drives seasonal wholesale commitments.
By volume, Skinny leads. By growth pace, Wide Leg is climbing the fastest.
Fabric Type:
Cost structures and certification requirements stratify fabric sourcing, with organic and selvedge commanding premium placement while stretch captures mass-premium scale.
- Organic Cotton:GOTS-certified fiber grown without synthetic pesticides or fertilizers, typically 12-14 oz construction. REACH and EU Green Deal mandates are accelerating certified acreage commitments from Italian and Portuguese mills, though yield volatility elevates raw material premiums.
- Selvedge:Narrow-loom fabric with self-finished edge, rope-dyed indigo on vintage shuttle looms. Kaihara's Okayama manufacturing cluster and Cone Mills' White Oak heritage supply anchor artisanal collections in United States and Japanese boutique channels, with master craftsman scarcity constraining capacity expansion.
- Stretch Denim:Elastane-blended construction enabling 2-4% recovery, dominating women's comfort-driven segments. Technical ceiling from elastane degradation limits warranty positioning.
- Raw Denim:Unwashed, unsanforized fabric requiring break-in period. Cult status persists in Japanese collector communities and Italian maker circles.
By volume, Stretch Denim dominates. By margin expansion, Organic Cotton is gaining share fastest.
Customer Type:
Purchase frequency and channel preference diverge by demographic, with women driving DTC acceleration and men sustaining heritage wholesale relationships.
- Women:Primary volume driver across skinny and wide leg categories, with comfort-stretch blends capturing direct-to-consumer repeat purchase. Fit personalization algorithms and same-day alteration services are penetrating underexploited Japanese domestic markets.
- Men:Selvedge and raw denim concentration, with higher average unit economics sustained through heritage archive storytelling. Wholesale reform strategies in North American and European doors preserve pricing power.
- Children:Growth-adjusted sizing requirements with shorter replacement cycles. Sustainability messaging transfers from parent purchase behavior.
- Unisex:Relaxed-fit constructions spanning gender categories, gaining placement in curated multi-brand boutiques.
By volume, Women lead. By emerging trajectory, Unisex is expanding most quickly.
Price Tier:
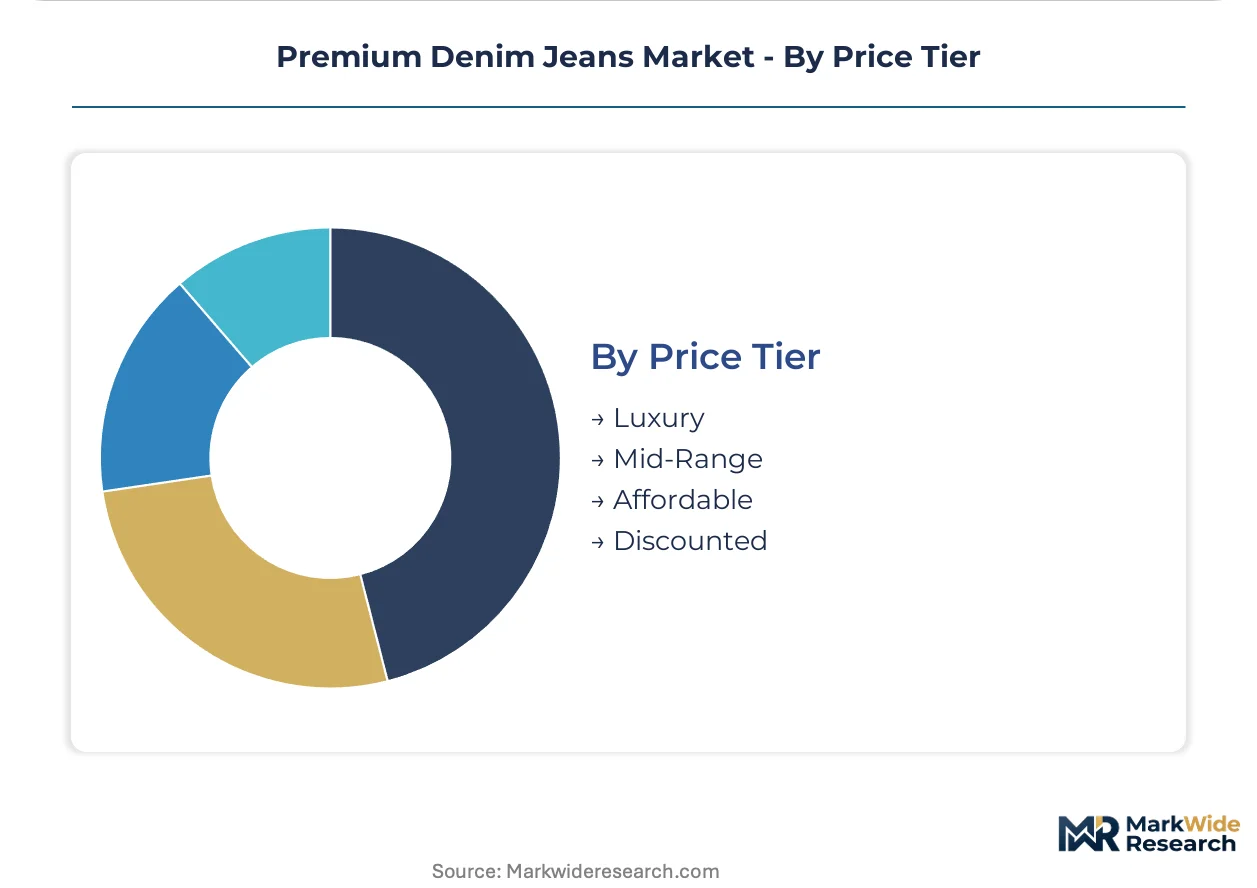
Manufacturing provenance and certification grade determine tier placement, with luxury capturing heritage scarcity and mid-range absorbing organic compliance costs.
- Luxury:Japanese selvedge and Italian artisanal construction, typically 16 oz+ rigid fabrics with hand-finished details. Kaihara rope-dyed supply and Okayama cluster scarcity reinforce pricing power in United States and Italian specialty retail.
- Mid-Range:Organic cotton and premium stretch blends, balancing ESG compliance with accessibility. Arvind Limited's waterless finishing scale serves Western brand volume commitments.
- Affordable:Conventional cotton with basic finishing, constrained by REACH chemical disclosure investments.
- Discounted:Overstock and previous-season placement, limited by extended producer responsibility framework disincentives.
By revenue concentration, Luxury leads. By volume scale, Mid-Range dominates channel flow.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles throughput underwrites United States import velocity for premium denim, while the Rhine-Alpine rail corridor sustains European distribution density from Italian and Portuguese mills.
United States
Affluent millennial purchase frequency through direct-to-consumer channels drives volume concentration in coastal metropolitan markets. EPA wastewater standards constrain North American finishing operations, elevating compliance investments for domestic laundries. Los Angeles and New York City anchor heritage brand flagship presence and specialty boutique density.
Italy
Heritage manufacturing clusters in Veneto and Tuscany reinforce artisanal pricing power for European specialty retail. EU Green Deal circularity obligations and REACH chemical disclosure mandates favor vertically integrated mills with captive chemical management. Prato's textile district concentrates organic cotton finishing capacity serving ESG-conscious Western brands.
Japan
Okayama Prefecture's Kojima manufacturing cluster commands global selvedge scarcity positioning through proprietary rope-dyeing expertise. METI promotes textile innovation through JIS quality benchmarks that reinforce domestic premium positioning. Tokyo and Osaka sustain collector-driven demand for raw denim and artisanal construction.
India
Arvind Limited's integrated scale dominates waterless finishing technology adoption for Western brand volume commitments. The country's national textile regulator advances sustainable manufacturing standards through compliance frameworks. Gujarat and Tamil Nadu concentrate denim mill capacity with ESG-certified export orientation.
United Kingdom
London's multi-brand curator consolidation drives exclusive colorway allocation demands and accelerated replenishment terms. REACH Annex XVII restrictions on azo dyes impose reformulation deadlines for European-sold collections. East London's design studios anchor trend-responsive sampling for heritage brand diffusion lines.
Premium Denim Jeans Market Key Industry Players
Listed leaders compete with private specialists across capital access and founder control dimensions. The vendor base stratifies between scale-driven integrated mills, heritage brand houses, and artisanal selvedge specialists. Three archetypes dominate: vertically controlled Japanese manufacturers, wholesale-reforming American heritage houses, and South Asian ESG-compliant volume producers. Competitive moves concentrate on direct-to-consumer platform buildout and sustainable finishing technology licensing.
Within the heritage brand tier, Levi Strauss & Co. and Diesel occupy positions defined by archive storytelling and wholesale reform strategies. Kaihara exemplifies the Japanese selvedge archetype through proprietary rope-dyeing capacity. Arvind Limited anchors the South Asian ESG-compliant volume producer segment with integrated waterless finishing scale.
| Leading Market Players |
|---|
| ISKO |
| Kaihara |
| Levi Strauss & Co. |
| Blue Age Denim |
| Grupo Denim |
| Diesel |
| Arvind Limited |
| Steve Apparel |
| Wrangler |
| Others |
Cost & Logistics Intelligence
Narrow-loom selvedge capacity utilization at Kaihara's Okayama facility anchors premium price floors across Japanese and Italian heritage tiers, while Arvind Limited's integrated waterless finishing scale compresses mid-range organic cotton premiums through volume efficiency. This concentration of artisanal scarcity alongside South Asian manufacturing density creates divergent margin architectures that reward provenance storytelling at the luxury tier and ESG compliance at scale.
Pricing Analysis
Three-tier pricing structure across luxury, mid-range, and affordable levels stratifies the market by certification grade and manufacturing provenance. Price differentiation hinges on GOTS organic certification and heritage selvedge construction, with REACH compliance costs intensifying margin pressure in European-bound production. Entry-premium buyers exhibit highest price sensitivity, while collector-driven segments absorb artisanal premiums without volume negotiation.
Supply Chain Analysis
Inventory lead times for certified organic fiber have compressed from traditional seasonal cycles to accelerated GOTS verification windows demanded by EU Green Deal deadlines. Raw cotton sourcing draws from India, Turkey, and the United States, with indigo dye concentrates resting on Chinese and Indian chemical suppliers. Single-source vulnerability concentrates in Kaihara's proprietary rope-dyeing capacity, while distribution runs through Los Angeles and New York City flagship channels for North American heritage placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Master craftsman expertise in narrow-loom selvedge production represents the critical capability gap constraining heritage-tier expansion, with retiring artisan populations limiting capacity growth for Japanese and Italian mills seeking to capture elevated pricing power.
For Market Incumbents: Secure captive supply agreements with Okayama and Prato manufacturing clusters before competitor consolidation locks out remaining artisan capacity. Invest in laser finishing automation to offset REACH-driven wet-processing cost inflation while preserving pricing power through exclusive colorway allocations at United States coastal boutiques. For New Entrants and Emerging Players: Lead with localized fit algorithms targeting underpenetrated Japanese domestic DTC channels where heritage brands maintain limited digital presence. Exploit white space in subscription-rental hybrid models enabled by EU extended producer responsibility frameworks, positioning same-day alteration services as the primary go-to-market wedge against established wholesale relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically controlled Italian mills with captive chemical management infrastructure capable of absorbing REACH disclosure burdens that displace fragmented competitors. Long-term viability rests on acquisition targets demonstrating rope-dyeing expertise transfer programs that mitigate craftsman scarcity risk. Watch laser finishing patent filings as the inflection signal for automation-driven margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Manufacturing Cluster Acquisition | Captures Kaihara and Okayama scarcity positioning before competitor lock-up. |
| Laser Finishing Technology Licensing | Reduces potassium permanganate dependency under REACH Annex XVII restrictions. |
| Direct-to-Consumer Platform Buildout | Captures first-party data for fit personalization in Japanese domestic markets. |
| GOTS Certification Investment | Secures shelf space in EU specialty retail under Green Deal circularity mandates. |
| Subscription-Rental Hybrid Launch | Enables residual value capture through EU textile take-back program infrastructure. |
Research Approach
Initial hypotheses were tested against primary input from denim brand supply chain directors, specialty boutique buyers, mill sustainability officers, and regulatory compliance leads and refined through secondary validation against customs trade records, GOTS certification databases, EPA wastewater discharge filings, and EU ECHA SCIP disclosure registries. Bottom-up volume estimates from individual mill capacity statements were triangulated against top-down category spend data from retail audit panels.
Variance decomposition across the projection horizon isolates volume drivers by silhouette category, fabric certification tier, channel mix, and regional regulatory cluster. CAGRs were derived from segment-level growth rate reconciliation against macro denim category trajectories, with specific inputs including Kaihara capacity utilization rates, Arvind Limited waterless finishing adoption curves, and REACH compliance cost pass-through elasticity estimates.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or abrupt organic cotton yield disruption would require recalibration. Forecasts reflect documented assumptions about artisan capacity retention and laser finishing penetration curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Europe Headwear Market
Apparel & Footwear
Outdoor Jacket Market
Apparel & Footwear
Women's Sports and Swimwear Market
Apparel & Footwear
Outdoor Sports Apparel Market
Apparel & Footwear
Online Apparel Market
Apparel & Footwear
Golf Outfit Market
Apparel & Footwear
Surfing Apparel and Accessory Market
Apparel & Footwear
Plus Size Clothing Market
Apparel & Footwear
Global Silk Pajamas Market
Apparel & Footwear
Ice Hockey Apparel Market
Apparel & Footwear
Bra Market
Apparel & Footwear
Insulated Jacket Market
Apparel & Footwear
Driving Apparel Market
Apparel & Footwear
Asia Pacific Hats Market
Apparel & Footwear
Designer Sneaker Market
Apparel & Footwear
Body Shaper Market