
 Sports Apparel Market | 2026-2036
Sports Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Apparel Market Intelligence
Buyer concentration across the sports apparel channel is rebalancing as direct-to-consumer platforms fragment traditional wholesale relationships while specialty running and yoga studios consolidate into multi-brand retail chains. Nike leverages its in-house manufacturing scale to control inventory velocity across these shifting channels. Adidas sustains technology leadership in performance footwear through its Boost platform chemistry. Under Armour specializes in compression fabrics and connected-fitness apparel for team sports contracts.
Sports apparel encompasses engineered garments constructed from synthetic blends, merino wool, or regenerated cellulose with moisture-wicking, thermal regulation, and abrasion-resistance specifications for athletic use. Manufacturing employs flatlock seams, ultrasonic welding, and 3D knitting to eliminate friction points during repetitive motion. Footwear commands the largest margin pool due to midsole patent density and brand premiumization, while training gear registers the fastest trajectory as home-based workout cultures persist. Online retail is displacing department stores as the primary volume channel, though specialty stores retain premium positioning for technical fitting services.
The EU Green Deal and REACH chemical restrictions are forcing reformulation of dye processes and fluorinated water-repellent coatings across European supply chains. The US EPA monitors per- and polyfluoroalkyl substance discharge from textile finishing facilities. China's MEE enforces wastewater standards at dyeing and printing clusters in Zhejiang and Guangdong provinces. Stakeholders must monitor how extended producer responsibility schemes in the EU and pending US state-level textile recycling laws reshape material sourcing decisions and regional cost structures.
Market Dynamics
The sports apparel market is undergoing structural reconfiguration as direct-to-consumer platforms fragment traditional wholesale channels while specialty retailers consolidate into multi-brand chains, forcing manufacturers to recalibrate inventory velocity and margin capture across hybrid distribution architectures.
Growth Catalysts
- EU Green Deal recycled polyester mandates:Binding recycled content thresholds for synthetic fibers are redirecting capital toward chemical recycling infrastructure and bio-based polymer R&D across European supply chains.
- Amateur fitness participation among women aged 25-40:This demographic cohort is driving premium technical apparel demand for studio-to-street crossover products with elevated performance specifications.
- China-India-Brazil middle-class expansion:Rising sports participation rates in these three markets are concentrating volume growth in Asia-Pacific and Latin American distribution networks.
Market Restraints
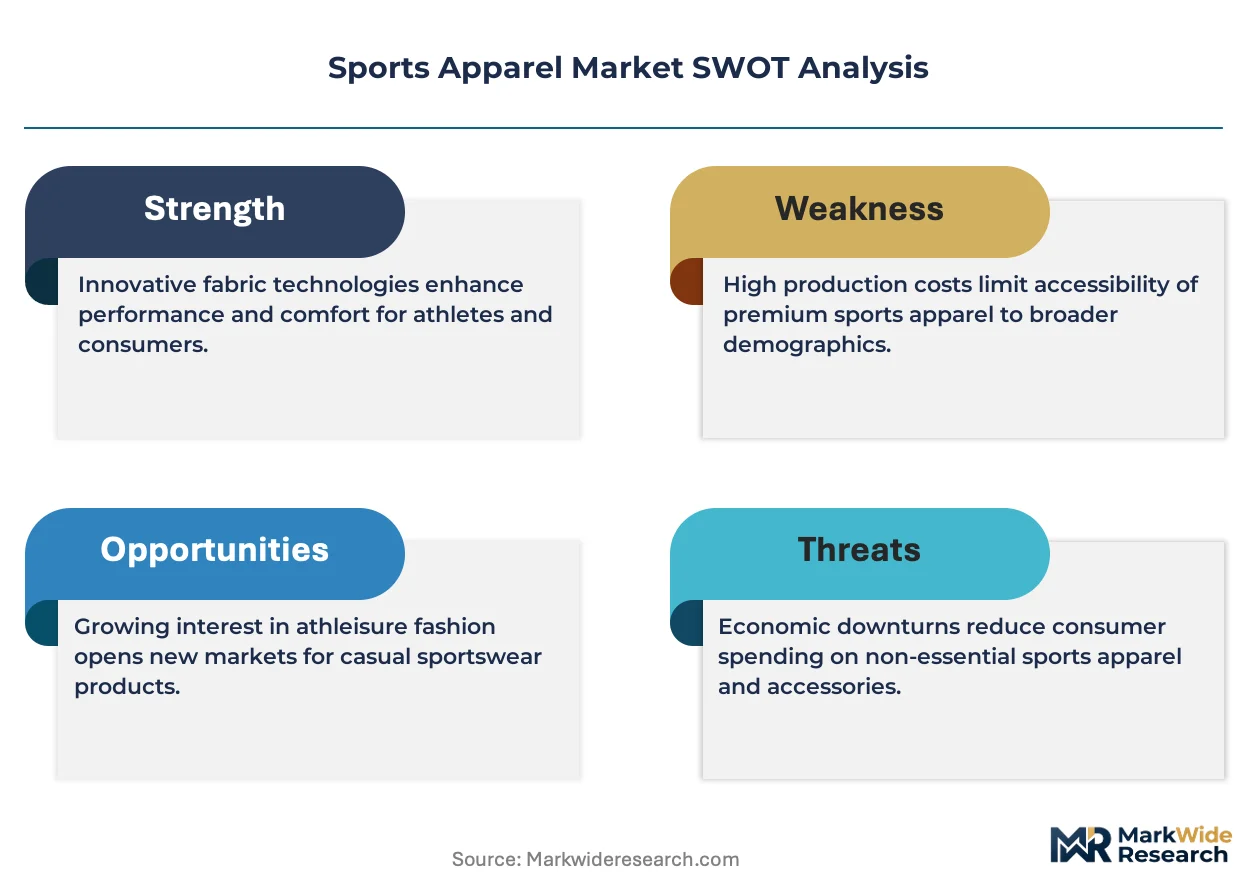
- Petrochemical input volatility:Crude-derived synthetic fiber feedstocks expose margin structures to energy market fluctuations without viable near-term substitution at scale.
- Zhejiang-Guangdong dyeing cluster concentration:Wastewater enforcement actions by China's MEE are creating supply bottlenecks for finished fabrics during seasonal peak demand.
- REACH chemical restriction compliance costs:Reformulation of fluorinated water-repellent coatings and azo dye alternatives is elevating R&D expenditure for European market access.
Strategic Opportunities
- Extended producer responsibility schemes:EU textile recycling mandates are creating first-mover advantages for brands establishing closed-loop take-back infrastructure and fiber-to-fiber regeneration partnerships.
- 3D knitting and seamless construction convergence:Integration of additive manufacturing with body-scanning customization is enabling made-to-measure performance wear at near-mass-production economics.
- Home-based workout culture persistence:Training gear demand is outpacing team sports apparel, rewarding brands with hybrid indoor-outdoor product architectures and connected-fitness integration.
Industry Challenges
- Technical talent scarcity in sustainable materials chemistry:Formulation expertise for bio-based alternatives to petroleum-derived performance fibers remains concentrated among a narrow pool of polymer scientists.
- Multi-jurisdiction certification complexity:Divergent chemical safety standards across EPA, REACH, and China's GB frameworks extend product launch timelines and compliance overhead.
- Legacy ERP integration with DTC analytics platforms:Wholesale-oriented inventory systems require costly reconfiguration to capture real-time demand signals from direct channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Apparel Market |
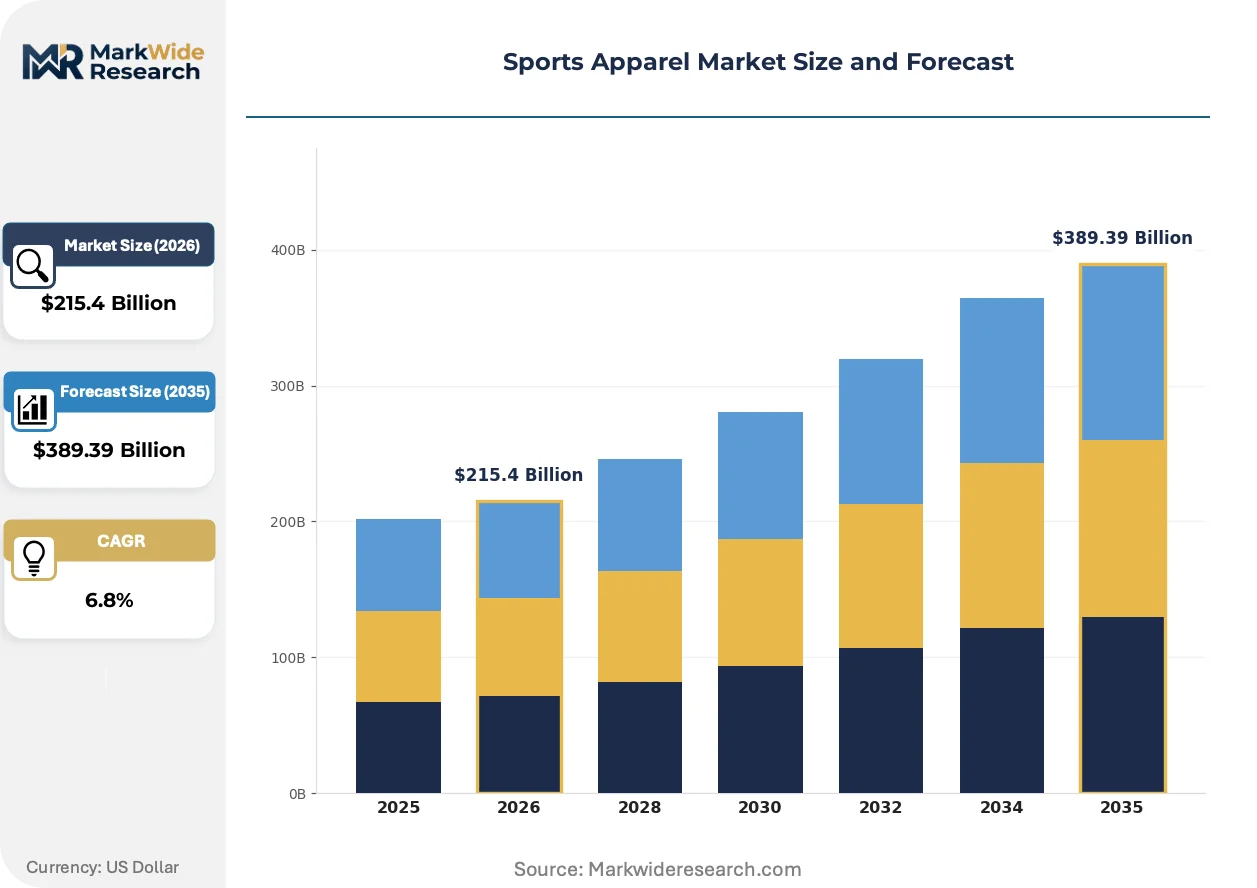
| Market Size in 2026 | $215.4 Billion |
| Market Size in 2035 | $389.39 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
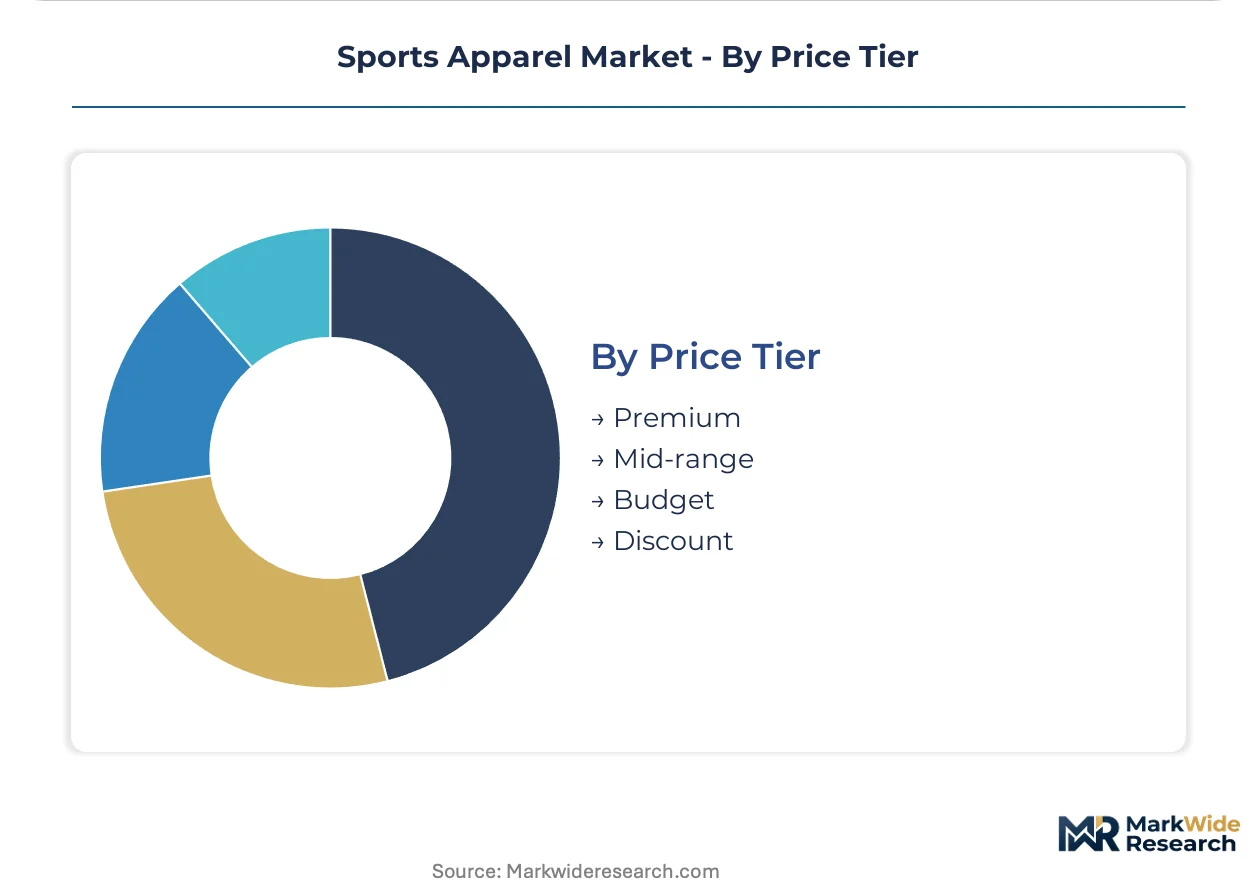
| Segmentation | Product Type: Footwear, Jerseys, Shorts, Training Gear End User: Men, Women, Children, Athletes Distribution Channel: Online Retail, Specialty Stores, Department Stores, Supermarkets Price Tier: Premium, Mid-range, Budget, Discount |
| Companies Covered | Nike, Adidas, Puma, Lululemon Athletica, Under Armour, Columbia Sportswear Company, Asics Corporation, New Balance, VF Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Apparel Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory chemistry restrictions are simultaneously expanding performance boundaries and compressing the approved substance palette, forcing concurrent innovation in fiber engineering and finishing process redesign.
Regenerated cellulose fibers derived from agricultural waste streams are expanding into moisture-management base layers previously dominated by petroleum synthetics. Yoga and pilates practitioners in North American and European markets are adopting these materials at accelerating rates as tactile performance parity improves. This shift is expanding into premium pricing tiers while pressuring conventional viscose producers to demonstrate closed-loop solvent recovery.
REACH restrictions on per- and polyfluoroalkyl substances are compelling reformulation of durable water-repellent treatments across outdoor and all-weather performance categories. The European Chemicals Agency's 2023 substance evaluation roadmap has accelerated phase-out timelines, forcing suppliers to commercialize silicone and hydrocarbon alternatives at commercial scale. Alpine and Nordic outdoor brands are absorbing the highest compliance costs while racing to maintain hydrostatic head ratings without fluorinated chemistry.
Specialty running and yoga studios are consolidating into multi-brand retail chains that demand exclusive product lines and co-developed capsule collections. These buyers are displacing department store volume with curated technical assortments and biometric fitting services. This concentration is most visible in Germany, Japan, and Australia's major metropolitan markets where studio density supports dedicated retail footprints.
Sports Apparel Market Segmentation

Sports apparel segmentation reveals how technical specifications, channel economics, and demographic targeting fragment purchasing behavior. Manufacturers calibrate fiber engineering, margin architecture, and inventory velocity differently across each axis.
Product Type:
Midsole patent density and seamless construction technology differentiate performance tiers and margin capture potential across garment categories.
- Footwear:Engineered with Boost platform chemistry, carbon fiber plates, and 3D-printed midsoles for energy return optimization. Demand concentrates in China and Germany where running participation is climbing fastest among amateur fitness practitioners. Patent-protected compounds sustain pricing power despite petrochemical input volatility.
- Training Gear:Compression fabrics with moisture-wicking synthetic blends or regenerated cellulose for home-based workout cultures. Volume is accelerating in Brazil and India as middle-class sports participation expands beyond traditional team sports. Connected-fitness integration is becoming a baseline specification.
- Jerseys:Lightweight polyester or recycled polyester constructions with flatlock seams for team sports contracts.
- Shorts:Abrasion-resistant woven or knit constructions with ultrasonic welded seams for friction elimination during repetitive motion.
Footwear leads on scale; training gear leads on momentum.
End User:
Demographic purchasing power and participation patterns reshape product development priorities and marketing expenditure allocation.
- Women:Studio-to-street crossover designs with elevated thermal regulation and tactile performance specifications. Amateur fitness participation among women aged 25-40 is driving premium technical apparel demand in North American and European markets. Yoga and pilates practitioners are adopting regenerated cellulose base layers at accelerating rates.
- Men:Traditional team sports and outdoor performance categories with established brand loyalty and replacement-cycle predictability. Demand concentrates in China and Brazil where football and basketball participation rates are rising fastest among middle-class consumers.
- Children:Growth-accommodating constructions with reinforced abrasion resistance for school sports and recreational programs.
- Athletes:Biomechanically optimized custom fits with biometric monitoring integration for elite performance contracts.
Men lead on scale; women lead on momentum.
Distribution Channel:
Channel fragmentation is forcing inventory system reconfiguration as real-time demand signals displace wholesale forecasting.
- Online Retail:Direct-to-consumer platforms with body-scanning customization and algorithmic recommendation engines. This channel is displacing department stores as the primary volume channel across all price tiers. Legacy ERP integration costs are creating competitive barriers for wholesale-oriented incumbents.
- Specialty Stores:Multi-brand retail chains with biometric fitting services and exclusive capsule collections. Consolidation into curated technical assortments is most visible in Germany, Japan, and Australia's major metropolitan markets where studio density supports dedicated retail footprints.
- Department Stores:Declining volume share with residual presence in budget and mid-range mass-market assortments.
- Supermarkets:Price-driven basic activewear with minimal technical specifications and high inventory turnover velocity.
Online retail leads on scale; specialty stores lead on momentum.
Price Tier:
Raw material specifications and certification requirements stratify cost structures and margin pools across purchasing segments.
- Premium:Bio-based polymers, chemical-recycled synthetics, and fluorinated water-repellent alternatives meeting REACH compliance. EU Green Deal recycled polyester mandates are redirecting R&D expenditure toward closed-loop fiber regeneration. Alpine and Nordic outdoor brands absorb the highest compliance costs while racing to maintain hydrostatic head ratings.
- Mid-range:Blended synthetic-natural constructions with selective technical features and accessible price points for expanding middle-class markets.
- Budget:Conventional petroleum-derived synthetics with basic moisture-wicking and standard seam constructions for price-sensitive volume.
- Discount:Unbranded or private-label activewear with minimal performance specifications and compressed margin structures.
Premium leads on scale; mid-range leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's middle-class sports participation is outpacing India's volume trajectory, while Brazil's amateur fitness culture accelerates faster than European market maturation. Regulatory chemistry restrictions and recycled content mandates are reshaping sourcing decisions across manufacturing clusters.
United States
Amateur fitness participation among women aged 25-40 is driving premium technical apparel demand for studio-to-street crossover products. The EPA monitors per- and polyfluoroalkyl substance discharge from textile finishing facilities under evolving enforcement protocols. Specialty running and yoga studios in Austin, Denver, and Portland are consolidating into multi-brand retail chains with biometric fitting services.
Germany
REACH chemical restrictions are compelling reformulation of fluorinated water-repellent coatings across outdoor performance categories. The EU Green Deal's binding recycled polyester mandates are redirecting capital toward chemical recycling infrastructure in North Rhine-Westphalia. Alpine and Nordic outdoor brands in Bavaria absorb the highest compliance costs while racing to maintain hydrostatic head ratings.
China
Rising middle-class sports participation is concentrating volume growth in Asia-Pacific distribution networks for training gear and team sports apparel. The MEE enforces wastewater standards at dyeing and printing clusters in Zhejiang and Guangdong provinces. Manufacturing gravity centers on the Yangtze River Delta and Pearl River Delta where flatlock seam and 3D knitting capabilities scale for export markets.
Brazil
Football and basketball participation rates among middle-class consumers are climbing fastest in São Paulo and Rio de Janeiro metropolitan corridors. ANVISA regulates chemical safety standards for imported textile finishes and synthetic fiber formulations. Domestic retail consolidation in the Southeast region is displacing informal channel volume with branded technical assortments.
India
Home-based workout cultures are accelerating training gear demand beyond traditional cricket and field hockey equipment cycles. BIS certification requirements for synthetic fiber imports are extending product launch timelines for international brands. Manufacturing investment clusters in Maharashtra and Tamil Nadu are expanding moisture-wicking fabric finishing capacity for domestic and export markets.
Sports Apparel Market Key Industry Players
North American producers anchor the premium-tier vector through direct-to-consumer platform scale and connected-fitness integration; European specialists hold compliance-advantaged positions under REACH and EU Green Deal chemistry mandates. The market structure stratifies across three tiers: global scale players with captive manufacturing, regional specialists with fiber-to-fiber regeneration partnerships, and private-label aggregators with compressed margin structures. Dominant competitive moves include backward integration into chemical recycling infrastructure and exclusive capsule collection partnerships with consolidating specialty retail chains.
Within the scale-driven tier, Nike and Adidas exemplify divergent strategic archetypes—Nike leveraging in-house manufacturing velocity across fragmented channels, Adidas sustaining midsole chemistry leadership through platform patent density. Under Armour occupies a specialist position in compression fabrics and team sports contract relationships. These three entities collectively represent the competitive tension between manufacturing control, materials science differentiation, and segment-specific technical positioning.
| Leading Market Players |
|---|
| Nike |
| Adidas |
| Puma |
| Lululemon Athletica |
| Under Armour |
| Columbia Sportswear Company |
| Asics Corporation |
| New Balance |
| VF Corporation |
| Others |
Cost & Logistics Intelligence
Crude-derived synthetic fiber feedstock indices cascade through polyester pricing tiers, compressing margin pools for budget-tier producers while REACH-compliant premium grades absorb reformulation costs through brand premiumization.
Pricing Analysis
Capacity additions in Vietnam and Bangladesh are reshaping price floors for basic activewear, forcing mid-range competitors toward certification differentiation. Three-tier pricing structure across premium, standard, and economy levels stratifies by REACH compliance status and recycled content thresholds. Pricing pressure stems from petrochemical input volatility, with polyester staple fiber costs transmitting unevenly across synthetic-blend garments. Price-sensitive volume buyers in supermarket channels face the steepest trade-offs between cost and performance specifications, while specialty retail chains absorb premiums for exclusive capsule collections.
Supply Chain Analysis
Polyester yarn supply rests on petrochemical complexes in China, South Korea, and Taiwan, with dyeing and finishing capacity concentrating in Zhejiang and Guangdong provinces. Raw material dependencies span PTA and MEG feedstocks, regenerated cellulose pulp, and fluorinated water-repellent chemistry alternatives. Single-source vulnerability runs through China's MEE-enforced dyeing clusters, where wastewater compliance actions disrupt seasonal peak output. Distribution runs through direct-to-consumer platforms and consolidating multi-brand specialty chains, displacing department store wholesale volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sports apparel operates as a regulatory compounder where EU Green Deal recycled polyester mandates are tightening material specifications and redirecting R&D capital toward chemical recycling infrastructure.
For Market Incumbents: Cement compliance-advantaged positions under REACH and EU Green Deal chemistry mandates through backward integration into fiber-to-fiber regeneration partnerships. Deepen channel control via exclusive capsule collections with consolidating specialty retail chains in Germany and Japan. Defend against private-label aggregators by accelerating 3D knitting and seamless construction capabilities that compress made-to-measure economics. For New Entrants and Emerging Players: The price-point gap between premium REACH-compliant tiers and budget petroleum-derived synthetics offers white-space entry through mid-range regenerated cellulose base layers. Target studio-to-street crossover demand among women aged 25-40 in North American and European markets where tactile performance parity is improving. Pursue go-to-market angles through connected-fitness platform integrations that bypass legacy wholesale ERP barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists possessing fiber-to-fiber regeneration partnerships and established take-back infrastructure under extended producer responsibility schemes. Long-term viability favors acquisition targets with demonstrated chemical recycling feedstock security and multi-jurisdiction certification expertise. Watch MEE enforcement intensity in Zhejiang-Guangdong clusters as an inflection indicator for supply bottleneck severity and margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Infrastructure Investment | EU Green Deal mandates are redirecting capital toward closed-loop polyester regeneration in North Rhine-Westphalia. |
| 3D Knitting and Seamless Construction Scale-Up | Integration with body-scanning customization enables made-to-measure economics for performance wear. |
| Direct-to-Consumer Platform Expansion | Real-time demand signals displace wholesale forecasting, rewarding legacy ERP reconfiguration. |
| Exclusive Capsule Collection Partnerships | Consolidating specialty retail chains in Germany and Japan demand co-developed technical assortments. |
| Regenerated Cellulose Fiber Diversification | Agricultural waste-derived alternatives expand into moisture-management tiers previously dominated by petroleum synthetics. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with brand sustainability officers, specialty retail buyers, chemical recycling plant managers, and polymer R&D directors. Secondary validation draws from EU ECHA substance evaluation roadmaps, China's MEE wastewater enforcement disclosures, SEC apparel company filings, and trade data from synthetic fiber import registries. Bottom-up demand modeling and top-down market sizing triangulate across these sources.
Rate-of-change decomposition separates volume growth from price-mix effects across the analysis window. Segmentation dimensions span product type, end user demographic, distribution channel, and price tier, with regional regulatory cluster as an additional modeled axis. CAGRs derive from fitted growth curves applied to validated baseline estimates, incorporating amateur fitness participation trajectories and recycled content mandate phase-in schedules as industry-specific forecast inputs.
Caveats apply where MEE enforcement intensity, REACH substance evaluation acceleration, or petrochemical price volatility could materially shift the outlook. Forecasts reflect assumptions about chemical recycling capacity buildout timelines and consumer willingness-to-pay for bio-based alternatives. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
North America E-Commerce Apparel Market
Apparel & Footwear
Women Apparel Market
Apparel & Footwear
Press-To-Close Zippers Market
Apparel & Footwear
Compression and Shapewear Market
Apparel & Footwear
Intimate Wear Market
Apparel & Footwear
Insulated Jacket Market
Apparel & Footwear
US Fanny Packs Market
Apparel & Footwear
Platform Shoes Market
Apparel & Footwear
Fanny Packs Market
Apparel & Footwear
North America Denim Jeans Market
Apparel & Footwear
Surfing Apparel and Accessory Market
Apparel & Footwear
France Denim Jeans Market
Apparel & Footwear
Sports Bras Market
Apparel & Footwear
Custom Cycling Clothing Market
Apparel & Footwear
Europe Denim Jeans Market
Apparel & Footwear
Heated Jacket Market