
 Online Apparel Market | 2026-2036
Online Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Online Apparel Market Intelligence
Buyer concentration in online apparel is broadening as digital-native demographics fragment purchasing power across specialized platforms rather than consolidating around legacy department stores. Amazon.com Inc leverages its fulfillment infrastructure to control last-mile delivery economics for mass-market apparel segments. Alibaba Group Holding Limited anchors cross-border trade flows through integrated payment and logistics ecosystems connecting Chinese manufacturers to Western consumers. Farfetch UK Limited differentiates via curated luxury marketplace positioning that aggregates boutique inventory inaccessible through conventional retail channels.
Online apparel comprises garments and accessories sold through internet-based channels, with product fulfillment relying on automated warehousing, AI-driven size recommendation engines, and reverse logistics systems handling return rates that structurally exceed physical retail. The commercial purpose centers on collapsing geographic and temporal constraints between fashion production clusters and dispersed consumer endpoints. Footwear commands disproportionate logistics complexity due to dimensional weight pricing and higher return rates from fit uncertainty. Social media as a distribution channel is capturing the fastest growth as shoppable content collapses discovery and transaction into single-session purchases. The luxury price tier maintains the densest margin pool despite representing the smallest volume share, sustained by authentication services and exclusive digital drops.
The EU Green Deal's Digital Product Passport requirements and the EU AI Act's algorithmic transparency mandates are reshaping how platforms disclose supply chain provenance and recommendation system logic to European consumers. The FTC's endorsement guidelines and emerging state-level extended producer responsibility laws in California and New York are tightening accountability for environmental claims and textile waste accountability in the United States. Stakeholders must monitor regulatory divergence between jurisdictions that treat fashion e-commerce as a waste-stream liability versus a digital services growth sector.
Market Dynamics
Live-stream commerce infrastructure is compressing purchase cycles from discovery to delivery, forcing platforms to rebuild fulfillment networks around impulse conversion rather than planned purchasing behavior.
Growth Catalysts
- EU Green Deal Digital Product Passport:Mandatory supply chain disclosure requirements are accelerating platform investment in traceability infrastructure, creating competitive differentiation for early adopters.
- AI-driven size recommendation engines:Machine learning fit prediction is reducing return rates in footwear and outerwear categories, improving unit economics for high-velocity sellers.
- China's tier-one city live-stream density:Same-day delivery networks anchored in Shanghai, Beijing, and Shenzhen are setting fulfillment speed benchmarks that Western platforms must match.
Market Restraints
- Cotton price volatility:Input cost swings in natural fiber markets compress margin predictability for mid-tier private label assortments.
- Reverse logistics cost concentration:Return processing expenses disproportionately burden footwear and accessories categories where dimensional weight pricing intersects with high fit-driven return rates.
- EU AI Act algorithmic transparency mandates:Recommendation system disclosure requirements impose compliance friction on personalized styling engines deployed in European markets.
Strategic Opportunities
- India's tier-two urban expansion:Underpenetrated digital apparel demand in cities like Jaipur, Lucknow, and Indore offers first-mover advantage for localized fulfillment investments.
- Social commerce channel convergence:Shoppable content integration across short-form video platforms is collapsing traditional advertising and transaction funnels into single-session purchase paths.
- Extended producer responsibility tailwinds:California and New York textile waste accountability laws are creating regulatory arbitrage for platforms with pre-built circular infrastructure.
Industry Challenges
- Authentication talent scarcity:Luxury resale platforms face acute shortages of trained authenticators capable of verifying boutique inventory at platform scale.
- Warehouse automation capex intensity:Automated sortation and robotic picking systems require capital deployment that strains mid-market platform balance sheets.
- Legacy ERP integration friction:Fashion brands operating on decades-old inventory management systems face data architecture gaps when connecting to real-time marketplace APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Apparel Market |
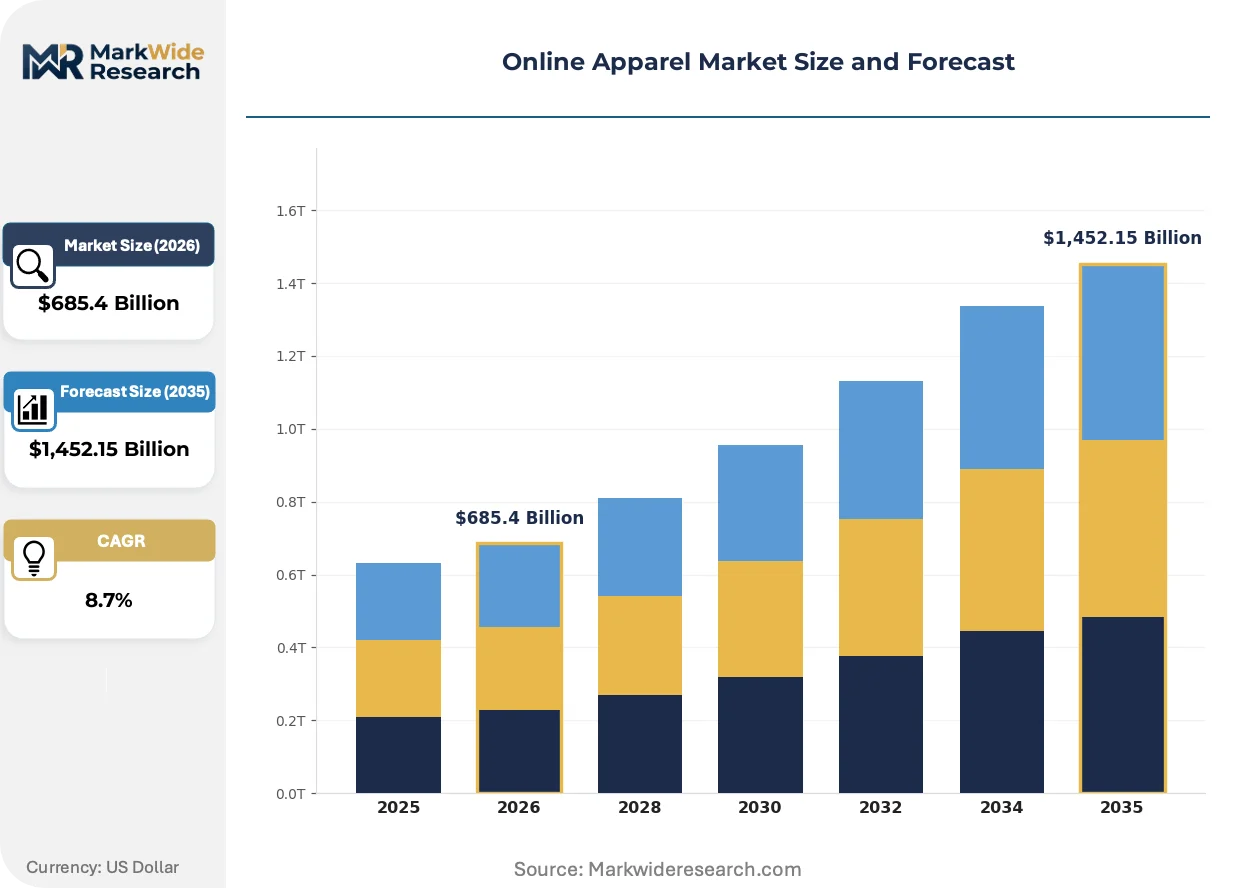
| Market Size in 2026 | $685.4 Billion |
| Market Size in 2035 | $1,452.15 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: T-Shirts, Dresses, Jackets, Footwear Customer Type: Men, Women, Children, Unisex Price Tier: Budget, Mid-range, Premium, Luxury Distribution Channel: Direct Sales, Online Marketplaces, Social Media, Brand Websites |
| Companies Covered | H & M Hennes & Mauritz AB, Levi Strauss & Co, Amazon.com Inc, Saks Fifth Avenue LLC, Flipkart Private Limited, Alibaba Group Holding Limited, Nordstrom Inc, Farfetch UK Limited, Adidas AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Apparel Market Strategic Shifts & Innovations
Generative artificial intelligence is collapsing content production timelines for apparel marketing, while regulatory disclosure mandates and shifting discovery channels are rewiring how platforms acquire and retain customers.
Computer vision-based virtual try-on is rewriting fit confidence dynamics for online apparel shoppers. Beauty and accessories retailers are deploying AR overlay technology at scale, compressing the hesitation window between browse and buy. The structural consequence is a reduction in size-driven returns that previously consumed 20-30% of logistics capacity for fashion e-commerce operators.
The EU AI Act's algorithmic transparency requirements are forcing platforms to document recommendation system logic for European consumers. Fashion marketplaces must now maintain audit trails for how styling suggestions are generated, increasing compliance overhead but creating trust differentiation. Luxury segments are responding fastest, leveraging authentication services as a parallel credibility layer.
Discovery behavior is fragmenting away from search-dominated purchasing toward algorithmic feed curation. Younger demographics in China's tier-one cities and India's metropolitan clusters now initiate apparel discovery through short-form video rather than category navigation. This shift is compressing brand loyalty cycles and elevating influencer-driven conversion mechanics over traditional seasonal campaigns.
Online Apparel Market Segmentation
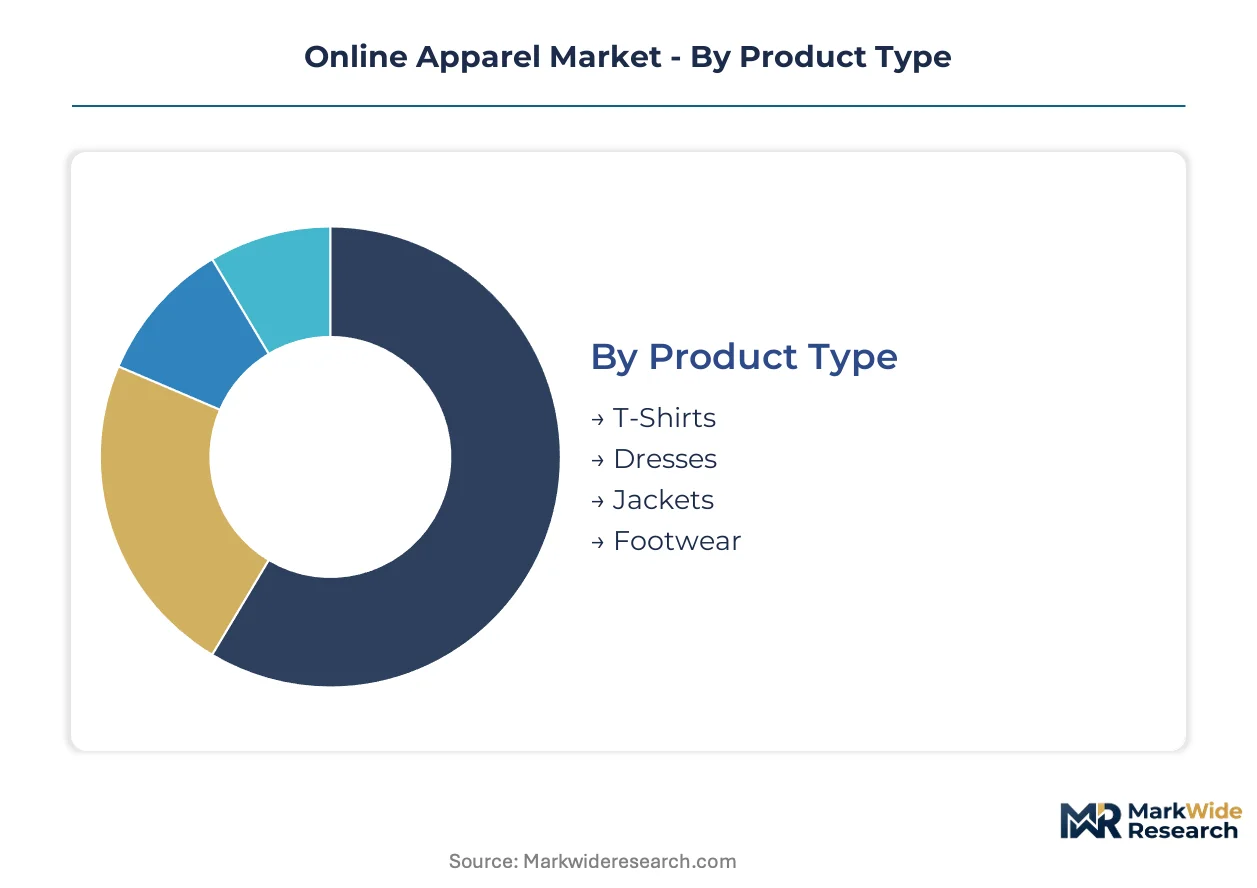
Online apparel segmentation reveals how capital deployment, customer acquisition costs, and fulfillment complexity vary dramatically across product and channel configurations. Platforms optimize inventory mix and logistics infrastructure around segments with divergent return rates, margin profiles, and size prediction challenges.
Product Type:
Footwear and outerwear demand the steepest upfront capital for specialized warehousing, given dimensional weight pricing and elevated return processing volumes from fit uncertainty.
- Footwear:Dimensional weight pricing and fit-driven return rates create disproportionate logistics complexity. Demand concentrates in China's tier-one cities where same-day delivery networks anchor impulse purchase behavior, though reverse logistics costs erode margin predictability for mid-tier private labels.
- Jackets:Seasonal inventory cycles and size prediction algorithms drive working capital intensity. European markets show accelerating demand for traceable outerwear under EU Green Deal Digital Product Passport mandates, rewarding early platform investment in supply chain disclosure infrastructure.
- T-Shirts:High-velocity basics with lowest size-driven return rates.
- Dresses:Fit variation across body types elevates virtual try-on technology adoption.
Most installed capacity flows through T-Shirts. Expansion is steepest in Footwear.
Customer Type:
Women's apparel commands the densest margin pool despite representing fragmented purchasing power across specialized platforms rather than consolidated department store loyalty.
- Women:Algorithmic feed curation now dominates discovery behavior, with short-form video platforms collapsing traditional seasonal campaign cycles. India's tier-two cities like Jaipur and Lucknow show underpenetrated digital demand where localized fulfillment investments yield first-mover positioning.
- Children:Rapid size turnover creates subscription and rental model opportunities. Parents in China's metropolitan clusters prioritize same-day delivery speed over brand loyalty, compressing repurchase windows and elevating inventory velocity requirements.
- Men:Lower return rates improve unit economics for automated warehousing.
- Unisex:Simplified size matrices reduce AI recommendation engine training costs.
Women's segment holds the largest revenue concentration. Children's segment is climbing the fastest on rental and subscription adoption.
Price Tier:
Luxury maintains the densest authentication and exclusivity infrastructure spend, while budget tiers compete on automated sortation capex efficiency.
- Luxury:Authentication services and exclusive digital drops sustain margin density despite smallest volume share. Farfetch UK Limited and comparable platforms face acute talent scarcity for trained authenticators capable of verifying boutique inventory at scale.
- Budget:Amazon.com Inc leverages fulfillment infrastructure to control last-mile delivery economics. California and New York extended producer responsibility laws create regulatory arbitrage for platforms with pre-built circular infrastructure in this high-volume, low-margin tier.
- Mid-range:Cotton price volatility compresses margin predictability for private label assortments.
- Premium:AI-driven size recommendation engines show strongest ROI on reduced return rates.
Premium tier captures the steepest technology investment. Budget tier shows the fastest volume scaling on infrastructure leverage.
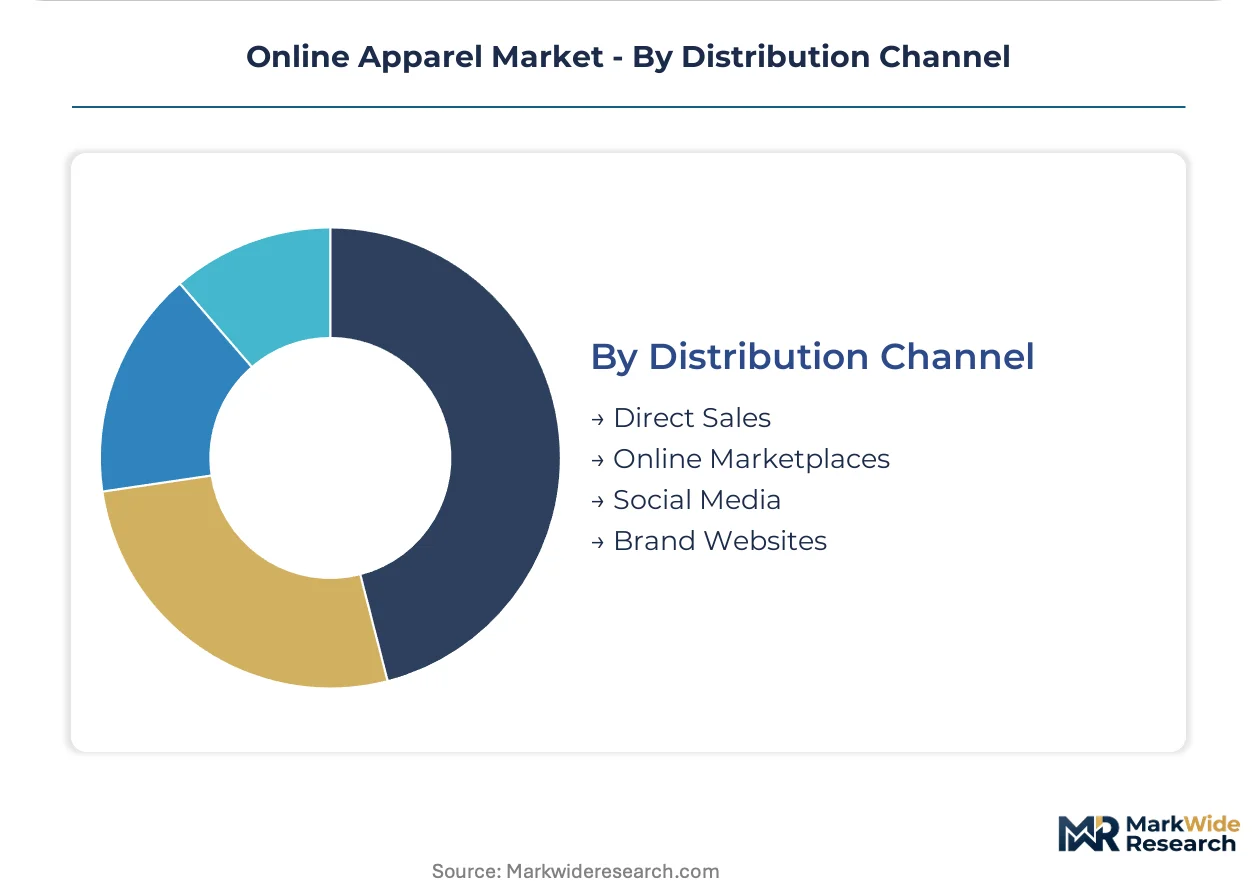
Distribution Channel:
Social commerce demands the heaviest content production and influencer relationship capital, while direct sales require owned logistics network investment.
- Social Media:Shoppable content collapses discovery and transaction into single-session purchases. Younger demographics in Shanghai and Beijing initiate apparel discovery through short-form video rather than category navigation, compressing brand loyalty cycles.
- Brand Websites:Legacy ERP integration friction strains fashion brands operating on decades-old inventory management systems when connecting to real-time marketplace APIs. First-party data capture justifies higher customer acquisition spend.
- Online Marketplaces:Alibaba Group Holding Limited anchors cross-border trade through integrated payment and logistics ecosystems.
- Direct Sales:Vertical control over fulfillment speed matches China's tier-one benchmarks.
Online Marketplaces hold the largest transaction volume. Social Media is gaining share fastest on generative AI content production efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's tier-one cities compress fulfillment timelines to same-day delivery, while India's tier-two urban centers remain underpenetrated for digital apparel infrastructure. Regulatory divergence between the EU Green Deal's traceability mandates and US state-level textile waste laws is fragmenting compliance architectures across major markets.
United States
Social commerce adoption accelerates through shoppable short-form video platforms, with younger demographics initiating discovery outside traditional search. California and New York extended producer responsibility laws impose textile waste accountability on high-volume sellers. Los Angeles and New York City anchor luxury resale authentication clusters facing acute talent scarcity.
China
Live-stream commerce infrastructure dominates apparel purchasing in Shanghai, Beijing, and Shenzhen, where impulse conversion replaces planned buying cycles. SAMR oversees platform compliance with dual carbon goals affecting logistics network electrification. The Yangtze River Delta concentrates automated warehousing investment for same-day delivery benchmarks.
Germany
EU Green Deal Digital Product Passport requirements accelerate platform investment in supply chain traceability infrastructure. ECHA coordinates with national regulators on textile chemical disclosure under REACH alignment. Berlin and Hamburg host sustainability-focused marketplace operators leveraging early compliance as competitive differentiation.
India
Tier-two cities including Jaipur, Lucknow, and Indore present first-mover opportunity for localized fulfillment investments in underpenetrated digital demand. DGFT oversees cross-border e-commerce policy affecting manufacturer-to-consumer export channels. Bangalore anchors AI-driven size recommendation engine development for footwear fit prediction.
United Kingdom
Curated luxury marketplace positioning aggregates boutique inventory inaccessible through conventional retail channels. The UK Fashion and Textile Association collaborates with regulators on circular economy standards preceding EU alignment. London concentrates authentication services and exclusive digital drop infrastructure for premium segments.
Online Apparel Market Key Industry Players
US-based mass-market platforms anchor one tier; European luxury specialists and Chinese cross-border integrators hold differentiated positions. The vendor base organizes around fulfillment infrastructure scale, authentication credibility, and social commerce content density. Three archetypes dominate: vertically integrated mass retailers, curated marketplace aggregators, and social-native direct-to-consumer operators. Competitive moves concentrate on warehouse automation capex deployment and strategic partnerships with live-stream influencers.
Among mass-market infrastructure deployers, Amazon.com Inc exemplifies fulfillment network leverage controlling last-mile delivery economics. Alibaba Group Holding Limited anchors cross-border trade flows through integrated payment and logistics ecosystems connecting Chinese manufacturers to Western consumers. Farfetch UK Limited occupies a position within the curated luxury tier, representing authentication-dependent marketplace positioning that aggregates geographically dispersed boutique inventory.
| Leading Market Players |
|---|
| H & M Hennes & Mauritz AB |
| Levi Strauss & Co |
| Amazon.com Inc |
| Saks Fifth Avenue LLC |
| Flipkart Private Limited |
| Alibaba Group Holding Limited |
| Nordstrom Inc |
| Farfetch UK Limited |
| Adidas AG |
| Others |
Cost & Logistics Intelligence
Luxury-authentication tier divergence from mass-market fulfillment economics manifests in both pricing power concentration and supply chain architecture. Premium platforms command margin density through boutique inventory aggregation and same-day delivery infrastructure, while budget tiers compete on automated sortation capex efficiency and last-mile cost compression.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for automated warehousing and same-day delivery benchmarks. Three-tier pricing structure across premium, standard, and economy levels separates authentication-dependent luxury from AI-recommendation-enhanced mid-range and volume-driven budget tiers. Price differentiation stems from certification grade (EU Green Deal Digital Product Passport compliance) and geographic delivery cost (tier-one city same-day versus tier-two 2-3 day). Cost compression in mid-range private labels is intensifying because cotton price volatility erodes margin predictability. Budget-tier mass-market buyers exhibit highest price sensitivity, while luxury authentication-dependent segments show lowest.
Supply Chain Analysis
EU Green Deal Digital Product Passport requirements and emerging US state-level extended producer responsibility laws are reshaping sourcing toward traceable fiber clusters and circular infrastructure investment. Manufacturing concentration rests on Bangladesh, Vietnam, and China for cut-make-trim operations, with India's Jaipur and Lucknow emerging for tier-two fulfillment localization. Raw material dependencies draw from cotton futures markets, synthetic polymer feedstocks, and leather tanning chemicals. Single-source vulnerability concentrates in live-stream commerce infrastructure and trained authenticator talent pools for luxury resale. Distribution runs through integrated payment-logistics ecosystems for cross-border trade, direct-to-consumer verticals for speed matching, and algorithmic feed curation for discovery-driven conversion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Online apparel functions as a stable compounder anchored by Gen Z digital-native demand fragmentation across specialized platforms rather than legacy department store consolidation.
For Market Incumbents: Anchor authentication credibility through exclusive digital drop infrastructure and boutique inventory aggregation that resists mass-market price erosion. Defensive consolidation moves center on warehouse automation capex deployment in China's tier-one cities and backward integration into circular textile processing under California and New York extended producer responsibility laws. Threat substitution from social-native direct-to-consumer operators compressing brand loyalty cycles demands preemptive influencer partnership networks. For New Entrants and Emerging Players: Begin with India's tier-two urban centers where localized fulfillment investments yield first-mover positioning in underpenetrated digital demand. White-space targets concentrate on AI-driven size recommendation engines for footwear fit prediction and generative AI content production for shoppable short-form video. The most penetrable segment is children's apparel rental and subscription models addressing rapid size turnover. Go-to-market angle: same-day delivery speed benchmarks matched to metropolitan parental purchase behavior. For Investors and Strategic Acquirers: Consolidation pressure builds where warehouse automation capex intensity strains mid-market platform balance sheets and legacy ERP integration friction blocks real-time marketplace API connectivity. Long-term viability frames around authentication talent scarcity and circular infrastructure pre-builds creating regulatory arbitrage. Acquisition target archetype: vertically integrated mid-cap specialists with owned logistics networks and pre-certified EU Green Deal traceability systems. Signal to watch: live-stream commerce infrastructure deployment rates in tier-two Chinese cities as impulse conversion benchmark diffusion.| Strategic Initiative | Industry Significance |
|---|---|
| Authentication Infrastructure Buildout | Trained authenticator pipelines address luxury resale platform talent scarcity and verification bottlenecks. |
| Circular Textile Processing Investment | Pre-built reverse logistics systems capture California and New York extended producer responsibility arbitrage. |
| AI-Driven Size Recommendation Deployment | Machine learning fit prediction reduces footwear return rates consuming 20-30% of logistics capacity. |
| Live-Stream Commerce Infrastructure | Same-day delivery networks in Shanghai and Beijing anchor impulse conversion replacing planned purchase cycles. |
| EU Green Deal Traceability Certification | Digital Product Passport compliance creates competitive differentiation in European cross-border e-commerce. |
Research Approach
Direct dialogue with platform operations executives, luxury authentication specialists, supply chain directors at cross-border integrators, and live-stream commerce infrastructure providers grounded qualitative insights. Secondary validation drew from SAMR dual carbon goal disclosures, EU ECHA textile chemical filings under REACH alignment, DGFT cross-border e-commerce policy circulars, and SEC 10-K filings from mass-market infrastructure deployers. Bottom-up segment sizing triangulated against top-down market envelope checks.
Market size and growth trajectory outputs reflect reconciliation across demand-side adoption curves, supply-side capacity deployment, and regulatory event timelines over the projection horizon. Segmentation dimensions modeled include product type (footwear, outerwear, basics), customer archetype (women, children, men), price tier (luxury, premium, mid-range, budget), and distribution channel (social commerce, marketplaces, direct sales). CAGRs derived from logistic diffusion curves fitted to live-stream commerce penetration data and generative AI content production efficiency gains.
Several conditions sit outside the modeled scope, including abrupt cotton futures volatility spikes, geopolitical disruption to Bangladesh-Vietnam-China manufacturing corridors, and algorithmic transparency enforcement variance under EU AI Act implementation. Forecasts reflect documented assumptions about Gen Z purchasing power fragmentation and social commerce channel convergence velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Women's Suits and Ensembles Market
Apparel & Footwear
US Fanny Packs Market
Apparel & Footwear
New Smart Wardrobe Market
Apparel & Footwear
Alpaca Apparel and Accessories Market
Apparel & Footwear
Jeans Market
Apparel & Footwear
Press-To-Close Zippers Market
Apparel & Footwear
India Denim Jeans Market
Apparel & Footwear
Men's Underwear Market
Apparel & Footwear
Sports Inspired Clothing Market
Apparel & Footwear
Apparel Re-Commerce Market
Apparel & Footwear
Asia-Pacific Jeans Market
Apparel & Footwear
Men Shirts Market
Apparel & Footwear
Yoga Clothing Market
Apparel & Footwear
Children's Suits and Ensembles Market
Apparel & Footwear
Global Apparel Market
Apparel & Footwear
Gymnastic Leotards Market