
 Press Brakes Market | 2026-2036
Press Brakes Market Size, Share, and Industry Trends Forecast 2026-2036
Press Brakes Market Analysis
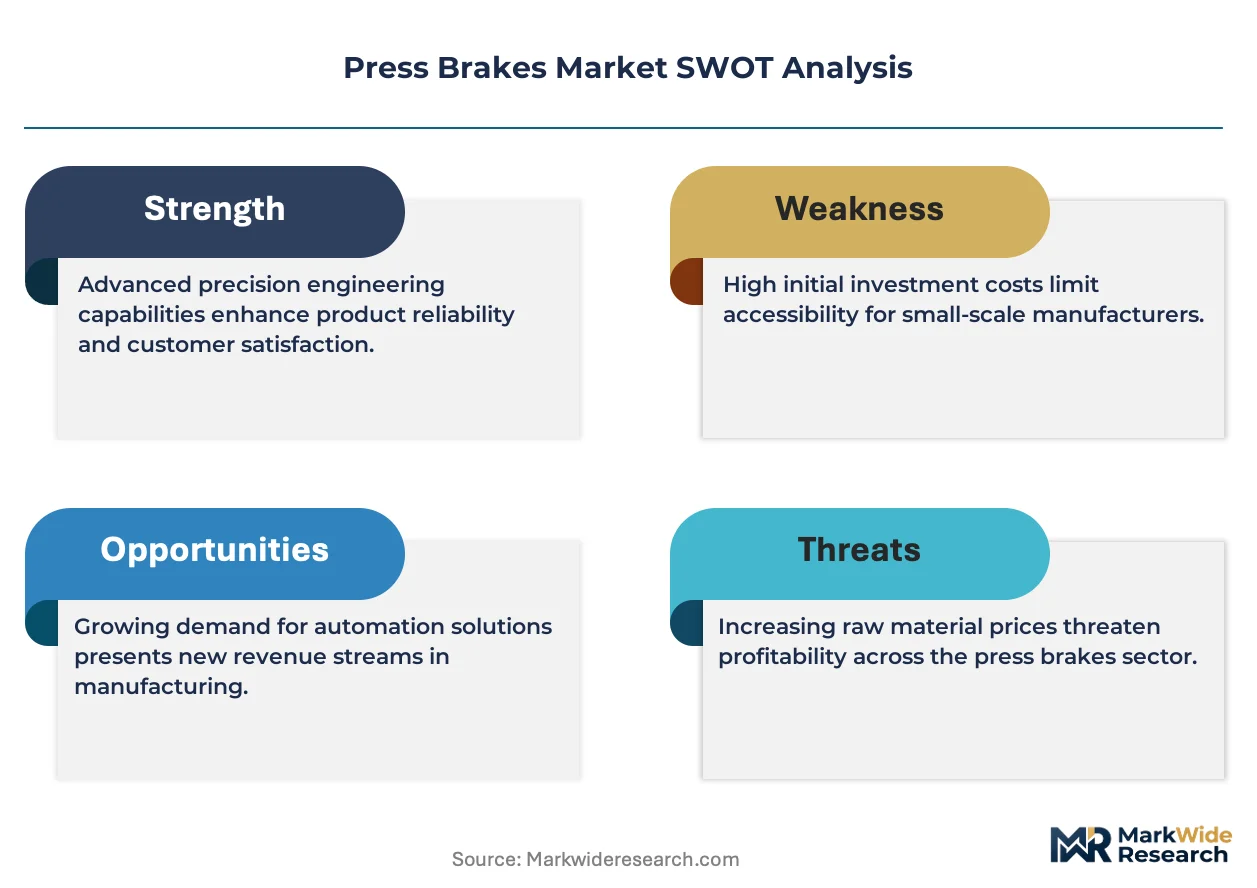
Asset-light leasing and pay-per-use financing for high-tonnage press brakes is narrowing the competitive gap between established multinationals and mid-tier regional suppliers. Trumpf leverages captive financing programs to anchor premium CNC installations across European automotive stamping operations. Amada sustains technology leadership through in-house servo-electric drive development that reduces energy draw per bending cycle. Baykal Makina competes on manufacturing scale, occupying price-sensitive tiers in Middle Eastern and African general fabrication markets.
Press brakes are machine tools that apply calculated force through synchronized upper and lower dies to bend sheet metal and plate at programmed angles, with modern CNC variants achieving positional accuracy within 0.01 millimeters via closed-loop feedback systems. Their primary purpose is precision metal forming for batch and mass-production environments across automotive body panels, aircraft structural components, and construction framing elements. Electric press brakes represent the fastest-expanding product category as manufacturers pursue energy-recovery systems and reduced hydraulic fluid maintenance. Software-controlled technology dominates margin pools, commanding premium pricing through integrated offline programming and automatic tooling-change databases that compress setup intervals. Sheet metal bending applications absorb the largest volume share, though aerospace-grade titanium forming commands substantially higher per-unit value due to specialized die materials and force-calibration protocols.
FDA standards for medical device enclosures, OSHA machine-guarding mandates, and ISO 16092 safety requirements for press brakes collectively shape product design and retrofit demand across North American and European installed bases. The EU Machinery Directive and CE marking enforcement compel European suppliers to integrate laser-safe light curtains and two-hand control systems as standard rather than optional configurations. Stakeholders must monitor how evolving carbon-border adjustment mechanisms and energy-efficiency labeling reshape total-cost-of-ownership calculations for hydraulic versus electric system procurement.
Market Dynamics
Servo-electric drive architectures are displacing hydraulic systems across automotive and aerospace stamping operations, compressing energy consumption benchmarks while forcing incumbent suppliers to reengineer core product platforms around closed-loop feedback electronics.
Growth Catalysts
- ISO 16092 Safety Mandates:European and North American fabricators must retrofit installed hydraulic press brakes with laser-safe light curtains and two-hand control systems, generating replacement demand across aging machine tool fleets.
- Energy-Efficiency Benchmarking:Germany's KBA and US EPA industrial energy programs reward servo-electric installations with accelerated depreciation allowances, pulling capital allocation away from conventional hydraulic architectures.
- Yangtze River Delta Cluster Upgrades:Chinese metalworking fabricators are systematically replacing mechanical press brakes with CNC-controlled systems to serve export-oriented automotive component contracts.
Market Restraints
- Specialized Servo Drive Supply Concentration:High-torque servo motors and precision ball screws for press brake applications concentrate among Japanese and German component suppliers, exposing OEMs to 16-24 week lead time volatility.
- Skilled CNC Programming Talent Scarcity:Offline programming and automatic tooling database management require operators trained in G-code adaptation and CAD/CAM integration, functions where vocational pipeline output lags equipment installation rates.
- Titanium Grade Forming Cost Structure:Aerospace-grade titanium bending demands specialized die materials and force-calibration protocols that multiply per-unit tooling costs versus standard sheet metal applications.
Strategic Opportunities
- Pay-Per-Use Financing Expansion:Asset-light leasing models for high-tonnage press brakes narrow the competitive gap between established multinationals and mid-tier regional suppliers across Middle Eastern general fabrication markets.
- Carbon Border Adjustment Mechanisms:EU Green Deal implementation creates regulatory tailwind for electric press brake procurement by embedding embodied carbon calculations into total-cost-of-ownership evaluations for imported metal components.
- Medical Device Enclosure Fabrication:FDA standards for surgical instrument and diagnostic equipment housings create certified demand for precision bending with documented force-traceability and surface finish compliance.
Industry Challenges
- Legacy Hydraulic System Integration Complexity:Fabricators with mixed fleets face protocol mismatches between analog hydraulic controls and digital servo-electric networks, complicating shop-floor data unification for predictive maintenance.
- CE Marking Certification Timeline Compression:European Machinery Directive enforcement demands third-party conformity assessment for safety-critical control systems, extending new product introduction cycles by 4-8 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Press Brakes Market |
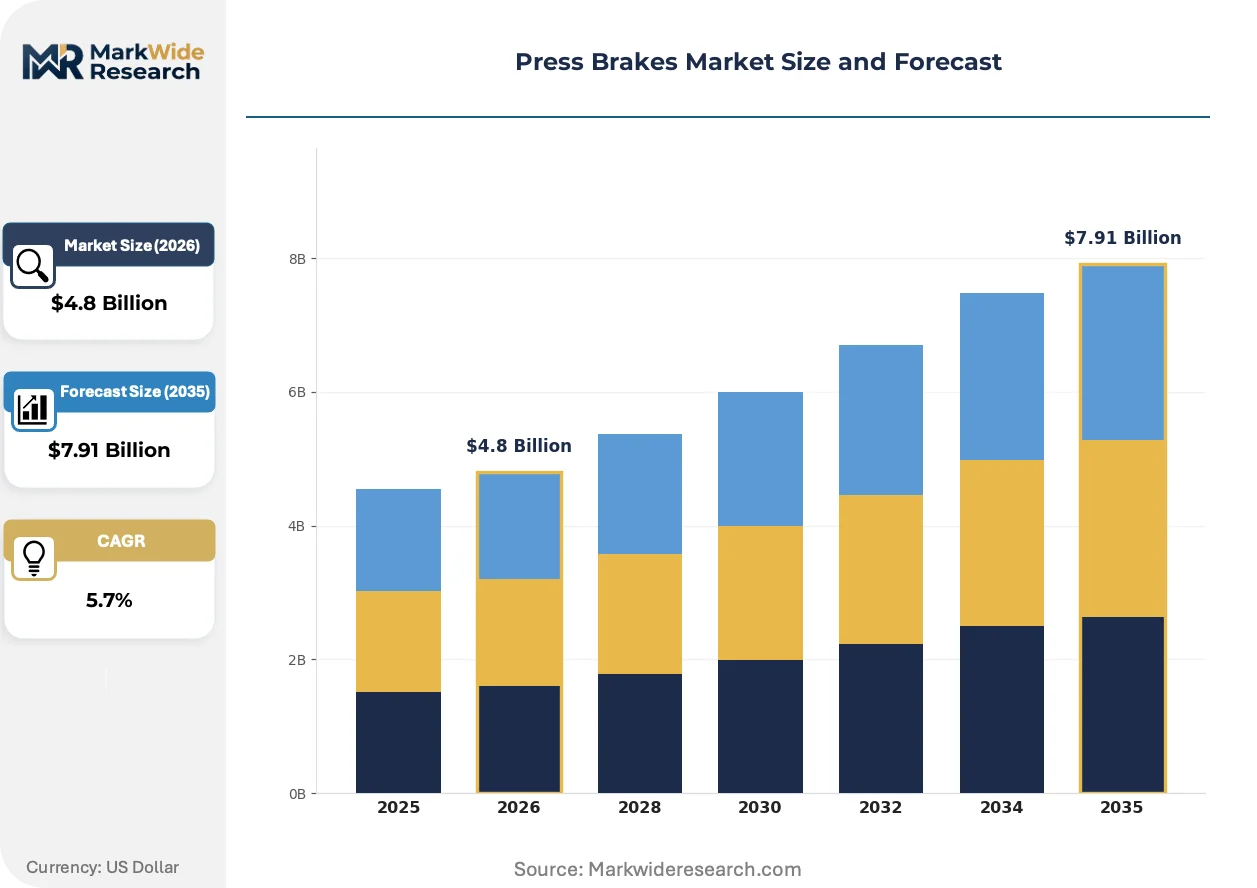
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Press Brakes, Mechanical Press Brakes, Electric Press Brakes, CNC Press Brakes Technology: Software-Controlled, Manual, Servo-Electric, Hybrid End User: Automotive Manufacturers, Aerospace Industry, Construction, General Manufacturing Application: Metal Forming, Sheet Metal Bending, Stamping, Fabrication |
| Companies Covered | Trumpf, Amada, Bystronic, Accurpress, Salvagnini, Wila, Prima Power, Baykal Makina, Accurl, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Press Brakes Market Emerging Trajectories
Software-controlled functionality is capturing disproportionate margin pools as automated tool change databases and offline programming capabilities compress setup intervals and reduce operator-dependent variability.
Closed-loop feedback systems with 0.01 millimeter positional accuracy are digitizing quality assurance protocols across automotive body panel stamping. Tier-1 suppliers in Germany and the United States are mandating these systems for new equipment purchases. Real-time bend angle verification is eliminating post-process inspection stations and reducing scrap rates in high-volume production environments.
EU Machinery Directive amendments are compelling integrated laser-safe light curtains and two-hand control architectures as standard configurations rather than optional retrofit kits. European OEMs must redesign guard systems around Category 3 safety PLCs. Asian exporters targeting European automotive supply chains are accelerating CE marking compliance to maintain contract eligibility.
After-sales service unbundling is fragmenting traditional equipment vendor relationships across North American job shop segments. Independent service providers now offer remote diagnostics and predictive maintenance subscriptions separate from original equipment procurement. This pattern concentrates in the US Great Lakes manufacturing corridor where multi-brand machine tool fleets dominate capital equipment portfolios.
Press Brakes Market Segmentation
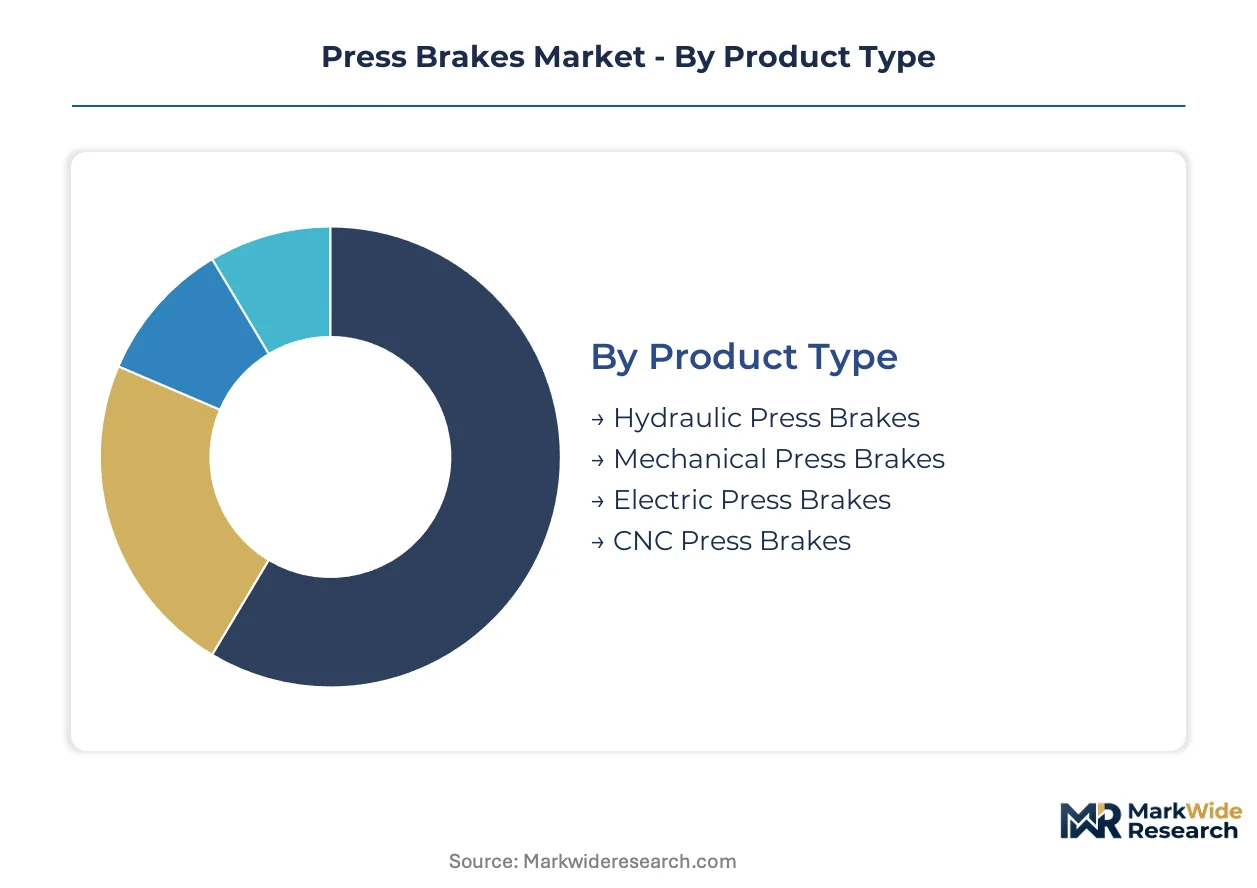
Press brake segmentation reveals distinct technology maturity curves and margin architectures. Product type and technology categories split along energy-efficiency compliance timelines, while end-user and application dimensions map directly to force-calibration requirements and tooling cost structures.
Product Type:
Mature hydraulic architectures coexist with emerging electric platforms as fabricators navigate energy-recovery mandates and maintenance cost trade-offs.
- Hydraulic Press Brakes:Fluid-powered force generation dominates installed bases across North American job shops. German automotive stampers and US Great Lakes fabricators face ISO 16092 retrofit deadlines driving replacement demand.
- Electric Press Brakes:Servo-motor actuation with regenerative braking captures German KBA and US EPA incentive programs. Yangtze River Delta metalworkers specify these for export-contract compliance.
- Mechanical Press Brakes:Flywheel-driven systems persist in price-sensitive African and Middle Eastern general fabrication.
- CNC Press Brakes:Closed-loop positioning with automatic tool databases commands premium positioning in aerospace-grade titanium forming.
Hydraulic press brakes handle the majority of throughput; electric press brakes are expanding most quickly on share.
Technology:
Cost tier stratification separates premium software-integrated systems from basic manual configurations across customer portfolios.
- Software-Controlled:Offline programming and automatic tooling databases compress setup intervals. Tier-1 automotive suppliers in Germany mandate these for body-panel stamping contracts.
- Servo-Electric:Precision ball-screw positioning achieves 0.01 millimeter accuracy for aerospace force-calibration protocols. Japanese and German component supply concentrates expose OEMs to lead-time volatility.
- Manual:Hand-crank adjustment persists in low-volume job shops with intermittent bending requirements.
- Hybrid:Dual hydraulic-electric architectures bridge energy-efficiency targets with high-tonnage forming needs.
Software-controlled technology commands the steepest margin expansion; servo-electric adoption is climbing the fastest among new installations.
End User:
Application-specific force requirements and certification protocols segment demand across customer types with divergent tooling investment appetites.
- Automotive Manufacturers:High-volume body-panel stamping with real-time bend-angle verification eliminates post-process inspection. German and US producers anchor equipment procurement volumes.
- Aerospace Industry:Titanium-grade forming demands specialized die materials and documented force-traceability. Per-unit tooling costs multiply versus standard sheet applications.
- Construction:Structural framing elements utilize mid-tonnage systems with shorter duty cycles.
- General Manufacturing:Diverse batch production favors flexible CNC configurations with rapid tool-change capability.
Automotive manufacturers absorb the largest equipment volume; aerospace applications generate the highest per-unit value.
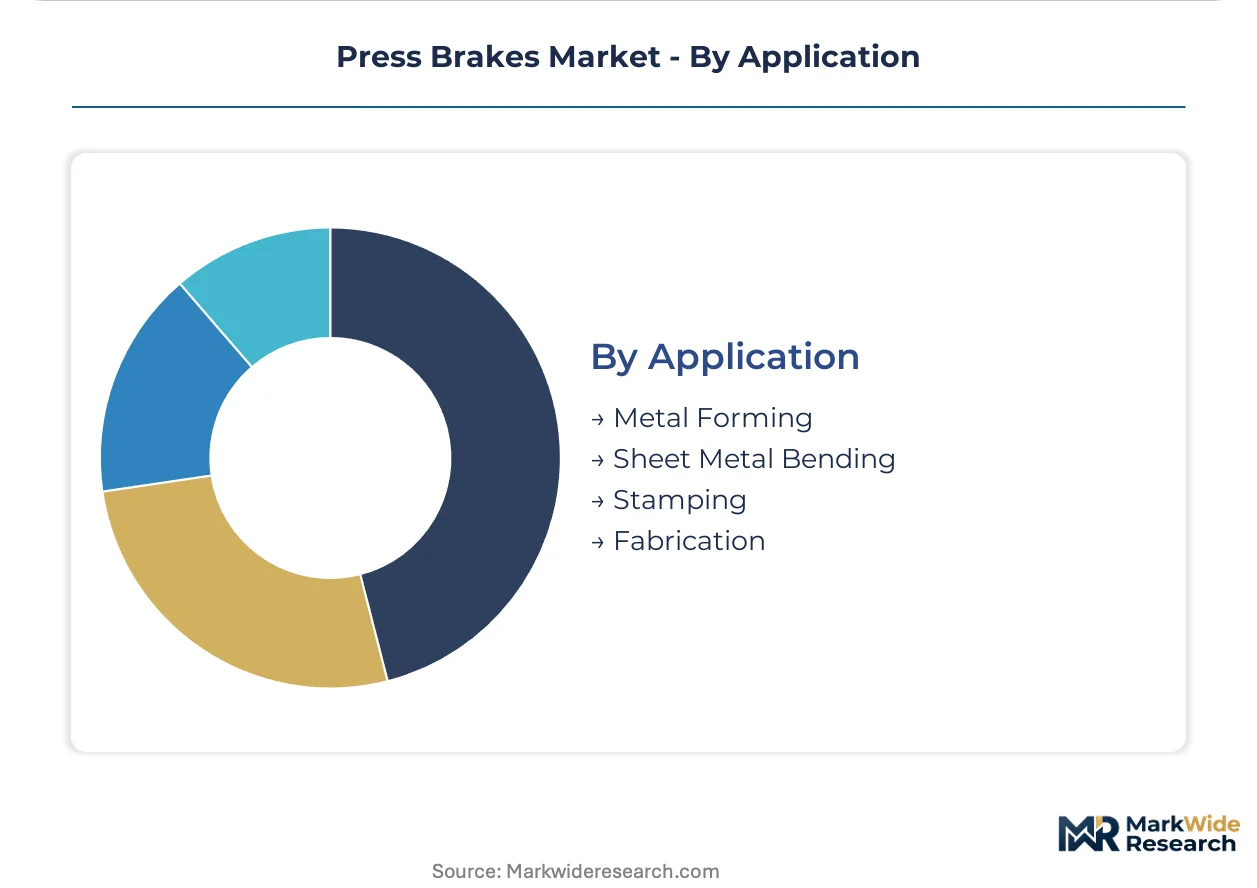
Application:
Volume concentration in sheet metal bending contrasts with specialized margin pools in precision stamping and fabrication workflows.
- Sheet Metal Bending:Thin-gauge forming for appliance and enclosure production absorbs the largest process volume. China's export-oriented fabricators drive CNC upgrade cycles.
- Metal Forming:Heavy-plate bending for industrial equipment frames requires high-tonnage force capacity. Leasing models expand access for mid-tier regional suppliers.
- Stamping:High-speed repetitive forming with dedicated die sets serves automotive mass production.
- Fabrication:Custom job-shop work with frequent changeovers prioritizes programming efficiency and setup reduction.
Sheet metal bending handles the majority of throughput; metal forming is gaining share fastest among capital-intensive applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese precision-equipment corridors, while Chinese fabricators compete on volume throughput in the Yangtze River Delta. This asymmetry shapes capital allocation patterns across automotive stamping and aerospace forming applications.
United States
Automotive body-panel stamping drives equipment procurement across Michigan and Ohio manufacturing corridors. OSHA machine-guarding mandates and EPA industrial energy programs accelerate servo-electric retrofits in aging Great Lakes fabricator fleets. Chicago-area job shops dominate multi-brand machine tool portfolios that fragment traditional vendor relationships.
Germany
Tier-1 automotive suppliers mandate closed-loop positioning systems for new press brake installations. KBA energy-efficiency benchmarking rewards servo-electric architectures with accelerated depreciation allowances. Stuttgart and Munich industrial clusters anchor European demand for CNC-controlled systems with automatic tooling databases.
China
Export-oriented automotive component contracts pull CNC upgrade cycles across metalworking fabricators. MIIT industrial equipment standards and dual carbon goals pressure mechanical system replacements. The Yangtze River Delta cluster systematically transitions from mechanical to CNC-controlled press brakes for contract compliance.
Japan
High-torque servo motor and precision ball screw supply concentrates among domestic component specialists. METI energy-recovery technology programs shape OEM product development priorities. Nagoya-area industrial machinery producers face 16-24 week lead time volatility for specialized drive components.
India
General fabrication demand concentrates in price-sensitive tier-2 and tier-3 manufacturing centers. BIS equipment safety standards and PLI scheme incentives for capital goods shape procurement decisions. Gujarat and Maharashtra metalworking clusters absorb mid-tonnage hydraulic systems for construction framing applications.
Press Brakes Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in servo drives and precision motion control. The vendor base separates into consolidated multinational CNC platform providers, regional scale manufacturers serving price-sensitive tiers, and specialized die and tooling suppliers. Three archetypes dominate: technology-integrated premium platform builders, manufacturing-scale regional competitors, and captive financing-enabled market anchors. M&A activity concentrates in servo-electric drive technology acquisition, while geographic expansion targets Middle Eastern and African general fabrication markets through asset-light leasing structures.
Among Germany-based platform integrators, Trumpf and Amada occupy positions as technology-integrated premium providers. Trumpf leverages captive financing programs to anchor CNC installations across European automotive stamping operations. Amada exemplifies in-house servo-electric development capability that reduces energy draw per bending cycle. Baykal Makina represents the manufacturing-scale regional competitor archetype, competing on production volume in price-sensitive Middle Eastern and African markets.
| Leading Market Players |
|---|
| Trumpf |
| Amada |
| Bystronic |
| Accurpress |
| Salvagnini |
| Wila |
| Prima Power |
| Baykal Makina |
| Accurl |
| Others |
Supply Flow & Price Mechanics
Japanese and German servo motor suppliers anchor upstream component availability, concentrating margin capture in precision drive systems while downstream fabricators compete on configured-system pricing and aftermarket service bundling.
Pricing Analysis
Configured-to-order CNC press brakes command substantial premiums over standard hydraulic configurations, with pricing stratifying across premium, standard, and economy tiers based on software integration depth and CE marking certification status. Price differentiation hinges on closed-loop positioning accuracy and automatic tooling database sophistication, with automotive Tier-1 suppliers showing lowest price sensitivity due to contract-mandated quality protocols. Cost compression in mid-tonnage hydraulic systems is intensifying because Chinese fabricators expand manufacturing scale. General fabrication job shops in India and the Middle East exhibit highest price sensitivity, driving demand for leasing structures over capital purchase.
Supply Chain Analysis
High-torque servo motors and precision ball screws feed from concentrated Japanese and German component specialists, with final system assembly distributed across German, Chinese, and Turkish production hubs. Raw material dependencies span specialized steel alloys for machine frames, rare-earth magnets for servo motors, and hardened die steels for tooling sets. Single-source vulnerability concentrates in precision ball screw manufacturing, where two domestic Japanese suppliers dominate aerospace-grade specifications. Distribution runs through direct OEM sales forces for large automotive accounts and regional distributor networks for job shop segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of G-code adaptation skills and CAD/CAM integration talent constrains equipment utilization rates, creating competitive advantage for vendors who bundle training with system procurement.
For Market Incumbents: Harden technology leadership by deepening in-house servo-electric drive development, insulating against Japanese component supply volatility. Anchor European automotive contracts through captive financing programs that extend replacement cycles. Defend against emerging Chinese CNC platform competitors by accelerating CE marking certification timelines for safety-critical control systems. For New Entrants and Emerging Players: Pursue white-space expansion in Middle Eastern and African general fabrication markets through asset-light leasing structures that bypass capital-intensive balance sheet requirements. Target price-sensitive tier-2 metalworking centers in India where BIS equipment standards create compliance barriers for unestablished suppliers. Enter through hybrid hydraulic-electric architectures that bridge energy-efficiency mandates with high-tonnage forming needs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional CNC platform specialists seeking exit liquidity after technology consolidation phases. Five-to-ten year viability favors vendors with integrated software-control stacks rather than pure hardware manufacturers exposed to commodity margin erosion. Monitor carbon border adjustment mechanism implementation schedules as inflection indicators for electric press brake procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Electric Drive Acquisition | Captures Japanese and German component technology to reduce energy draw per bending cycle. |
| Captive Financing Program Expansion | Anchors premium CNC installations across European automotive stamping operations against regional competitors. |
| CE Marking Certification Acceleration | Compresses new product introduction cycles to maintain contract eligibility with EU automotive supply chains. |
| Software-Controlled Platform Integration | Bundles offline programming and automatic tooling databases that compress setup intervals for Tier-1 suppliers. |
| Regional Manufacturing Footprint Expansion | Establishes Turkish or Chinese assembly presence to serve Middle Eastern and African price-sensitive markets. |
Methodological Framework
Desk research of trade association filings, customs and machinery export databases, and OEM technical documentation preceded structured interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads. Primary fieldwork captured equipment utilization patterns, retrofit timelines, and technology migration intentions across automotive stamping and aerospace forming operations. Secondary validation drew from SEC filings of listed industrial machinery producers, METI energy-recovery technology program disclosures, and KBA industrial equipment registration data. Bottom-up demand modeling triangulated against top-down production capacity assessments.
Assumption sets held regulatory enforcement timelines and carbon border adjustment implementation schedules fixed while varying capital expenditure sensitivity across end-user segments. Volume and value outputs across the analysis window reflect segment-level modeling across product type, technology tier, end-user industry, and application workflow dimensions. CAGRs were derived from equipment installation rate trajectories and replacement cycle compression patterns, with specific inputs including MIIT industrial equipment standard adoption curves and Yangtze River Delta cluster upgrade announcements.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles, automotive production volumes, or aerospace build rates would shift the trajectory. Forecasts reflect documented assumptions regarding energy-efficiency incentive program continuity and ISO 16092 enforcement rigor. Cross-checking against machinery order backlogs reported by national industrial associations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Compact Track Loader Market
Construction Equipment
Sandblasting Machines Market
Construction Equipment
US Waterjet Cutting Machines Market
Construction Equipment
Track Laying Equipment Market
Construction Equipment
Water Sprinkler Market
Construction Equipment
Industrial Agitators Market
Construction Equipment
Cutting and Bending Machine Market
Construction Equipment
Metal Machinery Market
Construction Equipment
Vibratory Plate Compactors Market
Construction Equipment
Truck Mounted Concrete Mixer Market
Construction Equipment
Global Welding Market
Construction Equipment
Compact Loaders Market
Construction Equipment
Smelting Furnace Equipment Market
Construction Equipment
Global Seam Welding Machine Market
Construction Equipment
Crane Rail Market
Construction Equipment
Inflatable Ramps Market