
 Fragrance-Free Skin Care Products Market | 2026-2036
Fragrance-Free Skin Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Fragrance-Free Skin Care Products Market Foresight
The dermatology clinic channel is restructuring its procurement priorities toward clinically validated fragrance-free protocols. CeraVe anchors its position through therapeutic-grade moisturizers developed with ceramide-dominant formulations. Drunk Elephant competes via biocompatible ingredient architectures that eliminate essential oils and synthetic masking agents. Paula’s Choice differentiates through transparent labeling standards and acid-based treatments engineered without aromatic additives.
Fragrance-free skin care products are topical formulations manufactured without added perfume compounds, masking agents, or essential oils, typically validated through dermatological testing for non-irritancy thresholds. These products serve consumers with contact dermatitis, rosacea, eczema, or fragrance sensitivities by eliminating a primary class of cutaneous irritants from daily regimens. Moisturizers occupy the largest volume position within product type segmentation due to their daily-use frequency and broad demographic applicability. Serums represent the fastest-expanding category as consumers seek concentrated active delivery without aromatic compromise. The sensitive skin treatment application commands premium pricing power through clinical validation requirements and prescriptive channel access.
The FDA oversees cosmetic labeling through the Fair Packaging and Labeling Act while the EPA monitors environmental claims related to fragrance-free positioning. The EU's REACH framework restricts twenty-six known allergenic fragrance substances, directly shaping formulation requirements for products entering European distribution. Dermatology clinics and online retailers must monitor evolving regulatory divergence between FDA cosmetic oversight and stricter EU hazard classification standards.
Market Dynamics
The EU's REACH regulation restricting twenty-six allergenic fragrance substances is forcing reformulation across export-oriented manufacturers, compressing product development timelines and elevating compliance costs throughout the value chain.
Growth Catalysts
- REACH Framework:The EU's restriction on allergenic fragrance compounds creates mandatory product redesign that validates fragrance-free positioning as a compliance-ready category for European distribution.
- Dermatology Clinics:Professional channels are expanding procurement of clinically validated fragrance-free protocols as patient sensitivity documentation mounts and insurance reimbursement patterns solidify.
- Ceramide-Dominant Formulations:Therapeutic-grade moisturizers incorporating lipid-replenishing technologies address barrier dysfunction in eczema and rosacea populations without aromatic masking agents.
Market Restraints
- Raw Material Concentration:Specialty-grade ceramides and non-irritant preservatives concentrate supply among German and Japanese chemical manufacturers, creating input vulnerability.
- Formulation Cost Structure:Fragrance-free protocols require higher-purity base ingredients and extended stability testing, elevating unit economics relative to conventional skincare.
- Consumer Perception Gap:Absence of scent signals reduced efficacy to some buyers, requiring educational investment that compressed-margin entrants cannot sustain.
Strategic Opportunities
- Serum Category Expansion:Concentrated active delivery formats without aromatic additives command premium positioning as consumers seek treatment-grade home care.
- Online Direct Distribution:E-commerce platforms enable transparent ingredient disclosure and educational content that converts skeptical buyers through detailed dermatological validation.
- Clean Beauty Retail Penetration:Specialty retailers in the United States are dedicating shelf space to verified fragrance-free assortments, creating channel access for validated entrants.
Industry Challenges
- Dermatological Testing Bottlenecks:Non-irritancy validation through patch testing and repeat insult protocols extends time-to-market by four to six months.
- Cross-Border Labeling Divergence:FDA cosmetic oversight under the Fair Packaging and Labeling Act conflicts with stricter EU hazard classification standards, complicating unified product architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fragrance-Free Skin Care Products Market |
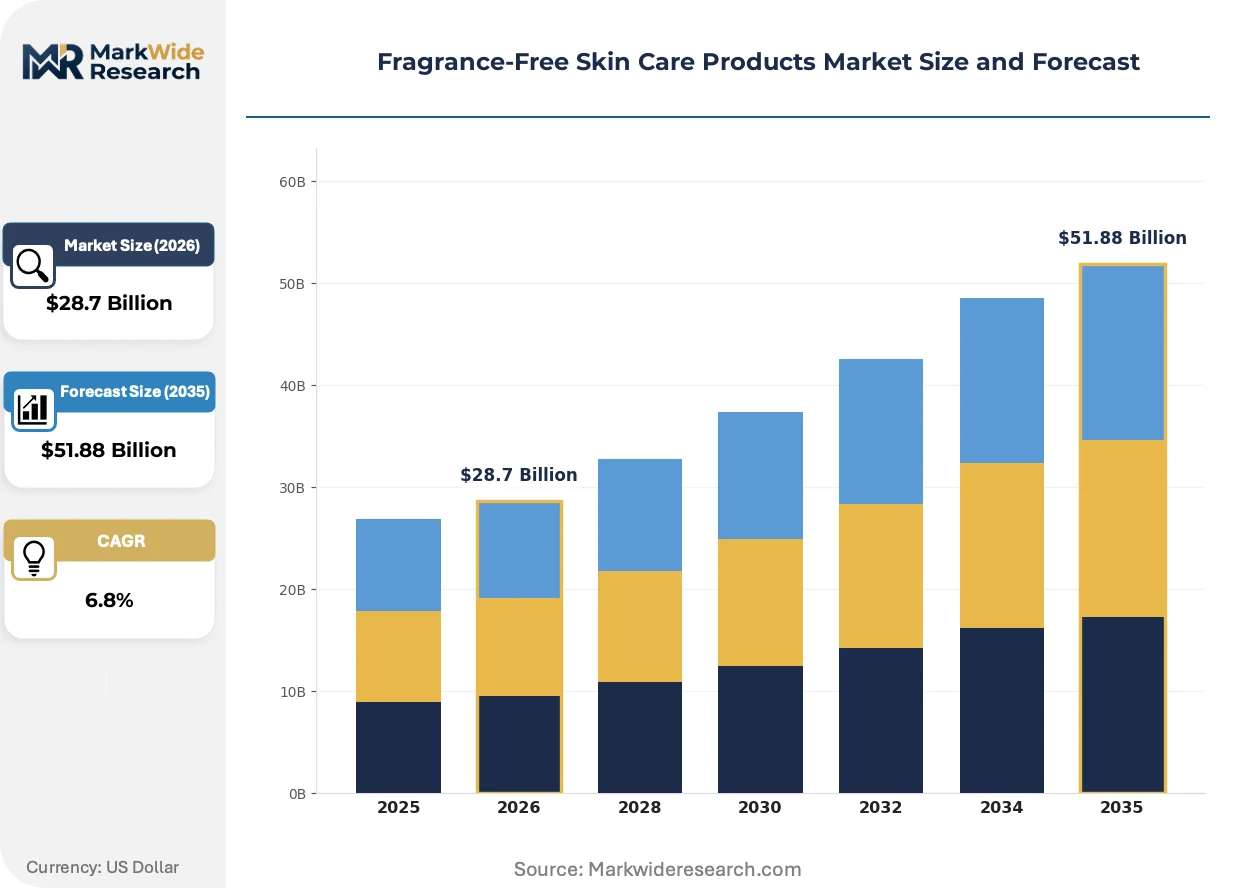
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Sunscreens, Cleansers, Serums, Toners Application: Anti-Aging, Sensitive Skin Treatment, Hydration, Eczema Relief, Acne Management End User: Dermatology Clinics, Spas & Wellness Centers, Pharmacies, Online Retailers Packaging Type: Tubes, Jars, Bottles, Pumps, Sachets |
| Companies Covered | Drunk Elephant, SkinFix, CeraVe, Tata Harper, True Botanicals, Cetaphil, Clinique, Weleda, Paula’s Choice, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fragrance-Free Skin Care Products Market Shifts & Advancements
Biocompatible ingredient architectures are displacing traditional preservation systems, while regulatory convergence between FDA and EU frameworks forces anticipatory compliance design. Distribution channels fragment between clinical endorsement and direct-to-consumer education platforms.
Microbiome-supportive formulations are absorbing research investment from major personal care laboratories. Dermatology clinics and sensitive-skin-focused retailers are adopting these systems at accelerated pace. The technology is absorbing market share from essential-oil-based alternatives by demonstrating measurable barrier repair outcomes without aromatic compromise.
REACH's restriction mechanism is tightening enforcement through 2025-2026 compliance windows. Export-oriented manufacturers must reformulate legacy stock or abandon European distribution. Fragrance-free moisturizers and treatment serums face the steepest reformulation burden given their volume exposure to EU markets.
Ingredient transparency platforms are compressing consumer decision cycles. Buyers now cross-reference product claims against independent databases before purchase. This behavioral shift concentrates demand in the United States and Nordic markets where digital literacy and clean beauty retail infrastructure align.
Fragrance-Free Skin Care Products Market Segmentation
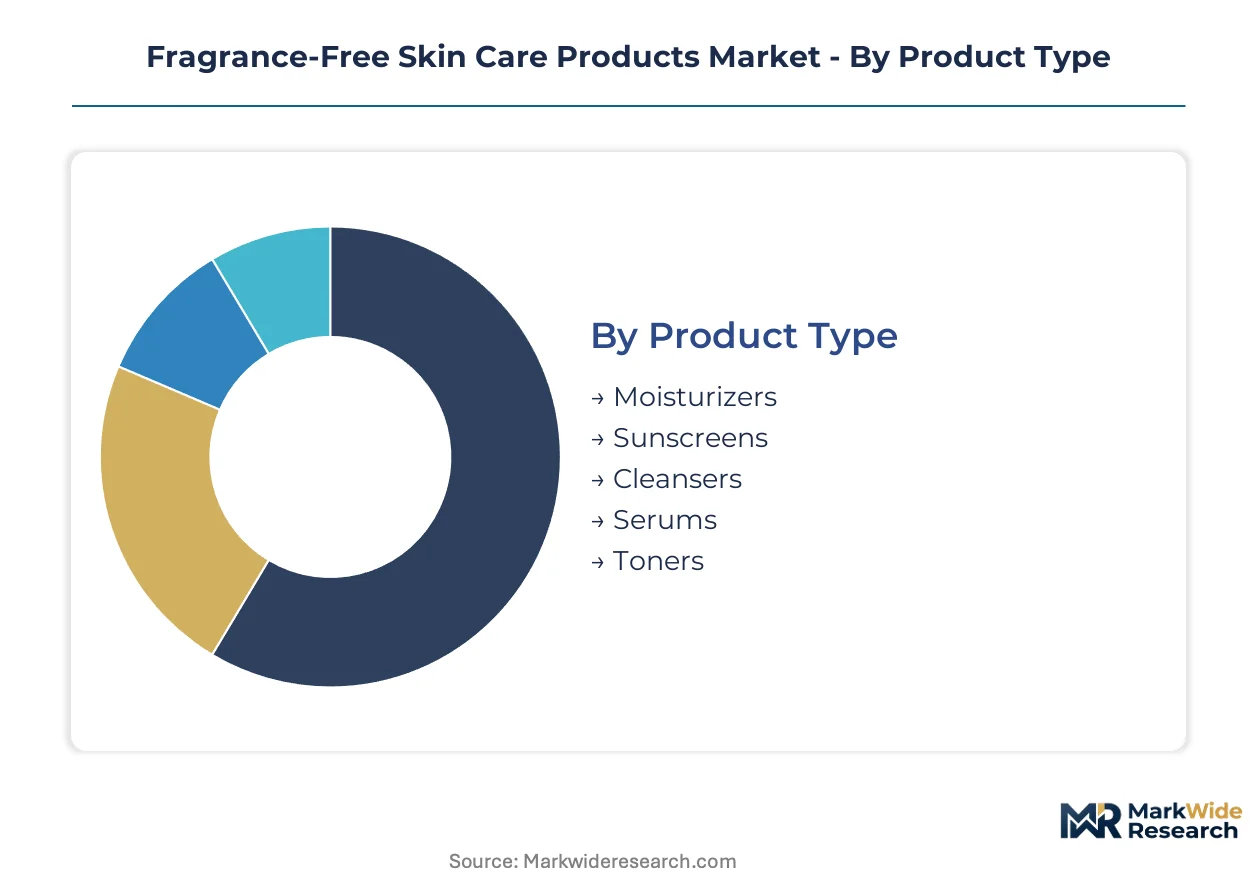
Fragrance-free formulations require precise technical segmentation because irritant thresholds vary dramatically by delivery format and clinical context. Manufacturers must align R&D investment with the specific barrier dysfunction or sensitivity mechanism each segment addresses.
Product Type:
Moisturizers attract the widest demographic cross-section, while serums capture consumers seeking concentrated actives without aromatic masking.
- Moisturizers:Ceramide-dominant formulations replenish lipid barriers in eczema and rosacea populations. Daily-use frequency across all age brackets sustains volume leadership in the United States and Nordic markets where clinical endorsement penetration remains deepest.
- Serums:Concentrated active delivery systems—niacinamide, vitamin C, peptides—engineered without essential oils or synthetic masking agents. United States clean beauty retailers and dermatology clinics drive procurement as consumers seek treatment-grade home care protocols.
- Sunscreens:Mineral-filter formulations with non-irritant bases for photosensitive skin conditions.
- Cleansers:Surfactant systems balanced for pH compatibility without aromatic additives.
- Toners:Acid-based or hydrating preparations for barrier-supportive routines.
Volume sits with moisturizers; growth tilts toward serums.
Application:
Clinical validation requirements and prescriptive channel access determine margin structure across therapeutic positioning tiers.
- Sensitive Skin Treatment:Protocols validated through patch testing and repeat insult protocols command premium positioning. Dermatology clinics in the United States and EU distribution channels concentrate procurement as patient documentation requirements solidify.
- Eczema Relief:Barrier-repair formulations targeting atopic dermatitis populations with documented fragrance sensitivity. REACH compliance windows accelerate reformulation investment for European market access.
- Anti-Aging:Retinoid and peptide systems without aromatic compromise for mature skin segments.
- Hydration:Hyaluronic acid and glycerin-based maintenance protocols for barrier-depleted skin.
- Acne Management:Non-comedogenic, fragrance-free protocols for retinoid and benzoyl peroxide compatibility.
Margin concentrates in sensitive skin treatment; eczema relief climbs fastest on regulatory tailwinds.
End User:
Channel selection determines formulation specification depth, with clinical channels demanding extensive dermatological documentation.
- Dermatology Clinics:Professional-grade protocols with therapeutic positioning and insurance reimbursement pathways. United States clinic networks expand procurement as patient sensitivity documentation mounts and prescriptive authority consolidates.
- Online Retailers:Direct-to-consumer platforms enabling transparent ingredient disclosure and educational content conversion. Nordic and United States markets show strongest digital literacy alignment with clean beauty verification systems.
- Pharmacies:Mass-market accessibility with pharmacist endorsement for mild sensitivity management.
- Spas & Wellness Centers:Experience-oriented positioning with aromatherapy-free treatment protocols.
Procurement volume flows through dermatology clinics; online retailers gain share fastest on transparency platforms.
Packaging Type:
Preservation system requirements and contamination risk profiles shape material selection and unit economics.
- Pumps:Airless delivery systems minimize oxidation and microbial contamination for preservative-reduced formulations. Premium serums and treatment moisturizers in United States and EU markets adopt this format for stability extension.
- Tubes:Collapsible aluminum or laminate structures for hygienic dispensing of cleansers and moisturizers. Cost efficiency sustains volume across pharmacy and mass retail channels.
- Jars:Wide-mouth containers for thick balm textures requiring finger application.
- Bottles:Standard cylindrical formats with flip-cap or disc-top closures for liquid toners and cleansers.
- Sachets:Single-use foil pouches for travel and trial-size distribution.
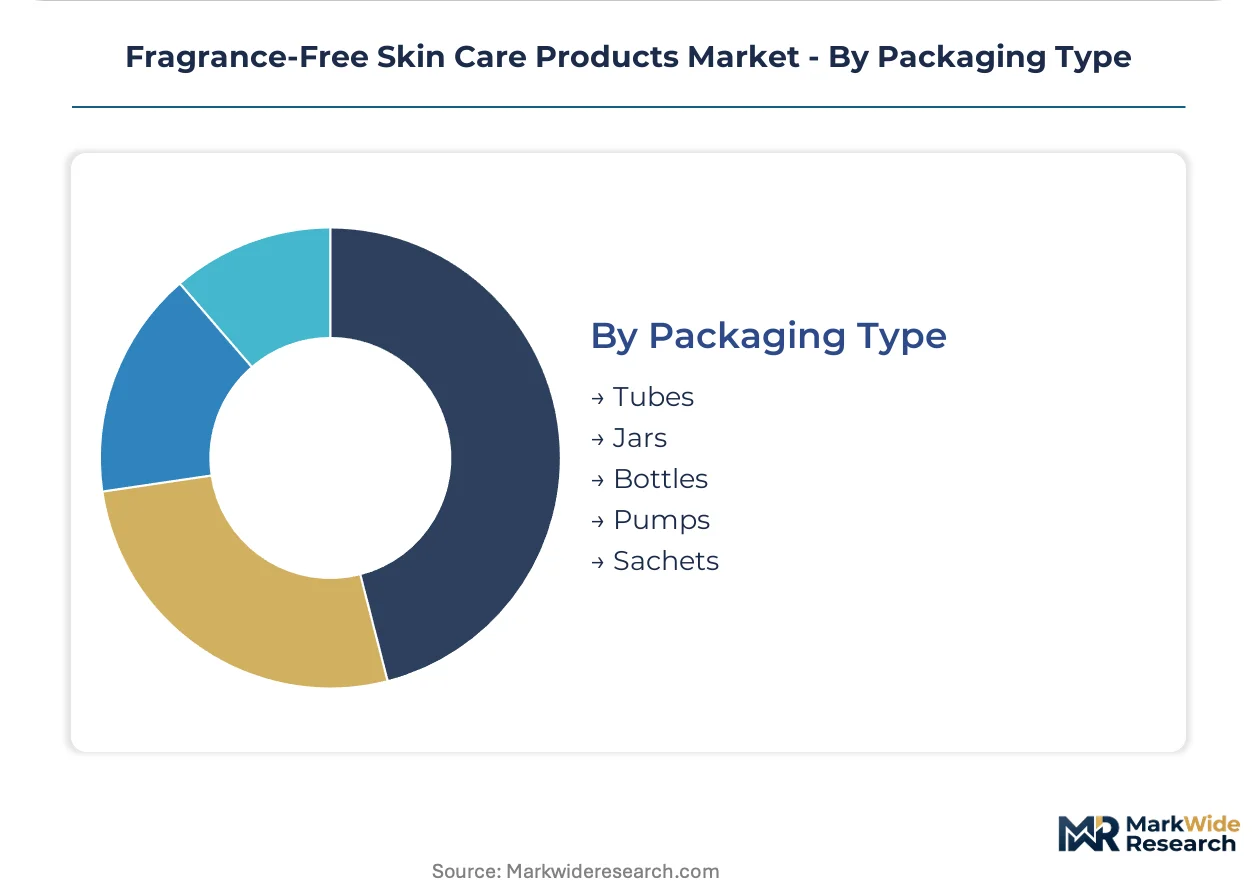
Unit economics favor tubes; pump systems expand most quickly on premium serum adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Singapore and free trade corridors in the Netherlands concentrate fragrance-free formulation facilities serving EU and Asia-Pacific distribution networks.
United States
Dermatology clinic procurement and clean beauty retail penetration drive formulation demand. FDA oversight under the Fair Packaging and Labeling Act governs cosmetic ingredient disclosure requirements. Greater Boston anchors clinical validation laboratories serving prescriptive channel networks.
Germany
ECHA enforcement of REACH's twenty-six allergenic fragrance restrictions accelerates reformulation investment. The EU Green Deal's chemical hazard classification standards shape anticipatory compliance design. North Rhine-Westphalia concentrates specialty-grade ceramide manufacturing for barrier-repair moisturizers.
United Kingdom
Online direct-to-consumer platforms enable transparent ingredient disclosure conversion. Post-Brexit regulatory divergence from EU REACH creates dual-track labeling requirements. London's specialty retail corridor dedicates shelf space to verified fragrance-free assortments.
Japan
Meti standards for cosmetic safety documentation elevate dermatological testing requirements. Aging demographics expand demand for treatment-grade home care without aromatic compromise. Osaka-Kobe industrial zones manufacture non-irritant preservative systems for export markets.
Australia
TGA therapeutic goods classification supports sensitive skin treatment premium positioning. Digital literacy alignment with clean beauty verification systems compresses consumer decision cycles. Sydney-Melbourne retail clusters adopt microbiome-supportive formulation protocols at accelerated pace.
Fragrance-Free Skin Care Products Market Competitive Landscape
Top-tier vendors anchor therapeutic-grade positioning, while mid-tier specialists compete through biocompatible ingredient architectures. The vendor base stratifies across clinical endorsement channels and direct-to-consumer transparency platforms. Dermatology-backed archetypes concentrate procurement through insurance reimbursement pathways; clean beauty archetypes convert skeptical buyers through educational content. Dominant competitive moves include portfolio diversification into serum formats and strategic partnerships with specialty retailers.
Among clinically validated specialists, CeraVe and Cetaphil exemplify therapeutic-grade archetypes through prescriptive channel presence. Drunk Elephant occupies a position within the biocompatible formulation tier, eliminating essential oils and synthetic masking agents from active delivery systems. Paula’s Choice represents transparent labeling standards, engineering acid-based treatments without aromatic additives for digitally literate consumer segments.
| Leading Market Players |
|---|
| Drunk Elephant |
| SkinFix |
| CeraVe |
| Tata Harper |
| True Botanicals |
| Cetaphil |
| Clinique |
| Weleda |
| Paula's Choice |
| Others |
Supply & Pricing Matrix
Dermatology clinic procurement concentrates demand for clinically validated fragrance-free protocols, anchoring a value-based pricing model where therapeutic-grade positioning commands premium positioning over mass-market alternatives.
Pricing Analysis
Short lead-time premiums apply to reformulated batches meeting REACH compliance windows, while spot inventory of legacy formulations trades at distressed levels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and dermatological testing depth. Pricing pressure stems from extended stability testing requirements and higher-purity base ingredient costs. Mass-market pharmacy buyers exhibit highest price sensitivity; dermatology clinics demonstrate lowest sensitivity due to insurance reimbursement pathways.
Supply Chain Analysis
Direct-to-clinic channels handle professional-grade demand, while e-commerce platforms serve digitally literate consumer segments. Specialty-grade ceramide production concentrates in Germany and Japan; non-irritant preservative systems originate from Osaka-Kobe industrial zones. Raw material dependencies include ceramide complexes, acid-stable vitamin C derivatives, and microbiome-supportive ferments. Single-source vulnerability characterizes Japanese preservative supply. Distribution runs through dermatology clinic networks, specialty retailers, and direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragrance-free skin care represents a vertical-integration race where upstream control over ceramide supply and downstream clinic channel access determine sustainable margin capture.
For Market Incumbents: Cement prescriptive channel relationships through insurance reimbursement pathway investment and clinical validation documentation. Deepen backward integration into ceramide manufacturing to offset German and Japanese supply concentration. Expand serum format portfolios to capture treatment-grade home care demand before biocompatible specialists consolidate this segment.
For New Entrants and Emerging Players: Direct-to-consumer educational platforms offer the most penetrable route for converting skeptical buyers through transparent ingredient disclosure and patch testing documentation. Target eczema relief applications where REACH regulatory tailwinds accelerate reformulation demand and incumbent switching costs remain lowest. Prioritize microbiome-supportive formulation differentiation to displace essential-oil-based alternatives.
For Investors and Strategic Acquirers: The window for entry favors clinically validated mid-cap specialists with established dermatology clinic procurement relationships and REACH-compliant formulation libraries. Long-term viability hinges on anticipatory compliance design as FDA-EU regulatory divergence widens. Monitor ECHA enforcement intensity as the primary inflection signal for reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH Compliance Reformulation | Mandatory product redesign secures European distribution access for export-oriented manufacturers. |
| Ceramide Supply Integration | Backward integration into lipid manufacturing reduces dependency on German and Japanese chemical suppliers. |
| Serum Category Expansion | Concentrated active delivery formats capture treatment-grade home care premium positioning. |
| Dermatology Clinic Partnership | Prescriptive channel access solidifies insurance reimbursement and patient loyalty pathways. |
| Microbiome Formulation Development | Barrier-repair technologies displace essential-oil alternatives with measurable clinical outcomes. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with dermatology clinic procurement directors, cosmetic chemists at formulation laboratories, retail category buyers, regulatory affairs specialists, and sensitive-skin consumer advocacy representatives. ECHA restriction databases, FDA cosmetic labeling guidance, and EU customs trade statistics provided cross-border movement validation. Bottom-up product-level modeling triangulated against top-down category spending estimates.
Data-stream reconciliation across manufacturer shipment records, retail point-of-sale tracking, and clinic procurement databases generated volume and value outputs across the analysis window. Segmentation dimensions spanned product type, application severity tier, end-user channel, and regional regulatory cluster. CAGRs derived from trend extrapolation of historical growth patterns adjusted for REACH enforcement intensity and clean beauty retail penetration curves. Forecast inputs incorporated dermatological testing bottleneck durations and ceramide supply capacity expansion timelines.
The model holds under stable REACH enforcement and continued clean beauty retail shelf space expansion; deviation in ECHA penalty severity or FDA-EU regulatory convergence would shift growth trajectories. Forecasts reflect documented assumptions regarding patient sensitivity documentation rates and insurance reimbursement pattern solidification. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Facial Mist Market
Skincare
Mineral Sunscreen Market
Skincare
Sensitive Skin Care Products Market
Skincare
Pseudo Collagen Market
Skincare
Hyaluronic Acid Personal Care Products Market
Skincare
CBD Skin Care Market
Skincare
Skin Bioactive Market
Skincare
Cosmeceuticals Market
Skincare
South Korea Anti-Acne Dermal Patch Market
Skincare
Cosmeceutical Ingredients Market
Skincare
Ultrasound Skin Cleaners Market
Skincare
Sheet Face Mask Market
Skincare
Dermocosmetics Skin Care Products Market
Skincare
Revitalizing Skin Wands Market
Skincare
Global Skin Tears Treatment Market
Skincare
Professional Skin Care Market