
 North America Tobacco Market | 2026-2036
North America Tobacco Market Size, Share, and Industry Trends Forecast 2026-2036
North America Tobacco Market Intelligence
Plant-based cellulose acetate is hardening as the dominant filter material across conventional cigarette production, displacing older acetate tow formulations with higher biodegradability profiles. Philip Morris USA leverages vertical integration across its Richmond manufacturing complex to control filter-to-finish supply chains. Reynolds American Inc. anchors its competitive stance through deep distribution relationships with convenience store networks spanning the southeastern United States. British American Tobacco p.l.c competes via specialized cigar operations that occupy distinct price tier positioning against mass-market cigarette portfolios.
Tobacco comprises cured and processed leaf from Nicotiana species, typically containing nicotine alkaloids at concentrations between 0.5% and 3% by dry weight, manufactured through flue-curing, air-curing, or fire-curing processes for inhalation or oral consumption. Cigarettes retain the largest revenue share across product type segmentation, though vapor products demonstrate the fastest structural expansion as nicotine salt formulations broaden adult user acceptance. Wholesale distributors represent a concentrated margin pool within customer type segmentation, capturing value through volume commitments and exclusive territory arrangements that downstream retailers cannot replicate.
The FDA Center for Tobacco Products enforces premarket authorization under the Family Smoking Prevention and Tobacco Control Act, while state-level excise tax regimes in California, New York, and Illinois directly shape retail price architecture and cross-border purchasing behavior. The Federal Trade Commission monitors advertising claims across emerging vapor product categories, constraining how manufacturers communicate reduced-risk positioning to adult consumers. Stakeholders must monitor pending FDA menthol prohibition rulemaking and state flavor ban expansions to anticipate portfolio restructuring requirements and manufacturing line reallocation decisions.
Market Dynamics
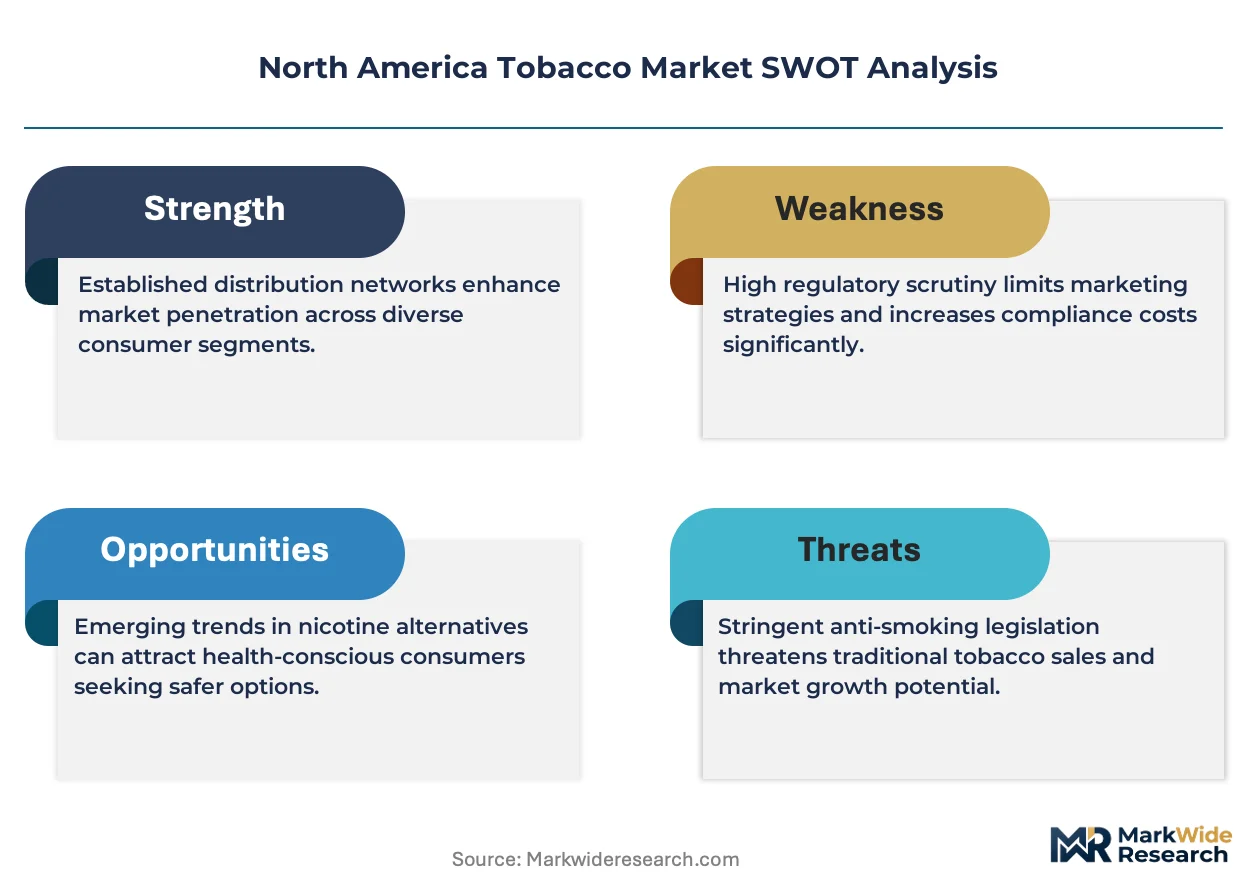
The FDA's premarket tobacco product application pathway is compressing competitive entry timelines while nicotine salt formulations in vapor products pull adult consumers away from combustible formats. This dual pressure is forcing incumbent manufacturers to reallocate capital across reduced-risk portfolios.
Growth Catalysts
- Nicotine salt technology:Formulation advances deliver smoother inhalation profiles at higher concentrations, expanding adult vapor product acceptance beyond early adopter segments.
- State excise tax differentials:Variations between California, New York, and Illinois create arbitrage opportunities for cross-border wholesale distributors capturing volume through territorial exclusivity.
- Cellulose acetate biodegradability:Plant-based filter materials with enhanced decomposition profiles respond to municipal waste management pressures in the Southeast and Midwest manufacturing corridors.
Market Restraints
- Leaf supply concentration:Flue-cured tobacco cultivation clusters in specific North Carolina and Kentucky counties expose processors to localized weather volatility and crop disease vectors.
- FDA authorization timelines:The Center for Tobacco Products' premarket review backlog extends product launch windows, freezing portfolio refresh cycles and capital deployment schedules.
- Combustible substitution:Oral nicotine pouches and heat-not-burn devices capture switching adult consumers, compressing revenue contribution from conventional cigarette formats.
Strategic Opportunities
- Mexico regulatory harmonization:Alignment with US FDA standards under USMCA provisions opens duty-advantaged manufacturing and distribution corridors for North American supply chain integration.
- Convenience store exclusive distribution:Deepened relationships with southeastern US retail networks create defensive moats against direct-to-consumer channel encroachment.
- Heat-not-burn device convergence:Integration of ceramic heating elements with precision temperature control addresses adult consumer demand for consistent nicotine delivery without combustion byproducts.
Industry Challenges
- Premarket application dossier compilation:The FDA's scientific review requirements demand toxicological studies and longitudinal usage data that extend internal R&D timelines and strain regulatory affairs staffing.
- Manufacturing line reallocation:Pending menthol prohibition rulemaking forces capital-intensive retooling decisions before regulatory certainty crystallizes, risking stranded equipment investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Tobacco Market |
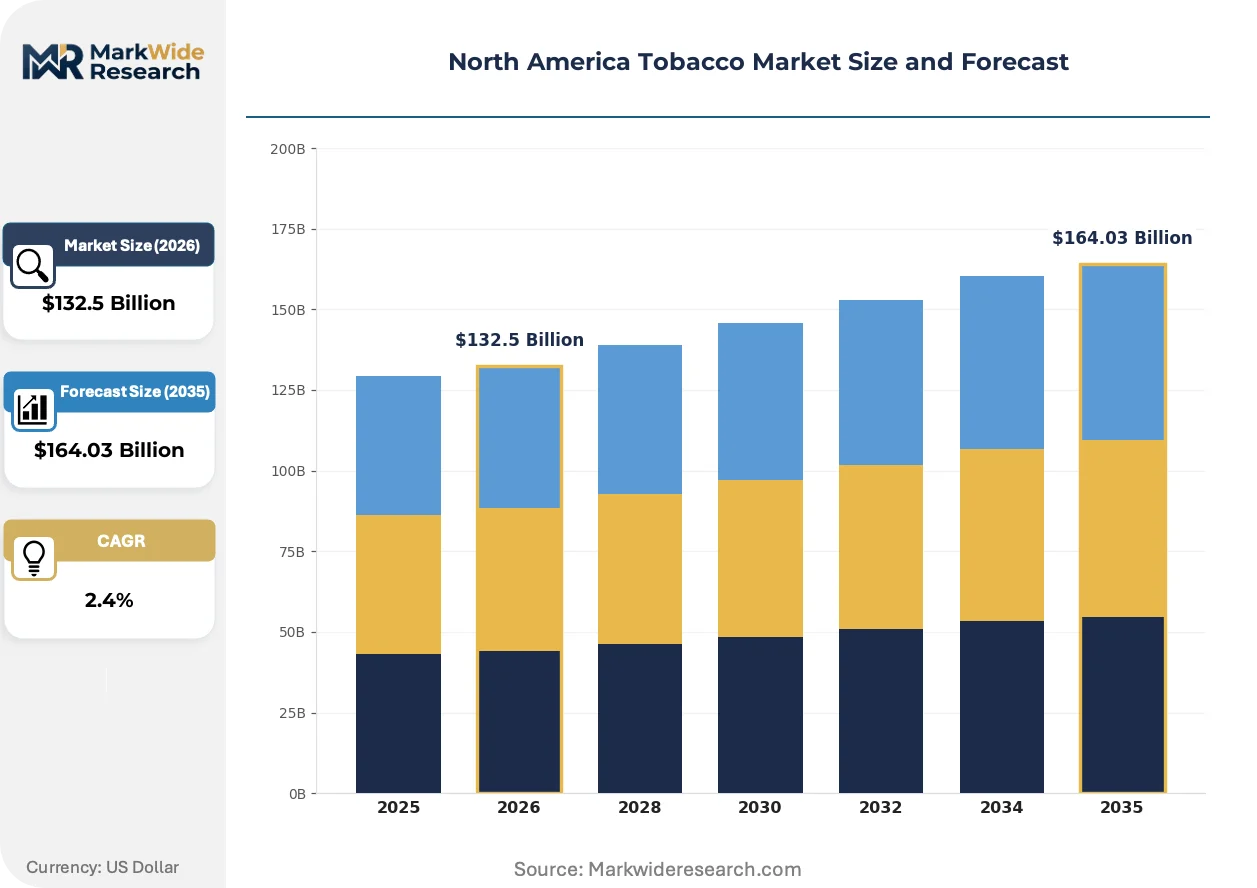
| Market Size in 2026 | $132.5 Billion |
| Market Size in 2035 | $164.03 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cigarettes, Cigars, Smokeless Tobacco, Vapor Products Customer Type: Retail Consumers, Wholesale Distributors, Convenience Stores, Online Retailers Distribution Channel: Supermarkets, Specialty Shops, Duty-Free, Pharmacies Price Tier: Premium, Mid-Range, Budget, Discount |
| Companies Covered | Altria Group, Inc., Philip Morris USA, Reynolds American Inc., British American Tobacco p.l.c, Imperial Brands plc, Japan Tobacco International, Swedish Match AB, ITG Brands, Swisher International Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Tobacco Market Strategic Shifts & Innovations
Adult consumption patterns are fragmenting across multiple nicotine delivery modalities, with technology convergence and regulatory segmentation driving parallel innovation tracks rather than single-format dominance.
Closed-system pod architectures are consolidating vapor product market structure by locking users into proprietary cartridge formats and recurring revenue streams. Adult consumers in the United States demonstrate higher retention rates with sealed systems versus open-tank alternatives. This technology is consolidating manufacturer control over liquid formulation, device calibration, and user data capture.
The FDA's pending menthol prohibition rule under the Family Smoking Prevention and Tobacco Control Act is forcing portfolio restructuring across mass-market cigarette manufacturers. State-level flavor ban expansions in California and Massachusetts create overlapping compliance jurisdictions. Combustible menthol formats face the steepest volume risk, with manufacturers accelerating heat-not-burn and oral product development pipelines.
Wholesale distributor consolidation is compressing downstream margin capture as volume commitments concentrate among fewer territorial operators. Independent retailers in the Midwest and Southeast confront exclusive supply arrangements that limit supplier diversification. This concentration is most visible in Illinois and Ohio, where distributor mergers have reduced competitive bidding for shelf space allocations.
North America Tobacco Market Segmentation
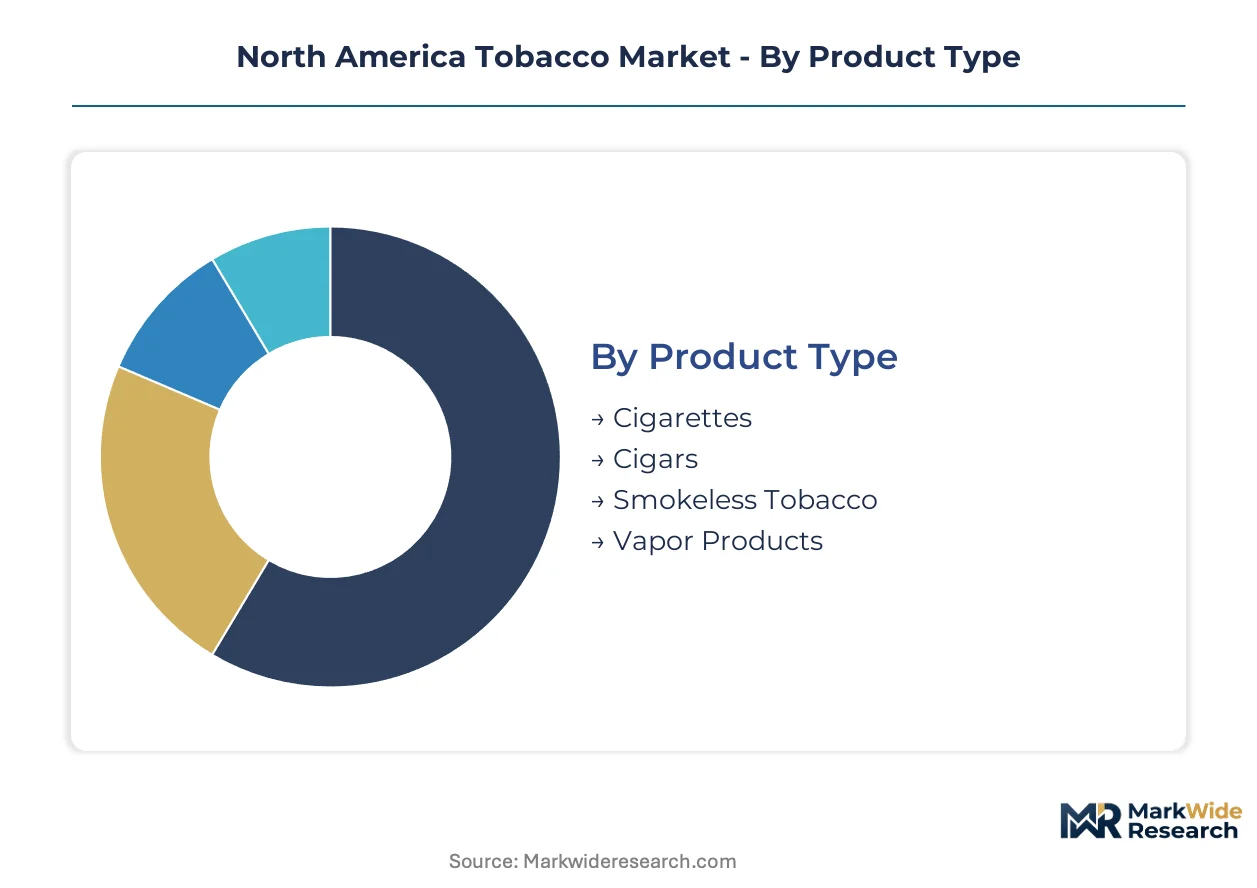
Segmentation in the North America Tobacco Market reveals how adult consumers fragment across delivery modalities and how regulatory pressure reshapes channel economics. Manufacturers must calibrate portfolio allocation across combustible, reduced-risk, and emerging formats while navigating divergent state-level compliance requirements.
Product Type:
The volume-premium split separates high-frequency combustible formats from emerging reduced-risk alternatives commanding price premiums per equivalent nicotine unit.
- Cigarettes:Flue-cured and air-cured tobacco blends dominate conventional manufacturing, with cellulose acetate filters now standard across mass-market production. Demand concentrates in the Southeast and Midwest manufacturing corridors, where state excise tax differentials between Illinois, Ohio, and neighboring jurisdictions drive cross-border wholesale arbitrage.
- Vapor Products:Closed-system pod architectures with nicotine salt formulations deliver smoother inhalation profiles at higher concentrations, pulling adult consumers from combustible formats. California and Massachusetts flavor ban expansions create overlapping compliance jurisdictions that constrain open-tank alternatives.
- Cigars:Specialized operations occupy distinct price tier positioning through fire-cured leaf and premium hand-rolling labor inputs.
- Smokeless Tobacco:Moist snuff and loose-leaf chewing varieties retain concentrated user bases in rural Kentucky and North Carolina counties with localized cultivation heritage.
Today's leader: Cigarettes. Tomorrow's challenger: Vapor Products.
Customer Type:
Channel concentration determines margin capture, with territorial exclusivity arrangements favoring volume-committed intermediaries over fragmented endpoints.
- Wholesale Distributors:Territorial operators in Illinois and Ohio capture value through exclusive supply arrangements that downstream retailers cannot replicate. Consolidation among fewer distributors compresses competitive bidding for shelf space allocations across Midwest and Southeast networks.
- Convenience Stores:Southeastern US retail networks anchor defensive moats through deepened manufacturer relationships, limiting direct-to-consumer channel encroachment. Volume commitments with Reynolds American and Philip Morris USA lock in proprietary display positioning and promotional calendars.
- Retail Consumers:Adult purchasers demonstrate channel-switching behavior driven by state excise tax differentials and municipal flavor restrictions.
- Online Retailers:Direct-to-consumer platforms face FDA premarket authorization requirements and state-specific shipping prohibitions that constrain growth relative to brick-and-mortar alternatives.
Power accrues to Wholesale Distributors. Vulnerability sits with Online Retailers.
Distribution Channel:
Regulatory visibility varies sharply across channel types, with pharmacy and duty-free formats facing distinct compliance architectures.
- Specialty Shops:Premium cigar and pipe tobacco retailers leverage knowledgeable staff and aging inventory to justify price premiums over mass-market alternatives. FDA Center for Tobacco Products enforcement actions concentrate on marketing claims in these high-touch environments.
- Supermarkets:High-volume cigarette and smokeless tobacco placement behind checkout counters generates impulse purchase velocity, though California and New York placement restrictions erode this advantage.
- Duty-Free:Cross-border arbitrage opportunities at US-Canada and US-Mexico entry points attract price-sensitive travelers from high-tax jurisdictions.
- Pharmacies:CVS and Walgreens cessation-focused policies have largely exited combustible sales, constraining this channel to nicotine replacement therapies and select reduced-risk alternatives.
Supermarkets dominate transaction volume. Specialty Shops defend margin per unit.
Price Tier:
Cost tier stratification reflects tax incidence, brand equity, and manufacturing input quality rather than pure product differentiation.
- Premium:Established brand portfolios from Philip Morris USA and British American Tobacco command shelf space through consumer recognition and distributor rebate structures. Adult consumers in the Southeast demonstrate higher loyalty coefficients to heritage brands despite state excise tax escalations.
- Mid-Range:Value-engineered products with reduced marketing expenditure capture price-sensitive switchers from premium tiers during economic pressure periods.
- Budget:Private-label and third-tier manufacturers in Kentucky and North Carolina compete on manufacturing cost minimization without national advertising support.
- Discount:Deep-discount brands and illicit cross-border products threaten tax revenue collection in New York and Illinois border counties.
Premium tiers absorb regulatory cost pass-through. Discount segments face enforcement pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Southeast and Midwest manufacturing corridors anchor North American tobacco production, with state excise tax differentials driving cross-border wholesale arbitrage and distribution network optimization across the continent.
United States
Kentucky and North Carolina counties concentrate flue-cured tobacco cultivation, supplying processors with leaf containing nicotine alkaloids at 0.5% to 3% dry weight concentrations. The FDA Center for Tobacco Products enforces premarket authorization under the Family Smoking Prevention and Tobacco Control Act, compressing competitive entry timelines. Richmond, Virginia hosts Philip Morris USA's vertically integrated manufacturing complex controlling filter-to-finish supply chains for conventional cigarette production.
Canada
Health Canada and the PMRA regulate tobacco product manufacturing standards and marketing restrictions across provincial jurisdictions. Ontario and Quebec concentrate manufacturing infrastructure serving domestic demand and duty-free export channels. Cross-border arbitrage at US-Canada entry points attracts price-sensitive travelers from high-tax American jurisdictions, particularly New York and Illinois residents.
Mexico
USMCA provisions enable regulatory harmonization with US FDA standards, opening duty-advantaged manufacturing corridors for North American supply chain integration. Northern border states concentrate production facilities serving export demand to American wholesale distributors. The Bajío Region and Mexico City Metro host processing operations for both domestic consumption and regional re-export.
North America Tobacco Market Key Industry Players
Global majors compete with regional champions across distribution network depth and regulatory compliance infrastructure. The vendor base concentrates among vertically integrated conglomerates controlling leaf procurement through finished goods distribution. Three archetypes dominate: heritage cigarette manufacturers with century-old brand portfolios, reduced-risk specialists pivoting toward heat-not-burn and oral nicotine formats, and private-label operators competing on manufacturing cost minimization. M&A activity consolidates territorial distributor networks, while portfolio diversification accelerates capital reallocation from combustible to reduced-risk categories.
Within the heritage manufacturer tier, Altria Group, Inc. and Reynolds American Inc. exemplify scale-driven positioning through deep convenience store relationships and southeastern US distribution dominance. Philip Morris USA anchors premium-tier brand equity with Richmond-based manufacturing control. These entities represent the defensive moat strategy of locking volume commitments through exclusive retail arrangements that downstream competitors cannot replicate.
| Leading Market Players |
|---|
| Altria Group, Inc. |
| Philip Morris USA |
| Reynolds American Inc. |
| British American Tobacco p.l.c |
| Imperial Brands plc |
| Japan Tobacco International |
| Swedish Match AB |
| ITG Brands |
| Swisher International Group Inc. |
| Others |
Cost & Logistics Intelligence
Flue-cured tobacco leaf costs transmit directly from North Carolina and Kentucky cultivation clusters through processor margins to wholesale distributor pricing tiers, with state excise tax differentials amplifying arbitrage opportunities across Illinois, Ohio, and neighboring jurisdictions. Cellulose acetate filter material pricing hardens as plant-based formulations displace legacy acetate tow, compressing margin capture for mid-range manufacturers while premium-tier players absorb input pass-through through brand equity.
Pricing Analysis
Input-cost pass-through from leaf procurement and filter materials shapes a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on brand heritage recognition and vertical integration depth, with Philip Morris USA and Reynolds American commanding shelf space premiums through exclusive convenience store arrangements. Cost compression in budget tiers intensifies because private-label operators lack national advertising support to defend positioning. Wholesale distributors demonstrate lowest price sensitivity due to volume commitment leverage, while retail consumers in high-tax jurisdictions like New York and California exhibit highest sensitivity with documented cross-border purchasing behavior.
Supply Chain Analysis
Workforce availability constraints in Richmond, Virginia and Winston-Salem, North Carolina manufacturing corridors tether production capacity to regional labor pool depth and specialized curing expertise. Geographic supply concentration centers on the United States for flue-cured processing, Mexico for USMCA-advantaged assembly under regulatory harmonization, and Canada for duty-free export channel positioning. Raw material dependencies draw from Kentucky burley leaf, North Carolina flue-cured varieties, and cellulose acetate tow feedstocks. Single-source vulnerability concentrates in menthol flavoring supply chains ahead of FDA prohibition rulemaking. Distribution runs through territorial wholesale operators with exclusive territory arrangements locking downstream access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Tobacco Market functions as a stable compounder, with nicotine delivery format diversification and reduced-risk portfolio expansion generating steady replacement revenue streams despite combustible volume pressure.
For Market Incumbents: Deepen exclusive distribution relationships with southeastern convenience store networks to lock proprietary display positioning against direct-to-consumer channel encroachment. Accelerate heat-not-burn device development pipelines ahead of FDA menthol prohibition rulemaking to preempt stranded equipment risk in conventional manufacturing lines.
For New Entrants and Emerging Players: The gap between premium heritage brands and deep-discount private-label offerings creates white-space opportunity for mid-range positioning with value-engineered products. Target oral nicotine pouch segments in rural Kentucky and North Carolina counties with localized cultivation heritage and concentrated smokeless tobacco user bases. Pursue regulatory compliance infrastructure investment as primary go-to-market angle, given FDA premarket authorization barriers.
For Investors and Strategic Acquirers: Consolidation pressure builds where territorial distributor networks fragment across Midwest and Southeast markets, compressing competitive bidding for shelf space allocations. Long-term viability favors reduced-risk specialists with heat-not-burn and oral nicotine capabilities over pure-play combustible manufacturers. Watch FDA menthol prohibition rulemaking timeline as inflection indicator for portfolio restructuring velocity and capital reallocation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Reduced-Risk Portfolio Expansion | Heat-not-burn and oral nicotine development captures switching adult consumers from combustible formats. |
| Exclusive Distribution Deepening | Territorial wholesale arrangements with convenience store networks create defensive moats against channel encroachment. |
| Regulatory Compliance Infrastructure | FDA premarket authorization capabilities compress competitive entry timelines and freeze rival launch windows. |
| Filter Material Biodegradability Transition | Plant-based cellulose acetate formulations respond to municipal waste management pressures in manufacturing corridors. |
| Cross-Border Arbitrage Optimization | State excise tax differentials between Illinois, Ohio, and neighboring jurisdictions enable volume capture through territorial exclusivity. |
Research Approach
Coverage spans the United States, Canada, and Mexico, with primary inputs from each jurisdiction combined with secondary validation across regulatory filings and trade databases. Primary interviews engaged regulatory affairs directors at manufacturers, wholesale distributor operations heads, convenience store category buyers, and state revenue department excise tax administrators. Secondary sources incorporated FDA Center for Tobacco Products premarket submission databases, Health Canada product licensing records, USMCA trade flow data, and SEC 10-K disclosures from publicly traded manufacturers. Bottom-up volume modeling triangulated against top-down market sizing from customs and excise revenue collections.
Rate-of-change decomposition across the analysis window separated volume trends from price realization effects, with segmentation modeling across product type, customer channel, and price tier dimensions. CAGRs derived from fitted trend analysis adjusted for regulatory inflection points including pending FDA menthol prohibition rulemaking and state-level flavor ban expansions. Industry-specific forecast inputs captured nicotine salt technology adoption curves and heat-not-burn device penetration patterns among adult combustible switchers.
Caveats apply where FDA authorization timeline delays, menthol prohibition rulemaking acceleration, or state flavor ban geographic expansion could materially shift the outlook. Forecasts reflect assumptions regarding regulatory enforcement intensity and adult consumer substitution elasticity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco
Egypt Tobacco Market
Tobacco
Tobacco Films Market
Tobacco
Cigarette Rolling Paper Market
Tobacco
Middle East and Africa Smokeless Tobacco Market
Tobacco
Heat-Not-Burn Market
Tobacco
Cigarette Paper Market
Tobacco
Tobacco Cutting Machines Market
Tobacco
Low Tar Cigarette Paper Market
Tobacco
Organic Tobacco Market
Tobacco
North America Cigarette Market
Tobacco
US Tobacco Market