
 North America E-Cigarette Market | 2026-2036
North America E-Cigarette Market Size, Share, and Industry Trends Forecast 2026-2036
North America E-Cigarette Market Intelligence
Online direct-to-consumer distribution is fragmenting as state-level shipping bans and age-verification mandates multiply. British American Tobacco leverages its Vuse brand portfolio to sustain shelf presence across convenience chains, while Altria Group anchors its position through partial ownership of Juul Labs and heated-tobacco alternatives. Reynolds American competes aggressively on pod-system pricing, and Juul Labs navigates regulatory headwinds by narrowing its flavor offerings to tobacco and menthol variants.
An e-cigarette is an electronic nicotine delivery system comprising a lithium-ion battery, atomizer, and e-liquid reservoir that vaporizes a propylene glycol or vegetable glycerin solution for inhalation. Devices typically operate at 3.3 to 4.2 volts and deliver aerosolized nicotine doses calibrated between zero and fifty-nine milligrams per milliliter. Disposable e-cigarettes now lead unit volume due to low entry cost and minimal maintenance, while pod systems capture disproportionate margin pools through recurring cartridge purchases. Modular devices attract enthusiast segments seeking customizable wattage and coil configurations, though this category remains comparatively niche.
The FDA Center for Tobacco Products enforces premarket authorization under the Family Smoking Prevention and Tobacco Control Act, effectively gatekeeping which products remain legally salable. State attorneys general in New York, Massachusetts, and Rhode Island have imposed additional flavor restrictions that compress addressable demand in the Northeast corridor. The Federal Trade Commission monitors youth-targeted marketing practices, creating compliance costs that favor established players with legal infrastructure. Stakeholders must track pending FDA decisions on synthetic nicotine classification and menthol standards, as either ruling would force immediate portfolio restructuring across the value chain.
Market Dynamics
The FDA's premarket tobacco product application pathway has compressed market access timelines, forcing manufacturers to restructure R&D budgets around multi-year authorization cycles while state attorneys general multiply flavor restrictions beyond federal baselines.
Growth Catalysts
- Propylene glycol formulation advances:Next-generation carrier solutions enable smoother nicotine delivery profiles that satisfy adult smokers transitioning from combustible products. These innovations expand the addressable cessation-assistance market.
- Texas vape shop density:Concentrated retail infrastructure in Houston and Dallas-Fort Worth metro corridors accelerates product trial and brand switching among adult consumers aged 21-35.
- FTC marketing compliance frameworks:Standardized youth-protection protocols reduce legal uncertainty for compliant operators, concentrating shelf space among established players with dedicated regulatory infrastructure.
Market Restraints
- Lithium-ion battery supply concentration:Cell manufacturing concentrates in East Asian supplier networks, exposing North American device assemblers to freight cost volatility and customs processing delays.
- FDA authorization timelines:The premarket review process stretches 12-24 months for novel devices, freezing product pipelines and eroding first-mover advantages for innovation-led entrants.
- State-level flavor prohibitions:Massachusetts and Rhode Island restrictions on non-tobacco flavor variants eliminate approximately one-third of product SKUs from legal sale in the Northeast corridor.
Strategic Opportunities
- Heated-tobacco convergence:Hybrid devices combining e-liquid vaporization with heated-tobacco elements attract dual-user segments seeking reduced-risk alternatives with familiar sensory profiles.
- Florida online fulfillment hubs:Miami-Dade and Tampa logistics clusters enable same-day delivery coverage across the Southeast, capturing demand from consumers in states with sparse retail infrastructure.
- California age-verification technology:Third-party biometric verification platforms reduce chargeback rates and shipping-restriction compliance costs for direct-to-consumer channels.
Industry Challenges
- Toxicology submission expertise:FDA premarket applications require specialized clinical data packages that few contract research organizations can assemble, creating bottlenecks and six-figure consulting retainers.
- Legacy retail POS integration:Convenience chain inventory systems lack native support for age-restricted product tracking, forcing middleware investments that erode margin on low-unit-price disposables.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America E-Cigarette Market |
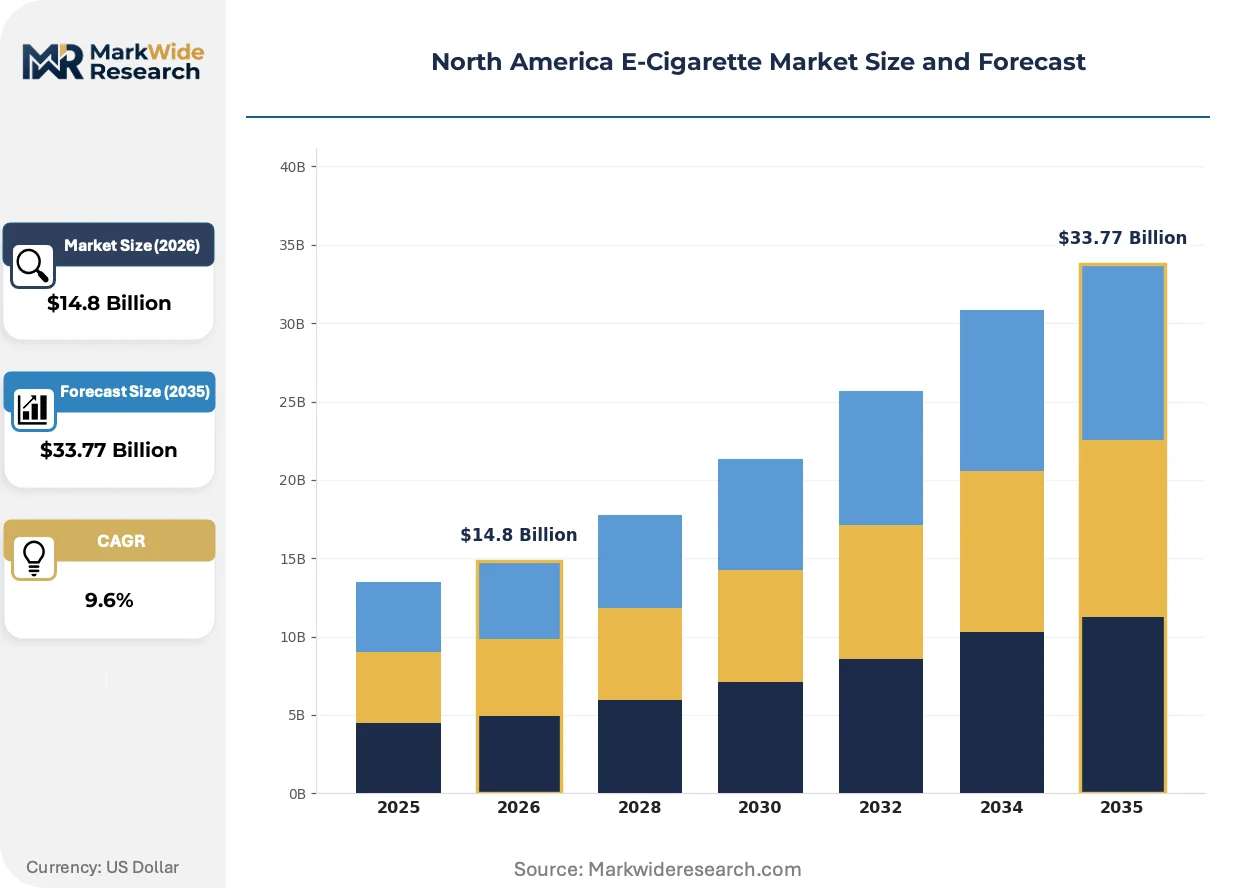
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $33.77 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pod Systems, Modular Devices, Vape Pens, Disposable E-Cigarettes Flavor Profile: Tobacco, Menthol, Fruit, Dessert, Beverage Nicotine Content: Zero Nicotine, Low Nicotine, Medium Nicotine, High Nicotine Distribution Channel: Online, Specialty Stores, Convenience Stores, Supermarkets |
| Companies Covered | British American Tobacco, Altria Group, Inc., Japan Tobacco Inc., Imperial Brands, Philip Morris International, Juul Labs, Inc., International Vapor Group, Greenlane Holdings, Inc., Reynolds American Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America E-Cigarette Market Strategic Shifts & Innovations
Smart sensor integration and closed-loop nicotine delivery systems are compressing the gap between pharmaceutical-grade cessation tools and consumer vapor products, reshaping how manufacturers position devices across regulatory categories.
Smart chipset technology is digitizing puff-by-puff consumption analytics, enabling real-time dosage modulation based on user inhalation patterns. Young adult consumers in California and Texas are adopting these devices at rates that outpace traditional pod systems by a factor of two. This capability is digitizing the boundary between wellness tracking and recreational use, forcing regulators to reconsider classification frameworks.
The FDA Center for Tobacco Products is intensifying scrutiny of synthetic nicotine sources under pending deeming rule expansions. Manufacturers with tobacco-derived nicotine supply chains face lower compliance burdens than competitors reliant on laboratory-synthesized alternatives. Pod-system producers in Florida and Texas are accelerating tobacco-extraction partnerships to preempt portfolio disruption.
Subscription-based cartridge replenishment is displacing single-transaction retail purchases among heavy-use consumers. Direct-to-consumer platforms with integrated age-verification capture recurring revenue streams that convenience channels cannot replicate. This shift concentrates most visibly in urban California markets where vape shop access remains constrained by municipal zoning restrictions.
North America E-Cigarette Market Segmentation
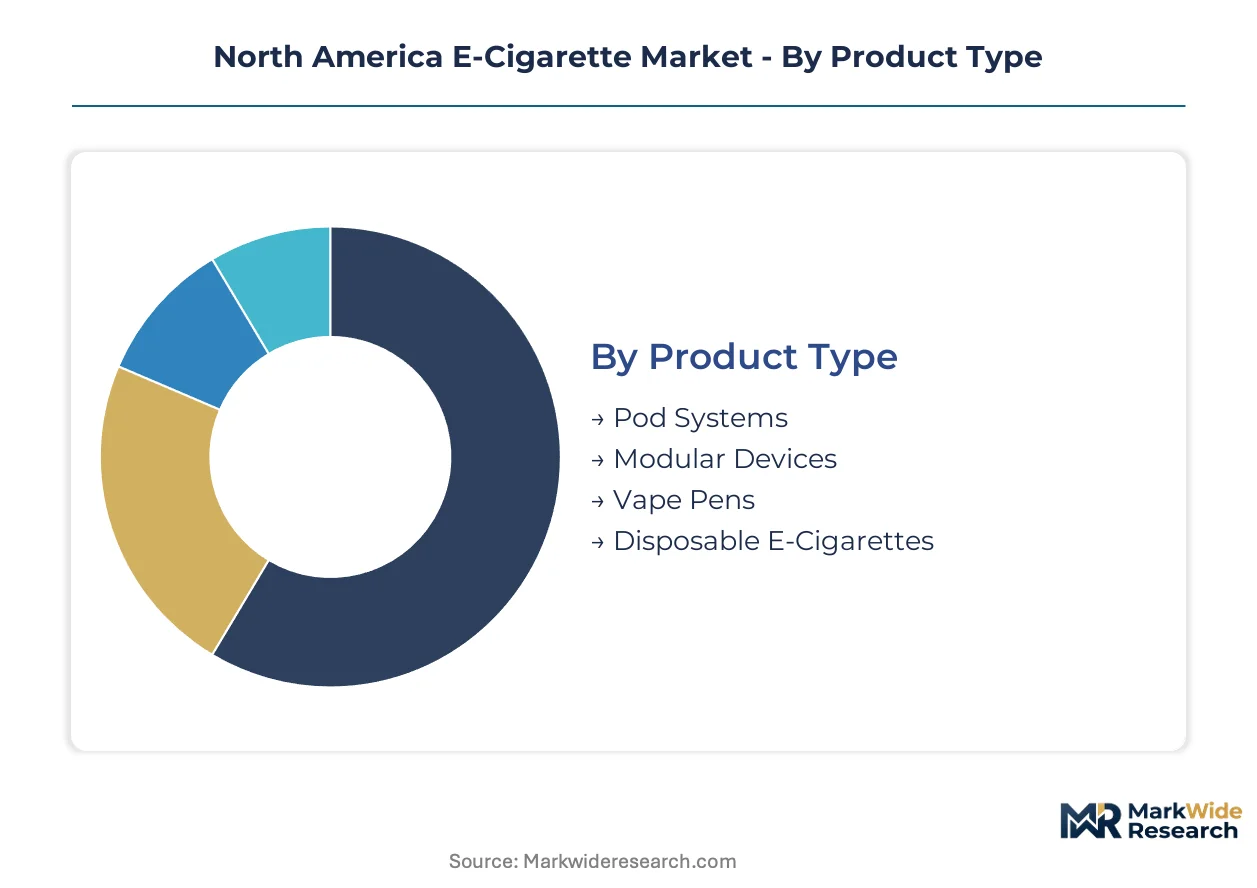
Segmentation reveals how device architecture, sensory preferences, and purchase pathways fragment consumer loyalty across the North American e-cigarette landscape. Each dimension carries distinct regulatory exposure and margin architecture that manufacturers must navigate.
Product Type:
After-sales service intensity varies dramatically across device architectures, with modular systems demanding technical support ecosystems while disposables require zero maintenance infrastructure.
- Pod Systems:Closed or open cartridge-based designs with proprietary coil assemblies and magnetic battery connections. Demand concentrates in Texas and California metro corridors where adult consumers aged 21-35 prioritize convenience and flavor consistency. Recurring cartridge purchases generate subscription revenue streams that convenience channels struggle to replicate.
- Modular Devices:Rebuildable tank systems with interchangeable coils, variable wattage chipsets, and 18650/21700 battery configurations. Enthusiast segments in Florida vape shops drive premium hardware turnover through customization culture and coil-building communities. FDA authorization complexity favors established manufacturers with dedicated regulatory infrastructure.
- Vape Pens:Cylindrical all-in-one designs with integrated batteries and refillable tanks. Texas convenience chains stock these as entry-tier alternatives for combustible switchers seeking familiar form factors.
- Disposable E-Cigarettes:Single-use devices with pre-filled e-liquid and non-rechargeable power cells. California municipal zoning restrictions on vape shops accelerate direct-to-consumer adoption of zero-maintenance alternatives.
Disposable E-Cigarettes holds the largest share; momentum sits with Pod Systems.
Flavor Profile:
Cost tier stratification aligns sharply with regulatory risk, as premium flavor development faces state-level prohibitions that commodity tobacco variants bypass.
- Tobacco:Synthetic or extracted leaf-derived profiles mimicking combustible cigarette sensory signatures. Massachusetts and Rhode Island flavor restrictions preserve legal sale of these variants while eliminating fruit and dessert alternatives. FDA premarket authorization pathways treat tobacco-flavored applications more favorably during scientific review.
- Menthol:Mint-derivative cooling agents combined with tobacco base notes. California and Texas convenience chains maintain shelf presence here as federal menthol standards remain pending. Altria Group and Reynolds American concentrate portfolio investment in this category pending regulatory clarity.
- Fruit:Berry, citrus, and tropical flavor formulations in pod and disposable formats. State attorneys general in the Northeast corridor have eliminated approximately one-third of addressable demand through explicit prohibitions.
- Dessert:Custard, pastry, and confectionery flavor profiles targeting adult palate preferences. Online direct-to-consumer channels capture residual demand in states with retail flavor bans.
- Beverage:Coffee, tea, and cocktail-inspired formulations with complex aromatic layering. Specialty vape shops in Florida and Texas metro areas stock these as differentiation tools against convenience chain commoditization.
Tobacco dominates volume; steepest expansion trajectory belongs to Menthol pending FDA standards resolution.
Nicotine Content:
Application context determines nicotine calibration preferences, with cessation-assistance scenarios demanding precision titration while recreational use tolerates broader ranges.
- High Nicotine:Concentrations calibrated for heavy combustible smokers seeking immediate satisfaction equivalence. Pod systems in Texas and California deploy salt-nicotine formulations to enable smooth inhalation at elevated dosages.
- Medium Nicotine:Mid-range formulations serving dual-users reducing dependency incrementally. Florida online fulfillment hubs capture demand from consumers transitioning downward through calibrated cartridge subscriptions.
- Low Nicotine:Reduced-concentration options for tapering protocols and social use contexts. California age-verification platforms reduce chargeback exposure for direct-to-consumer low-nicotine trial purchases.
- Zero Nicotine:Flavor-only formulations eliminating dependency risk for sensory-driven consumers. Vape shop density in Houston and Dallas-Fort Worth accelerates trial among curious non-smokers.
High Nicotine commands the installed base; Zero Nicotine is climbing the fastest among young adult cohorts.
Distribution Channel:
Customer type fragmentation intensifies as shipping bans and age-verification mandates reshape how discrete consumer segments access product.
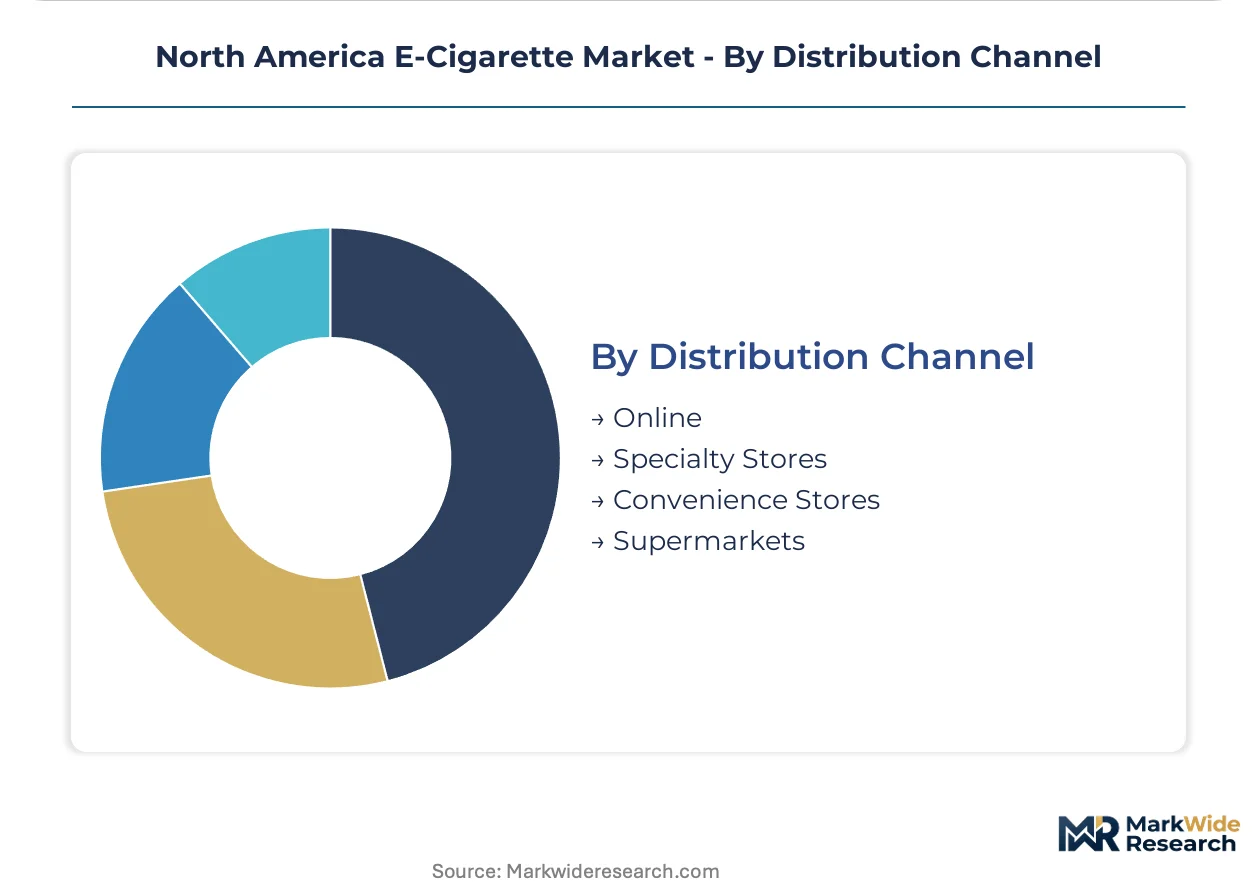
- Online:Direct-to-consumer platforms with integrated biometric age verification and subscription replenishment. California and Florida logistics clusters enable same-day coverage where municipal zoning constrains physical retail.
- Specialty Stores:Dedicated vape shops with staff expertise, flavor sampling, and hardware troubleshooting. Texas metro corridors sustain the densest retail infrastructure for adult consumers aged 21-35.
- Convenience Stores:Cigarette-alternative positioning with limited SKU breadth and minimal staff guidance. British American Tobacco leverages Vuse portfolio breadth to secure shelf space against pod-system pricing pressure.
- Supermarkets:Mass retail with tobacco-menthol concentration and self-service checkout integration. Legacy POS integration challenges erode margin on low-unit-price disposables.
Online channels are gaining share fastest; Convenience Stores retain the largest transaction volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Center for Tobacco Products enforcement anchors regulatory gravity in the United States, while Health Canada and Mexico's national health regulator apply parallel premarket review frameworks that compress cross-border product mobility.
United States
California, Texas, and Florida concentrate demand through mature vape shop density and online fulfillment infrastructure. The FDA's premarket tobacco product application pathway stretches authorization timelines to 12-24 months, freezing pipelines for novel devices. Houston and Dallas-Fort Worth metro corridors sustain the densest retail infrastructure for adult consumers aged 21-35.
Canada
Ontario and Quebec anchor national volume through provincial distribution networks serving dual-user segments. Health Canada's vaping products labeling and packaging regulations mandate nicotine concentration disclosures and child-resistant containers. Toronto and Vancouver logistics clusters enable cross-border fulfillment coverage where municipal zoning constrains physical retail expansion.
Mexico
Mexico City Metro and Nuevo León concentrate demand among young adult cohorts seeking reduced-risk alternatives. Mexico's national health regulator applies tobacco control law extensions to vapor products, restricting flavor variants and advertising channels. Guadalajara manufacturing assemblers source lithium-ion cells from East Asian supplier networks exposed to freight cost volatility.
North America E-Cigarette Market Key Industry Players
Tobacco conglomerates and independent vapor specialists split the market into consolidated premium tiers and fragmented value segments. Altria Group and British American Tobacco anchor the upper tier through portfolio breadth and regulatory infrastructure, while pod-system specialists and disposable manufacturers populate lower-margin strata. Strategic moves concentrate on flavor portfolio narrowing and heated-tobacco convergence.
Among tobacco-major incumbents, British American Tobacco, Altria Group, and Juul Labs occupy positions defined by premarket authorization capabilities and convenience chain shelf presence. British American Tobacco exemplifies the diversified portfolio archetype through its Vuse brand concentration. Altria Group represents the strategic investment model via its partial ownership structure in pod-system platforms. Juul Labs anchors the regulatory-adaptation archetype through flavor restriction compliance and menthol-tobacco portfolio narrowing.
| Leading Market Players |
|---|
| British American Tobacco |
| Altria Group, Inc. |
| Japan Tobacco Inc. |
| Imperial Brands |
| Philip Morris International |
| Juul Labs, Inc. |
| International Vapor Group |
| Greenlane Holdings, Inc. |
| Reynolds American Inc. |
| Others |
Cost & Logistics Intelligence
Shenzhen lithium-ion cell manufacturing clusters anchor North American device pricing through capacity concentration and freight cost pass-through. FDA premarket authorization timelines compress margin flexibility for assemblers competing on pod-system and disposable price points.
Pricing Analysis
Texas-to-California price spreads widen as state flavor restrictions eliminate premium SKUs from Northeast shelves. Three-tier pricing structure across premium, standard, and economy levels separates Vuse Alto systems from entry disposables and enthusiast modular builds. Price differentiation hinges on FDA authorization status and proprietary pod compatibility. Pricing pressure stems from disposable unit commoditization in California convenience chains. Heavy-use consumers aged 21-35 show lowest price sensitivity through subscription lock-in; occasional users in Florida supermarkets drive volume through promotional trial.
Supply Chain Analysis
Propylene glycol feedstock draws from Texas petrochemical corridors and imported pharmaceutical-grade streams. Lithium-ion cells source from China, South Korea, and Japan through East Asian supplier networks. Vegetable glycerin and nicotine extract inputs rest on agricultural and tobacco-extraction supply chains with seasonal volatility. Single-source vulnerability concentrates in battery cell manufacturing, exposing assemblers to customs processing delays. Distribution runs through Miami-Dade and Tampa logistics clusters for Southeast same-day coverage, with California biometrics-enabled platforms handling direct-to-consumer age verification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America E-Cigarette Market functions as a regulatory-entrenchment moat story. FDA premarket authorization infrastructure creates switching costs that concentrate shelf space among capitalized incumbents.
For Market Incumbents: Build regulatory-approval moats by accelerating synthetic nicotine classification compliance investments and securing state-level flavor restriction carve-outs. Threats from disposable price erosion in California convenience chains demand backward integration into lithium-ion cell sourcing. Capacity addition in Guadalajara assembly clusters reduces freight cost exposure. For New Entrants and Emerging Players: Pursue white-space in Florida online fulfillment infrastructure gaps and Texas metro vape shop density corridors. Zero-nicotine flavor formulations for California's age-verified direct-to-consumer channels represent the most penetrable segment. Go-to-market through biometric age-verification platform partnerships bypasses retail zoning constraints. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because FDA authorization bottlenecks will compress viable independent manufacturers to acquisition targets. Firms with tobacco-extraction nicotine supply chains and existing PMTA submissions carry defensive value. Watch FDA menthol standards resolution as portfolio restructuring inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| PMTA Submission Acceleration | FDA authorization timelines favor early filers with clinical data packages. |
| Tobacco-Extraction Partnership | Synthetic nicotine reclassification risk elevates leaf-derived supply security. |
| Biometric Age-Verification Integration | California chargeback reduction enables direct-to-consumer subscription scaling. |
| Heated-Tobacco Convergence R&D | Dual-user segments in Texas seek reduced-risk alternatives with familiar profiles. |
| Florida Fulfillment Hub Expansion | Miami-Dade logistics clusters capture Southeast demand from retail-zoning constrained states. |
Research Approach
Initial hypotheses were tested against primary input from regulatory affairs directors, vape shop operators, convenience chain category buyers, and nicotine supply procurement managers and refined through secondary validation. FDA Center for Tobacco Products filings, Health Canada product databases, state attorney general enforcement actions, and customs import records anchored quantitative baselines. Bottom-up device shipment estimates and top-down nicotine solution volume triangulation converged on market sizing.
Demand-supply-balance framing structured projections across the analysis window. Segmentation dimensions modeled include device architecture, flavor profile, nicotine concentration tier, and distribution channel. CAGRs derived from installed base turnover rates and cohort-specific adoption curves. FDA authorization pipeline status and state-level regulatory trajectories fed scenario-weighted outcomes.
Macroeconomic conditions sit as an overlay; deviation in freight cost indices and lithium carbonate pricing would shift the trajectory. Forecasts assume stable FDA enforcement intensity and no federal flavor prohibition. Cross-checking against convenience chain scanner data and direct-to-consumer platform transaction benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco Products
Asia-Pacific E Cigarettes Market
Tobacco Products
Heat-Not-Burn Tobacco Products Market
Tobacco Products
Global Flavor Capsule Cigarette Market
Tobacco Products
Smokeless Cigarettes Market
Tobacco Products
Japan Heated Tobacco Products Market
Tobacco Products
Roll-Your-Own Tobacco Products Market
Tobacco Products
United States Pipe Tobacco Market
Tobacco Products
Latin America E-Cigarette Market
Tobacco Products
Electronic Cigarette Atomizer Market
Tobacco Products
E-Cigarette and Vape Market
Tobacco Products
US E-Cigarette and Vape Market
Tobacco Products
Global E-Cigarettes Market
Tobacco Products
United States E-Cigarette Market
Tobacco Products
Homemade Cigars Market
Tobacco Products
GCC Cigarette Lighter Market
Tobacco Products
Tobacco Products Market