
 West Africa Cigarettes Market | 2026-2036
West Africa Cigarettes Market Size, Share, and Industry Trends Forecast 2026-2036
West Africa Cigarettes Market Analytics
The WHO Framework Convention on Tobacco Control is restructuring compliance obligations for manufacturers operating across West African states. British American Tobacco leverages its integrated leaf-to-pack supply chain to sustain volume leadership in Nigeria and Ghana. Philip Morris International competes through heated-tobacco diversification while Imperial Brands anchors its position via value-tier pricing and extensive distributor relationships.
Cigarettes are tobacco products manufactured from cured and finely cut leaf, wrapped in paper or similar material, designed for combustion and inhalation, typically containing between 7 and 20 milligrams of tar per stick depending on blend and filter configuration. The product serves as a mass-market nicotine delivery vehicle for adult consumers across formal and informal retail environments. Regular cigarettes dominate volume across West Africa due to price accessibility, though menthol variants command disproportionate margin strength in coastal urban centers. Slim formats are gaining traction among young adult demographics, while soft pack packaging retains preference in traditional retail channels where individual stick sales prevail.
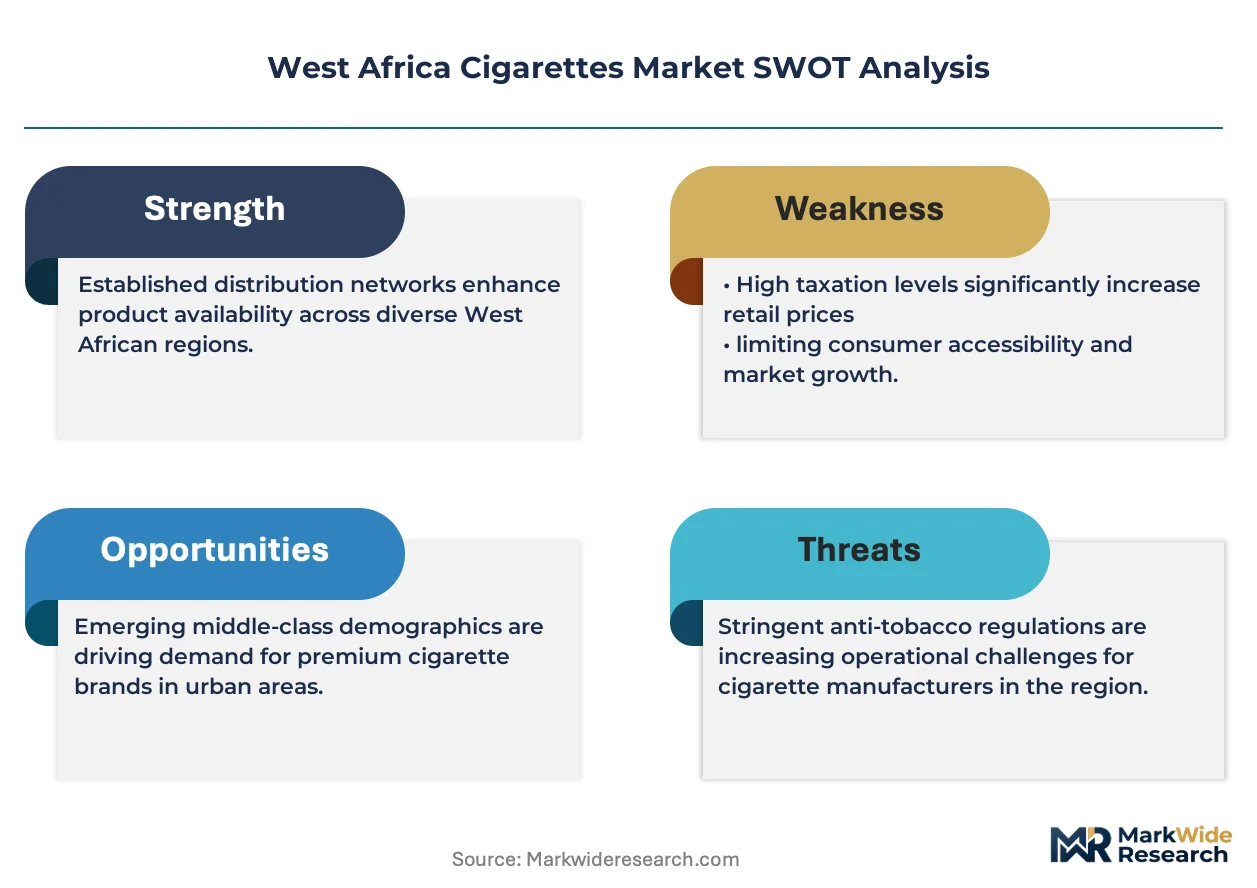
Nigeria's National Agency for Food and Drug Administration and Control enforces tobacco product standards including pictorial health warnings and advertising restrictions, while Ghana's Food and Drugs Authority imposes parallel labeling and import licensing requirements. The Economic Community of West African States harmonization agenda threatens to tighten cross-border regulatory alignment, potentially elevating compliance costs for non-integrated operators. Stakeholders must monitor whether excise harmonization proceeds through ECOWAS mechanisms or fragments into national-level enforcement divergence.
Market Dynamics
Nigeria's graphic warning mandates and advertising restrictions are compressing traditional marketing channels while informal retail networks deepen penetration among urban working-age adults across the region.
Growth Catalysts
- ECOWAS Harmonization Agenda:Cross-border regulatory alignment is streamlining compliance frameworks for manufacturers operating across multiple West African states, reducing fragmentation costs.
- Urban Working-Age Demographics:Population concentration in Lagos, Accra, and Abidjan creates dense distribution nodes where informal retail infrastructure maximizes product accessibility.
- Heated-Tobacco Diversification:Reduced-combustion nicotine delivery systems are opening incremental revenue streams as regulatory pressure intensifies on conventional cigarette formats.
Market Restraints
- Input Cost Volatility:Fluctuations in cured leaf tobacco prices and paper packaging materials squeeze margin structures for operators without backward integration into leaf sourcing.
- Regulatory Friction:Nigeria's NAFDAC pictorial health warning requirements and Ghana's FDA import licensing mandates impose compliance burdens that disproportionately burden non-integrated distributors.
- Substitution Threat:Smokeless nicotine pouches and electronic vapor products are capturing trial among young adult demographics in coastal urban centers.
Strategic Opportunities
- Underpenetrated Hinterland Markets:Northern Nigerian states and inland Côte d'Ivoire regions present volume expansion potential where formal retail infrastructure remains sparse.
- Slim Format Adoption:Young adult consumers in Abidjan and Lomé are shifting toward reduced-diameter cigarette formats, creating margin differentiation opportunities.
- Channel Innovation:Mobile money-integrated distribution networks are enabling direct-to-retailer ordering systems that bypass traditional wholesaler layers.
Industry Challenges
- Compliance Timeline Compression:Accelerated NAFDAC and FDA labeling revision cycles strain packaging procurement and inventory management systems.
- Supply Chain Reconfiguration:Cross-border leaf sourcing disruptions force rapid supplier qualification and alternative origin identification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | West Africa Cigarettes Market |
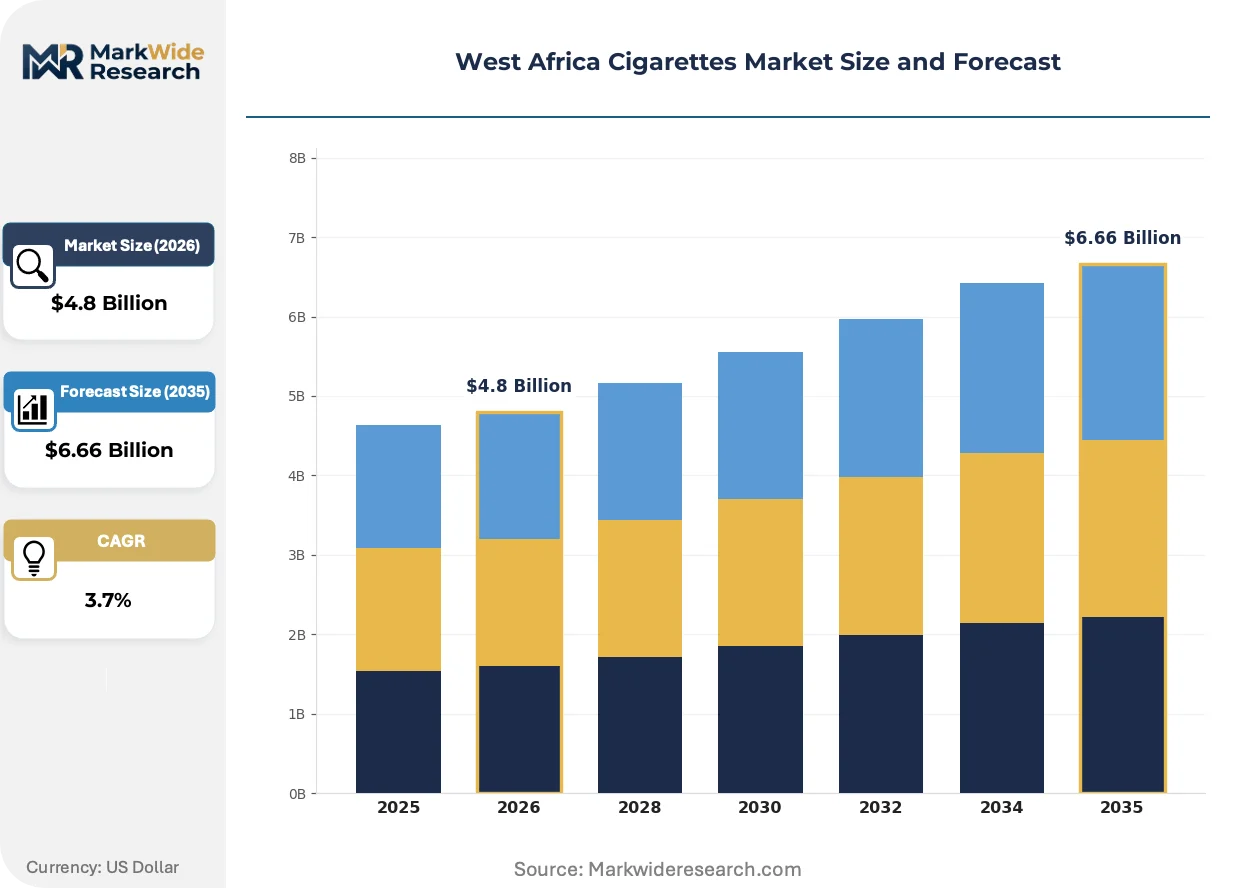
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular, Menthol, Slim, Super Slim Sales Channel: Retail Stores, Online, Supermarkets, Distributors Packaging Type: Soft Pack, Hard Pack, Cartons, Packs Consumer Demographics: Adolescents, Young Adults, Middle-aged, Seniors |
| Companies Covered | British American Tobacco, Philip Morris International, Imperial Brands, Japan Tobacco International, PANAFRICAN TOBACCO GROUP HOLDING Ltd., Black Horse Tobacco Ltd, Orion Agro Industries Ltd, Société ivoirienne de tabac, Manufacture des tabacs de l’Ouest Africain, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
West Africa Cigarettes Market Evolving Landscape
Product format diversification and regulatory compliance automation are restructuring how manufacturers design, package, and distribute cigarettes across West African markets.
Heated-tobacco technology is electrifying competitive positioning in Nigeria and Ghana. British American Tobacco and Philip Morris International are deploying reduced-combustion devices in Lagos and Accra metropolitan zones. This technology is electrifying R&D allocation away from conventional filter and blend optimization toward device ecosystem development.
Nigeria's National Agency for Food and Drug Administration and Control is enforcing pictorial health warning mandates that cover 50% of pack surfaces. Manufacturers are responding with shrink-sleeve overlabeling systems and digital printing investments. Value-tier operators face disproportionate cost absorption challenges compared to integrated multinationals with in-house packaging capabilities.
Individual stick purchasing patterns dominate traditional retail channels across the region. Urban consumers in Lagos, Accra, and Abidjan increasingly expect single-unit availability at kiosks and roadside vendors. Soft pack formats with tear-strip accessibility are displacing rigid box configurations in these environments, forcing packaging line reconfiguration at manufacturing facilities.
West Africa Cigarettes Market Segmentation
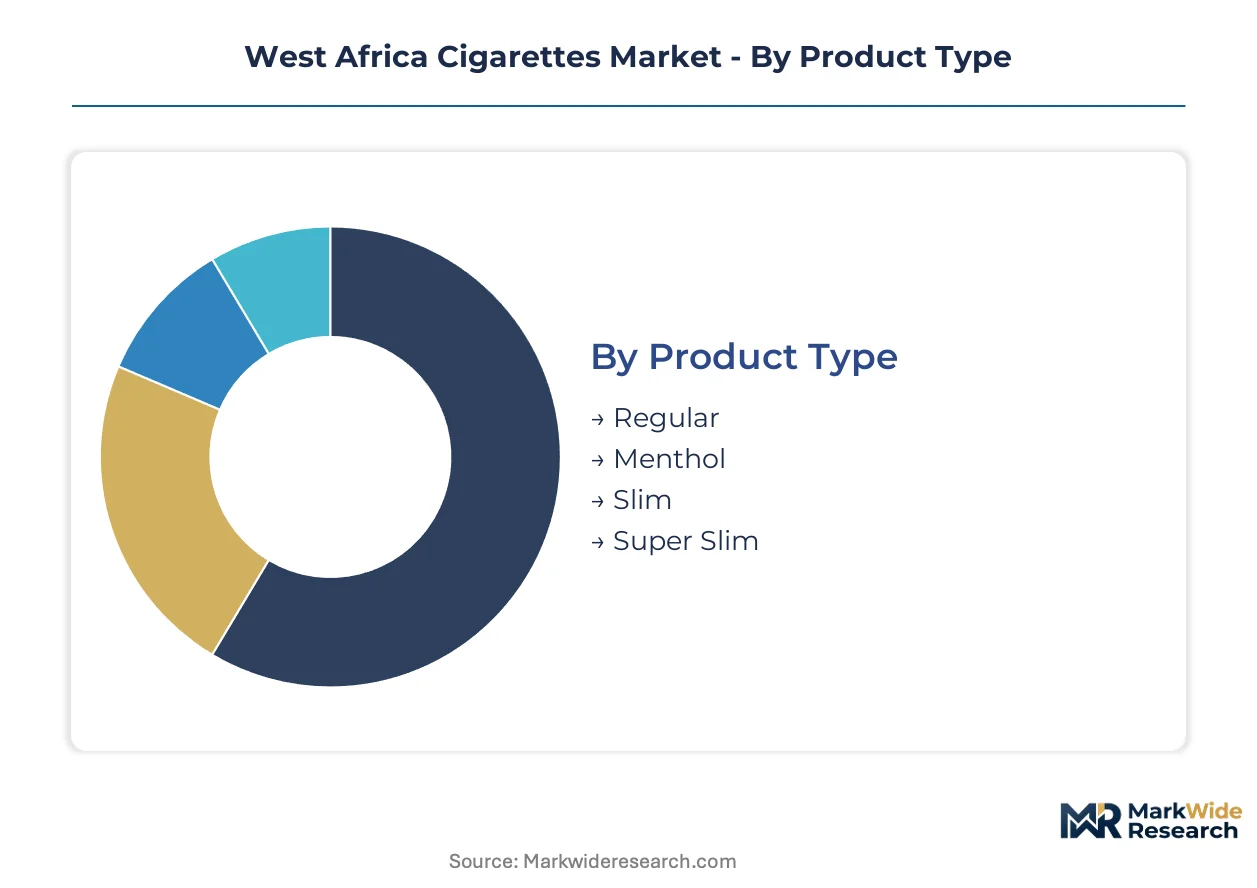
Segmentation across West Africa's cigarette market reveals how manufacturers balance standardized mass-market formats against localized adaptations for informal retail channels and evolving consumer preferences. Understanding these divides illuminates where margin capture concentrates and where volume expansion remains feasible.
Product Type:
Standardization dominates at the economy tier while premium-positioned variants command customization investment for specific urban demographics.
- Regular:Full-flavor blends with conventional filter configurations serve price-sensitive consumers across Lagos, Accra, and Abidjan informal retail networks. Demand concentrates in northern Nigerian states and inland Côte d'Ivoire where purchasing power limits format experimentation.
- Menthol:Characterized by mentholated tobacco blends delivering cooling sensory profiles, these variants disproportionately attract coastal urban consumers in Lomé and Abidjan. NAFDAC flavor additive scrutiny is compressing formulation flexibility for non-integrated manufacturers.
- Slim:Reduced-diameter formats target young adult demographics in metropolitan Lagos and Accra seeking perceived reduced-intensity consumption. Social signaling drives trial among urban professionals.
- Super Slim:Ultra-narrow configurations occupy niche premium positioning in Abidjan's upscale retail environments. Limited distribution infrastructure constrains penetration beyond coastal capitals.
Leading the category by volume: Regular. Growing fastest: Slim.
Sales Channel:
Channel selection maps directly to consumer liquidity patterns and regulatory exposure across Nigerian, Ghanaian, and Ivorian markets.
- Retail Stores:Kiosk and roadside vendor networks dominate transaction frequency across West Africa. Individual stick sales prevail where daily wage purchasing patterns predominate.
- Online:Digital commerce faces NAFDAC advertising restrictions and Ghana FDA e-commerce monitoring. Limited logistics infrastructure constrains delivery reliability outside Lagos and Accra metropolitan zones.
- Supermarkets:Formal retail environments in Lagos, Accra, and Abidjan enforce pack-sealed sales with pictorial health warning compliance. Higher price transparency pressures margin structures.
- Distributors:Wholesaler networks manage cross-border ECOWAS trade flows and hinterland penetration. Inventory financing relationships determine retail credit access in underbanked regions.
Volume leadership sits with Retail Stores. Channel innovation concentrates in Distributor mobile money integration.
Packaging Type:
Packaging economics reflect the tension between manufacturing scale efficiency and retail accessibility requirements in fragmented distribution environments.
- Soft Pack:Flexible paperboard construction with tear-strip accessibility dominates traditional retail where individual stick sales prevail. Lower unit cost supports price competitiveness in value-tier positioning.
- Hard Pack:Rigid box configurations protect product integrity in formal retail and urban professional consumption contexts. Premium positioning in Lagos and Accra supermarkets favors this format.
- Cartons:Bulk packaging serves distributor-tier procurement and informal wholesale restocking across northern Nigeria. Volume discounts align with trader capital constraints.
- Packs:Standard ten-stick and twenty-stick configurations balance manufacturing line efficiency with retail display requirements. NAFDAC pictorial warning mandates apply at this unit level.
Soft Pack commands volume leadership through informal retail penetration. Hard Pack gains share fastest in coastal urban centers.
Consumer Demographics:
Age-based segmentation correlates with income trajectory, brand loyalty formation, and regulatory targeting intensity across West African markets.
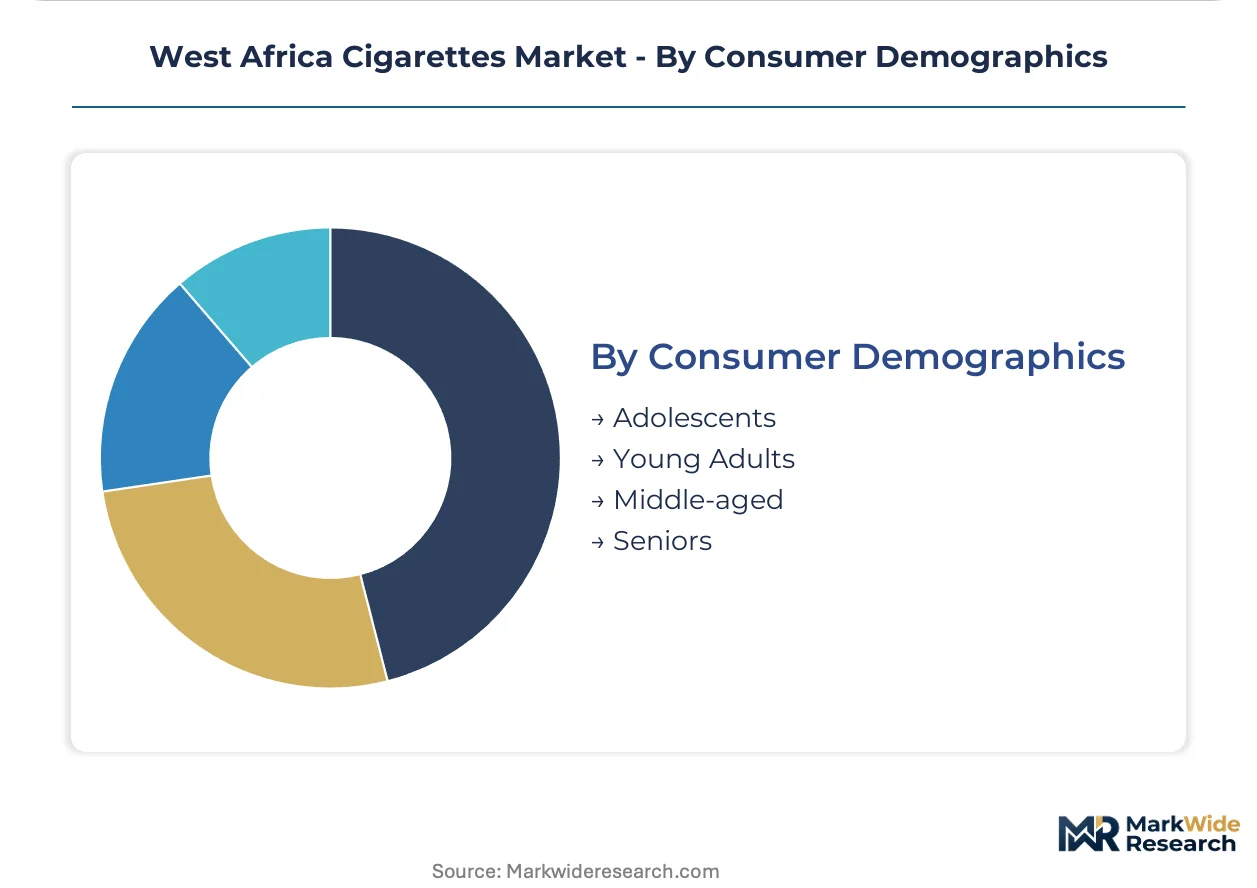
- Adolescents:Underage consumption occurs despite NAFDAC and Ghana FDA sales restrictions. Enforcement gaps in informal retail enable access, though marketing regulations prohibit direct targeting.
- Young Adults:Urban working-age consumers aged 18-30 in Lagos, Accra, and Abidjan drive format innovation trial including slim and heated-tobacco categories. Social consumption patterns dominate purchase occasions.
- Middle-aged:Established consumption habits and brand loyalty characterize consumers aged 30-50. Regular formats and conventional retail channels predominate in this cohort.
- Seniors:Long-term smokers with ingrained brand preferences represent stable but contracting demand. Health concern escalation drives some cessation, though nicotine dependence sustains residual consumption.
Middle-aged consumers anchor volume. Young Adults represent the steepest expansion trajectory for format innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lagos anchors West Africa's cigarette demand through its dense informal retail networks and working-age population concentration. The metropolitan corridor generates transaction volumes that outpace formal distribution infrastructure across the sub-region. Port access and ECOWAS trade facilitation position Lagos as the primary distribution node for coastal and hinterland markets.
Nigeria
Kano and northern Nigerian states sustain regular-format volume through price-sensitive consumption patterns and sparse formal retail coverage. NAFDAC enforces pictorial health warnings covering 50% of pack surfaces, compressing marketing flexibility for non-integrated operators. Lagos-Ibadan corridor distribution networks are integrating mobile money systems to bypass traditional wholesaler financing constraints.
Ghana
Accra's coastal urban consumers disproportionately trial menthol and slim-format variants driven by social signaling preferences. Ghana's Food and Drugs Authority imposes import licensing requirements and parallel labeling standards that elevate compliance costs for cross-border distributors. Tema port logistics infrastructure supports regional re-export positioning into Burkina Faso and Mali.
Côte d'Ivoire
Abidjan's upscale retail environments command super-slim and premium-packaging configurations unavailable in interior regions. The country's national tobacco regulator monitors flavor additive formulations under regional harmonization pressures. San Pedro and Abidjan port clusters concentrate manufacturing and import consolidation for Francophone West African distribution.
Senegal
Dakar's urban professional demographics sustain hard-pack preference in supermarket channels contrasting with soft-pack dominance in informal trade. National tobacco control legislation aligns with ECOWAS harmonization timelines, threatening accelerated labeling revision cycles. Dakar-Thiès industrial corridor hosts limited domestic manufacturing serving Senegalese and Gambian border markets.
Benin
Cotonou's port functions as informal re-export hub leveraging customs differentials with Nigerian markets. Limited domestic regulatory enforcement creates distribution arbitrage opportunities for unlicensed product flows. Northern Borgou and Alibori regions present underpenetrated volume potential where formal retail infrastructure remains undeveloped.
West Africa Cigarettes Market Competitive Landscape
Premium-margin players sit above commodity-margin players across brand architecture and distribution integration depth. British American Tobacco and Philip Morris International occupy integrated positions with captive leaf sourcing and packaging capabilities, while regional specialists compete on price accessibility and local distributor relationships. Three archetypes define competitive positioning: multinational integrated operators, regional value-tier specialists, and informal import-dependent traders. Dominant competitive moves include heated-tobacco portfolio diversification and mobile money-integrated distribution network expansion.
Among multinational integrated operators, British American Tobacco and Philip Morris International exemplify the premium-tier archetype through reduced-combustion technology deployment and metropolitan-focused retail positioning. Imperial Brands occupies a distinct value-tier position leveraging extensive distributor financing relationships across informal channels. PANAFRICAN TOBACCO GROUP HOLDING Ltd. represents the regional specialist archetype with manufacturing proximity advantages in Francophone markets.
| Leading Market Players |
|---|
| British American Tobacco |
| Philip Morris International |
| Imperial Brands |
| Japan Tobacco International |
| PANAFRICAN TOBACCO GROUP HOLDING Ltd. |
| Black Horse Tobacco Ltd |
| Orion Agro Industries Ltd |
| Société ivoirienne de tabac |
| Manufacture des tabacs de l'Ouest Africain |
| Others |
Value Network & Pricing Analysis
Heated-tobacco device manufacturing is reconfiguring cost structures across West African production facilities while concentrating supply leverage among operators with captive R&D capabilities. This technology shift elevates fixed-cost absorption requirements for conventional cigarette producers while fragmenting procurement patterns for leaf tobacco and filter components.
Pricing Analysis
Value-based pricing anchored to nicotine delivery efficiency and reduced-harm perception commands premium positioning in Lagos and Accra metropolitan zones. Three-tier pricing structure across premium, standard, and economy levels reflects brand heritage, packaging compliance investment, and distribution depth. Cost compression in the economy tier intensifies because NAFDAC labeling mandates disproportionately burden non-integrated operators. Urban working-age consumers in informal retail channels exhibit highest price sensitivity, while coastal professional demographics accept premium positioning for slim and heated-tobacco formats.
Supply Chain Analysis
Workforce availability constraints in Nigerian and Ghanaian manufacturing zones are elevating automation investment requirements at packaging facilities. Supply concentration centers on Nigeria, Ghana, and Côte d'Ivoire for finished goods, with leaf sourcing drawing from Malawi, Zimbabwe, and Brazil. Cured tobacco, acetate tow filters, and paper packaging materials constitute critical input dependencies. Single-source vulnerability in leaf procurement channels threatens margin stability during climate-induced crop disruptions. Distribution runs through ECOWAS-bonded warehouse networks and mobile money-integrated wholesaler financing systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
West Africa's cigarette market reads as supply-constrained where backward integration into compliant packaging capabilities props pricing power for integrated multinationals against fragmented import-dependent competitors.
For Market Incumbents: Extend heated-tobacco ecosystem deployment across Lagos and Accra metropolitan corridors to capture format substitution premiums. Deepen captive leaf sourcing relationships in Malawi and Zimbabwe to insulate against cross-border trade disruption. Secure NAFDAC-compliant packaging line capacity ahead of accelerated labeling revision cycles to compress competitor response windows. For New Entrants and Emerging Players: Mobile money-integrated distributor networks present the most penetrable channel infrastructure for bypassing established wholesaler financing relationships. Northern Nigerian states and inland Côte d'Ivoire regions offer white-space volume expansion where formal retail penetration remains sparse. A value-tier soft-pack positioning with tear-strip accessibility aligns with individual stick purchasing patterns dominating traditional retail channels. For Investors and Strategic Acquirers: Re-rating potential sits with regionally integrated manufacturers possessing captive packaging capabilities given ECOWAS harmonization enforcement timelines. Long-term viability over a five-to-ten year window favors operators with heated-tobacco R&D allocation and Francophone distribution reach. Monitor NAFDAC-FDA labeling convergence as the signal indicating accelerated compliance cost absorption for non-integrated distributors.| Strategic Initiative | Industry Significance |
|---|---|
| Heated-Tobacco Portfolio Expansion | Philip Morris International and British American Tobacco device deployments in Lagos capture format substitution premiums ahead of regulatory combustion restrictions. |
| NAFDAC-Compliant Packaging Investment | Shrink-sleeve overlabeling systems and digital printing capabilities reduce inventory obsolescence risk during accelerated pictorial warning revision cycles. |
| Mobile Money Distribution Integration | Direct-to-retailer ordering platforms bypass traditional wholesaler financing layers in underbanked northern Nigerian states. |
| Leaf Sourcing Backward Integration | Captive supply from Malawi and Zimbabwe insulates margin structures against cross-border trade disruptions and currency volatility. |
| Slim Format Product Line Extension | Reduced-diameter configurations target young adult social consumption occasions in Abidjan and Accra with premium positioning. |
Research Methodology
Document review covered customs and trade flow databases, NAFDAC regulatory filings, and ECOWAS harmonization protocols, complemented by interviews with manufacturing operations directors, informal retail network managers, leaf procurement specialists, and distributor financing officers. Secondary validation drew from Ghana FDA import licensing records, Nigerian National Bureau of Statistics consumption surveys, and industry association production estimates. Bottom-up channel volume assessments and top-down macroeconomic consumption models were triangulated for convergence.
Segmented volume and value trajectories across the projection horizon reflect product type, packaging format, sales channel, and consumer demographic dimensions. CAGRs were derived from regression analysis against urbanization rates, working-age population growth, and regulatory enforcement intensity indices. Forecast inputs incorporated ECOWAS excise harmonization probability scenarios and heated-tobacco adoption elasticity parameters.
Caveats apply where NAFDAC-FDA labeling divergence, leaf crop failure events, or electronic nicotine product substitution acceleration could materially shift the outlook. Forecasts embed assumptions regarding informal retail network persistence and mobile money penetration trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco Products
Global E-Cigarettes Market
Tobacco Products
Luxury Cigarette Market
Tobacco Products
United States E-Cigarette Market
Tobacco Products
Electronic Cigarette Atomizer Market
Tobacco Products
Roll-Your-Own Tobacco Products Market
Tobacco Products
Global Cigarette Vending Machine Market
Tobacco Products
Cigarettes Filter Market
Tobacco Products
GCC E-Cigarette Market
Tobacco Products
Premium Cigarette Market
Tobacco Products
Disposable E-Cigarettes Market
Tobacco Products
Cigarette Market
Tobacco Products
Tobacco Products Market
Tobacco Products
Flavored Cigar Market
Tobacco Products
Heated Tobacco Products Market
Tobacco Products
Philippines E-Cigarette and Vape Market
Tobacco Products
Global Flavor Capsule Cigarette Market