
 Asia-Pacific E Cigarettes Market | 2026-2036
Asia-Pacific E Cigarettes Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific E Cigarettes Market Outlook
Ceramic coil technology is broadening the thermal efficiency and flavor consistency of pod system devices across the Asia-Pacific E Cigarettes landscape. Philip Morris International leverages its IQOS heated tobacco platform to dominate Japan's convenience channel infrastructure. RELX Technology anchors its position through deep R&D investment in closed-system pod designs tailored to Chinese regulatory parameters. Smoore International Holdings Ltd sustains manufacturing scale advantages across multiple brand portfolios through its Shenzhen production base.
An e cigarette is a battery-powered electronic device that aerosolizes a liquid solution—typically containing propylene glycol, vegetable glycerin, nicotine, and flavoring compounds—through resistive heating of a coil-wicked element, producing an inhalable vapor as an alternative to combustible tobacco consumption. Pod system devices command the largest installed base among product types due to their rechargeable format and prefilled cartridge convenience, while disposable units represent the fastest-growing format as entry-level users prioritize low-commitment trial. Online retailers face structural pressure from flavor restriction enforcement, pushing margin pools toward specialty shops with verified-age protocols and supervised product consultation.
Japan's Ministry of Health, Labour and Welfare classifies heated tobacco separately from combustible products, creating a distinct regulatory pathway that shapes product development priorities for manufacturers seeking market access. China's SAMR flavor ban and Australia's Therapeutic Goods Administration prescription requirements for nicotine vaping products together compress demand toward tobacco-menthol portfolios and medical-channel distribution. Stakeholders must monitor how Australia's prescription model evolves relative to New Zealand's regulatory liberalization, as divergence between neighboring frameworks will determine regional investment allocation and product pipeline configuration.
Market Dynamics
China's SAMR flavor restrictions have triggered a wholesale portfolio pivot toward tobacco-menthol formulations, compressing manufacturer margins while accelerating ceramic coil R&D investment as the primary differentiation vector.
Growth Catalysts
- Heated tobacco regulatory pathway:Japan's Ministry of Health, Labour and Welfare maintains distinct classification for heated tobacco products, enabling mainstream convenience store distribution and accelerating category normalization among adult smokers seeking reduced-risk alternatives.
- Ceramic coil thermal efficiency:Advanced alumina substrate materials are delivering superior flavor consistency and coil longevity, driving replacement cycle compression and brand stickiness across pod system installed bases.
- Young adult user expansion:Demographic concentration in metropolitan centers across South Korea and Vietnam is creating organic viral adoption patterns through social visibility and peer influence networks.
Market Restraints
- Flavor portfolio compression:China's SAMR prohibition on non-tobacco flavoring compounds has eliminated approximately two-thirds of historical SKU diversity, constraining manufacturer ability to differentiate through taste innovation.
- Prescription channel friction:Australia's Therapeutic Goods Administration nicotine vaping prescription requirements impose medical practitioner gatekeeping that limits trial accessibility and concentrates distribution through pharmacy networks.
- Battery supply concentration:Cylindrical lithium-ion cell production concentrates in Guangdong and Jiangsu provinces, creating input vulnerability for device manufacturers lacking captive supply arrangements or multi-source qualification.
Strategic Opportunities
- Indonesia market underpenetration:Southeast Asia's largest population exhibits minimal heated tobacco penetration and limited domestic e-cigarette manufacturing, presenting first-mover advantage for portfolio entrants establishing local distribution partnerships.
- Closed-system pod convergence:Integration of NFC authentication chips with ceramic coil architectures enables anti-counterfeiting verification and usage tracking, opening subscription-based revenue models and regulatory compliance automation.
- New Zealand regulatory divergence:Liberalized vaping product frameworks relative to Australia's prescription model create natural experiment conditions for testing reduced-harm product positioning and retail accessibility strategies.
Industry Challenges
- Aerosol toxicology expertise scarcity:Manufacturers face acute shortage of inhalation toxicologists capable of designing premarket tobacco product application submissions acceptable to multiple national regulators simultaneously.
- Coil-to-liquid compatibility certification:Proprietary pod-cartridge interfaces require extensive thermal stability testing across flavor chemistries, extending product development timelines and straining quality assurance capacity.
- Retailer age-verification infrastructure:Convenience store networks lack standardized biometric or digital ID integration, creating compliance execution risk amid intensifying enforcement of youth access prohibitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific E Cigarettes Market |
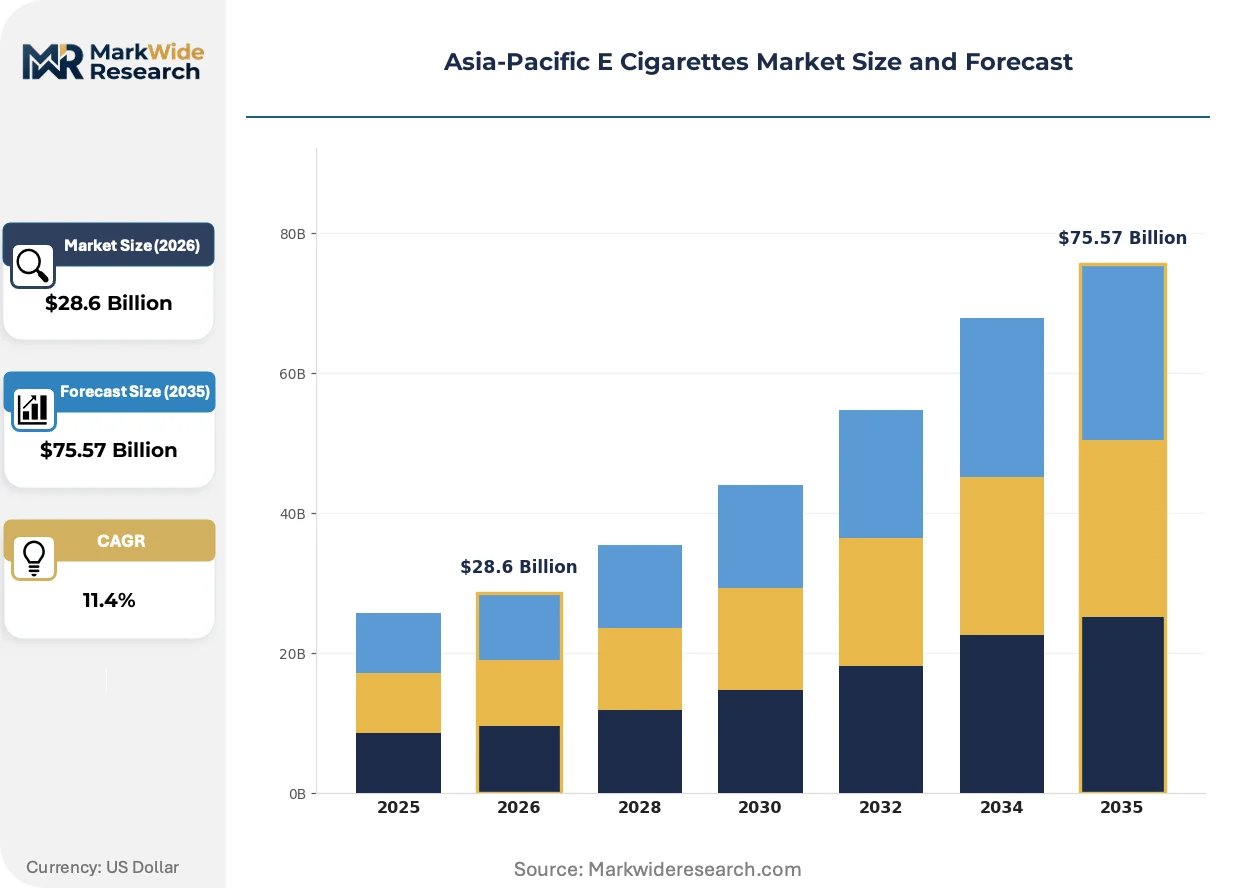
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Rechargeable, Pod System, Vape Pens User Profile: Teenagers, Young Adults, Middle-Aged, Smokers Flavor Profile: Tobacco, Menthol, Fruit, Dessert Distribution Channel: Convenience Stores, Online Retailers, Specialty Shops, Supermarkets |
| Companies Covered | Philip Morris International, JUUL Labs, Inc., British American Tobacco plc, Smoore International Holdings Ltd, Japan Tobacco International, RELX Technology, Imperial Brands PLC, Altria Group, Inc., Vaping Gadget Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific E Cigarettes Market Strategic Shifts
Product architecture and distribution mechanics across the Asia-Pacific E Cigarettes landscape are being reconfigured by thermal technology advances, regulatory classification experiments, and shifting channel economics that reward compliance infrastructure investment.
Precision temperature control modules using embedded thermocouple feedback loops are automating coil heating curves to eliminate dry-hit phenomena and extend cartridge consistency. Premium pod system manufacturers in Japan and South Korea are integrating these modules as standard features, compressing competitive differentiation timelines for mid-tier brands lacking comparable semiconductor sourcing relationships.
Japan's Ministry of Health, Labour and Welfare maintains its bifurcated regulatory classification that separates heated tobacco from combustible cigarettes, creating industrial incentive for manufacturers to concentrate R&D expenditure on aerosol chemistry rather than device electronics. This policy architecture has channeled Philip Morris International and British American Tobacco toward tobacco stick innovation, while e-liquid vapor manufacturers face exclusion from convenience store networks reserved for the heated tobacco category.
Specialty vape shops with verified-age protocols and supervised product consultation are displacing online retailers as the primary margin pool for flavored product distribution. Australia's pharmacy channel concentration under Therapeutic Goods Administration prescription requirements, combined with China's flavor enforcement pushing consumers toward gray-market sources, has created geographic divergence in channel strategy that manufacturers must navigate with territory-specific compliance infrastructure rather than unified regional approaches.
Asia-Pacific E Cigarettes Market Segmentation
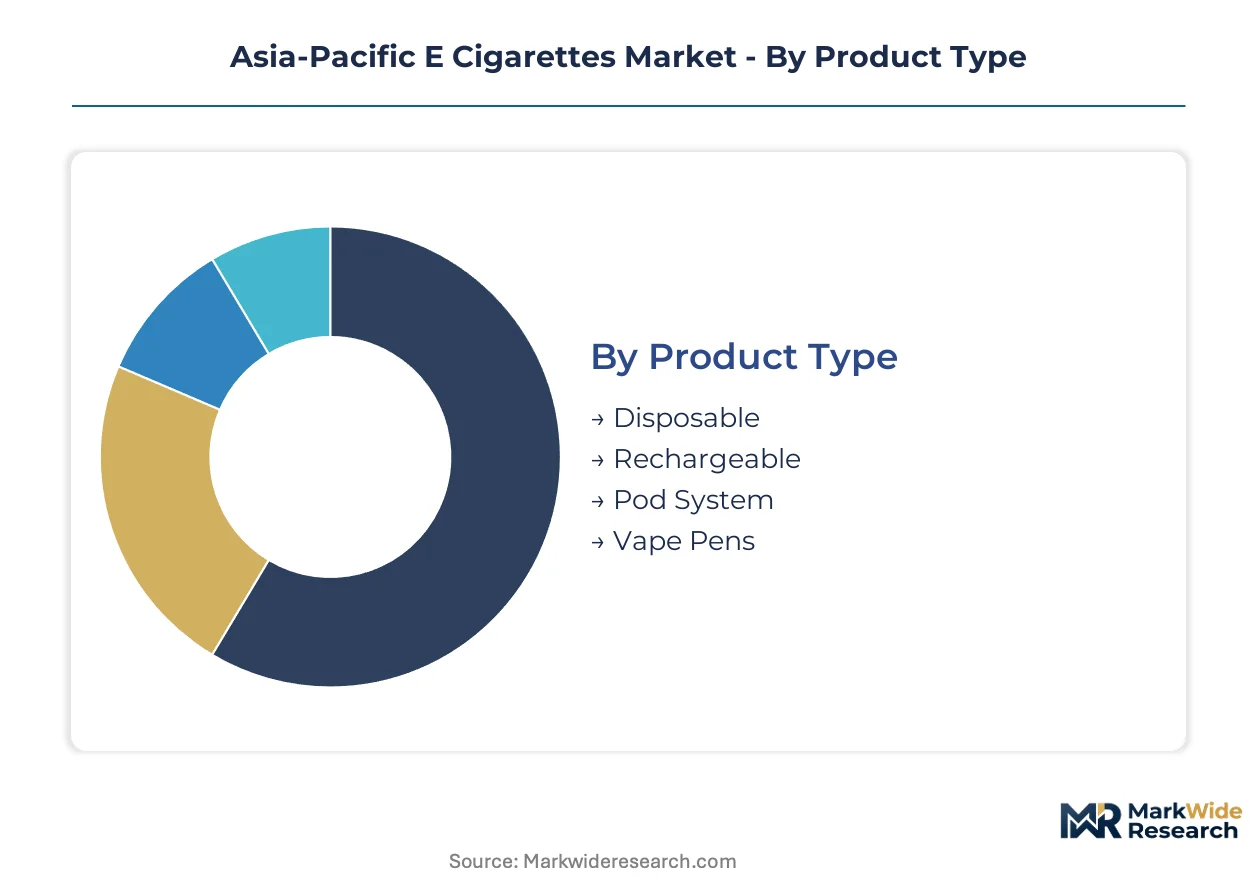
Segmentation across the Asia-Pacific E Cigarettes Market reveals how regulatory pressure and user preference divergence create distinct competitive arenas. Each category demands tailored portfolio architecture and channel strategy to capture value.
Product Type:
Standardization dominates at the entry tier while premium tiers chase thermal efficiency differentiation through ceramic coil architectures.
- Disposable:Single-use lithium-polymer cells power non-rechargeable formats with fixed e-liquid reservoirs. Demand concentrates in Vietnam and Indonesia among trial-seeking users where low-commitment price points outweigh lifetime cost calculations. SAMR flavor enforcement in China has compressed margins here as manufacturers absorb compliance costs rather than pass through to price-sensitive entrants.
- Pod System:Closed-system cartridges with proprietary coil interfaces command the largest installed base across Japan and South Korea metropolitan corridors. Ceramic substrate materials deliver thermal consistency that extends replacement cycles and builds brand stickiness. Japan's Ministry of Health, Labour and Welfare classification framework channels these devices through convenience store networks with verified-age protocols.
- Rechargeable:Open-tank formats with user-refillable reservoirs serve enthusiast segments seeking coil customization and flavor experimentation flexibility.
- Vape Pens:Cylindrical form factors with integrated batteries target transitional smokers prioritizing familiar hand-feel over technical sophistication.
Leading the category by volume: Pod System. Growing fastest: Disposable.
User Profile:
Application intensity varies sharply—social visibility drives metropolitan adoption while cessation intent shapes medical-channel concentration.
- Young Adults:Metropolitan clusters in Seoul, Ho Chi Minh City, and Bangkok generate organic viral adoption through peer influence networks and social media visibility. Ceramic coil pod systems dominate this segment where flavor consistency and device aesthetics carry premium weight. Regulatory scrutiny from Australia's TGA prescription requirements creates geographic divergence in accessibility.
- Smokers:Combustible tobacco transition seekers in Japan and South Korea prioritize reduced-risk positioning and thermal efficiency metrics over flavor variety. Philip Morris International's IQOS platform captured this cohort through heated tobacco's distinct regulatory pathway and convenience store penetration.
- Teenagers:Access-restricted demographic facing intensified enforcement of youth prohibition protocols across all regional jurisdictions.
- Middle-Aged:Cessation-focused users with established nicotine dependency patterns and higher willingness to engage medical practitioner consultation.
Volume concentration sits with Smokers. Steepest expansion trajectory belongs to Young Adults.
Flavor Profile:
Margin structure inverts as regulatory compression eliminates differentiation vectors—tobacco-menthol portfolios now carry compliance premiums.
- Tobacco:Synthetic and extracted nicotine formulations replicate combustible taste profiles for transition smokers. China's SAMR restrictions have elevated this from commodity baseline to strategic necessity, forcing R&D investment in aerosol chemistry refinement. Manufacturers lacking in-house flavor houses face sourcing vulnerability.
- Menthol:Cooling agent formulations survive regulatory scrutiny where fruit and dessert compounds face prohibition. Japan's heated tobacco category maintains menthol variants as core SKUs within convenience store distribution. British American Tobacco and Japan Tobacco International concentrate thermal innovation here.
- Fruit:Eliminated from legal portfolios in China; surviving demand concentrates in gray-market channels and liberalized jurisdictions like New Zealand.
- Dessert:Bakery and confectionery flavor profiles face equivalent SAMR prohibition, compressing manufacturer R&D focus toward tobacco-menthol convergence.
Tobacco dominates current volume. Menthol carries the fastest regulatory-survival expansion.
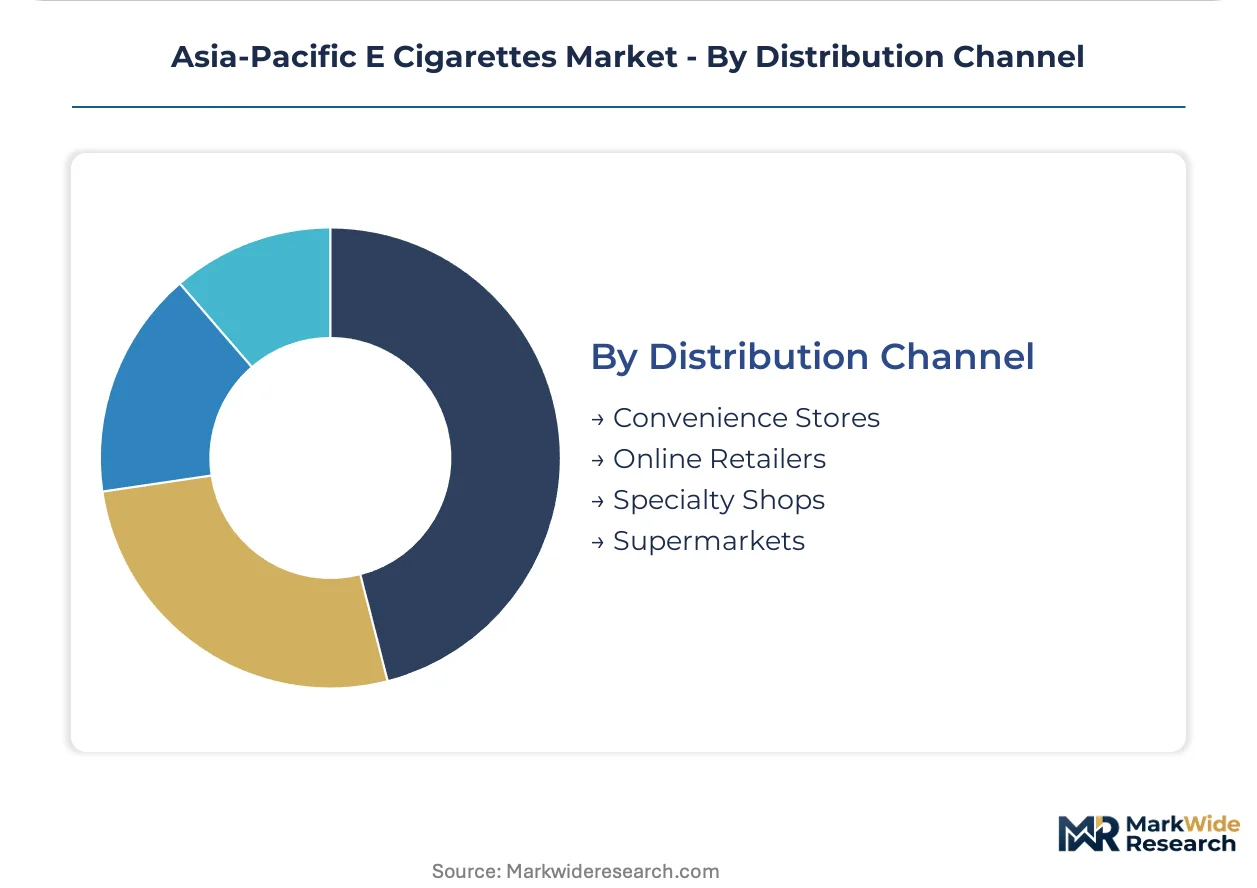
Distribution Channel:
Supply concentration in Shenzhen manufacturing clusters dictates channel economics—proximity to production shapes margin capture.
- Convenience Stores:Japan's Lawson, 7-Eleven, and FamilyMart networks deliver mainstream accessibility for heated tobacco and compliant pod systems. Age-verification infrastructure investments separate authorized from unauthorized retail. METI classification frameworks determine product eligibility for this channel.
- Specialty Shops:Verified-age protocols with supervised product consultation capture flavored product margins displaced from online enforcement. Australia's pharmacy concentration under TGA prescription requirements represents extreme channel compression. Staff expertise in coil-to-liquid compatibility drives repeat visitation.
- Online Retailers:Structural pressure from flavor restriction enforcement and age-verification liability pushes margin pools toward physical retail with biometric ID integration.
- Supermarkets:Mass retail with limited consultation capacity serves standardized tobacco-menthol portfolios in liberalized regulatory environments.
Convenience Stores lead by transaction volume. Specialty Shops gain share fastest amid compliance infrastructure differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Japan's metropolitan corridors and China's manufacturing clusters, with regulatory divergence between these poles reshaping investment flows. Young adult adoption in South Korean and Vietnamese cities accelerates trial rates, while Australia's prescription model compresses accessibility. Indonesia's underpenetrated population base offers expansion terrain for portfolio entrants.
China
Domestic consumption pivots toward tobacco-menthol formulations following SAMR flavor restrictions. Shenzhen anchors global device manufacturing through concentrated lithium-ion cell supply and ceramic coil fabrication capacity. Gray-market channels absorb residual demand for prohibited flavor profiles.
Japan
Heated tobacco products achieve mainstream retail penetration through Lawson and 7-Eleven convenience networks. METI classification frameworks separate these devices from combustible cigarettes, enabling distinct regulatory treatment. Tokyo and Osaka metropolitan areas concentrate adult smoker transition demand.
South Korea
Young adult clusters in Seoul drive organic viral adoption of pod system devices through social visibility dynamics. MFDS oversight maintains flavor availability beyond China's prohibition scope. Busan-Ulsan corridor hosts distribution infrastructure serving domestic and export flows.
Australia
TGA prescription requirements impose medical practitioner gatekeeping on nicotine vaping product access. Pharmacy channel concentration limits trial accessibility relative to retail-liberalized neighbors. New South Wales and Victoria concentrate cessation-focused user populations.
Indonesia
Southeast Asia's largest population exhibits minimal heated tobacco penetration and limited domestic manufacturing presence. Jakarta and Surabaya metropolitan areas present first-mover partnership opportunities for portfolio entrants. Local distribution relationships determine market access feasibility.
Asia-Pacific E Cigarettes Market Competitive Environment
Portfolio diversification dominates the current landscape as manufacturers pivot toward tobacco-menthol formulations and ceramic coil architectures. The vendor base stratifies across three tiers: multinational tobacco conglomerates with heated tobacco platforms, Chinese closed-system specialists with deep R&D integration, and contract manufacturers with Shenzhen production scale. Strategic archetypes include convenience channel dominators leveraging regulatory classification advantages, compliance infrastructure builders capturing specialty retail margins, and technology licensors monetizing ceramic coil IP. Competitive moves concentrate on geographic licensing partnerships and backward integration into battery cell supply.
Within the multinational tier, Philip Morris International and British American Tobacco occupy positions shaped by heated tobacco regulatory pathways. Among China-based specialists, RELX Technology and Smoore International Holdings Ltd exemplify divergent strategic postures—one anchored in brand-facing closed-system design, the other in manufacturing scale across multiple portfolios. Japan Tobacco International represents the regional incumbent leveraging domestic distribution depth.
| Leading Market Players |
|---|
| Philip Morris International |
| JUUL Labs, Inc. |
| British American Tobacco plc |
| Smoore International Holdings Ltd |
| Japan Tobacco International |
| RELX Technology |
| Imperial Brands PLC |
| Altria Group, Inc. |
| Vaping Gadget Limited |
| Others |
Value Chain & Pricing Dynamics
Ceramic coil engineers concentrated in Shenzhen and Dongguan manufacturing corridors generate labor-cost differentials that widen pricing-tier spreads between premium pod systems and economy disposables. China's SAMR flavor enforcement compresses margins at the entry tier while ceramic substrate R&D investment elevates premium-tier cost structures.
Pricing Analysis
Volume concentrates in economy-tier disposables where price-sensitive trial users in Vietnam and Indonesia prioritize low-commitment entry points, while margins pool in premium ceramic-coil pod systems serving brand-loyal young adults in Seoul and Tokyo. Pricing stratifies across premium, standard, and economy tiers based on coil architecture sophistication and flavor chemistry certification. Cost compression in the disposable segment intensifies as manufacturers absorb SAMR compliance overhead rather than pass through to price-elastic entrants. Specialty shops with verified-age protocols command pricing premiums over online channels facing enforcement liability.
Supply Chain Analysis
Direct-to-specialty-shop channels handle premium pod system distribution with supervised consultation requirements, while convenience store networks manage heated tobacco volume flows. Device manufacturing concentrates in China's Guangdong and Jiangsu provinces, with lithium-ion cell supply anchored in Shenzhen production bases. Raw material dependencies span alumina substrates for ceramic coils, pharmaceutical-grade nicotine from India, and flavor compounds from European specialty chemical houses. Single-source vulnerability in cylindrical battery cell qualification creates procurement risk for brands lacking multi-source arrangements. Distribution runs through METI-authorized convenience networks in Japan and pharmacy channels in Australia under TGA prescription frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific E Cigarettes Market sits in a technology-transition phase as ceramic coil architectures displace traditional metal-coil legacy systems across pod system portfolios. This thermal efficiency shift reconfigures R&D investment priorities and manufacturing qualification requirements for competitive positioning.
For Market Incumbents: Deepen backward integration into ceramic substrate supply chains to secure alumina sourcing amid coil-architecture standardization. Defend convenience store shelf space through METI classification compliance and age-verification infrastructure investment. Philip Morris International's IQOS platform demonstrates how regulatory pathway capture creates channel access moats against e-liquid competitors.
For New Entrants and Emerging Players: Convenience store franchise operators in Indonesia's Jakarta and Surabaya corridors represent underexploited distribution partnerships for portfolio entrants. Target gray-market flavor demand compression in China through compliant tobacco-menthol positioning with superior ceramic coil performance. White-space opportunity concentrates in Southeast Asia's largest population base where heated tobacco penetration remains minimal.
For Investors and Strategic Acquirers: The window for entry favors ceramic coil IP holders with Shenzhen manufacturing relationships and multi-regulatory submission capabilities. Long-term viability hinges on aerosol toxicology expertise scarcity resolution and premarket tobacco product application track records. Watch Australia's TGA prescription model evolution relative to New Zealand's liberalized framework as the inflection signal for regional investment allocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Coil IP Licensing | Technology licensors monetize thermal efficiency patents across multiple brand portfolios. |
| Backward Integration into Battery Supply | Captive lithium-ion cell production reduces input vulnerability for device manufacturers. |
| Convenience Channel Partnership Expansion | Lawson and 7-Eleven network penetration accelerates heated tobacco category normalization. |
| Aerosol Toxicology Capability Buildout | Inhalation toxicologist hiring enables simultaneous multi-regulator premarket submissions. |
| NFC Authentication Chip Integration | Anti-counterfeiting verification opens subscription revenue models and compliance automation. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Asia-Pacific E Cigarettes Market analysis. Primary interviews with device manufacturing executives, flavor house technical directors, convenience store category managers, and pharmacy procurement officers combined with bottom-up shipment tracking and top-down consumer spend estimates. Secondary sources included SAMR administrative guidance documents, METI classification frameworks, TGA prescription registry extracts, and MFDS product notification databases.
Segmentation-level modeling addressed product type granularity across disposable, pod system, rechargeable, and vape pen formats alongside flavor profile, user demographic, and distribution channel dimensions. CAGRs derived from installed base replacement cycle analysis and trial-to-adoption conversion assumptions across metropolitan corridors. Industry-specific forecast inputs incorporated ceramic coil adoption curves, heated tobacco regulatory pathway expansion timelines, and flavor restriction enforcement intensity differentials across the analysis window.
Several conditions sit outside the modeled scope, including potential SAMR enforcement escalation beyond current tobacco-menthol parameters, Australia-New Zealand regulatory convergence or divergence scenarios, and battery cell supply disruption events. Forecasts reflect assumptions about ceramic coil cost-down trajectories and convenience store age-verification infrastructure deployment rates. Periodic stress-testing of base assumptions is recommended against aerosol toxicology study outcomes and youth access prohibition enforcement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco Products
Japan Heated Tobacco Products Market
Tobacco Products
Africa Tobacco Products Market
Tobacco Products
Heated Tobacco Products Market
Tobacco Products
West Africa Cigarettes Market
Tobacco Products
Premium Tobacco Products Market
Tobacco Products
Handmade Cigars Market
Tobacco Products
E-Cigarettes and Vaporizer Market
Tobacco Products
Cigar Tubes Market
Tobacco Products
Global Flavor Capsule Cigarette Market
Tobacco Products
GCC Cigarette Lighter Market
Tobacco Products
Smokeless Cigarettes Market
Tobacco Products
Global Smokeless Tobacco Market
Tobacco Products
Tobacco Pouch Market
Tobacco Products
Disposable E-Cigarettes Market
Tobacco Products
Nicotine Pouches Market
Tobacco Products
US E-Cigarette and Vape Market