
 United States Pipe Tobacco Market | 2026-2036
United States Pipe Tobacco Market Size, Share, and Industry Trends Forecast 2026-2036
United States Pipe Tobacco Market Outlook
Market Context
Natural leaf wrappers and air-cured burley varieties are restructuring cost structures across premium product lines. Turning Point Brands leverages its diversified smokeless portfolio to sustain shelf presence in constrained retail environments. Scandinavian Tobacco Group anchors its position through specialized pipe tobacco subsidiaries with deep blending expertise. Cornell & Diehl competes on small-batch craftsmanship and regional loyalty among dedicated enthusiasts.
Technical Definition and Segment Structure
United States pipe tobacco comprises cut, shredded, or pressed leaf formulations designed for combustion in briar, meerschaum, or corncob pipes, with moisture content and cut width determining burn rate and flavor delivery. The product serves recreational and ceremonial consumption, with aromatic blends commanding the widest entry-level adoption. Non-aromatic and premium categories concentrate margin pools among aging collectors and connoisseurs, while distribution through specialty shops captures the highest per-unit profitability despite lower throughput than convenience channels.
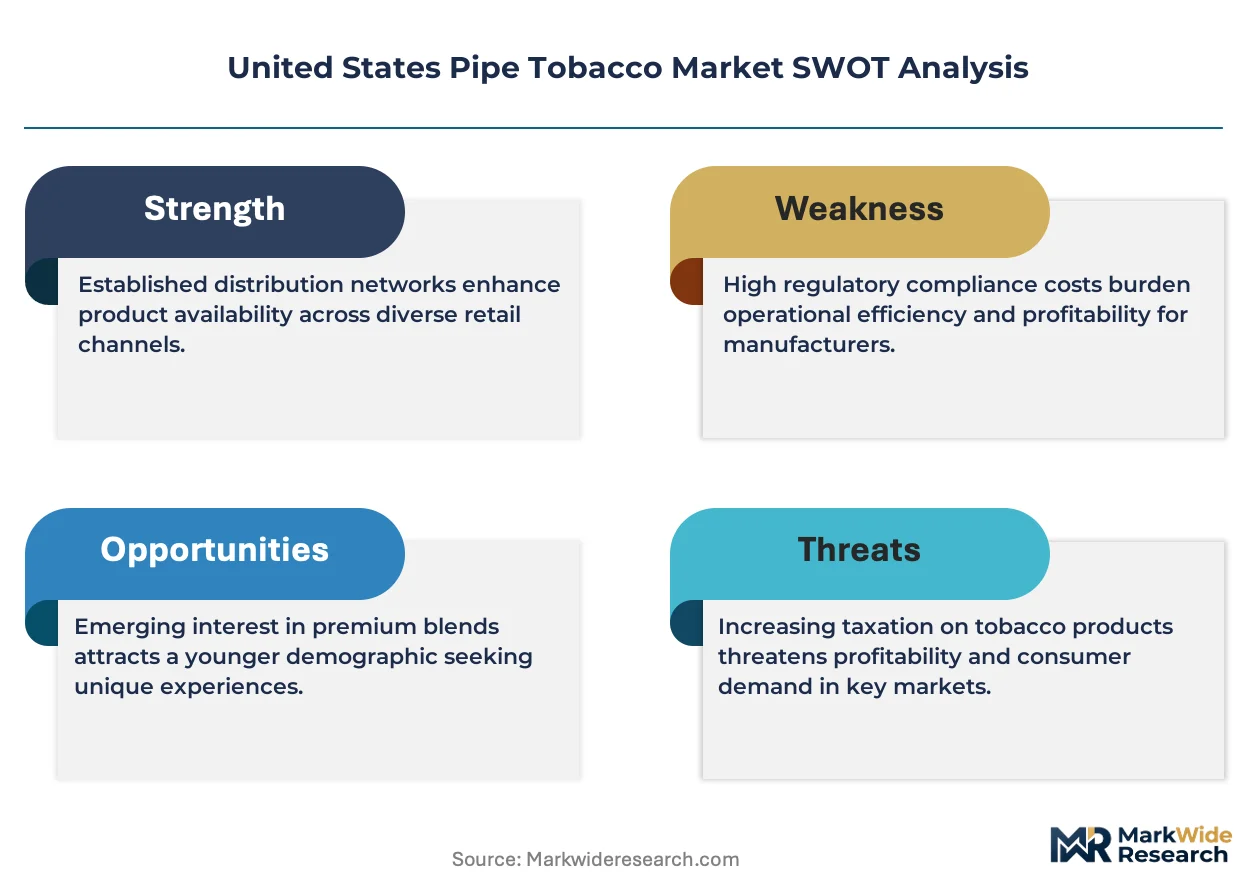
Regulatory Framework
FDA oversight under the Tobacco Control Act mandates premarket authorization for new pipe tobacco formulations, while state-level excise tax regimes in California, New York, and Illinois create fragmented pricing landscapes. The Prevent All Cigarette Trafficking Act and state minimum-age laws to twenty-one years constrain direct-to-consumer shipping channels. Stakeholders must monitor pending FDA guidance on flavored tobacco restrictions and assess whether grandfathered product status will survive judicial review.
Market Dynamics
FDA's deeming rule under the Family Smoking Prevention and Tobacco Control Act compresses product registration timelines while specialty retailers expand curated offerings, creating a bifurcated market where regulatory compliance costs and artisanal premiumization pull in opposite directions.
Growth Catalysts
- Ceremonial consumption revival:Ritual pipe smoking in veteran and fraternal organizations drives steady demand for traditional burley and Virginia blends across the Southeast.
- Specialty retail expansion:Boutique lounges in North Carolina and Virginia are building regional loyalty through small-batch curation and blending expertise.
- Air-cured leaf innovation:Natural wrapper varieties are reducing additive dependence and opening pathways for cleaner-label positioning within premium lines.
Market Restraints
- Excise tax fragmentation:California, New York, and Illinois impose divergent state-level levies that distort pricing parity and complicate national distribution strategies.
- Input cost volatility:Burley tobacco leaf prices fluctuate with weather patterns in Kentucky and Tennessee, squeezing margin predictability for mid-tier blenders.
- Direct-to-consumer shipping constraints:The Prevent All Cigarette Trafficking Act and state minimum-age laws block e-commerce channels, forcing reliance on brick-and-mortar networks.
Strategic Opportunities
- Flavor restriction carve-outs:Pending FDA guidance on flavored tobacco may exempt certain aromatic categories, creating grandfathered positioning for established blenders.
- Collector segment deepening:Aging connoisseurs in Virginia and North Carolina are driving demand for limited-release pressed cakes and aged cellar stock.
- Hybrid retail-lounge models:Combined tasting rooms and retail counters in urban Southern markets are capturing higher per-visit spend than conventional tobacconists.
Industry Challenges
- Blender skill scarcity:Master tobacconists with generational knowledge of air-curing and pressing techniques are retiring faster than apprenticeship programs replace them.
- Premarket authorization timelines:FDA review queues for new formulations extend development cycles, freezing innovation pipelines for smaller producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Pipe Tobacco Market |
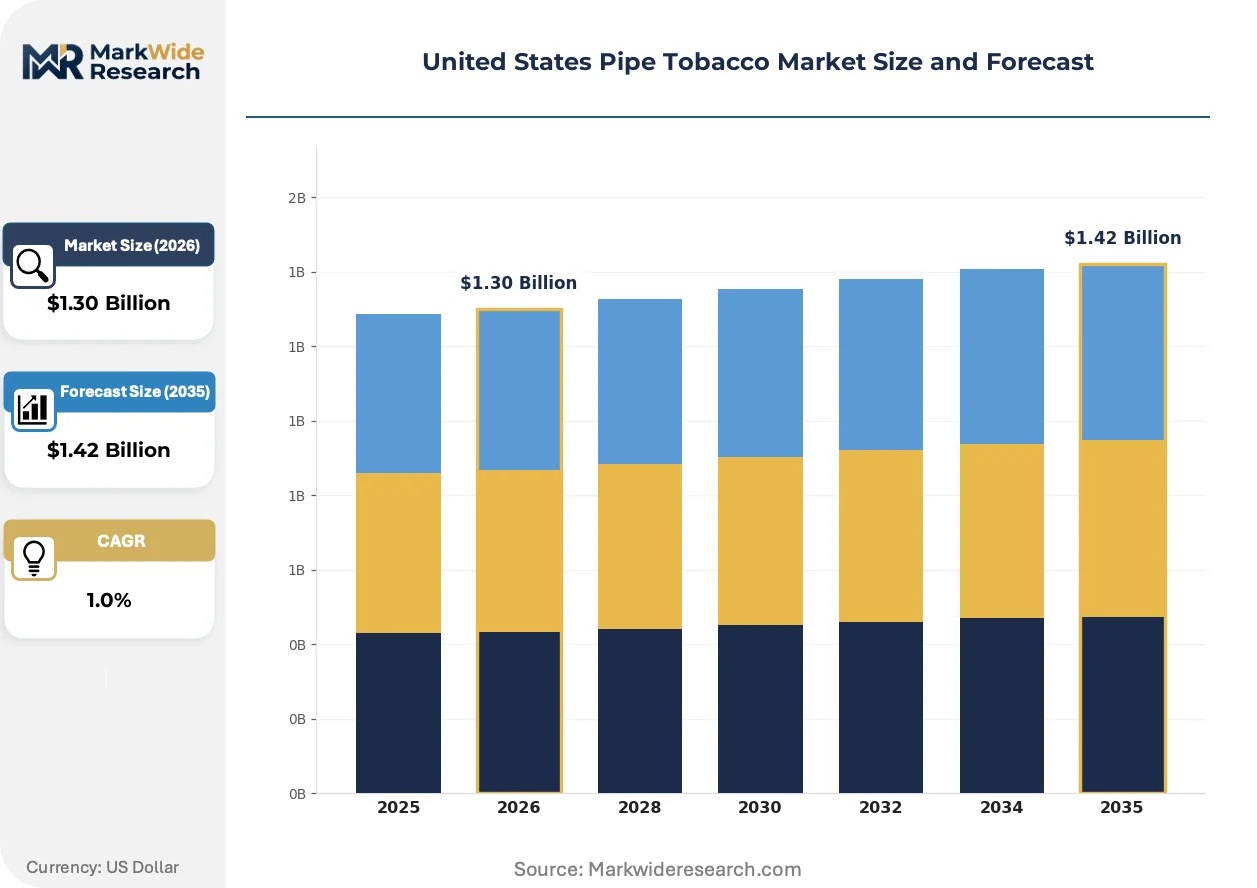
| Market Size in 2026 | $1.30 Billion |
| Market Size in 2035 | $1.42 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blended, Aromatic, Non-Aromatic, Premium Consumer Segment: Occasional Users, Regular Smokers, New Users, Long-Term Smokers Distribution Channel: Specialty Shops, Online Retail, Convenience Stores, Supermarkets Flavor Profile: Vanilla, Cherry, Cavendish, Menthol |
| Companies Covered | Turning Point Brands, Cornell & Diehl, Scandinavian Tobacco Group, British American Tobacco, Imperial Brands, Altria Group, Universal Corporation, S. M. Frank, Philip Morris USA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Pipe Tobacco Market Strategic Shifts
Moisture-controlled packaging and precision-cut technologies are redefining product consistency standards while regulatory pressure on flavor additives accelerates investment in natural curing methods.
Precision humidity control systems are converging with vacuum-sealed tin packaging to preserve optimal moisture content across extended distribution cycles. Specialty retailers in Virginia and North Carolina are adopting these systems to reduce inventory spoilage and justify premium positioning. The technology is converging with traditional cellar-aging practices, enabling controlled maturation programs that were previously limited to private collections.
FDA's pending guidance on flavored tobacco restrictions is forcing blenders to reformulate aromatic lines around natural leaf character rather than synthetic top-notes. Manufacturers with grandfathered product status are accelerating submissions to secure predicate eligibility before rule finalization. Non-aromatic and English-style categories stand to benefit as consumers migrate away from potentially restricted flavor profiles.
Collector-driven procurement is consolidating around limited-release drops and cellar-direct relationships with established blenders. Boutique lounges are displacing conventional tobacconists as the primary discovery channel for premium enthusiasts. This behavioral shift concentrates most visibly in North Carolina's Research Triangle and Richmond's fan district, where tasting events drive batch pre-sales.
United States Pipe Tobacco Market Segmentation
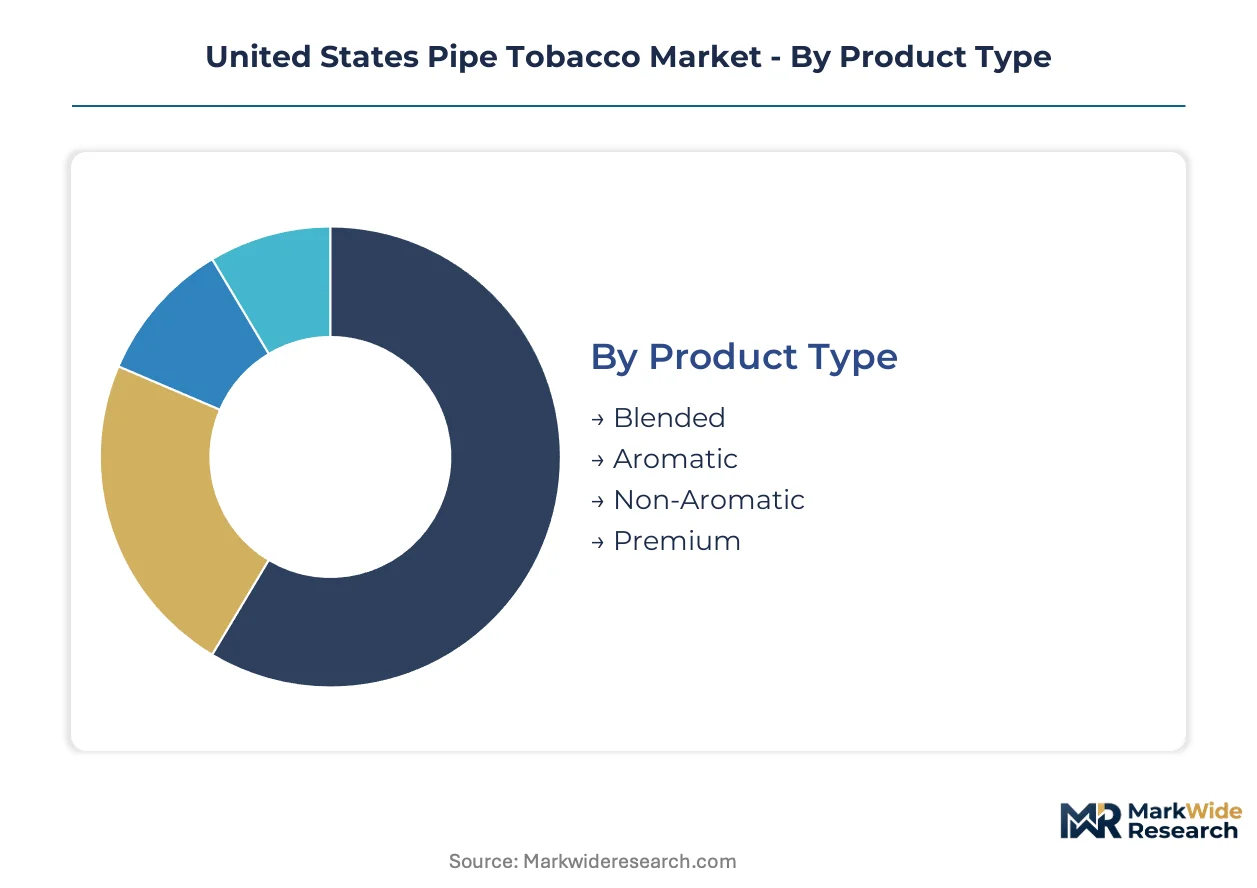
Pipe tobacco segmentation in the United States reflects divergent consumption rituals and procurement pathways. Product formulation determines margin structure while distribution channel governs customer acquisition economics and regulatory exposure.
Product Type:
Moisture content, cut width, and pressing method differentiate functional performance and cellar-aging potential across formulations.
- Blended:Combines burley, Virginia, and Oriental leaf varieties in precise ratios to balance combustion rate and nicotine delivery. Demand concentrates among regular smokers in North Carolina seeking consistent daily rotation stocks, constrained by burley price volatility from Kentucky growing regions.
- Aromatic:Top-dressed with casing solutions—vanilla, cherry, or honey—to produce pronounced room note and entry-level accessibility. New users in Virginia's college towns drive fastest adoption, though FDA flavor restriction proposals threaten reformulation requirements.
- Non-Aromatic:Relies on natural leaf character without synthetic additives, appealing to purists who prioritize tobacco-forward taste profiles. Long-term smokers in Richmond's fan district sustain niche demand.
- Premium:Limited-release pressed cakes and aged cellar stock command per-gram pricing multiples above standard lines. Collector procurement in the Research Triangle sustains small-batch profitability.
Blended leads on scale; Premium leads on momentum.
Consumer Segment:
Purchase frequency and ritual integration separate casual experimentation from committed consumption patterns.
- Occasional Users:Seasonal or ceremonial consumption tied to veteran gatherings and fraternal lodge meetings. Southeast ceremonial demand provides steady baseline volume.
- Regular Smokers:Daily or near-daily consumption with established cellar rotation and multi-tin procurement. North Carolina specialty shops capture highest per-customer lifetime value from this cohort.
- New Users:Entry-level aromatic adoption driven by boutique lounge sampling events. Virginia's urban markets show steepest expansion trajectory among younger demographics.
- Long-Term Smokers:Aging collectors with decades of cellar accumulation and direct blender relationships. Richmond and Durham clusters concentrate highest-value procurement.
Regular Smokers anchor revenue stability; New Users drive expansion velocity.
Distribution Channel:
Regulatory compliance burden and customer education requirements determine viable channel economics.
- Specialty Shops:Curated inventory with staff blending expertise and tasting room amenities. North Carolina and Virginia boutiques justify premium pricing through experiential service.
- Online Retail:Prevent All Cigarette Trafficking Act and state minimum-age laws block direct-to-consumer shipping, forcing platform reliance on age-verification partnerships with reduced margin.
- Convenience Stores:Mass-market aromatic pouches with minimal staff knowledge and price-competitive positioning. California and New York excise tax regimes compress profitability.
- Supermarkets:Limited SKU depth in tobacco-authorized sections, serving occasional replenishment rather than discovery.
Specialty Shops command margin concentration; Convenience Stores dominate unit velocity.
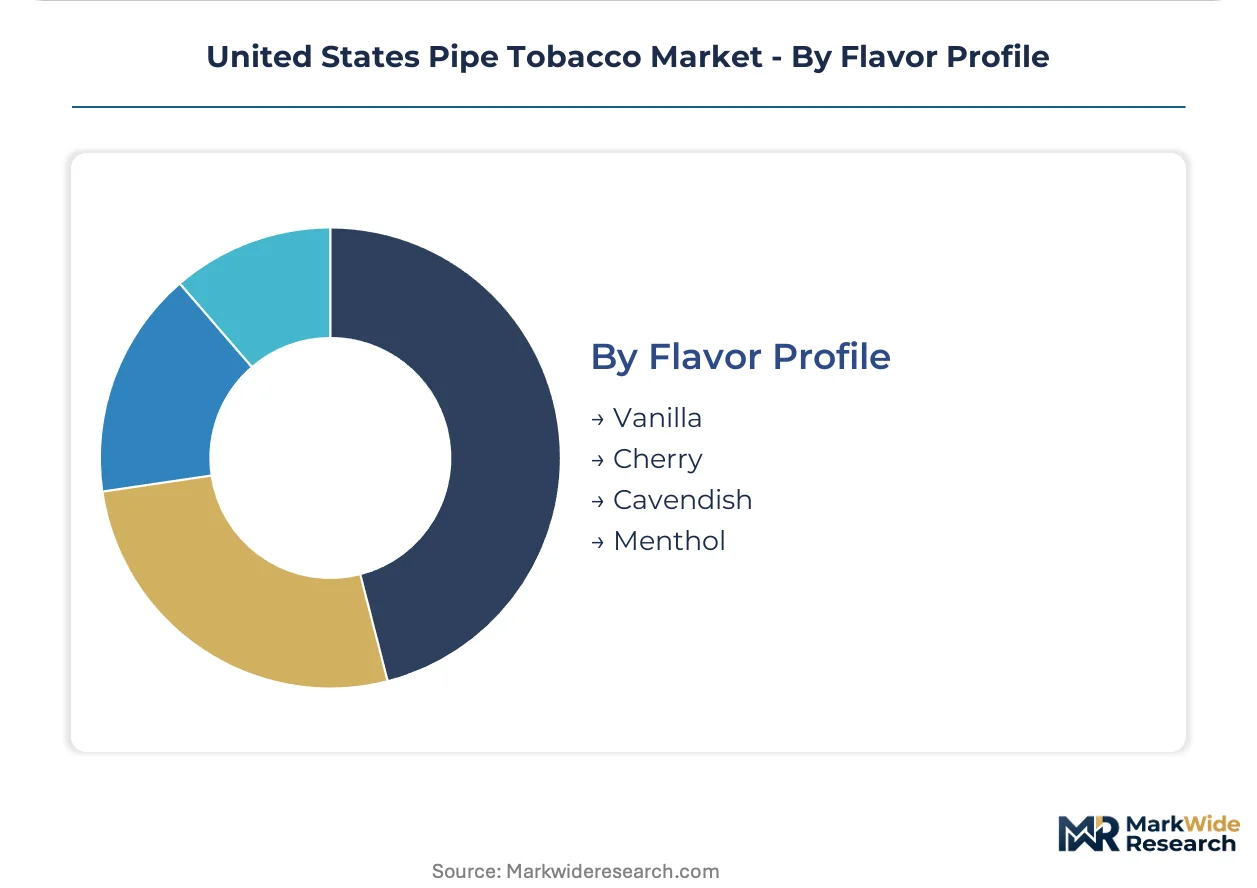
Flavor Profile:
Casing chemistry and top-note intensity separate mass-market accessibility from connoisseur segmentation.
- Vanilla:Creamy, sweet casing dominating entry-level aromatic lines. New user adoption in Virginia college markets sustains volume leadership.
- Cherry:Fruit-forward profile with pronounced room note, historically popular among ceremonial smokers in Southeast veteran organizations.
- Cavendish:Steam-pressed and cased burley or Virginia delivering mild, sweet smoke. Long-term smokers favor this for all-day rotation compatibility.
- Menthol:Cooling additive historically marginal in pipe tobacco, facing heightened FDA scrutiny under pending flavor restriction guidance.
Vanilla holds volume dominance; Cavendish gains share among aging connoisseurs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Research Triangle anchors national demand for premium pipe tobacco, with Raleigh-Durham boutiques driving collector procurement through limited-release drops and cellar-direct relationships with established blenders.
Southeast
Veteran organizations and fraternal lodges sustain ceremonial consumption of traditional burley and Virginia blends across North Carolina and Georgia. State excise tax regimes remain moderate relative to coastal markets, preserving price competitiveness for daily rotation stocks. Richmond's Fan District concentrates aging connoisseurs with decades of cellar accumulation.
Mid-Atlantic
Virginia's college towns generate entry-level aromatic adoption through boutique lounge sampling events targeting younger demographics. The FDA's deeming rule compliance costs weigh heavily on small-batch producers without grandfathered predicate status. Charlottesville and Fredericksburg specialty shops justify premium positioning through experiential tasting rooms.
Northeast Corridor
New York and Massachusetts impose elevated state-level excise levies that compress margin predictability for mass-market distribution. The Prevent All Cigarette Trafficking Act enforcement blocks direct-to-consumer shipping channels into these jurisdictions. Boston's historic tobacconists pivot toward private club models to sustain customer relationships.
Midwest
Kentucky and Tennessee growing regions supply burley leaf subject to weather-driven price volatility that squeezes mid-tier blender margins. Illinois divergent tax structure creates pricing discontinuities with neighboring states. Chicago's remaining specialty retailers concentrate on European import lines to differentiate from convenience channel commoditization.
West Coast
California's flavor restriction proposals threaten aromatic category viability in the nation's most populous state. Oregon and Washington follow similar regulatory trajectories, constraining product registration pathways for new formulations. Los Angeles and San Francisco lounges emphasize non-aromatic and English-style categories as consumers migrate away from potentially restricted profiles.
United States Pipe Tobacco Market Competitive Environment
Global majors compete with regional champions across distribution channel access, with diversified smokeless portfolios sustaining shelf presence in constrained retail environments while boutique specialists capture margin through experiential service models. The vendor base separates into three strategic archetypes: diversified conglomerates with regulatory compliance infrastructure, specialized pipe tobacco subsidiaries with generational blending expertise, and artisanal craft producers competing on small-batch scarcity. Dominant competitive moves include hybrid retail-lounge format expansion and accelerated premarket authorization submissions to secure grandfathered positioning ahead of pending FDA guidance.
Among diversified conglomerates, Turning Point Brands and Altria Group occupy positions defined by smokeless portfolio breadth and regulatory affairs capacity. Scandinavian Tobacco Group anchors the specialized subsidiary tier through dedicated pipe tobacco operations with deep air-curing and pressing knowledge. Cornell & Diehl exemplifies the artisanal craft archetype, representing small-batch producers competing on regional loyalty and limited-release scarcity within enthusiast communities.
| Leading Market Players |
|---|
| Turning Point Brands |
| Cornell & Diehl |
| Scandinavian Tobacco Group |
| British American Tobacco |
| Imperial Brands |
| Altria Group |
| Universal Corporation |
| S. M. Frank |
| Philip Morris USA |
| Others |
Value Chain & Pricing Dynamics
Master tobacconist labor concentration in Kentucky and Tennessee establishes the wage-cost baseline that separates premium pressed-cake pricing from mass-market pouch tiers. Generational blending expertise scarcity in these regions widens the spread between artisanal small-batch premiums and convenience-channel aromatics.
Pricing Analysis
Input-cost pass-through from burley leaf volatility in Kentucky growing regions compresses margins for mid-tier blenders while grandfathered premium lines absorb fluctuations through collector inelasticity. Three-tier pricing structure across premium, standard, and economy levels stratifies by cellar-aging potential and pressing method. Price differentiation hinges on moisture-control certification and limited-release scarcity. Pricing pressure stems from FDA premarket authorization costs freezing innovation pipelines. Occasional ceremonial users exhibit highest price sensitivity; aging connoisseurs in Richmond demonstrate lowest elasticity.
Supply Chain Analysis
Freight cost escalation on aged-cellar stock shipments from North Carolina's Research Triangle to West Coast lounges intensifies regional price discontinuities. Leaf sourcing concentrates in Kentucky, Tennessee, and Virginia with burley, Virginia Bright, and air-cured Oriental varieties. Raw material dependencies include climate-sensitive curing barn capacity, specialized pressing equipment, and vacuum-sealed tin packaging. Supply chain risk centers on single-source vulnerability for generational blending expertise. Distribution runs through hybrid retail-lounge networks in Southern states and constrained brick-and-mortar channels elsewhere.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as collector procurement shifts toward limited-release pressed cakes with documented cellar provenance.
For Market Incumbents: Acquire master tobacconist apprenticeship programs and cellar-aging facilities in Kentucky before generational knowledge retires. Secure grandfathered predicate status through accelerated FDA submissions to defend against flavor restriction rulings. Backward integration into air-cured leaf operations in Tennessee reduces burley price volatility exposure. For New Entrants and Emerging Players: Boutique lounge digital reservation and pre-sale platforms offer the lowest-friction customer acquisition pathway. Target Virginia's college-town aromatic segment through experiential sampling events. Hybrid retail-tasting room formats in North Carolina's secondary cities present the most penetrable white space. For Investors and Strategic Acquirers: Diversified smokeless conglomerates are the most active acquirer in this space, seeking artisanal craft producers with regional loyalty moats. Long-term viability rests on collector segment deepening and regulatory grandfathering durability. Watch FDA guidance finalization timing as the dominant inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Premarket Authorization Acceleration | Grandfathered predicate status under FDA deeming rule secures product continuity against flavor restrictions. |
| Master Tobacconist Apprenticeship | Generational blending knowledge transfer in Kentucky preserves air-curing expertise and pressing technique quality. |
| Hybrid Retail-Lounge Expansion | Combined tasting rooms and retail counters in North Carolina capture higher per-visit spend than conventional channels. |
| Cellar-Direct Relationship Building | Limited-release drops through established blender partnerships consolidate collector loyalty in Richmond and Durham. |
| Moisture-Control Packaging Investment | Vacuum-sealed tin technology with precision humidity systems reduces inventory spoilage for specialty retailers. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement covered master tobacconists, specialty shop proprietors, FDA regulatory affairs consultants, and veteran organization procurement officers. Secondary validation drew from FDA deeming rule dockets, state excise tax filings, customs leaf import records, and boutique lounge trade publications. Bottom-up volume modeling and top-down value triangulation reconciled segment-level estimates.
Comparable-period anchoring used historical consumption baselines from ceremonial and collector segments to calibrate projection trajectories across the analysis window. Segmentation dimensions included product formulation, consumer ritual frequency, distribution channel regulatory burden, and regional flavor preference clusters. CAGRs were derived from trend-line extrapolation adjusted for input cost volatility and compliance cost absorption rates. Forecast inputs incorporated burley leaf price indices and FDA review queue duration assumptions.
Flavor restriction finalization, master tobacconist retirement waves, and state excise tax harmonization are the dominant revision risks. Forecasts embody assumptions on grandfathered product survival and collector demand persistence. A model refresh is warranted upon material change in FDA guidance implementation timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco Products
Roll-Your-Own Tobacco Products Market
Tobacco Products
Middle East and Africa E-Cigarettes Market
Tobacco Products
E-Cigarette and Vape Market
Tobacco Products
Homemade Cigars Market
Tobacco Products
Tobacco Products Market
Tobacco Products
United States E-Cigarette Market
Tobacco Products
Electronic Cigarette Atomizer Market
Tobacco Products
Asia-Pacific E Cigarettes Market
Tobacco Products
Europe Cigarette Vending Machine Market
Tobacco Products
Tobacco Pouch Market
Tobacco Products
Premium Cigarette Market
Tobacco Products
Menthol Cigarette Market
Tobacco Products
GCC Cigarette Lighter Market
Tobacco Products
Europe E-Cigarettes Market
Tobacco Products
Global Flavor Capsule Cigarette Market
Tobacco Products
US E-Cigarette and Vape Market