
 Pregnancy Products Market | 2026-2036
Pregnancy Products Market Size, Share, and Industry Trends Forecast 2026-2036
Pregnancy Products Market Analysis
CE marking under the EU Medical Device Regulation is bifurcating competitive access between established manufacturers and new entrants seeking European market entry. Johnson & Johnson leverages its clinical heritage to anchor premium positioning across maternity skincare and prenatal nutrition. Abbott Laboratories specializes in evidence-based nutritional supplements, while Procter & Gamble competes through mass-channel distribution density and household brand recognition.
Pregnancy products encompass formulations, garments, and devices engineered for gestational health support, including prenatal vitamins with folic acid dosages between 400-800 mcg, stretch-mark creams with centella asiatica or hyaluronic acid matrices, and supportive maternity wear with adjustable compression engineering. Nutritional supplements and prenatal vitamins command the deepest margin pools due to recurring purchase cycles and physician endorsement requirements, while skincare segments attract premium pricing through clean-label and dermatologist-tested positioning. Online delivery modes are displacing pharmacy channels for replenishment purchases, though retail stores retain dominance for first-time trial and sizing-dependent maternity wear categories.
FDA oversight of prenatal supplements under 21 CFR Part 111 and EPA guidelines for fish oil mercury thresholds shape product formulation and label claim substantiation in the United States. The EU F-Gas Regulation and REACH restrictions on certain cosmetic preservatives further constrain ingredient palettes for skincare formulations sold across European markets. Stakeholders must monitor evolving pharmacovigilance reporting requirements and state-level supplement labeling laws to anticipate compliance cost shifts and regional portfolio prioritization.
Market Dynamics
Self-directed prenatal care is compressing traditional clinical intermediation, as expecting mothers leverage direct-to-consumer channels and digital health tools to manage gestational wellness independently of obstetric gatekeepers.
Growth Catalysts
- FDA 21 CFR Part 111:Stringent prenatal supplement manufacturing standards elevate physician trust in certified brands, driving prescription-adjacent purchasing behavior.
- Centella asiatica extraction:Advanced botanical processing yields higher-purity stretch-mark actives, expanding premium skincare addressability.
- Direct-to-consumer channels:Subscription replenishment models capture recurring vitamin purchases previously routed through pharmacy intermediaries.
Market Restraints
- Fish oil mercury thresholds:EPA contamination limits constrain omega-3 sourcing to Alaskan and Norwegian cold-water fisheries, creating supply bottlenecks.
- REACH cosmetic preservatives:ECHA restrictions on parabens and formaldehyde-releasing compounds force European skincare reformulation at elevated R&D cost.
- Adjustable compression engineering:Technical complexity in maternity wear sizing algorithms limits automation and scales labor intensity.
Strategic Opportunities
- Pharmacovigilance reporting:Evolving FDA adverse-event databases create first-mover advantage for manufacturers investing in real-world evidence infrastructure.
- Telehealth-integrated prenatal kits:Convergence of remote patient monitoring and at-home diagnostic devices opens clinical-adjacent positioning.
- Clean-label dermatologist testing:Third-party certification protocols enable premium pricing separation from mass-market skincare competitors.
Industry Challenges
- CE marking under EU MDR:Extended conformity assessment timelines for prenatal medical devices delay European market entry by 12-18 months.
- Hyaluronic acid matrix stabilization:Formulation chemistry expertise scarcity constrains stretch-mark cream efficacy claims and shelf-life extension.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pregnancy Products Market |
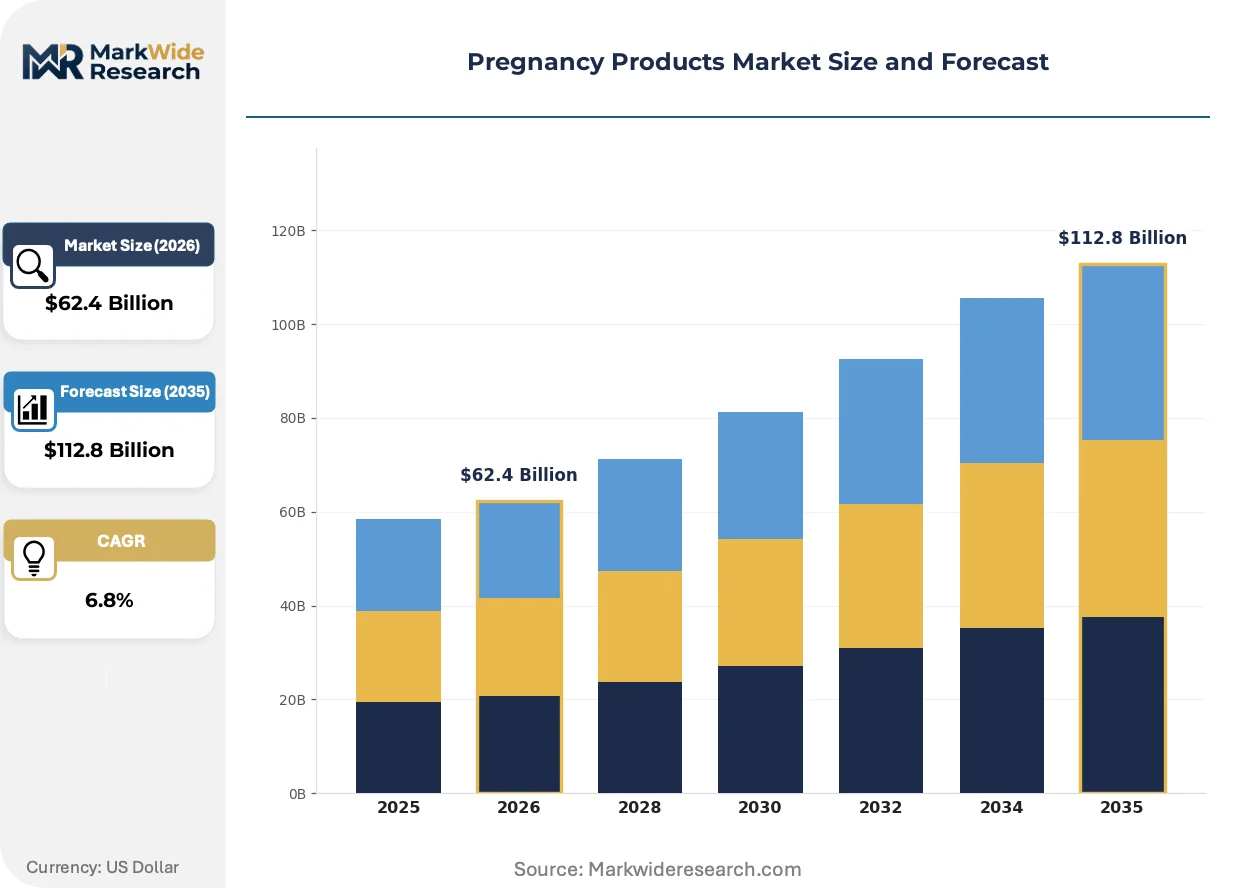
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $112.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Maternity Wear, Nutritional Supplements, Prenatal Vitamins, Skincare Delivery Mode: Online, Retail Store, Pharmacy, Subscription Customer Type: Expecting Mothers, Healthcare Providers, Family Members, Caregivers End Use Industry: Retail, Healthcare, E-commerce, Fitness |
| Companies Covered | Pfizer Inc., Church & Dwight Co., Inc., Johnson & Johnson, Nestlé S.A., Abbott Laboratories, Procter & Gamble Company, Reckitt Benckiser Group plc, Clarins Group, Bayer Aktiengesellschaft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pregnancy Products Market Emerging Trajectories
Wearable biometric integration and algorithmic sizing are redefining how pregnancy products deliver personalized gestational support, shifting value capture from static formulations to adaptive systems.
Wearable fetal heart rate monitors are miniaturizing from clinical-grade Doppler systems to consumer wristband formats. Expecting mothers in the United States are adopting these devices for daily anxiety reduction between obstetric visits. This compression of monitoring hardware is miniaturizing the boundary between medical-grade diagnostics and wellness accessories, forcing regulatory reclassification debates.
EU F-Gas Regulation phase-down schedules are eliminating hydrofluorocarbon propellants from aerosolized skincare delivery systems. Manufacturers serving European markets are reformulating with nitrogen or compressed air alternatives at 15-20% packaging cost elevation. Maternity skincare segments with high spray-format penetration face compressed margin structures and accelerated packaging supplier consolidation.
Subscription-based replenishment is displacing pharmacy counter purchasing for prenatal vitamin continuity. Direct-to-consumer platforms capture 60-day and 90-day supply commitments with automated dosage reminders and telehealth integration. This behavioral shift concentrates most visibly in United States metropolitan markets with high out-of-pocket health spending and established e-commerce logistics density.
Pregnancy Products Market Segmentation
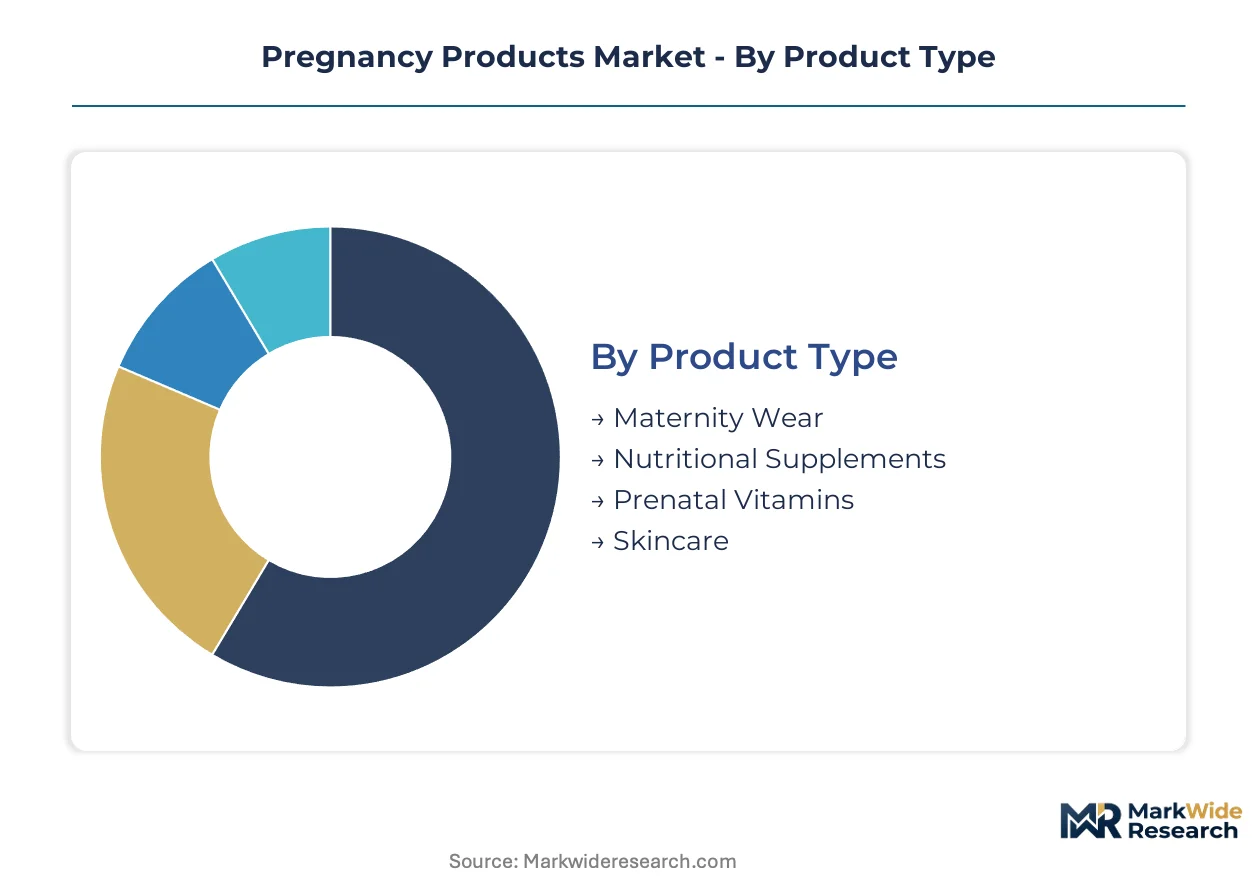
Segmentation in pregnancy products reveals how formulation science, channel economics, and care delivery models intersect to create distinct value pools. Understanding these divides helps manufacturers allocate R&D and distribution investments against shifting maternal behavior patterns.
Product Type:
Nutritional supplements face intensifying substitution pressure from food-based wellness protocols and personalized nutrition services, forcing brands to defend through clinical validation and physician channel anchoring.
- Nutritional Supplements:Evidence-based formulations including omega-3 DHA, iron bisglycinate, and choline complexes target gestational neurological development and maternal anemia prevention. Demand concentrates in United States metropolitan markets where obstetrician endorsement drives prescription-adjacent purchasing and recurring replenishment cycles.
- Prenatal Vitamins:Folic acid at 400-800 mcg dosages anchors all compliant formulations, with methylated B12 variants gaining share among MTHFR polymorphism-aware consumers. United States pharmacy and direct-to-consumer channels capture the deepest volume as FDA 21 CFR Part 111 certification elevates physician trust in certified brands.
- Maternity Wear:Compression-engineered garments with adjustable belly panels and lumbar support systems address third-trimester discomfort and postpartum recovery transitions.
- Skincare:Stretch-mark formulations deploy centella asiatica triterpenes and hyaluronic acid matrices to address dermal collagen remodeling during rapid abdominal expansion.
Nutritional supplements retain volume leadership; prenatal vitamins hold the steepest expansion curve.
Delivery Mode:
Channel cost structures stratify sharply, with subscription models capturing lifetime value through automated replenishment while retail stores absorb fixed real estate burdens for trial-dependent categories.
- Subscription:Automated 60-day and 90-day supply commitments with dosage reminder algorithms and telehealth integration capture recurring vitamin purchases. United States direct-to-consumer platforms dominate this mode where high out-of-pocket health spending and established e-commerce logistics density concentrate maternal purchasing behavior.
- Online:Marketplace and brand-direct websites displace pharmacy counter purchasing for replenishment and sizing-independent categories, though maternity wear returns logistics constrain pure-play penetration.
- Retail Store:Physical locations retain dominance for first-time trial, emergency replenishment, and sizing-dependent maternity wear categories where fit verification reduces return rates.
- Pharmacy:Counter-access channels maintain relevance for prescription-adjacent prenatal vitamins and pharmacist-counseled supplement selection, particularly among first-time mothers seeking clinical reassurance.
Retail stores retain volume leadership; subscription holds the steepest expansion curve.
Customer Type:
Purchasing authority fragmentation creates multiple entry points, with self-directed maternal decision-making compressing traditional clinical intermediation while family members expand gift and support-oriented buying.
- Expecting Mothers:Self-directed gestational wellness management through direct-to-consumer channels and digital health tools defines this segment's purchasing patterns. United States metropolitan consumers exhibit the strongest autonomous prenatal care behavior, driving subscription vitamin and wearable monitor adoption.
- Family Members:Gift-oriented purchasing for baby shower registries and postpartum support kits creates seasonal demand spikes and premium positioning opportunities in skincare and comfort products.
- Healthcare Providers:Obstetrician and midwife recommendation channels anchor prescription-adjacent supplement purchasing and medical-grade device referrals, though their direct intermediation role is compressing.
- Caregivers:Postpartum doula and home health aide procurement of recovery garments and nutritional support products serves secondary maternal care workflows.
Expecting mothers retain volume leadership; family members hold the steepest expansion curve.
End Use Industry:
Industry boundaries blur as healthcare and retail converge through telehealth-integrated commerce, while fitness applications extend product utility into gestational exercise protocols.
- Healthcare:Clinical settings and telehealth platforms drive medical-grade prenatal device adoption and prescription supplement protocols, with FDA premarket notification requirements tightening compliance obligations for device manufacturers.
- E-commerce:Pure-play and omnichannel platforms capture replenishment purchasing through algorithmic personalization and subscription infrastructure, displacing traditional pharmacy intermediation.
- Retail:Mass and specialty merchants maintain first-touch discovery and emergency purchasing roles, particularly for sizing-dependent categories and immediate-need scenarios.
- Fitness:Prenatal yoga studios and maternal exercise programs drive demand for supportive garments and recovery products targeting active gestational wellness protocols.
Healthcare retains volume leadership; e-commerce holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 21 CFR Part 111 certification requirements and high out-of-pocket health spending in the United States create the strongest regulatory and commercial incentives for pregnancy product manufacturers. Direct-to-consumer channels and subscription infrastructure concentrate maternal purchasing behavior in metropolitan markets with established e-commerce logistics density.
United States
Expecting mothers in metropolitan areas drive subscription vitamin adoption and wearable monitor penetration. FDA premarket notification requirements for prenatal medical devices tighten compliance obligations for manufacturers seeking clinical-adjacent positioning. The Boston-Cambridge corridor anchors medical-grade device development, while Los Angeles and New York concentrate clean-label skincare formulation.
Germany
CE marking under the EU Medical Device Regulation bifurcates competitive access between established manufacturers and new entrants. ECHA REACH restrictions on cosmetic preservatives force skincare reformulation at elevated R&D cost. The Rhine-Ruhr industrial cluster houses pharmaceutical-grade supplement manufacturing, while Bavaria concentrates precision engineering for compression garment production.
United Kingdom
Pharmacist-counseled supplement selection maintains relevance among first-time mothers seeking clinical reassurance. The Medicines and Healthcare products Regulatory Agency oversees prenatal device safety standards. London anchors direct-to-consumer brand headquarters, while the Midlands concentrate contract manufacturing for private-label maternity nutrition.
China
NMPA registration requirements for imported prenatal supplements create extended approval timelines for foreign brands. SAMR oversight of cross-border e-commerce channels shapes market entry strategies. Shanghai and Beijing concentrate premium skincare distribution, while Guangzhou anchors manufacturing for adjustable compression maternity wear exported to Southeast Asian markets.
India
FSSAI fortification guidelines for maternal nutrition products elevate domestic manufacturer compliance investment. CDSCO medical device rules classify certain prenatal monitors as regulated products requiring import licensing. Maharashtra and Gujarat concentrate pharmaceutical-grade supplement production, while Karnataka's Bangalore tech corridor hosts telehealth-integrated prenatal kit startups.
Pregnancy Products Market Vendor Landscape
Player mix skews toward diversified healthcare conglomerates with clinical heritage and mass-market consumer goods multinationals with pharmacy channel density. The competitive structure tiers across premium dermatologist-tested positioning, mass-channel volume scale, and evidence-based nutritional specialization. Dominant competitive moves include portfolio diversification into telehealth-integrated formats and geographic expansion through CE marking compliance for European market access.
Within the clinical heritage tier, Johnson & Johnson and Abbott Laboratories exemplify divergent strategic positioning. Johnson & Johnson anchors premium maternity skincare and prenatal nutrition through household brand recognition and physician channel relationships. Abbott Laboratories occupies a position centered on evidence-based nutritional supplements with methylated B12 variants and choline complexes. Nestlé S.A. represents the nutrition-science archetype with global formulation capabilities and emerging market distribution infrastructure.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Church & Dwight Co., Inc. |
| Johnson & Johnson |
| Nestlé S.A. |
| Abbott Laboratories |
| Procter & Gamble Company |
| Reckitt Benckiser Group plc |
| Clarins Group |
| Bayer Aktiengesellschaft |
| Others |
Supply Flow & Price Mechanics
Alaskan and Norwegian cold-water fishery capacity utilization anchors omega-3 DHA supply, concentrating ingredient pricing power among vertically integrated nutritional extractors while compressing margin pools for downstream formulators lacking backward integration into marine sourcing.
Pricing Analysis
Certification level (FDA 21 CFR Part 111/CE marking under EU MDR) creates the primary spread between prescription-adjacent prenatal vitamins and unverified dietary supplements. Three-tier pricing structure across premium dermatologist-tested skincare, mass-channel maternity wear, and economy generic nutrition separates methylated B12 formulations from standard folic acid variants. Pricing pressure stems from REACH cosmetic preservative reformulation costs and F-Gas Regulation packaging conversions in European markets. First-time mothers through pharmacy channels exhibit highest price sensitivity; subscription-committed direct-to-consumer buyers demonstrate lowest elasticity.
Supply Chain Analysis
Strait of Malacca transit bottlenecks threaten centella asiatica extract flows from Southeast Asian cultivation zones to European formulation facilities. Manufacturing gravity centers on the United States for FDA-certified supplements, Germany for precision-engineered compression garments, and China for adjustable maternity wear components. Raw material dependencies include Norwegian cod liver oil, Indian botanical extracts, and Chinese textile substrates. Single-source vulnerability concentrates in Alaskan pollock fisheries for DHA concentration. Distribution runs through direct-to-consumer platforms for replenishment cycles and retail pharmacy networks for trial purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telehealth-integrated prenatal kit ecosystems are compressing traditional channel intermediation, creating platform-economics inflection where interoperability between wearable biometric devices and subscription vitamin protocols determines customer lifetime value capture.
For Market Incumbents: Secure physician channel anchoring through FDA 21 CFR Part 111 certification investment to defend against direct-to-consumer subscription disintermediation. Backward integration into Alaskan and Norwegian marine sourcing protects omega-3 margin pools from extract supply volatility. Capacity addition in United States metropolitan markets with established e-commerce logistics density reinforces subscription replenishment capture. For New Entrants and Emerging Players: Lead with clean-label dermatologist-tested skincare positioning in United States coastal metropolitan markets where premium pricing tolerance concentrates. Telehealth-integrated prenatal kits represent the most penetrable white space, combining remote patient monitoring hardware with automated vitamin replenishment protocols. Go-to-market execution through Instagram-native influencer partnerships bypasses incumbent pharmacy channel control. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated nutritional specialists with captive marine extraction and methylated B12 formulation capabilities over pure-play skincare brands facing REACH reformulation cost compression. Acquisition target archetype: direct-to-consumer platforms with 60-day and 90-day subscription infrastructure and telehealth integration partnerships. Watch FDA premarket notification timeline extensions for wearable fetal monitors as inflection indicator for clinical-adjacent device valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth-Integrated Prenatal Kit Launch | Convergence of remote patient monitoring and subscription vitamin protocols captures clinical-adjacent positioning. |
| CE Marking Pathway Investment | EU MDR conformity assessment timelines determine European market entry sequencing against competitors. |
| Backward Integration into Marine Extraction | Captive Alaskan pollock sourcing insulates omega-3 DHA margins from fishery supply volatility. |
| Clean-Label Dermatologist Certification | Third-party testing protocols enable premium pricing separation from mass-market skincare competitors. |
| Direct-to-Consumer Platform Acquisition | Subscription infrastructure with automated dosage reminders displaces pharmacy counter replenishment. |
Methodological Framework
A standing panel of obstetricians, direct-to-consumer brand executives, FDA regulatory consultants, and maternity wear procurement managers provided ongoing calibration against market developments. Primary interviews with GPO contracts managers and hospital purchasing committees cross-referenced secondary validation through FDA 21 CFR Part 111 filings, EPA fish oil mercury threshold guidelines, ECHA REACH restriction updates, and customs records for centella asiatica extract imports. Bottom-up demand modeling and top-down category sizing triangulated volume estimates.
Consistency checks validated projections against external benchmarks including hospital procurement database trends and direct-to-consumer platform subscription disclosures. Segmentation dimensions spanned product type (nutritional supplements, prenatal vitamins, maternity wear, skincare), delivery mode (subscription, online, retail store, pharmacy), and customer archetype (expecting mothers, family members, healthcare providers, caregivers). CAGRs derived from logistic adoption curves for wearable biometric integration and subscription replenishment penetration. Industry-specific inputs included FDA premarket notification approval timelines and EU MDR CE marking assessment durations.
Underlying assumptions cover sustained direct-to-consumer channel expansion and stable EPA fish oil mercury thresholds, with deviation risk concentrated in REACH cosmetic preservative scope extensions and F-Gas Regulation phase-down acceleration. Practitioners should keep alternative scenarios live as telehealth reimbursement policy and state-level supplement labeling laws evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Baby Food Dispensing Spoon Market
Baby Products
Baby Bottle Warmers Market
Baby Products
Baby Bottle Holder Market
Baby Products
Baby Nose Suckers Market
Baby Products
Breast Milk Storage Products Market
Baby Products
Baby Pacifier Market
Baby Products
Automatic Baby Swing Market
Baby Products
Puppy Teething Toys Market
Baby Products
Baby Care Products Market
Baby Products
Baby and Toddler Feeding Products and Accessories Market
Baby Products
Baby Sleepsuits Market
Baby Products
South Africa Baby Care Products Market
Baby Products
Baby Sleeping Bag Market
Baby Products
Global Baby Car Seats Market
Baby Products
Baby Playpens Market
Baby Products
Asia-Pacific Baby Care Products Market