
 Automatic Baby Swing Market | 2026-2036
Automatic Baby Swing Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Baby Swing Market Analysis
Aftermarket service revenue is rewriting how manufacturers capture lifetime value from automatic baby swing owners. 4moms leverages its connected-product ecosystem to extend recurring revenue through app-based support and replacement part subscriptions. Graco sustains mass-market dominance through backward integration into frame manufacturing and broad retail distribution control. Nuna International BV differentiates through Scandinavian design positioning and premium material sourcing that commands elevated price tiers.
An automatic baby swing is a motorized infant seating device that generates rhythmic rocking motion through electromechanical drive systems, typically operating at variable speeds between 6 and 30 cycles per minute with AC adapter or battery power configurations. Its primary commercial purpose is to soothe infants through vestibular stimulation while freeing caregivers for concurrent household or professional tasks. Multi-function swing configurations now capture the fastest-growing margin pool as parents prioritize products combining motion, sound, and mobile device integration in single units. Bluetooth connectivity features attract disproportionate R&D investment as manufacturers compete for data-enabled customer relationships, while budget-tier portable swings face commoditization pressure from private-label import competition.
The Consumer Product Safety Commission enforces mandatory stability and restraint system standards for infant swing products sold in the United States, directly shaping engineering specifications and testing protocols. The EU's General Product Safety Regulation and CE marking requirements govern electrical safety and chemical compliance for European market access, while China's GB standards and SAMR oversight control domestic manufacturing certification and export quality benchmarks. Stakeholders must monitor evolving battery safety mandates and connected-device privacy frameworks as regulatory scope expands beyond mechanical safety into data governance and sustainable material disclosure obligations.
Market Dynamics
Bluetooth-enabled connectivity architectures are compressing R&D timelines across the automatic baby swing sector as manufacturers race to capture recurring revenue through app-based customer relationships and data-enabled service layers.
Growth Catalysts
- Dual-income household expansion:Working parents in the United States and Germany prioritize hands-free infant soothing solutions that enable concurrent professional and domestic task completion.
- EU General Product Safety Regulation:Tightened electrical and mechanical safety requirements for motorized nursery equipment are accelerating compliance investments that favor established manufacturers with testing infrastructure.
- Multi-function swing configurations:Integrated motion-sound-mobile units capture expanding margin pools as parents consolidate nursery equipment purchases into single premium devices.
Market Restraints
- Private-label import competition:Budget-tier portable swings from unbranded Asian manufacturers compress pricing power at the economy tier across mass retail channels.
- Input cost volatility:Electromechanical drive systems and certified flame-retardant textiles face supply concentration risk from concentrated Asian component suppliers.
- Substitution threat:Wearable infant carriers and smart bassinets with automated rocking functions divert demand from standalone swing purchases.
Strategic Opportunities
- Connected-device privacy frameworks:Early compliance with emerging data governance standards in the European Union creates competitive differentiation for privacy-forward brands.
- Replacement part subscriptions:Aftermarket service revenue streams through app-based support and component replacement programs extend lifetime customer value.
- Premium material sourcing:Scandinavian design positioning with certified organic textiles commands elevated price tiers in environmentally conscious urban markets.
Industry Challenges
- Certification timeline compression:CE marking and Consumer Product Safety Commission approval processes create launch delays for new electromechanical configurations.
- Integration complexity:Legacy manufacturing facilities face retrofitting costs to accommodate connected-product assembly lines and firmware update infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Baby Swing Market |
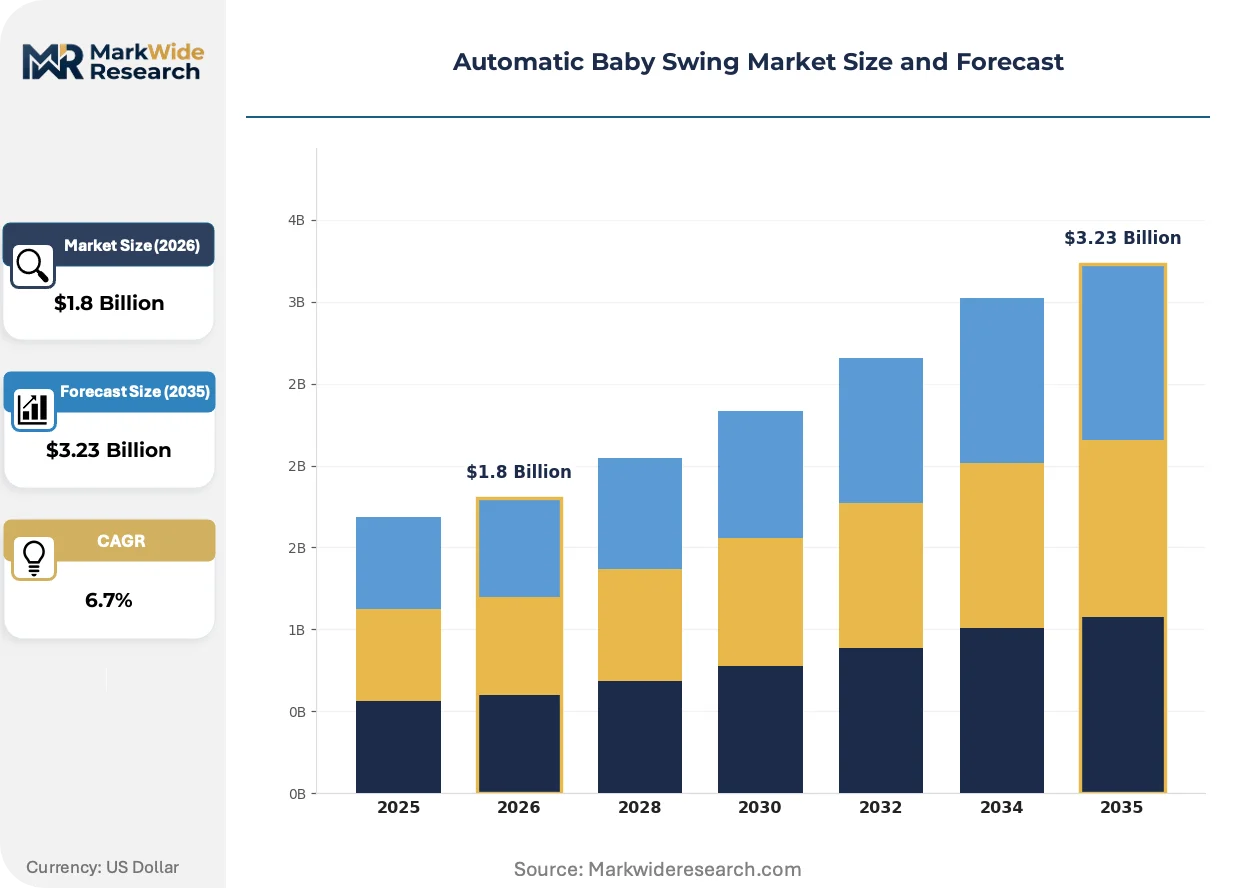
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Swing, Travel Swing, Multi-Function Swing, Portable Swing Feature: Bluetooth Connectivity, Battery Operated, Adjustable Speed, Reclining Seat End User: Parents, Caregivers, Retailers, Daycare Centers Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | 4moms, Artsana S.p.A., Kids II Inc., Mamas & Papas, Mattel Inc., Newell Brands Inc., Nuna International BV, Thorley Industries LLC, Graco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Baby Swing Market Emerging Trajectories
Electromechanical architectures and digital service layers are converging to redefine how infant soothing equipment generates value, shifting competitive advantage from hardware durability to ecosystem stickiness and data-enabled personalization.
Variable-speed motor control with adaptive motion sensing is migrating from fixed-cycle electromechanical systems to AI-responsive platforms that adjust rocking patterns based on infant biometric feedback. Premium buyers in the United States and United Kingdom are adopting these responsive configurations at accelerating rates. This migration from preset mechanical cycles to sensor-driven personalization is compressing replacement cycles for legacy inventory and forcing firmware-update capabilities into base product specifications.
REACH chemical compliance and the EU's expanding sustainable material disclosure obligations are reshaping textile sourcing protocols for infant contact surfaces. Manufacturers serving European markets must now document full supply chain chemical footprints from polymer production through finished fabric treatment. Swing producers with Nordic and German material partnerships are responding fastest, converting compliance investments into premium positioning through third-party organic certifications.
After-sales service unbundling from hardware purchase is disrupting traditional retail margin structures as direct-to-consumer brands capture replacement part and extended warranty revenue previously retained by physical retailers. Specialty baby boutiques and big-box chains face margin compression from this channel shift. The behavioral pivot is most visible in United States coastal metros where subscription-native millennial parents dominate nursery equipment procurement.
Automatic Baby Swing Market Segmentation
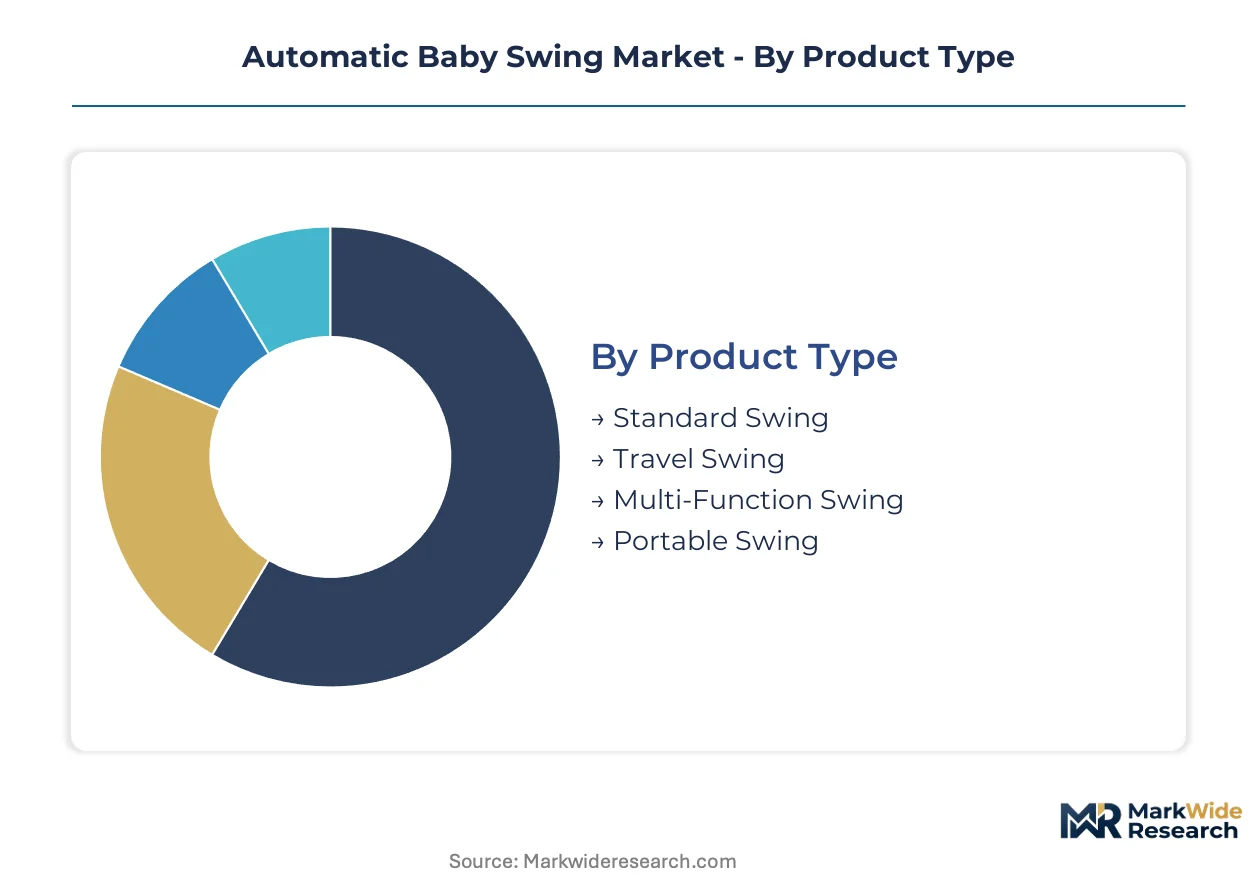
Automatic baby swing manufacturers calibrate portfolio depth across four intersecting dimensions—product configuration, connectivity features, buyer identity, and price positioning. Each segmentation axis carries distinct margin profiles and regulatory exposure that shape resource allocation decisions.
Product Type:
Mature electromechanical designs dominate hospital discharge gift registries while emerging multi-function configurations capture urban dual-income households seeking equipment consolidation.
- Standard Swing:Fixed-base electromechanical units with AC adapter power and preset motion cycles constitute the volume foundation. Demand concentrates in suburban United States markets where first-time parents prioritize proven safety certifications over feature expansion.
- Multi-Function Swing:Integrated platforms combining variable-speed motion, white noise generation, and mobile device docking command the fastest price tier expansion. Scandinavian and German urban buyers drive adoption as nursery space constraints favor equipment consolidation.
- Travel Swing:Collapsible frame designs with battery-first power configurations target grandparents and secondary caregivers. Compact folded dimensions enable trunk storage.
- Portable Swing:Lightweight battery-operated units with reduced swing arcs serve travel and multi-location caregiving. Private-label Asian imports compress margins at mass retail.
Standard Swing handles the majority of throughput; Multi-Function Swing is the fastest mover on share.
Feature:
Cost tier stratification runs from basic mechanical operation through app-enabled ecosystems that extend customer lifetime value.
- Bluetooth Connectivity:Firmware-updatable architectures enabling smartphone control and usage analytics capture disproportionate R&D investment. United States coastal metro parents adopt at rates exceeding interior markets as subscription-native behaviors transfer to nursery equipment.
- Adjustable Speed:Variable-frequency motor control between 6 and 30 cycles per minute addresses infant temperament variation. German and Austrian buyers treat precise speed calibration as a safety prerequisite.
- Battery Operated:Cordless power configurations using sealed lithium cells enable placement flexibility without outlet proximity. SAMR certification requirements in China constrain supplier selection.
- Reclining Seat:Multi-position mechanical or motorized seat angle adjustment accommodates infant development stages from newborn neck support to seated observation.
Adjustable Speed handles the majority of throughput; Bluetooth Connectivity is expanding most quickly.
End User:
Customer type segmentation maps to procurement authority and volume scale, from individual household decision-makers to institutional purchasing committees.
- Parents:Primary household decision-makers with direct usage experience drive premium tier adoption and connected-feature willingness to pay. United States dual-income households consolidate research and purchase authority.
- Caregivers:Extended family members and professional nannies influence replacement timing and portability requirements. Grandparent purchases skew toward travel-configured units.
- Retailers:Buyers for specialty baby boutiques and mass merchandisers calibrate assortment depth against inventory velocity and warranty return rates.
- Daycare Centers:Institutional procurement with multi-unit volume and commercial-grade durability specifications. CPSC commercial use standards apply.
Parents handle the majority of throughput; Daycare Centers are gaining share fastest.
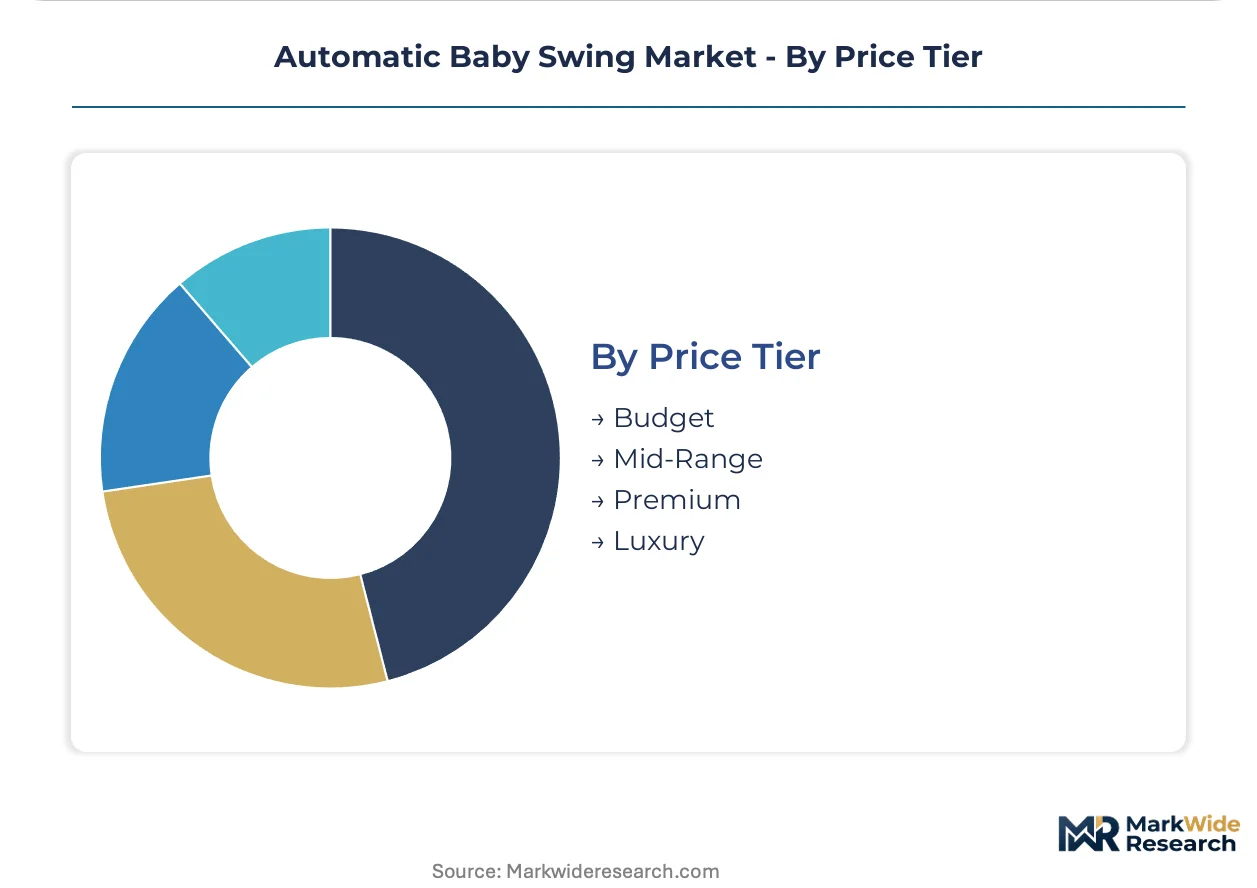
Price Tier:
Margin structure stratifies across four distinct value propositions from functional minimums through design-forward luxury positioning.
- Premium:Scandinavian design positioning with certified organic textiles and extended warranty terms commands elevated price floors. REACH-compliant supply chains enable EU market access.
- Mid-Range:Balanced feature sets with brand recognition and retail distribution support capture mainstream household budgets. Graco and similar established manufacturers anchor this tier.
- Budget:Functional electromechanical operation without connectivity or premium materials. Private-label competition and direct-from-Asia e-commerce compress differentiation.
- Luxury:Limited-edition collaborations with fashion houses and interior designers. Handmade components and exclusive textile sourcing create scarcity positioning.
Mid-Range handles the majority of throughput; Premium is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dual-income households in the United States deploy automatic baby swings as productivity tools for concurrent task completion, while German buyers treat precise electromechanical calibration as a safety prerequisite. This consumption-mix differential shapes divergent product specifications and pricing architecture across developed markets.
United States
Premium childcare technology commands sustained willingness to pay among coastal metropolitan parents with subscription-native purchasing behaviors. The Consumer Product Safety Commission enforces mandatory stability and restraint system standards that directly shape engineering specifications. Greater Boston and Pacific Northwest urban clusters drive adoption of Bluetooth-enabled configurations with app-based customer relationships.
Germany
Working parents prioritize hands-free infant soothing solutions that enable professional task completion alongside caregiving responsibilities. REACH chemical compliance and expanded sustainable material disclosure obligations reshape textile sourcing protocols for infant contact surfaces. Bavarian and Baden-Württemberg industrial regions host testing infrastructure that accelerates CE marking approval for compliant manufacturers.
United Kingdom
Urban nursery space constraints favor equipment consolidation into multi-function swing configurations combining motion, sound, and mobile integration. GDPR-connected device privacy frameworks create compliance differentiation for privacy-forward brands. London and Southeast England metropolitan areas concentrate demand for Scandinavian design positioning with certified organic textiles.
China
Domestic manufacturing certification under SAMR oversight controls export quality benchmarks for electromechanical drive systems. GB standards govern electrical safety and chemical compliance for products serving both domestic and international markets. Yangtze River Delta and Pearl River Delta industrial clusters concentrate component supply for motorized nursery equipment.
France
Environmentally conscious urban markets respond to third-party organic certifications that convert compliance investments into premium positioning. ANSM and CNIL oversight extends into connected-device data governance for Bluetooth-enabled nursery products. Île-de-France and Auvergne-Rhône-Alpes regions concentrate demand for design-forward luxury positioning with limited-edition textile sourcing.
Automatic Baby Swing Market Vendor Landscape
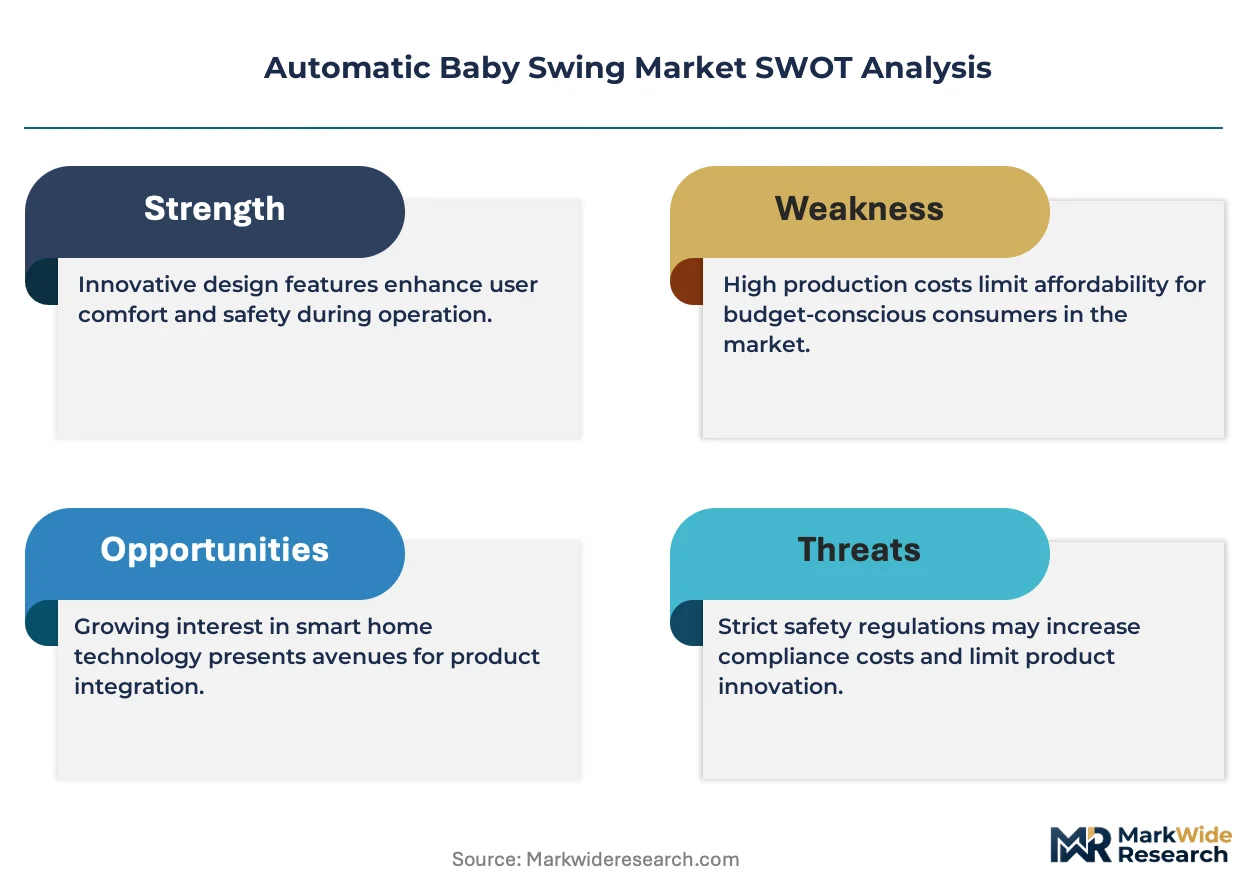
Capability concentration sits with design-forward specialists commanding premium price tiers; scale advantage sits with mass-market manufacturers with backward integration into frame production and broad retail distribution control. The vendor base stratifies across three strategic archetypes: connected-product ecosystem builders, Scandinavian design positioning specialists, and mass-market volume players with captive supply chains. Dominant competitive moves include portfolio diversification into multi-function configurations and geographic expansion through direct-to-consumer channels that capture aftermarket service revenue.
Within the connected-product ecosystem tier, 4moms exemplifies firmware-updatable architectures that extend recurring revenue through app-based support and replacement part subscriptions. Graco anchors the mass-market vector with in-house production capabilities and retail distribution density. Nuna International BV occupies a position within the Scandinavian design specialist tier, leveraging premium material sourcing partnerships that command elevated price floors in environmentally conscious urban markets.
| Leading Market Players |
|---|
| 4moms |
| Artsana S.p.A. |
| Kids II Inc. |
| Mamas & Papas |
| Mattel Inc. |
| Newell Brands Inc. |
| Nuna International BV |
| Thorley Industries LLC |
| Graco |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta manufacturing clusters determine downstream pricing power for electromechanical drive systems, with capacity utilization swings in Jiangsu and Zhejiang provinces feeding directly into component cost volatility for finished swing manufacturers. Battery cell availability and certified flame-retardant textile sourcing from concentrated Asian suppliers create asymmetric negotiating leverage that favors scaled incumbents with forward purchase commitments.
Pricing Analysis
Long-term offtake contracts for electromechanical components anchor manufacturer cost predictability, while spot market exposure for lithium cells and specialty textiles introduces margin volatility. Three-tier pricing structure across premium, standard, and economy levels separates Scandinavian design positioning with REACH compliance from mass-market feature parity and private-label commodity tiers. Price differentiation hinges on certification grade and after-sales service bundling. Pricing pressure stems from private-label Asian imports compressing economy-tier margins. Daycare center procurement committees exhibit highest price sensitivity; coastal dual-income households show lowest.
Supply Chain Analysis
Contract manufacturing concentration rests with Dongguan and Shenzhen electronics assemblers for drive system integration, paired with Ningbo and Shaoxing textile converters for certified infant-contact fabrics. Electromechanical motors, lithium battery packs, and flame-retardant polymers draw from Chinese, South Korean, and Taiwanese supplier bases. Single-source vulnerability in semiconductor motor controllers poses structural risk. Distribution runs through mass retail chains, specialty baby boutiques, and direct-to-consumer channels capturing replacement part subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Few manufacturers possess integrated firmware development capabilities alongside certified textile supply chains, creating a capability scarcity that rewards players bridging hardware and connected-service competencies.
For Market Incumbents: Build ecosystem stickiness through app-based customer relationships that capture replacement part subscriptions and extend lifetime value beyond hardware margins. Fortify backward integration into frame manufacturing to defend against private-label import competition. Accelerate CE marking and CPSC certification investments to compress new entrant launch timelines. For New Entrants and Emerging Players: Premium Scandinavian design positioning in environmentally conscious urban markets represents the most penetrable entry point, as established players underinvest in third-party organic certifications. Direct-to-consumer channels with subscription-native millennial parents in United States coastal metros offer lower customer acquisition costs than retail slotting battles. Lead with privacy-forward GDPR compliance as competitive differentiation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors connected-product ecosystem builders with firmware-updatable architectures over pure hardware manufacturers facing replacement cycle compression. Long-term viability rests on data-enabled service revenue streams rather than transactional hardware margins. Monitor Bluetooth connectivity adoption rates and replacement part subscription attach ratios as inflection indicators. Quarterly review of regulatory filing velocity and connected-device privacy framework compliance is advised to detect inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Connected-Product Ecosystem Development | Firmware-updatable architectures enable recurring revenue through app-based support and replacement part subscriptions. |
| Backward Integration into Frame Manufacturing | In-house production capabilities defend margin position against private-label Asian import competition. |
| REACH Compliance and Organic Certification | Third-party certifications convert regulatory investments into premium positioning in EU urban markets. |
| Direct-to-Consumer Channel Expansion | Subscription-native millennial parents in coastal metros drive higher lifetime value capture than retail. |
| Multi-Function Configuration Portfolio | Integrated motion-sound-mobile units address nursery space constraints in dense urban households. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of CPSC enforcement databases, EU RAPEX safety alerts, customs trade records, and manufacturer SEC filings. Product development executives at connected-device manufacturers, procurement leads at mass retail chains, regulatory affairs specialists, and aftermarket service heads provided structured input. Bottom-up shipment triangulation against top-down household penetration estimates validates volume assumptions.
Forecast inputs span product configuration segmentation, connectivity feature tiers, buyer identity archetypes, and price positioning bands across the analysis window. CAGRs derive from regression against dual-income household formation rates, regulatory compliance cost trajectories, and substitution elasticity from wearable carriers and smart bassinets. Electromechanical component cost curves and connected-device privacy framework adoption timelines inform trajectory bounds.
Practitioners should monitor SAMR certification delays, REACH chemical disclosure expansion, and lithium cell supply concentration for early signals of forecast revision. Assumptions reflect current regulatory enforcement intensity and parental technology adoption patterns. Quarterly review of CPSC recall filings, EU rapid alert system entries, and Bluetooth connectivity feature attach rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Feeding Pillow Market
Baby Products
Baby Feeding Accessories Market
Baby Products
Baby Sleepsuits Market
Baby Products
Baby and Toddler Feeding Products and Accessories Market
Baby Products
Global Baby Pajamas and Sleepwears Market
Baby Products
Noise-Muffling Infant Hat Market
Baby Products
Asia-Pacific Baby Care Products Market
Baby Products
Baby Bassinets Market
Baby Products
Children Products Market
Baby Products
LAMEA Baby Care Products Market
Baby Products
Breast Milk Storage Products Market
Baby Products
Baby Nail Trimmer Market
Baby Products
Italy Baby Care Products Market
Baby Products
Durable Juvenile Products Market
Baby Products
Baby Swaddle Wrap Market
Baby Products
Global Pregnancy Pillow Market