
 Baby and Toddler Feeding Products and Accessories Market | 2026-2036
Baby and Toddler Feeding Products and Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Baby and Toddler Feeding Products and Accessories Market Analysis
Hospital nursery and neonatal intensive care unit procurement is realigning toward clinically validated feeding systems with measurable flow-rate consistency. Philips Avent leverages its clinical channel partnerships across European maternity wards to sustain premium positioning. Medela AG anchors its presence through hospital-grade pump-to-bottle ecosystems that dominate lactation consultant recommendations. Pigeon Corporation competes in Asian markets with specialized anti-colic venting geometries developed for smaller infant oral anatomy.
Baby and toddler feeding products and accessories encompass vessels, utensils, and supplementary equipment engineered for controlled nutrient delivery from birth through preschool years, typically specified by flow-rate capacity, nipple shore hardness, thermal shock resistance, and compliance with food-contact migration limits. Silicone formulations with Shore A 30-50 softness now lead infant segments due to peristaltic latch compatibility and thermal stability from -40°C to 230°C. Glass bottles retain structural share among caregivers prioritizing chemical inertness despite weight and fragility trade-offs, while stainless steel sippy cups capture toddler transition demand through impact resistance and extended temperature retention.
The FDA maintains food-contact notification requirements under 21 CFR for polymer migration testing, while the EU REACH Annex XVII restricts phthalate plasticizers in articles for children under three years. China's SAMR enforces GB standards for infant feeding vessels with mandatory migration testing for volatile organic compounds and heavy metals. Stakeholders must monitor evolving substance restrictions and certification reciprocity agreements to anticipate reformulation costs and regional market access conditions.
Market Dynamics
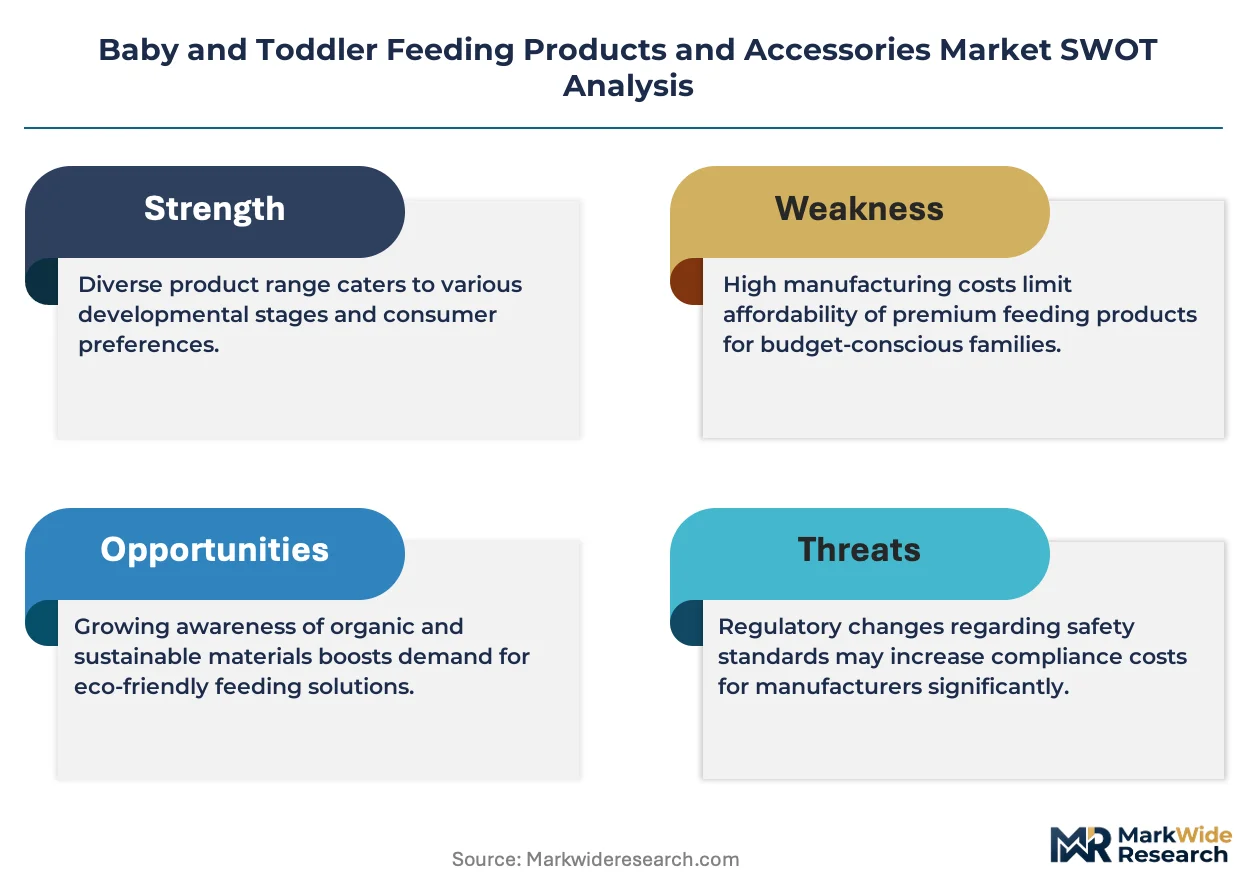
Material compliance costs are compressing mid-tier margins as FDA food-contact notifications and EU REACH phthalate restrictions force simultaneous reformulation across silicone, TPE, and polymer supply chains.
Growth Catalysts
- Urban Middle-Class Expansion:China's tier-one cities sustain volume through birth-rate stabilization policies and dual-income household formation. SAMR-enforced GB standards create quality-tier segmentation that rewards certified suppliers.
- REACH Annex XVII Restrictions:Phased phthalate bans in articles for children under three years accelerate BPA-free and alternative plasticizer adoption across European procurement channels.
- Anti-Colic Venting Geometries:Specialized nipple designs addressing smaller infant oral anatomy penetrate Asian hospital nursery and retail channels through lactation consultant validation.
Market Restraints
- Medical-Grade Silicone Concentration:Four specialty chemical suppliers control 70% of Shore A 30-50 formulation capacity, creating input cost volatility during semiconductor and automotive demand spikes.
- Glass Weight Penalty:Structural fragility and 3-4x mass versus polymer alternatives limit caregiver portability demand and constrain distribution economics.
- Migration Testing Burden:FDA 21 CFR polymer notification requirements and EU food-contact regulations impose 12-18 month certification timelines that freeze product refresh cycles.
Strategic Opportunities
- Stainless Steel Toddler Transition:Impact-resistant sippy cups with extended temperature retention capture preschool-aged demand in North American and European markets where durability premiums command pricing power.
- Hospital-Grade Pump Integration:Closed-system breast pump-to-bottle ecosystems reduce contamination risk and create captive accessory demand through proprietary connector geometries.
- India PLI Scheme Alignment:Domestic manufacturing incentives for medical devices and food-contact materials reduce import dependency and enable cost-competitive export positioning.
Industry Challenges
- Peristaltic Latch Simulation:Biomechanical engineering talent scarcity constrains nipple softness optimization and flow-rate consistency validation for premature infant segments.
- Multi-Jurisdiction Certification:Simultaneous FDA, EFSA, and SAMR compliance requires redundant testing protocols that extend product development cycles and strain quality assurance bandwidth.
- Thermal Shock Resistance:Glass-to-polymer hybrid designs demand materials science capabilities that mid-tier manufacturers lack, creating capability gaps in premium segment access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby and Toddler Feeding Products and Accessories Market |
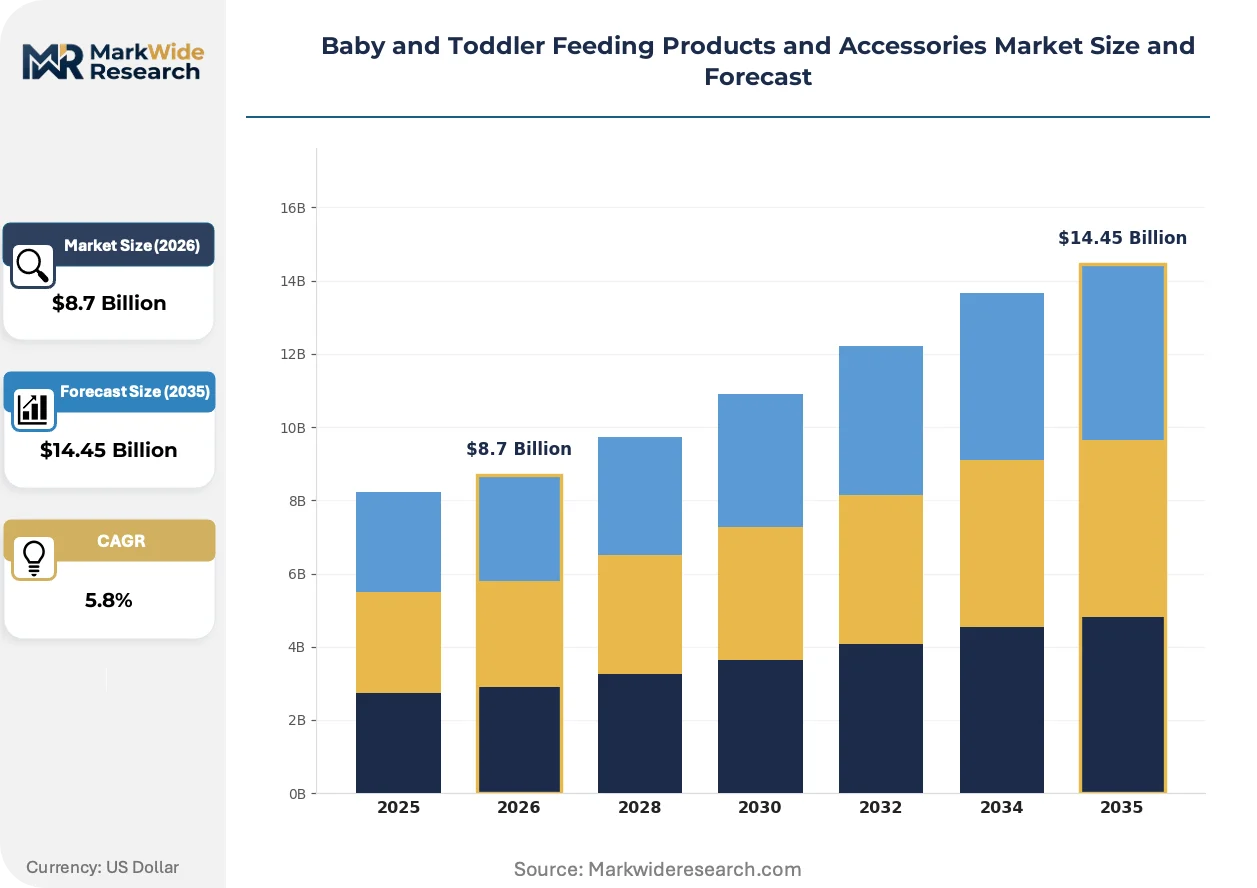
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Sippy Cups, Feeding Bowls, Utensils Material: Plastic, Glass, Silicone, Stainless Steel Age Group: Infants, Toddlers, Newborns, Preschoolers Distribution Channel: Online Retailers, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | Philips Avent, Medela AG, Tommee Tippee, NUK, Dr. Brown's, Munchkin, Pigeon Corporation, Chicco, Playtex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby and Toddler Feeding Products and Accessories Market Emerging Trajectories
Silicone formulation chemistry and connected monitoring technologies are redrawing competitive boundaries between clinical-grade and consumer-grade feeding systems.
Advanced Shore A durometer control is decentralizing production scale requirements for peristaltic-compatible nipples. Regional compounders in Germany, Japan, and the United States now achieve medical-grade softness consistency without captive chemical plant investment. This capability diffusion enables mid-tier brands to source clinically validated materials from third-party specialists rather than vertically integrated multinationals.
EU REACH substance restrictions are tightening migration limits for volatile organic compounds in infant feeding vessels. The industrial consequence is accelerated substitution of conventional plasticizers with bio-based alternatives and cross-linked silicone architectures. Asian export-oriented manufacturers are responding with dedicated GB-standard-plus-REACH compliance lines to maintain European market access.
Caregiver purchasing behavior is fragmenting across subscription-based replenishment models and direct-to-clinic procurement channels. Traditional retail shelf presence is losing share to lactation consultant recommendations and hospital discharge kit inclusion in North American and European markets. This channel rotation is most visible in neonatal intensive care unit procurement, where measurable flow-rate consistency documentation overrides brand recognition.
Baby and Toddler Feeding Products and Accessories Market Segmentation
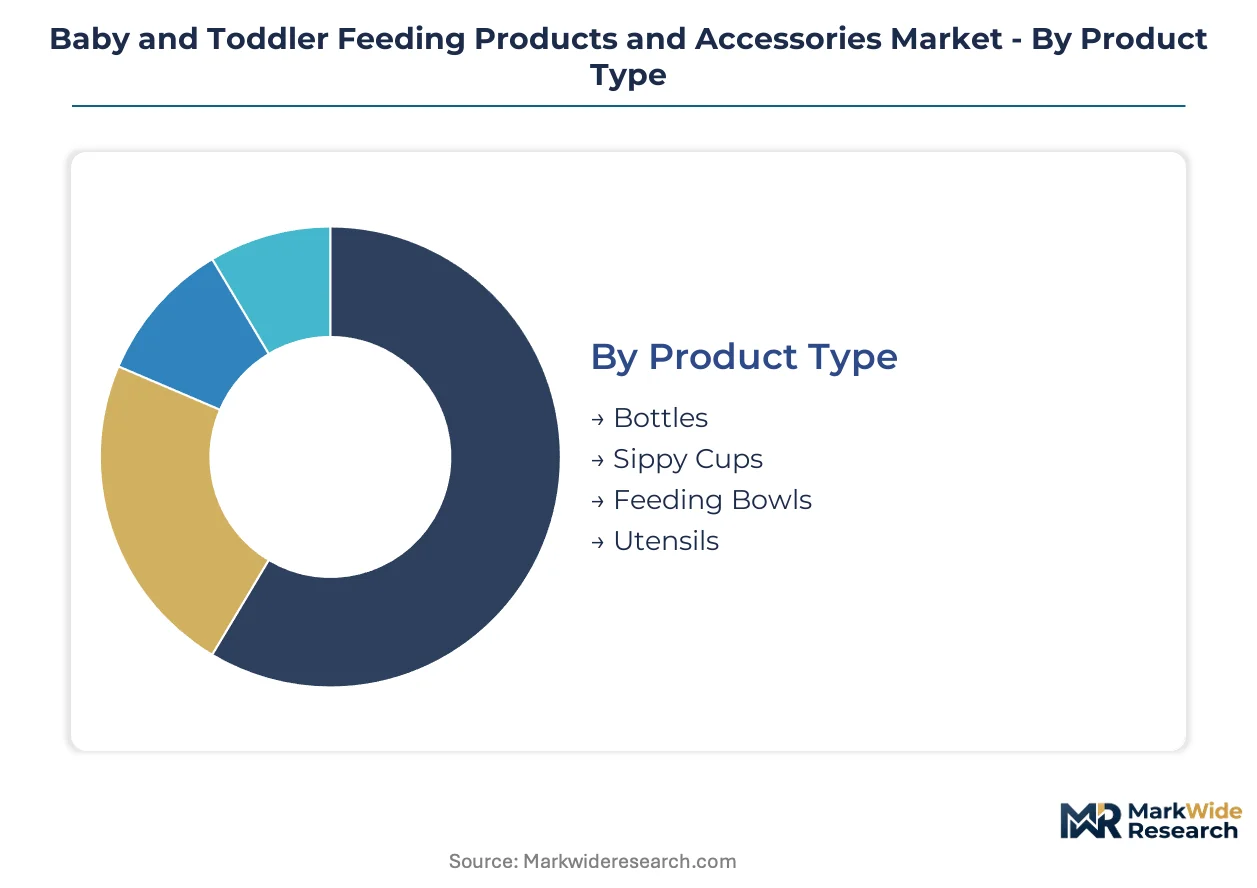
Segmentation in baby and toddler feeding products reveals how material science, developmental physiology, and channel economics intersect to shape procurement decisions across clinical and consumer settings. Understanding these dimensions exposes where formulation investments concentrate and which compliance frameworks govern market access.
Product Type:
Bottle geometry and flow-rate engineering separate hospital-grade procurement from mass-market retail, with anti-colic venting commanding premium positioning.
- Bottles:Vessels with Shore A 30-50 silicone nipples dominate clinical validation pathways through measurable flow-rate consistency. Hospital nursery and NICU procurement in Germany, Japan, and the United States prioritizes documented peristaltic latch compatibility over brand recognition.
- Sippy Cups:Toddler transition vessels with spill-resistant valve mechanisms capture durability premiums in North American and European markets. Stainless steel variants with extended temperature retention command pricing power among dual-income households prioritizing impact resistance.
- Feeding Bowls:Suction-base designs with thermal compartments address independent feeding skill development. BPA-free polymer formulations with microwave-safe ratings concentrate in mass-market retail channels.
- Utensils:Ergonomic grip geometries for pincer grasp development accompany bowl sets in bundled offerings. Soft-tip silicone spoons lead infant segments due to gum-safe Shore hardness ratings.
Bottles lead volumes today; sippy cups are gaining share fastest through preschool-aged durability demand.
Material:
Migration testing burdens and thermal performance requirements fragment sourcing strategies across silicone chemistry, glass architecture, and metal forming capabilities.
- Silicone:Cross-linked Shore A 30-50 formulations achieve peristaltic latch compatibility with thermal stability from -40°C to 230°C. Regional compounders in Germany and Japan now supply medical-grade consistency without captive chemical plant investment.
- Plastic:BPA-free TPE and polymer alternatives face REACH Annex XVII phthalate restrictions forcing bio-based plasticizer substitution. FDA 21 CFR notification requirements impose 12-18 month certification timelines.
- Glass:Borosilicate structures retain chemical inertness demand among caregivers prioritizing zero-migration assurance. Weight penalties of 3-4x versus polymer alternatives constrain portability economics.
- Stainless Steel:Impact-resistant 18/8 grade compositions capture toddler sippy cup demand through extended temperature retention. India PLI scheme alignment enables cost-competitive export positioning.
Plastic leads volumes today; silicone is expanding most quickly through clinical channel penetration.
Age Group:
Oral anatomy development stages dictate nipple shore hardness specifications and flow-rate capacity engineering.
- Newborns:Preterm infant segments demand ultra-soft Shore A 20-30 formulations with micro-flow orifices validated for measurable consistency. Biomechanical engineering talent scarcity constrains supply.
- Infants:Standard 0-12 month specifications center on peristaltic latch simulation with anti-colic venting geometries. Pigeon Corporation's Asian-market specialized designs address smaller oral anatomy.
- Toddlers:Transition feeding with sippy cup valves and self-feeding utensils accompanies motor skill milestones. Durability premiums command pricing power in stainless steel and reinforced polymer segments.
- Preschoolers:Independent feeding proficiency sustains demand for impact-resistant tableware with portion-control features. Extended-use warranties differentiate premium offerings.
Infants lead volumes today; newborns show steepest expansion trajectory through NICU procurement realignment.
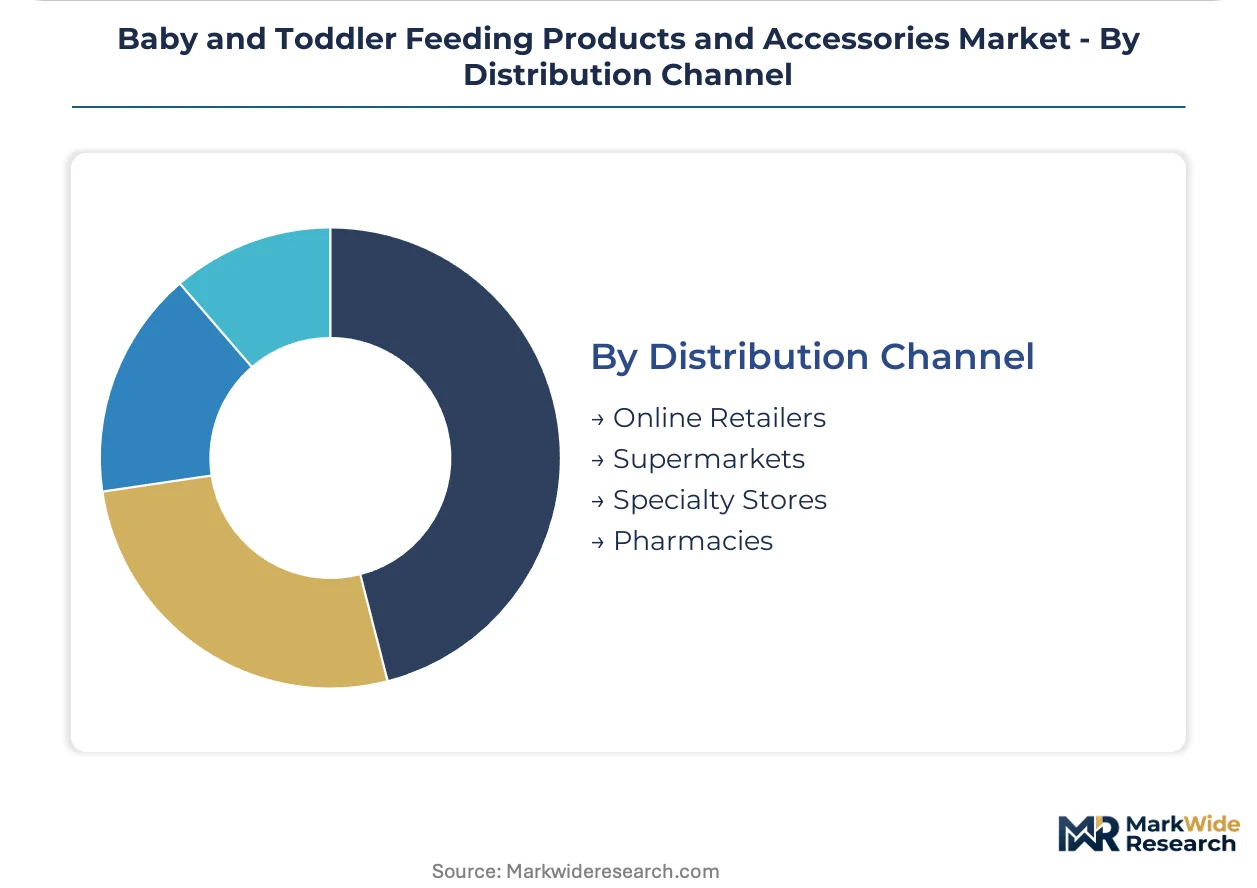
Distribution Channel:
Channel selection determines whether lactation consultant validation or retail shelf presence governs purchase decisions.
- Online Retailers:Subscription-based replenishment models fragment traditional retail economics through direct-to-consumer logistics. Review aggregation platforms amplify clinical validation signals.
- Supermarkets:Mass-market volume concentrates in bundled starter sets with price-promotional mechanics. SAMR-enforced GB standards in China create quality-tier segmentation rewarding certified suppliers.
- Specialty Stores:Curated assortments with lactation consultant endorsement capture premium positioning in European and North American urban markets. Hospital discharge kit inclusion drives brand loyalty.
- Pharmacies:Clinical-grade pump-to-bottle ecosystems dominate through Medela AG's closed-system connector geometries. Pharmacist recommendation protocols sustain repeat accessory purchases.
Supermarkets lead volumes today; specialty stores are climbing the fastest through consultant-validated channel rotation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting manufacturing investment toward jurisdictions where GB-standard-plus-REACH compliance lines lower cost-of-entry for European market access. Specialty chemical compounders in Germany and Japan now supply medical-grade silicone without captive plant investment, enabling mid-tier brands to bypass legacy multinational supply chains.
China
SAMR-enforced GB standards for infant feeding vessels sustain quality-tier segmentation that rewards certified suppliers. Birth-rate stabilization policies and urban middle-class expansion in tier-one cities concentrate volume demand. Yangtze River Delta manufacturing clusters host dedicated export lines combining GB, REACH, and FDA compliance to serve European and North American procurement channels.
United States
FDA 21 CFR food-contact notification requirements impose 12-18 month certification timelines that freeze product refresh cycles for polymer formulations. Hospital nursery and NICU procurement in metropolitan maternity wards prioritizes clinically validated feeding systems with documented flow-rate consistency. Greater Boston and Pacific Northwest clusters anchor lactation consultant-validated distribution networks.
Germany
ECHA REACH Annex XVII phthalate restrictions in articles for children under three years accelerate BPA-free and bio-based plasticizer substitution. Bavaria and North Rhine-Westphalia host regional silicone compounders achieving Shore A 30-50 medical-grade consistency. These specialty chemical suppliers now serve mid-tier brands seeking clinical-channel penetration without vertical integration.
Japan
METI industrial standards and PMDA medical device frameworks govern hospital-grade pump-to-bottle ecosystem validation. Kanto and Kansai manufacturing corridors specialize in anti-colic venting geometries developed for smaller infant oral anatomy. Domestic compounders supply peristaltic-compatible nipple formulations that penetrate Asian hospital nursery procurement.
India
PLI scheme incentives for medical devices and food-contact materials reduce import dependency and enable cost-competitive export positioning. Maharashtra and Gujarat industrial corridors attract stainless steel forming capacity for toddler sippy cup segments. SAMR-plus-REACH compliance investments position Indian fabricators as alternative sourcing nodes for European retailers.
Baby and Toddler Feeding Products and Accessories Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with clinical-channel validation commanding premium positioning in hospital procurement while mass-market retail concentrates in price-promotional mechanics. The vendor base organizes around three strategic archetypes: vertically integrated multinationals with captive silicone chemistry, regional compounder-dependent mid-tier brands, and OEM fabricators serving private-label programs. Competitive moves center on hospital-grade pump ecosystem integration and geographic diversification through India PLI scheme alignment.
Within the clinical-validation tier, Philips Avent and Medela AG occupy positions sustained by European maternity ward partnerships and lactation consultant recommendation networks. Pigeon Corporation anchors Asian-market specialization through geometries engineered for smaller infant oral anatomy. These three exemplify how channel-specific validation protocols create defensive positioning against price-based competition in mass retail.
| Leading Market Players |
|---|
| Philips Avent |
| Medela AG |
| Tommee Tippee |
| NUK |
| Dr. Brown's |
| Munchkin |
| Pigeon Corporation |
| Chicco |
| Playtex |
| Others |
Supply Flow & Price Mechanics
Hospital nursery procurement realignment toward clinically validated feeding systems with documented flow-rate consistency is forcing suppliers to absorb extended certification timelines and specialized silicone formulation costs that compress mid-tier margins.
Pricing Analysis
Retailer markup layers in mass-market channels sustain three-tier pricing structure across premium, standard, and economy levels, with certification grade and brand premium as primary differentiation drivers. Pricing pressure stems from REACH Annex XVII compliance costs accelerating bio-based plasticizer substitution. Mass-market retail buyers exhibit highest price sensitivity, while hospital procurement committees prioritize measurable performance documentation over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese specialty chemical compounders controlling medical-grade Shore A 30-50 silicone formulation capacity. Raw material dependencies center on cross-linked silicone polymers, borosilicate glass, and 18/8 stainless steel feedstock. Tariff exposure on Chinese-manufactured components creates margin volatility. Distribution runs through hospital discharge kit inclusion, lactation consultant recommendation networks, and supermarket bundled starter sets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Baby and Toddler Feeding Products and Accessories Market functions as a stable compounder, with birth-rate stabilization policies and urban middle-class expansion in China's tier-one cities providing steady volume foundations.
For Market Incumbents: Deploy hospital-grade pump ecosystem integration to lock in proprietary connector geometries and captive accessory demand. Deepen clinical channel partnerships across European maternity wards to sustain premium positioning against emerging regional compounder-dependent mid-tier brands. Certification investment in simultaneous FDA, EFSA, and SAMR compliance creates defensive moats. For New Entrants and Emerging Players: Launch via direct-to-clinic procurement channels with lactation consultant-validated anti-colic venting geometries for smaller infant oral anatomy. Target India's PLI scheme-aligned manufacturing corridors for cost-competitive stainless steel toddler sippy cup export positioning. White-space opportunity concentrates in preterm infant segments where biomechanical engineering talent scarcity constrains incumbent supply. For Investors and Strategic Acquirers: Asymmetric upside sits with regional compounder-dependent mid-tier brands achieving clinical-channel penetration without vertical integration. Long-term viability rests on durable shift from retail shelf presence toward consultant-validated procurement channels. Watch for India PLI scheme capacity announcements as inflection signal for export-competitive sourcing node emergence.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital-Grade Pump Ecosystem Integration | Closed-system connector geometries reduce contamination risk and create captive accessory demand through proprietary interfaces. |
| India PLI Scheme Manufacturing Alignment | Domestic incentives for food-contact materials reduce import dependency and enable cost-competitive European export positioning. |
| Anti-Colic Venting Geometry Development | Specialized nipple designs validated for smaller infant oral anatomy penetrate Asian hospital nursery procurement channels. |
| Multi-Jurisdiction Certification Investment | Simultaneous FDA, EFSA, and SAMR compliance extends product development cycles but creates quality-tier segmentation rewards. |
| Direct-to-Clinic Channel Expansion | Lactation consultant recommendation networks and hospital discharge kit inclusion displace traditional retail shelf economics. |
Methodological Framework
Direct dialogue with lactation consultants, hospital procurement managers, silicone compounder technical directors, and infant product brand managers grounded qualitative insights. Secondary validation drew from FDA 21 CFR food-contact notifications, ECHA REACH substance restriction updates, SAMR GB standard enforcement records, and customs trade data. Bottom-up and top-down triangulation reconciled channel shipment data with end-user demand signals.
Bottom-up modeling aggregated segment-level volume and value across product type, material chemistry, age group developmental stage, and distribution channel, then cross-checked against top-down macroeconomic drivers. CAGRs were derived from regression analysis of historical procurement patterns and policy trajectory assumptions. Forecast inputs incorporated birth-rate stabilization policy effectiveness, REACH Annex XVII implementation timelines, and India PLI scheme capacity buildout schedules across the analysis window.
Several conditions sit outside the modeled scope, including unannounced substance restrictions, abrupt trade policy shifts, and novel material science breakthroughs. Forecasts reflect documented assumptions about regulatory reciprocity agreements and certification timeline stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Smart Baby Monitor Market
Baby Products
Baby Pacifier Market
Baby Products
US Baby Care Products Market
Baby Products
Diaper Pails Market
Baby Products
Baby Sleeping Bag Market
Baby Products
Infant Care and Baby Care Equipment Market
Baby Products
Portable Cribs Market
Baby Products
Global Smart Connected Baby Monitors Market
Baby Products
Baby Swing Market
Baby Products
Baby Bottle Warmers Market
Baby Products
Potty Training Seat Market
Baby Products
Canada Baby Care Products Market
Baby Products
Feeding Pillow Market
Baby Products
Baby Walker Market
Baby Products
Baby Bassinets Market
Baby Products
Automatic Baby Swing Market