
 Baby Nose Suckers Market | 2026-2036
Baby Nose Suckers Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Nose Suckers Market Insights
China is rewriting production economics for baby nose suckers as domestic manufacturers scale silicone molding capacity for export markets. NoseFrida leverages its proprietary filter design to sustain premium positioning across North American retail channels. Pigeon anchors Asian market share through pediatrician endorsement programs in Japan and South Korea. Braun competes on clinical-grade suction precision, extending its medical device heritage into home care segments.
A baby nose sucker is a nasal aspiration device, typically employing bulb syringe, oral suction, or motorized vacuum mechanisms to clear mucus from infant nasal passages; electric variants generate continuous suction between 50 and 80 kPa while incorporating anti-backflow valves and BPA-free silicone tips to prevent cross-contamination. The primary commercial purpose is relieving infant nasal congestion to restore feeding and sleep patterns during cold seasons or allergic episodes. Manual aspirators still occupy the largest volume share due to low price points and zero power dependency, though electric models are capturing margin pools through rechargeable lithium-ion batteries and hospital-grade suction calibration. Silicone is displacing standard plastic in tip construction as thermal stability and biocompatibility standards tighten across distribution channels.
The FDA's 510(k) clearance pathway for motorized infant aspirators shapes product development timelines, while the Consumer Product Safety Commission monitors choking hazard compliance for detachable components. The EU Medical Device Regulation classifies certain electric nose suckers as Class I devices, requiring CE marking and post-market surveillance documentation for European market access. Stakeholders must monitor evolving material certification requirements and channel-specific reimbursement policies to align R&D investment with shifting regulatory thresholds.
Market Dynamics
The baby nose suckers market is restructuring around hospital-grade suction technology migrating into home-use formats, as FDA material safety requirements tighten and suburban pediatric clinics expand procurement of clinical-caliber devices for parent purchase programs.
Growth Catalysts
- Suburban Clinic Procurement:Pediatric practices in United States metropolitan peripheries are establishing retail partnerships to dispense hospital-grade electric aspirators directly to new parents, creating a controlled channel for premium device adoption.
- 510(k) Clearance Pathway:The FDA's streamlined premarket notification process for Class II medical devices is compressing development timelines for motorized infant aspirators with validated anti-backflow systems.
- Silicone Molding Scale-Up:Chinese manufacturers are expanding biocompatible silicone production capacity to serve export markets, reducing input costs for BPA-free tip construction across price tiers.
Market Restraints
- Medical-Grade Silicone Volatility:Pharmaceutical-grade silicone supply concentrates among three Asian petrochemical suppliers, exposing manufacturers to feedstock price swings and qualification delays.
- Lithium-Ion Cell Concentration:Rechargeable battery supply for electric aspirators depends on Chinese cathode processing facilities, creating geopolitical exposure for brands assembling devices outside mainland China.
- Bulb Syringe Substitution:Zero-cost manual aspirators remain the default discharge gift from United States maternity wards, limiting electric model penetration among price-sensitive first-time parents.
Strategic Opportunities
- Telehealth Integration:Remote pediatric consultation platforms are creating attachment points for connected aspirators with suction logging and symptom tracking for post-visit monitoring.
- EU MDR Classification Gap:The European Medical Device Regulation's Class I designation for certain electric models allows faster market entry than FDA 510(k) routes, rewarding early CE marking investment.
- Pediatrician Endorsement Programs:Japan and South Korea demonstrate that formal physician recommendation networks convert parental trust into sustained brand loyalty for nasal care devices.
Industry Challenges
- Biocompatibility Certification Timelines:ISO 10993 testing for prolonged infant mucosal contact adds 14-18 months to product development cycles for novel silicone formulations.
- Anti-Backflow Valve Precision:Micro-molding tolerances for one-way valves require capital-intensive cleanroom infrastructure that fragments manufacturing scale economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Nose Suckers Market |
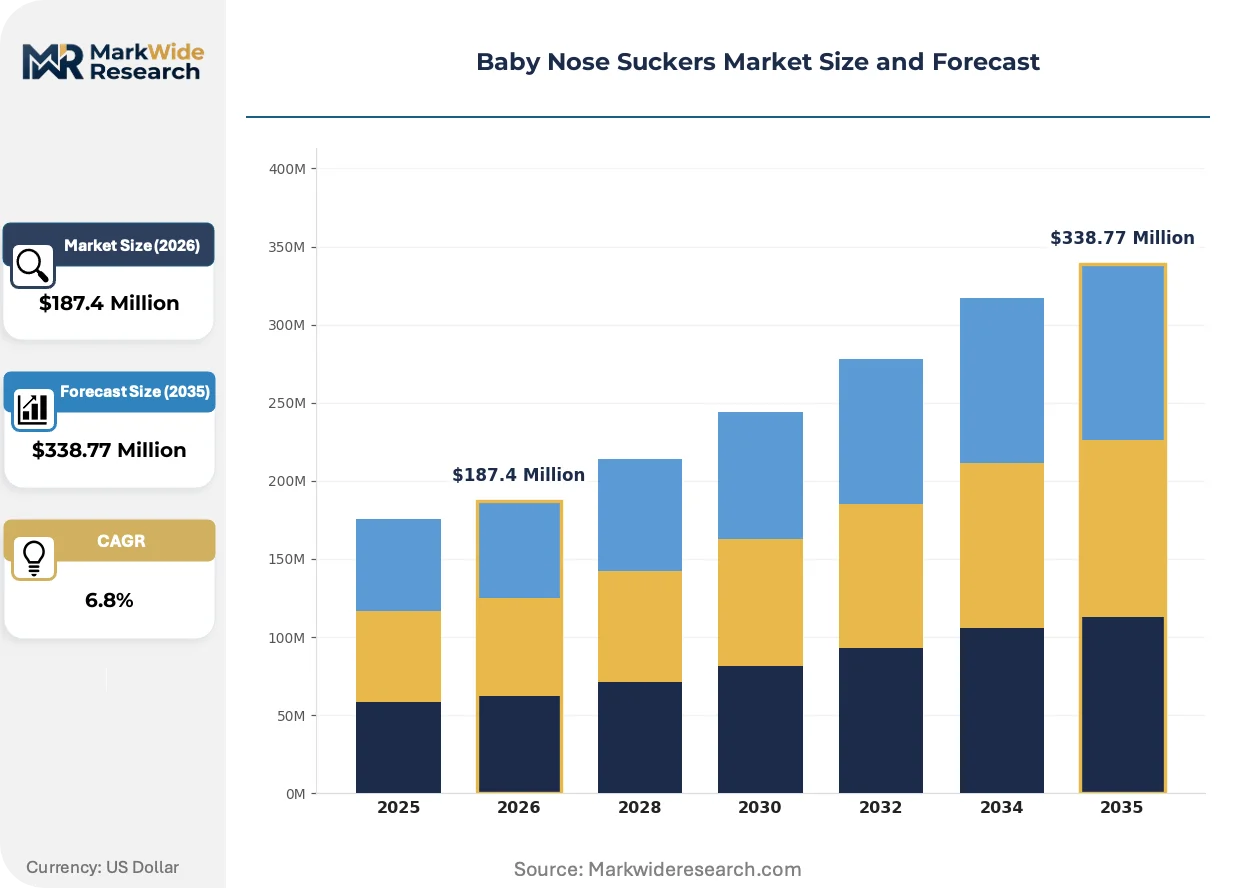
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Electric, Battery Operated, Disposable Material: Plastic, Silicone, Rubber, Stainless Steel Distribution Channel: Online, Pharmacies, Supermarkets, Specialty Stores End User: Parents, Pediatricians, Hospitals, Caregivers |
| Companies Covered | NoseFrida (Frida Baby), Braun, Pigeon, Grownsy, Safety 1st, Dr. Brown's, Momcozy, NUK, Innovo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Nose Suckers Market Trends and Innovations
Product architecture is bifurcating between disposable simplicity and connected precision, with material science and regulatory classification driving divergence in development investment and channel strategy across manufacturer tiers.
Continuous suction technology is migrating from hospital respiratory equipment into home-use infant aspirators, with pressure-calibrated motors replacing manual bulb compression. United States parents of infants with chronic congestion are adopting these devices fastest, paying premiums for suction precision measured in kilopascals rather than subjective force. The technology shift is compressing margins for basic bulb syringes while opening subscription revenue streams for filter replacement programs.
REACH substance restrictions are forcing European manufacturers to reformulate soft-tip compounds ahead of 2026 sunset dates for certain phthalate plasticizers. The regulatory pressure is accelerating biobased silicone adoption and disqualifying legacy PVC formulations from CE-marked devices. German and French distributors are now requiring full material disclosure documentation as a listing prerequisite, filtering out Asian suppliers with incomplete chemical registries.
First-time United States parents are prioritizing clinically validated devices over price-based selection, shifting purchase authority from big-box retail toward specialty baby boutiques and hospital gift shops. This preference compression is elevating brands with FDA 510(k) clearance and pediatrician co-development histories, while generic Amazon-listed aspirators face return-rate penalties that degrade search ranking. The channel rotation is most visible in coastal metropolitan markets where parental education levels correlate with medical-device literacy.
Baby Nose Suckers Market Segmentation
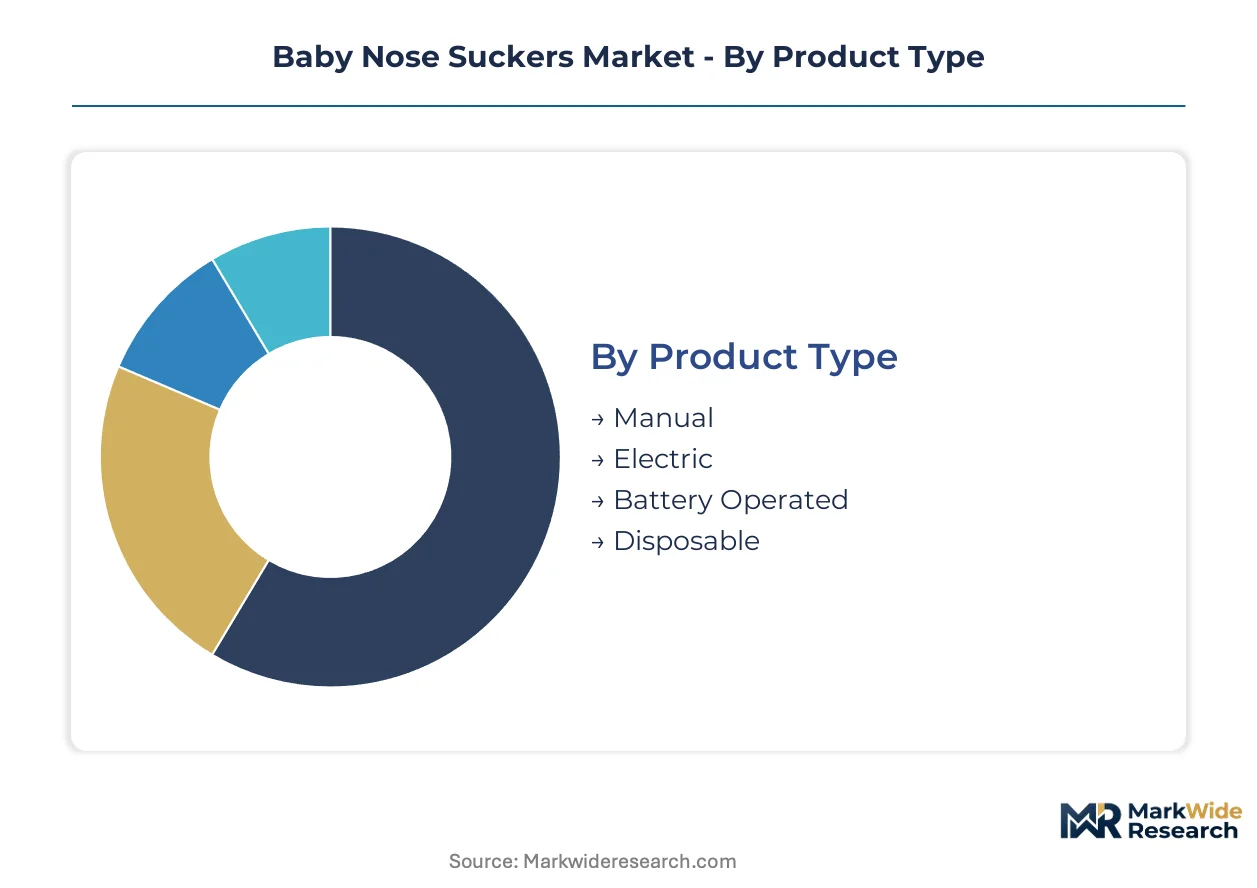
Segmentation in baby nose suckers reveals how product architecture, material science, and channel economics create distinct margin pools. Manufacturers align R&D investment and certification pathways against the specific replacement cycles and purchasing authority within each category.
Product Type:
Replacement cycles vary dramatically across product types, from single-use disposables to multi-year electric aspirators with rechargeable battery systems.
- Manual:Bulb syringes and oral suction aspirators employ simple compression or parent-generated vacuum without power dependency. United States maternity wards distribute these as standard discharge gifts, embedding zero-cost acquisition habits among first-time parents that constrain electric model conversion.
- Electric:Motorized units deliver calibrated suction between 50 and 80 kPa through rechargeable lithium-ion systems with anti-backflow valves. Suburban pediatric clinics in the United States are expanding retail partnerships to dispense hospital-grade variants directly to parents seeking clinical precision for chronic congestion management.
- Battery Operated:Single-use or replaceable alkaline battery designs bridge portability and cost tiers for travel-focused parents. These devices occupy mid-range retail positioning where outlet access is unreliable.
- Disposable:Pre-sterilized single-use aspirators eliminate cross-contamination concerns for hospital settings and immunocompromised infants. Demand concentrates in acute care discharge protocols where infection control protocols override unit economics.
Manual aspirators dominate installed base through maternity ward distribution. Electric models are where expansion concentrates as suburban clinic procurement programs elevate clinical-grade home use.
Material:
Material selection directly determines biocompatibility certification timelines and regulatory qualification pathways across manufacturing geographies.
- Silicone:Pharmaceutical-grade silicone offers thermal stability and ISO 10993-compliant biocompatibility for prolonged mucosal contact. Chinese manufacturers are scaling molding capacity to serve export markets as FDA and ECHA restrictions tighten on legacy compounds.
- Plastic:Standard polymer formulations persist in economy bulb syringes where cost minimization outweighs durability requirements. REACH sunset dates for certain phthalate plasticizers are forcing European reformulation ahead of 2026 deadlines.
- Rubber:Natural and synthetic rubber compounds provide compression resilience in bulb mechanisms. Latex allergy concerns limit neonatal applications and drive substitution toward silicone in premium positioning.
- Stainless Steel:Medical-grade 316L stainless steel enables autoclave sterilization for reusable professional instruments. Hospital procurement specifications require this material for multi-patient clinical environments.
Plastic dominates volume through low-cost manual aspirators. Silicone is gaining share fastest as regulatory pressure and parental preference for BPA-free construction reshape material specifications.
Distribution Channel:
Channel selection reflects purchasing authority migration from price-driven mass retail toward clinically validated specialty environments.
- Online:E-commerce platforms aggregate comparison shopping for feature-rich electric models with subscription filter replacement programs. Return-rate penalties for generic listings are degrading search visibility for non-certified aspirators.
- Pharmacies:Drugstore chains capture impulse purchases during cold season symptom onset. Pharmacist recommendation authority elevates FDA-cleared devices over price-competitive alternatives.
- Supermarkets:Mass retail placement drives bulb syringe volume through basket-stuffing economics and low-consideration purchase behavior. Shelf space compression favors private label over branded premium positioning.
- Specialty Stores:Boutique baby retailers and hospital gift shops curate clinically validated assortments for educated first-time parents. Coastal United States metropolitan markets show strongest preference compression toward specialty channels.
Supermarkets dominate transaction volume through low-price manual aspirators. Specialty stores are where margin expansion concentrates as parental education correlates with medical-device literacy.
End User:
End-user segmentation maps purchasing authority against clinical validation requirements and replacement frequency.
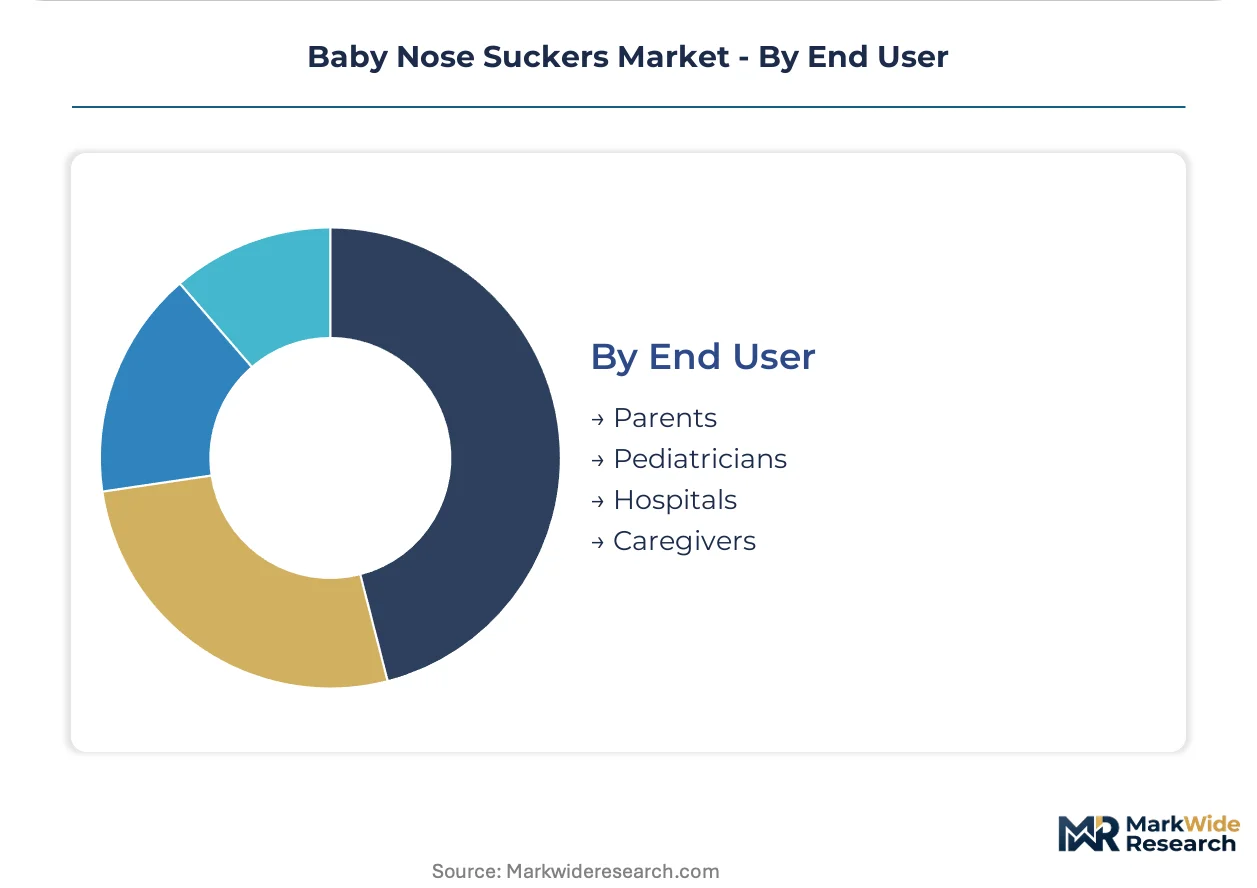
- Parents:First-time parents in the United States prioritize FDA 510(k) clearance and pediatrician co-development histories over price-based selection. Digital-native cohorts research suction calibration specifications before purchase.
- Pediatricians:Physician endorsement networks in Japan and South Korea convert professional trust into sustained brand loyalty. Suburban United States practices are establishing direct retail dispensing partnerships for hospital-grade aspirators.
- Hospitals:Acute care and neonatal intensive care units specify autoclave-sterilizable stainless steel instruments with validated anti-backflow engineering. Procurement committees prioritize infection control documentation over unit cost.
- Caregivers:Professional childcare providers and home health aides require durable multi-patient devices with rapid sterilization protocols. Liability concerns drive preference toward clinically certified electric models.
Parents represent the largest addressable population. Pediatrician channels are where premium positioning concentrates as formal recommendation networks reshape purchase authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: United States parents prioritize FDA-cleared clinical precision, while Japanese and South Korean markets respond to pediatrician endorsement networks, and Chinese manufacturing clusters reshape export economics through silicone molding scale.
United States
Suburban pediatric clinics in metropolitan peripheries are establishing retail partnerships to dispense hospital-grade electric aspirators directly to new parents. FDA 510(k) clearance requirements for Class II medical devices compress development timelines for motorized units with validated anti-backflow systems. Greater Boston and coastal California metropolitan markets show strongest preference compression toward specialty baby boutiques over mass retail channels.
China
Domestic manufacturers are scaling pharmaceutical-grade silicone molding capacity to serve export markets as biocompatibility standards tighten. NMPA alignment with international medical device standards accelerates qualification timelines for BPA-free tip construction. The Yangtze River Delta industrial corridor concentrates precision molding infrastructure serving North American and European brand supply chains.
Japan
Pediatrician endorsement programs convert professional trust into sustained brand loyalty for nasal care devices among first-time parents. PMDA medical device classification requires clinical validation documentation for electric aspirators seeking reimbursement eligibility. The Kanto region around Tokyo anchors distribution networks linking hospital procurement committees with specialty retail channels.
Germany
REACH substance restrictions are forcing reformulation of soft-tip compounds ahead of 2026 sunset dates for certain phthalate plasticizers. EU Medical Device Regulation Class I designation for certain electric models permits faster market entry than FDA 510(k) routes. Bavarian distributors now require full material disclosure documentation as a listing prerequisite, filtering suppliers with incomplete chemical registries.
South Korea
MFDS medical device approval pathways reward early investment in ISO 10993 biocompatibility testing for prolonged infant mucosal contact. Physician recommendation networks in Seoul Capital Area demonstrate higher conversion rates than advertising-driven purchase decisions. Busan-Ulsan manufacturing clusters supply precision micro-molding components for anti-backflow valve assemblies.
Baby Nose Suckers Market Competitive Landscape
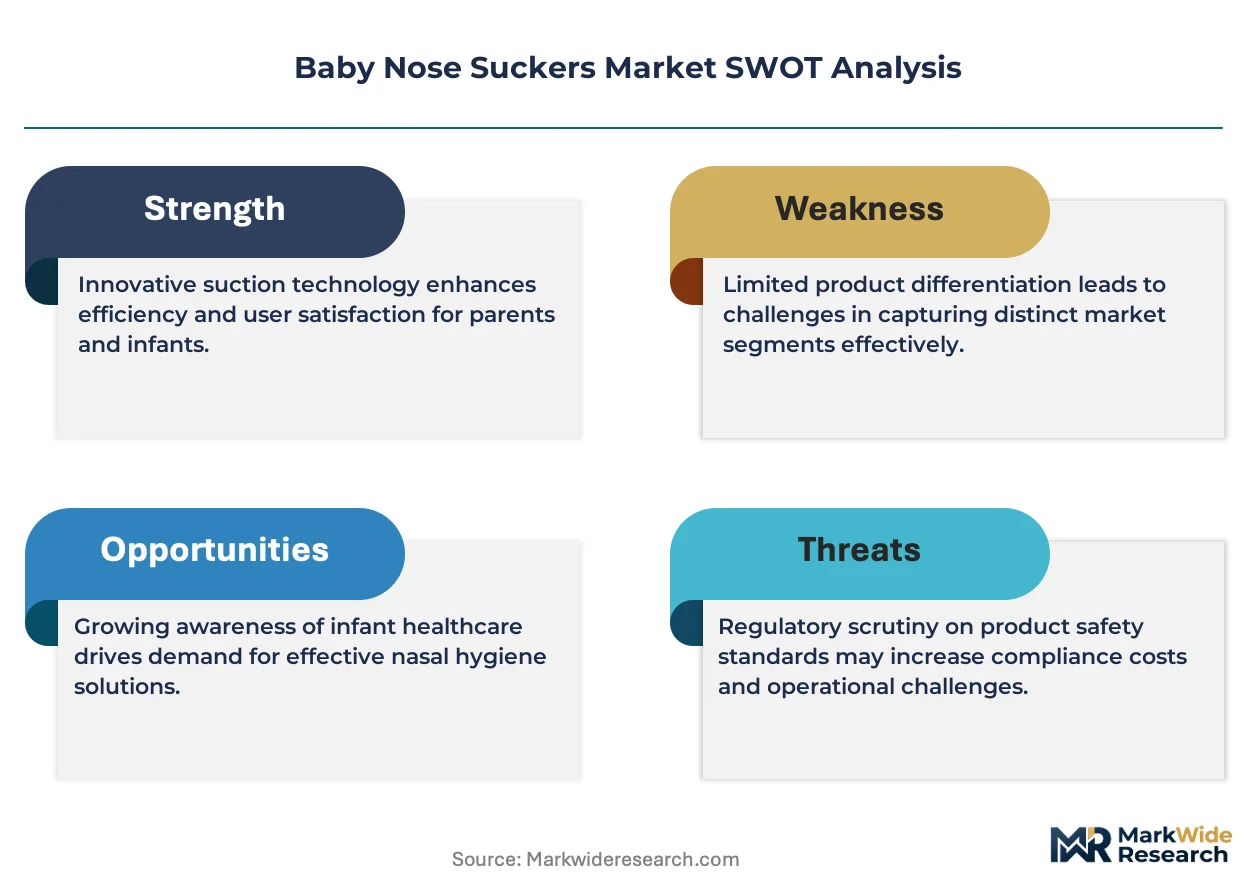
Capability concentration sits with medical-device heritage brands possessing FDA clearance expertise and pediatrician co-development histories; scale advantage sits with Asian manufacturers leveraging silicone molding infrastructure and lithium-ion battery supply chains. The vendor base organizes into three strategic archetypes: clinical-precision specialists with 510(k) portfolios, mass-market consumer brands with retail shelf dominance, and contract manufacturers supplying private-label aspirators to pharmacy chains. Consolidation pressure is building through strategic partnerships between device designers and Chinese molding facilities, alongside geographic expansion of Japanese endorsement-network models into Southeast Asian markets.
Among clinically positioned specialists, NoseFrida and Braun exemplify the premium-tier vector where proprietary filter engineering and suction calibration precision anchor brand positioning. Pigeon occupies a distinct geography-first position within Asian endorsement-network markets. These three companies represent how regulatory qualification depth converts into channel access advantages across divergent regional purchasing authority structures.
| Leading Market Players |
|---|
| NoseFrida (Frida Baby) |
| Braun |
| Pigeon |
| Grownsy |
| Safety 1st |
| Dr. Brown's |
| Momcozy |
| NUK |
| Innovo |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Yangtze River Delta silicone molding facilities is compressing input costs for BPA-free tip construction while simultaneously eroding supplier pricing power across export markets. This utilization dynamic creates divergent incentives: contract manufacturers absorb margin pressure to maintain volume commitments, while brand owners capture downstream pricing flexibility to defend market share against manual aspirator substitution.
Pricing Analysis
Long-term offtake agreements between North American retail distributors and Chinese molding houses dominate procurement structures for electric aspirator components, insulating tier-one brands from spot-market volatility in pharmaceutical-grade silicone. Pricing stratifies across FDA 510(k)-cleared premium units, CE-marked standard devices, and non-certified economy bulb syringes, with certification grade commanding the widest spreads. Cost compression in mid-range battery-operated segments is intensifying because lithium-ion cell suppliers are consolidating cathode processing capacity. Hospital procurement committees show the least price sensitivity, while first-time parents purchasing through mass retail channels exhibit acute elasticity to unit cost differentials.
Supply Chain Analysis
Extended payment terms from United States retail pharmacy chains are squeezing working capital for Asian contract manufacturers, forcing reliance on supply-chain finance facilities backed by export credit agencies. Component sourcing concentrates in China for silicone molding and lithium-ion cell assembly, South Korea for precision micro-molding of anti-backflow valves, and Germany for REACH-compliant soft-tip compounds. Feedstock exposure rests on three Asian petrochemical suppliers controlling pharmaceutical-grade silicone precursors. Single-source vulnerability in battery cathode processing creates geopolitical contingency risk. Distribution runs through pediatric clinic dispensing partnerships, specialty baby boutiques, and e-commerce platforms with subscription filter replenishment programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across purchasing authority—between clinically validated specialty channels and price-driven mass retail—creates defendable niche positions for differentiated entrants. First-time parent demand is bifurcating toward either zero-cost manual aspirators or premium electric models with documented suction precision, squeezing mid-range battery-operated offerings.
For Market Incumbents: Pre-empt margin erosion in battery-operated tiers by accelerating FDA 510(k) submissions for connected aspirators with telehealth logging capabilities. Defend channel position through exclusive dispensing partnerships with suburban pediatric clinic networks. Backward integration into silicone compounding insulates against feedstock volatility from Asian petrochemical suppliers. For New Entrants and Emerging Players: Build out white-space presence in EU MDR Class I electric models where CE marking timelines compress market entry relative to FDA routes. Target German and French distributors requiring full material disclosure documentation as a listing filter against incomplete chemical registries. Pursue pediatrician endorsement networks in Japan and South Korea where professional recommendation converts trust into sustained brand loyalty. For Investors and Strategic Acquirers: Capital is best deployed toward clinically positioned specialists possessing 510(k) clearance expertise and pediatrician co-development histories rather than undifferentiated contract manufacturers. Long-term viability over a multi-year horizon favors assets with regulatory qualification depth that converts into channel access advantages. Watch for inflection signals in suburban clinic procurement program expansion rates as indicators of premium electric aspirator adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Validates anti-backflow engineering for Class II motorized aspirator market access. |
| CE Marking Investment | Exploits EU MDR Class I designation for faster European market entry timelines. |
| Pediatrician Endorsement Program | Converts professional trust into brand loyalty across Japanese and South Korean markets. |
| Silicone Molding Scale-Up | Captures cost advantages as biocompatibility standards tighten across distribution channels. |
| Telehealth Platform Integration | Creates attachment points for connected aspirators with suction logging and symptom tracking. |
Research Methodology
The analysis maps manual, electric, battery-operated, and disposable aspirator sub-sectors, each validated through pediatricians, hospital procurement committees, biomedical engineers, and retail category buyers. Primary interviews with these stakeholders were cross-referenced against FDA 510(k) filings, EU MDR classification databases, hospital procurement records, and customs trade data. Bottom-up unit economics triangulated against top-down market sizing across product type, material, distribution channel, and end-user segmentation dimensions.
Assumptions held fixed include regulatory classification thresholds and material certification requirements, while variables such as suburban clinic dispensing partnership expansion and lithium-ion cell supply concentration were stress-tested across scenarios. Growth trajectories were derived from modeled replacement cycles, penetration rates by product tier, and channel shift dynamics across the projection horizon. Forecast inputs incorporated ISO 10993 biocompatibility testing timelines and REACH substance restriction sunset dates.
Stress conditions across silicone feedstock pricing, battery supply chain disruption, and FDA clearance pathway delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and would prompt revision upon macroeconomic, regulatory, or technological deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Japan Baby Care Product Market
Baby Products
Baby Bouncers Market
Baby Products
Automatic Baby Swing Market
Baby Products
Baby Products Detergents Market
Baby Products
Baby Personal Care Products Market
Baby Products
Tissue and Hygiene Market
Baby Products
Global Baby Play Mats Market
Baby Products
India Baby Care Products Market
Baby Products
Baby Cradles Market
Baby Products
Baby Sleeping Bag Market
Baby Products
US Baby Care Products Market
Baby Products
Electric Baby Nail Trimmer Market
Baby Products
Breastfeeding Accessories Market
Baby Products
Baby Shoes Market
Baby Products
Baby Nail Trimmer Market
Baby Products
Baby Wipes Market