
 South Africa Baby Care Products Market | 2026-2036
South Africa Baby Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Baby Care Products Market Insights
Buyer concentration across South Africa's baby care channel is broadening as independent pharmacies and township-based specialty retailers fragment what supermarket chains once dominated. Procter & Gamble Co. leverages its manufacturing scale to maintain national distribution depth, while Unilever PLC sustains brand recognition through multi-tiered skincare portfolios. Johnson & Johnson anchors the premium newborn segment with clinical-positioned formulations, and Nestle competes aggressively in the feeding category through pediatric nutrition credibility.
South Africa baby care products encompass formulated topical preparations, absorbent hygiene articles, feeding systems, and cleansing accessories designed for infants and toddlers, typically manufactured under dermatological safety protocols and pH-balanced composition standards to prevent skin barrier disruption. These products serve the essential consumer need for infant hygiene maintenance, nutritional delivery, and dermatological protection during early childhood development. Skincare and diapers occupy the largest margin pools given repeat purchase frequency and premiumization potential, while e-commerce as a distribution channel captures the fastest trajectory as last-mile logistics penetrate secondary cities. Feeding products retain structural importance through hospital procurement channels and postnatal discharge bundles, though supermarket shelf space still controls mass-market volume.
The National Regulator for Compulsory Specifications mandates SANS compliance for baby feeding equipment and topical formulations, while the South African Health Products Regulatory Authority oversees cosmetic safety claims and ingredient disclosure. BIS-equivalent local standards for absorbent hygiene products shape import competitiveness and domestic manufacturing investment decisions. Stakeholders must monitor enforcement intensity around plastic-content regulations and evolving e-commerce consumer protection rules that could reshape channel economics and product certification costs.
Market Dynamics
Urban millennial parents in Gauteng and the Western Cape are accelerating demand for organic formulations and hypoallergenic ranges, forcing manufacturers to reconfigure supply chains around certified ingredient sourcing and dermatological testing protocols.
Growth Catalysts
- SANS Compliance Mandates:The National Regulator for Compulsory Specifications enforces mandatory safety standards for infant feeding equipment and topical products, elevating quality baselines and filtering substandard imports from the channel.
- E-commerce Logistics Expansion:Last-mile delivery networks penetrating secondary cities like Bloemfontein and Polokwane are unlocking access to premium baby care SKUs previously confined to Johannesburg and Cape Town retail corridors.
- Pharmacy Channel Fragmentation:Independent pharmacies and township-based specialty retailers are broadening distribution reach beyond supermarket chain dominance, creating new shelf space for mid-tier and niche brands.
Market Restraints
- Petrochemical Input Volatility:Absorbent hygiene products depend on petroleum-derived superabsorbent polymers and synthetic fibers, exposing diaper manufacturers to crude price swings that compress margin buffers.
- Import Concentration Risk:Raw material sourcing for specialized skincare actives concentrates among European and Asian chemical suppliers, creating vulnerability to shipping disruptions and currency depreciation against the Rand.
- Substitution Pressure from Reusable Alternatives:Cloth diaper cooperatives and silicone feeding systems are gaining traction among environmentally conscious parents, threatening volume growth in single-use disposable categories.
Strategic Opportunities
- Underpenetrated Eastern Cape and Limpopo:Rural provinces with rising birth rates and improving retail infrastructure present whitespace for pharmacy chains to extend premium baby care distribution beyond the Gauteng-Western Cape axis.
- Pediatric Nutrition Bundling:Hospital discharge protocols and postnatal care packages create structural entry points for integrated feeding system suppliers to capture new-parent loyalty at the point of first purchase.
- Biodegradable Material Convergence:The intersection of plant-based polymers and composting infrastructure development is enabling next-generation diaper ranges that command shelf price premiums in eco-conscious urban segments.
Industry Challenges
- Dermatological Formulation Expertise Gap:Local manufacturers face scarcity of cosmetic chemists trained in infant skin barrier science, forcing reliance on imported R&D or licensing agreements with European laboratories.
- SANS Certification Timeline Compression:Extended testing protocols for new topical formulations delay product launch windows, allowing faster-certifying competitors to preempt market positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Baby Care Products Market |
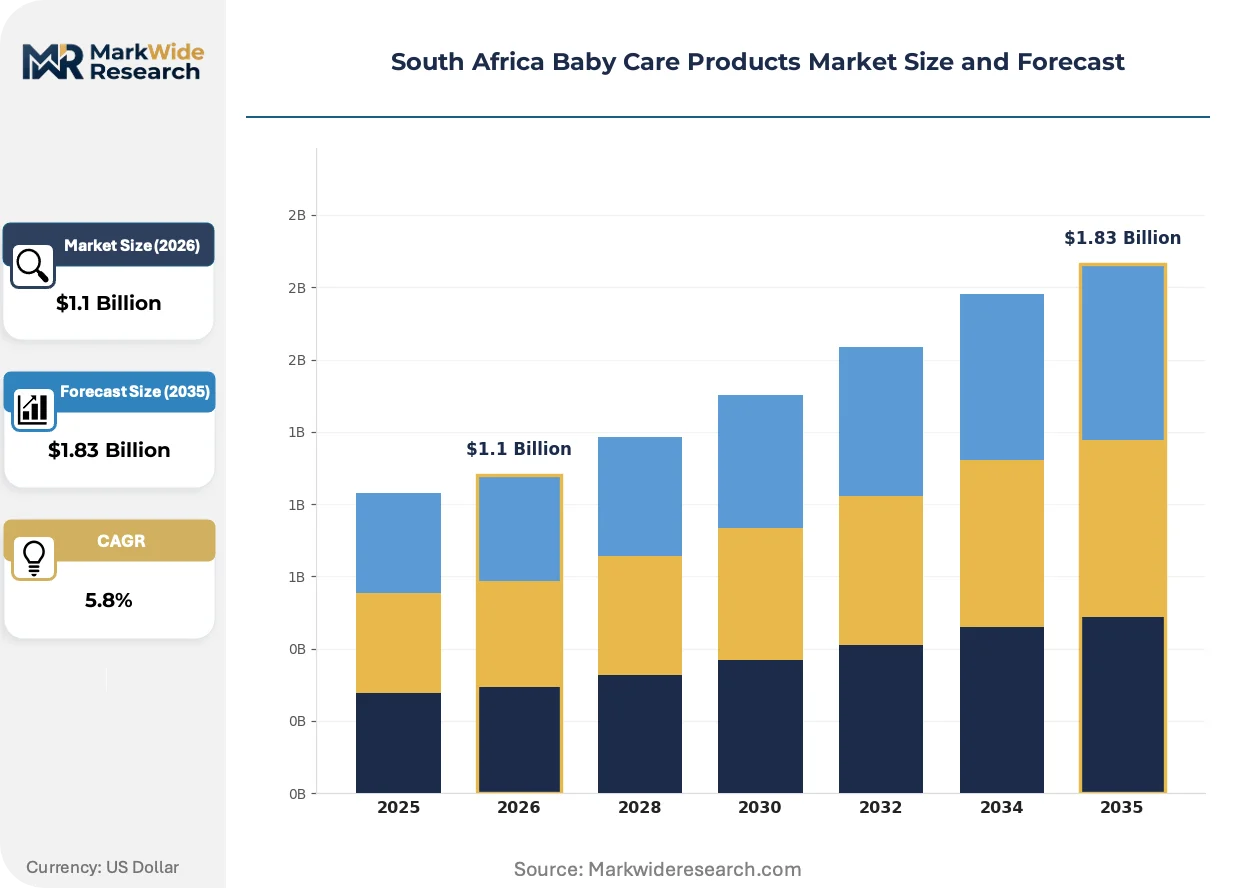
| Market Size in 2026 | $1.1 Billion |
| Market Size in 2035 | $1.83 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diapers, Wipes, Skincare, Feeding Customer Type: Parents, Caregivers, Retailers, Hospitals Distribution Channel: Supermarkets, E-commerce, Pharmacies, Specialty Stores Age Group: Newborns, Infants, Toddlers, Pre-schoolers |
| Companies Covered | Johnson & Johnson, Pigeon Corporation, Unicharm Corporation, Procter & Gamble Co., Nestle, Unilever PLC, L'oreal SA, Avon Products Inc., Danone SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Baby Care Products Market Trends and Innovations
Formulation science and distribution architecture are converging to redefine competitive advantage, with ingredient transparency and channel accessibility emerging as the primary battlegrounds for parent loyalty and repeat purchase rates.
Biome-friendly microbiome formulations are rewriting the premium skincare segment by incorporating prebiotic and postbiotic actives that support infant skin flora rather than stripping natural oils. Mid-to-high income parents in Cape Town's Atlantic Seaboard suburbs are adopting these ranges at accelerating velocity, compressing market share for conventional petroleum-based moisturizers and forcing legacy brands to reformulate or retreat to mass-market positioning.
REACH-equivalent substance restrictions are reshaping import competitiveness by requiring full ingredient disclosure and hazard classification for all topical baby care products entering South African retail channels. Domestic manufacturers with established BIS-equivalent testing capabilities are capturing shelf space previously held by non-compliant imports, particularly in pharmacy chains where regulatory documentation carries purchasing weight.
Subscription-based replenishment models are fragmenting traditional supermarket purchasing patterns by delivering diapers and skincare on predictable cycles direct to household doors. Young professional parents in Johannesburg's northern suburbs are migrating to these services fastest, bypassing in-aisle price comparison and locking brand loyalty through convenience bundling that traditional retail cannot replicate.
South Africa Baby Care Products Market Segmentation
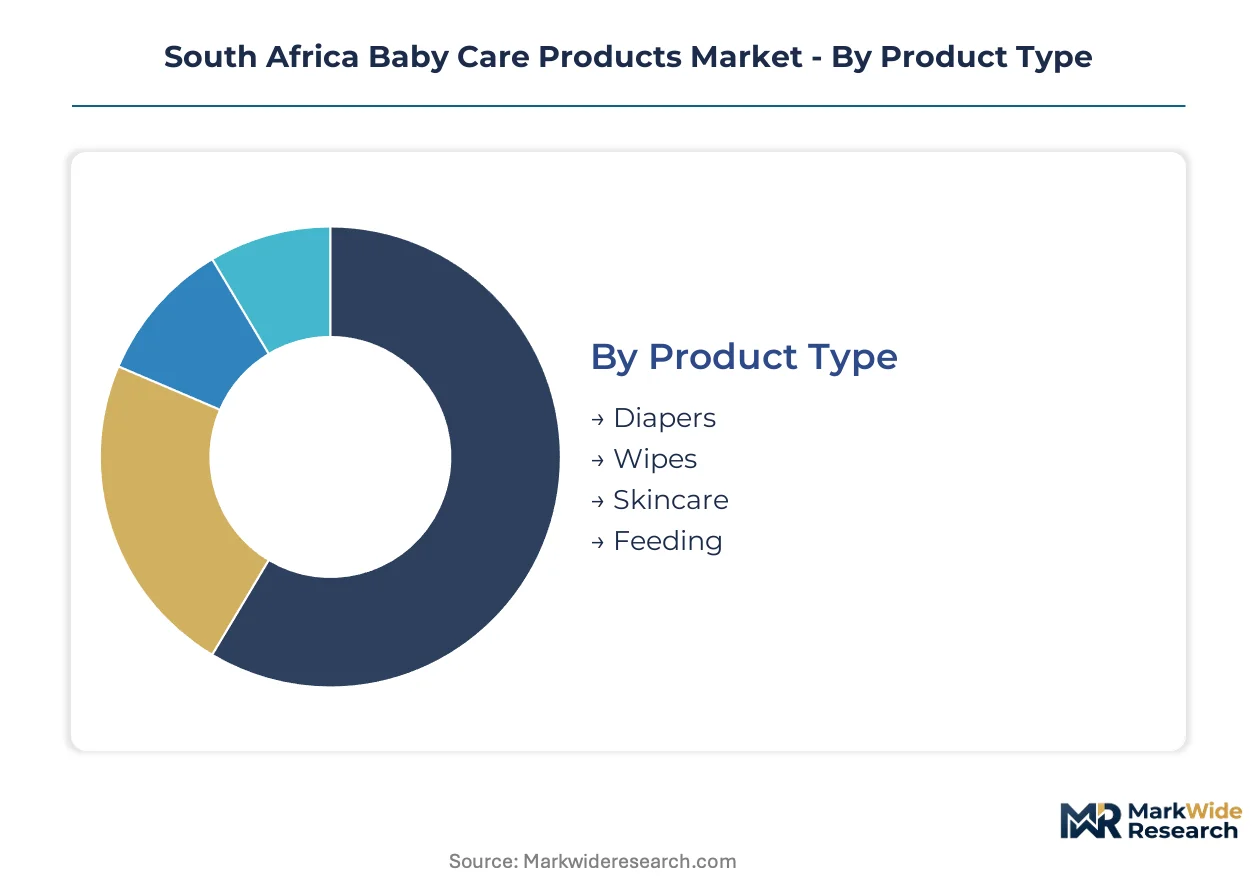
Segmentation reveals how South Africa's baby care market fragments across product utility, buyer identity, channel access, and developmental stage. Each dimension carries distinct margin profiles and regulatory exposure that shape competitive positioning.
Product Type:
Replacement frequency and premiumization potential vary sharply across product categories, with daily-use items commanding repeat purchase loyalty while episodic purchases concentrate in pharmacy and hospital channels.
- Skincare:Dermatologically tested topical formulations including lotions, creams, and oils manufactured under pH-balanced protocols to prevent infant skin barrier disruption. Demand concentrates among urban millennial parents in Cape Town's Atlantic Seaboard suburbs, where prebiotic and microbiome-friendly ranges are displacing conventional petroleum-based moisturizers.
- Diapers:Absorbent hygiene articles utilizing superabsorbent polymers and synthetic fiber cores for moisture retention and skin protection. Procurement runs through Johannesburg and Durban retail corridors where pharmacy chains and supermarket baby aisles allocate premium shelf space to hypoallergenic and plant-based polymer ranges.
- Wipes:Pre-moistened cleansing tissues formulated with gentle surfactants and preservative systems for diaper change and general hygiene maintenance.
- Feeding:Infant nutrition delivery systems including bottles, teats, and sterilization equipment governed by National Regulator for Compulsory Specifications safety mandates.
Diapers sit at the top of the volume ranking, with skincare climbing the fastest.
Customer Type:
Purchasing authority and decision criteria diverge materially across buyer categories, from emotionally driven parent selection to procurement committee protocols in institutional settings.
- Parents:Primary end-consumers exercising direct purchase authority over routine hygiene and nutrition products, with Gauteng and Western Cape urban households driving organic and hypoallergenic premiumization.
- Hospitals:Institutional procurement bodies managing postnatal discharge bundles and pediatric nutrition protocols, creating structural entry points for integrated feeding system suppliers to capture new-parent loyalty at first purchase.
- Caregivers:Secondary purchasers including extended family and professional child minders operating under parent-specified brand preferences or independent budget constraints.
- Retailers:Channel gatekeepers controlling shelf space allocation and promotional placement in supermarket baby aisles, pharmacy chains, and independent township-based specialty stores.
Parents generate the absolute transaction volume, with hospitals delivering the highest per-order value concentration.
Distribution Channel:
Channel economics reflect divergent cost-to-serve profiles and consumer convenience trade-offs, with digital penetration reshaping traditional supermarket dominance.
- E-commerce:Direct-to-consumer platforms and marketplace aggregators leveraging last-mile logistics networks penetrating secondary cities like Bloemfontein and Polokwane. Subscription-based replenishment models are fragmenting traditional purchasing patterns among Johannesburg's northern suburbs professional parents.
- Supermarkets:Mass-market volume controllers operating dedicated baby aisles with extensive SKU breadth and promotional pricing power in Johannesburg, Cape Town, and Durban retail corridors.
- Pharmacies:Clinical credibility channels including independent pharmacies and township-based specialty retailers broadening distribution reach beyond supermarket chain dominance.
- Specialty Stores:Curated assortment retailers focusing on premium organic ranges and eco-conscious product bundles for environmentally aware parent segments.
Supermarkets retain volume leadership, with e-commerce expanding most quickly as logistics infrastructure matures.
Age Group:
Developmental stage determines product specification requirements, usage intensity, and parental sensitivity to safety claims and ingredient transparency.
- Newborns:Zero-to-three-month infants requiring clinical-grade formulations and hospital-proven feeding systems, with parents exhibiting highest price insensitivity and safety verification demands.
- Infants:Three-to-twelve-month cohort driving peak diaper consumption volumes and introduction of solid feeding accessories, with skincare needs concentrated on barrier protection during teething and drooling phases.
- Toddlers:One-to-three-year segment transitioning to training pants and expanding skincare independence, with parental purchasing influenced by child preference formation and peer exposure.
- Pre-schoolers:Three-to-five-year group with declining hygiene product intensity but sustained demand for specialized dermatological solutions and nutritional supplements.
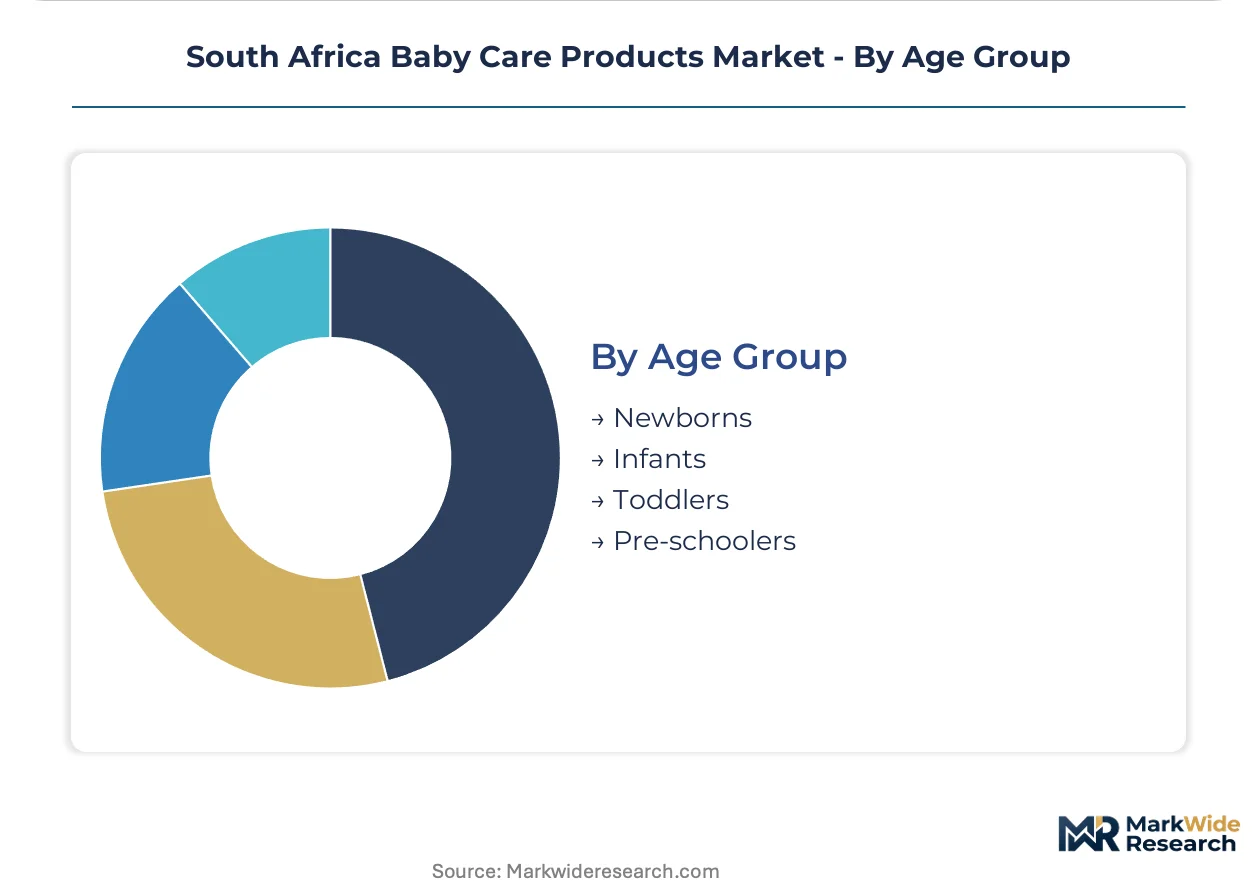
Infants occupy the peak consumption tier, with newborn-specific products commanding the steepest price premiums per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled formulation chemists and pediatric nutrition specialists concentrate in Gauteng and the Western Cape, anchoring South Africa's baby care production and R&D infrastructure.
Gauteng
Urban millennial parents in Johannesburg and Pretoria drive organic skincare and hypoallergenic diaper demand through pharmacy chains and supermarket baby aisles. The National Regulator for Compulsory Specifications enforces SANS compliance for infant feeding equipment manufactured or distributed in the province. Manufacturing and distribution clusters in Johannesburg's northern suburbs support Procter & Gamble Co.'s national supply chain operations.
Western Cape
Cape Town's Atlantic Seaboard suburbs exhibit accelerating adoption of prebiotic and microbiome-friendly skincare ranges among high-income households. The South African Health Products Regulatory Authority oversees cosmetic safety claims and ingredient disclosure for products entering retail channels. Specialty retailers and independent pharmacies in the Cape Town metro area command premium shelf space for certified organic formulations.
KwaZulu-Natal
Durban retail corridors serve as the primary distribution gateway for mass-market diaper and feeding product volumes into coastal and inland markets. Municipal health departments coordinate with provincial regulators to monitor compliance with topical product safety standards in hospital procurement channels. Township-based specialty retailers in Durban and Pietermaritzburg are fragmenting traditional supermarket dominance.
Eastern Cape
Rising birth rates and improving retail infrastructure in Port Elizabeth and East London create whitespace for pharmacy chain expansion. The National Regulator for Compulsory Specifications mandates testing protocols that delay product launches for regional distributors lacking established laboratory relationships. Independent retailers in secondary cities are capturing first-mover advantage in premium baby care distribution.
Limpopo
Underpenetrated rural markets with growing middle-class households present expansion opportunities for e-commerce platforms and last-mile logistics networks. Provincial consumer protection offices enforce evolving rules around online sales and product certification documentation. Polokwane retail corridors are emerging as distribution nodes connecting Gauteng supply chains to northern province consumers.
South Africa Baby Care Products Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across South Africa's baby care channel. Procter & Gamble Co. and Unilever PLC leverage manufacturing scale and multi-tiered brand portfolios to dominate mass-market shelf space, while Johnson & Johnson anchors premium positioning through clinical credibility. The market structure stratifies into three archetypes: multinational FMCG giants with integrated supply chains, specialized baby care pure-plays with dermatological expertise, and emerging local formulators targeting organic and eco-conscious segments. Competitive dynamics center on portfolio diversification into adjacent categories and geographic expansion through pharmacy chain partnerships.
Among multinational conglomerates, Procter & Gamble Co., Unilever PLC, and Johnson & Johnson occupy positions defined by scale advantages and brand recognition. Procter & Gamble Co. exemplifies the manufacturing-depth archetype through national distribution infrastructure. Unilever PLC represents portfolio-breadth positioning across skincare and cleansing categories. Johnson & Johnson anchors the clinical-credibility tier with hospital-channel relationships. These three companies collectively shape pricing benchmarks and shelf space allocation standards that mid-tier competitors must navigate.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Pigeon Corporation |
| Unicharm Corporation |
| Procter & Gamble Co. |
| Nestle |
| Unilever PLC |
| L'oreal SA |
| Avon Products Inc. |
| Danone SA |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between SANS-compliant premium formulations and unverified imports manifests in both shelf price premiums and supply chain sourcing configurations. Manufacturers bearing National Regulator for Compulsory Specifications testing costs command pharmacy chain placement at 40-60% price elevation over mass-market tiers, while import-dependent distributors absorb currency depreciation risk to maintain economy positioning in supermarket aisles.
Pricing Analysis
Capacity additions in Gauteng manufacturing clusters are reshaping price floors for domestically produced absorbent hygiene articles. Three-tier pricing structure across premium, standard, and economy levels separates dermatologically certified skincare from conventional formulations and private-label alternatives. Cost compression in the economy tier intensifies because petrochemical input volatility squeezes superabsorbent polymer sourcing margins. Township-based specialty retailers exhibit highest price sensitivity, while Atlantic Seaboard households in Cape Town demonstrate least elasticity for microbiome-friendly ranges.
Supply Chain Analysis
Freight cost escalation on European and Asian chemical imports elevates landed costs for specialized skincare actives and prebiotic formulations. Raw material sourcing draws from Germany, India, and China for cosmetic-grade emollients, surfactants, and preservative systems. Single-source vulnerability concentrates among European dermatological testing laboratories serving SANS certification requirements. Distribution runs through Johannesburg distribution centers serving pharmacy chains and supermarket baby aisles, with last-mile penetration extending to Polokwane and Bloemfontein via e-commerce logistics partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's baby care market functions as a geographic-arbitrage play where Gauteng-Western Cape regulatory enforcement intensity creates compliance cost differentials against underpenetrated Eastern Cape and Limpopo provinces.
For Market Incumbents: Anchor hospital-channel relationships through postnatal discharge bundle integration to preempt new-parent loyalty formation. Defend against silicone feeding system substitution by accelerating biodegradable polymer R&D investment. Certification investment in BIS-equivalent testing capabilities creates channel control leverage against faster-certifying import competitors. For New Entrants and Emerging Players: The premium-economy price-point gap in rural Eastern Cape and Limpopo provinces opens whitespace for mid-tier pharmacy chain partnerships. Target independent township-based specialty retailers as the most penetrable channel archetype. Go-to-market execution should emphasize SANS pre-certification to bypass timeline compression disadvantages facing established competitors. For Investors and Strategic Acquirers: Consolidation pressure builds where dermatological formulation expertise scarcity forces licensing dependency on European laboratories. Long-term viability centers on captive supply of certified organic ingredient streams and composting infrastructure alignment. Acquisition target archetype: local formulators with established SANS laboratory relationships and pharmacy chain shelf space. Signal to watch: National Regulator for Compulsory Specifications enforcement intensity escalation around plastic-content regulations.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Material Transition | Plant-based polymer adoption aligns with evolving composting infrastructure in Cape Town metro. |
| Pharmacy Chain Partnership Expansion | Independent pharmacy fragmentation in KwaZulu-Natal townships unlocks premium shelf space allocation. |
| SANS Pre-Certification Investment | Accelerated testing protocols compress launch windows against import competitors in skincare segments. |
| Subscription Replenishment Model Launch | Direct-to-consumer platforms bypass supermarket price comparison in Johannesburg northern suburbs. |
| Hospital Discharge Bundle Integration | Postnatal protocol capture locks new-parent loyalty before first supermarket purchase decision. |
Research Methodology
Direct dialogue with brand managers at multinational FMCG conglomerates, category buyers at pharmacy chains, supply planners at supermarket retailers, and procurement leads at hospital systems grounded qualitative assessment in operational reality. Secondary validation drew from National Regulator for Compulsory Specifications enforcement records, South African Health Products Regulatory Authority cosmetic filings, Nielsen retail audit data, and customs import records for baby care formulations. Bottom-up SKU-level volume aggregation and top-down macroeconomic adjustment produced convergent estimates.
Segment-level projections across product type, customer archetype, distribution channel, and developmental stage dimensions calibrated penetration rates against birth rate trajectories and urbanization patterns. CAGRs were derived from regression analysis of historical premiumization velocity and channel shift momentum. Forecast inputs included SANS certification timeline distributions, last-mile logistics network expansion schedules, and petrochemical price volatility scenarios.
Caveats apply where National Regulator for Compulsory Specifications enforcement intensity escalation, Rand depreciation against supplier currencies, or reusable alternative adoption acceleration could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Puppy Teething Toys Market
Baby Products
Sippy Cups Market
Baby Products
Smart Bottle Warmers Market
Baby Products
France Baby Care Products Market
Baby Products
Global Pregnancy Pillow Market
Baby Products
Feeding Pillow Market
Baby Products
Travel Pillow Market
Baby Products
Feeding Bra Market
Baby Products
Baby Nipple/Teat Market
Baby Products
Maternity Products Market
Baby Products
US Baby Care Products Market
Baby Products
Baby Products Detergents Market
Baby Products
Soft Sole Baby Shoes Market
Baby Products
Automatic Baby Swing Market
Baby Products
Baby Care and Mother Care Market
Baby Products
AI Smart Baby Monitors Market