
 Breast Milk Storage Products Market | 2026-2036
Breast Milk Storage Products Market Size, Share, and Industry Trends Forecast 2026-2036
Breast Milk Storage Products Market Intelligence
Working parents is reorganizing demand patterns across the breast milk storage products landscape, displacing traditional hospital-centric procurement with direct-to-consumer purchasing. Medela AG leverages its clinical heritage to sustain credibility in both institutional and retail channels. Lansinoh Laboratories specializes in affordable, widely distributed bag formats that dominate pharmacy and big-box retail. Koninklijke Philips N.V. competes through integrated ecosystem play, bundling storage with its broader mother-and-child care portfolio.
Breast milk storage products encompass containers, bags, and accessory systems engineered to preserve expressed human milk at refrigerated or frozen temperatures, typically constructed from food-grade polypropylene, polyethylene, or borosilicate glass with hermetic sealing mechanisms to prevent contamination and nutrient degradation. Storage bags command the largest volume position due to disposability and unit economics, while silicone-based reusable containers capture expanding margin pools as sustainability preferences intensify. Glass containers occupy a premium niche where chemical-free assurance drives parental willingness to pay, though breakage risk constrains mass-market penetration.
FDA food-contact substance notifications govern material safety for plastic storage products in the United States, while the EU REACH framework and F-Gas Regulation indirectly shape manufacturing location and refrigerant-dependent cold-chain compatibility. BIS certification requirements in India and GB standards in China create divergent compliance thresholds that fragment supplier strategies across major production bases. Stakeholders must monitor evolving extended producer responsibility mandates for single-use plastics and anticipate how workplace lactation legislation in additional jurisdictions will redirect channel investments.
Market Dynamics
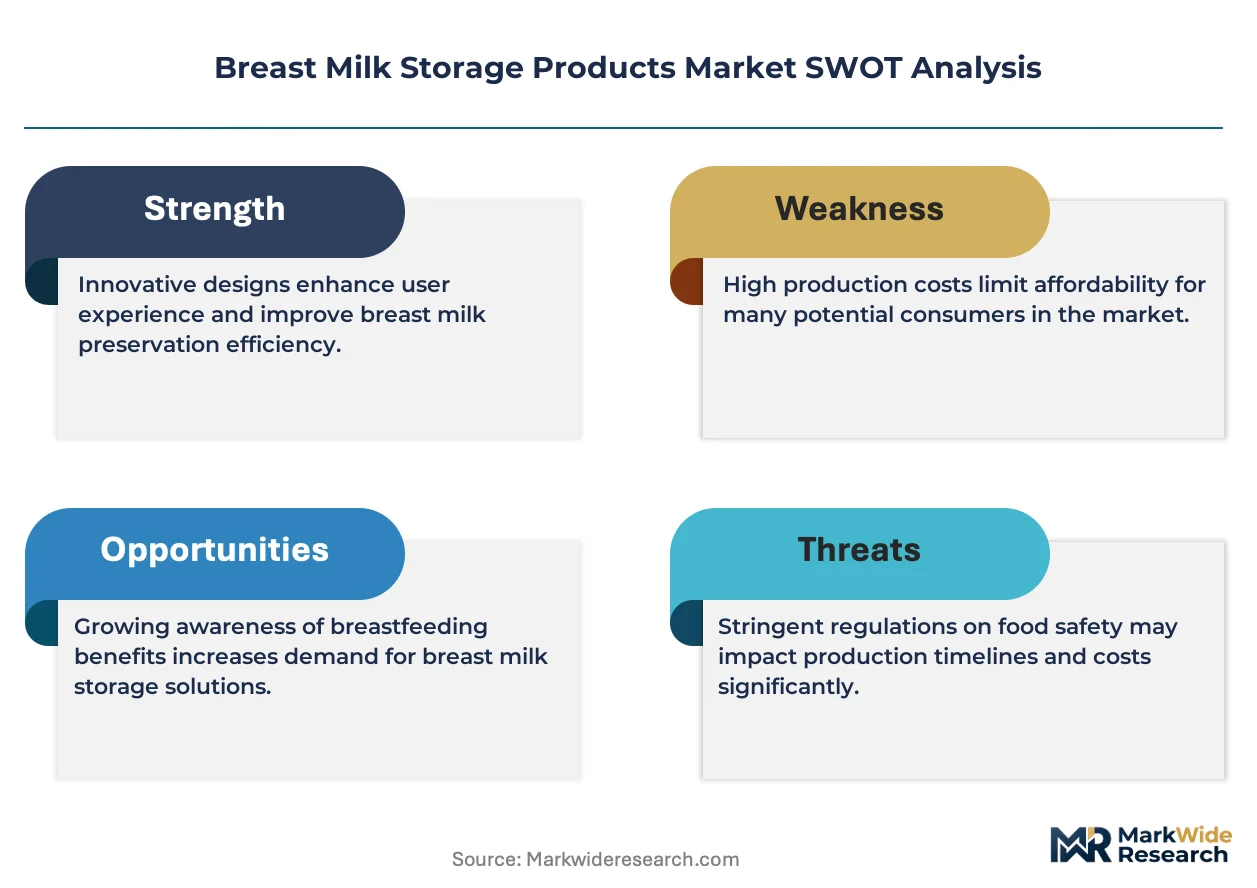
Workplace lactation accommodation mandates are displacing hospital-centric procurement with direct-to-consumer purchasing, forcing manufacturers to reconfigure distribution networks and product formats simultaneously.
Growth Catalysts
- US PUMP Act enforcement:Employer-provided lactation spaces now cover 9 million additional workers, expanding the addressable base for portable storage solutions.
- Silicone material substitution:Platinum-cured silicone containers eliminate plastic degradation concerns while supporting 500+ use cycles, attracting sustainability-motivated buyers.
- India:BIS certification requirements for food-contact materials are professionalizing domestic manufacturing, enabling export-grade capacity expansion.
Market Restraints
- Polypropylene feedstock volatility:Propylene monomer prices fluctuate with naphtha cracking economics, compressing margins on standard bag formats.
- Single-supplier concentration:Hermetic zipper seals rely on three Japanese precision-molding houses, creating geographic chokepoints.
- EU F-Gas Regulation:Cold-chain compatibility testing for frozen storage now requires alternative refrigerant validation, extending product development timelines.
Strategic Opportunities
- Brazil:ANVISA's pending food-contact notification pathway for breast milk storage materials will unlock Latin America's largest consumer base.
- Smart temperature monitoring:NFC-enabled bags integrating with smartphone cold-chain tracking address hospital-grade compliance needs in home settings.
- Extended producer responsibility:France's AGEC law mandates recyclable packaging quotas, rewarding suppliers with established take-back infrastructure.
Industry Challenges
- Migration testing capacity:FDA food-contact substance notification backlogs exceed 14 months, delaying new material introductions.
- Cross-contamination protocols:Dairy processing equipment standards do not map cleanly to human milk handling, forcing redundant validation investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breast Milk Storage Products Market |
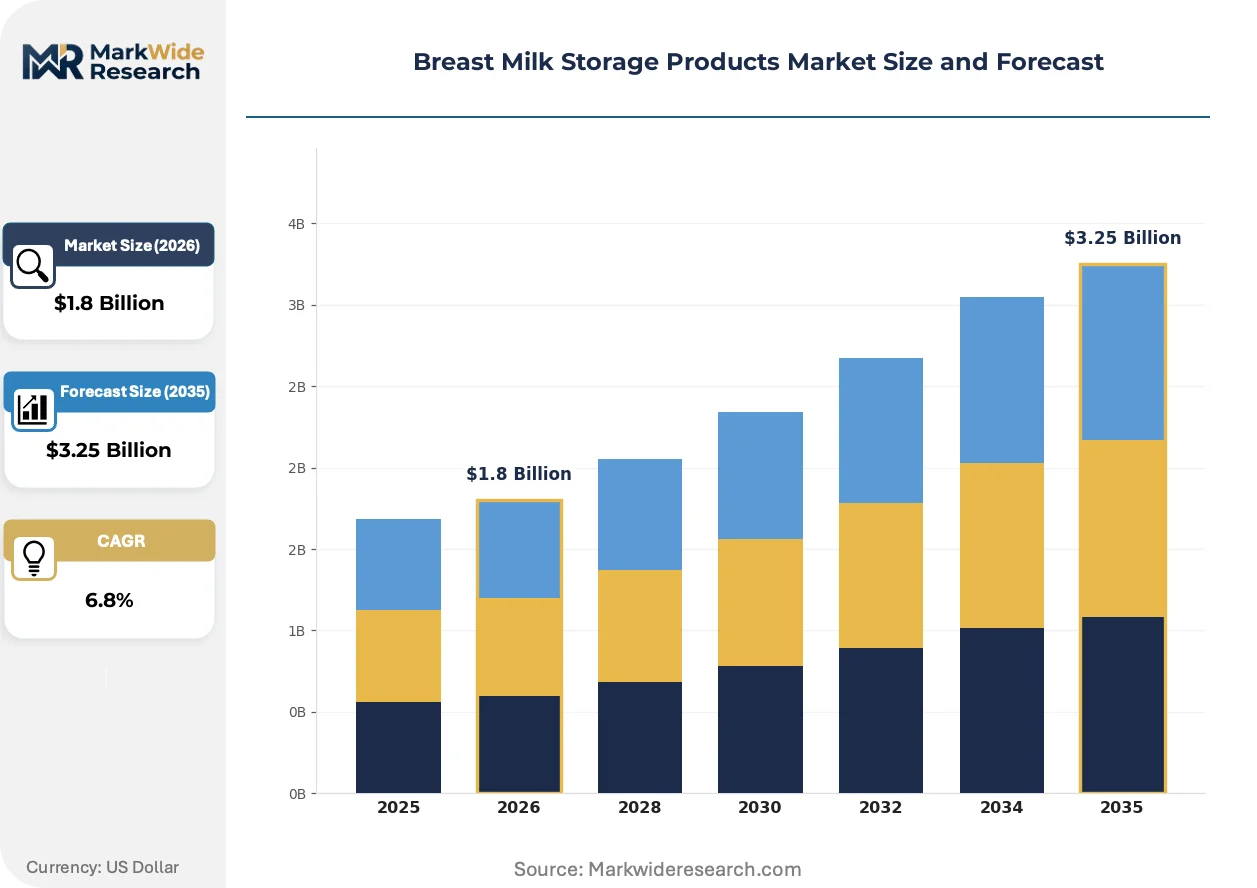
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Storage Bags, Storage Containers, Freezer Kits, Bottle Sets Material: Plastic, Glass, Silicone, BPA-Free End User: Parents, Hospitals, Lactation Consultants, Childcare Centers Storage Capacity: 50 ml, 100 ml, 150 ml, 200 ml |
| Companies Covered | Pigeon Corporation, Spectra Baby USA, LLC, Medela AG, Kiinde International, Inc., Ardo Medical AG, Koninklijke Philips N.V., Ameda, Inc., Mayborn Group Limited, Lansinoh Laboratories, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breast Milk Storage Products Market Strategic Shifts & Innovations
Material science advances and regulatory fragmentation are simultaneously expanding performance boundaries and compliance complexity across storage formats.
Platinum-cured silicone is bifurcating the reusable container segment from commodity plastics. Eco-conscious parents in Germany and Scandinavia are adopting these containers at triple the rate of conventional alternatives. This material transition is compressing price elasticity in the premium tier while forcing polypropylene suppliers to defend volume positions through cost reduction.
REACH SVHC candidate list expansion is reshaping additive formulations across European supply chains. Phthalate and bisphenol restrictions now cover 233 substances, compelling reformulation of sealants and colorants. Bag manufacturers serving EU markets are accelerating migration to bio-based polyethylene to preempt future restrictions.
Subscription-based replenishment models are displacing episodic retail purchasing among working parents. Direct-to-consumer platforms now capture one-third of US volume, bypassing pharmacy and big-box intermediaries. This channel shift concentrates most visibly in coastal metropolitan areas with dense employer lactation program penetration.
Breast Milk Storage Products Market Segmentation
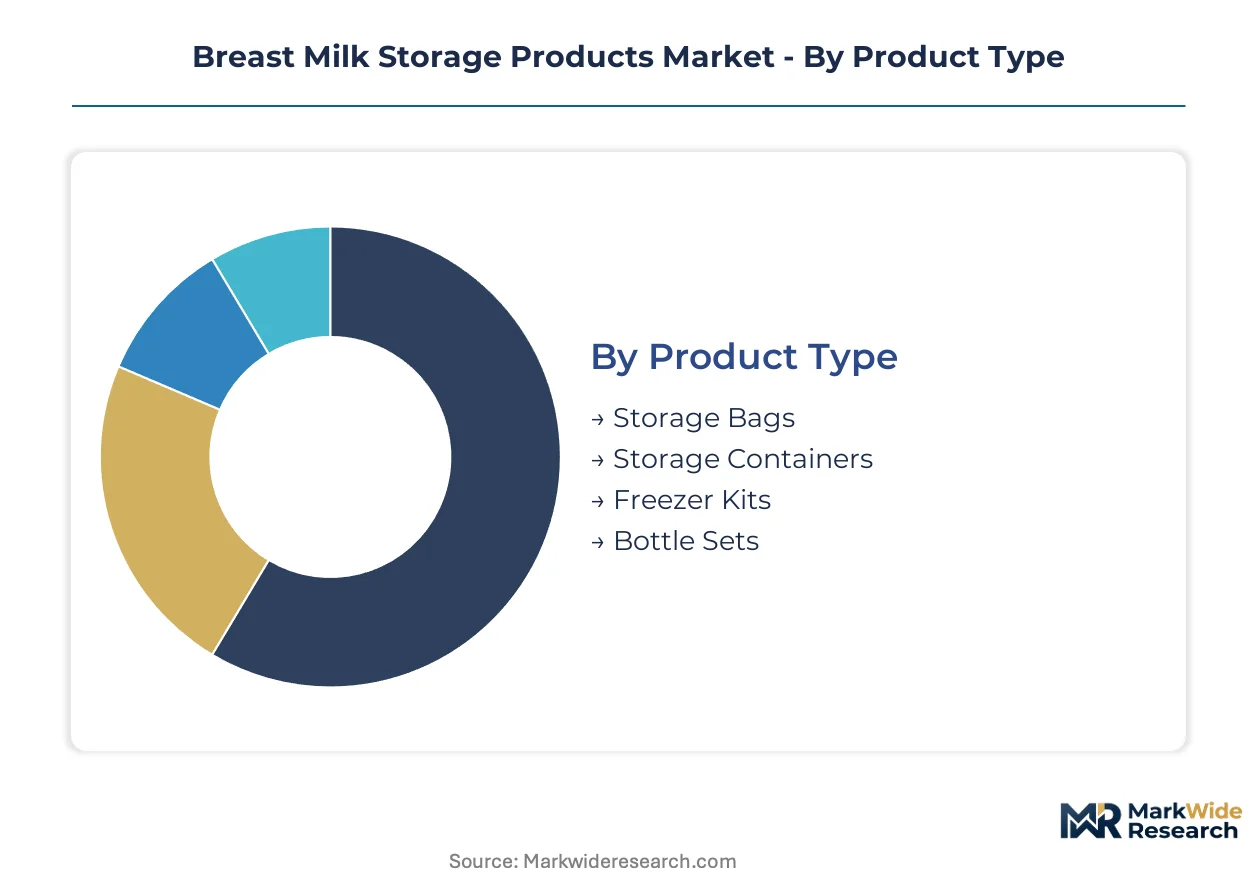
Segmentation in breast milk storage products reveals how material preferences, capacity requirements, and procurement channels fragment into distinct commercial battlegrounds. Manufacturers must align formulation investments and distribution partnerships with the specific compliance and convenience priorities of each buyer type.
Product Type:
Storage bags dominate export volumes to North American and European markets, while bottle sets and freezer kits concentrate in domestic Asian supply chains serving hospital discharge programs.
- Storage Bags:Single-use polyethylene or polypropylene pouches with hermetic zipper seals and pre-sterilized packaging. Demand concentrates in the United States where workplace lactation mandates drive portable, disposable formats for daily pumping routines.
- Storage Containers:Rigid vessels in plastic, glass, or silicone with threaded lids for repeated use. German and Scandinavian parents favor these for home freezer organization, motivated by sustainability preferences and extended reuse cycles.
- Freezer Kits:Comprehensive systems combining trays, containers, and labeling accessories for systematic frozen milk management. Hospital partnerships in India and China anchor procurement for postnatal discharge protocols.
- Bottle Sets:Integrated collections linking storage directly to feeding nipples, reducing transfer steps. Japanese and South Korean manufacturers lead design innovation for this segment.
Storage bags hold the largest share; momentum sits with storage containers as silicone substitution accelerates.
Material:
Cost tiers separate commodity polypropylene from premium platinum-cured silicone, with glass occupying a narrow certification-driven niche.
- Plastic:Polypropylene and polyethylene formulations dominate unit economics. FDA food-contact substance notifications govern US market entry, while REACH SVHC restrictions force additive reformulation for European access.
- Silicone:Platinum-cured medical-grade containers support 500+ use cycles without degradation. France's AGEC law and extended producer responsibility mandates reward suppliers with established silicone take-back infrastructure.
- Glass:Borosilicate vessels offer chemical-free assurance for premium buyers. Breakage risk and weight constrain adoption despite parental willingness to pay for purity guarantees.
- BPA-Free:Formulations excluding bisphenol-A and related compounds, now baseline expectation rather than differentiator. BIS certification in India and GB standards in China enforce varying testing protocols.
Plastic captures volume leadership; silicone gains share fastest as sustainability premiums reshape purchasing.
End User:
Procurement patterns diverge sharply between institutional buyers with compliance departments and direct-to-consumer parents prioritizing convenience.
- Parents:Individual purchasers through retail, pharmacy, and subscription platforms. US coastal metropolitan areas with dense employer lactation program penetration show highest direct-to-consumer conversion rates.
- Hospitals:Institutional procurement for maternity ward discharge kits and NICU storage protocols. Joint Commission standards and AAP guidelines shape specification requirements.
- Lactation Consultants:Professional advisors influencing brand selection through recommendation authority. Independent practice networks in Canada and Australia drive regional preference formation.
- Childcare Centers:Licensed facilities requiring batch-labeled, tamper-evident storage for regulatory compliance. State-level daycare licensing variations in the US fragment standardization.
Parents represent the dominant volume; hospitals anchor pricing discipline through tender processes.
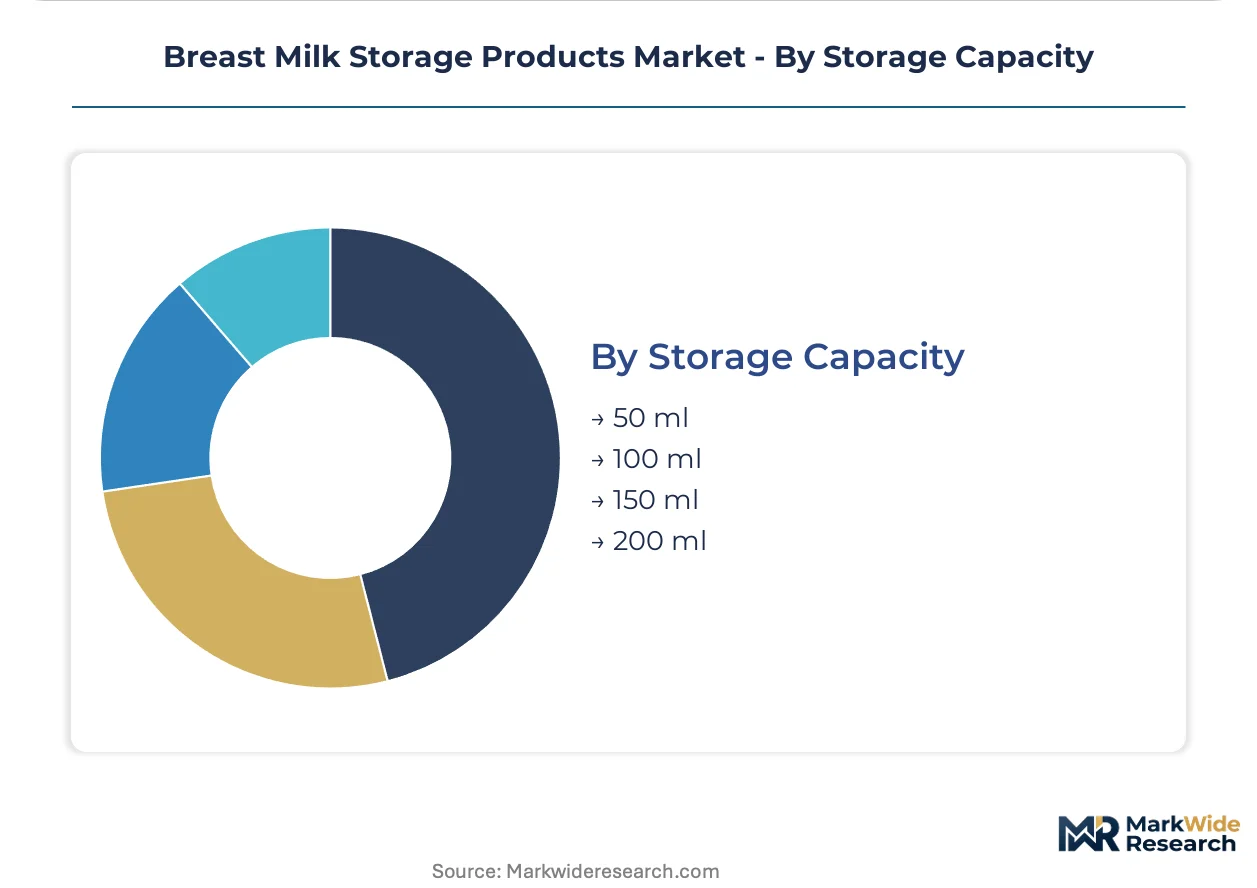
Storage Capacity:
Volume segmentation tracks feeding-stage progression from colostrum collection through weaning transition.
- 50 ml:Colostrum and early lactation collection for premature infant feeding. NICU partnerships and hospital lactation programs standardize this capacity for initial expression protocols.
- 100 ml:Transitional stage serving established supply with moderate single-session yields. Retail assortment breadth peaks at this capacity across pharmacy channels.
- 150 ml:Standard working-parent portion aligning with typical pump session output. Workplace lactation room provisioning favors this capacity for employer-sponsored kit distribution.
- 200 ml:High-capacity formats for overnight accumulation and freezer stockpiling. Bulk purchasing and subscription replenishment models concentrate demand here.
150 ml holds the largest share; 50 ml climbs fastest as NICU-grade home care expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers supply polyethylene storage bags to North American workplace lactation programs, while German silicone processors serve Scandinavian sustainability-focused buyers. Trade corridors concentrate procurement power in three demand clusters.
United States
Employer-sponsored lactation kit distribution drives volume through hospital discharge partnerships and workplace benefit programs. FDA food-contact substance notifications govern material safety for all plastic storage formats entering the market. California and New York metropolitan areas concentrate direct-to-consumer subscription penetration.
Germany
REACH SVHC restrictions on 233 substances force additive reformulation across sealant and colorant supply chains. Platinum-cured silicone containers from Bavarian processors capture triple the adoption rate of conventional plastics among eco-conscious parents. Berlin-Brandenburg hosts specialized migration testing laboratories serving EU notification requirements.
China
GB standards for food-contact materials and dual carbon goals reshape domestic manufacturing toward export-grade capacity. Yangtze River Delta producers dominate polyethylene bag output for North American private-label contracts. Zhejiang province concentrates hermetic zipper seal component fabrication.
India
BIS certification requirements professionalize domestic manufacturing while enabling export-grade silicone and glass container production. Hospital discharge kit partnerships in Maharashtra and Karnataka anchor institutional procurement volumes. Tamil Nadu processors specialize in 50 ml colostrum collection formats for NICU-grade home care.
Brazil
ANVISA's pending food-contact notification pathway for breast milk storage materials will unlock Latin America's largest consumer base. São Paulo state concentrates pharmacy and retail distribution infrastructure. Minas Gerais houses emerging domestic bag manufacturing capacity serving Mercosur markets.
Breast Milk Storage Products Market Key Industry Players
Listed leaders compete with private specialists across material technology and channel access, producing a tiered structure where scale advantages meet niche positioning. Three archetypes dominate: diversified healthcare conglomerates bundling storage within mother-and-child ecosystems; pure-play lactation specialists leveraging clinical credibility; and private-label manufacturers serving pharmacy and retail intermediaries. Competitive moves concentrate on silicone material substitution partnerships and direct-to-consumer platform buildout.
Among diversified healthcare conglomerates, Koninklijke Philips N.V. and Medela AG exemplify ecosystem bundling strategies that integrate storage with broader maternity care portfolios. Lansinoh Laboratories occupies a position within the specialist tier, representing affordable, widely distributed formats that anchor pharmacy channel presence. These three entities illustrate how competitive positioning splits between integrated platform plays and focused format specialization.
| Leading Market Players |
|---|
| Pigeon Corporation |
| Spectra Baby USA, LLC |
| Medela AG |
| Kiinde International, Inc. |
| Ardo Medical AG |
| Koninklijke Philips N.V. |
| Ameda, Inc. |
| Mayborn Group Limited |
| Lansinoh Laboratories, Inc. |
| Others |
Cost & Logistics Intelligence
FDA food-contact substance notifications govern both supplier qualification timelines and tiered price positioning across plastic storage formats, compressing margins for new entrants while rewarding incumbents with cleared material libraries. REACH SVHC restrictions in Europe and BIS certification in India create parallel gating regimes that fragment pricing power by geography.
Pricing Analysis
Prior-generation polypropylene bag formats trade at commodity unit economics while current-generation platinum-cured silicone containers command sustainability premiums, and next-generation NFC-enabled smart bags are establishing hospital-grade price benchmarks. Three-tier pricing structure across premium silicone, standard plastic, and economy polypropylene levels separates buyers by certification requirements and reuse intensity. Pricing pressure stems from propylene monomer volatility driven by naphtha cracking economics, squeezing standard bag margins. Working parents in employer-sponsored lactation programs show lowest price sensitivity due to benefit coverage, while uninsured direct-to-consumer purchasers in pharmacy channels exhibit highest elasticity.
Supply Chain Analysis
Hermetic zipper seal fabrication concentrates in Zhejiang province and three Japanese precision-molding houses, creating geographic chokepoints that constrain capacity expansion. Chinese polyethylene processors, German silicone compounders, and Indian glass fabricators anchor regional supply clusters. Raw material dependencies center on propylene monomer, platinum-cured silicone catalysts, and borosilicate glass tubing. Single-source vulnerability runs through Japanese zipper seal suppliers, exposing brands to allocation risk. Distribution runs through hospital discharge kit partnerships, pharmacy retail networks, and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Workplace lactation mandate expansion fragments procurement authority between employers, hospitals, and individual parents, creating niche positioning opportunities for specialized formats. This demand-side shift rewards players who align certification investments with specific buyer archetypes rather than pursuing undifferentiated scale.
For Market Incumbents: Consolidate silicone material partnerships to preempt platinum-cured supply constraints, and deepen hospital system relationships to anchor tender-based volume against direct-to-consumer disintermediation. FDA notification backlogs exceeding fourteen months create defensive moats for cleared material libraries. Backward integration into hermetic seal component production reduces Japanese supplier concentration risk. For New Entrants and Emerging Players: Lead with 50 ml colostrum collection formats targeting NICU-grade home care expansion, where clinical credibility requirements filter out commodity competitors. Brazil's pending ANVISA food-contact pathway offers the most penetrable geography for first-mover certification investment. Direct-to-consumer subscription platforms in US coastal metropolitan areas provide the cleanest go-to-market angle for bypassing pharmacy channel gatekeepers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across platinum-cured silicone container manufacturing as cleanroom requirements and migration testing capacity demands escalate. Five-to-ten year viability favors suppliers with established take-back infrastructure under extended producer responsibility mandates. Acquisition targets should profile as mid-cap silicone specialists with cleared EU REACH formulations. The signal to watch is FDA food-contact substance notification processing velocity as a leading indicator of new material introduction cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Silicone Material Substitution Partnership | Platinum-cured supply agreements with Bavarian processors lock in sustainability-premium positioning against polypropylene commoditization. |
| Direct-to-Consumer Platform Buildout | Subscription replenishment models in California and New York metropolitan areas bypass pharmacy intermediaries and capture employer lactation program penetration. |
| Smart Temperature Monitoring Integration | NFC-enabled bag development aligns with Joint Commission cold-chain standards for hospital-grade compliance in home settings. |
| Extended Producer Responsibility Infrastructure | France's AGEC law-compliant take-back systems reward early investment with regulatory preference and brand differentiation. |
| ANVISA Certification Pre-positioning | Brazilian food-contact notification preparation unlocks Latin America's largest consumer base ahead of pathway formalization. |
Research Approach
Desk research of FDA food-contact substance notification databases, EU REACH SVHC candidate list updates, and hospital procurement contract disclosures preceded structured interviews with lactation product category managers, biomedical engineers at NICU departments, employer benefits administrators, and silicone material compounders. Secondary validation drew from customs trade records, BIS certification registries, and GPO contract databases. Bottom-up segment sizing triangulated against top-down market boundary estimates.
Variance decomposition across material substitution rates, workplace lactation mandate enforcement trajectories, and channel shift velocities shaped the analytical framework. Segmentation dimensions modeled include product format, material chemistry, end-user procurement type, and storage capacity tier. CAGRs derived from fitted growth curves applied to employer-sponsored program expansion data and silicone adoption rate differentials. Forecast inputs incorporated propylene monomer price volatility indices and extended producer responsibility implementation schedules.
The analysis sits within stated boundaries; outcomes outside sustained workplace lactation policy expansion or accelerated silicone material cost reduction would require recalibration. Forecasts reflect assumptions regarding FDA notification processing timelines and REACH SVHC list evolution. Practitioners should keep alternative scenarios live as ANVISA pathway formalization and F-Gas Regulation refrigerant transition requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Home Care Packaging Market
Baby Products
Global Baby Carriers Market
Baby Products
Global Baby Play Mats Market
Baby Products
Maternity Products Market
Baby Products
Noise-Muffling Infant Hat Market
Baby Products
Global Pregnancy Pillow Market
Baby Products
Baby Wipes Market
Baby Products
Australia Baby Care Products Market
Baby Products
Breastfeeding Accessories Market
Baby Products
Baby Shoes Market
Baby Products
Baby Swaddle Wrap Market
Baby Products
Baby Bottle Warmer and Sterilizer Market
Baby Products
Baby Feeding Accessories Market
Baby Products
Baby Care and Mother Care Market
Baby Products
United Arab Emirates Baby Care Products Market
Baby Products
Diaper Bag Market