
 Baby Sleepsuits Market | 2026-2036
Baby Sleepsuits Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Sleepsuits Market Outlook
Digital textile printing and AI-driven size-optimization algorithms is reconfiguring how baby sleepsuits are designed, prototyped, and restocked across direct-to-consumer platforms. Carter's, Inc. leverages vertically integrated North American manufacturing to sustain rapid inventory turns for big-box retail partners. H&M Group anchors its competitive stance through circular design protocols and transparent fiber tracing across its babywear assortment. Inditex competes via hyper-responsive supply chains that compress design-to-shelf cycles for seasonal sleepsuit collections.
Baby sleepsuits are one-piece infant garments engineered with envelope necklines, snap or zipper closures, and fabric weights measured in grams per square meter to regulate thermoregulation during sleep. Cotton-dominant constructions remain standard, though bamboo-derived viscose gains traction for moisture-wicking performance in warm-climate markets. Zip-up configurations command premium positioning due to convenience-driven parent preference and reduced fabric waste in manufacturing. Bamboo material volumes expand fastest among synthetic-averse consumers, while fleece-reinforced variants occupy stable demand in seasonal cold-weather regions.
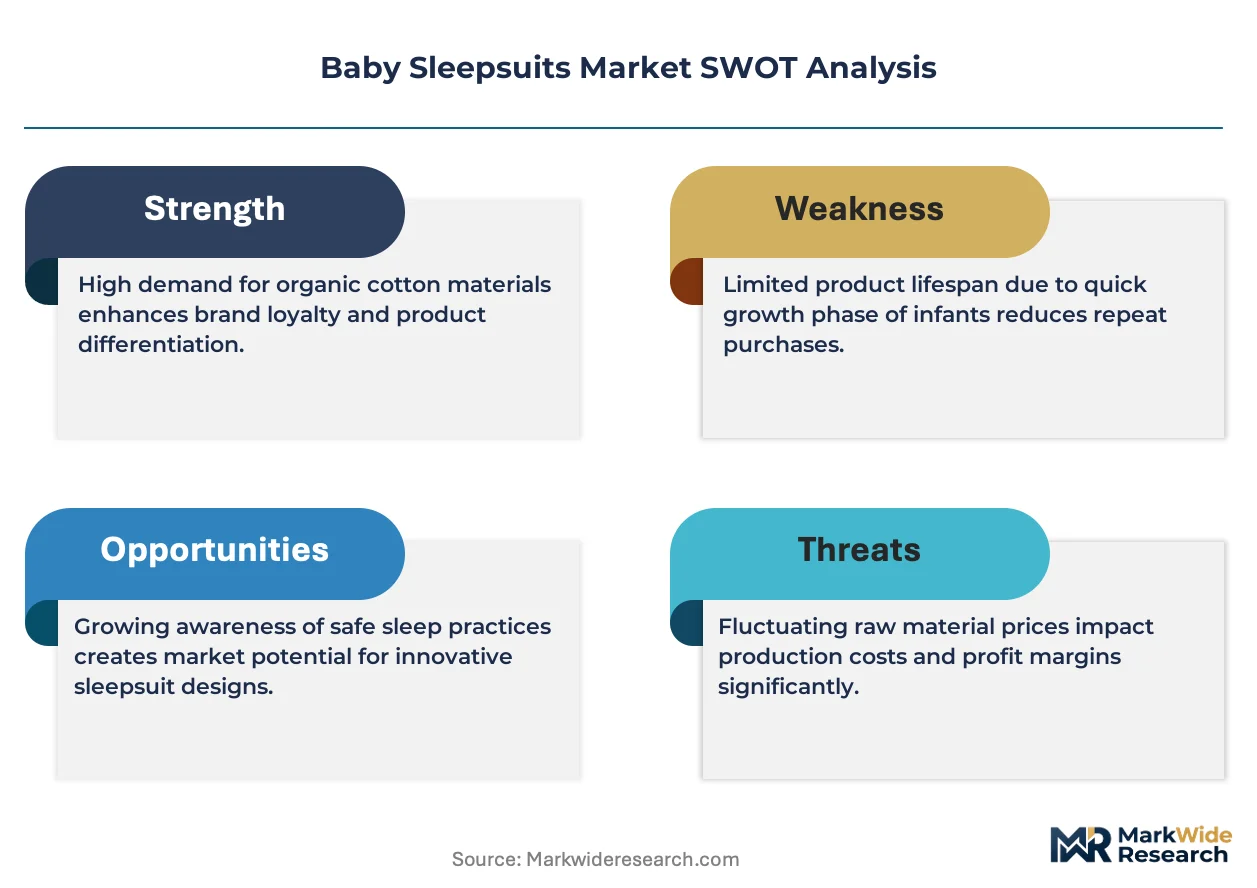
OEKO-TEX Standard 100 and REACH compliance in Europe, alongside CPSC flammability standards enforced by US regulators, elevate barrier costs for new entrants and redirect R&D spending toward certified organic supply chains. China's GB 31701 national textile safety standard for infant products tightens chemical residue thresholds, reshaping sourcing decisions for brands manufacturing in East Asia. Stakeholders must monitor evolving chemical restriction lists and certification portability across jurisdictions to preempt supply disruptions and maintain shelf access.
Market Dynamics
Millennial and Gen Z parents are compressing purchase cycles through algorithmic personalization on direct-to-consumer platforms, forcing manufacturers to reconfigure inventory models around micro-batch production and predictive sizing.
Growth Catalysts
- REACH chemical compliance:European REACH restrictions on azo dyes and formaldehyde residues push manufacturers toward certified organic cotton supply chains, creating premium positioning for compliant brands.
- Bamboo viscose adoption:Moisture-wicking performance in warm-climate markets accelerates substitution away from petroleum-based synthetics among environmentally conscious buyers.
- E-commerce channel expansion:Direct-to-consumer platforms in the United States, China, and Germany enable data-driven restocking and reduced markdown exposure for seasonal collections.
Market Restraints
- Organic cotton input volatility:Weather-dependent yields and limited certified acreage concentrate supply risk with Texas and India-based growers.
- GB 31701 compliance costs:China's tightened chemical residue thresholds for infant textiles elevate testing expenditure for East Asian manufacturing facilities.
- Fleece substitution threat:Polyester fleece variants maintain stable demand in cold-weather regions, constraining pure-cotton market expansion in seasonal segments.
Strategic Opportunities
- Underpenetrated Indian market:Rising disposable incomes among urban middle-class parents create whitespace for premium certified organic positioning.
- AI-driven size optimization:Machine learning algorithms predicting infant growth curves enable subscription-based replenishment models.
- EU Green Deal procurement incentives:Public and private sector sustainable purchasing mandates favor circular design protocols and fiber tracing transparency.
Industry Challenges
- Certification timeline compression:OEKO-TEX Standard 100 and CPSC flammability testing cycles delay seasonal product launches.
- Digital textile printing capex:On-demand color customization requires capital-intensive printer fleets and specialized technician training.
- Legacy ERP integration:Real-time inventory synchronization between DTC platforms and contract manufacturers demands middleware investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Sleepsuits Market |
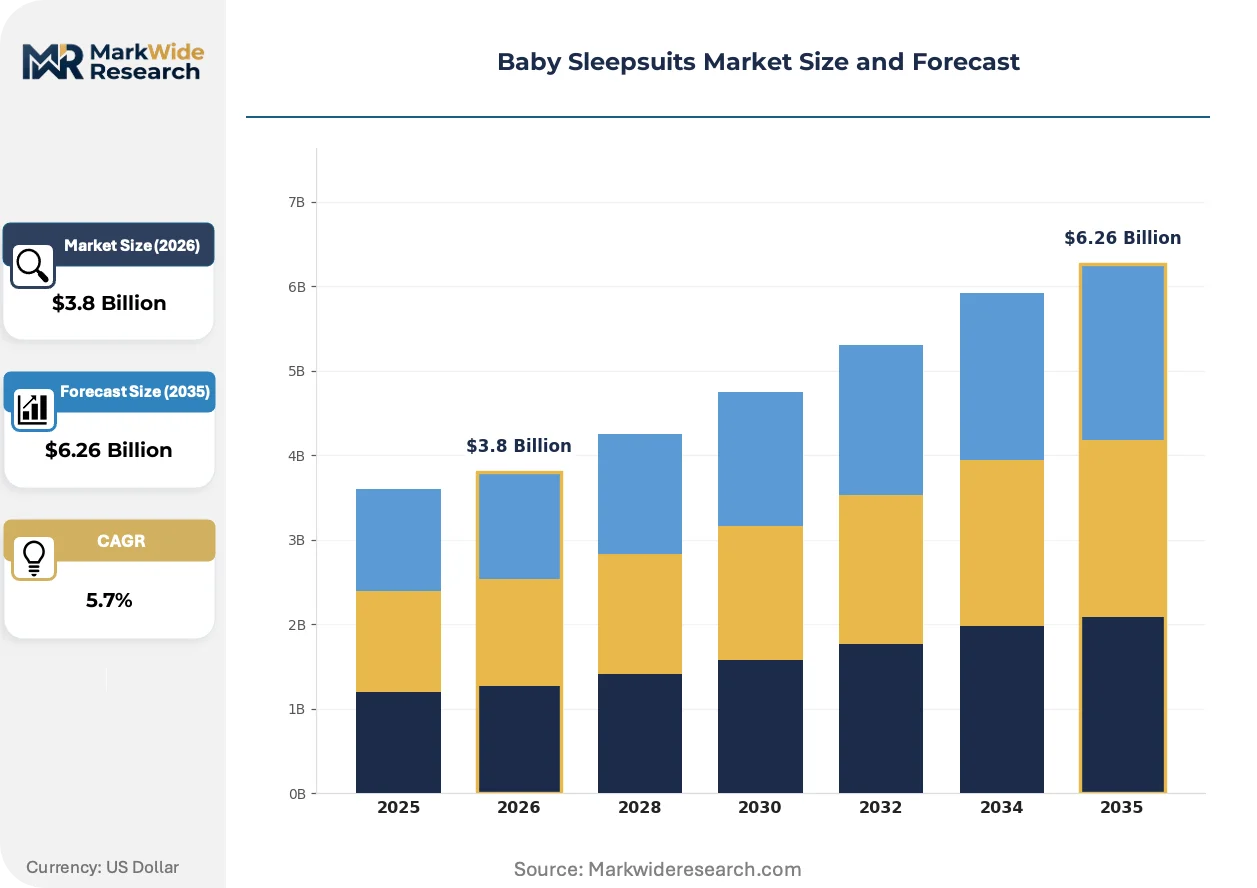
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Footed, Non-Footed, Zip-Up, Button-Up Material: Cotton, Polyester, Bamboo, Fleece Size: Newborn, 0-3 Months, 3-6 Months, 6-12 Months Color: Pastel, Bright, Neutral, Print |
| Companies Covered | Carter’s, Inc., H&M Group, Gap Inc., Inditex, The Children’s Place, Inc., Mothercare PLC, Gerber Childrenswear LLC, Hanna Andersson, Petit Bateau, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Sleepsuits Market Strategic Shifts
Digital workflows and predictive analytics are compressing design-to-shelf timelines while regulatory chemical restrictions reshape material sourcing priorities across manufacturing bases.
3D knitting technology is virtualizing traditional cut-and-sew production by constructing seamless sleepsuit bodies directly from yarn, eliminating fabric waste and enabling customized fit profiles. Boutique manufacturers in Portugal and Japan are adopting these machines for made-to-order infantwear. The technology is virtualizing inventory risk by enabling on-demand production against confirmed orders rather than speculative seasonal builds.
REACH Annex XVII restrictions on nickel in fasteners and CPSC flammability standards for children's sleepwear are elevating barrier costs for new market entrants. European manufacturers redirect R&D spending toward certified organic supply chains and alternative closure systems. Small-batch producers in Germany and France respond by partnering with OEKO-TEX certified Turkish mills for compliant component sourcing.
Subscription-based replenishment models are displacing episodic retail purchasing among digitally native parents who prioritize convenience and sizing continuity. Direct-to-consumer platforms capture recurring revenue through algorithmic growth prediction and automated shipment timing. This behavioral shift concentrates in the United States and United Kingdom where delivery infrastructure and payment flexibility support membership economics.
Baby Sleepsuits Market Segmentation
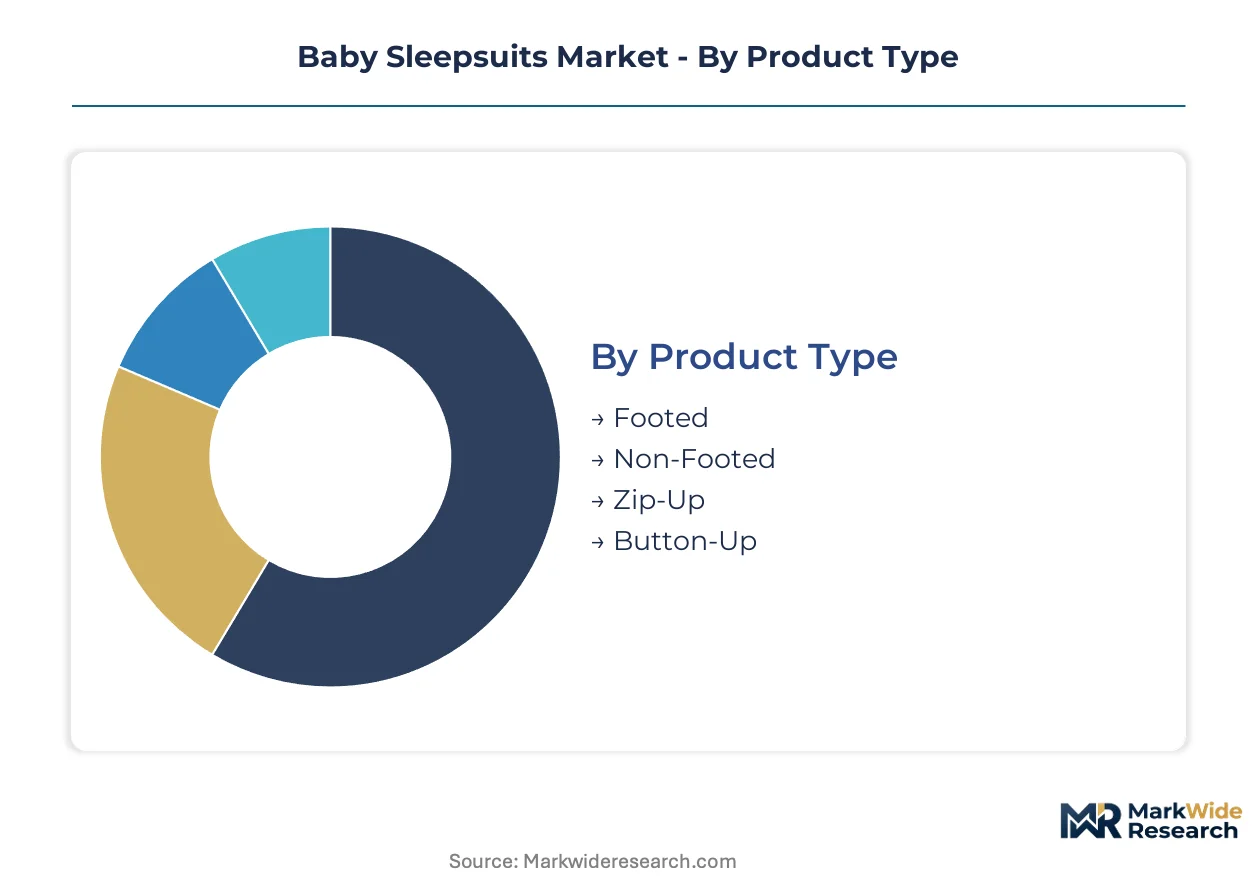
Segmentation in baby sleepsuits reveals how parents trade off convenience features against material preferences and sizing accuracy. Manufacturers configure production lines around these dimensions to match channel-specific demand patterns.
Product Type:
Application context determines closure preference and thermal coverage needs across climates and caregiving routines.
- Zip-Up:Front-zip construction enables single-handed diaper changes with minimal infant disturbance. Premium positioning in the United States and Germany reflects convenience-driven parent willingness to pay for reduced nighttime friction.
- Footed:Integrated enclosed feet eliminate separate sock management for non-ambulatory infants. Concentrated demand in seasonal cold-weather regions constrains pure-cotton expansion where polyester fleece variants maintain stable share.
- Non-Footed:Open-ankle design supports mobility development and temperature layering flexibility.
- Button-Up:Snap-closure construction offers durability and repairability advantages over zipper mechanisms.
Footed configurations hold installed capacity. Zip-Up is rotating up the share rankings.
Material:
Margin structures diverge sharply between commodity fiber inputs and certified organic supply chains with traceability premiums.
- Cotton:Standardized GSM-weighted constructions dominate baseline production with established dye affinity and breathability profiles. REACH chemical compliance in Europe redirects sourcing toward certified organic acreage in India and Turkey.
- Bamboo:Viscose-derived cellulose delivers moisture-wicking performance exceeding cotton in warm-humidity conditions. Substitution accelerates among synthetic-averse consumers in Australia and Singapore seeking petroleum-free alternatives.
- Polyester:Petroleum-based synthetic maintains cost advantage in mass-market fleece-reinforced cold-weather variants.
- Fleece:Brushed polyester construction provides thermal retention for seasonal segments with stable demand in northern China and Canada.
Cotton maintains baseline volume leadership. Bamboo is climbing the fastest among material alternatives.
Size:
Customer type shifts dramatically across developmental windows as growth velocity and caregiving contexts evolve.
- Newborn:Preemie-to-full-term sizing accommodates rapid physiological transitions in the first weeks. Hospital discharge gifting concentrates demand in the United States and United Kingdom through registry-based purchasing.
- 0-3 Months:Core entry segment for first-time parent acquisition with highest trial-to-repeat conversion potential.
- 3-6 Months:Mid-infancy sizing aligns with motor development milestones and sleep pattern stabilization.
- 6-12 Months:Extended wear window supports subscription replenishment models with algorithmic growth prediction.
Newborn sizing anchors registry economics. 0-3 Months is gaining share fastest as a customer acquisition lever.
Color:
Supply concentration in digital textile printing capacity is reconfiguring how color assortment gets deployed across direct-to-consumer channels.
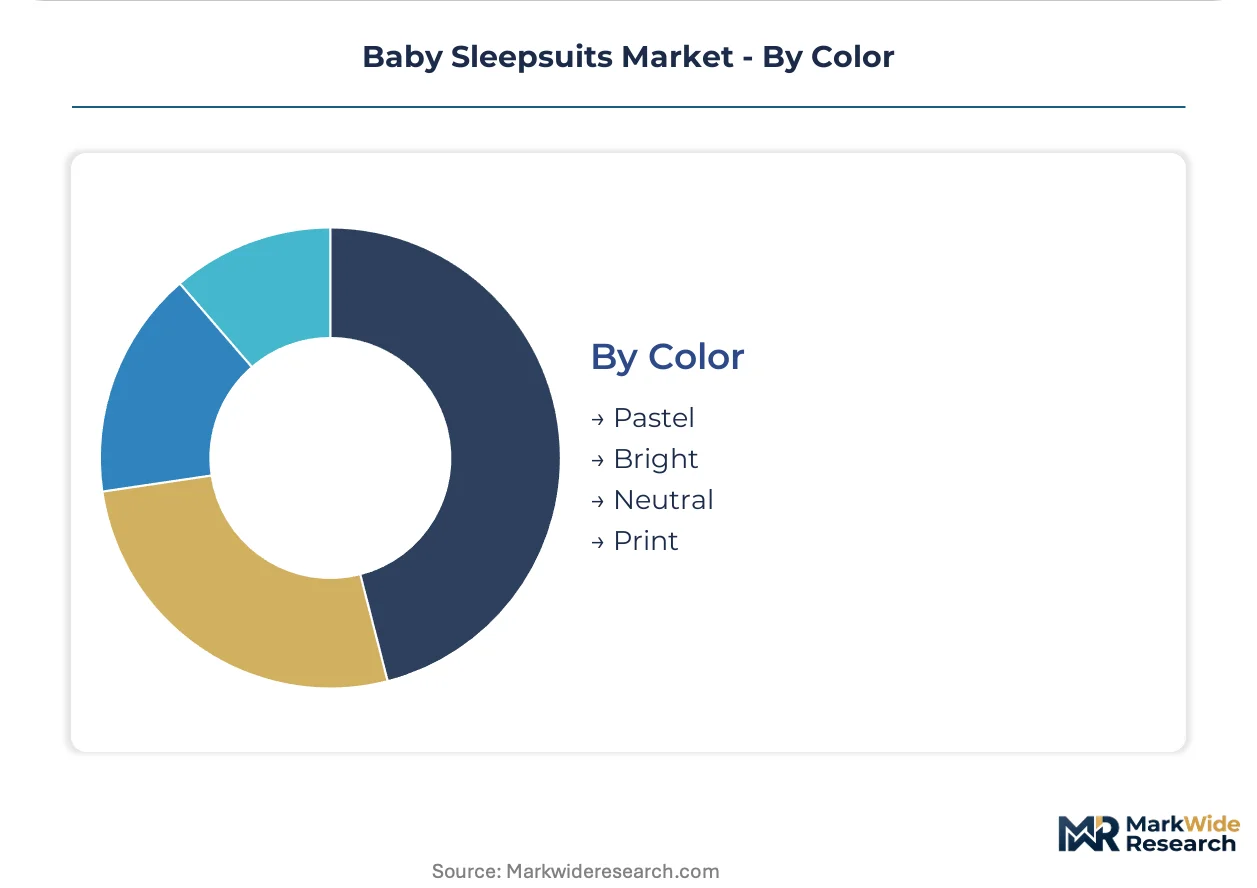
- Neutral:Beige, gray, and cream palettes support gender-agnostic gifting and multi-child reuse. Urban parents in Germany and Scandinavia prioritize minimalist aesthetic compatibility with nursery design schemes.
- Pastel:Soft-toned traditional infant colorways maintain registry and retail fixture presence.
- Bright:Saturated hues support visual stimulation theories and social media shareability.
- Print:Patterned designs enable seasonal storytelling and licensed character collaborations.
Neutral holds design-forward positioning. Print is rotating up the share rankings through micro-batch customization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturing clusters supply finished sleepsuits to United States and German retail channels through vertically integrated textile corridors. E-commerce penetration varies sharply across consumer markets, reshaping last-mile distribution economics.
United States
Registry-based gifting concentrates newborn demand through hospital discharge partnerships and digital platform integrations. CPSC flammability standards for children's sleepwear elevate testing expenditure for imported finished goods. Carter's anchors domestic supply through captive manufacturing in Georgia and distribution partnerships with big-box retailers.
Germany
Urban parents in Berlin and Hamburg prioritize OEKO-TEX Standard 100 certification for organic cotton sourcing in minimalist nursery aesthetics. REACH Annex XVII restrictions on nickel fasteners redirect component procurement toward Turkish certified mills. Bavaria-based specialty retailers coordinate micro-batch production with Portuguese 3D knitting facilities.
China
GB 31701 national textile safety standards tighten chemical residue thresholds for infant products manufactured in Yangtze River Delta clusters. Domestic e-commerce platforms capture millennial parent demand through algorithmic personalization and same-city delivery networks. Zhejiang province hosts concentrated digital textile printing capacity for on-demand color customization.
India
Rising disposable incomes among urban middle-class parents in Maharashtra and Karnataka create whitespace for premium certified organic positioning. BIS certification requirements for infant textiles remain less stringent than European equivalents, enabling price-accessible entry tiers. Tiruppur's organic cotton processing cluster supplies GOTS-certified fabric to export-oriented brands.
United Kingdom
Subscription-based replenishment models displace episodic retail purchasing among digitally native parents in Greater London and Manchester. EU-UK regulatory divergence post-Brexit complicates OEKO-TEX certification portability for cross-channel inventory. Scottish textile heritage brands leverage transparent fiber tracing as competitive differentiation.
Baby Sleepsuits Market Competitive Environment
Channel-controlling players compete with product-specialist players through divergent inventory velocity strategies. The vendor base stratifies across three tiers: vertically integrated mass-market producers, fast-fashion platform operators, and boutique certified-organic specialists. Two dominant competitive moves define current positioning: backward integration into certified cotton supply chains and algorithmic personalization investments for direct-to-consumer platforms.
Within the mass-market tier, Carter's, Inc. and The Children's Place, Inc. occupy positions defined by North American manufacturing scale and retail channel density. Among European fast-fashion operators, H&M Group and Inditex exemplify divergent approaches to circular design protocols and hyper-responsive supply chain compression. Hanna Andersson represents the boutique-certified archetype through Pacific Northwest heritage positioning.
| Leading Market Players |
|---|
| Carter's, Inc. |
| H&M Group |
| Gap Inc. |
| Inditex |
| The Children's Place, Inc. |
| Mothercare PLC |
| Gerber Childrenswear LLC |
| Hanna Andersson |
| Petit Bateau |
| Others |
Value Chain & Pricing Dynamics
GB 31701 compliance cost volatility in Chinese manufacturing clusters compresses margin spreads between certified organic and conventional cotton tiers while reshaping sourcing footprints toward Turkish and Indian alternatives. This regulatory chokepoint simultaneously elevates entry barriers for price-accessible positioning and rewards backward-integrated players with captive certified supply.
Pricing Analysis
Digital textile printing capability gaps separate pricing tiers: established DTC platforms command premium positioning through on-demand color customization, while conventional screen-printed inventory rotates through markdown cycles at mass retail. Price differentiation rests on OEKO-TEX certification grade and algorithmic personalization depth. Cost compression in standard cotton tiers intensifies as Zhejiang digital printing capacity expands. Subscription-based replenishment models exhibit lowest price sensitivity; episodic gift purchasers show highest elasticity.
Supply Chain Analysis
REACH Annex XVII restrictions on nickel fasteners and azo dyes limit component flows from non-certified Asian suppliers toward Turkish and Portuguese certified mills. Finished garment assembly concentrates in China, Bangladesh, and Vietnam. Raw material dependencies center on Texas and Indian organic cotton acreage, OEKO-TEX certified dye houses, and YKK-compliant zipper mechanisms. Single-source vulnerability sits with concentrated Indian organic cotton processing. Distribution runs through direct-to-consumer platforms, specialty boutique networks, and big-box retail partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among algorithmically driven direct-to-consumer platforms, with registry-integrated gifting and subscription replenishment models consolidating purchase influence among millennial and Gen Z parents.
For Market Incumbents: Entrench certified organic supply chain control through captive acreage partnerships in India and Turkey, insulating against GB 31701 compliance cost escalation. Deepen AI-driven size optimization capabilities to defend against boutique 3D knitting entrants. Prioritize middleware investment for real-time inventory synchronization between DTC platforms and contract manufacturers. For New Entrants and Emerging Players: Urban middle-class whitespace in Maharashtra and Karnataka offers lowest competitive density for premium certified organic positioning. Target subscription-based replenishment models in the United Kingdom and United States where delivery infrastructure supports membership economics. Lead with transparent fiber tracing and circular design protocols to differentiate against fast-fashion platform operators. For Investors and Strategic Acquirers: EU Green Deal procurement mandates reshape the acquisition landscape toward circular design capability and OEKO-TEX certified supply chain control. Long-term viability favors boutique-certified specialists with Portuguese 3D knitting partnerships or Pacific Northwest heritage positioning over undifferentiated mass-market exposure. Monitor REACH chemical restriction list expansions as inflection signal for certified supply chain premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Organic Supply Chain Integration | Captive Indian and Turkish acreage secures OEKO-TEX compliance against REACH tightening. |
| AI-Driven Size Optimization Platform | Machine learning growth prediction enables subscription economics and reduces return rates. |
| 3D Knitting Technology Adoption | Portuguese and Japanese on-demand production eliminates inventory risk and fabric waste. |
| Direct-to-Consumer Channel Expansion | Algorithmic personalization captures recurring revenue from digitally native parent segments. |
| Transparent Fiber Tracing System | EU Green Deal procurement incentives reward circular design protocol documentation. |
Study Parameters
Desk research of customs trade databases, OEKO-TEX certification registries, and retail audit data preceded structured interviews with brand supply chain directors, Turkish mill procurement heads, DTC platform operations leads, and German specialty retailer buyers. Primary fieldwork combined with secondary validation across SEC filings, GB standards documentation, and REACH Annex XVII restriction lists. Bottom-up volume modeling triangulated against top-down value estimates from e-commerce transaction data and big-box retail partnership disclosures.
Assumptions held organic cotton yield volatility and regulatory chemical restriction timelines within observed patterns while varying e-commerce penetration rates and subscription model adoption curves across geographies. Segmentation dimensions modeled include closure type, material certification grade, sizing window, and channel structure. CAGRs derived from regression analysis against historical volume trajectories and demographic cohort spending projections. Forecast inputs incorporated millennial parent purchasing behavior shifts and digital textile printing capacity expansion schedules.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by fast-fashion platform operators would shift outcomes. Material shifts in REACH chemical restriction scope or GB 31701 enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Breastfeeding Accessories Market
Baby Products
Baby Feeding Accessories Market
Baby Products
Indonesia Baby Care Products Market
Baby Products
Baby Slings Market
Baby Products
Baby Swing Market
Baby Products
India Baby Care Products Market
Baby Products
Smart Crib Market
Baby Products
Baby Nose Suckers Market
Baby Products
Portable Cribs Market
Baby Products
Baby Bouncers Market
Baby Products
Baby Bottle Market
Baby Products
Baby Shoes Market
Baby Products
Sippy Cups Market
Baby Products
Baby Prams and Strollers Market
Baby Products
Baby Tableware Market
Baby Products
Electric Baby Nail Trimmer Market